
 Calcium Oxide Market | 2026-2036
Calcium Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Oxide Market Analysis
Asset-light leasing arrangements for lime kilns and slaking equipment is narrowing the capital barrier for mid-scale entrants in the calcium oxide sector. Graymont leverages captive limestone reserves across the Great Lakes to sustain integrated supply security. Carmeuse anchors its North American position through dense storage terminal networks. Lhoist Group competes on specialty high-purity grades for chemical and pharmaceutical precursors.
Calcium oxide, commonly called quicklime, is an alkaline inorganic compound produced by calcining calcium carbonate at temperatures exceeding 900°C, yielding a material with typical CaO content above 90% and significant exothermic reactivity upon hydration. Its primary industrial purpose centers on acid gas neutralization, metallurgical fluxing, and soil pH amendment across heavy process industries. Quicklime commands the largest volume share in steel flue gas treatment and iron ore pelletization, where margin pools concentrate among producers with direct marine access to coastal mills. High-purity grades represent the fastest-growing product tier, driven by pharmaceutical and food-grade calcium salt derivatives. Hydrated lime maintains mature demand profiles in municipal water treatment, where procurement patterns favor long-term offtake contracts with regional distributors.
The EPA enforces Maximum Achievable Control Technology standards for lime kiln particulate emissions, compelling US producers to retrofit scrubber systems or face operating curtailments. REACH registration requirements in Europe restrict heavy metal content in construction-grade quicklime, bifurcating compliance costs between export and domestic product streams. China's MEE imposes escalating carbon intensity benchmarks on calcination facilities under dual carbon implementation timelines. Stakeholders must monitor how tightening kiln emission protocols in multiple jurisdictions reshape the cost structure of merchant versus captive lime supply.
Market Dynamics
China's MEE carbon intensity benchmarks are forcing calcination facilities to abandon conventional rotary kilns for oxy-fuel and electric arc alternatives, fragmenting the cost structure between coastal merchant suppliers and inland captive operations.
Growth Catalysts
- Steel decarbonization mandates:EU Green Deal carbon border adjustments incentivize quicklime consumption in electric arc furnace slag conditioning across German and Italian mills.
- India's western industrial corridor expansion:Gujarat and Maharashtra cement capacity additions concentrate demand for high-reactivity quicklime within 200 kilometers of limestone deposits.
- Pharmaceutical precursor demand:Food-grade calcium salt derivatives require ultra-high-purity CaO, creating specification premiums for producers with dedicated hydration lines.
Market Restraints
- Natural gas price volatility:Calcination energy costs comprise 35-45 percent of production economics, exposing merchant producers to Henry Hub and TTF benchmark swings.
- Supply concentration in coastal China:Shandong and Hebei provinces control over half of Asia-Pacific export capacity, concentrating disruption risk from MEE enforcement actions.
- Hydrated lime substitution in water treatment:Municipal utilities increasingly specify calcium hydroxide over quicklime for pH adjustment, compressing merchant demand in North American and European utilities.
Strategic Opportunities
- Saudi Arabia's industrial city buildout:Jubail and Yanbu chemical complex expansions lack captive limestone, creating import-dependent demand for GCC producers with Red Sea terminal access.
- Carbon capture integration:Post-combustion calcium looping for cement plant flue gas treatment is hybridizing quicklime production with CO2 mineralization revenue streams.
- Indonesia's nickel processing boom:HPAL (high-pressure acid leach) laterite refineries require pH neutralization reagents at volumes exceeding domestic lime capacity.
Industry Challenges
- Kiln operator skill scarcity:Advanced combustion control and emissions monitoring systems require process engineers with cross-training in metallurgy and environmental compliance, talent concentrated at legacy European and Japanese producers.
- REACH registration timeline compression:Heavy metal content documentation for construction-grade quicklime demands laboratory accreditation cycles that lag project procurement schedules.
- Legacy equipment retrofit complexity:Vertical shaft kilns predating 2010 MEE standards require structural reinforcement for scrubber installation, extending downtime beyond seasonal maintenance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Oxide Market |
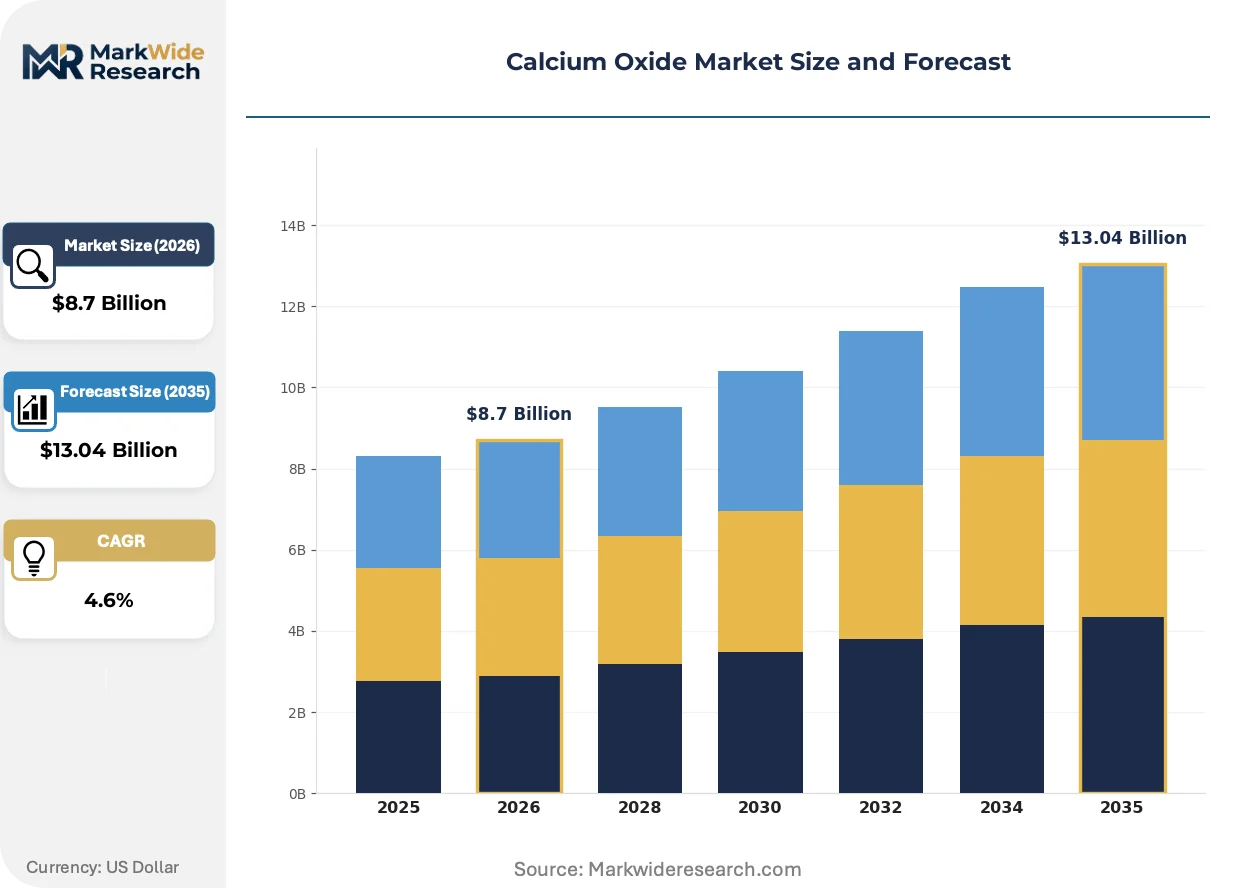
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Quicklime, Hydrated Lime, Calcium Hydroxide End Use Industry: Chemical Manufacturing, Construction, Agriculture, Water Treatment Application: Flue Gas Treatment, Iron and Steel Production, Soil Stabilization, Acid Neutralization Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Graymont, Carmeuse, Lhoist Group, Mississippi Lime Company, Minerals Technologies Inc., American Elements, Heidelberg Materials, Calchem, CAO Industries Sdn Bhd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Oxide Market Emerging Trajectories
Calcination technology is fragmenting across three vectors: energy source substitution, emissions capture integration, and product specification stratification. These shifts are compressing the viable scale range for new entrants while rewarding incumbent producers with captive raw material positions.
Flash calcination systems using plasma torch ignition are hybridizing traditional rotary kiln throughput with electric heating precision. Specialty chemical producers in Belgium and the Netherlands adopt these units for pharmaceutical-grade output where temperature uniformity outweighs energy cost premiums. The technology is compressing the minimum efficient scale for high-purity production from 200,000 to 40,000 tonnes annually.
REACH heavy metal content restrictions for construction-grade quicklime are bifurcating European product streams into export and domestic compliance grades. German and Polish producers face elevated testing costs for lead and cadmium certification, while Italian and Spanish suppliers redirect non-compliant material to North African markets. The regulation is accelerating vertical integration between quarrying and calcination operations to control feedstock traceability.
Long-term offtake contracting is displacing spot procurement in municipal water treatment as utilities consolidate supplier panels. Regional distributors in the US Great Lakes and Ohio River corridors are capturing volume commitments through bundled chemical and equipment service agreements. The shift is most visible in Michigan and Wisconsin utilities where EPA lead and copper rule revisions demand consistent reagent quality documentation.
Calcium Oxide Market Segmentation
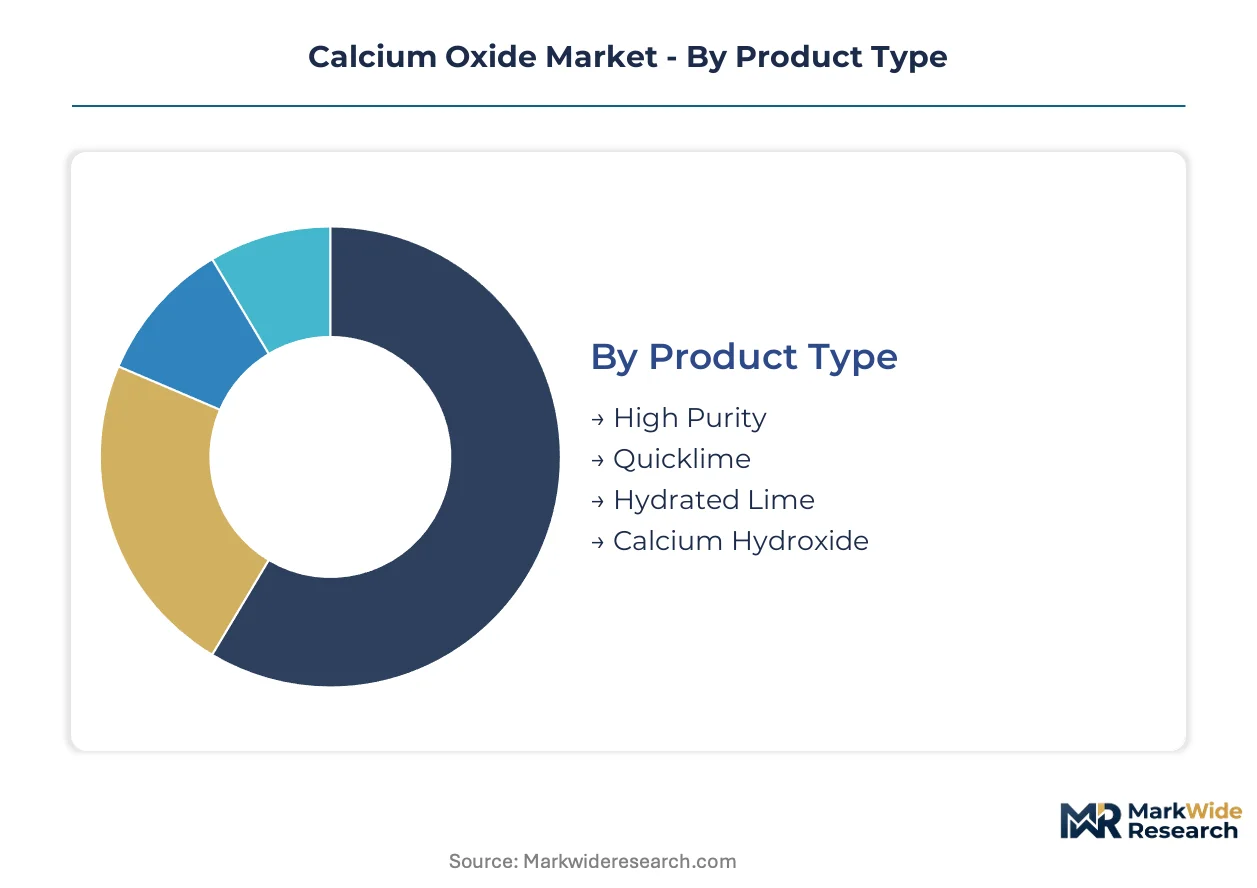
Calcium oxide market segmentation reveals how specification stratification and channel economics fragment margin pools across industrial versus specialty applications. Product purity tiers and end-use regulatory burdens create distinct competitive arenas with divergent capital intensity requirements.
Product Type:
Mature commodity grades dominate volume throughput while emerging specialty specifications capture expanding margin premiums in regulated downstream applications.
- High Purity:Ultra-low trace metal content below 50 ppm total impurities enables pharmaceutical-grade calcium salt synthesis and food additive production. German and Belgian chemical manufacturers drive procurement concentration as EFSA purity documentation requirements tighten. Specification premiums widen for producers with dedicated hydration and micronization lines.
- Quicklime:Standard CaO content of 90-95% with high reactivity upon slaking serves metallurgical fluxing and acid gas neutralization across heavy process industries. Steel mills in India's western industrial corridor and coastal China concentrate demand for bulk quicklime within 150 kilometers of limestone deposits.
- Hydrated Lime:Calcium hydroxide produced through controlled quicklime slaking delivers consistent particle sizing for municipal water treatment pH adjustment.
- Calcium Hydroxide:Finely milled hydrated lime grades specified for soil stabilization and construction lime mortars compete on regional distribution density.
Quicklime handles the majority of throughput; High Purity is expanding most quickly on share as pharmaceutical precursor demand accelerates.
End Use Industry:
Cost tier stratification separates capital-intensive integrated producers serving bulk industries from specialized merchants targeting compliance-heavy downstream sectors.
- Chemical Manufacturing:Precursor demand for calcium salts, bleaching powders, and caustic soda derivatives requires consistent reactivity specifications and batch traceability. REACH-registered producers in Poland and Spain capture volume from European specialty chemical formulators.
- Construction:Soil stabilization, asphalt modification, and masonry lime applications consume standard-grade quicklime with tolerance for moderate variability in reactivity. India's cement capacity expansion in Gujarat and Maharashtra concentrates procurement within rail-linked supply radii.
- Agriculture:Soil pH amendment and animal feed calcium supplementation demand cost-optimized hydrated lime with basic purity certification.
- Water Treatment:Municipal utilities specify hydrated lime for drinking water pH adjustment and wastewater neutralization, favoring regional distributors with storage terminal networks.
Chemical Manufacturing commands the highest specification premiums; Water Treatment is gaining share fastest as EPA lead and copper rule revisions drive consistent reagent quality documentation.
Application:
Customer type fragmentation separates spot-market commodity buyers from long-term offtake partners requiring integrated service bundling.
- Flue Gas Treatment:Dry sorbent injection and semi-dry scrubbing systems in coal-fired power plants and waste incinerators consume high-reactivity quicklime for SO2 and HCl capture. China's MEE emission standards enforcement is accelerating kiln technology upgrades among Shandong and Hebei suppliers.
- Iron and Steel Production:Basic oxygen furnace and electric arc furnace slag conditioning demands consistent CaO content above 92% with controlled residual CO2. German and Italian mills under EU Green Deal carbon border adjustments are expanding EAF capacity and associated flux consumption.
- Soil Stabilization:Highway construction and brownfield remediation projects specify quicklime for clay modification and load-bearing improvement.
- Acid Neutralization:Industrial wastewater and mine drainage treatment applications utilize hydrated lime for pH control.
Iron and Steel Production anchors volume demand; Flue Gas Treatment is climbing the fastest as carbon capture integration creates hybrid revenue streams.
Distribution Channel:
Supply concentration dynamics favor established networks with captive storage infrastructure over emerging digital procurement platforms.
- Direct Sales:Long-term offtake contracts with steel mills, cement plants, and chemical manufacturers integrate logistics planning with production scheduling. Graymont and Carmeuse leverage captive terminal networks across the Great Lakes for volume commitments.
- Distributors:Regional chemical distributors bundle reagent supply with slaking equipment leasing and technical service support, capturing municipal water treatment procurement consolidation in Michigan and Wisconsin.
- Online Sales:Digital platforms for hydrated lime and specialty grades remain limited to small-volume agricultural and construction customers.
- Retail:Bagged hydrated lime for consumer gardening and masonry applications represents marginal volume share.
Direct Sales commands the majority of value throughput; Distributors are gaining share fastest as utilities consolidate supplier panels and demand bundled service agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MEE carbon intensity benchmarks are restructuring calcination economics across major producing regions, while India's western industrial corridor expansion and EU Green Deal compliance deadlines are redrawing procurement patterns for metallurgical and chemical-grade quicklime.
China
Shandong and Hebei provinces control over half of Asia-Pacific export capacity for standard-grade quicklime, with coastal mills driving flux demand for steel pelletization. MEE enforcement of dual carbon timelines is forcing rotary kiln abandonment for oxy-fuel and electric arc alternatives. Qingdao and Tianjin terminals anchor merchant supply to Japanese and South Korean steelmakers.
India
Gujarat and Maharashtra cement capacity additions concentrate demand for high-reactivity quicklime within 200 kilometers of limestone deposits in the western industrial corridor. BIS certification requirements for construction-grade material are tightening feedstock traceability standards. The Dahej and Hazira chemical complexes are expanding specialty chemical precursor procurement.
Germany
Electric arc furnace slag conditioning demand is climbing as EU Green Deal carbon border adjustments reshape German and Italian mill flux procurement. ECHA REACH heavy metal documentation for construction-grade quicklime is elevating testing costs for lead and cadmium certification. The Ruhr industrial basin maintains integrated quarry-to-kiln operations for steel sector supply security.
United States
EPA Maximum Achievable Control Technology standards for lime kiln particulate emissions are compelling Great Lakes producers to retrofit scrubber systems or face operating curtailments. The Ohio River corridor and Michigan utilities are consolidating supplier panels through bundled chemical and equipment service agreements. Graymont and Carmeuse leverage captive terminal networks for long-term offtake commitments.
Saudi Arabia
Jubail and Yanbu chemical complex expansions lack captive limestone, creating import-dependent demand for GCC producers with Red Sea terminal access. SFDA food-grade certification requirements are opening specification premiums for pharmaceutical precursor supply. The industrial city buildout is attracting merchant quicklime from UAE and Jordanian calcination facilities.
Calcium Oxide Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a market structure that rewards captive raw material positions and punishes merchant exposure to energy volatility. The vendor base clusters around three strategic archetypes: integrated producers with quarry-to-terminal control, specialty chemical merchants serving pharmaceutical and food-grade specifications, and regional distributors bundling reagent supply with equipment leasing. Dominant competitive moves include backward integration into limestone reserves and geographic expansion through marine terminal networks.
Within the integrated producer tier, Graymont and Carmeuse exemplify channel control through captive storage infrastructure across the Great Lakes and Ohio River corridors. Lhoist Group occupies a position on the specialty-grade vector, representing the high-purity archetype for pharmaceutical and chemical precursor applications. These three anchors demonstrate how specification stratification and logistics integration separate margin pools in merchant versus captive supply configurations.
| Leading Market Players |
|---|
| Graymont |
| Carmeuse |
| Lhoist Group |
| Mississippi Lime Company |
| Minerals Technologies Inc. |
| American Elements |
| Heidelberg Materials |
| Calchem |
| CAO Industries Sdn Bhd |
| Others |
Supply Flow & Price Mechanics
Natural gas price volatility determines both pricing tier spreads and supply chain shape in calcium oxide markets, forcing merchant producers to absorb Henry Hub and TTF benchmark swings while integrated operators with captive limestone reserves capture margin stability. Contract structures bifurcate between long-term offtake agreements favored by steel mills and municipal utilities versus spot procurement for construction-grade material, with energy cost pass-through clauses becoming the decisive negotiation lever.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade and construction-grade quicklime, with EFSA documentation requirements and REACH heavy metal thresholds commanding specification premiums. Pricing stratifies across premium, standard, and economy tiers based on purity grade, reactivity consistency, and geographic delivery cost. Cost compression in standard-grade quicklime is intensifying because hydrated lime substitution in water treatment compresses merchant demand. Municipal utilities exhibit highest price sensitivity due to consolidated supplier panels and bundled service procurement, while pharmaceutical formulators show lowest sensitivity given ultra-low trace metal requirements.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are emerging as competitive tools for distributors serving cash-constrained municipal utilities in Michigan and Wisconsin. Production concentrates in China, India, and Germany, with Shandong and Hebei provinces controlling over half of Asia-Pacific export capacity. Feedstock draws from high-calcium limestone deposits, metallurgical coke for kiln fuel, and specialized refractory linings. Single-source vulnerability concentrates in coastal China terminals where MEE enforcement actions disrupt export flows. Distribution runs through captive marine terminal networks for bulk industrial buyers and regional chemical distributors for water treatment segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated procurement panels at municipal utilities and integrated steel mills, fragmenting margin pools for merchant producers while rewarding channel controllers with long-term offtake security.
For Market Incumbents: Entrench position through backward integration into captive limestone reserves in the Great Lakes and Ohio River corridors, securing feedstock traceability against REACH documentation requirements. Expand terminal storage density to capture bundled service agreements from consolidating utilities facing EPA lead and copper rule revisions. Prioritize oxy-fuel kiln retrofits ahead of MEE carbon intensity enforcement timelines. For New Entrants and Emerging Players: Build out specialty high-purity production capacity serving pharmaceutical precursor demand in Belgium and the Netherlands, where flash calcination technology compresses minimum efficient scale. Target Indonesia's nickel processing boom for HPAL pH neutralization reagents, where domestic lime capacity falls short of refinery requirements. Pursue asset-light leasing arrangements for slaking equipment to narrow capital barriers for mid-scale chemical complex supply. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors integrated producers with captive raw material positions and emission-compliant kiln assets. Long-term viability over the coming decade rests on control of coastal terminal access and carbon-capture integration capabilities. Watch for MEE enforcement acceleration in Shandong and Hebei as the inflection signal for supply restructuring and import substitution opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Reserves | Graymont's captive Great Lakes quarries secure supply security against REACH traceability mandates. |
| Oxy-Fuel Kiln Technology Transition | Chinese producers abandoning rotary kilns for MEE compliance fragment cost structures between coastal and inland operations. |
| Long-Term Offtake Contracting | Carmeuse leverages Ohio River terminal networks to capture bundled agreements from consolidating Michigan utilities. |
| Carbon Capture Integration | Post-combustion calcium looping hybridizes quicklime production with CO2 mineralization revenue streams at cement plants. |
| Specialty High-Purity Capacity Buildout | Lhoist Group's dedicated hydration lines capture EFSA-grade pharmaceutical precursor premiums in Belgian chemical manufacturing. |
Methodological Framework
The analysis maps quicklime, hydrated lime, and high-purity calcium oxide sub-sectors, each validated through kiln operations managers, steel mill procurement leads, municipal utility chemical buyers, and specialty chemical formulators. Primary interviews with plant engineers and distribution channel partners combined with secondary validation from ECHA REACH registrations, EPA MACT compliance filings, China MEE carbon intensity benchmarks, and SEC 10-K disclosures from listed producers. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates across the projection horizon.
Assumptions held MEE enforcement timelines and EU Green Deal carbon border adjustment implementation as fixed regulatory conditions, while natural gas price trajectories and electric arc furnace capacity buildout rates varied across sensitivity scenarios. Segmentation modeling spanned purity grade tiers, end-use industries, and regional production hub clusters. CAGRs derived from installed capacity expansion schedules and downstream demand elasticity coefficients for steel fluxing, cement additive, and pharmaceutical precursor applications.
The forecast holds incumbent behavior within observed patterns; aggressive moves by merchant traders or flash calcination technology specialists would shift outcomes. Macroeconomic deviation in construction activity, regulatory acceleration in kiln emission standards, or breakthroughs in electric calcination efficiency would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Ceramics Market
Ceramics
West Africa Ceramic Tiles Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
White Fused Alumina Market
Ceramics
Co-Fired Ceramic Market
Ceramics
USA and Canada Alumina Market
Ceramics
Construction Ceramics Market
Ceramics
Calcium Aluminosilicate Market
Ceramics
Global Functional Ceramics Market
Ceramics
Calcined Kaolin Market
Ceramics
Ceramic Frit Market
Ceramics
Refractories Market
Ceramics
Global Zirconia Oxygen Sensors Market
Ceramics
North America Barium Carbonate Market
Ceramics
Pyrolytic Boron Nitride Market
Ceramics
China Clay Market