
 Glass Substrate Market | 2026-2036
Glass Substrate Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Substrate Market Analysis
South Korea is fragmenting as domestic and foreign substrate makers expand competing fabs near Seoul and Pyeongtaek. Samsung Electro-Mechanics leverages its captive semiconductor supply chain to secure preferred customer status among domestic chipmakers. Corning Incorporated anchors North American supply through specialized fusion-draw capacity serving high-performance display markets. SCHOTT AG differentiates via deep specialization in borosilicate and aluminosilicate formulations for optical and pharmaceutical-grade applications.
Glass substrate denotes a rigid, dimensionally stable sheet manufactured from soda-lime, borosilicate, or alkali-free compositions, typically produced through float, fusion-draw, or down-draw processes with controlled thickness tolerances ranging from sub-millimeter to several millimeters. These substrates serve as foundational platforms for thin-film transistor arrays, semiconductor interposers, photovoltaic cells, and precision optical assemblies where thermal stability and surface flatness prove critical. Float glass dominates volume production for cost-sensitive display and solar applications, while coated glass commands premium positioning in anti-reflective and conductive-layer deployments for advanced electronics. Chemical vapor deposition technology leads capital allocation among substrate makers seeking atomic-level film uniformity for next-generation chip packaging.
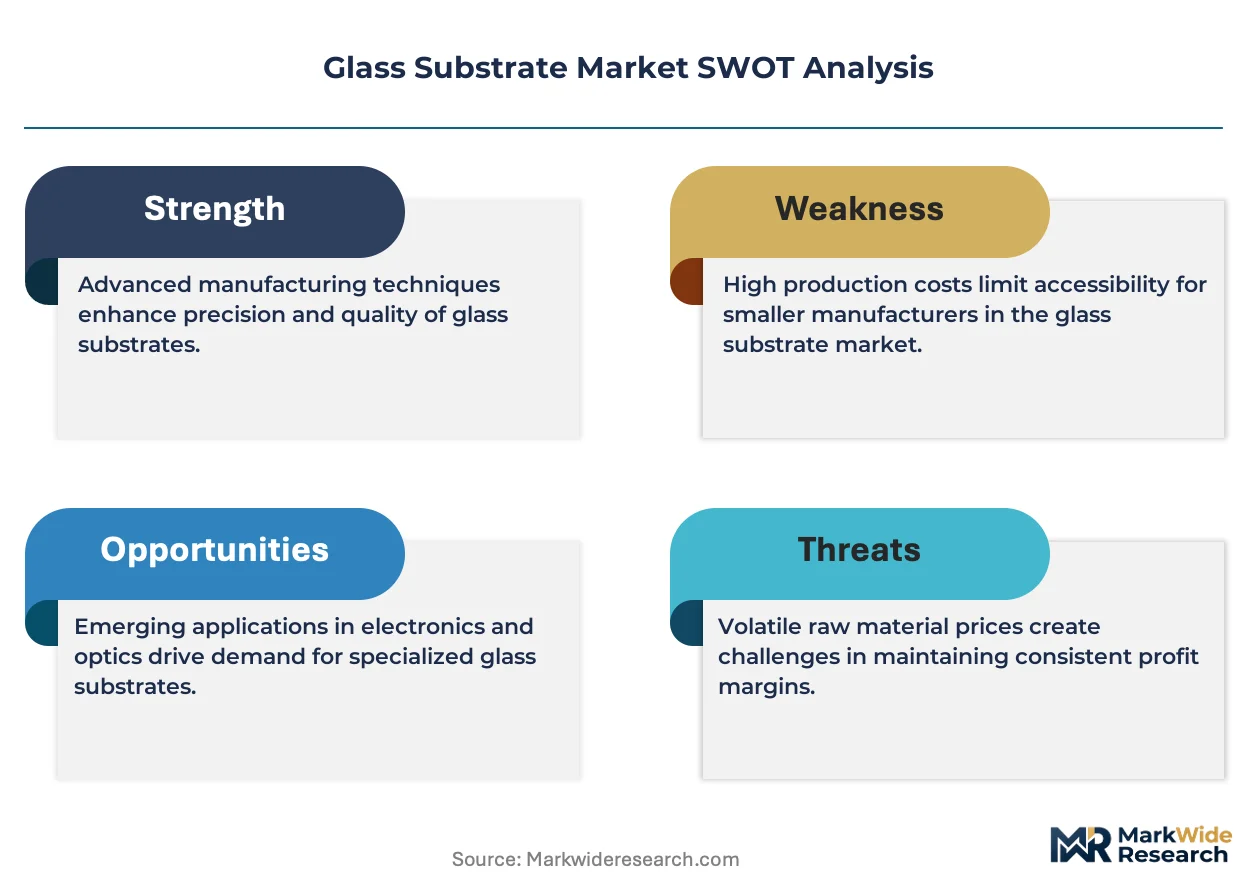
Japan's METI enforces stringent energy-efficiency standards that constrain legacy melting furnace operations, while South Korea's environmental ministry imposes carbon-intensity caps on heavy industrial glass production. REACH compliance in Europe restricts certain heavy-metal additives in specialty glass formulations, redirecting R&D toward halogen-free alternatives. Stakeholders must monitor how substrate makers reconcile tightening environmental compliance with the ultra-low thermal expansion coefficients demanded by advanced semiconductor packaging architectures.
Market Dynamics
Semiconductor packaging architectures are forcing substrate makers to reconcile ultra-low thermal expansion coefficients with tightening carbon-intensity caps across East Asian manufacturing clusters. This structural tension between performance specifications and environmental compliance is redrawing competitive boundaries.
Growth Catalysts
- China's dual carbon goals:Mandatory energy-efficiency benchmarks are accelerating furnace upgrades and fusion-draw technology deployment among domestic producers.
- Advanced interposer demand:Chiplet-based semiconductor designs require glass substrates with sub-ppm thermal expansion tolerances for heterogeneous integration.
- South Korea's display ecosystem:Dense clustering of OLED and quantum-dot manufacturing near Seoul and Pyeongtaek generates captive demand for alkali-free substrate supply.
Market Restraints
- Fused silica supply concentration:High-purity quartz feedstock remains concentrated among limited specialty chemical suppliers, exposing substrate makers to input volatility.
- Japan's METI furnace standards:Stringent energy-efficiency mandates constrain legacy melting operations and extend capital replacement cycles.
- Organic substrate competition:Advanced ABF and buildup laminates continue displacing glass in cost-sensitive mobile packaging applications.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for semiconductor and display manufacturing are attracting substrate makers to establish localized supply.
- Photonic integrated circuits:Silicon photonics packaging requires ultra-low-loss glass interposers with precision waveguide patterning capabilities.
- EU Green Deal procurement:Public sector buying mandates for low-carbon materials create preferential access for substrates with verified lifecycle emissions data.
Industry Challenges
- Fusion-draw engineering talent:The specialized skill set for controlling molten glass ribbon formation at atomic-scale tolerances remains scarce outside established manufacturing clusters.
- REACH halogen-free transition:European restrictions on heavy-metal additives demand reformulation of specialty glass compositions without compromising optical or thermal properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Substrate Market |
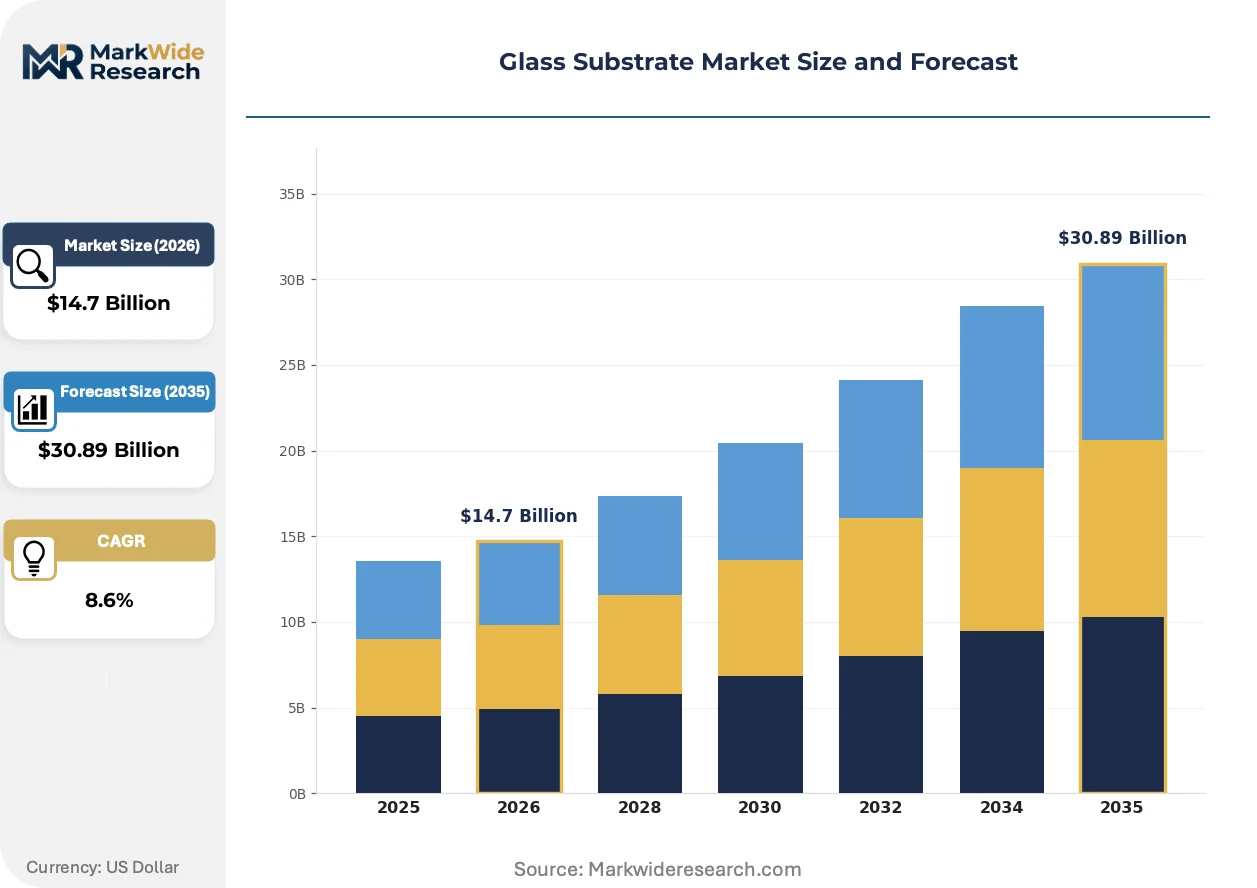
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
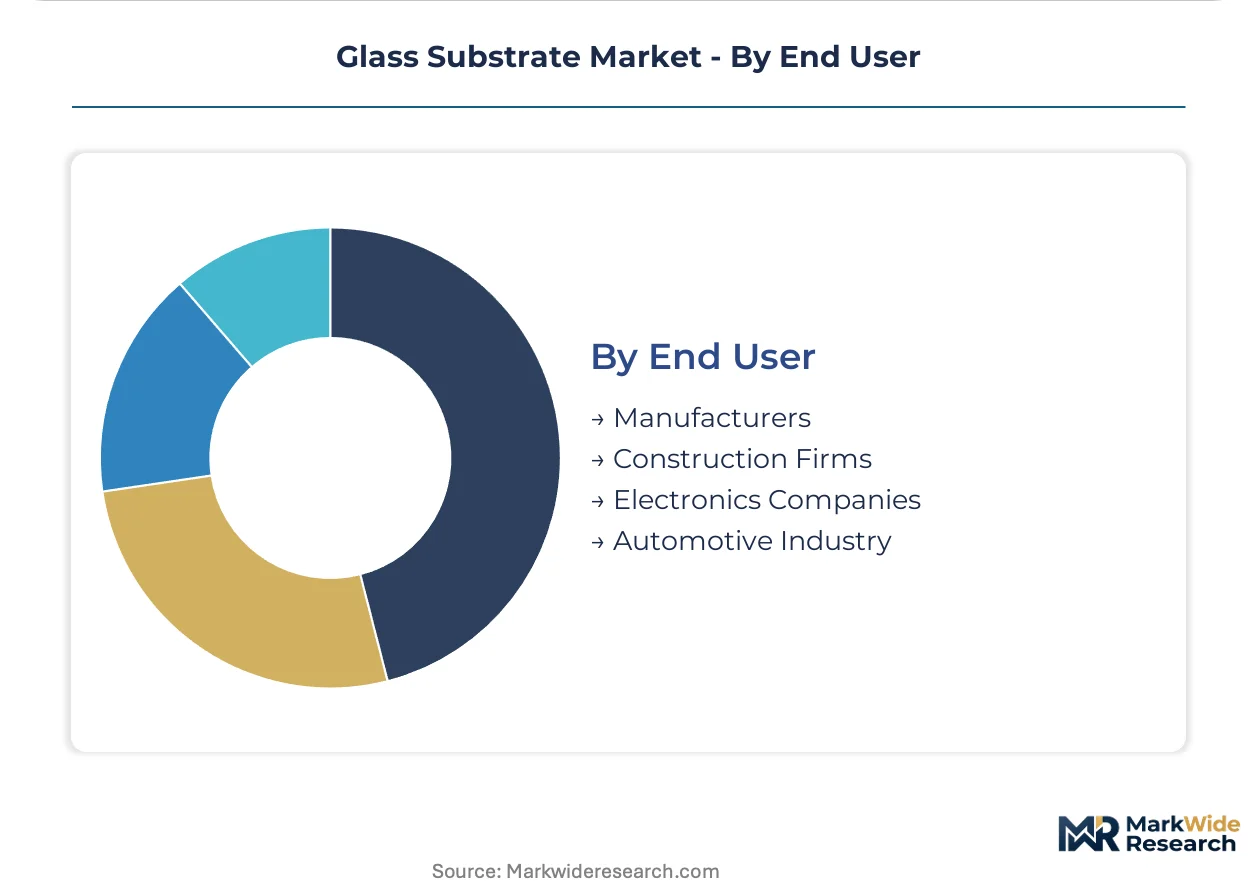
| Segmentation | Product Type: Float Glass, Coated Glass, Tempered Glass, Laminated Glass Technology: Screen Printing, Chemical Vapor Deposition, Physical Vapor Deposition, Laser Cutting Application: Electronics, Solar Cells, Optics, Automotive End User: Manufacturers, Construction Firms, Electronics Companies, Automotive Industry |
| Companies Covered | Nippon Electric Glass, Samsung Electro-Mechanics, Corning Incorporated, BOE, HOYA Corporation, AGC Inc., Absolics, LG Innotek, SCHOTT AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Substrate Market Emerging Trajectories
Digital process control and predictive quality systems are penetrating substrate manufacturing floors, compressing defect rates and enabling thickness uniformity at angstrom-scale precision. This automation wave is redefining capital deployment priorities across the value chain.
Chemical vapor deposition coating systems are digitizing quality assurance workflows across South Korean and Japanese display substrate fabs. Samsung Display and LG Display have integrated inline spectroscopic monitoring that adjusts gas flow parameters in real time. This closed-loop control is digitizing yield management and reducing offline inspection bottlenecks that previously constrained throughput.
REACH compliance deadlines are forcing reformulation of borosilicate and aluminosilicate compositions used in pharmaceutical and optical-grade substrates. ECHA restrictions on arsenic and antimony refining aids are redirecting R&D toward cerium-based alternatives. Specialty glass makers serving European medical device and analytical instrument markets are accelerating halogen-free certification timelines to maintain preferred supplier status.
Consolidated procurement by semiconductor foundries is compressing supplier qualification cycles and unbundling technical service from material supply contracts. TSMC and Intel have established centralized substrate qualification labs that bypass traditional distributor technical support. This direct engagement model is most visible in Taiwan and Arizona, where foundry ecosystem concentration enables volume-commitment pricing without channel intermediation.
Glass Substrate Market Segmentation
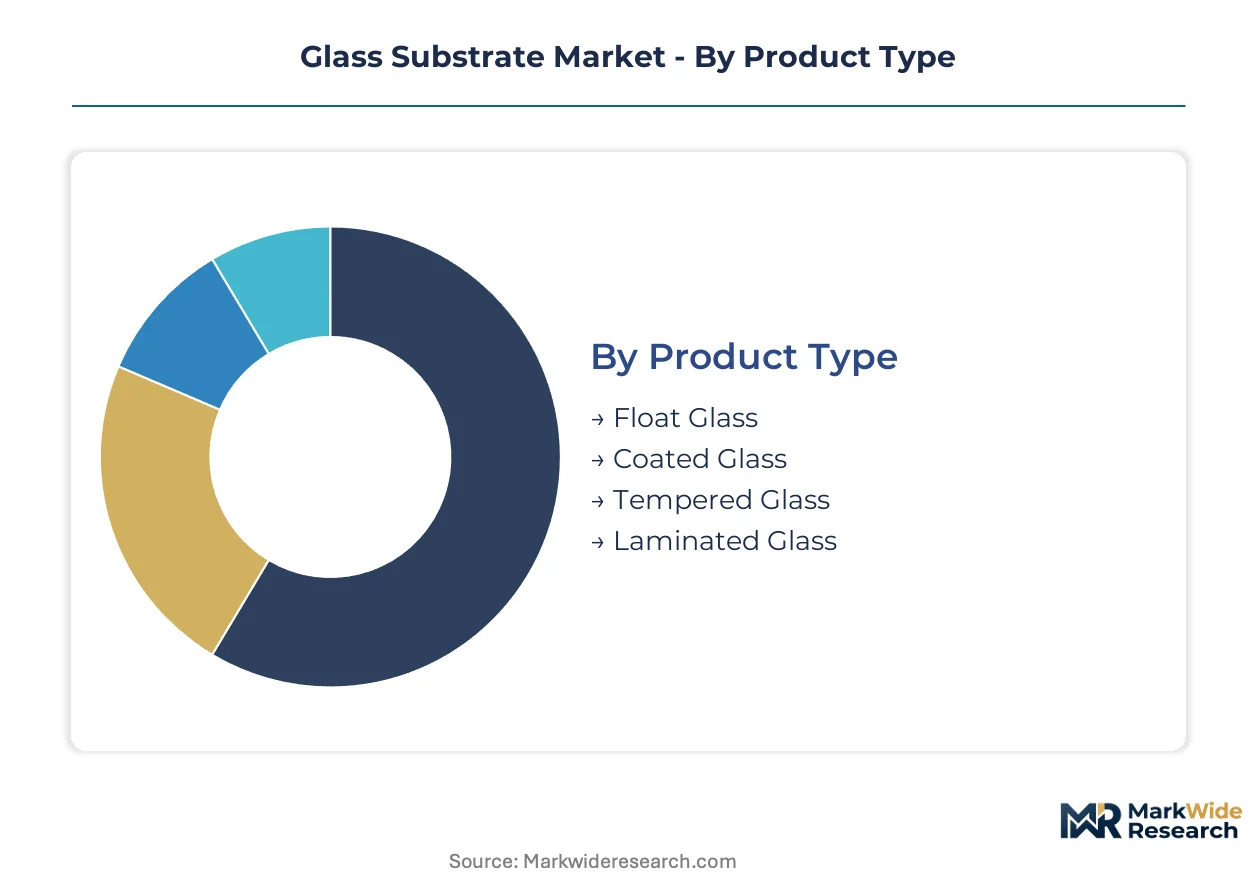
Glass substrate segmentation reveals how manufacturing process economics and end-use performance requirements create distinct competitive arenas. Each dimension carries implications for capital intensity, customer qualification cycles, and margin architecture.
Product Type:
Mature float processes dominate volume economics while emerging specialty formats capture premium positioning in advanced applications.
- Float Glass:Molten glass spreads across molten tin baths to achieve uniform thickness with minimal surface defects. Display panel manufacturers in South Korea and Japan source float substrates for cost-sensitive TFT-LCD backplanes where dimensional tolerances permit slight variation.
- Coated Glass:Thin-film layers deposited via CVD or PVD impart conductive, anti-reflective, or barrier properties. Semiconductor packaging demand concentrates here as chiplet architectures require substrates with precisely engineered surface chemistries for interposer bonding.
- Tempered Glass:Thermal or chemical strengthening creates compressive surface layers for mechanical durability. Automotive HUD and infotainment systems specify tempered substrates for vibration resistance.
- Laminated Glass:Interlayer bonding of multiple glass sheets enhances structural integrity and safety performance. Architectural and specialized transportation applications specify laminated constructions.
Float glass handles the majority of throughput; coated glass is the fastest mover on share.
Technology:
Cost tier differentiation separates high-volume patterning methods from precision deposition systems commanding 3-5x capital intensity per unit output.
- Chemical Vapor Deposition:Gas-phase precursor reactions deposit angstrom-scale films with exceptional uniformity. South Korean display fabs deploy CVD for OLED encapsulation layers where pinhole density directly impacts device lifetime.
- Screen Printing:Mesh-based stencil deposition applies thick-film pastes and coatings at throughputs exceeding 1000 substrates per hour. Solar cell manufacturers favor screen printing for metallization patterns on photovoltaic glass.
- Physical Vapor Deposition:Sputtering and evaporation techniques deposit metals and dielectrics in vacuum environments. Optical filter manufacturers specify PVD for precision wavelength-selective coatings.
- Laser Cutting:Non-contact material removal enables complex geometries without mechanical stress. MicroLED display development relies on laser dicing for die singulation from glass carrier wafers.
Screen printing sustains the highest unit volumes; CVD is climbing the fastest as advanced packaging specifications tighten.
Application:
Customer type segmentation tracks how procurement authority and technical specification control vary across downstream industries.
- Electronics:TFT arrays, interposers, and MEMS substrates demand sub-ppm thermal expansion matching silicon. TSMC and Intel qualification protocols govern material selection here.
- Solar Cells:Front glass for crystalline and thin-film modules prioritizes transmission efficiency and weathering resistance. China's dual carbon goals are accelerating domestic capacity expansion for photovoltaic substrate supply.
- Optics:Precision flatness and homogeneity specifications serve lithography, laser systems, and analytical instruments. SCHOTT AG and Corning dominate this niche through proprietary fusion-draw expertise.
- Automotive:HUD combiners, display covers, and sensor windows integrate glass substrates with stringent safety certifications. NHTSA and EU type-approval standards govern optical quality and fragmentation behavior.
Electronics commands the dominant revenue share; solar applications are expanding most quickly on policy-driven installation targets.
End User:
Supply concentration patterns differ markedly between captive integrated producers and merchant substrate purchasers.
- Electronics Companies:Samsung Display and LG Display operate captive glass processing for internal OLED manufacturing. These integrated buyers source raw float or fusion-draw substrates for downstream patterning.
- Manufacturers:Merchant substrate specialists serve diversified industrial customers without internal glass capabilities. Construction and appliance OEMs rely on this channel for standardized sheet supply.
- Construction Firms:Architectural glazing projects specify laminated and tempered formats for safety compliance. Regional fabricators dominate procurement relationships here.
- Automotive Industry:Tier-1 suppliers like AGC and NSG Group supply directly to vehicle assembly programs. JIT delivery requirements favor geographically proximate substrate conversion facilities.
Electronics companies internalize the largest substrate volumes; merchant manufacturers are gaining procurement leverage fastest through consolidated specification standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan handles the majority of specialty glass feedstock entering East Asian substrate fabrication clusters, underwriting the region's concentration of advanced display and semiconductor packaging capacity.
China
Photovoltaic module manufacturing and domestic OLED panel production drive substrate consumption in Jiangsu and Guangdong provinces. MIIT enforces GB standards on industrial energy consumption that compel furnace technology upgrades among domestic glassmakers. The Yangtze River Delta hosts expanding alkali-free substrate capacity serving BOE and other display panel manufacturers.
South Korea
Chiplet-based semiconductor architectures and quantum-dot display manufacturing generate demand for ultra-low thermal expansion substrates. The environmental ministry imposes carbon-intensity caps on heavy industrial glass production that reshape melting furnace economics. Pyeongtaek and the Seoul Capital Area concentrate competing substrate fabs from Samsung Electro-Mechanics and foreign entrants.
Japan
Precision optical instruments and lithography systems require borosilicate substrates with sub-nanometer surface flatness. METI enforces stringent energy-efficiency standards that constrain legacy melting furnace operations and extend capital replacement cycles. The Chubu region around Nagoya maintains fusion-draw expertise clusters serving analytical instrument and laser system manufacturers.
United States
Defense photonics programs and silicon photonics packaging drive demand for ultra-low-loss glass interposers. NHTSA safety standards govern automotive HUD substrate specifications for vibration resistance and optical clarity. Arizona's semiconductor foundry ecosystem attracts substrate qualification labs from TSMC and Intel that bypass traditional distributor channels.
Germany
Pharmaceutical-grade packaging and analytical instrumentation sustain demand for aluminosilicate substrates with halogen-free certification. REACH compliance deadlines restrict arsenic and antimony refining aids, redirecting R&D toward cerium-based alternatives. Baden-Württemberg's precision engineering clusters source specialty glass from SCHOTT AG for medical device and industrial laser applications.
Glass Substrate Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply architecture. The vendor base stratifies across three tiers: captive display divisions, merchant specialty glassmakers, and emerging semiconductor-focused entrants. Strategic archetypes include fusion-draw technology guardians, alkali-free formulation specialists, and CVD coating system integrators. Capacity expansion and direct foundry qualification partnerships represent the dominant competitive moves reshaping procurement relationships.
Among East Asian electronics conglomerates, Samsung Electro-Mechanics and LG Innotek occupy positions that exemplify captive integration strategies, while Corning Incorporated anchors North American supply through specialized manufacturing assets. SCHOTT AG represents the European specialist archetype, with deep formulation expertise in borosilicate and aluminosilicate compositions serving pharmaceutical and optical-grade applications.
| Leading Market Players |
|---|
| Nippon Electric Glass |
| Samsung Electro-Mechanics |
| Corning Incorporated |
| BOE |
| HOYA Corporation |
| AGC Inc. |
| Absolics |
| LG Innotek |
| SCHOTT AG |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on high-purity quartz feedstock from limited specialty chemical suppliers determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic clustering of fusion-draw capacity near East Asian manufacturing hubs. This input concentration compresses margin architecture at the standard tier while amplifying premium capture for substrates with verified lifecycle emissions data.
Pricing Analysis
Volume-discount tiering structures dominate procurement relationships between semiconductor foundries and substrate makers, with TSMC and Intel leveraging centralized qualification labs to extract favorable contract terms through volume-commitment pricing. Price differentiation rests on thermal expansion coefficient certification grades and geographic delivery cost to Arizona and Taiwan fab clusters. Cost compression in standard-grade float glass is intensifying because Chinese domestic capacity expansion under MIIT energy-efficiency mandates is flooding cost-sensitive display applications. Merchant manufacturers exhibit the highest price sensitivity, while captive integrated producers like Samsung Display absorb premium pricing for alkali-free formulations.
Supply Chain Analysis
Contract-manufacturing concentration among Samsung Electro-Mechanics and LG Innotek in South Korea, alongside Corning's specialized fusion-draw facilities in the United States, anchors global supply for high-performance applications. Raw material dependencies draw from high-purity quartz deposits, borosilicate precursor chemicals, and cerium-based refining aids replacing restricted arsenic compounds. Single-source vulnerability on fused silica feedstock exposes substrate makers to input volatility when specialty chemical suppliers face production constraints. Distribution runs through direct foundry engagement models that bypass traditional distributor channels in Taiwan and Arizona semiconductor clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase driven by chiplet-based semiconductor architecture deployment, which is generating captive demand for ultra-low thermal expansion substrates after a prolonged period of organic substrate displacement in mobile packaging.
For Market Incumbents: Pre-empt emerging entrant challenges from India's PLI scheme beneficiaries by accelerating captive supply of halogen-free borosilicate formulations before REACH compliance deadlines tighten. Defend margin position through backward integration into high-purity quartz sourcing and capacity addition in Pyeongtaek to serve Samsung's quantum-dot display ecosystem. Certification investment in EU Green Deal procurement standards represents the critical lever for preferred supplier status. For New Entrants and Emerging Players: Establish a beachhead in photonic integrated circuit packaging, where silicon photonics demand for ultra-low-loss glass interposers remains underpenetrated by incumbent specialists. Target India's semiconductor and display manufacturing zones under PLI incentives, where localized substrate supply lacks established fusion-draw expertise. A technical qualification partnership with TSMC or Intel's Arizona labs offers the most credible go-to-market angle for bypassing traditional channel intermediation. For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors acquisition of CVD coating system integrators with atomic-scale film uniformity capabilities. Long-term viability over the next decade hinges on environmental compliance differentiation rather than scale alone. The signal to watch is carbon-intensity cap enforcement progression across South Korea and Japan, which will determine which substrate makers can maintain premium positioning without furnace technology write-downs.| Strategic Initiative | Industry Significance |
|---|---|
| Fusion-Draw Capacity Expansion | Samsung Electro-Mechanics strengthens captive supply for domestic chipmakers near Seoul and Pyeongtaek. |
| Halogen-Free Formulation Transition | SCHOTT AG accelerates cerium-based refining aid adoption to maintain REACH compliance for pharmaceutical-grade substrates. |
| Direct Foundry Qualification Partnership | TSMC and Intel's centralized substrate labs in Arizona bypass distributor channels for volume-commitment pricing. |
| Backward Integration into Feedstock | Corning secures high-purity quartz supply chains against specialty chemical supplier concentration risk. |
| EU Green Deal Certification Investment | Substrate makers with verified lifecycle emissions data gain preferential access to public sector procurement mandates. |
Methodological Framework
Operator-level perspectives from fusion-draw process engineers, semiconductor packaging procurement leads, display fab operations managers, and specialty glass R&D directors anchored the qualitative base for this study. Primary interview insights combined with secondary validation from SEC filings of listed substrate makers, MIIT industrial energy consumption disclosures, ECHA REACH restriction updates, and customs trade data for high-purity quartz imports. Bottom-up capacity modeling across South Korean, Japanese, Chinese, and North American manufacturing clusters triangulated against top-down demand estimates from semiconductor foundry capex plans and display panel shipment forecasts.
Scenario-bracketing around carbon-intensity cap enforcement timelines and chiplet architecture adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include substrate product type, deposition technology, end-use application, and customer procurement archetype. CAGRs derived from installed capacity expansion schedules, furnace technology upgrade cycles, and foundry substrate qualification pipeline visibility. Industry-specific forecast inputs incorporated METI energy-efficiency standard compliance costs and EU Green Deal procurement mandate implementation progress.
Stress conditions across quartz feedstock price volatility, REACH halogen-free transition timelines, and organic substrate substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on technology adoption curves and regulatory enforcement intensity. Quarterly review of semiconductor foundry substrate qualification announcements and environmental ministry carbon-intensity cap adjustments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Global Glass Flake Coatings Market
Glass
Global Ultra-Thin Glass Market
Glass
Glass Polishing Powder Market
Glass
Glazing Gel Market
Glass
North America Glass Insulators Market
Glass
Glass Like Carbon Market
Glass
Insulated Glass Market
Glass
Glass Insulator Market
Glass
Glass Balustrade Lamination Market
Glass
Foam Glass Granulate Market
Glass
Laboratory Glassware Market
Glass
Coated Solar Control Glass Market
Glass
Tempered Glass Market
Glass
North America Flat Glass Market
Glass
Float Glass Market
Glass
Europe Flat Glass Market