
 Ceramic Solid End Mills Market | 2026-2036
Ceramic Solid End Mills Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Solid End Mills Market Insights
Ultra-precision grade specifications is collapsing the gap between ceramic and carbide performance in high-speed machining centers. Sandvik leverages its captive powder metallurgy capabilities to control raw material consistency from mine to finished insert. Mitsubishi Materials anchors its position through proprietary silicon nitride formulations optimized for interrupted cuts in aerospace turbine blades. Kennametal competes on scale, operating integrated ceramic pressing and sintering lines across multiple continents.
Ceramic solid end mills are monolithic rotary cutting tools fabricated from advanced ceramic materials such as silicon nitride or alumina-zirconia composites, typically featuring diameters from 0.5 mm to 20 mm and operating at cutting speeds exceeding 600 m/min in hardened steels and heat-resistant superalloys. Their primary purpose is to enable dry or near-dry machining of materials that thermally degrade conventional carbide tools, reducing cycle times in aerospace and medical component production. Square and ball nose geometries dominate current volume, with corner radius variants capturing expanding share in mold and die applications where edge strength determines tool life. Silicon nitride material grades lead in thermal shock resistance for cast iron machining, while zirconia-toughened alumina compositions extend into medical device finishing where surface integrity requirements are most stringent.
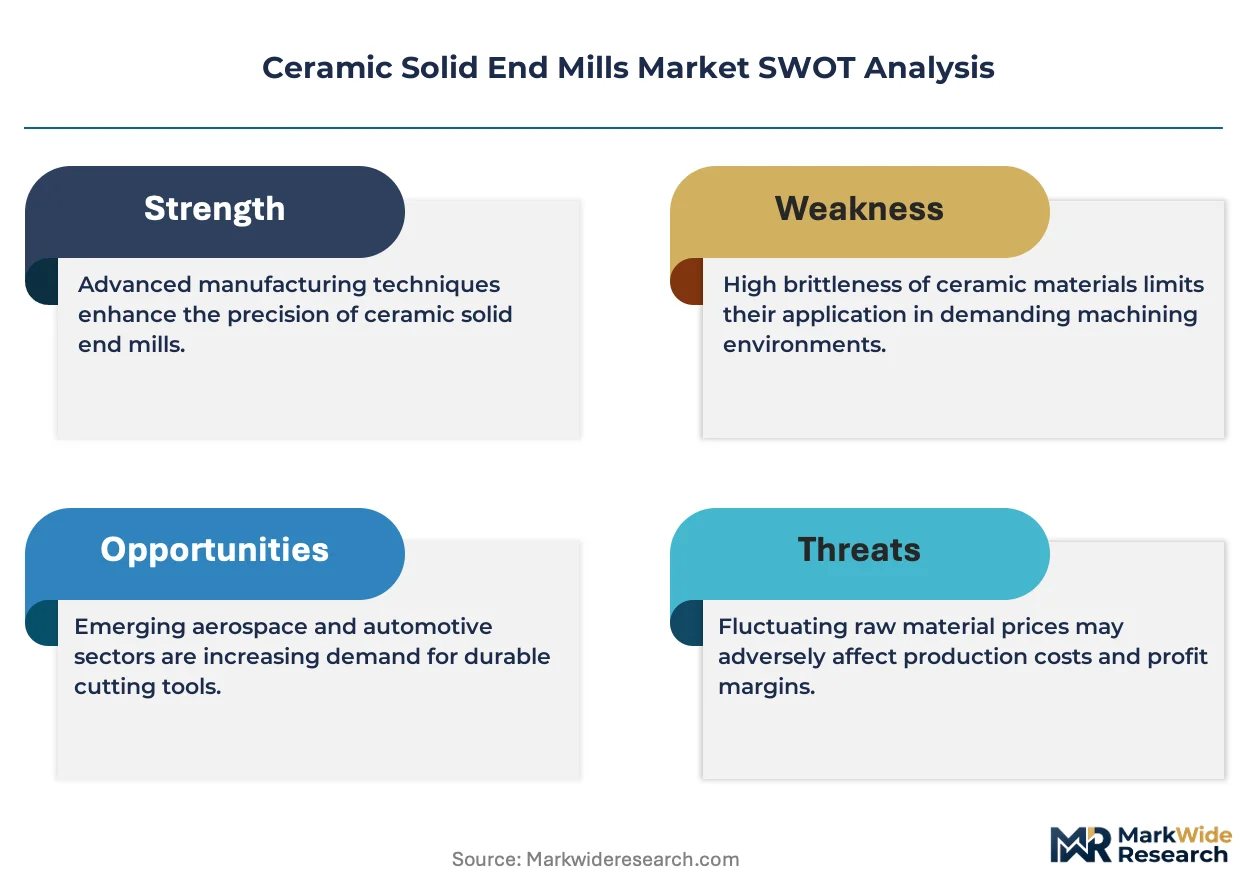
ISO standards for tool nomenclature and cutting data exchange, REACH regulations governing ceramic powder handling and sintering additives in Europe, and FDA quality system requirements for medical device cutting tools collectively elevate compliance costs while creating barriers to unqualified suppliers. Japan's METI industrial standards and Germany's KBA automotive certification pathways further fragment approval requirements for tool vendors seeking cross-sector placement. Stakeholders must monitor evolving sustainability mandates for ceramic waste recycling and energy-intensive sintering processes as these factors increasingly influence procurement criteria and facility siting decisions.
Market Dynamics
Aerospace manufacturers are forcing ceramic solid end mills into superalloy machining workflows previously dominated by carbide, compressing acceptable thermal limits and reshaping supplier qualification criteria across precision component supply chains.
Growth Catalysts
- Nickel-based superalloy machining demand:Aerospace engine programs in Switzerland and South Korea require cutting speeds above 600 m/min that thermally degrade carbide, pulling silicon nitride tools into turbine blade finishing operations.
- ISO 13399 tool data standardization:Unified digital nomenclature for cutting tool parameters reduces engineering validation cycles, accelerating cross-border procurement between German automotive suppliers and Japanese machine tool builders.
- Dry machining mandates:REACH chemical restrictions on metalworking fluid disposal in Europe eliminate flood-cooling dependencies, positioning ceramic end mills as compliant alternatives for hardened steel component production.
Market Restraints
- Raw material concentration:High-purity silicon nitride powder production concentrates in Chinese and Japanese suppliers, exposing tool manufacturers to export quota volatility and quality batch inconsistency.
- Carbide performance convergence:Coated carbide grades with nanolayer thermal barriers now operate at 400-450 m/min, narrowing the speed gap that justifies ceramic's brittleness premium in general machining.
- Sintering energy intensity:Gas-pressure sintering furnaces require 48-hour thermal cycles at 1800°C, locking producers into regions with stable industrial electricity pricing and complicating capacity expansion.
Strategic Opportunities
- Medical device finishing expansion:Zirconia-toughened alumina compositions meet FDA surface integrity requirements for orthopedic implant machining, opening precision component contracts with Swiss and US device manufacturers.
- Additive manufacturing hybrid workflows:Near-net-shape metal 3D printing leaves 0.3-0.5 mm stock allowances requiring high-speed finishing, matching ceramic end mill capabilities in aerospace repair depots.
- Japan METI green procurement incentives:Public funding for energy-efficient manufacturing equipment favors dry machining technologies, creating preferential placement channels for ceramic tooling in domestic supply chains.
Industry Challenges
- Ceramic-specific CAM programming expertise:Toolpath strategies for brittle materials differ fundamentally from carbide conventions, and machine shop engineering teams lack training infrastructure for safe speed/feed parameter selection.
- Multi-standard certification timelines:Concurrent pursuit of KBA automotive approval, FDA medical device registration, and aerospace NADCAP accreditation extends product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Solid End Mills Market |
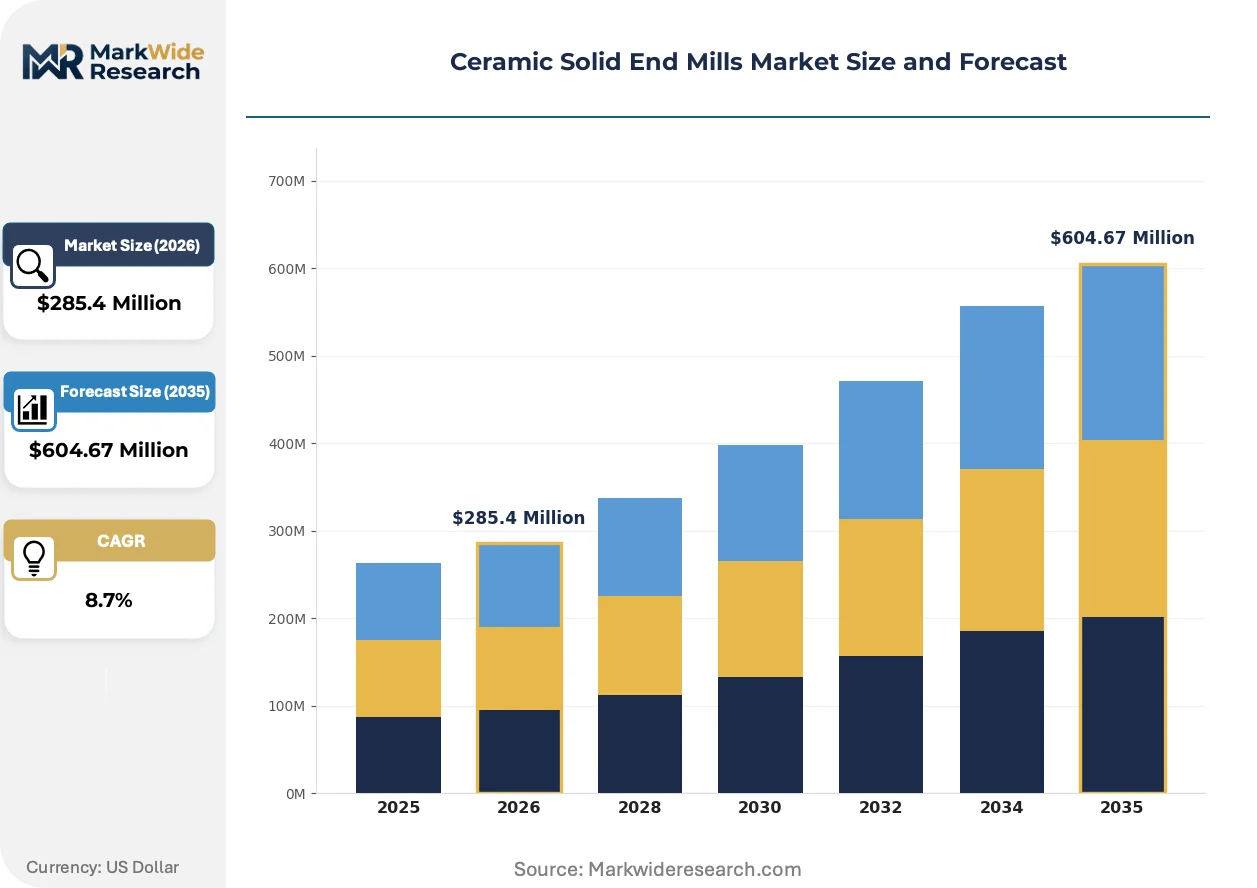
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Square, Ball Nose, Corner Radius, Tapered Material: Alumina, Zirconia, Silicon Nitride, Others Application: Aerospace, Automotive Components, Medical Devices, Electronics End User: Manufacturers, Job Shops, Tooling Companies, Research Institutes |
| Companies Covered | Sandvik, Mitsubishi Materials, Kennametal, OSG Corporation, Greenleaf Corporation, ISCAR, NTK, Taegutec, OPT Cutting Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Solid End Mills Market Trends and Innovations
Silicon nitride formulation advances and digital tool data standards are compressing the performance-validation cycle, while procurement patterns in precision manufacturing are fragmenting traditional distributor relationships.
Whisker-reinforced alumina matrix composites are decomposing the thermal-shock resistance ceiling that previously restricted ceramic tools to continuous-cut applications. Aerospace maintenance repair and overhaul facilities in the United States are adopting these grades for interrupted machining of Inconel turbine housings. The technology is decomposing the historical trade-off between speed and edge integrity, collapsing tool change frequency in high-mix production environments.
REACH Annex XVII restrictions on cobalt compound exposure in metalworking are accelerating substitution away from cemented carbide substrates in European precision machining. German mold and die shops now face mandatory risk assessment documentation for cobalt-containing cutting tools. The regulation is compressing carbide's installed base in medical device and food-contact component production where surface contamination liability exceeds tooling cost differentials.
Direct vendor relationships are displacing traditional cutting tool distribution in high-volume aerospace and medical component manufacturing. Tier-one suppliers in Switzerland and South Korea now require tool data integration with their MES and ERP systems, bypassing distributor technical support layers. This pattern concentrates procurement authority with manufacturing engineering teams and compresses price transparency across supply tiers.
Ceramic Solid End Mills Market Segmentation
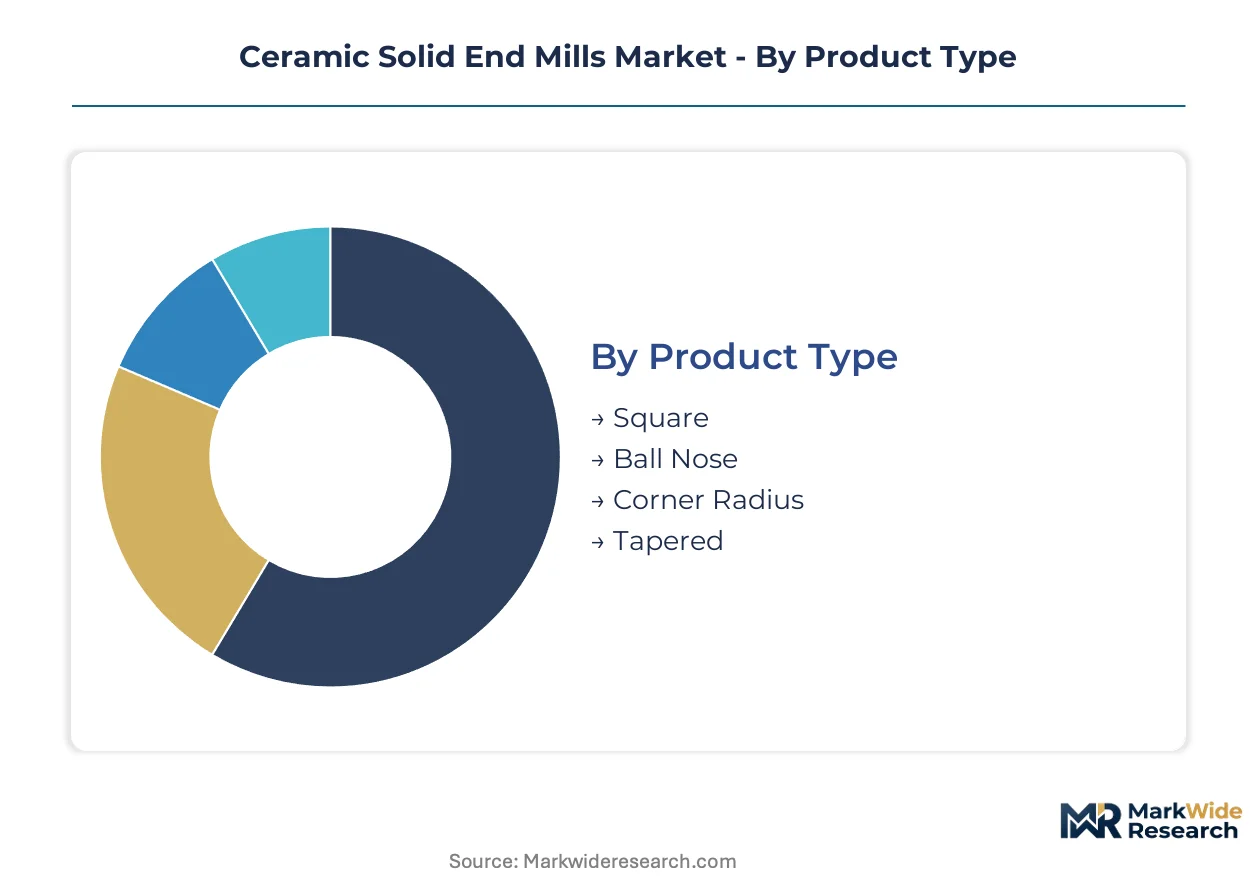
Ceramic solid end mills fragment across four structural dimensions that determine procurement authority, certification pathways, and margin capture. Product geometry dictates CAM programming complexity and toolpath optimization. Material chemistry governs thermal shock tolerance and regulatory compliance for medical and aerospace placement.
Product Type:
REACH chemical restrictions on metalworking fluids in Europe and FDA surface integrity mandates for orthopedic implants create divergent performance specifications across geometries.
- Square:Four-flute designs with 90-degree cutting edges dominate high-volume roughing of nickel-based superalloys. Swiss aerospace suppliers specify these for dry machining of Inconel turbine brackets where thermal degradation eliminates carbide alternatives.
- Ball Nose:Spherical tip geometries enable 3D contouring of complex mold cavities and medical implant surfaces. South Korean automotive mold shops drive demand for sub-2mm diameters in precision hard milling applications.
- Corner Radius:Chamfered edge profiles balance surface finish with edge strength in interrupted cuts. German die manufacturers specify these for hardened steel stamping tools.
- Tapered:Conical shank designs access deep cavity features in aerospace structural components. US repair depots use these for blade root machining.
Square geometry handles the majority of throughput; Ball Nose is gaining share fastest in medical device finishing workflows.
Material:
Cost tiers separate commodity alumina from engineered silicon nitride formulations that command aerospace qualification premiums.
- Silicon Nitride:Self-reinforced microstructures deliver thermal shock resistance above 800°C. Japanese METI green procurement incentives accelerate placement in domestic automotive supply chains for dry cast iron machining.
- Zirconia:Transformation-toughened compositions achieve fracture toughness exceeding 10 MPa·m½ for medical device finishing. Swiss orthopedic manufacturers specify these for cobalt-chrome implant surface preparation under FDA quality system requirements.
- Alumina:Cost-optimized grades serve general machining where speed advantages over carbide justify brittleness trade-offs. Chinese suppliers dominate volume production.
- Others:Whisker-reinforced and silicon carbide matrix variants address niche aerospace applications. Limited commercial scale restricts qualification pathways.
Silicon Nitride commands the highest volume in aerospace-qualified supply chains; Zirconia climbs fastest on medical device contract wins.
Application:
Customer maturity separates specification-driven aerospace procurement from price-sensitive automotive component sourcing.
- Aerospace:Engine and airframe manufacturers mandate NADCAP-accredited tooling for nickel superalloy machining. South Korean tier-one suppliers integrate tool data directly into MES systems.
- Medical Devices:Orthopedic and dental implant producers require FDA-registered cutting tools with documented surface integrity. Swiss device clusters concentrate demand for sub-micron finishing grades.
- Automotive Components:Powertrain and transmission producers balance cycle time reduction with tool cost control. German KBA certification pathways govern brake component machining specifications.
- Electronics:Printed circuit board and connector manufacturers use micro-diameter ceramics for non-ferrous machining. Limited thermal load requirements restrict premium material adoption.
Aerospace absorbs the majority of high-performance silicon nitride volume; Medical Devices expands most quickly on aging demographic demand and implant procedure growth.
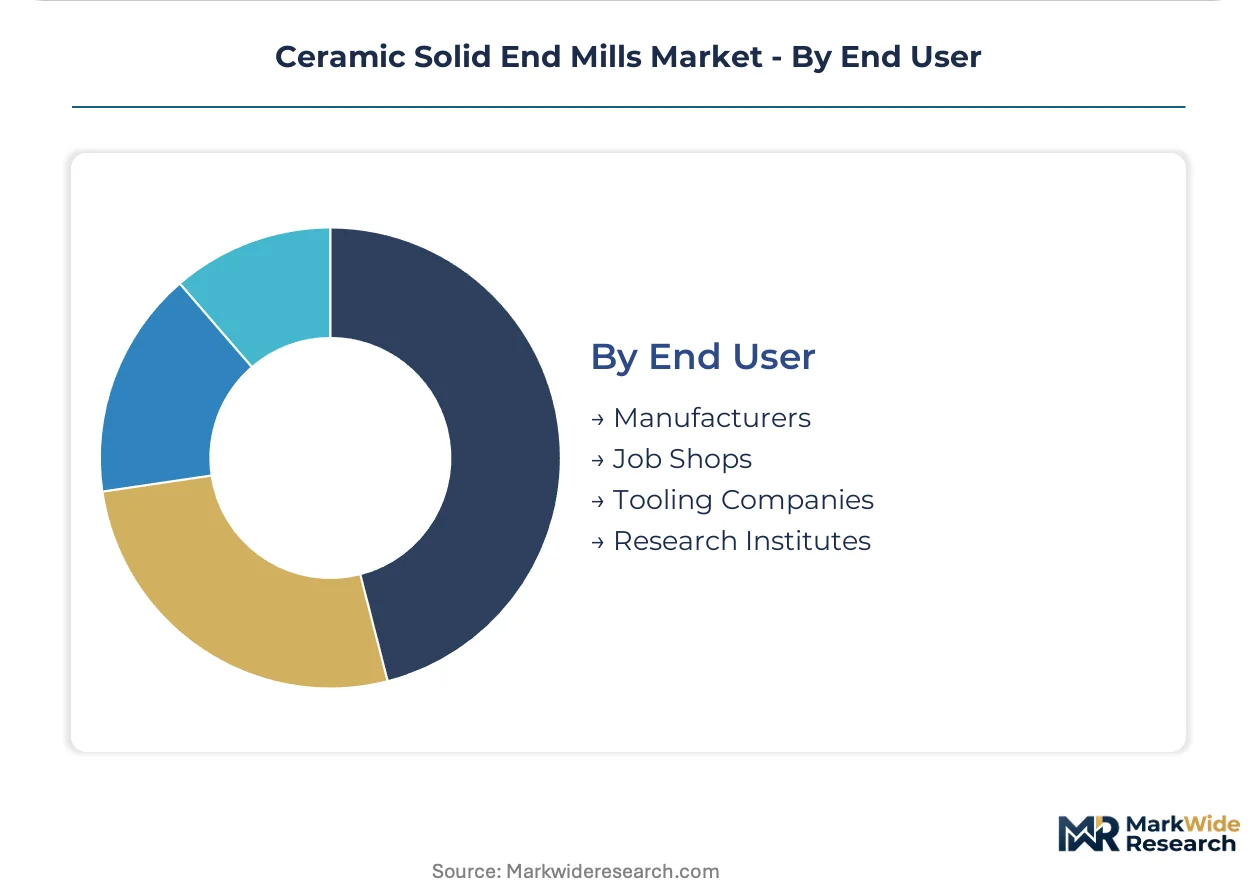
End User:
Procurement concentration distinguishes integrated manufacturers with captive tooling engineering from fragmented job shop demand.
- Manufacturers:Tier-one aerospace and medical device producers specify tools directly, bypassing distribution. Direct vendor relationships compress price transparency.
- Job Shops:High-mix, low-volume operators prioritize tool flexibility over material optimization. Limited CAM programming expertise constrains ceramic adoption.
- Tooling Companies:Cutting tool distributors and reconditioning services aggregate demand across fragmented end users. Inventory risk concentrates in standard geometries.
- Research Institutes:National laboratories and university machining centers validate next-generation formulations. Japanese and German public funding supports silicon nitride development programs.
Manufacturers drive the majority of qualified volume; Research Institutes show steepest expansion trajectory on government-backed advanced materials initiatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in advanced ceramic powders are reshaping manufacturing footprints. Tool producers face raw material access constraints that favor proximity to aerospace and medical device clusters.
United States
Aerospace repair depots in Connecticut and Ohio drive demand for silicon nitride grades in Inconel turbine blade machining. FAA airworthiness directives on engine component tolerances tighten tooling qualification requirements. Connecticut's Hartford aerospace corridor concentrates precision machining contracts with direct vendor integration into MES systems.
Germany
KBA automotive certification for brake component production mandates documented cutting tool traceability. REACH Annex XVII cobalt restrictions accelerate substitution away from cemented carbide in medical device machining. Stuttgart's mold and die cluster specifies corner radius geometries for hardened steel stamping tools under mandatory risk assessment protocols.
Japan
METI green procurement incentives channel public funding toward dry machining technologies in domestic automotive supply chains. JIS standards for silicon nitride powder purity create entry barriers for imported ceramic substrates. Nagoya's Chubu region anchors integrated pressing and sintering operations serving tier-one powertrain producers.
Switzerland
Swissmedic quality system requirements for orthopedic implant surface integrity drive zirconia-toughened alumina adoption. ISO 13399 tool data standardization reduces engineering validation cycles for cross-border procurement. The Jura arc manufacturing belt concentrates sub-micron finishing grade demand from medical device OEMs.
South Korea
MFDS medical device registration requirements align with FDA pathways for cobalt-chrome implant machining contracts. Government-backed advanced materials initiatives fund silicon nitride development programs at national laboratories. Busan-Ulsan's aerospace tier-one suppliers integrate ceramic tool data directly into ERP systems, bypassing traditional distribution.
Ceramic Solid End Mills Market Competitive Landscape
Concentration sits with diversified materials conglomerates possessing captive powder metallurgy capabilities. Three to four vertically integrated specialists control high-purity silicon nitride supply chains from mine to finished insert. The competitive terrain separates premium-grade aerospace qualifiers from cost-optimized general machining suppliers. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as producers seek to secure raw material access and compress sintering cycle times.
Among diversified multinational materials groups, Sandvik, Mitsubishi Materials, and Kennametal occupy positions defined by backward integration into powder production and multi-continent manufacturing footprints. Sandvik exemplifies the captive supply archetype through controlled raw material consistency. Mitsubishi Materials represents proprietary formulation specialization optimized for thermal shock resistance. Kennametal anchors the scale-driven tier with integrated pressing and sintering lines across multiple geographies. OSG Corporation and Greenleaf Corporation sit within the specialist fabricator category, while ISCAR, NTK, and Taegutec exemplify regional champions with concentrated presence in specific aerospace or automotive supply chains.
| Leading Market Players |
|---|
| Sandvik |
| Mitsubishi Materials |
| Kennametal |
| OSG Corporation |
| Greenleaf Corporation |
| ISCAR |
| NTK |
| Taegutec |
| OPT Cutting Tools |
| Others |
Pricing and Supply Chain Analysis
Gas-pressure sintering furnace capacity utilization above 80% in Japanese and German facilities establishes minimum efficient scale thresholds that compress marginal cost curves and elevate price floors for non-integrated competitors. This concentration of thermal processing capability simultaneously anchors supply-side bargaining power and segments the market into captive-powder premium tiers versus outsourced-substrate commodity tiers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. NADCAP aerospace qualification and FDA medical device registration separate premium silicon nitride grades from standard automotive formulations, while Chinese alumina suppliers compete on spot-market pricing for general machining. Cost compression in the economy tier is intensifying because South Korean and Swiss tier-one suppliers are consolidating procurement volumes and demanding direct vendor integration into MES systems. Job shops and small mold manufacturers exhibit the highest price sensitivity, while aerospace engine OEMs prioritize thermal performance consistency over unit cost differentials.
Supply Chain Analysis
High-purity silicon nitride powder production concentrates in Chinese and Japanese suppliers, exposing tool manufacturers to export quota volatility. Raw material flows draw from yttria-stabilized zirconia deposits, alumina refineries, and rare-earth sintering additives. Single-source vulnerability in gas-pressure sintering furnace technology—dominated by German and Japanese equipment builders—creates capacity expansion bottlenecks. Distribution runs through direct vendor relationships with tier-one aerospace and medical device manufacturers, bypassing traditional cutting tool distributors in high-volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ceramic solid end mills market is entering a cyclical recovery phase as aerospace engine production rates normalize and medical device procedure volumes rebound from pandemic-depressed baselines. Capital expenditure cycles at tier-one manufacturers are accelerating qualification timelines for next-generation superalloy machining programs.
For Market Incumbents: Secure captive powder metallurgy supply through long-term offtake agreements with Japanese and Chinese silicon nitride producers before export quota restrictions tighten. Defend aerospace qualification positions by accelerating whisker-reinforced alumina R&D to counter coated carbide performance convergence in the 400-450 m/min range. Capacity addition in South Korea and Switzerland aligns with direct vendor integration demands from tier-one suppliers. For New Entrants and Emerging Players: Differentiate on zirconia-toughened alumina formulations optimized for FDA-registered medical device finishing contracts with Swiss orthopedic manufacturers. Target the additive manufacturing hybrid workflow segment where near-net-shape metal 3D printing stock allowances require high-speed ceramic finishing capabilities. A go-to-market angle anchored in CAM programming training and parameter libraries addresses the ceramic-specific expertise gap constraining job shop adoption. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated manufacturers with captive sintering operations and multi-continent qualification portfolios. Five-to-ten year viability favors acquisition targets possessing backward integration into powder production and existing NADCAP or FDA registration pathways. The signal to watch is Japanese METI green procurement funding disbursement rates, which indicate dry machining technology placement velocity in automotive supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Production | Captive silicon nitride supply secures raw material consistency for aerospace qualification programs. |
| Multi-Standard Certification Investment | Concurrent NADCAP, FDA, and KBA pathways compress product launch cycles by 18-24 months. |
| Direct Vendor MES Integration | Tool data standardization under ISO 13399 enables procurement bypass of distributor technical layers. |
| Whisker-Reinforced Formulation Development | Alumina matrix composites decompose thermal-shock resistance ceilings for interrupted cut applications. |
| Energy-Efficient Sintering Capacity Expansion | Gas-pressure furnace investments in stable electricity pricing regions lock in cost-competitive thermal processing. |
Research Methodology
Cross-validation between primary interviews with cutting tool R&D directors, aerospace manufacturing engineers, medical device quality managers, and ceramic powder procurement leads anchors the qualitative findings. Secondary validation draws from SEC filings of diversified materials conglomerates, Japanese METI industrial statistics, Swiss customs export data for precision machining equipment, and FDA 510(k) device registration databases. Bottom-up triangulation across product geometry, material chemistry, and end-use application segments converges with top-down aerospace and medical device production forecasts.
Sensitivity analysis on gas-pressure sintering energy costs, silicon nitride powder export quota scenarios, and coated carbide performance convergence rates tests forecast robustness across the projection horizon. Segmentation dimensions modeled include product geometry, material grade tier, application vertical, and procurement authority concentration. CAGRs derive from installed base replacement cycles, superalloy machining demand elasticity, and regulatory compliance cost trajectories. Industry-specific inputs incorporate REACH Annex XVII enforcement timelines and Japanese green procurement incentive disbursement schedules.
The analysis sits within stated boundaries; outcomes outside stable industrial electricity pricing and aerospace production rate normalization would require recalibration. Forecasts reflect assumptions regarding ISO 13399 adoption velocity, cobalt compound substitution rates in European precision machining, and ceramic waste recycling mandate implementation. Practitioners should keep alternative scenarios live as REACH chemical restriction expansions and METI funding program renewals evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Germany Ceramic Tiles Market
Ceramics
Global Pseudo Boehmite Market
Ceramics
Magnesia Carbon Bricks Market
Ceramics
UAE Ceramic Tiles Market
Ceramics
North America Activated Alumina Market
Ceramics
Advanced Ceramics Market
Ceramics
Titanates Market
Ceramics
Europe Ceramic Tiles Market
Ceramics
Refractories Market
Ceramics
China Clay Market
Ceramics
Thermal Spray Powder Market
Ceramics
Global Barium Carbonate Market
Ceramics
Advanced Ceramic Additives Market
Ceramics
Mexico Ceramic Tiles Market
Ceramics
Transparent Ceramics Market
Ceramics
Low Density Ceramic Proppant Market