
 Fire Clay Market | 2026-2036
Fire Clay Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Clay Market Analysis
Industrial buyers in the cement sector is reorganizing demand away from commodity-grade fireclay toward high-performance refractory formulations. Morgan Advanced Materials leverages its R&D intensity in alumina-silicate composites to capture premium specification work. RHI Magnesita anchors its position through captive magnesite-fireclay blends and dense service networks across European steel corridors. Zibo Jucos Co., Ltd. competes on manufacturing scale, operating integrated mines-to-kiln operations that control raw material variability.
Fire clay denotes a sedimentary aluminosilicate material with alumina content typically ranging from 25% to 45%, fired at 1,000–1,400°C to produce refractory shapes or monolithic linings that withstand thermal shock and chemical attack in high-temperature industrial processes. The high alumina clay segment leads in value contribution due to its critical role in blast furnace and glass tank applications where service life directly determines maintenance scheduling. Powder and granular forms are gaining fastest in foundry and ceramics end uses, as gunning and ramming mixes displace traditional brick installations for repair speed and labor reduction.
EPA emissions rules in the United States and REACH chemical safety registration in Europe constrain binder chemistries and dust exposure limits during fireclay installation, elevating certified product premiums. China's MEE enforces dual carbon targets that push refractory consumers toward longer-campaign linings, indirectly filtering supplier qualification. India's BIS product standards for refractory materials create compliance thresholds for imported fireclay bricks. Stakeholders must monitor how carbon border adjustments and localized mining permitting reshape cost structures for raw fireclay extraction and cross-border trade.
Market Dynamics
Cement sector buyers are consolidating specifications around longer-campaign refractory linings, forcing suppliers to recalibrate product portfolios toward high-alumina formulations and integrated service contracts rather than commodity brick sales.
Growth Catalysts
- EU Green Deal emissions protocols:Steel and cement producers face tightening NOx and particulate limits that extend kiln relining intervals, directly expanding demand for dense, thermally stable fireclay composites in European industrial corridors.
- India's western industrial corridor expansion:Greenfield steel and cement capacity in Gujarat and Maharashtra generates concentrated bulk consumption of standard-grade fireclay for initial furnace construction and lining installation.
- Monolithic refractory technology:Gunning and ramming mixes displace traditional shaped brick in repair applications, accelerating consumption of powdered and granular fireclay forms in foundry maintenance cycles.
Market Restraints
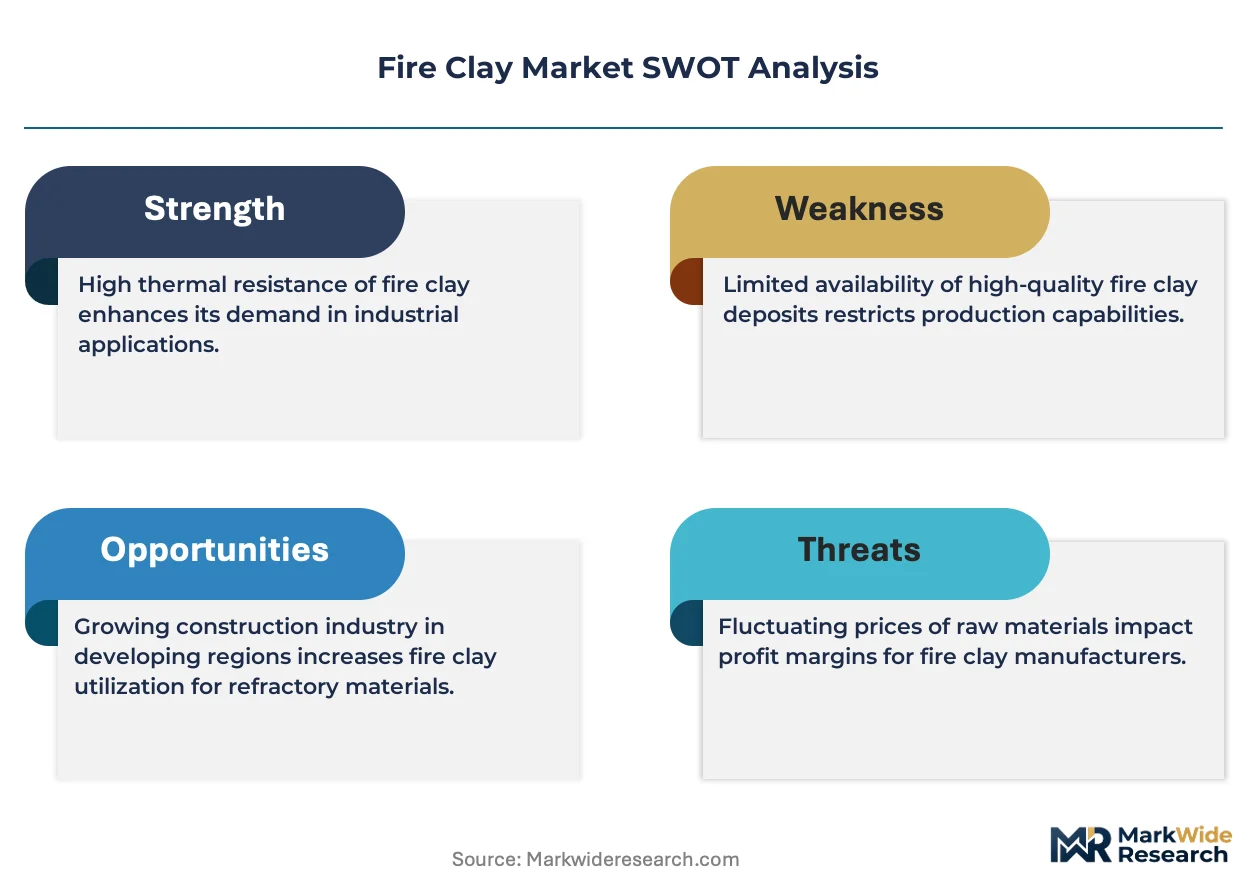
- Raw material quality inconsistency:Sedimentary fireclay deposits exhibit alumina content variability between 25% and 45%, forcing processors to blend multiple mine sources and absorb yield losses during beneficiation.
- Freight cost exposure:Low value-to-weight ratios make finished refractory products vulnerable to diesel price volatility and distance penalties, disadvantaging suppliers without captive mine-to-plant logistics.
- Substitute refractory systems:Fused cast AZS blocks and basic magnesia-chrome formulations capture premium positions in glass tank and non-ferrous smelting applications where fireclay's chemical resistance proves inadequate.
Strategic Opportunities
- China's dual carbon implementation:MEE enforcement of longer-campaign lining mandates creates qualification barriers that favor foreign suppliers with certified low-cement castable formulations and documented carbon footprints.
- Secondary aluminum growth:Scrap remelting operations in Turkey and Southeast Asia require rapid-repair refractory systems, opening channels for pre-mixed gunning materials with tailored thermal shock resistance.
- Digital refractory monitoring:Integration of thermocouple arrays and predictive wear algorithms with monolithic lining installations enables performance-based contracting models that lock in multi-year supply relationships.
Industry Challenges
- Installation certification bottlenecks:EPA dust exposure limits and REACH binder registration requirements extend product qualification timelines, delaying market entry for reformulated low-toxicity castables.
- Refractory engineering talent scarcity:Specialized expertise in high-temperature material selection and kiln design concentrates among retiring practitioners, constraining technical support capacity for complex lining projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Clay Market |
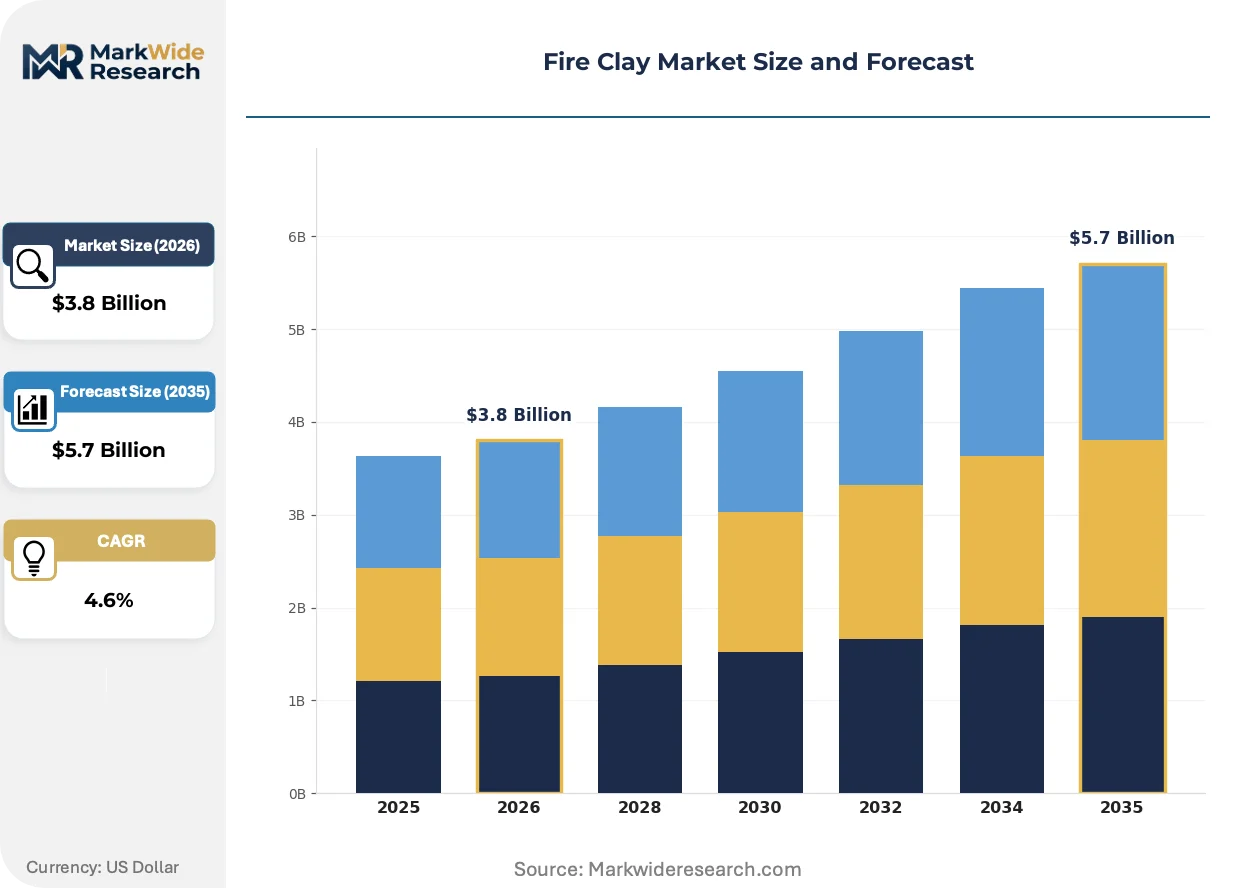
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Alumina Clay, Low Alumina Clay, Shale Clay, Fireclay Bricks End Use Industry: Cement, Glass, Ceramics, Foundries Form: Powder, Granules, Blocks, Bricks Packaging Type: Bags, Bulk, Pallets, Containers |
| Companies Covered | Sibelco, Vitcas, Morgan Advanced Materials, YUFENGREC REFRACTORY, Fireramo Industrial, RHI Magnesita, Sheffield Pottery, Zibo Jucos Co., Ltd., Imerys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Clay Market Emerging Trajectories
Active specification rewriting across steel and cement end-uses is compressing traditional product lifecycles and elevating performance-based procurement criteria over historical supplier relationships.
High-purity calcined fireclay is bifurcating the specification landscape between premium long-life linings for blast furnace hearths and economy-grade repair materials for periodic maintenance. Steel producers in Germany and Japan are specifying alumina contents above 40% for critical zones, while secondary foundries in India and Mexico accept lower-grade blends for non-structural applications. This divergence is compressing mid-tier product viability and forcing suppliers to choose specialization paths.
REACH chemical safety registration in Europe constrains binder chemistries used in monolithic refractory installation, elevating certified product premiums and disqualifying uncertified imports. Industrial buyers now require documented compliance for silica sol and alumina cement components before contract award. Glass manufacturers in Italy and the Czech Republic have shifted procurement toward pre-registered European suppliers to avoid installation liability exposure.
Integrated service contracting is displacing discrete product sales in large cement and steel accounts, bundling material supply with installation supervision and performance guarantees. Equipment OEMs in India and Turkey are capturing refractory specification authority by offering turnkey kiln lining packages that lock out independent material suppliers. This channel consolidation concentrates volume among vertically integrated providers and erodes traditional distributor roles in emerging industrial markets.
Fire Clay Market Segmentation
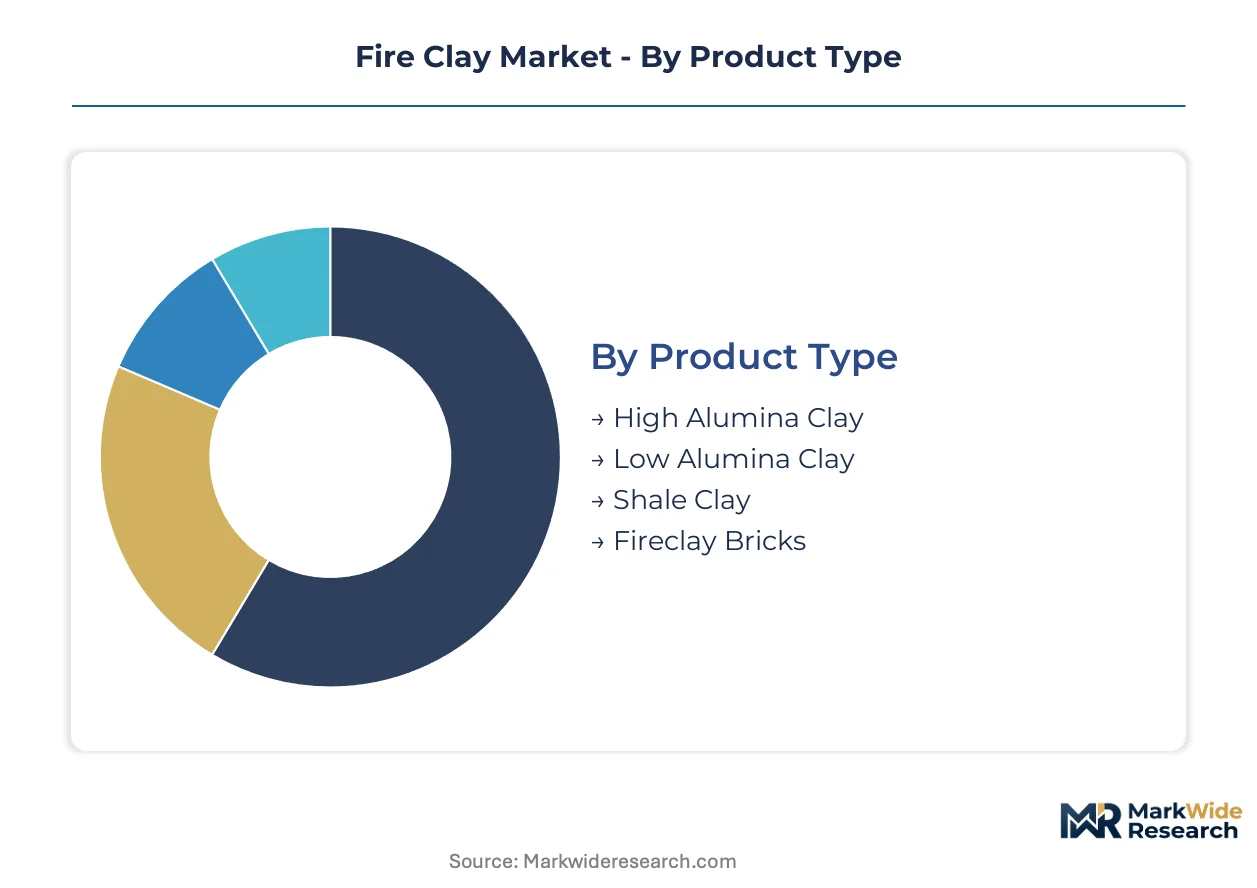
Fire clay segmentation reflects divergent margin structures across material grades, installation formats, and end-use specifications. Procurement patterns in steel and cement sectors increasingly favor performance-tiered purchasing rather than commodity sourcing.
Product Type:
Premium margin pools concentrate in high-specification alumina grades where blast furnace and glass tank applications command technical certification premiums.
- High Alumina Clay:Alumina content exceeding 40% delivers superior thermal shock resistance and chemical stability in blast furnace hearths. German and Japanese steel producers specify these grades for critical zones where campaign extension directly reduces maintenance downtime.
- Low Alumina Clay:Standard 25-35% alumina content serves economy-grade applications in secondary foundries and periodic repair cycles. Indian secondary aluminum remelters and Mexican non-ferrous foundries absorb volume here for non-structural lining components where service life requirements remain modest.
- Shale Clay:Sedimentary deposits with intermediate alumina-silica ratios support brick manufacturing for moderate-temperature kiln applications.
- Fireclay Bricks:Pre-formed refractory shapes dominate legacy installation protocols in mature industrial corridors with established mason workforces.
The dominant share belongs to High Alumina Clay, while Low Alumina Clay is expanding most quickly in emerging market foundry construction.
End Use Industry:
Application-driven segmentation tracks divergent specification intensity, with cement and glass sectors rewriting procurement criteria around campaign length guarantees.
- Cement:Rotary kiln operators in India's western corridor and Turkey's Anatolian belt specify dense, thermally stable linings for extended campaigns. EU Green Deal NOx limits are compressing relining intervals and elevating demand for certified high-performance formulations.
- Glass:Tank furnace operators face REACH-registered binder requirements and silica sol compliance documentation. Italian and Czech manufacturers have shifted procurement toward pre-registered European suppliers to eliminate installation liability exposure.
- Ceramics:Tunnel kiln and intermittent firing operations in China's Jiangxi province consume standard-grade fireclay for structural refractory supports.
- Foundries:Scrap remelting growth in Turkey and Southeast Asia drives rapid-repair gunning material demand with tailored thermal shock resistance for ladle and tundish maintenance.
Cement retains volume leadership, though glass applications command the steepest specification premiums per ton installed.
Form:
Format selection determines labor economics and installation speed, with monolithic systems displacing traditional shaped products in repair-intensive segments.
- Powder:Finely milled fireclay serves gunning mix formulations for rapid furnace repair without cooldown. Foundry maintenance cycles in secondary aluminum operations favor pre-blended powders for application speed.
- Granules:Coarse-graded material supports ramming mix installations with superior packing density in blast furnace hearths and glass tank substructures.
- Blocks:Pre-cast monolithic shapes reduce on-site forming labor for complex kiln geometries.
- Bricks:Traditional fired shapes persist where mason labor availability and established installation protocols dominate procurement decisions.
Bricks still anchor installed base volumes, yet powder formats are gaining share fastest in maintenance contracting channels.
Packaging Type:
Packaging configuration aligns with consumption scale and logistics infrastructure, separating bulk industrial users from distributed repair operations.
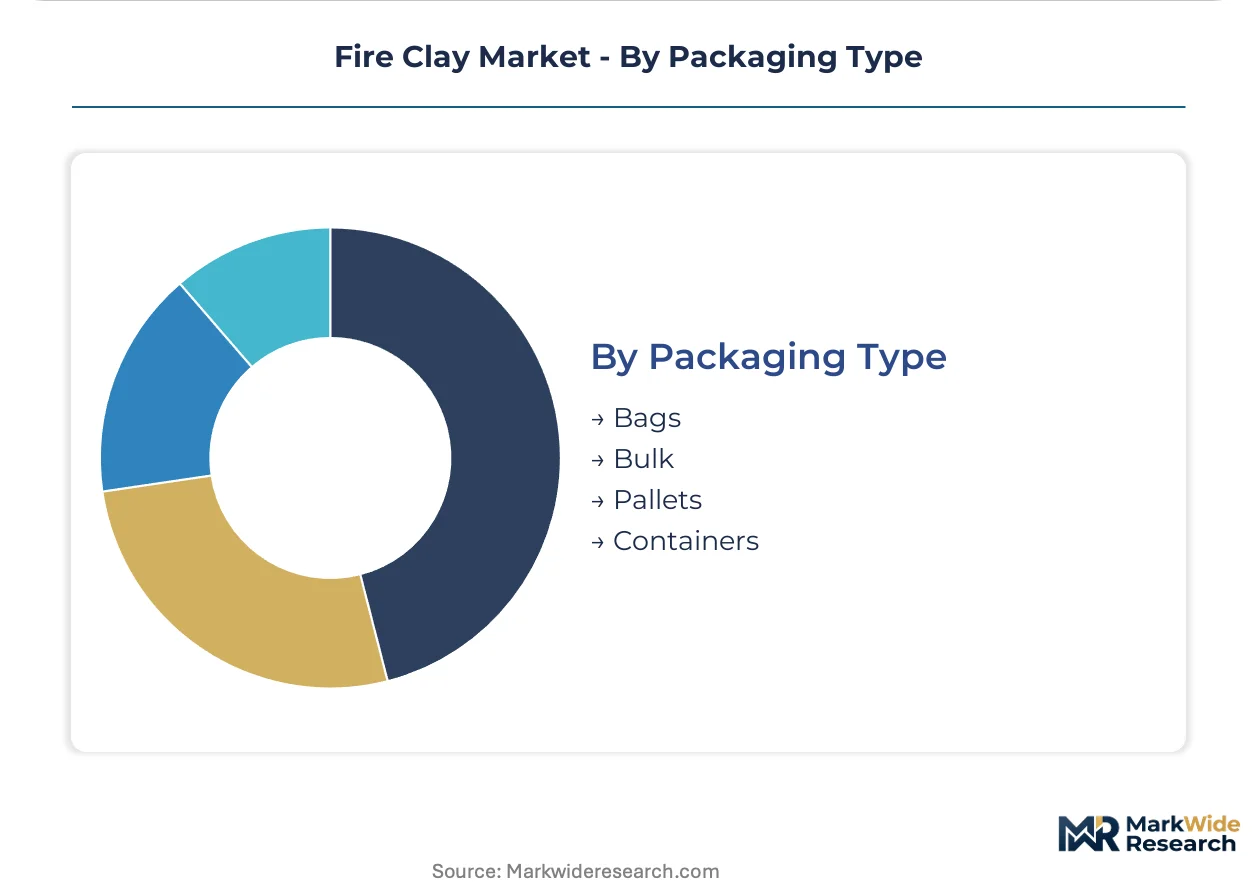
- Bags:Standard 25-50kg units serve job-site mobility requirements for foundry repair crews and small-scale ceramics producers.
- Bulk:Pneumatic discharge systems feed continuous manufacturing lines at integrated steel and cement complexes with captive storage silos.
- Pallets:Unitized brick shipments protect shaped products during long-haul transport to construction sites.
- Containers:Intermodal packaging supports export flows to emerging industrial markets with underdeveloped bulk handling infrastructure.
Bulk packaging commands the largest volume throughput, while bagged formats maintain resilience in fragmented repair and maintenance channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Duisburg-Ruhrort inland port complex anchors European fire clay logistics, channeling bulk refractory materials to steel corridors along the Rhine. India's Western Dedicated Freight Corridor underwrites raw material flows to Gujarat's cement belt. China's Belt and Road rail links distribute processed fire clay from Shandong to Central Asian construction markets.
Germany
Blast furnace operators in the Ruhr region specify high-alumina fire clay for campaign extensions exceeding 15 years. The EU Green Deal's Industrial Emissions Directive compresses relining windows, elevating demand for certified low-cement castables. Duisburg's refractory service clusters supply integrated steelworks along the Rhine with technical support and rapid repair materials.
India
Greenfield cement capacity in Gujarat and Maharashtra drives bulk consumption of standard-grade fire clay for rotary kiln construction. BIS product standards for refractory materials create compliance thresholds that filter imported brick specifications. The western industrial corridor's Mundra and Hazira ports concentrate material handling infrastructure for mine-to-plant logistics.
China
MEE enforcement of dual carbon targets pushes steel producers toward longer-campaign linings, indirectly raising qualification barriers for refractory suppliers. The Shandong Peninsula's integrated mining-to-kiln operations control raw material variability for domestic glass and ceramics sectors. Zhengzhou's rail hub distributes processed fire clay to Central Asian markets via Belt and Road corridors.
United States
EPA emissions rules constrain binder chemistries and dust exposure limits during fire clay installation, elevating certified product premiums. Foundry maintenance cycles in the Great Lakes automotive belt absorb powdered fire clay for rapid-repair gunning applications. Pittsburgh's legacy steel corridor retains specification authority for high-performance blast furnace linings.
Turkey
Secondary aluminum remelting growth in Izmir and Istanbul drives demand for pre-mixed gunning materials with tailored thermal shock resistance. The Anatolian cement belt's rotary kiln operators specify dense, thermally stable linings for extended campaigns. Iskenderun's port infrastructure handles bulk refractory imports for distribution to Black Sea industrial zones.
Fire Clay Market Vendor Landscape
Listed leaders compete with private specialists across integrated service capabilities and raw material control. The vendor base stratifies between multinational refractory houses with captive mineral reserves and regional fabricators competing on logistics proximity. Three archetypes dominate: integrated mining-to-lining operators, formulation specialists with R&D intensity, and scale-driven commodity producers. Capacity expansion and backward integration into captive clay deposits represent the dominant competitive moves.
Within the premium formulation tier, Morgan Advanced Materials and RHI Magnesita occupy positions defined by technical certification depth and service network density. Zibo Jucos Co., Ltd. exemplifies the scale-driven archetype through integrated Shandong-based mining and kiln operations. These three anchors illustrate how competitive positioning stratifies across certification intensity, raw material control, and manufacturing scale rather than product differentiation alone.
| Leading Market Players |
|---|
| Sibelco |
| Vitcas |
| Morgan Advanced Materials |
| YUFENGREC REFRACTORY |
| Fireramo Industrial |
| RHI Magnesita |
| Sheffield Pottery |
| Zibo Jucos Co., Ltd. |
| Imerys |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at integrated Shandong mining-to-kiln operations sets price floors across standard-grade fireclay segments, compressing margins for regional fabricators without captive clay deposits or dense European service networks. Scale concentration among Chinese producers with backward control over sedimentary alumina-silicate reserves feeds directly into volume-discount tiering that rewards multi-year cement sector contracts.
Pricing Analysis
Volume-discount tiering structures separate premium high-alumina formulations certified for EU Green Deal compliance from standard-grade bricks serving Indian cement construction and economy repair blends for Mexican foundries. Price differentiation rests on alumina content certification and REACH binder registration documentation. Cost compression in economy tiers is intensifying because Indian bulk buyers consolidate procurement around longer-campaign guarantees. Secondary aluminum remelters in Turkey exhibit highest price sensitivity; German blast furnace operators accept steep premiums for campaign extension assurances.
Supply Chain Analysis
Strait of Malacca transit underwrites seaborne fireclay flows from Shandong Peninsula processors to Indian western corridor ports and Southeast Asian foundry markets. Geographic supply concentration centers on China, India, and Germany. Raw material sourcing draws from sedimentary alumina-silicate deposits, calcined clay processing capacity, and registered silica sol binder stocks. Single-source vulnerability concentrates around Shandong's integrated mining-to-kiln complexes. Distribution runs through bulk pneumatic discharge systems at integrated steel and cement complexes alongside containerized shipments for fragmented repair channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in high-temperature kiln design and lining campaign engineering is concentrating among retiring practitioners, creating capability scarcity that constrains technical support capacity for complex blast furnace and glass tank projects.
For Market Incumbents: Compound defensive positioning through captive magnesite-fireclay blend production and dense European service network expansion. Magnesia-chrome substitute formulations threaten premium glass tank positions; counter by deepening R&D intensity in alumina-silicate composites. Certification investment for EU Green Deal low-cement castable compliance remains the critical lever. For New Entrants and Emerging Players: Lead with pre-mixed gunning materials for Turkey's secondary aluminum remelting corridor and Southeast Asian foundry maintenance cycles. Scrap remelting growth in Izmir and Istanbul offers the most penetrable white space. Target rapid-repair channels with tailored thermal shock resistance formulations and job-site mobility packaging. For Investors and Strategic Acquirers: Regional fabricators with logistics proximity to India's western cement belt and documented BIS compliance pathways represent the target acquisition archetype. Long-term viability frames around refractory service contracting displacement of discrete product sales. Watch for carbon border adjustment implementation in European steel corridors as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Clay Deposits | Shandong and Gujarat mining concessions control raw material variability and yield losses. |
| REACH-Registered Low-Cement Castable Certification | Italian and Czech glass manufacturers require documented silica sol compliance before contract award. |
| Integrated Service Contracting Bundles | Indian equipment OEMs capture specification authority through turnkey kiln lining packages. |
| Digital Refractory Monitoring Integration | Thermocouple arrays with predictive wear algorithms enable multi-year performance-based supply relationships. |
| Capacity Positioning Along India's Western Dedicated Freight Corridor | Mundra and Hazira port infrastructure concentrates mine-to-plant logistics for Gujarat cement construction. |
Methodological Framework
Initial hypotheses were tested against primary input from refractory plant managers, cement procurement leads, glass tank furnace operators, and technical R&D directors at integrated mining-to-kiln operations and refined through secondary validation. Sources included customs and trade flow databases, SEC 10-K filings from listed refractory houses, EU ETS emissions registry data, and Indian BIS product standard documentation. Bottom-up volume modeling across alumina grade tiers and installation format segments was triangulated against top-down market sizing from end-use industry consumption patterns.
Variance-decomposition framing isolated drivers across the projection horizon by alumina content tier, end-use industry specification intensity, installation format adoption curves, and regional regulatory cluster. Modeled dimensions spanned high versus low alumina grades, cement versus glass versus foundry applications, monolithic versus shaped formats, and captive mine-to-plant versus merchant supply structures. CAGRs were derived from segment-level volume buildups adjusted for campaign extension trends and substitution dynamics from fused cast AZS blocks.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement, China's dual carbon target adherence, or India's western corridor capacity execution would require recalibration. Forecasts reflect assumptions around refractory engineering talent availability and REACH registration timeline continuity. Practitioners should keep alternative scenarios live as carbon border adjustment mechanisms and localized mining permitting regimes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Wollastonite Market
Ceramics
Thailand Ceramic Tiles Market
Ceramics
South Korea Ceramic Tiles Market
Ceramics
Ceramics Market
Ceramics
Yttria-Stabilized Zirconia (YSZ) Market
Ceramics
Global Magnesium Silicate Market
Ceramics
Ceramic Additives Market
Ceramics
United States Ceramics Tableware Market
Ceramics
Ceramic Binders Market
Ceramics
North America Ceramic Coatings Market
Ceramics
Ceramic and Natural Stone Tiles Market
Ceramics
Ceramic Sanitary Ware Market
Ceramics
Technical Ceramics Market
Ceramics
Advanced Ceramics Market
Ceramics
Global Alumina Market
Ceramics
Global Functional Ceramics Market