
 Europe Internal Combustion Engines Market | 2026-2036
Europe Internal Combustion Engines Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Internal Combustion Engines Market Insights
Hybrid integration is reconfiguring how internal combustion engines are engineered for European vehicle platforms. Volkswagen Group leverages its modular matrix to sustain gasoline and diesel variants alongside electrified architectures. Mercedes-Benz Group anchors its premium segment position through high-performance combustion powertrains with advanced thermal management. MAN SE dominates commercial vehicle applications where long-haul duty cycles still favor diesel density.
Internal combustion engines convert fuel energy into mechanical work through controlled combustion within cylinders, with modern European units achieving thermal efficiency above 40 percent through turbocharging and direct injection systems. These powertrains serve as the primary propulsion source for passenger vehicles, freight logistics, and off-highway equipment across the continent. Diesel engines retain structural importance in commercial vehicles and marine applications where torque density and fuel energy content outweigh electrification timelines. Gasoline engines occupy the passenger vehicle segment where hybrid integration is expanding fastest. Natural gas and dual-fuel variants command narrow but strategically defended positions in municipal bus fleets and regional shipping corridors with established bunkering infrastructure.
The European Union's Euro 7 standards and the F-Gas Regulation are tightening emission ceilings and refrigerant constraints, forcing recalibration of exhaust after-treatment systems and thermal circuit designs. EMA guidelines and CE marking requirements further shape product validation cycles and market access protocols for engine manufacturers. National regulators in Germany, France, and Italy enforce type-approval procedures that extend development timelines and concentrate compliance investment among scaled producers. Stakeholders must track how the EU Green Deal's carbon-border adjustments and national fleet mandates redistribute competitive advantage between pure-play ICE suppliers and hybrid-integrated platforms.
Market Dynamics
The Euro 7 emission standards are compressing development timelines for European engine manufacturers, forcing simultaneous investment in after-treatment miniaturization and thermal efficiency gains while electrification timelines accelerate.
Growth Catalysts
- Hybrid powertrain mandates:Germany's fleet CO2 regulations and France's malus écologique are sustaining demand for high-efficiency gasoline engines integrated with 48-volt mild-hybrid systems in passenger vehicles.
- Poland's freight corridor expansion:The Baltic-Adriatic TEN-T corridor upgrades are extending replacement demand for heavy-duty diesel powertrains in long-haul logistics fleets.
- Dual-fuel bunkering infrastructure:LNG terminal expansions at Rotterdam and Barcelona are creating new demand for marine and heavy-truck engines capable of dual-fuel operation.
Market Restraints
- Platinum group metal volatility:Exhaust catalyst palladium and rhodium price swings are destabilizing cost structures for gasoline after-treatment systems.
- Turbocharger supply concentration:BorgWarner, Garrett Motion, and Mitsubishi Heavy Industries control 80 percent of European variable geometry turbo supply, creating single-source vulnerability.
- Electrification substitution:Battery-electric urban delivery vans from Renault and Fiat are displacing small diesel engines in last-mile logistics applications below 3.5 tonnes.
Strategic Opportunities
- Romania and Bulgaria fleet modernization:EU cohesion fund vehicle renewal programs are opening demand for Euro 6d-compliant diesel engines in municipal and regional bus fleets.
- Synthetic fuel compatibility:Porsche and Siemens Energy's Haru Oni e-fuels pilot in Chile is validating engine architectures for renewable gasoline and diesel drop-in fuels.
- Remanufacturing regulatory tailwind:France's reparability index and proposed EU right-to-repair extensions are incentivizing certified engine remanufacturing as a formal channel.
Industry Challenges
- Combustion calibration expertise scarcity:Volkswagen, BMW, and Mercedes-Benz are competing for finite talent pools in high-pressure direct injection and particulate filter regeneration algorithms.
- Euro 7 certification timeline compression:The September 2025 type-approval deadline is forcing parallel validation of real-driving emission and laboratory test cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Internal Combustion Engines Market |
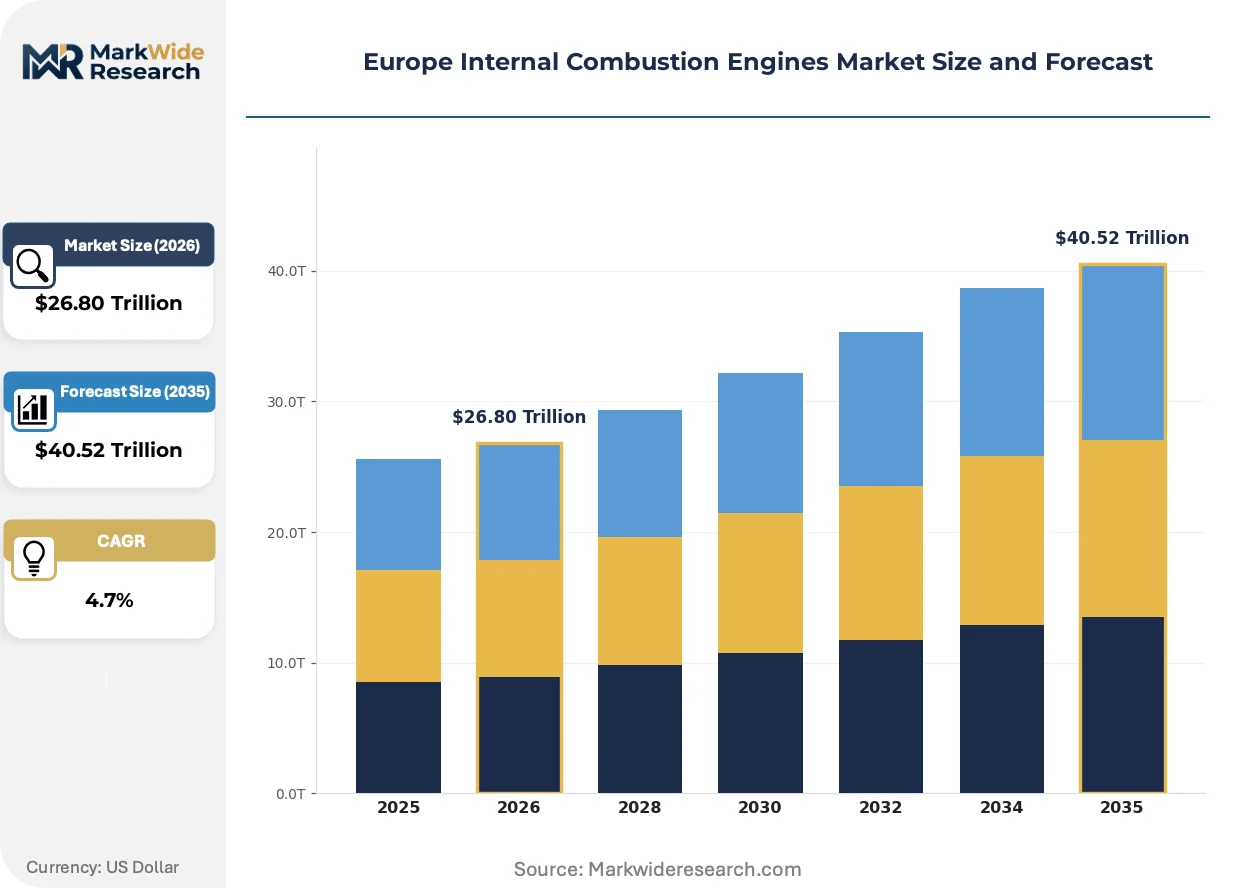
| Market Size in 2026 | $26.80 Trillion |
| Market Size in 2035 | $40.52 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline Engines, Diesel Engines, Natural Gas Engines, Dual-Fuel Engines End User: Automotive Manufacturers, Marine Applications, Agricultural Equipment, Industrial Machinery Technology: Turbocharged, Supercharged, Direct Injection, Hybrid Integration Application: Passenger Vehicles, Commercial Vehicles, Construction Equipment, Recreational Vehicles |
| Companies Covered | Volkswagen Group, Audi, Volvo AB, MAN SE, Bayerische Motoren Werke AG, Toyota Motor Corporation, Hyundai Motors, Mercedes-Benz Group, Stellantis, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Internal Combustion Engines Market Trends and Innovations
European engine development is bifurcating between extreme thermal efficiency optimization for hybrid applications and modular architecture design that accommodates synthetic fuel retrofits without block replacement.
Pre-chamber ignition technology is collapsing the thermal efficiency gap between gasoline and diesel architectures. Mahle and Maserati are deploying turbulent jet ignition in high-performance applications, achieving diesel-comparable compression ratios without particulate generation. This compression is enabling smaller displacement engines to replace larger naturally aspirated units without power degradation.
The EU F-Gas Regulation is banning refrigerants with global warming potential above 150 from mobile air conditioning systems by 2025. Engine thermal management circuits must now integrate heat pump functionality and CO2-based refrigerant architectures. Passenger vehicle OEMs in Germany and Sweden are most affected, accelerating R-744 system adoption.
Fleet procurement departments are consolidating engine supply contracts across passenger, light commercial, and off-highway divisions. Stellantis and Volvo Group are negotiating multi-division engine platform agreements that compress supplier margins while demanding common rail and after-treatment modularity. This concentration is most visible in Nordic markets where municipal, logistics, and construction fleets often share ownership structures.
Europe Internal Combustion Engines Market Segmentation
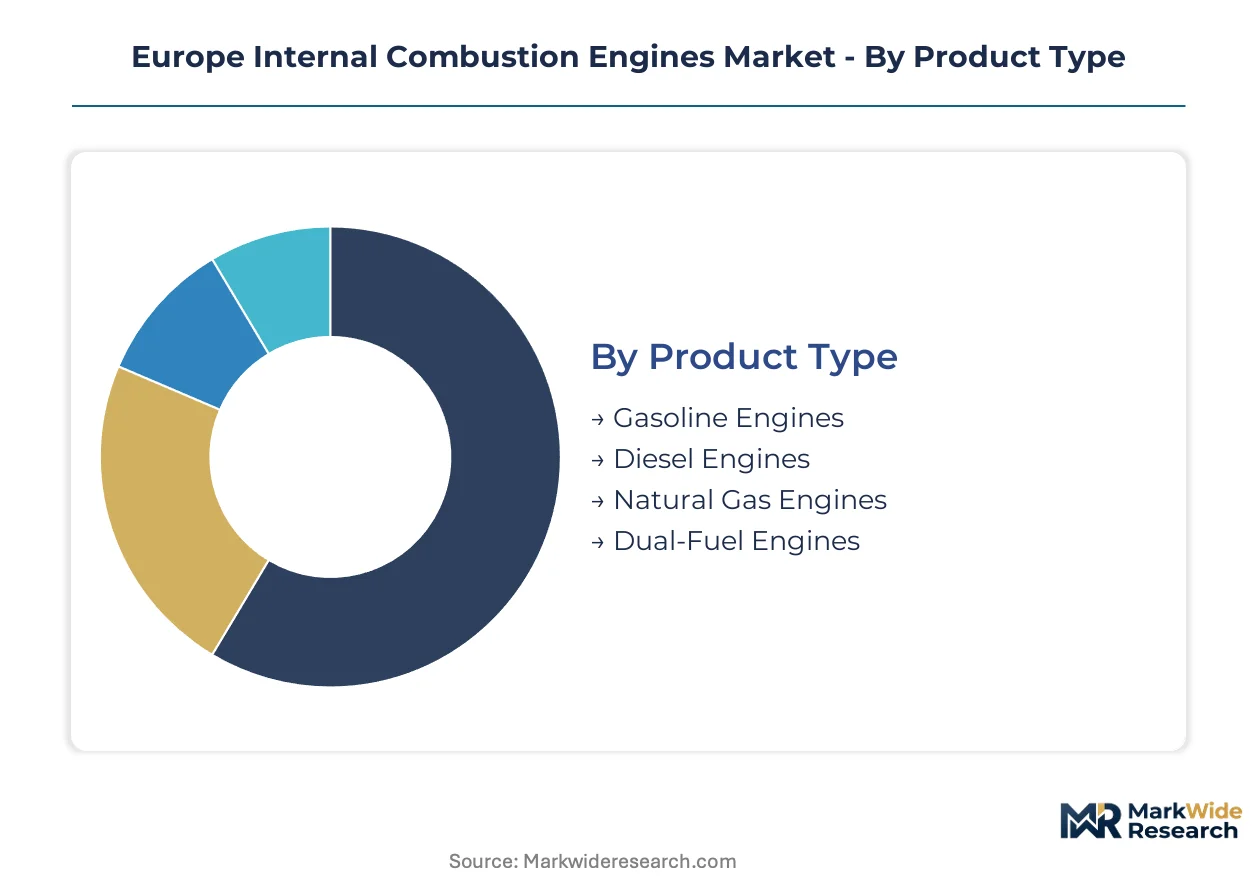
Internal combustion engines across Europe serve divergent duty cycles that demand fundamentally different engineering trade-offs. Segmentation reveals how thermal efficiency, emission compliance, and fuel infrastructure shape procurement decisions across passenger mobility, freight logistics, and off-highway applications.
Product Type:
Engine architectures span the full fuel energy density spectrum from gasoline through dual-fuel configurations, each calibrated to specific load profiles and bunkering access.
- Diesel Engines:Compression-ignition architectures deliver torque density above 250 Nm per liter through high-pressure common rail injection. Heavy-duty commercial vehicle fleets across Germany's Autobahn corridors and Poland's Baltic-Adriatic TEN-T routes sustain replacement demand despite electrification pressure.
- Gasoline Engines:Spark-ignition powertrains achieve thermal efficiency above 40 percent through turbocharging and direct injection. French and German passenger vehicle OEMs integrate these with 48-volt mild-hybrid systems to meet fleet CO2 regulations.
- Natural Gas Engines:Otto-cycle variants optimized for compressed or liquefied methane serve municipal bus operators in Barcelona and Rotterdam with established bunkering terminals.
- Dual-Fuel Engines:Compression-ignition blocks with port-injected gas capability enable marine and long-haul operators to arbitrage fuel costs at LNG-ready ports.
Established volume favors diesel architectures; emerging adoption favors gasoline-hybrid configurations.
End User:
Customer procurement patterns split between integrated OEMs specifying engine platforms and aftermarket operators replacing powertrains in existing asset bases.
- Automotive Manufacturers:Volkswagen Group, Stellantis, and Mercedes-Benz Group specify engine families across multiple vehicle architectures, demanding modular after-treatment and common rail compatibility.
- Marine Applications:Coastal shipping operators in Mediterranean and Baltic corridors require medium-speed engines with dual-fuel flexibility to comply with IMO emission control area regulations.
- Agricultural Equipment:John Deere and CLAAS specify high-torque diesel engines for combine harvesters and tractors operating across France's cereal belt and Germany's livestock regions.
- Industrial Machinery:Construction equipment OEMs source engines for excavators and wheel loaders where intermittent load cycles favor turbocharged diesel density.
Procurement consolidation among automotive OEMs compresses supplier margins; marine and agricultural end users retain fragmented sourcing with higher service content.
Technology:
Forced induction and combustion control technologies determine thermal efficiency ceilings and emission compliance costs across European engine portfolios.
- Direct Injection:High-pressure fuel delivery above 350 bar enables lean combustion strategies that reduce particulate output while maintaining power density. German passenger vehicle OEMs deploy this across gasoline and diesel architectures to meet Euro 7 laboratory test cycles.
- Turbocharged:Variable geometry turbines with electric actuation recover exhaust energy to boost low-end torque without displacement penalties. BorgWarner and Garrett Motion supply 80 percent of European demand, creating concentration risk.
- Supercharged:Belt-driven compressors deliver immediate boost response for high-performance applications where transient torque matters more than peak efficiency.
- Hybrid Integration:48-volt belt-alternator starter systems enable coasting, boost, and recuperation without full electrification complexity. French malus écologique penalties accelerate adoption in premium passenger segments.
Mature deployment centers on turbocharged architectures; regulatory pressure is accelerating hybrid integration fastest.
Application:
Duty cycle characteristics—load factor, operating hours, and speed profile—dictate engine sizing and durability specifications across mobility and equipment segments.
- Commercial Vehicles:Long-haul tractors and rigid trucks above 3.5 tonnes retain diesel dominance where battery energy density cannot match range requirements. Poland's freight corridor expansion sustains replacement cycles.
- Passenger Vehicles:C-segment and above platforms integrate downsized gasoline engines with hybrid assist to balance performance and fleet CO2 compliance.
- Construction Equipment:Excavators and wheel loaders operate in transient load regimes where diesel torque response outweighs electrification timelines for heavy lifting cycles.
- Recreational Vehicles:Motorhomes and pleasure craft prioritize noise suppression and fuel flexibility over peak efficiency, favoring gasoline and dual-fuel configurations.
Commercial vehicle applications anchor current volume; passenger vehicle powertrains face the steepest technology substitution pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement departments in Germany, Poland, and France concentrate replacement demand for heavy-duty diesel powertrains. Industrial clusters in Italy and Spain sustain engineering capacity for gasoline-hybrid integration. Regulatory divergence across these markets fragments compliance investment.
Germany
Volkswagen Group and Mercedes-Benz Group anchor passenger vehicle engine demand through Stuttgart and Wolfsburg engineering centers. The KBA enforces Euro 7 type-approval procedures that compress development timelines for domestic OEMs. Munich's automotive supplier corridor concentrates thermal management and after-treatment R&D investment.
Poland
Long-haul freight operators along the Baltic-Adriatic TEN-T corridor sustain heavy-duty diesel replacement cycles. EU cohesion fund infrastructure allocations accelerate corridor upgrades through 2027. Silesian manufacturing zones host engine component fabrication for German OEM supply chains.
France
Stellantis integrates downsized gasoline engines with 48-volt mild-hybrid systems to offset malus écologique fleet penalties. ANSM and DGAC coordinate emission enforcement with EU Green Deal carbon-border adjustment protocols. Île-de-France hosts powertrain calibration centers serving premium passenger segments.
Italy
Ferrari and Lamborghini anchor high-performance gasoline engine demand with pre-chamber ignition development. EMA guidelines shape pharmaceutical logistics fleet procurement, indirectly sustaining commercial vehicle diesel demand. Emilia-Romagna's motor valley clusters engineering talent for combustion optimization.
Spain
SEAT and Ford Valencia manufacture gasoline engines for European export markets. Port of Barcelona LNG terminal expansions create dual-fuel marine engine demand for Mediterranean coastal shipping. Catalonia's automotive supplier base retools for hybrid-integrated powertrain component supply.
Europe Internal Combustion Engines Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. German and Swedish automotive OEMs consolidate procurement across passenger, commercial, and off-highway divisions, compressing supplier margins. Three archetypes dominate: integrated automotive groups with captive engine production, commercial vehicle specialists with heavy-duty diesel focus, and Asian manufacturers with scale-driven hybrid integration. Competitive moves center on multi-division platform agreements and synthetic fuel compatibility validation.
Among Germany-based automotive groups, Volkswagen Group, Bayerische Motoren Werke AG, and Mercedes-Benz Group exemplify the integrated OEM archetype with captive powertrain development. Volvo AB and MAN SE occupy positions within the commercial vehicle specialist tier, anchoring heavy-duty diesel demand in Nordic and Central European freight corridors. Toyota Motor Corporation represents the scale-driven hybrid integrator, leveraging gasoline engine refinement for 48-volt and full-hybrid architectures across multiple European markets.
| Leading Market Players |
|---|
| Volkswagen Group |
| Audi |
| Volvo AB |
| MAN SE |
| Bayerische Motoren Werke AG |
| Toyota Motor Corporation |
| Hyundai Motors |
| Mercedes-Benz Group |
| Stellantis |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Silesian engine component fabrication is forcing Polish suppliers into aggressive price competition, compressing margins across the diesel powertrain supply base while German OEMs consolidate procurement leverage. This utilization imbalance rewards scaled producers with thermal management expertise and marginalizes mid-tier foundries lacking Euro 7 certification investment.
Pricing Analysis
Cost-plus contracts indexed to platinum group metal spot markets dominate heavy-duty diesel after-treatment procurement, transferring palladium and rhodium volatility directly to fleet operators. Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified remanufactured engines from grey-market rebuilds and authorized dealer channels. Pricing pressure stems from electrification substitution in last-mile logistics below 3.5 tonnes. Municipal bus fleets in Romania and Bulgaria exhibit highest price sensitivity due to EU cohesion fund dependency, while German premium passenger OEMs prioritize thermal efficiency over unit cost.
Supply Chain Analysis
Tariff exposure between China and Germany dominates turbocharger sourcing risk for European engine manufacturers dependent on BorgWarner and Garrett Motion variable geometry systems. Component fabrication concentrates in Germany, Poland, and the Czech Republic, with final assembly anchored in Wolfsburg, Stuttgart, and Turin. High-pressure common rail injection systems, particulate filter substrates, and electric actuator modules represent critical input dependencies. Single-source vulnerability in variable geometry turbo supply creates concentration risk. Distribution runs through captive OEM logistics networks for new powertrains and fragmented aftermarket channels for remanufactured units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across hybrid integration timelines creates niche opportunities for specialists serving the gap between pure ICE and full electrification. Euro 7 compliance cost divergence between scaled OEMs and component suppliers is redistributing margin pools toward thermal management and after-treatment engineering.
For Market Incumbents: Entrench platform standardization across passenger, commercial, and off-highway divisions to amortize Euro 7 validation costs. Volkswagen Group and Stellantis procurement consolidation compresses supplier margins; backward integration into thermal management circuits defends position. Captive production of high-pressure direct injection systems limits exposure to Bosch and Continental pricing power. For New Entrants and Emerging Players: Mid-market commercial vehicle fleets in Poland and Romania represent the most penetrable entry point for Euro 6d-compliant diesel remanufacturing. Synthetic fuel compatibility validation for existing engine architectures opens service revenue streams without block replacement investment. Partner with municipal bus operators on LNG dual-fuel retrofits leveraging Rotterdam and Barcelona bunkering infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among certified engine remanufacturers with formal OEM partnerships. Long-term viability in this market hinges on synthetic fuel drop-in compatibility and hybrid integration service capabilities. Acquisition targets should demonstrate thermal management R&D depth and established Euro 7 type-approval relationships. Monitor battery-electric commercial vehicle range extension as the critical inflection signal for diesel replacement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen Group's modular matrix reduces Euro 7 validation costs across gasoline, diesel, and hybrid architectures. |
| Backward Integration | Mercedes-Benz Group in-house production of thermal management circuits limits supplier margin capture. |
| Synthetic Fuel Validation | Porsche and Siemens Energy's Haru Oni pilot certifies engine architectures for renewable gasoline compatibility. |
| Remanufacturing Certification | France's reparability index creates formal channel advantages for OEM-authorized engine rebuild programs. |
| Dual-Fuel Bunkering Partnership | MAN SE marine engine contracts leverage Rotterdam LNG terminal expansion for Mediterranean coastal shipping. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier 1 supplier procurement data anchors the qualitative findings. Primary interviews with powertrain calibration specialists, thermal management R&D directors, fleet procurement managers, and aftermarket service heads combined with secondary validation from KBA type-approval filings, EMA regulatory guidance, EU Green Deal carbon-border adjustment protocols, and vehicle production databases. Bottom-up segment sizing and top-down macroeconomic triangulation ensure consistency across the analysis window.
Calibration against historical Euro 6 adoption curves and real-driving emission test cycle implementation timelines shapes the projection framework. Segmentation dimensions include fuel type, vehicle class, propulsion architecture, and regional regulatory cluster across the modeling period. CAGRs derive from weighted average of scenario-based volume trajectories. Forecast inputs incorporate Euro 7 certification timeline compression and hybrid powertrain mandate enforcement intensity by member state.
Practitioners should monitor battery-electric commercial vehicle range extension and synthetic fuel production scale-up for early signals of ICE demand inflection. Forecasts reflect assumptions regarding regulatory enforcement consistency and platinum group metal price stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Fuel Injection Pump Market
Powertrain
Power Liftgate for Automotive Market
Powertrain
Continuously Variable Transmission (CVT) Market
Powertrain
Transmission Oil Pumps Market
Powertrain
Automotive Drivetrain Market
Powertrain
Automotive Crankshaft Market
Powertrain
Power Assisted Steering Market
Powertrain
Turbocharger Actuators Market
Powertrain
Automotive Powertrain Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Global Automotive Engine Cover Market
Powertrain
Canada Automotive Engine Oils Market
Powertrain
Asia-Pacific Torque Vectoring Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Automotive Driveline Market