
 Electric Powertrain Systems Market | 2026-2036
Electric Powertrain Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Powertrain Systems Market Insights
The shift from outsourced powertrain assembly toward captive in-house motor and inverter production is pivoting how OEMs manage supplier relationships. Tesla Inc dominates vertical integration by controlling cell-to-pack battery architecture and permanent magnet motor design. Robert Bosch GmbH anchors its position through sustained investment in 800-volt inverter platforms and thermal management software. Continental AG competes by leveraging its integrated axle systems for European premium passenger vehicle programs.
Electric powertrain systems comprise the integrated assembly of traction motors, power electronics, energy storage units, and thermal management hardware that converts electrical energy into mechanical propulsion, typically operating at voltages from 400V to 800V in contemporary architectures. These systems replace internal combustion engines in battery-electric and hybrid configurations, serving the primary purpose of zero-emission or reduced-emission vehicle propulsion across road, marine, and industrial mobility platforms. Battery Electric configurations occupy the dominant margin pool as cell chemistry costs decline and energy density improves, while Hybrid Electric maintains structural relevance in regions where charging infrastructure remains sparse. Thermal Management technology is emerging as a critical differentiation layer as manufacturers push power density limits in performance vehicle and commercial fleet applications.
The EPA tailpipe standards, EU F-Gas Regulation, and China's MIIT dual carbon goals collectively mandate electrification timelines that compress supplier development cycles and enforce efficiency benchmarks. REACH compliance and CE marking requirements in Europe restrict rare-earth magnet sourcing and power electronics material composition, reshaping procurement geography for motor manufacturers. Stakeholders must monitor how battery recycling mandates and raw material certification schemes alter cost structures before committing to long-term platform architectures.
Market Dynamics
The Electric Powertrain Systems Market is undergoing a fundamental reconfiguration as OEMs abandon outsourced motor-inverter assembly in favor of captive production architectures. This shift compresses supplier margins while concentrating technical capability within vertically integrated vehicle manufacturers.
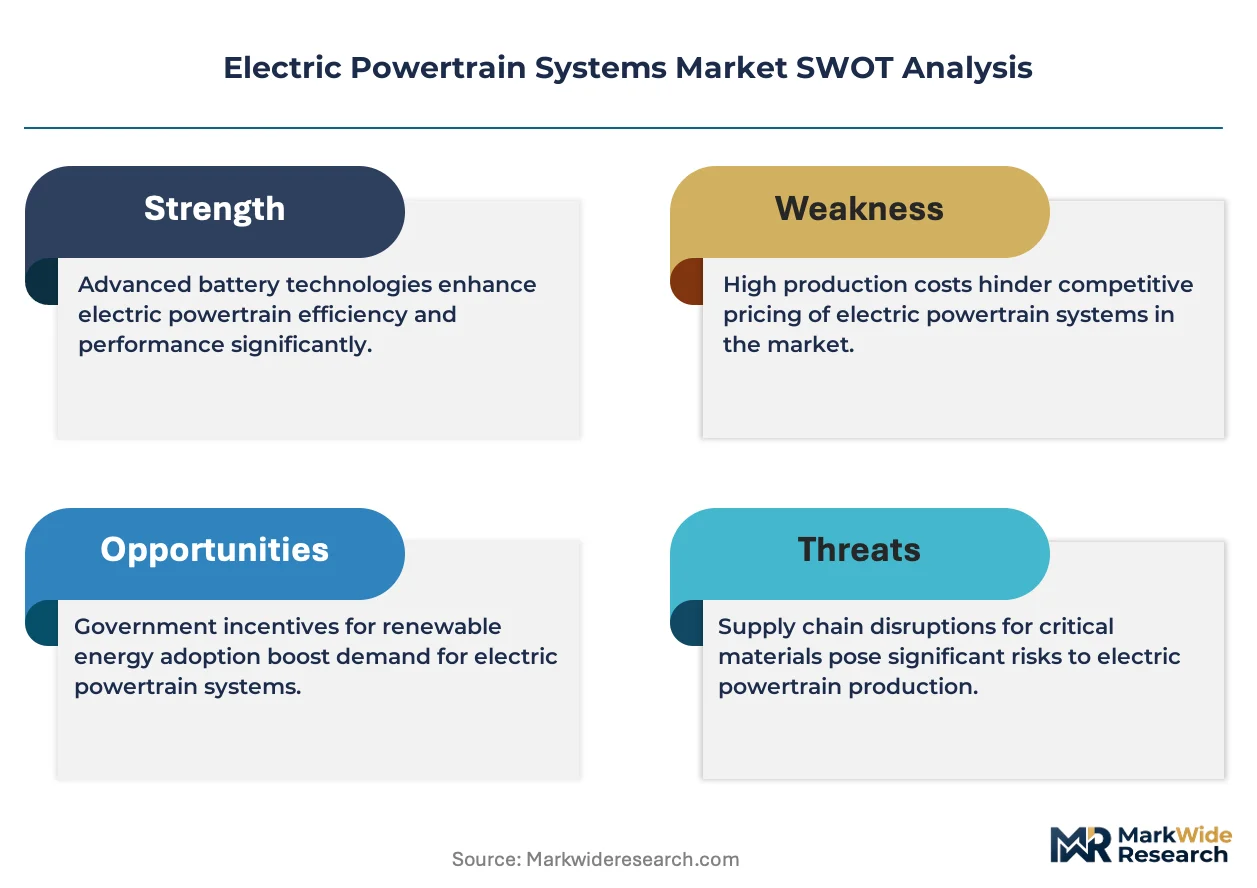
Growth Catalysts
- EU CO2 Fleet Mandates:Binding emission reduction targets for medium- and heavy-duty vehicles are compelling European commercial fleet operators to accelerate battery-electric procurement timelines.
- 800-Volt Platform Migration:High-voltage architectures are reducing charging durations and enabling lighter cabling harnesses across premium passenger vehicle segments.
- Shanghai-Shenzhen Industrial Corridor:Dense clustering of cell-to-pack manufacturing and permanent magnet motor production is compressing component lead times for domestic Chinese OEMs.
Market Restraints
- Neodymium-Dysprosium Price Volatility:Rare-earth magnet cost swings are destabilizing motor cost models and forcing redesigns toward ferrite or externally-excited synchronous alternatives.
- Southeast Asian Semiconductor Concentration:Power module foundry capacity bottlenecks in Malaysia and Vietnam are extending inverter delivery schedules for European tier suppliers.
- REACH Compliance Friction:European chemical registration requirements are restricting epoxy resin and thermal interface material formulations, forcing reformulation cycles that delay platform launches.
Strategic Opportunities
- Marine Electrification:Harbor craft and short-sea shipping operators in Norway and Denmark are specifying integrated electric propulsion systems for zero-emission zone compliance.
- US IRA Manufacturing Credits:Domestic content bonus thresholds are incentivizing North American cell and module assembly investments that reshape procurement geography.
- Solid-State Battery Convergence:Silicon carbide inverters paired with sulfide electrolyte cells are opening thermal management architectures incompatible with incumbent liquid-cooled designs.
Industry Challenges
- Power Electronics Firmware Talent Scarcity:Shortages of engineers proficient in motor control algorithms and functional safety (ISO 26262) are inflating R&D compensation costs.
- Homologation Timeline Compression:Parallel certification requirements across EPA, UNECE, and China's MIIT are forcing redundant validation testing that strains program budgets.
- Legacy Platform Integration Complexity:Retrofitting electric axles into existing vehicle architectures requires redesigning crash structures and suspension mounting points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Powertrain Systems Market |
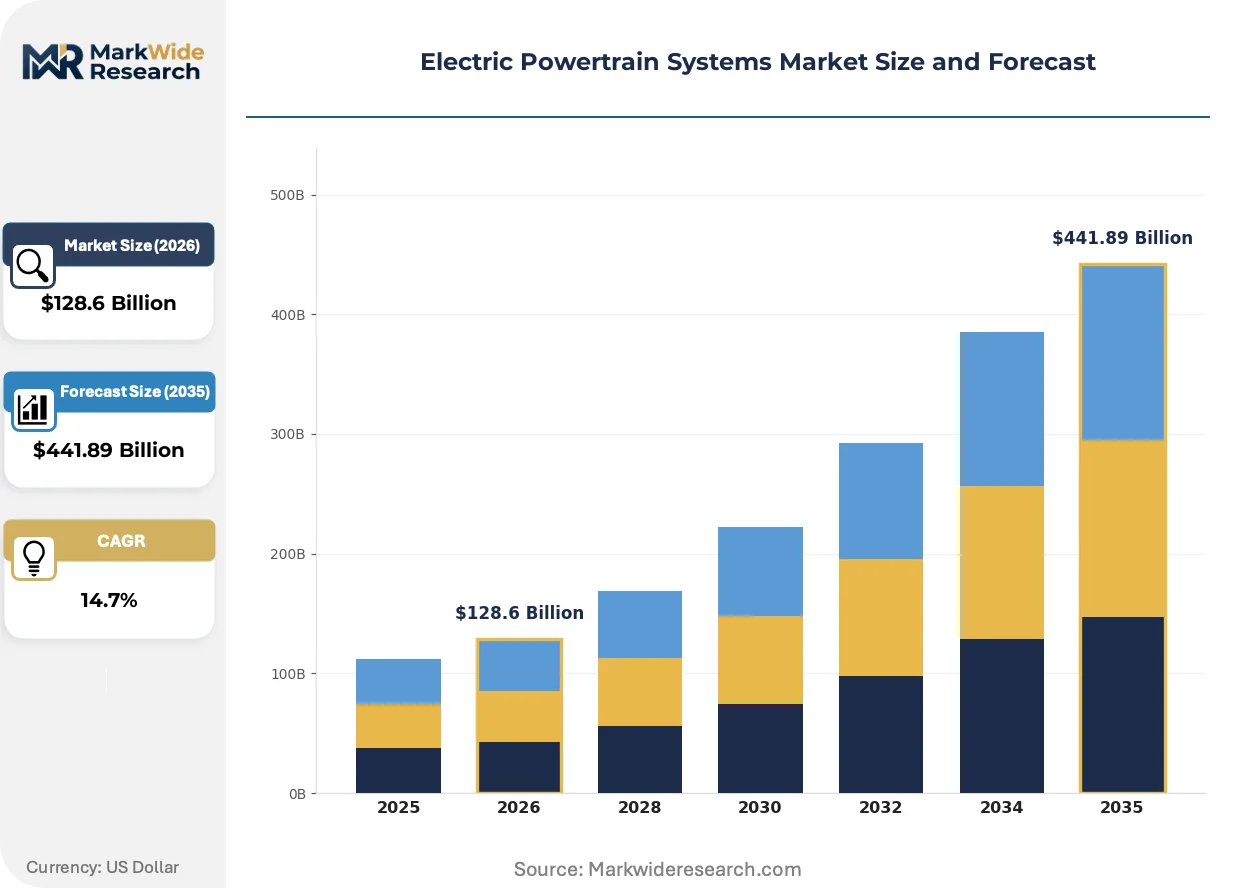
| Market Size in 2026 | $128.6 Billion |
| Market Size in 2035 | $441.89 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Electric, Hybrid Electric, Plug-in Hybrid, Fuel Cell End User: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Transport Fleets Technology: Regenerative Braking, Energy Management, Thermal Management, Power Distribution Application: Urban Mobility, Long-Distance Travel, Performance Vehicles, Marine Applications |
| Companies Covered | Tesla Inc, Robert Bosch GmbH, Continental AG, BorgWarner Inc, Magna International Inc, ZF Friedrichshafen AG, BYD Co Ltd, Hitachi Astemo Americas Inc, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Powertrain Systems Market Trends and Innovations
Power density escalation and thermal management sophistication are redefining competitive differentiation in electric powertrain architectures. Manufacturers are racing to integrate functions previously handled by discrete subsystems.
Silicon carbide MOSFET technology is replacing silicon IGBTs in traction inverters, enabling switching frequencies above 20 kHz that shrink passive component volumes. Commercial vehicle manufacturers in Germany and California are adopting these modules for 800-volt platforms. The technology is modularizing inverter designs, allowing scalable power stages that serve passenger cars and heavy trucks from common hardware bases.
China's MIIT dual carbon goals are mandating battery recycling traceability that extends upstream to cathode precursor sourcing. This regulatory architecture is forcing European and Korean cell suppliers to establish local joint ventures for black mass processing. The policy is reshaping raw material procurement geography, with compliance costs concentrating among smaller pack assemblers lacking integrated recycling partnerships.
Fleet operators are consolidating powertrain procurement under total cost of ownership frameworks that internalize residual value risk previously borne by lessors. Large logistics providers in the Netherlands and California are negotiating direct cell supply agreements that bypass traditional tier-one integrators. This purchasing model shift is most visible in North American last-mile delivery, where operators specify battery-electric step vans with guaranteed degradation warranties rather than standard equipment leases.
Electric Powertrain Systems Market Segmentation
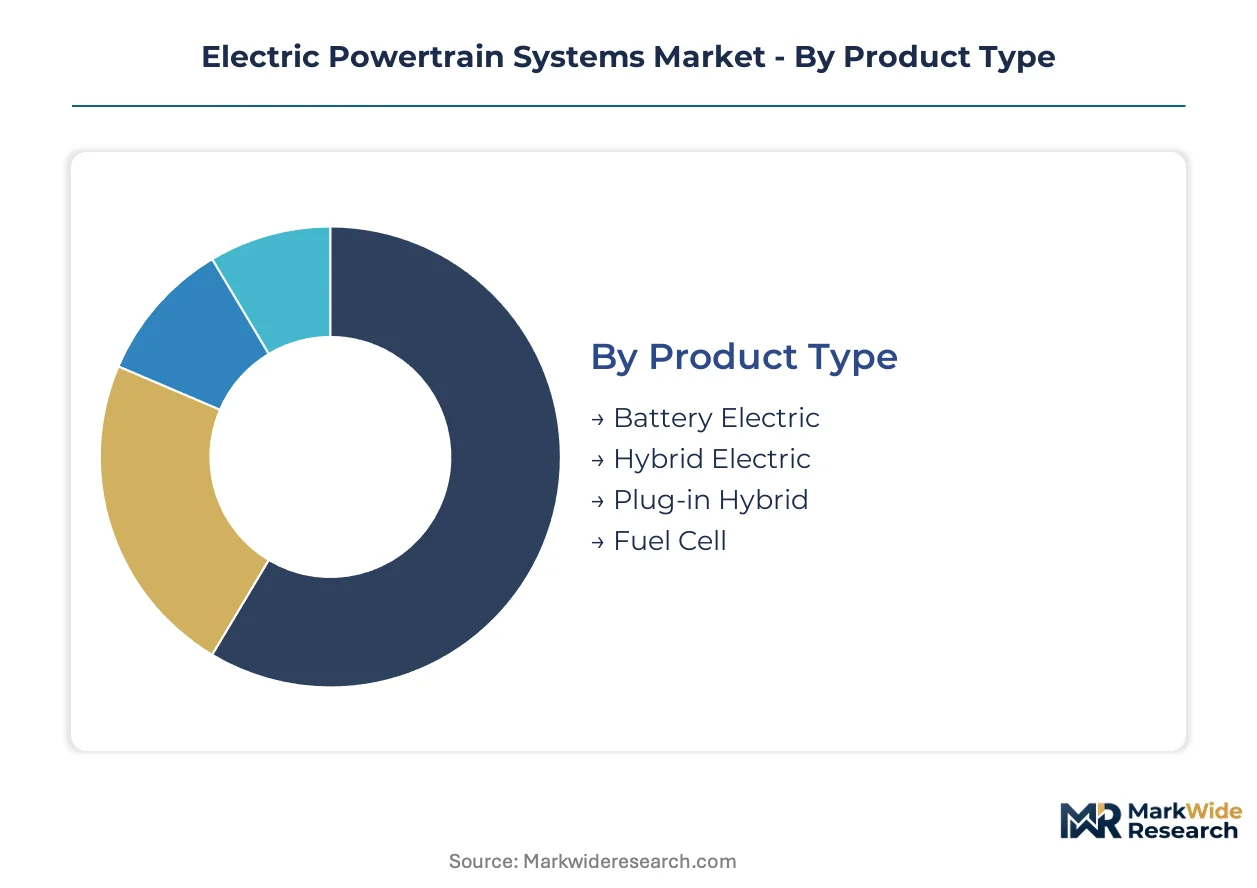
Powertrain architectures diverge sharply between high-volume commodity applications and premium performance segments, with each configuration demanding distinct thermal, electrical, and packaging specifications. Understanding these fault lines enables suppliers to align R&D investment with margin concentration and regulatory exposure.
Product Type:
Volume deployment concentrates in battery-dominant architectures, while premium positioning attaches to range-extended and zero-emission alternatives that command higher unit economics.
- Battery Electric:Fully-electric architectures eliminate mechanical transmission complexity through direct-drive motors paired with cell-to-pack battery structures. Demand clusters in China's Yangtze River Delta manufacturing corridor, where BYD and CATL's integrated supply chains compress procurement lead times for domestic OEMs facing MIIT dual carbon compliance deadlines.
- Hybrid Electric:Parallel and series-parallel configurations retain internal combustion range extension while downsizing engines through electric torque supplementation. Commercial fleet operators in Germany and California specify these systems for route flexibility where charging infrastructure remains incomplete, though EPA tailpipe standards are narrowing their regulatory runway.
- Plug-in Hybrid:Larger battery capacities enable 40-80 kilometer electric-only operation before combustion engagement, appealing to premium passenger segments with garage charging access.
- Fuel Cell:Proton-exchange membrane stacks paired with hydrogen storage serve heavy-duty trucking corridors in South Korea and Japan where METI subsidies offset infrastructure capital requirements.
Mature deployment sits with Hybrid Electric. Newer deployment is concentrated in Battery Electric.
End User:
Customer procurement patterns split between individual ownership with residual value sensitivity and fleet operators optimizing total cost of ownership through guaranteed degradation warranties.
- Passenger Vehicles:Private ownership demands prioritize charging speed and cabin thermal comfort over absolute power density, shaping 400V to 800V platform decisions.
- Commercial Vehicles:Medium- and heavy-duty specifications require continuous duty cycles and regenerative braking energy recovery that strains thermal management capacity. Last-mile delivery operators in the Netherlands negotiate direct cell supply agreements that bypass tier-one integrators, internalizing residual value risk previously borne by lessors.
- Two-Wheelers:Swappable battery architectures dominate Southeast Asian urban cores where grid reliability varies and parking constraints prevent overnight charging.
- Transport Fleets:Consolidated procurement under total cost of ownership frameworks is visible across North American postal and parcel networks specifying battery-electric step vans with performance guarantees rather than standard equipment leases.
Fleet consolidation is advancing fastest in Transport Fleets. Individual ownership retains structural importance in Passenger Vehicles.
Technology:
System integration priorities shift from power conversion efficiency toward thermal stability as manufacturers push power density limits in performance and commercial applications.
- Regenerative Braking:Kinetic energy recovery through motor-generator units recaptures deceleration energy to extend range, with calibration sophistication determining driver acceptance.
- Energy Management:Battery state-of-charge algorithms and predictive routing optimization coordinate propulsion and auxiliary loads.
- Thermal Management:Liquid cooling circuits, heat pumps, and phase-change materials stabilize cell temperatures across ambient extremes. Performance vehicle manufacturers in Germany are specifying these systems as primary differentiation layers as power density escalates beyond 4 kW per liter.
- Power Distribution:High-voltage bus architectures and DC-DC conversion manage energy flow between battery, motor, and auxiliary systems with fault tolerance for ISO 26262 functional safety compliance.
Thermal Management is gaining share fastest as power density escalation strains incumbent cooling designs. Energy Management remains foundational across all architectures.
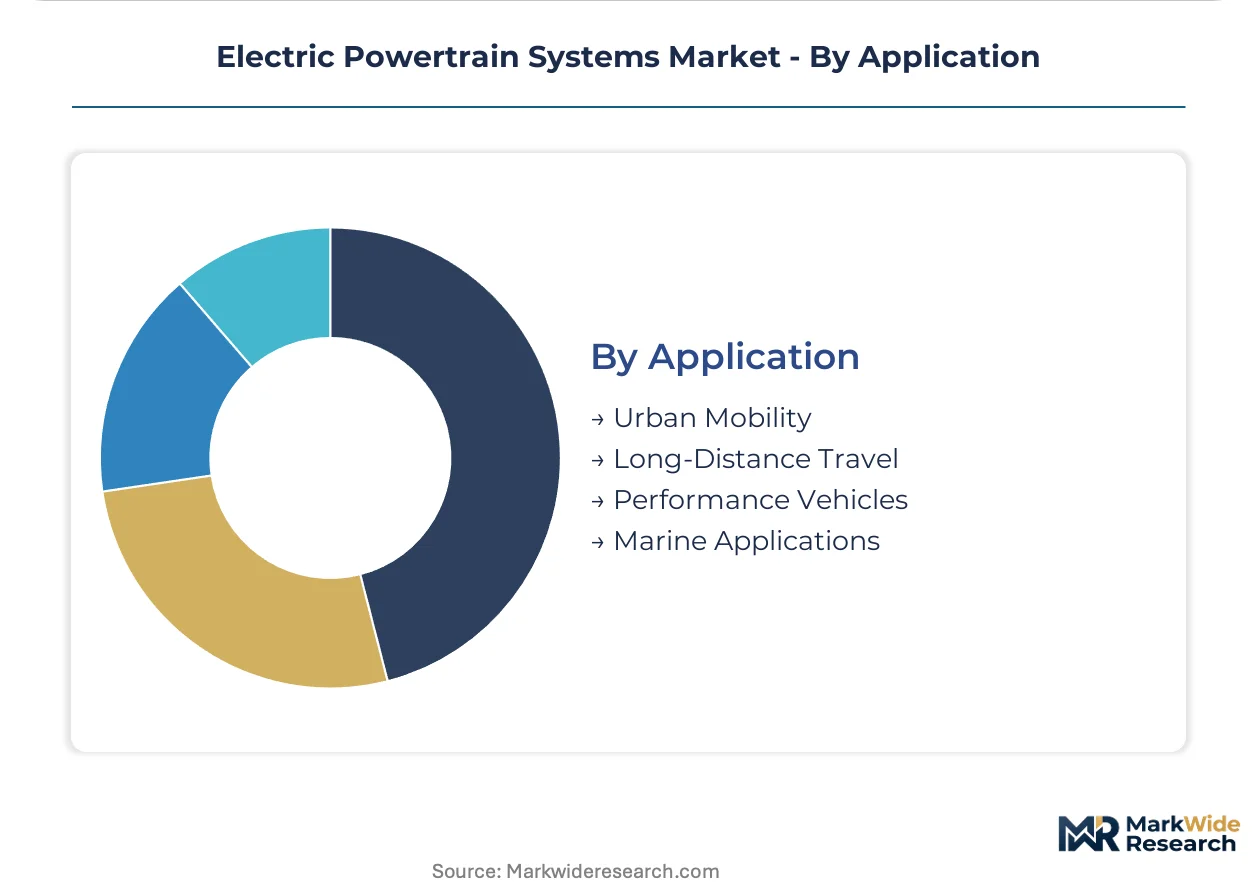
Application:
Use case differentiation separates urban duty cycles with predictable regeneration opportunities from sustained high-load operation demanding thermal headroom.
- Urban Mobility:Stop-start operation with frequent regenerative braking events favors compact motor packaging and rapid thermal cycling durability. Micro-mobility and last-mile logistics in Shenzhen and Rotterdam specify these configurations for zero-emission zone compliance with minimal range anxiety.
- Long-Distance Travel:Sustained highway speeds demand aerodynamic efficiency and 800V fast-charging compatibility to minimize dwell time.
- Performance Vehicles:Track-capable thermal management and torque vectoring through dual-motor architectures command premium positioning.
- Marine Applications:Harbor craft and short-sea shipping in Norway and Denmark specify integrated electric propulsion for zero-emission zone mandates, with battery-swapping infrastructure replacing shore power constraints.
Urban Mobility anchors current volume. Marine Applications are expanding most quickly as regulatory deadlines for port emissions harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial corridor from Shanghai to Shenzhen commands the densest concentration of cell-to-pack manufacturing and permanent magnet motor production, compressing procurement lead times for domestic OEMs facing MIIT dual carbon compliance deadlines. Germany and the United States follow as secondary demand centers where EPA tailpipe standards and EU CO2 fleet mandates accelerate commercial fleet electrification.
China
Domestic OEM procurement concentrates in the Yangtze River Delta and Pearl River Delta manufacturing belts where BYD and CATL anchor integrated battery-motor-inverter supply chains. MIIT dual carbon goals mandate battery recycling traceability extending upstream to cathode precursor sourcing, forcing foreign cell suppliers into local joint ventures for black mass processing. Shenzhen and Shanghai host the tightest clustering of permanent magnet motor foundries serving zero-emission commercial vehicle programs.
Germany
Commercial fleet operators in North Rhine-Westphalia and Bavaria accelerate battery-electric procurement as EU CO2 fleet mandates for medium- and heavy-duty vehicles harden. KBA homologation requirements intersect with REACH compliance friction, restricting epoxy resin formulations and thermal interface materials. Stuttgart and Munich anchor development of 800-volt inverter platforms and integrated axle systems for premium passenger vehicle programs.
United States
Last-mile delivery operators in California and the Midwest negotiate direct cell supply agreements that bypass traditional tier-one integrators, internalizing residual value risk. EPA tailpipe standards tighten faster than infrastructure deployment, creating regulatory pressure in advance of charging network completion. Detroit and the San Francisco Bay Area concentrate power electronics firmware talent pools, though ISO 26262 functional safety expertise remains scarce.
South Korea
Heavy-duty trucking corridors between Seoul and Busan deploy proton-exchange membrane fuel cell stacks where METI-aligned subsidies offset hydrogen infrastructure capital requirements. Domestic cell manufacturers face MIIT-mandated recycling traceability requirements when supplying Chinese OEMs, reshaping cathode precursor procurement geography. Incheon and Ulsan host power module foundry capacity serving silicon carbide inverter demand from German tier suppliers.
Japan
Automotive OEMs in Aichi Prefecture and the Kanto region advance externally-excited synchronous motor designs to reduce neodymium-dysprosium exposure amid rare-earth price volatility. METI technology roadmaps coordinate solid-state battery convergence with silicon carbide inverter pairing. Nagoya and Tokyo-Yokohama concentrate thermal management engineering for performance vehicle applications pushing beyond 4 kW per liter power density.
Electric Powertrain Systems Market Competitive Landscape
Backward integration into captive motor and inverter production dominates the current landscape as OEMs abandon outsourced powertrain assembly. The vendor base compresses toward vertically integrated vehicle manufacturers on one vector and specialized component suppliers on another, with tier-one integrators caught in margin pressure between these poles. Two strategic archetypes define positioning: silicon carbide inverter specialists and integrated axle system providers. M&A activity and capacity expansion in 800-volt platform manufacturing represent the dominant competitive moves reshaping supplier relationships.
Among Germany-based diversified suppliers, Robert Bosch GmbH and ZF Friedrichshafen AG exemplify the component-systems archetype, while Tesla Inc represents the vertically integrated OEM model. Continental AG occupies a position between these poles through its integrated axle systems focus. These three entities anchor the competitive structure without exhausting its variation, as Chinese and Japanese manufacturers occupy parallel tracks shaped by domestic regulatory and procurement geography.
| Leading Market Players |
|---|
| Tesla Inc |
| Robert Bosch GmbH |
| Continental AG |
| BorgWarner Inc |
| Magna International Inc |
| ZF Friedrichshafen AG |
| BYD Co Ltd |
| Hitachi Astemo Americas Inc |
| Mitsubishi Electric Corporation |
| Others |
Pricing and Supply Chain Analysis
Neodymium-dysprosium magnet costs cascade from Chinese mining consortiums through motor manufacturers into three-tier pricing structures across premium, standard, and economy levels for passenger and commercial vehicle platforms. Battery cell chemistry expenses anchor the upstream cost stack, with cathode precursor sourcing compliance under China's MIIT dual carbon goals adding certification premiums that tier-one suppliers pass to OEM procurement teams.
Pricing Analysis
Volume deployment in battery-electric architectures compresses unit margins while premium performance segments retain pricing power through thermal management sophistication and 800-volt platform differentiation. Price differentiation rests on silicon carbide inverter certification tiers and guaranteed degradation warranty terms, with fleet operators in California and the Netherlands exhibiting highest sensitivity to total cost of ownership calculations. Cost compression in commodity motor-inverter assemblies intensifies as Chinese domestic suppliers expand capacity, while pricing softness in hybrid electric configurations reflects narrowing regulatory runway under EPA tailpipe standards.
Supply Chain Analysis
US IRA domestic content bonus thresholds and EU REACH compliance requirements are reshaping sourcing geography away from Southeast Asian semiconductor concentration toward North American cell assembly and European thermal interface material reformulation. Power module foundry capacity draws from Malaysia, Vietnam, and South Korea, with rare-earth magnet supply anchored in China's Jiangxi and Inner Mongolia processing corridors. Single-source vulnerability in silicon carbide wafer supply creates structural risk for 800-volt platform ramp schedules. Distribution runs through captive OEM integration for premium segments and tier-one integrator aggregation for commercial fleet volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU CO2 fleet mandates and EPA tailpipe standards erect barrier-to-entry moats favoring players with certified 800-volt platforms and integrated recycling partnerships.
For Market Incumbents: Hedge rare-earth exposure by accelerating externally-excited synchronous motor R&D in Aichi Prefecture and Stuttgart engineering centers while locking ferrite magnet supply agreements. Defend margin position through captive silicon carbide inverter production rather than outsourced power module procurement threatened by Southeast Asian foundry bottlenecks. For New Entrants and Emerging Players: Enter via marine electrification white space in Norwegian harbor craft and Danish short-sea shipping corridors where zero-emission zone mandates outpace incumbent supplier coverage. Target battery-swapping infrastructure partnerships for Southeast Asian two-wheeler fleets as the most penetrable segment lacking integrated thermal management expertise from established automotive tier ones. For Investors and Strategic Acquirers: Distressed-cycle entries favor silicon carbide inverter specialists with ISO 26262 functional safety certification in South Korea and Japan where METI technology roadmaps converge with solid-state battery development. Watch cathode precursor black mass processing joint venture formation as the inflection signal for compliance-cost concentration among smaller pack assemblers.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Inverter Platform Migration | Enables 800-volt architectures that reduce charging dwell time for German premium OEM programs. |
| Cell-to-Pack Battery Supply Agreement | Compresses procurement lead times for Yangtze River Delta OEMs facing MIIT compliance deadlines. |
| Thermal Management Software Investment | Differentiates performance vehicle positioning as power density exceeds 4 kW per liter in Stuttgart. |
| Black Mass Recycling Joint Venture | Satisfies China's MIIT traceability mandates for European and Korean cathode precursor suppliers. |
| Direct Fleet Procurement Model | Bypasses tier-one integrators for California last-mile operators internalizing residual value risk. |
Research Methodology
Document review covered SEC filings from power electronics suppliers, EPA regulatory dockets, and EU ECHA REACH registration databases, complemented by interviews with OEM platform engineers, tier-one supplier procurement leads, commercial fleet operators, and thermal management R&D directors. Secondary validation drew from vehicle production databases, IHS Markit registration data, and MIIT policy circulars. Bottom-up cell and pack demand modeling triangulated against top-down OEM electrification commitment aggregation.
Historical production volume trajectories cross-referenced against expert panel input on silicon carbide adoption curves and solid-state battery convergence timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include propulsion architecture, vehicle class, content per vehicle, and regional regulatory cluster. CAGRs derived from unit shipment elasticity to battery cost decline curves and charging infrastructure deployment density.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare-earth price volatility spikes and Southeast Asian semiconductor supply disruptions. Forecasts reflect assumptions on MIIT dual carbon enforcement intensity and IRA domestic content threshold evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Fuel Cock Market
Powertrain
Colombia Automotive Engine Oils Market
Powertrain
Automotive Oil Sump Market
Powertrain
Clutch Friction Plate Market
Powertrain
North America Electro Hydraulic Power Steering Market
Powertrain
Test Automation Systems for Powertrain Dynamometer Market
Powertrain
Exhaust Flexible Couplings Market
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
Turbocharger Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Fuel Injection Systems Market
Powertrain
Automotive Power Distribution Block Market
Powertrain
Fuel Cell Powertrain Market
Powertrain
Plug-In Hybrid Electric Vehicle Powertrain Market
Powertrain
Car Oil Filter Market