
 Oil Filter Market | 2026-2036
Oil Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Filter Market Intelligence
The gap between premium synthetic media and commodity cellulose oil filters is recalibrating procurement patterns across the automotive value chain. MANN+HUMMEL leverages its captive filter media manufacturing to sustain margin control in European OEM supply agreements. MAHLE GmbH anchors its position through deep specialization in modular cartridge architectures for downsized engines. Donaldson Company, Inc. competes in heavy-duty applications where service intervals and contaminant loads demand differentiated engineering.
An oil filter is a fluid conditioning device, typically comprising a steel canister, pleated filter media of cellulose or synthetic polymer, a bypass valve, and anti-drainback seals, designed to remove particulate contaminants and maintain lubricant viscosity integrity within internal combustion and hydraulic systems. Spin-on configurations retain dominant installed base across passenger vehicle aftermarket channels due to familiar service protocols and broad tool compatibility, while cartridge formats gain structural ground in European and Asian OEM assembly as lightweighting and material-recovery regulations tighten. Mechanical filtration technology still occupies the majority of unit volume, though advanced filtration incorporating multi-layer synthetic media and electronic pressure-differential sensing commands expanding share in premium segments and industrial equipment uptime contracts.
EPA tailpipe and crankcase emissions standards in the United States, ECE R24 type-approval requirements in Europe, and China's Stage VI fuel quality and vehicle emissions rules collectively elevate filter efficiency mandates and accelerate replacement cycles in regulated fleets. California Air Resources Board protocols and EU Green Deal-aligned CO2 reduction pathways are embedding filter performance into broader powertrain compliance architectures. Stakeholders must monitor how electrification transition timelines in major automotive markets reshape aftermarket demand trajectories and filter technology investment priorities.
Market Dynamics
Fleet operators are compressing service intervals to protect powertrain warranty coverage, while California Air Resources Board and EU Green Deal protocols force filter media upgrades that ripple through aftermarket procurement calendars.
Growth Catalysts
- EU Stage V particulate mandates:Non-road mobile machinery regulations in Europe require high-efficiency filtration for engines above 19 kW, pulling demand toward synthetic-nanofiber composite media.
- Extended drain intervals:Synthetic lubricant formulations now support 15,000-mile service cycles in passenger vehicles, increasing per-unit filter performance requirements and replacement value capture.
- China:Domestic vehicle parc expansion above 300 million units and localized aftermarket supply chains concentrate volume growth in eastern manufacturing clusters.
Market Restraints
- Steel canister cost volatility:Cold-rolled steel input prices fluctuate with energy-intensive European smelter output, compressing margin on spin-on filter formats.
- Cellulose media supply concentration:Hardwood pulp sourcing clusters in southeastern United States and Scandinavian timber regions create geographic concentration risk for commodity filter grades.
- Bypass valve calibration limits:Mechanical spring-actuated designs face pressure-differential accuracy constraints that cap filtration efficiency gains in high-viscosity cold-start conditions.
Strategic Opportunities
- India:PLI scheme incentives for automotive component manufacturing attract filter assembly investment as domestic vehicle production scales toward 5 million annual units.
- Predictive maintenance integration:Pressure-differential sensors and telematics platforms enable condition-based filter replacement, opening service contract models for industrial fleet operators.
- Modular cartridge architectures:Lightweighting regulations in Germany and France favor plastic housing designs with tool-less service protocols, displacing metal canister formats in OEM assembly.
Industry Challenges
- Filter media engineering talent:Synthetic polymer and nanofiber layer design requires materials science specialization that competes with battery and semiconductor sectors for technical graduates.
- Cross-contamination certification:API SP and ILSAC GF-6 lubricant standards demand validated compatibility testing that extends new product qualification timelines.
- Reverse logistics infrastructure:Core return programs for cartridge element recovery require collection network density that fragments across dispersed rural service territories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Filter Market |
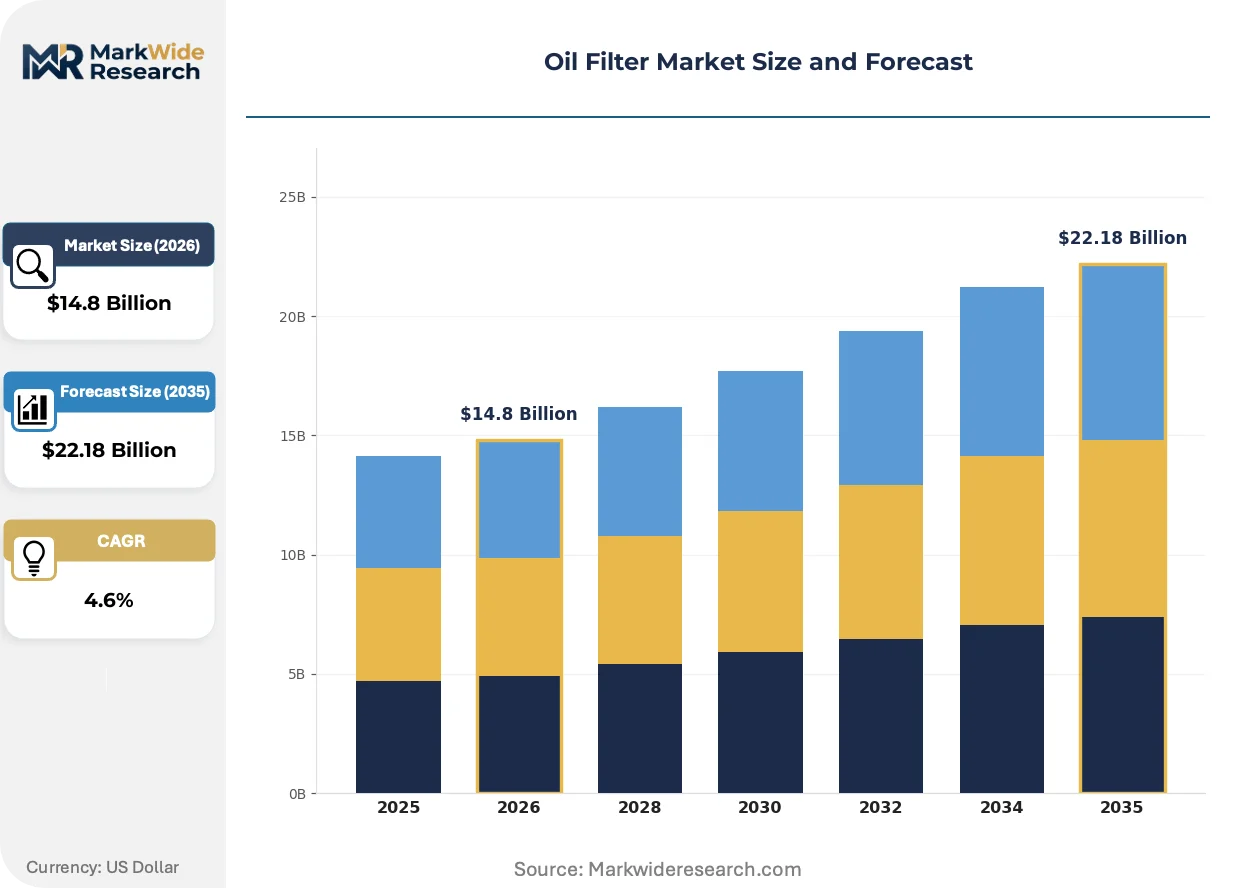
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spin-On, Cartridge, Oil Bath, Screen Technology: Mechanical, Electronic, Hybrid, Advanced Filtration Application: Passenger Vehicles, Heavy-Duty Vehicles, Industrial Equipment, Marine End User: Automotive OEMs, Aftermarket Suppliers, Fleet Operators, DIY Consumers |
| Companies Covered | MANN+HUMMEL, MAHLE GmbH, Donaldson Company, Inc., Denso Corporation, Sogefi SpA, Hengst SE & Co. KG, Robert Bosch GmbH, Cummins Inc., FRAM Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Filter Market Strategic Shifts & Innovations
Synthetic media layers are displacing cellulose as the baseline specification, while regulatory pressure on particulate emissions fuses filter performance into powertrain compliance architectures.
Multi-layer synthetic-nanofiber composite media is consolidating technical differentiation in premium filter segments. Heavy-duty fleet operators with uptime contracts now specify 99% efficiency at 20-micron ratings as standard procurement language. This technology compression is marginalizing single-layer cellulose designs to price-sensitive economy channels.
California Air Resources Board crankcase emissions protocols now embed filter efficiency into heavy-duty engine certification pathways. Manufacturers must demonstrate 95% particulate capture across duty cycles to maintain CARB compliance. The regulation is forcing aftermarket suppliers to upgrade test lab capacity and documentation systems for California-registered fleets.
Service bundling is fragmenting as fleet maintenance software unbundles filter replacement from full-service contracts. Independent quick-lube chains now compete directly with OEM dealer networks on price transparency for scheduled maintenance. This channel disintermediation is most visible in United States suburban markets where digital scheduling platforms aggregate consumer demand.
Oil Filter Market Segmentation
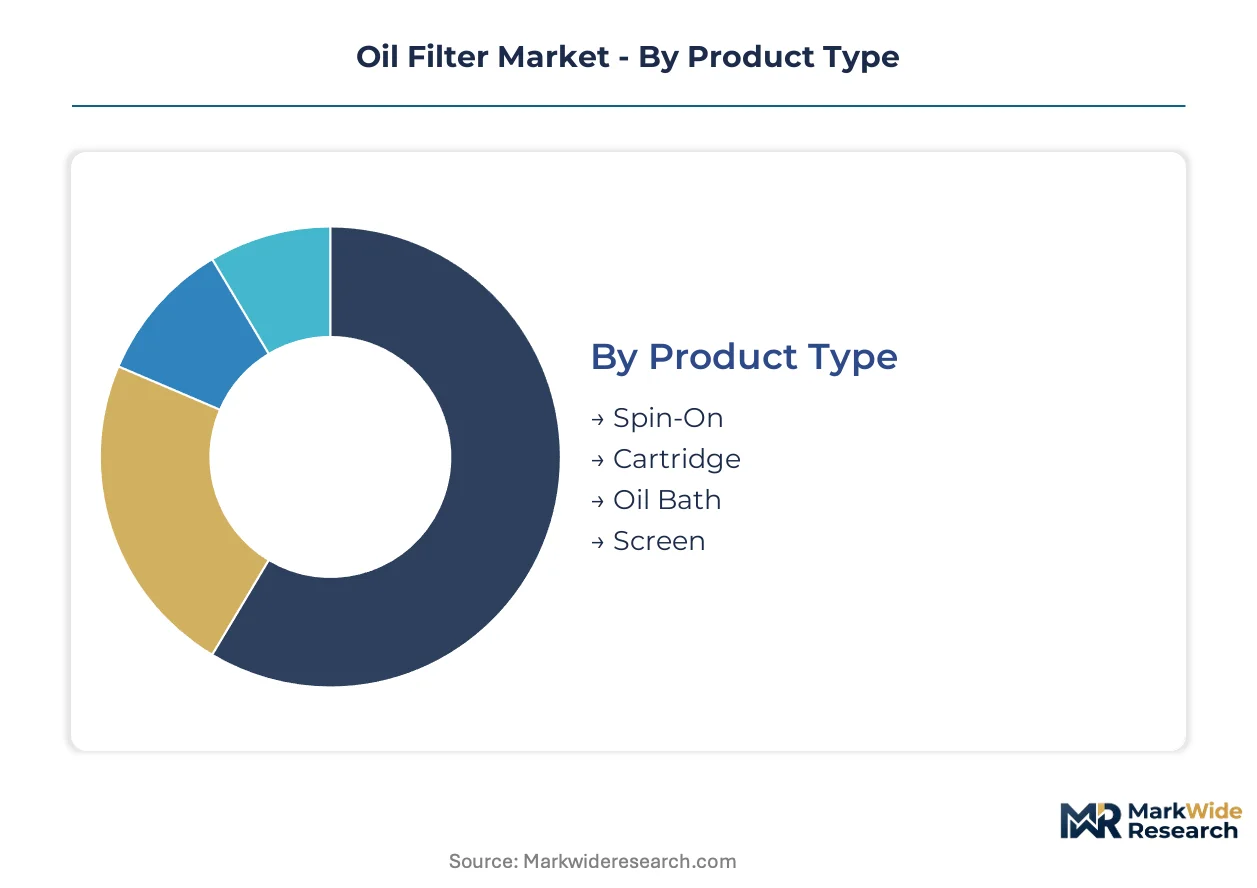
Oil filter procurement decisions map directly to certification pathways, with CARB crankcase protocols and EU Stage V mandates filtering which technologies qualify for fleet contracts. Segment boundaries harden around efficiency ratings and service interval compatibility, not just mechanical form factors.
Product Type:
API SP and ILSAC GF-6 lubricant standards impose validation burdens that spin-on and cartridge formats navigate differently, with plastic-housed cartridges facing additional material-recovery documentation for EU Green Deal alignment.
- Spin-On:Steel canister construction with integrated bypass valve and anti-drainback seal dominates United States quick-lube channels due to tool-standardized removal protocols. Fleet operators in Texas and California specify spin-on for service interval predictability under CARB-monitored maintenance programs, though cold-rolled steel input volatility compresses margin on commodity grades.
- Cartridge:Modular plastic housing with replaceable filter element gains OEM assembly share in Germany and France under lightweighting regulations; tool-less service protocols reduce technician labor time. The format requires denser core return logistics that fragment across rural United States service territories, slowing aftermarket penetration outside urban clusters.
- Oil Bath:Immersion filtration using oil-coated mesh screens persists in vintage agricultural equipment and certain industrial compressors where particulate loads tolerate lower efficiency thresholds.
- Screen:Metal mesh strainers without disposable media serve hydraulic systems and small-engine applications in price-sensitive economy channels.
Leading the category by volume: Spin-On. Expanding most quickly: Cartridge.
Technology:
Cost stratification separates mechanical baseline from premium-tier synthetic-nanofiber composites, with electronic sensing commanding service-contract premiums in uptime-guaranteed fleets.
- Mechanical:Single-layer cellulose or basic synthetic media with spring-actuated bypass valves retains majority unit volume in economy aftermarket channels. Cold-start viscosity spikes challenge pressure-differential accuracy, capping efficiency gains in high-duty-cycle applications.
- Advanced Filtration:Multi-layer synthetic-nanofiber composites achieving 99% efficiency at 20-micron ratings consolidate premium positioning; heavy-duty fleet operators with uptime contracts specify this as baseline procurement language. CARB crankcase emissions protocols embed this technology into California-registered heavy-duty engine certification pathways.
- Electronic:Pressure-differential sensors with telematics integration enable condition-based replacement for industrial fleet operators, opening predictive maintenance service contracts.
- Hybrid:Combines mechanical media with electronic monitoring at mid-tier price points for fleet operators transitioning from interval-based to condition-based maintenance.
Mechanical filtration dominates unit shipments. Advanced filtration climbs the fastest on regulatory pull.
Application:
Service interval compression varies sharply by duty cycle, with marine salt-corrosion environments and industrial contaminant loads demanding specialized media engineering.
- Heavy-Duty Vehicles:Extended drain intervals to 15,000 miles on synthetic lubricants increase per-unit filter performance requirements; EPA tailpipe standards and CARB protocols force media upgrades that ripple through aftermarket procurement calendars.
- Passenger Vehicles:Spin-on familiarity and broad tool compatibility sustain aftermarket channel dominance in United States suburban markets where digital scheduling platforms aggregate consumer demand.
- Industrial Equipment:Uptime contracts and contaminant-heavy operating environments drive specification toward advanced filtration with electronic pressure monitoring.
- Marine:Salt-laden intake air and corrosion-resistant housing requirements create specialized procurement channels with distinct certification testing.
Passenger vehicles lead by installed base. Heavy-duty applications gain share fastest on fleet preventive maintenance expansion.
End User:
Channel power concentrates in fleet procurement offices and OEM supply agreements, with DIY fragmentation limiting price-setting leverage for independent retailers.
- Fleet Operators:Compress service intervals to protect powertrain warranty coverage; maintenance software unbundles filter replacement from full-service contracts, creating direct price competition between quick-lube chains and dealer networks.
- Automotive OEMs:Modular cartridge architectures for downsized engines anchor supply agreements in European assembly plants, with plastic housing designs favored under material-recovery regulations.
- Aftermarket Suppliers:Distribute through quick-lube chains and parts retailers, facing margin pressure from steel canister cost volatility and cellulose media supply concentration.
- DIY Consumers:Price-transparent digital platforms aggregate demand in United States suburban markets, fragmenting service bundling and eroding traditional channel premiums.
Fleet operators command the steepest procurement volume. Aftermarket suppliers face the most margin compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit's automotive corridor anchors North American oil filter procurement, with fleet operators and OEM assembly plants driving specification standards that ripple through aftermarket channels.
United States
Texas and California fleet operators compress service intervals under CARB-monitored maintenance programs. EPA tailpipe standards force media upgrades that synchronize with synthetic lubricant drain cycles. Dallas-Fort Worth quick-lube chains compete directly with dealer networks on price transparency for scheduled maintenance.
Germany
Bavarian OEM assembly plants favor modular cartridge architectures for downsized engines under material-recovery regulations. EU Stage V particulate mandates pull demand toward synthetic-nanofiber composite media. Stuttgart-based suppliers leverage captive filter media manufacturing to sustain margin control in European supply agreements.
China
Shanghai and Yangtze River Delta manufacturing clusters concentrate volume growth as domestic vehicle parc expansion exceeds 300 million units. MEE Stage VI fuel quality rules accelerate replacement cycles in regulated fleets. Localized aftermarket supply chains pull procurement eastward from traditional import channels.
India
Maharashtra and Gujarat automotive corridors scale filter assembly investment under PLI scheme incentives. BIS certification requirements extend new product qualification timelines for domestic suppliers. Chennai and Pune production hubs target 5 million annual vehicle units, embedding filter demand into component manufacturing ecosystems.
Japan
Kanto region OEM supply agreements anchor precision filtration requirements for hybrid powertrain architectures. METI industrial standards pressure-differential accuracy specifications challenge mechanical spring-actuated bypass valve designs. Nagoya-based engineering talent competes with battery and semiconductor sectors for materials science specialization.
Oil Filter Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a tiered structure where captive media manufacturing separates margin leaders from commodity assemblers. The vendor base concentrates around three strategic archetypes: integrated media-to-filter manufacturers, modular cartridge specialists, and heavy-duty uptime contractors. M&A activity targets regional distribution density, while backward integration into synthetic polymer supply secures cost control against cellulose pulp volatility.
Within the integrated manufacturing tier, MANN+HUMMEL and MAHLE GmbH exemplify European-based structures with in-house media production capabilities. Donaldson Company, Inc. occupies a position among North American specialists serving heavy-duty applications. These three anchors represent divergent competitive vectors: captive supply control, modular architecture specialization, and industrial fleet uptime contracting.
| Leading Market Players |
|---|
| MANN+HUMMEL |
| MAHLE GmbH |
| Donaldson Company, Inc. |
| Denso Corporation |
| Sogefi SpA |
| Hengst SE & Co. KG |
| Robert Bosch GmbH |
| Cummins Inc. |
| FRAM Group |
| Others |
Cost & Logistics Intelligence
Fleet procurement offices in California and Texas concentrate buying power around uptime-guaranteed service contracts, compressing margins on commodity spin-on filters while elevating value-capture for advanced filtration with electronic monitoring. This buyer concentration forces suppliers to anchor pricing on performance outcomes rather than unit throughput alone.
Pricing Analysis
Uptime-based contracting anchors value pricing for heavy-duty fleet operators who specify 99% efficiency at 20-micron ratings as baseline procurement language. Three-tier pricing structure across premium, standard, and economy levels separates synthetic-nanofiber composites from single-layer cellulose and basic mechanical designs. Cost compression in commodity grades is intensifying because cold-rolled steel input volatility erodes margin on spin-on canister construction. DIY consumers in United States suburban markets show highest price sensitivity, while industrial uptime contractors demonstrate lowest sensitivity due to warranty protection requirements.
Supply Chain Analysis
Direct-to-OEM channels handle high-volume assembly demand from Bavarian and Shanghai manufacturing clusters, while aftermarket distribution runs through quick-lube chains and independent parts retailers. Geographic supply concentration centers on Germany for precision cartridge architectures, China for localized aftermarket volume, and the United States for heavy-duty fleet specification. Raw material dependencies draw from Scandinavian and southeastern United States hardwood pulp for cellulose media, synthetic polymer feedstocks from petrochemical corridors, and cold-rolled steel from European smelters. Single-source vulnerability in cellulose pulp sourcing clusters creates geographic concentration risk. Distribution feeds from tiered manufacturer-distributor-retail networks with core return logistics fragmenting across rural service territories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive filter media manufacturing separates margin leaders from commodity assemblers in a vertical-integration race where backward integration into synthetic polymer supply secures cost control against cellulose pulp volatility.
For Market Incumbents: Cement supply agreements with Bavarian and Shanghai OEM assembly plants by deepening in-house production of multi-layer synthetic-nanofiber media. Lock in cartridge architecture specialization under EU material-recovery regulations to defend against emerging Asian suppliers with localized cost positions. Prioritize certification investment for CARB crankcase emissions protocols to maintain California fleet contract eligibility. For New Entrants and Emerging Players: EU Stage V particulate mandates in Europe open a window for synthetic-nanofiber composite specialists to penetrate non-road mobile machinery channels above 19 kW. Target India's PLI scheme corridors in Maharashtra and Gujarat for assembly investment as domestic vehicle production scales. Pursue tool-less cartridge designs with plastic housing formats to capture lightweighting-driven OEM specification shifts in Germany and France. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap cartridge specialists with captive media testing labs in European manufacturing clusters. Long-term viability hinges on differentiation durability against battery-sector talent competition for materials science graduates. Monitor synthetic lubricant drain interval extension as inflection indicator for per-unit filter value capture compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Polymer Supply | Captive media production insulates margin from cellulose pulp price volatility in commodity grades. |
| Cartridge Architecture Specialization | Modular plastic housing designs align with EU Green Deal material-recovery mandates in German assembly. |
| Electronic Pressure-Differential Sensor Integration | Telematics-enabled condition-based replacement opens predictive maintenance contracts for industrial fleets. |
| Regional Distribution Network Density Expansion | Core return logistics concentration in urban clusters accelerates cartridge aftermarket penetration. |
| CARB Compliance Test Lab Investment | California-registered heavy-duty engine certification requires documented 95% particulate capture validation. |
Research Approach
Document review covered SEC filings, EPA regulatory dockets, EU Stage V implementation guidance, and vehicle production databases, complemented by interviews with OEM procurement teams, aftermarket distributor operations heads, fleet maintenance directors, and filter media R&D specialists. Primary fieldwork engaged Tier 1 supplier procurement officers, quick-lube chain category managers, and industrial equipment uptime contract administrators. Secondary validation drew from customs trade data, IHS Markit registration statistics, and automotive component manufacturing disclosures. Bottom-up unit shipment modeling and top-down value triangulation anchored market size estimation.
Historical volume trajectories were cross-referenced against expert panel input on synthetic lubricant adoption curves and regulatory compliance timelines across the analysis window. Segmentation modeling incorporated product format, filtration technology tier, vehicle duty cycle, and end-user procurement channel. CAGRs were derived from elasticity-adjusted replacement cycle compression and geographic production scaling assumptions. Industry-specific forecast inputs included CARB crankcase protocol phase-in schedules and China Stage VI fleet turnover rates.
Caveats apply where electrification transition timelines or battery-sector materials science talent competition could materially shift the outlook for aftermarket demand trajectories and filter technology investment priorities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Nigeria Automotive Lubricants Market
Automotive Parts
Road Marking Machine Market
Automotive Parts
Automotive Step Plate Market
Automotive Parts
Italy Automotive Airfilters Market
Automotive Parts
Automotive Oil Pressure Switch Market
Automotive Parts
Automotive Hinges Market
Automotive Parts
Automotive Electric Water Pump Market
Automotive Parts
Bearing Steel Balls for New Energy Vehicles Market
Automotive Parts
South Africa Automotive Lubricants Market
Automotive Parts
Automotive Remanufactured Parts Market
Automotive Parts
External Combustion Engine Market
Automotive Parts
Global Intelligent Steering System Market
Automotive Parts
Large Volume Injector Market
Automotive Parts
Germany Automotive Parts Aluminium Die Casting Market
Automotive Parts
Asia-Pacific Passenger Vehicles Lubricants Market
Automotive Parts
Brazil Automotive Hydraulic Actuators Market