
 Automotive Power Steering Cooler Market | 2026-2036
Automotive Power Steering Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Power Steering Cooler Market Outlook
ISO/TS 16949 qualification is redrawing supplier eligibility across the Automotive Power Steering Cooler landscape, forcing tier-two thermal component makers into costly quality system overhauls. Mahle GmbH leverages its captive aluminum foundry network to control billet-to-fin cost curves across European and North American plants. Dana Incorporated anchors its position through backward integration into brazing sheet production for plate-bar architectures. Bosch Mobility Solutions competes on mechatronic integration, bundling cooler modules with its electric power steering rack programs for premium OEM platforms.
An automotive power steering cooler is a heat exchanger that maintains hydraulic fluid or electric motor thermal equilibrium within prescribed viscosity bands, typically constructed from aluminum multi-port tubes with louvered fins brazed in controlled-atmosphere furnaces. Its primary purpose is to prevent steering system fade under sustained high-load maneuvering while extending seal and pump service life. Plate-bar configurations dominate OEM volume for their packaging efficiency in cramped engine bays, while tube-and-fin designs sustain aftermarket demand through lower unit cost and universal fitment flexibility. Aluminum alloys capture the majority material share, though copper-nickel tubing persists in heavy-duty truck applications where galvanic compatibility with brass fittings matters more than mass reduction.
NHTSA FMVSS 135 braking and steering integrity standards, EPA Phase 3 GHG regulations, and California Air Resources Board fleet thermal efficiency mandates collectively tighten cooler performance verification requirements in the United States. ECE R79 steering equipment type approval in Europe adds electromagnetic compatibility and failure-mode testing burdens for suppliers serving EU-based assemblers. Stakeholders must monitor how EPA enforcement discretion on thermal management credits interacts with state-level zero-emission vehicle rules that eliminate hydraulic steering entirely from certain platforms.
Market Dynamics
EPA Phase 3 greenhouse gas standards are compressing thermal management tolerances for hydraulic steering systems while electric power steering architectures eliminate coolers entirely from battery-electric platforms, creating a bifurcated demand structure across OEM portfolios.
Growth Catalysts
- Commercial fleet expansion:North American logistics operators are extending cooler replacement intervals for heavy-duty trucks under stricter thermal monitoring protocols.
- EPA Phase 3 compliance:Light truck and SUV manufacturers in Mexico's manufacturing corridor require integrated cooling modules to meet export-bound efficiency thresholds.
- Aluminum brazing advances:Controlled-atmosphere furnace improvements enable thinner-walled multi-port tubes without sacrificing burst pressure ratings.
Market Restraints
- Copper-nickel input volatility:Heavy-duty truck applications still dependent on copper-nickel tubing face raw material cost swings from mining supply disruptions.
- Supplier concentration in European foundries:Captive aluminum billet production concentrates among three integrated groups, limiting second-tier pricing leverage.
- Hydraulic elimination mandate:California Air Resources Board zero-emission vehicle rules remove hydraulic steering from certain platforms entirely.
Strategic Opportunities
- Aftermarket tube-and-fin retrofit kits:Universal fitment designs address aging vehicle parc in price-sensitive service channels.
- Mechatronic bundling:Electric power steering rack programs create attach opportunities for thermal modules in hybrid architectures.
- ISO/TS 16949 qualification services:Tier-two thermal component makers require third-party quality system overhaul support to maintain OEM eligibility.
Industry Challenges
- Brazing sheet certification timelines:Backward integration into plate-bar architectures demands 18-24 month qualification cycles with major assemblers.
- Electromagnetic compatibility testing:ECE R79 steering equipment type approval adds failure-mode validation burdens for EU-bound suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Power Steering Cooler Market |
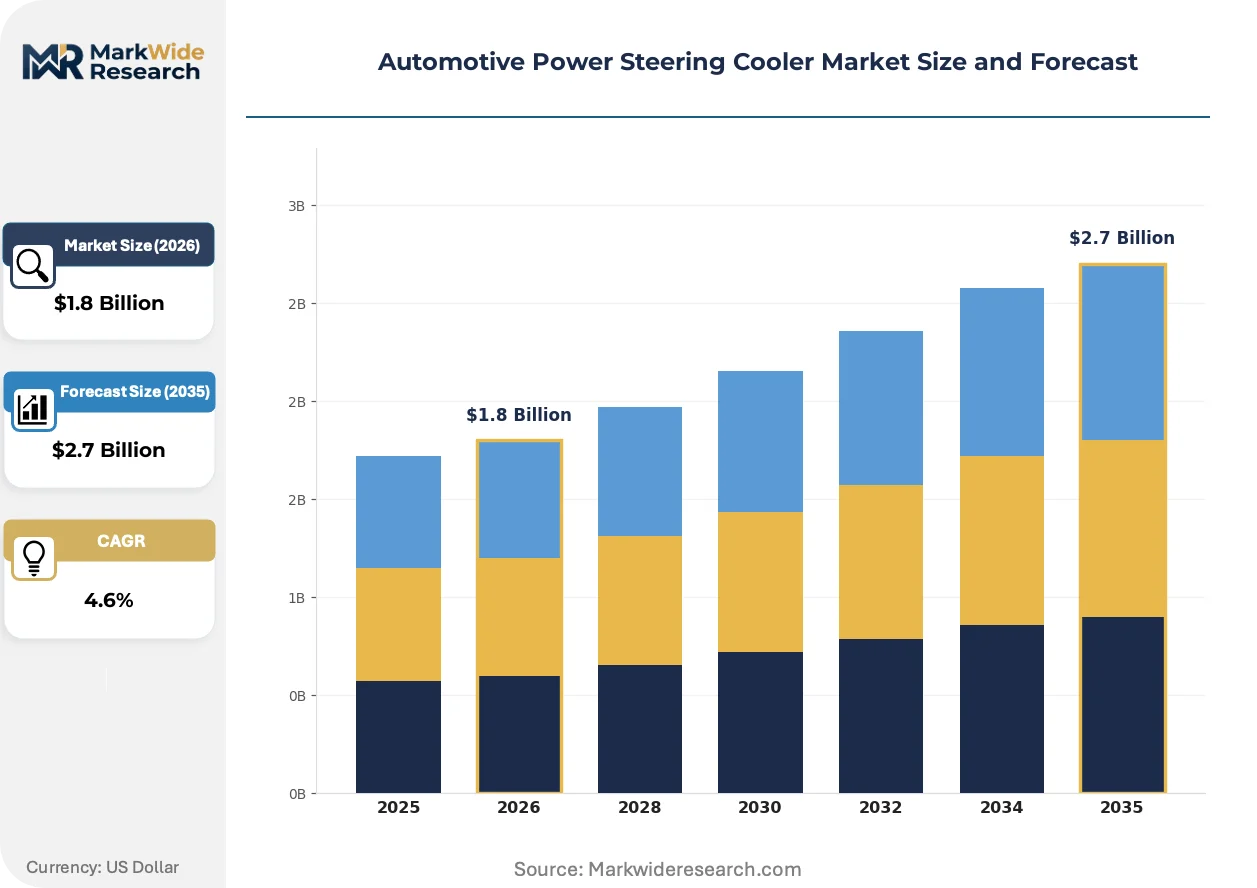
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tube and Fin, Plate Bar, Shell and Tube, Modular Material: Aluminum, Steel, Copper, Composite Application: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, SUVs End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Distributors |
| Companies Covered | Mahle GmbH, Dana Incorporated, Bosch Mobility Solutions, Valeo SA, Denso Corporation, Modine Manufacturing, Hayden Automotive, Gallay Ltd, AKG Thermotechnik International GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Power Steering Cooler Market Strategic Shifts
Material substitution and regulatory compression are actively reshaping cooler architectures, with aluminum alloys displacing legacy metals and integrated module designs consolidating discrete thermal components into single procurement units.
Multi-port extruded aluminum tubes with louvered fin arrays are displacing copper-brass constructions in medium-duty applications. OEM procurement teams specify these configurations for packaging density in cramped engine bays. The shift is compressing unit economics for traditional tube-and-fin suppliers serving the aftermarket.
EPA enforcement discretion on thermal management credits interacts unpredictably with state-level zero-emission mandates. Suppliers must maintain dual qualification tracks for hydraulic and electric steering thermal systems. European assemblers face parallel pressure from ECE R79 electromagnetic compatibility requirements.
Fleet operators now unbundle cooler replacement from full steering system overhauls, compressing service intervals and favoring universal-fit aftermarket designs. Independent service channels in the United States capture this demand rotation. OEM authorized dealers respond with certified remanufactured programs to retain attach rates.
Automotive Power Steering Cooler Market Segmentation
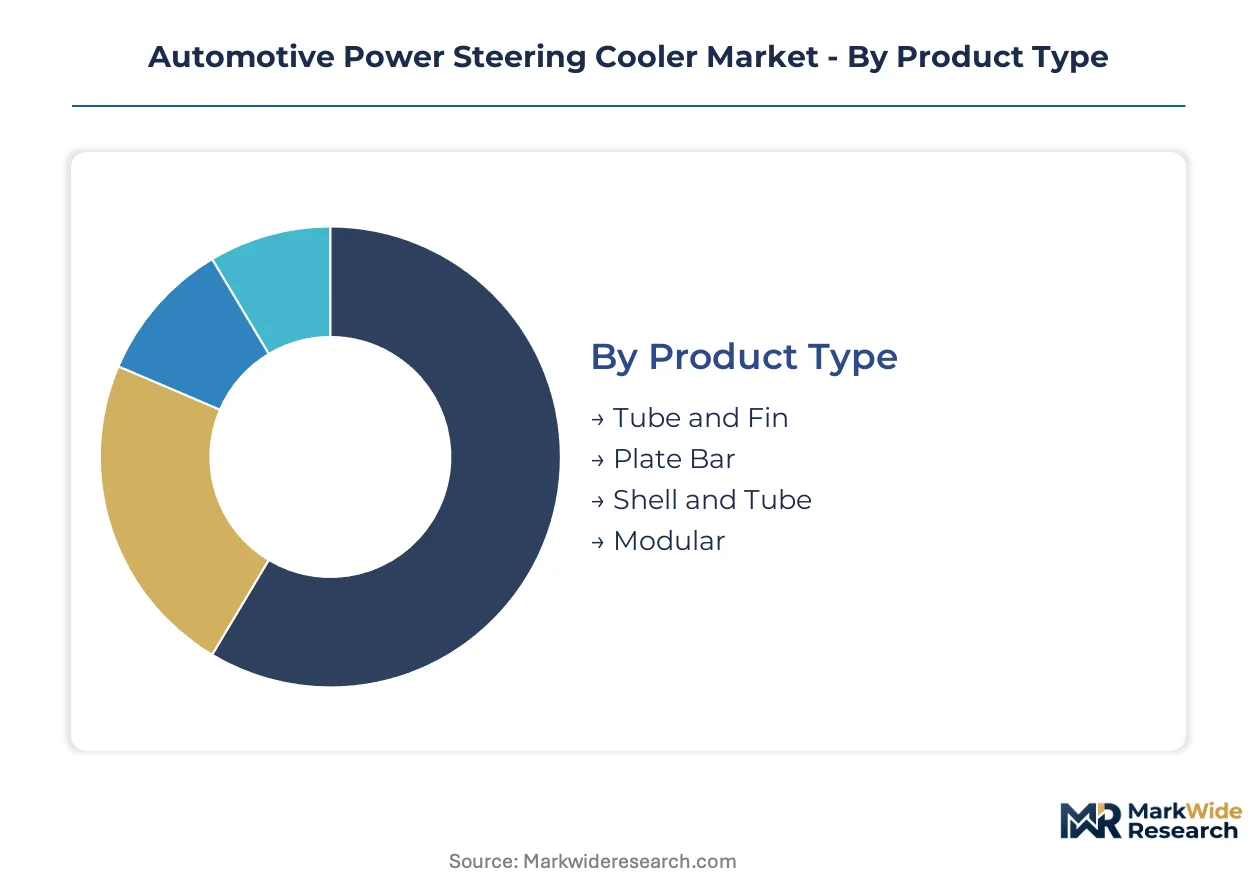
Power steering cooler procurement patterns diverge sharply across thermal architectures and supply channel structures. OEMs specify integrated modules by vehicle platform thermal load, while aftermarket demand fragments across universal-fit replacements for aging hydraulic systems.
Product Type:
Margin pools concentrate in brazed aluminum architectures where furnace qualification barriers protect incumbent suppliers from price erosion.
- Plate Bar:Multi-layer aluminum sheets with internal turbulators deliver maximum surface density per unit volume. OEM assembly plants in Mexico's manufacturing corridor specify these configurations for light truck and SUV export programs facing EPA Phase 3 thermal efficiency thresholds.
- Tube and Fin:Round or oval tubes mechanically expanded into louvered fin arrays offer lower tooling costs and universal fitment flexibility. Independent service channels in the United States favor this architecture for fleet replacement programs where procurement cost outweighs packaging constraints.
- Shell and Tube:Cylindrical pressure vessels with internal tube bundles persist in heavy-duty truck applications requiring burst pressure margins above 50 bar.
- Modular:Pre-assembled cooling units with integrated mounting brackets and connection manifolds reduce assembly line labor for vehicle assemblers.
The dominant share belongs to Plate Bar, while Modular is closing the gap fastest as OEMs consolidate thermal component procurement into single-source modules.
Material:
Raw material cost trajectories and brazing compatibility requirements divide supplier capabilities across metal systems.
- Aluminum:3003 and 6061 alloys with clad brazing layers enable controlled-atmosphere furnace joining without flux residues. Captive foundry networks at Mahle and Dana lock in billet-to-fin cost curves across European and North American plants.
- Copper:C11000 and C12200 tubing maintains galvanic compatibility with brass hydraulic fittings in legacy heavy-duty platforms where corrosion resistance trumps mass reduction targets.
- Steel:Coated mild steel constructions serve price-sensitive aftermarket channels where unit cost compression overrides service life extension.
- Composite:Polyamide-aluminum hybrid structures address electromagnetic shielding requirements in electric power steering architectures where ECE R79 compliance adds validation burdens.
Aluminum commands the volume base, though Composite is expanding most quickly as hybrid steering systems proliferate.
Application:
Thermal load profiles and regulatory exposure create distinct specification tiers across vehicle categories.
- Commercial Vehicles:Class 6-8 trucks with sustained high-load maneuvering demand oversized coolers with redundant flow paths. Fleet operators under EPA Phase 3 monitoring protocols are unbundling cooler replacement from full steering overhauls.
- SUVs:Body-on-frame architectures with high curb weights and trailer tow ratings require integrated cooling modules that package within cramped engine bays alongside intercoolers and transmission oil coolers.
- Passenger Vehicles:Unibody sedans and hatchbacks with lower steering duty cycles specify smaller-capacity coolers or eliminate hydraulic steering entirely in favor of electric racks.
- Heavy-Duty Trucks:Severe-service applications with continuous off-highway operation specify copper-nickel tubing for galvanic stability in abrasive environments.
Commercial Vehicles anchor procurement volume, while SUVs are gaining share fastest as light truck platforms dominate North American OEM portfolios.
End User:
Channel structure and qualification requirements fragment pricing power across the value chain.
- OEMs:Vehicle manufacturers specify cooler modules at platform development stage with 18-24 month brazing sheet certification timelines. ISO/TS 16949 qualification requirements force tier-two thermal component makers into costly quality system overhauls.
- Aftermarket Providers:Independent distributors and private-label suppliers source universal-fit tube-and-fin designs from second-tier manufacturers without captive foundry assets.
- Vehicle Assemblers:Contract manufacturers in Mexico's automotive corridor procure integrated cooling modules for export-bound production under maquiladora duty arrangements.
- Distributors:National parts chains and regional jobbers maintain inventory positions across multiple cooler architectures to service fragmented vehicle parc age distributions.
OEMs control specification authority, though Aftermarket Providers are capturing margin expansion as fleet replacement intervals compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Phase 3 greenhouse gas standards and NHTSA FMVSS 135 braking integrity rules are reshaping cooler specifications across major automotive manufacturing centers. Export-bound production corridors face divergent thermal management mandates as electric power steering architectures eliminate hydraulic cooling from battery-electric platforms.
United States
Commercial fleet operators under EPA Phase 3 monitoring protocols are unbundling cooler replacement from full steering overhauls. NHTSA enforcement of FMVSS 135 steering integrity standards tightens thermal performance verification for heavy-duty truck suppliers. Detroit's automotive corridor anchors Class 6-8 truck cooler procurement, with independent service channels capturing compressed replacement intervals.
Mexico
Maquiladora duty arrangements drive integrated cooling module procurement for export-bound light trucks and SUVs. Vehicle assemblers in the Bajío Region source brazed aluminum architectures to meet EPA thermal efficiency thresholds for US-bound production. Querétaro's manufacturing cluster concentrates plate-bar cooler fabrication for OEM platform integration.
Germany
ECE R79 steering equipment type approval adds electromagnetic compatibility testing burdens for EU-bound suppliers. KBA certification requirements compress qualification timelines for thermal module integration into electric power steering racks. Stuttgart's automotive engineering cluster drives mechatronic bundling strategies for premium OEM platforms.
China
MIIT fuel consumption standards and dual carbon goals accelerate aluminum substitution in hydraulic steering thermal systems. GB standards for automotive heat exchangers tighten burst pressure and corrosion resistance specifications. Yangtze River Delta manufacturing bases supply multi-port extruded tubes for domestic and export vehicle programs.
Japan
METI energy efficiency mandates favor compact cooler packaging in hybrid architectures where electric and hydraulic steering coexist. JIS standards govern brazing quality for aluminum multi-port tubes in severe-service applications. Nagoya's Chubu automotive corridor concentrates thermal module development for kei truck and compact commercial vehicle platforms.
Automotive Power Steering Cooler Market Competitive Environment
Listed leaders compete with private specialists across brazing furnace qualification and captive aluminum supply. The vendor base stratifies into three tiers: integrated thermal system houses with captive foundries, independent fabricators sourcing billet externally, and aftermarket-focused tube-and-fin suppliers. Structural concentration favors players controlling upstream aluminum production. Dominant competitive moves include backward integration into brazing sheet production and strategic bundling of cooler modules with electric steering rack programs.
Among German-based integrated thermal system houses, Mahle GmbH and AKG Thermotechnik International GmbH & Co. KG occupy positions defined by captive aluminum supply chains. Dana Incorporated represents North American backward integration into plate-bar architectures. Bosch Mobility Solutions exemplifies mechatronic bundling strategies for hybrid and electric steering platforms. These three anchors illustrate how geographic origin and corporate structure map to divergent competitive archetypes across the value chain.
| Leading Market Players |
|---|
| Mahle GmbH |
| Dana Incorporated |
| Bosch Mobility Solutions |
| Valeo SA |
| Denso Corporation |
| Modine Manufacturing |
| Hayden Automotive |
| Gallay Ltd |
| AKG Thermotechnik International GmbH & Co. KG |
| Others |
Value Chain & Pricing Dynamics
ISO/TS 16949 qualification gates both supplier eligibility and price differentiation across the Automotive Power Steering Cooler landscape, forcing tier-two thermal component makers into costly quality system overhauls while OEM procurement teams pay premiums for certified brazing sheet sources. This certification barrier simultaneously constrains supply-side participation and stratifies pricing tiers between qualified module suppliers and aftermarket tube-and-fin fabricators.
Pricing Analysis
Certification level creates the primary spread between premium plate-bar modules and economy tube-and-fin replacements. OEMs contract brazed aluminum architectures on long-term offtake agreements with price escalation clauses tied to London Metal Exchange aluminum billet indices. Cost compression in the aftermarket tier intensifies as independent distributors source universal-fit designs from second-tier manufacturers without captive foundry assets. Fleet operators show highest price sensitivity through unbundled cooler replacement programs, while premium OEM platforms tolerate elevated module pricing for integrated thermal management bundled with electric power steering racks.
Supply Chain Analysis
Just-in-time inventory strategies dominate OEM assembly plants in Mexico's manufacturing corridor, where maquiladora duty arrangements demand synchronized delivery of integrated cooling modules to export-bound light truck and SUV production lines. Supply concentrates in Germany, China, and Mexico for brazed aluminum multi-port tubes and louvered fin arrays. Raw material dependencies rest on primary aluminum billet, brazing sheet with clad layers, and copper-nickel tubing for heavy-duty galvanic compatibility. Single-source vulnerability around captive foundry networks at integrated thermal system houses exposes second-tier fabricators to allocation risk during capacity constraints. Distribution runs through authorized dealer networks for OEM-certified remanufactured programs and independent parts chains for aftermarket retrofit kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as EPA Phase 3 greenhouse gas standards extend cooler replacement intervals across commercial fleets while hybrid architectures sustain thermal module demand alongside hydraulic elimination from battery-electric platforms.
For Market Incumbents: Secure backward integration into brazing sheet production to defend margin position against aluminum input volatility and captive foundry concentration among Mahle and Dana networks. Add furnace qualification capacity in Mexico's Bajío Region to capture maquiladora procurement growth for export-bound SUV and light truck platforms. ISO/TS 16949 certification investment represents the critical lever for maintaining OEM eligibility as procurement teams tighten supplier quality audits. For New Entrants and Emerging Players: Aftermarket service-layer gaps in fleet thermal monitoring protocols create white-space opportunity for universal-fit tube-and-fin retrofit kits with embedded temperature sensors. Target independent distributors in the United States where compressed replacement intervals and unbundled procurement favor lower unit cost over packaging density. Pursue private-label arrangements with national parts chains rather than direct OEM qualification given 18-24 month brazing sheet certification timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with non-core thermal component divisions lacking ISO/TS 16949 qualification or captive aluminum supply. Long-term viability hinges on dual-track capability across hydraulic cooler modules and electric power steering thermal management for hybrid architectures. Watch EPA enforcement discretion on thermal management credits as the inflection signal—material relaxation would accelerate hydraulic elimination and compress addressable market scope.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brazing Sheet Production | Mahle and Dana lock in billet-to-fin cost curves across European and North American captive foundry networks. |
| ISO/TS 16949 Quality System Overhaul | Tier-two thermal component makers require third-party certification support to maintain OEM assembly plant eligibility. |
| Mechatronic Bundling with Electric Steering Racks | Bosch Mobility Solutions attaches thermal modules to premium OEM hybrid platform programs. |
| Geographic Manufacturing Footprint Expansion | Querétaro's manufacturing cluster concentrates plate-bar fabrication for Mexico maquiladora export production. |
| Aftermarket Sensor-Enabled Retrofit Kits | Fleet operators unbundle cooler replacement from full steering overhauls under EPA Phase 3 thermal monitoring protocols. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, OEM procurement disclosures, and aluminum trade flow records. The research team conducted structured interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and thermal system R&D directors across North America, Europe, and Asia-Pacific. Bottom-up triangulation of cooler unit demand by vehicle platform was cross-validated against top-down thermal module procurement value estimates from SEC filings and industry association reports.
Segmentation dimensions modeled span product architecture, material system, vehicle application class, propulsion type, and end-user channel structure across the projection horizon. CAGRs were derived from regression analysis of historical cooler content per vehicle trajectories, fleet replacement interval compression rates, and regulatory thermal efficiency mandate schedules. Industry-specific forecast inputs incorporated EPA Phase 3 compliance timelines, ECE R79 electromagnetic compatibility testing burdens, and MIIT fuel consumption standard trajectories for China-bound production.
Forecasts assume regulatory continuity in EPA Phase 3 greenhouse gas standards, ECE R79 steering equipment type approval, and California Air Resources Board zero-emission vehicle rules; material policy shifts would require re-modeling of hydraulic steering elimination rates and thermal module attach rates. Revision becomes warranted when state-level zero-emission mandates accelerate beyond current adoption curves or when aluminum billet supply disruptions exceed historical volatility bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Reciprocating Engine Market
Powertrain
Transmission Sales Market
Powertrain
Automotive Dual Mass Flywheel Market
Powertrain
Automotive Clutch Actuator Market
Powertrain
Global Automotive GD Injector Market
Powertrain
Automotive Powertrain Components Market
Powertrain
Vehicle Power Tailgate System Market
Powertrain
Automotive Vacuum Brake Booster Market
Powertrain
Industrial Diesel Turbocharger Market
Powertrain
Gear Oil Market
Powertrain
Gasoline Turbochargers Market
Powertrain
Automotive Variable Oil Pump Market
Powertrain
Automotive Powertrain Market
Powertrain
Automotive Turbocharger Hose Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
Automotive Drivetrain Market