
 Automotive Balance Shaft Market | 2026-2036
Automotive Balance Shaft Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Balance Shaft Market Intelligence
Luxury and performance vehicle OEMs is redrawing procurement priorities across the automotive balance shaft landscape. Musashi Seimitsu Industry Co., Ltd. leverages its vertical integration from forging to finishing across Japanese and North American plants. Schaeffler AG anchors European supply through precision cold-forming expertise and captive heat-treatment capacity. Sansera Engineering Limited specializes in high-volume machined balance shaft assemblies for motorcycle and compact car platforms.
An automotive balance shaft is a rotating counterweighted component engineered to cancel second-order harmonic vibrations inherent in inline-four and larger displacement engines, typically manufactured from forged steel or ductile iron with journal surfaces ground to sub-10-micron tolerances. Its primary purpose is to extend engine component life and improve occupant comfort by reducing noise, vibration, and harshness transmission. Steel balance shafts dominate material selection for heavy-duty truck and SUV applications where torsional loads peak, while aluminum variants gain share in sedan platforms seeking mass reduction. Dynamic balance shafts represent the fastest-growing product category as direct-injection turbocharged architectures proliferate. Aftermarket Providers occupy a fragmented but margin-rich channel serving aging vehicle parc replacement demand.
EPA tailpipe standards, Euro 7 emission frameworks, and China's MIIT fuel consumption regulations collectively tighten engine refinement mandates that elevate balance shaft specification rates. NHTSA noise compliance testing in the United States and ECE R51 homologation in Europe further embed these components in powertrain design cycles. Stakeholders must monitor how electrification transition timelines reshape ICE investment horizons and balance shaft technology roadmaps.
Market Dynamics
The shift toward downsized turbocharged gasoline direct-injection engines is amplifying second-order vibration challenges, forcing OEMs to specify balance shafts across broader displacement ranges and vehicle classes than historical norms.
Growth Catalysts
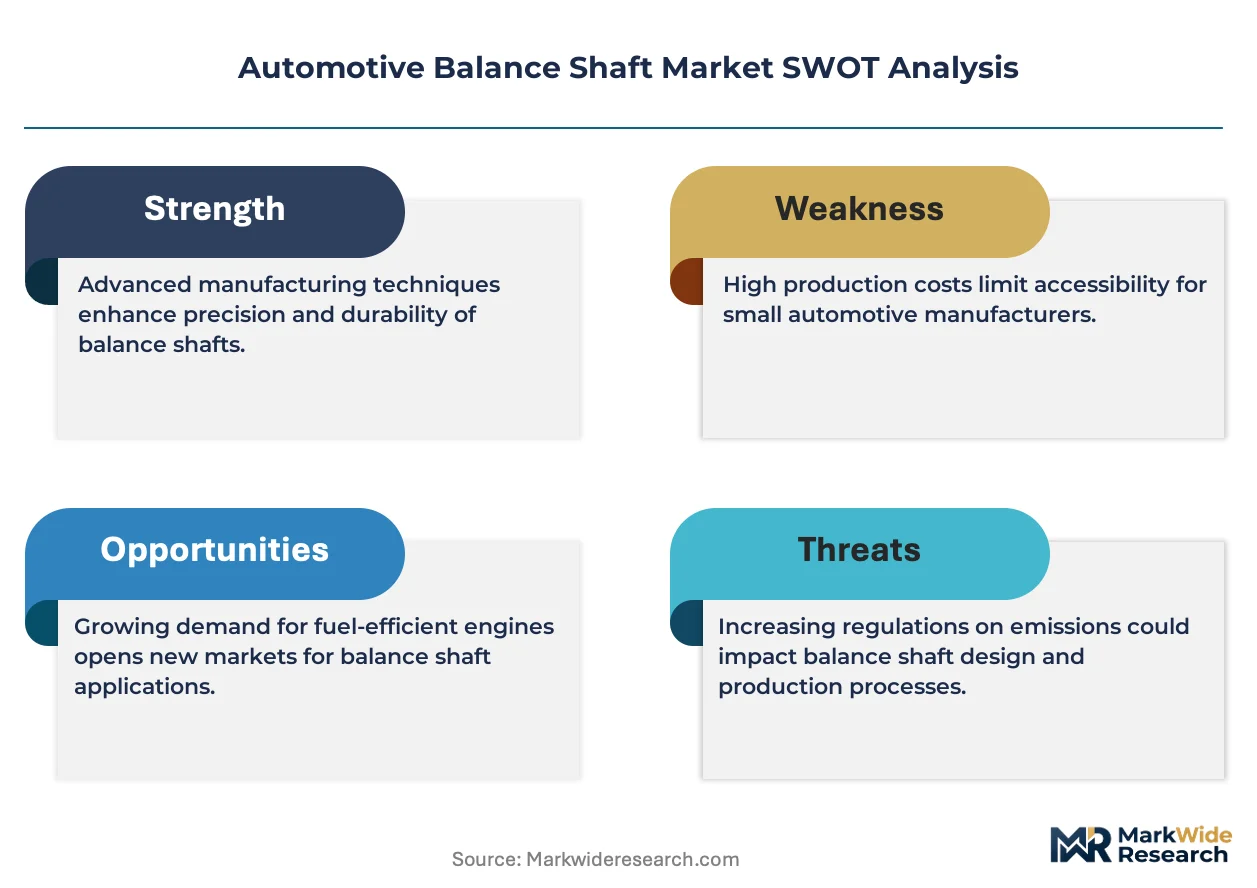
- EPA Tier 3 tailpipe standards:Tightened NOx and particulate limits compel engine refinement investments that embed balance shafts in four-cylinder architectures previously exempt from such components.
- Inline-three engine proliferation:Three-cylinder turbocharged powertrains for compact crossovers generate inherent primary imbalances that mandate dual balance shaft configurations.
- China MIIT fuel consumption regulations:Corporate average fuel economy targets accelerate small-displacement turbo adoption, expanding balance shaft specification rates in domestic-brand powertrains.
Market Restraints
- Alloy steel price volatility:Forged 4140 and 4340 steel bar stock fluctuates with scrap metal and energy input costs, compressing margin stability for forged component suppliers.
- Supplier concentration in East Asia:Precision forging and CNC grinding capacity clusters in Japan, South Korea, and eastern China, creating geographic risk exposure for European and North American OEMs.
- Electrification substitution threat:Battery-electric powertrains eliminate reciprocating mass imbalances entirely, eroding long-term addressable market for mechanical vibration cancellation systems.
Strategic Opportunities
- India compact SUV segment:Underpenetrated balance shaft adoption in sub-1.2L turbocharged three-cylinder engines presents white-space expansion for tier-one suppliers.
- EU Green Deal industrial incentives:Manufacturing investment credits for low-carbon forging processes enable European capacity expansion with embedded sustainability credentials.
- Aftermarket channel digitization:Direct-to-workshop e-commerce platforms bypass traditional distributor layers, capturing margin-rich replacement demand from aging European and Japanese vehicle parc.
Industry Challenges
- Precision grinding talent scarcity:Sub-10-micron journal tolerance requirements demand specialized machinist expertise that vocational pipelines struggle to replenish.
- Heat-treatment certification timelines:NADCAP and IATF 16949 audit cycles extend 12-18 months, delaying new supplier qualification for urgent OEM capacity needs.
- Legacy ERP integration friction:Real-time production data exchange with OEM just-in-sequence systems requires expensive middleware upgrades at mid-tier forging operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Balance Shaft Market |
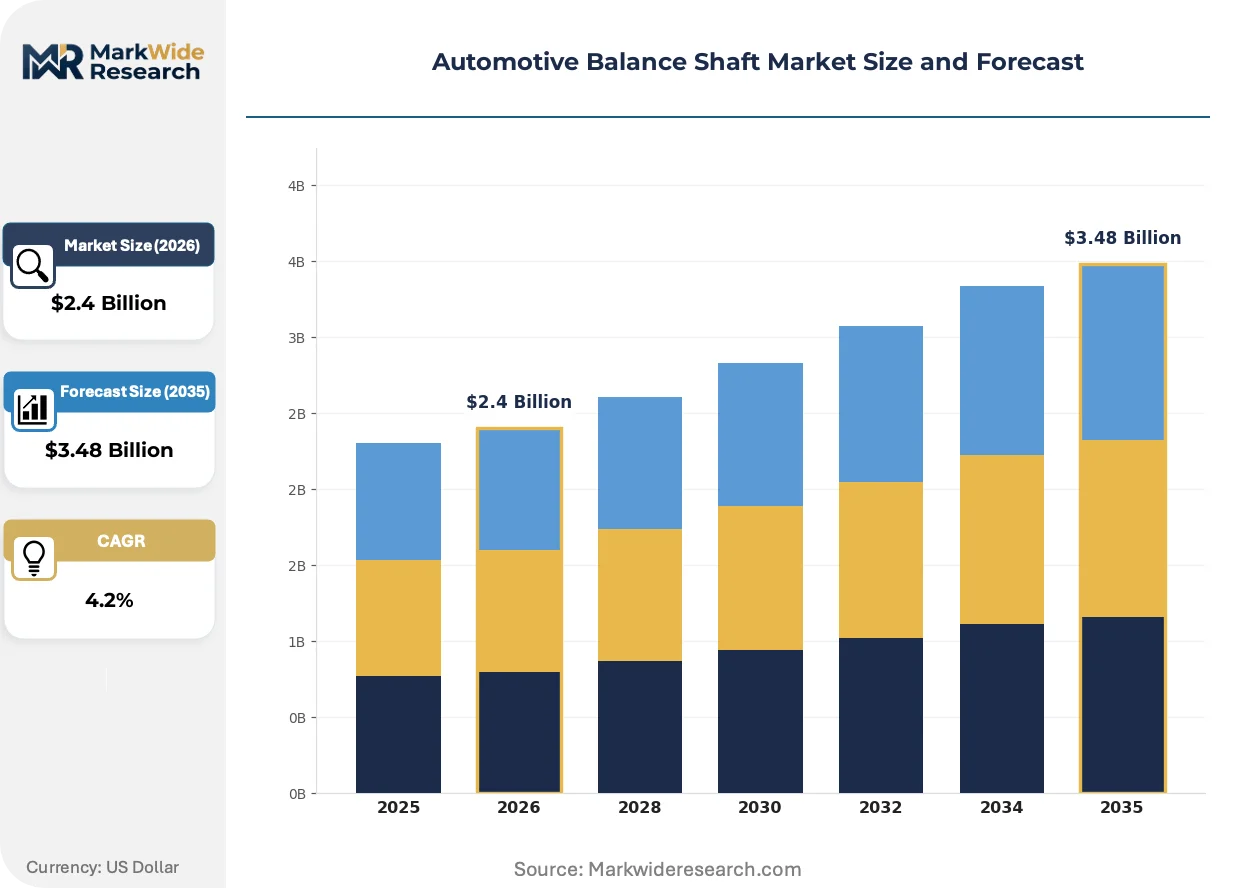
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Balance Shafts, Torsional Balance Shafts, Static Balance Shafts, Dynamic Balance Shafts Material: Aluminum, Steel, Carbon Fiber, Composite Materials Vehicle Type: Sedans, SUVs, Trucks, Motorcycles End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Musashi Seimitsu Industry Co., Ltd., SHW AG, Schaeffler AG, Sansera Engineering Limited, OTICS Corp., American Axle & Manufacturing, MAT Foundry Group Ltd., TFO Corporation, Hirschvogel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Balance Shaft Market Strategic Shifts & Innovations
Material science advances and regulatory stringency are fragmenting historical design consensus, creating parallel development tracks for mass-optimized and durability-optimized balance shaft architectures.
Hollow-bore steel balance shafts are bifurcating the product landscape between heavy-duty and light-duty applications. The design removes 15-20% of rotating mass while maintaining torsional rigidity. German luxury OEMs specify hollow-bore variants for inline-six engines above 3.0L displacement. Japanese suppliers now offer both solid and hollow configurations from shared forging dies, compressing development lead times for platform-flexible sourcing.
Euro 7 emission frameworks mandate real-world driving emissions compliance that exposes powertrain NVH deficiencies previously masked by laboratory test cycles. The regulation forces recalibration of engine mounting systems and harmonic dampers alongside balance shaft specification. Powertrain engineers in Stuttgart and Turin are expanding balance shaft integration into 1.5L mild-hybrid architectures previously deemed insufficiently refined for premium segment placement.
Direct sourcing from forging houses is displacing tiered supplier hierarchies in North American procurement. Ford and General Motors now issue technical specifications directly to Japanese and Korean forging specialists, bypassing traditional module integrators. The pattern concentrates in V6 and V8 truck engine programs where balance shafts integrate with camshaft carrier modules. Michigan and Ohio engineering centers staff dedicated supplier quality engineers to manage these direct relationships.
Automotive Balance Shaft Market Segmentation
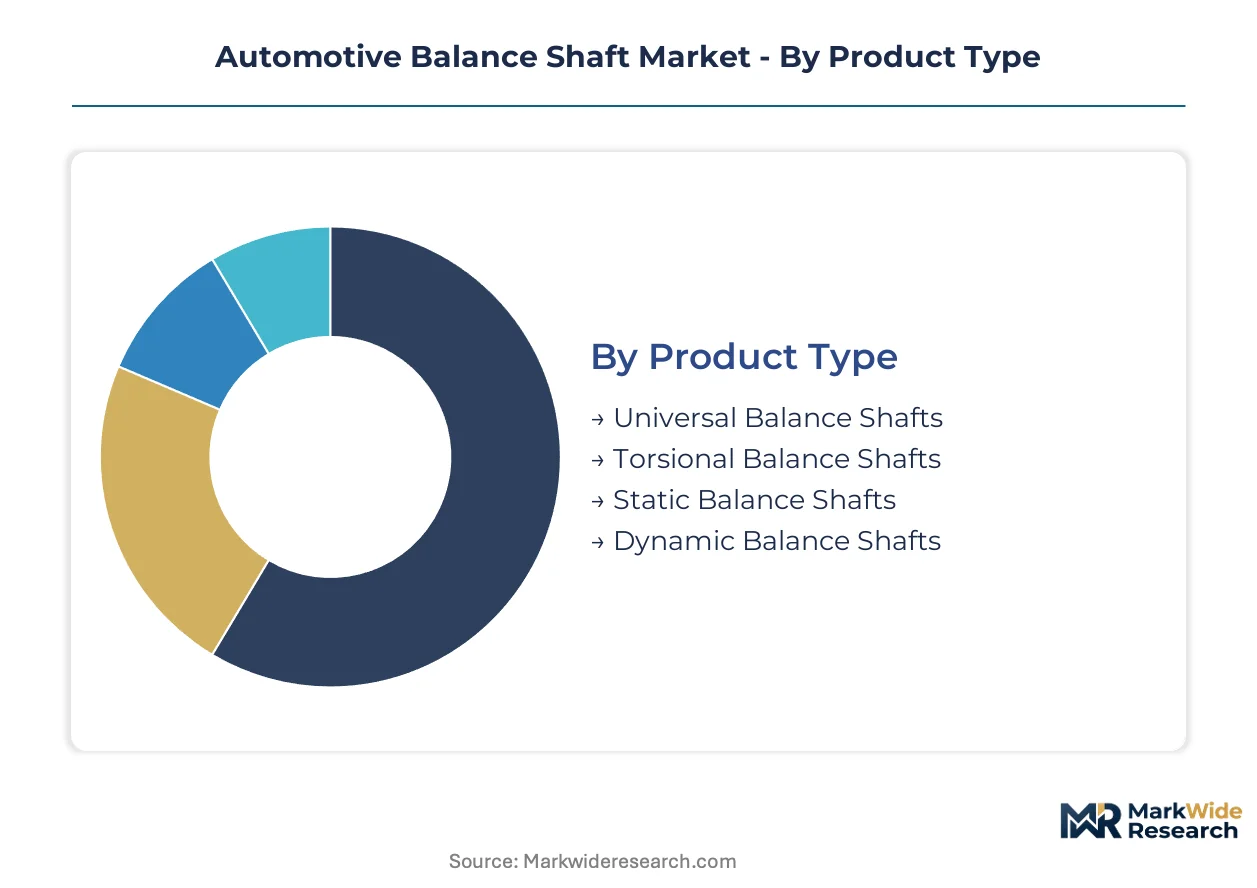
Balance shaft procurement patterns diverge sharply across product architectures, material grades, and vehicle platforms. OEMs configure sourcing strategies around engine displacement, NVH targets, and regional regulatory stringency rather than applying uniform specifications.
Product Type:
Domestic production concentrates on static and universal variants for high-volume compact car programs, while dynamic and torsional configurations flow through specialized export channels serving premium European and North American OEMs.
- Dynamic Balance Shafts:These assemblies incorporate variable-speed counterweight mechanisms calibrated to engine RPM ranges. German luxury OEMs in Stuttgart and Munich specify dynamic variants for inline-four turbocharged hybrids. EPA Tier 3 real-driving emissions testing exposes NVH deficiencies that dynamic shafts address.
- Universal Balance Shafts:Standardized counterweight geometries suit multiple engine architectures without platform-specific redesign. Japanese suppliers ship universal configurations to Thailand and Mexico assembly plants serving North American compact SUV demand. MIIT fuel consumption regulations in China accelerate small-displacement turbo adoption requiring these cost-optimized solutions.
- Torsional Balance Shafts:Engineered to address twisting vibrations in long-stroke diesel architectures.
- Static Balance Shafts:Fixed counterweight designs for legacy powertrain programs with stable operating ranges.
Universal balance shafts hold the largest share; momentum sits with dynamic variants.
Material:
Cost tier stratification separates forged steel for heavy-duty applications from aluminum and emerging composites where mass reduction commands premium pricing.
- Steel:Forged 4140 and 4340 alloys dominate truck and SUV segments where torsional loads peak. North American heavy-duty pickup programs source steel shafts from captive forging operations in Ohio and Indiana. Alloy price volatility tied to scrap metal and energy inputs compresses margin stability.
- Aluminum:Gravity-cast and forged aluminum variants reduce rotating mass for sedan platforms pursuing fuel economy targets. Japanese OEMs specify aluminum shafts for hybrid powertrains where electric motor torque masks lower torsional rigidity. China's domestic-brand sedans increasingly adopt aluminum as MIIT corporate average fuel consumption tighten.
- Carbon Fiber:Emerging in motorsport and ultra-premium limited-production vehicles.
- Composite Materials:Glass-reinforced polymer shafts under evaluation for range-extender applications.
Steel commands volume leadership; aluminum climbs fastest on mass-reduction mandates.
Vehicle Type:
Application intensity varies—SUVs and trucks mandate balance shafts across nearly all engine displacements, while motorcycle and sedan adoption remains conditional on cylinder count and NVH positioning.
- SUVs:Compact and midsize crossover platforms generate the densest balance shaft specification rates. Three-cylinder turbocharged architectures for sub-1.5L engines in European and Chinese markets require dual-shaft configurations. Ford's EcoBoost and Volkswagen's TSI families embed balance shafts across 80% of SUV powertrain variants.
- Trucks:Heavy-duty diesel and gasoline V6/V8 programs integrate balance shafts with camshaft carrier modules. Direct sourcing from Japanese and Korean forging houses bypasses traditional tiered supplier hierarchies in Michigan and Ohio procurement.
- Sedans:Balance shaft penetration correlates with premium segment positioning and hybrid electrification.
- Motorcycles:High-displacement touring bikes and parallel-twin platforms represent the primary addressable segment.
SUVs absorb the greatest volume; trucks offer the steepest expansion trajectory on direct-forging procurement trends.
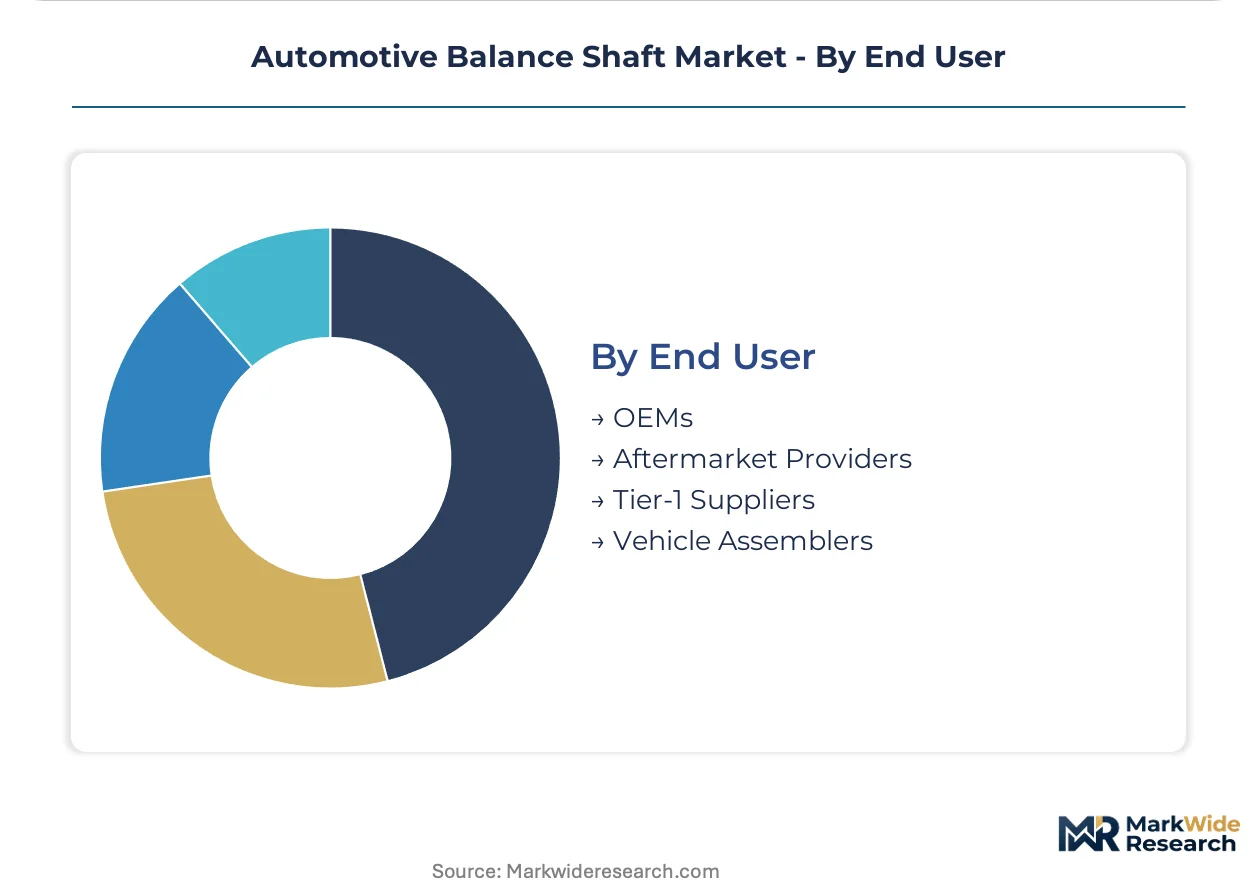
End User:
Customer type determines margin structure—OEMs and tier-1 suppliers negotiate long-term capacity contracts, while aftermarket providers capture replacement demand from aging vehicle parc at premium pricing.
- OEMs:Vehicle manufacturers issue technical specifications directly to forging specialists for powertrain programs above 2.0L displacement. NHTSA noise compliance testing and ECE R51 homologation embed balance shafts in design cycles. OEM procurement teams in Germany, Japan, and the United States concentrate the bulk of annual procurement volume.
- Aftermarket Providers:Fragmented distributor and workshop networks serve replacement demand from European and Japanese vehicle parc. Direct-to-workshop e-commerce platforms bypass traditional layers, capturing margin-rich demand as 10-15 year vehicle fleets age.
- Tier-1 Suppliers:Module integrators face displacement by direct-forging relationships in North American truck programs.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations source through tier-1 channels.
OEMs dominate volume; aftermarket channels expand most quickly on digitization and parc aging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese OEM procurement teams command the densest concentration of balance shaft specification activity, while Chinese domestic-brand powertrains and North American truck programs drive volume expansion across divergent regulatory frameworks.
China
MIIT corporate average fuel consumption regulations accelerate small-displacement turbo adoption across domestic-brand sedans and compact crossovers. Balance shaft specification rates climb in three-cylinder architectures from Geely, Great Wall, and BYD powertrain divisions. Yangtze River Delta forging clusters in Jiangsu and Zhejiang provinces scale precision CNC grinding capacity to serve both local OEMs and export programs.
Germany
Luxury OEMs in Stuttgart and Munich specify dynamic balance shaft variants for inline-four turbocharged hybrids and mild-hybrid architectures. Euro 7 emission frameworks mandate real-world driving emissions compliance that exposes NVH deficiencies previously masked by laboratory cycles. Bavarian and Baden-Württemberg engineering centers expand balance shaft integration into 1.5L powertrains previously deemed insufficiently refined for premium placement.
United States
EPA Tier 3 tailpipe standards compel engine refinement investments that embed balance shafts in four-cylinder architectures previously exempt from such components. Ford and General Motors issue technical specifications directly to Japanese and Korean forging specialists for V6 and V8 truck engine programs. Michigan and Ohio engineering centers staff dedicated supplier quality engineers to manage these direct-forging relationships.
Japan
METI fuel efficiency targets and domestic OEM hybrid strategies sustain demand for aluminum balance shafts in mass-reduction-focused powertrains. Japanese suppliers offer both solid and hollow-bore steel configurations from shared forging dies, compressing development lead times. Kanto and Chubu industrial corridors concentrate precision forging and heat-treatment capacity serving global OEM export programs.
South Korea
Hyundai and Kia powertrain divisions specify balance shafts across expanding SUV and compact crossover lineups for North American and European export markets. Domestic forging houses capture direct-sourcing relationships from Michigan-based OEM procurement teams. Gyeonggi-do and Busan-Ulsan manufacturing belts scale hollow-bore steel production for hybrid and turbocharged gasoline direct-injection architectures.
Automotive Balance Shaft Market Key Industry Players
Player mix skews toward vertically integrated forging specialists and precision machining houses with captive heat-treatment capacity. The vendor base separates into three strategic archetypes: Japanese multi-plant forging conglomerates with backward integration into steel bar stock, German precision cold-forming specialists serving luxury OEM programs, and Indian high-volume machined assembly producers for motorcycle and compact car platforms. Dominant competitive moves include direct technical specification relationships with OEM engineering centers and geographic capacity expansion to mirror customer assembly plant footprints.
Among Japanese forging conglomerates, Musashi Seimitsu Industry Co., Ltd. and OTICS Corp. occupy positions defined by multi-continental plant networks and upstream control over raw material conversion. German fabricators Schaeffler AG and SHW AG exemplify the precision-tier archetype through European-centric engineering relationships and captive metallurgical processing. Sansera Engineering Limited represents the high-volume machined assembly specialist archetype, with positioning shaped by motorcycle and compact car platform concentration. MAT Foundry Group Ltd. and Hirschvogel Group sit within the European forging house tier serving direct OEM procurement channels.
| Leading Market Players |
|---|
| Musashi Seimitsu Industry Co., Ltd. |
| SHW AG |
| Schaeffler AG |
| Sansera Engineering Limited |
| OTICS Corp. |
| American Axle & Manufacturing |
| MAT Foundry Group Ltd. |
| TFO Corporation |
| Hirschvogel Group |
| Others |
Cost & Logistics Intelligence
Ninety-day forging lead times for precision-ground balance shaft blanks concentrate pricing power among Japanese and Korean suppliers with captive heat-treatment capacity, while European and North American OEMs absorb freight premiums and tariff exposure to secure NADCAP-certified output. This inventory compression cascades through tiered supplier hierarchies, forcing module integrators to accept margin erosion or risk qualification delays.
Pricing Analysis
Prior-generation solid steel balance shafts trade at commodity-forging rates, current-generation hollow-bore variants command mass-reduction premiums, and next-generation composite-reinforced architectures sit at pre-commercial valuation. Three-tier pricing structure across premium dynamic configurations, standard universal shafts, and economy static designs stratifies around certification grade and volume scale. Cost compression in economy-tier static shafts is intensifying because Chinese domestic-brand OEMs negotiate consolidated annual contracts. Tier-1 module integrators exhibit highest price sensitivity; German luxury OEMs demonstrate lowest sensitivity due to NVH-driven specification rigidity.
Supply Chain Analysis
Forty-five days of finished-goods inventory at Kanto and Chubu forging clusters buffers against alloy steel price volatility, yet exposes downstream buyers to geographic concentration risk. Supply concentrates in Japan, South Korea, and eastern China, with precision CNC grinding capacity clustering in Jiangsu and Gyeonggi-do. Raw material dependencies rest on forged 4140 and 4340 steel bar stock, nodular iron feedstock, and specialized grinding wheel abrasives. Single-source vulnerability around NADCAP-certified heat-treatment ovens creates qualification bottlenecks. Distribution runs through tier-1 powertrain module integrators for OEM assembly plants, with direct-forging relationships displacing traditional channels in North American truck programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive balance shaft market tracks cyclical recovery patterns tied to light-vehicle production schedules, with ICE powertrain investment cycles now extending through hybrid transition phases.
For Market Incumbents: Fortify backward integration into alloy steel bar stock conversion to buffer margin compression from scrap metal volatility. Expand captive heat-treatment capacity in Ohio and Indiana to serve direct-forging relationships with Detroit-based OEM procurement teams. Electrification substitution threatens long-term addressable demand; prioritize dynamic balance shaft R&D for mild-hybrid architectures to extend relevance through the transition window. For New Entrants and Emerging Players: Anchor in India's compact SUV segment where three-cylinder turbo penetration remains underdeveloped and domestic forging capacity is scarce. Target aftermarket digitization through direct-to-workshop e-commerce platforms serving aging European and Japanese vehicle parc replacement demand. Pursue qualification partnerships with tier-1 module integrators facing displacement pressure rather than competing head-to-head for OEM direct specifications. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified forging conglomerates seeking to divest non-core automotive precision components. Mid-term viability extends through the hybrid transition phase; battery-electric substitution caps terminal value. Monitor EPA Tier 3 and Euro 7 enforcement timelines as inflection indicators for specification rate acceleration or deceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct OEM Forging Relationships | Bypasses tier-1 integrators to capture V6 and V8 truck program margins in Michigan and Ohio. |
| Hollow-Bore Steel Capacity Expansion | Addresses German luxury OEM demand for mass-reduced inline-six engine configurations. |
| Aftermarket Channel Digitization | Captures margin-rich replacement demand from 10-15 year European and Japanese vehicle parc. |
| NADCAP Heat-Treatment Certification | Unlocks qualification for urgent OEM capacity needs facing 12-18 month audit timelines. |
| Aluminum Shaft Platform Development | Serves Japanese hybrid powertrains where electric motor torque enables lighter rotating mass. |
Research Approach
The analysis maps dynamic, universal, torsional, and static balance shaft configurations, each validated through OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and precision forging operations. Primary interviews with powertrain NVH specialists and heat-treatment certification auditors combined with secondary validation from vehicle production databases, EPA emission compliance filings, Euro 7 regulatory drafts, and IHS Markit registration data. Bottom-up volume triangulation against top-down OEM procurement spend estimates anchored segment-level outputs.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product architecture, material grade, vehicle platform class, and regional regulatory cluster. CAGRs derived from production-weighted specification rate trajectories, with inputs from ICE powertrain investment cycles and hybrid transition timelines. Alloy steel price indices and NADCAP certification queue lengths fed industry-specific forecast adjustments.
Material uncertainties — electrification substitution pace, alloy steel commodity volatility, and regulatory enforcement timing — sit outside the modeled envelope. Forecasts reflect documented assumptions about specification rate persistence and supplier qualification throughput. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Global Automotive Exhaust Gas Turbochargers Market
Powertrain
Clutch Hub Puller Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Automotive Slipper Clutch Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
Diesel Engine Management System Market
Powertrain
Continuous Variable Transmission Market
Powertrain
Drive Shaft Market
Powertrain
Automotive Engine Piston Rings Market
Powertrain
Automotive Tuner Market
Powertrain
Automotive Turbocharger Hose Market
Powertrain
Automotive Engine Air Filter Market
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Global Driveline Market
Powertrain
Test Automation Systems for Powertrain Dynamometer Market