
 Global Fuel and Oil Filters Market | 2026-2036
Global Fuel and Oil Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fuel and Oil Filters Market Analysis
Fleet operators is unwinding the historical dominance of individual vehicle owners in aftermarket filter procurement. Mann+Hummel leverages captive production of synthetic media to control cost curves across European truck fleets. Donaldson Company anchors its position in high-durability industrial applications where service intervals extend margin capture. MAHLE GmbH competes through modular filter architectures that reduce installation complexity for OEM assembly lines.
Fuel and oil filters are mechanical separation devices engineered from pleated cellulose, microglass, or synthetic polymer media bonded to metal or polymer housings, designed to remove particulate contaminants and water from hydrocarbon streams before combustion or lubrication contact. Oil filter demand concentrates in the automotive vertical where extended drain intervals and full-flow synthetic media configurations command premium positioning. Fuel filter growth tracks fastest in the marine and industrial verticals, where high-pressure common-rail injection systems impose sub-five-micron absolute filtration requirements that cellulose cannot satisfy.
EPA regulations in the United States, Euro VI standards enforced by ECHA and national type-approval bodies in Europe, and China's GB VI emissions framework administered by MEE collectively mandate tighter filtration efficiency, forcing material upgrades from cellulose to microglass and synthetic media. ISO 4548 and SAE test protocols define laboratory validation thresholds that determine OEM qualification and aftermarket interchangeability. Stakeholders must monitor regulatory divergence between particulate number limits and filter efficiency testing methods as the decisive variable for regional product line rationalization.
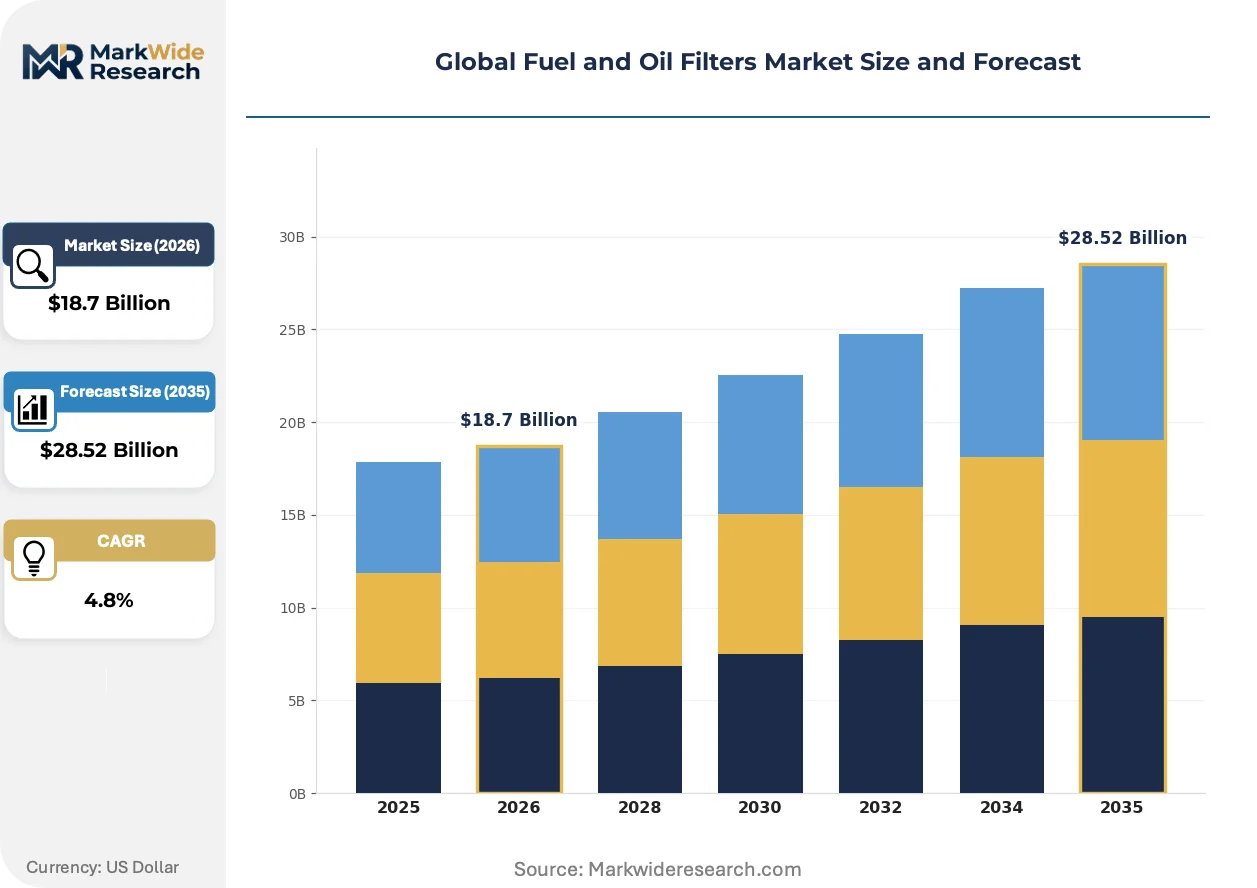
Market Dynamics
Fleet consolidation and tightening emissions mandates are compressing replacement cycles while forcing material upgrades from cellulose to synthetic media across automotive and industrial verticals.
Growth Catalysts
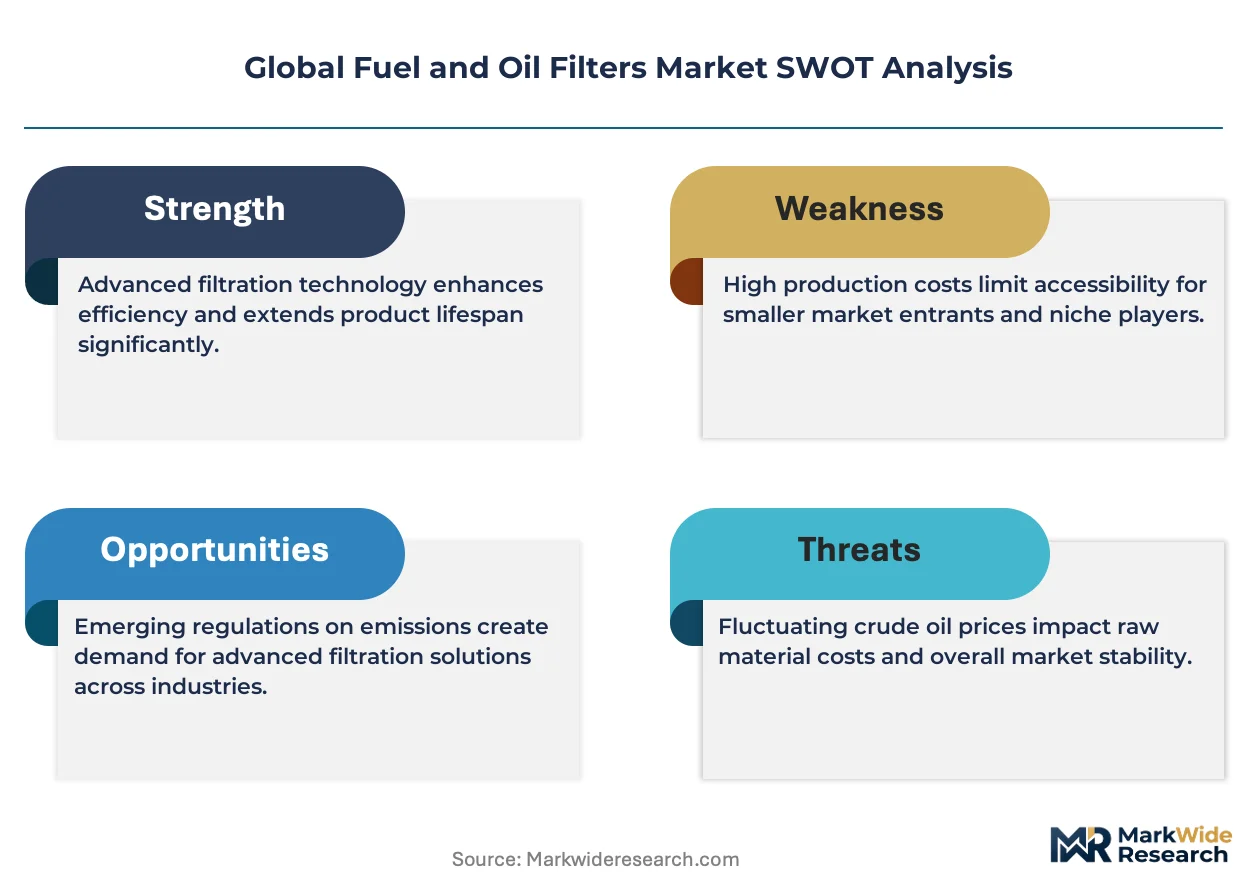
- EPA Tier 4 and Euro VI mandates:These frameworks tighten particulate and NOx thresholds, compelling filter replacements at shorter intervals across commercial vehicle fleets in the United States and European Union.
- High-pressure common-rail injection:Marine and industrial engines now require sub-five-micron absolute filtration that cellulose cannot deliver, accelerating synthetic media penetration in heavy-duty applications.
- Aftermarket infrastructure scaling:China, India, and Brazil are witnessing rapid expansion of service networks and parts distribution, concentrating incremental demand in these high-volume markets.
Market Restraints
- Raw material cost volatility:Synthetic polymer and microglass fiber prices fluctuate with petrochemical feedstock markets, squeezing margin stability for media producers.
- Supply concentration in specialty resin production:A limited number of chemical suppliers control high-performance polymer grades, creating bottleneck risk for filter manufacturers.
- Technical ceiling in cellulose filtration:Cellulose media cannot achieve the efficiency ratings demanded by modern common-rail systems, rendering legacy production lines obsolete.
Strategic Opportunities
- Underpenetrated Indian commercial vehicle aftermarket:Fleet standardization and emissions enforcement are creating first-mover advantage for synthetic media suppliers establishing local production.
- Remanufacturing and circular service models:Extended producer responsibility frameworks in the European Union incentivize filter core return and reconditioning programs.
- Electrification-adjacent thermal management:Hybrid powertrains retain internal combustion components requiring specialized filtration, opening a transitional product category.
Industry Challenges
- ISO 4548 and SAE validation timelines:Laboratory certification protocols for OEM qualification extend product development cycles and delay revenue recognition.
- Retrofit compatibility engineering:Aftermarket suppliers must design modular housings that interface with legacy vehicle architectures across multiple engine generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fuel and Oil Filters Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Filter, Oil Filter, Air Filter, Cabin Filter Industry Vertical: Automotive, Marine, Industrial, Powersport Filter Technology: Microglass, Cellulose, Synthetic Media, Carbon Connection Type: Threaded, Quick-Connect, Clamp-On, Bayonet |
| Companies Covered | Mann+Hummel, Donaldson Company, MAHLE GmbH, Robert Bosch GmbH, Denso Corporation, Sogefi SpA, Cummins Inc., UFI Filters, FRAM Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fuel and Oil Filters Market Emerging Trajectories
Synthetic media formulations and digital fleet management tools are converging to redefine filter performance metrics and procurement patterns across commercial vehicle operations.
Synthetic polymer nanofiber layers bonded to cellulose substrates are displacing pure cellulose constructions in heavy-duty diesel applications. Fleet operators in North American long-haul trucking are specifying these composites to extend drain intervals beyond fifteen thousand miles. This displacement is compressing demand for conventional pleated paper filters while elevating price realization for premium media grades.
China's GB VI emissions framework administered by MEE mandates particulate number limits that mirror Euro VI stringency. Domestic engine manufacturers are qualifying microglass and synthetic media to meet these thresholds ahead of enforcement deadlines. The commercial vehicle segment is absorbing the steepest compliance costs as retrofit certification requirements multiply.
Telematics-enabled condition monitoring is altering how fleet managers schedule filter replacements. Predictive algorithms tracking pressure differential and flow degradation are supplanting fixed-interval maintenance in large European trucking operations. Germany and the Netherlands display the deepest penetration of sensor-integrated filtration systems tied to centralized fleet management platforms.
Global Fuel and Oil Filters Market Segmentation
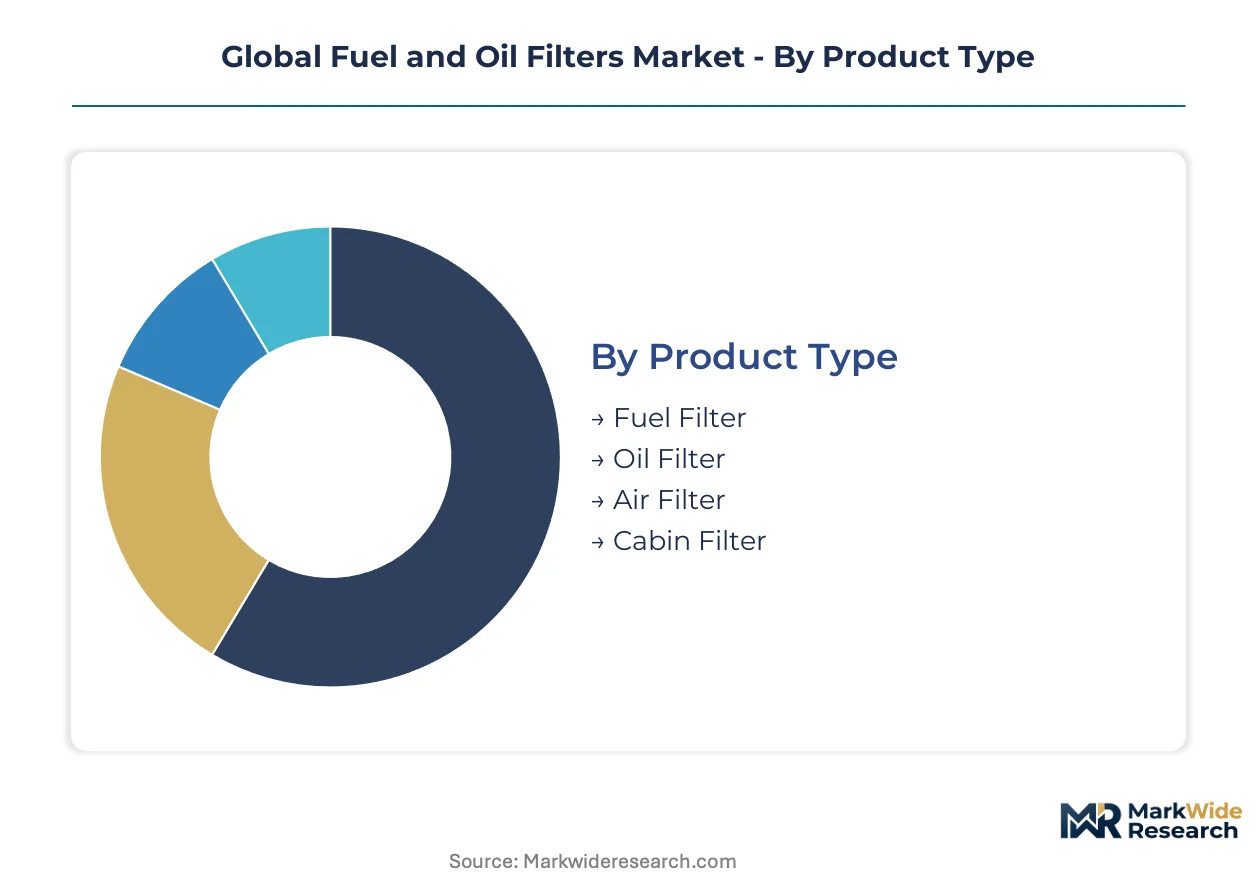
Filter procurement patterns diverge sharply across product categories and end-use specifications. Fleet managers and OEM buyers prioritize different performance thresholds, media compositions, and installation geometries depending on operating environment and regulatory exposure.
Product Type:
EPA Tier 4 and Euro VI emissions frameworks mandate distinct filtration efficiencies for fuel versus oil systems, creating divergent material specifications across each product category.
- Fuel Filter:Engineered to remove water and particulate contaminants from hydrocarbon streams before high-pressure common-rail injection. Marine and industrial engine builders in Germany and Japan specify sub-five-micron absolute ratings that synthetic media alone can deliver. Demand concentrates in commercial vehicle fleets facing China's GB VI particulate number limits.
- Oil Filter:Full-flow and bypass configurations built from pleated cellulose, microglass, or synthetic polymer media bonded to metal housings. Automotive OEMs in the United States specify extended drain intervals beyond fifteen thousand miles, elevating synthetic media penetration. This segment handles the majority of throughput; Fuel Filter is the fastest mover on share.
- Air Filter:Intake filtration systems protecting combustion chambers from abrasive dust and debris.
- Cabin Filter:HVAC-integrated media capturing particulates and activated carbon-impregnated variants addressing odor and VOC reduction.
Oil Filter commands the largest installed base across passenger and commercial vehicle populations; Fuel Filter is expanding most quickly as common-rail injection spreads through heavy-duty applications.
Industry Vertical:
Cost tier differentiation separates premium OEM qualification from aftermarket price competition across end-use segments.
- Automotive:Passenger cars, light trucks, and commercial vehicles requiring full-flow oil filtration and fuel water separation. Extended drain interval specifications from Detroit Three and German premium OEMs drive synthetic media adoption. Brazil and India concentrate aftermarket volume growth as fleet standardization accelerates.
- Marine:Diesel propulsion and auxiliary engines operating in high-humidity, salt-laden environments demanding corrosion-resistant housings and water-absorbing fuel media. IMO MARPOL Annex VI sulfur regulations and EPA marine Tier 3 standards impose filtration upgrades on vessel operators in the United States and European Union ports.
- Industrial:Stationary power generation, construction equipment, and agricultural machinery with extended service interval requirements. Donaldson Company and Mann+Hummel anchor positions here through high-durability synthetic media formulations.
- Powersport:Motorcycles, ATVs, and recreational vehicles with compact packaging constraints and seasonal usage patterns.
Automotive generates the largest absolute volume; Marine exhibits the steepest technology-driven margin expansion.
Filter Technology:
Volume concentration shifts from cellulose legacy capacity toward synthetic and microglass as emissions thresholds tighten.
- Microglass:Borosilicate fiber media achieving sub-ten-micron absolute filtration with minimal flow restriction. High-pressure common-rail systems in European commercial vehicles specify this technology to meet Euro VI particulate number mandates. Mann+Hummel and MAHLE GmbH control captive microglass production lines.
- Synthetic Media:Polymer nanofiber layers bonded to cellulose substrates or pure synthetic constructions. North American long-haul fleets specify these composites for drain intervals exceeding OEM recommendations. The technology is displacing pure cellulose in heavy-duty diesel applications fastest.
- Cellulose:Pleated paper media from wood pulp feedstocks, cost-competitive but efficiency-limited.
- Carbon:Activated carbon-impregnated media for cabin air and specialized fuel vapor recovery applications.
Cellulose retains the largest production footprint; Synthetic Media is gaining share fastest as fleet specifications harden.
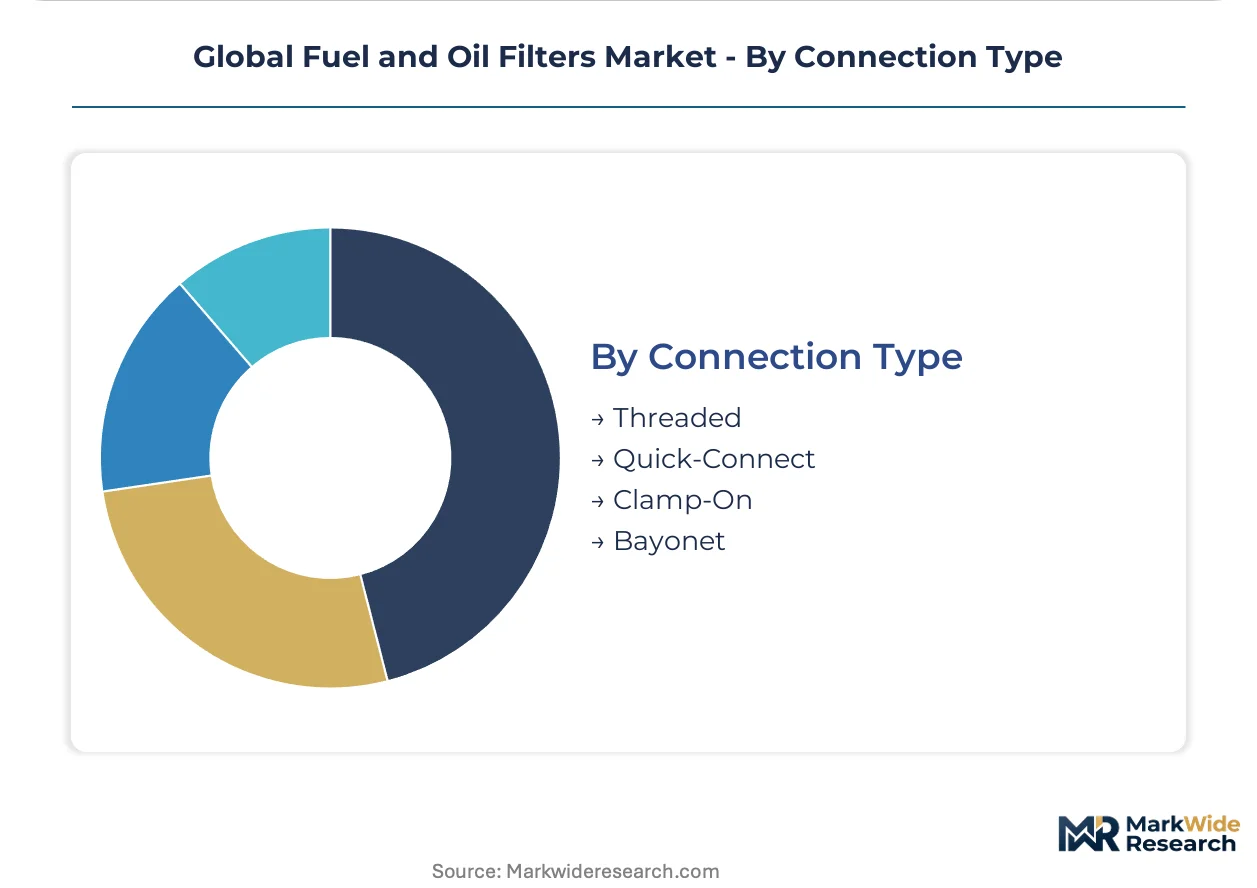
Connection Type:
Installation geometry and service accessibility dictate procurement patterns across OEM assembly lines versus aftermarket service bays.
- Threaded:Spin-on canister designs dominating automotive oil filter replacement. Standardized SAE thread specifications enable aftermarket interchangeability across vehicle populations in the United States and Japan.
- Quick-Connect:Tool-free installation systems specified by European OEMs for fuel filter modules. Volkswagen Group and BMW assembly lines favor these designs to reduce warranty labor exposure.
- Clamp-On:Band-clamp retention for large-diameter industrial and marine filter housings.
- Bayonet:Quarter-turn locking mechanisms in compact powersport and motorcycle applications.
Threaded connections handle the majority of replacement volume; Quick-Connect is climbing the fastest as European OEM assembly specifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk terminals anchor European fuel filter distribution, while China's Belt and Road rail corridors accelerate aftermarket parts movement across Central Asia. These infrastructure assets concentrate procurement flows and shape regional competitive positioning.
United States
Commercial vehicle fleets along the I-10 corridor drive synthetic media demand as EPA Tier 4 mandates compress replacement intervals. The Environmental Protection Agency enforces particulate number limits that disqualify cellulose filtration in heavy-duty applications. Detroit's automotive cluster hosts OEM qualification labs where SAE test protocols determine supplier eligibility for Ford and General Motors assembly lines.
Germany
Long-haul trucking operators in the Rhine-Ruhr industrial belt specify microglass media to meet Euro VI particulate thresholds enforced by ECHA. The country's national type-approval body, KBA, administers filtration efficiency certifications that gate aftermarket interchangeability. Mannheim's logistics hub concentrates fleet management platform providers integrating telematics-enabled condition monitoring for predictive filter replacement scheduling.
China
Domestic engine manufacturers in the Yangtze River Delta qualify synthetic media ahead of MEE's GB VI enforcement deadlines. The Ministry of Ecology and Environment mandates particulate number limits mirroring Euro VI stringency. Shanghai's port infrastructure scales aftermarket parts distribution to inland provinces where commercial vehicle fleet standardization accelerates filter procurement consolidation.
India
Truck fleet operators in Maharashtra and Gujarat expand synthetic media adoption as BIS emissions standards tighten. The Bureau of Indian Standards enforces filtration benchmarks that legacy cellulose production cannot satisfy. Pune's automotive manufacturing corridor attracts first-mover suppliers establishing local production capacity for underpenetrated commercial vehicle aftermarket segments.
Brazil
Agricultural machinery fleets in São Paulo state drive industrial filter demand amid expanding biofuel blending requirements. ANVISA and national environmental regulators impose fuel quality standards that elevate water-separation specifications. Campinas' engineering cluster hosts service network expansion by multinational suppliers targeting Latin America's largest commercial vehicle installed base.
Global Fuel and Oil Filters Market Vendor Landscape
Concentration sits with diversified filtration conglomerates controlling captive media production. The vendor base spans three tiers: integrated conglomerates with in-house synthetic fiber spinning, mid-scale specialists sourcing media from chemical suppliers, and regional assemblers of commodity cellulose products. Strategic moves center on backward integration into polymer resin production and modular housing designs that reduce OEM assembly labor exposure.
Within the integrated conglomerate tier, Mann+Hummel and Donaldson Company exemplify archetypes built on synthetic media control and high-durability industrial positioning respectively. MAHLE GmbH occupies a position emphasizing modular architectures that streamline OEM assembly line integration. These three anchors demonstrate how competitive positioning derives from upstream control over material cost curves versus downstream proximity to fleet procurement consolidation.
| Leading Market Players |
|---|
| Mann+Hummel |
| Donaldson Company |
| MAHLE GmbH |
| Robert Bosch GmbH |
| Denso Corporation |
| Sogefi SpA |
| Cummins Inc. |
| UFI Filters |
| FRAM Group |
| Others |
Supply Flow & Price Mechanics
Synthetic polymer nanofiber layers replacing pure cellulose constructions are redrawing procurement geography toward resin producers in Germany and Japan while compressing margin structures for legacy paper filter assemblers in China and India. Fleet operators in North America and Europe now specify extended-drain composites that command premium realization, forcing aftermarket distributors to rebalance inventory toward higher-cost synthetic grades.
Pricing Analysis
Volume-discount tiering separates OEM qualification contracts from aftermarket spot procurement, with synthetic media carrying ISO 4548 certification premiums over uncertified cellulose alternatives. Price differentiation hinges on SAE validation status and fleet scale commitments, with largest commercial vehicle operators extracting steepest rebates. Pricing pressure stems from raw material cost volatility in petrochemical feedstocks, squeezing margin stability for media producers without captive resin supply. Aftermarket distributors serving individual vehicle owners exhibit highest price sensitivity; OEM procurement teams prioritize performance guarantees over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for borosilicate microglass fiber sourced from German specialty chemical producers. Supply concentrates in Germany, China, and the United States for synthetic polymer resin and microglass media, with pleated paper legacy capacity anchored in India and Brazil. Raw material dependencies center on high-performance polymer grades, cellulose pulp feedstocks, and corrosion-resistant metal housings. Single-source vulnerability in specialty resin production creates bottleneck risk for filter manufacturers qualifying new OEM platforms. Distribution runs through port-centric bulk terminals in Rotterdam and Shanghai, feeding regional aftermarket hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial vehicle production cycles and emissions enforcement timelines position this market for cyclical recovery as fleet replacement demand accelerates through tightening EPA Tier 4 and Euro VI implementation windows.
For Market Incumbents: Shield margin structures through backward integration into synthetic polymer resin production, eliminating exposure to petrochemical feedstock volatility that squeezes non-integrated competitors. Capture fleet procurement consolidation by embedding telematics-enabled condition monitoring into filter housings, creating switching costs against lower-priced cellulose alternatives. Prioritize ISO 4548 certification investments that gate OEM qualification and aftermarket interchangeability. For New Entrants and Emerging Players: Differentiate on modular housing architectures that reduce installation complexity for European OEM assembly lines, where Volkswagen Group and BMW specifications favor tool-free quick-connect designs. Target India's underpenetrated commercial vehicle aftermarket, where BIS emissions enforcement is disqualifying legacy cellulose suppliers and first-mover synthetic media production in Pune offers localized cost positioning. Pursue joint development agreements with domestic engine manufacturers qualifying ahead of MEE deadlines. For Investors and Strategic Acquirers: Euro VI and China's GB VI enforcement reshapes the acquisition landscape toward synthetic media specialists with captive microglass production and established OEM qualification relationships. Long-term viability favors vertically integrated platforms controlling resin-to-housing cost curves over pure assembly operations exposed to raw material volatility. Monitor fleet telematics penetration rates in Germany and the Netherlands as the signal indicating predictive maintenance adoption and associated premium filter specification pull-through.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Resin Production | Captive polymer supply insulates margin from petrochemical volatility while securing OEM qualification timelines. |
| Telematics-Enabled Condition Monitoring Integration | Sensor-embedded housings create fleet switching costs and predictive replacement revenue streams in European trucking. |
| Local Production Capacity in India | Pune manufacturing footprint captures BIS-driven synthetic media substitution in underpenetrated commercial vehicle aftermarket. |
| Modular Quick-Connect Housing Design | Tool-free installation specifications align with Volkswagen Group and BMW assembly line labor reduction targets. |
| Remanufacturing and Core Return Programs | Extended producer responsibility frameworks in the European Union incentivize circular service model economics. |
Methodological Framework
A spread of perspectives from fleet procurement directors, OEM platform engineers, aftermarket distributor category managers, and synthetic media R&D directors converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against EPA regulatory filings, ECHA enforcement databases, SAE technical standards, and customs trade records for filter media and housing components. Bottom-up triangulation across vehicle production databases and top-down reconciliation with emissions enforcement timelines anchored volume estimates.
Segmentation dimensions modeled span product type, industry vertical, filter technology, and connection geometry across the projection horizon. CAGRs derived from regression analysis against fleet replacement cycles, regulatory phase-in schedules, and synthetic media penetration curves. Forecast inputs incorporated commercial vehicle fleet standardization rates in China, India, and Brazil alongside common-rail injection system adoption in marine and industrial applications.
The analysis sits within stated boundaries; outcomes outside sustained emissions enforcement intensity or accelerated electrification adoption would require recalibration. Forecasts reflect assumptions regarding raw material cost trajectories, OEM qualification timeline stability, and aftermarket infrastructure scaling in target geographies. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Power Liftgate Market
Automotive Parts
Automotive Viscosity Index Improvers Market
Automotive Parts
Automotive Wiping Systems Market
Automotive Parts
Bumper Beam Market
Automotive Parts
Global Automotive Gas Charged Shock Absorbers Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Automotive Hydraulic Filters Market
Automotive Parts
Malaysia Brake Pads Market
Automotive Parts
Automotive Grease Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
UAE Automotive Lubricants Market
Automotive Parts
Automotive Oil Pans Market
Automotive Parts
Automotive Brake Fluid Market
Automotive Parts
Auxiliary Oil Cooler Market
Automotive Parts
Cycloid Gear Market
Automotive Parts
Automotive Hinges Market