
 Transitional Care Management Services Market | 2026-2036
Transitional Care Management Services Market Size, Share, and Industry Trends Forecast 2026-2036
Transitional Care Management Services Market Intelligence
Post-acute care coordination is realigning toward health plan and payer-led models as Medicare Advantage enrollment expands. WellSky leverages its interoperability platform to anchor hospital-to-home workflows across multiple states. PharMerica Corporation sustains specialized medication reconciliation services that reduce thirty-day readmission risk. NextGen Healthcare competes through embedded care transition modules within its ambulatory EHR suite.
Transitional Care Management Services encompass structured clinical oversight during the thirty-day period following discharge from acute inpatient settings, combining medication reconciliation, timely follow-up appointments, and care plan communication across settings. These services operate through registered nurse outreach, physician engagement, and real-time health information exchange to prevent adverse events and unplanned rehospitalization. Value-Based Care payment models within the Payment Model segment capture expanding margin pools as CMS penalties for excess readmissions tighten. Telehealth delivery within the Delivery Model segment leads post-pandemic infrastructure buildout, though In-Person Care retains dominance in rural service areas where broadband gaps persist.
CMS reimbursement rules and the Medicare Access and CHIP Reauthorization Act shape provider participation requirements and documentation standards for billable TCM codes. FDA oversight of remote patient monitoring devices and HIPAA privacy frameworks constrain data flows between acute and post-acute settings. Stakeholders must monitor evolving CMS rulemaking on scope-of-practice flexibilities and telehealth parity to calibrate workforce deployment and technology investment.
Market Dynamics
CMS readmission penalty expansion under the Hospital Readmissions Reduction Program is compressing hospital margins and forcing accelerated outsourcing of post-discharge oversight to specialized TCM vendors.
Growth Catalysts
- Medicare Advantage network expansion:CMS reimbursement parity for TCM services in MA plans pulls enrollment toward capitated models that embed transitional care as a covered benefit.
- Remote patient monitoring integration:FDA-cleared biometric devices enable continuous physiologic surveillance during the thirty-day window, triggering earlier clinical intervention.
- Interoperability mandates:The 21st Century Cures Act information blocking rules compel EHR vendors to open APIs, reducing friction in hospital-to-home data handoffs.
Market Restraints
- Rural broadband deficits:Telehealth-dependent TCM delivery fails in census tracts lacking FCC-mapped broadband infrastructure, forcing costlier in-person staffing.
- Registered nurse labor scarcity:Post-acute care settings compete with acute hospitals for the same limited pool of licensed RNs, inflating wage costs.
- HIPAA-compliant data architecture:Technical requirements for encrypted transmission between disparate EHR systems impose implementation delays and vendor lock-in.
Strategic Opportunities
- Behavioral health comorbidity protocols:Depression and anxiety screening during TCM outreach opens reimbursement under collaborative care codes.
- SNF-at-home waiver expansion:CMS demonstration authority permits skilled nursing facility-level services in residential settings, extending TCM reach.
- Social determinants data integration:Z-code capture for housing instability and food insecurity enables risk-adjusted MA premium revenue capture.
Industry Challenges
- Documentation burden for billable codes:TCM 99495 and 99496 require precise timestamping of interactive contact and face-to-face visits, creating audit exposure.
- Physician engagement fragmentation:Community primary care panels resist assuming accountability for hospital-initiated care plans, generating handoff failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transitional Care Management Services Market |
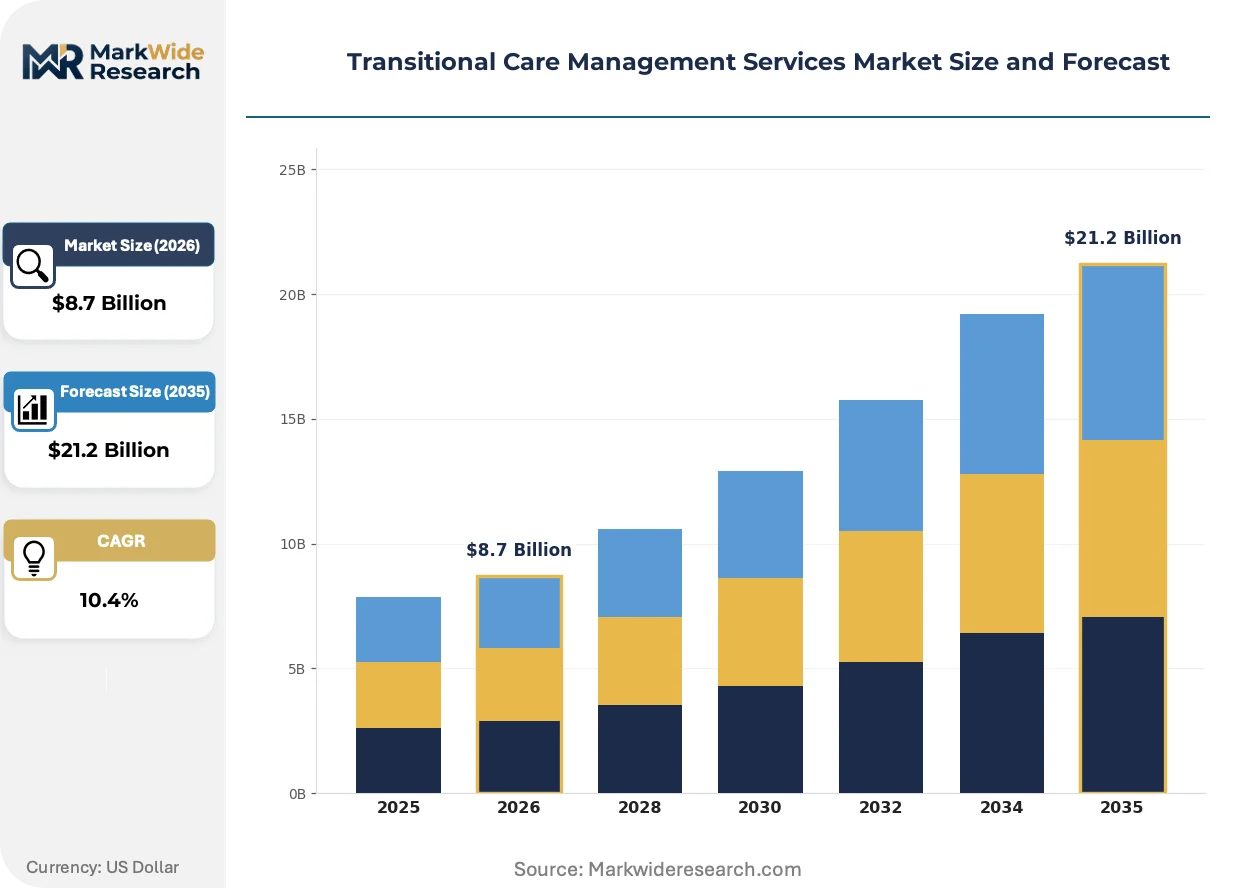
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $21.2 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Home Health, Skilled Nursing Facility, Outpatient, Rehabilitation Delivery Model: Telehealth, In-Person Care, Community-Based, Hospital-Based End User: Patients, Healthcare Providers, Caregivers, Health Plans Payment Model: Fee-for-Service, Capitation, Value-Based Care, Insurance Reimbursement |
| Companies Covered | Rijuven Corp., ACT Health Solutions, Humworld Inc., Monogram Health, WellSky, NextGen Healthcare, CareVitality, Vivify Health, PharMerica Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transitional Care Management Services Market Strategic Shifts & Innovations
Artificial intelligence triage algorithms and predictive risk stratification are resequencing how post-acute resources deploy across patient populations.
Machine learning models trained on admission-to-discharge data streams are overtaking static LACE scores for readmission risk prediction. Medicare Advantage plans in Florida and Texas deploy these tools to prioritize high-touch outreach. The technology is compressing the window between discharge and first clinical contact from seventy-two hours to under twenty-four.
CMS scope-of-practice flexibilities for nurse practitioners and physician assistants expand the eligible workforce for TCM service delivery. The policy shift permits non-physician clinicians to conduct the required face-to-face visit in states with reduced supervision requirements. Rural health clinics in the Mountain West states respond by restructuring staffing models to maximize APP utilization.
Health system procurement departments now bundle TCM services into multi-year post-acute network agreements rather than purchasing standalone programs. The contracting shift displaces point-solution vendors in favor of platforms offering hospital-at-home, palliative care, and chronic care management integration. Integrated delivery networks in the Upper Midwest exhibit the most advanced bundling sophistication.
Transitional Care Management Services Market Segmentation
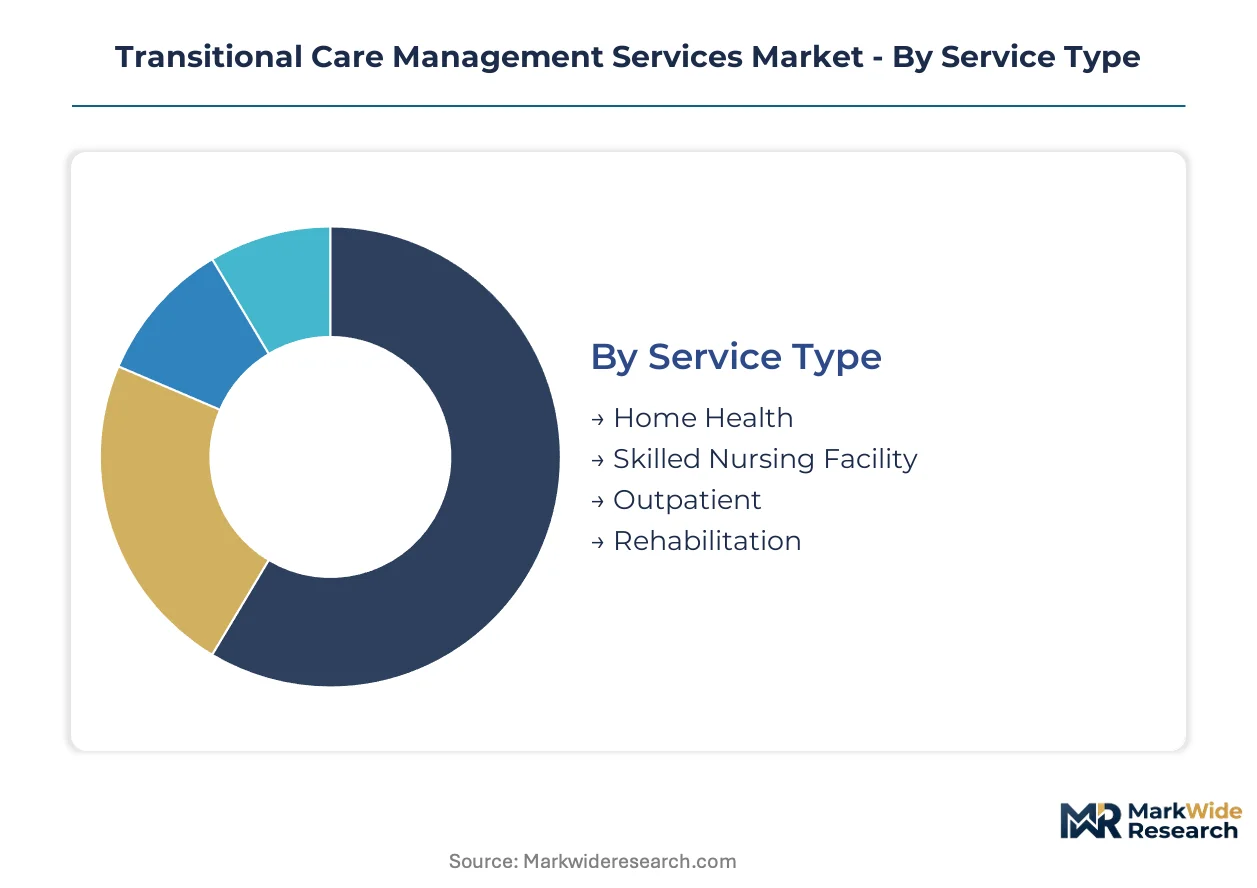
Segmentation in transitional care management reveals how reimbursement mechanics and care setting preferences reshape vendor capabilities. Each axis exposes different margin pressures and technology requirements that determine competitive positioning.
Service Type:
Clinical intensity and site-of-care regulations differentiate service capabilities across post-acute settings.
- Home Health:Registered nurse and therapist visits delivered in residential settings under Medicare Part A certification requirements. Demand concentrates in Medicare Advantage networks across Florida and Texas where capitated rates favor lower-cost alternatives to institutional care. CMS home health value-based purchasing adjustments tighten quality thresholds.
- Skilled Nursing Facility:Twenty-four-hour licensed nursing care with rehabilitation therapy in Medicare-certified institutional settings. Volume clusters in Upper Midwest states with aging demographics and higher SNF bed density. Three-day prior hospitalization rule constrains admission flows.
- Outpatient:Physician or nurse practitioner visits in ambulatory clinics without overnight stay. Rapid expansion in hospital-owned medical groups seeking to capture professional fee revenue.
- Rehabilitation:Intensive therapy services for functional recovery post-stroke or orthopedic surgery. Inpatient rehabilitation facilities face Medicare IRF prospective payment system compliance burdens.
Home Health leads on scale; Skilled Nursing Facility leads on momentum as SNF-at-home waivers expand.
Delivery Model:
Technology infrastructure and workforce deployment models determine reach and cost structure across patient populations.
- Telehealth:Two-way audio-video and remote patient monitoring for virtual care coordination. FCC-mapped broadband gaps exclude rural census tracts in Mountain West states. HIPAA-compliant platforms require encrypted transmission architectures.
- In-Person Care:Face-to-face clinical contact by licensed staff in patient homes or clinics. Dominates rural service areas where telehealth fails. Registered nurse labor scarcity inflates wage costs.
- Community-Based:Services anchored in senior centers, faith organizations, and housing complexes. Emerging in Massachusetts and California accountable care organizations addressing social determinants.
- Hospital-Based:TCM programs operated directly by acute care systems. Contracting shifts favor bundled multi-year post-acute network agreements displacing standalone programs.
In-Person Care retains volume concentration; Telehealth gains share fastest as RPM integration accelerates.
End User:
Accountability structures and reimbursement capture mechanisms determine which stakeholder controls purchasing decisions.
- Patients:Medicare beneficiaries and dual-eligibles navigating thirty-day post-discharge protocols. Medication reconciliation and timely follow-up appointment adherence drive outcomes.
- Healthcare Providers:Hospitals and physician groups bearing CMS readmission penalties. Hospital Readmissions Reduction Program compresses margins and accelerates outsourcing.
- Caregivers:Family members and informal supports receiving structured education and care plan communication. Depression and anxiety screening opens collaborative care reimbursement.
- Health Plans:Medicare Advantage organizations capturing risk-adjusted premiums through Z-code documentation. Social determinants data integration enables premium revenue optimization.
Healthcare Providers anchor current procurement; Health Plans are displacing them as network contracting centralizes.
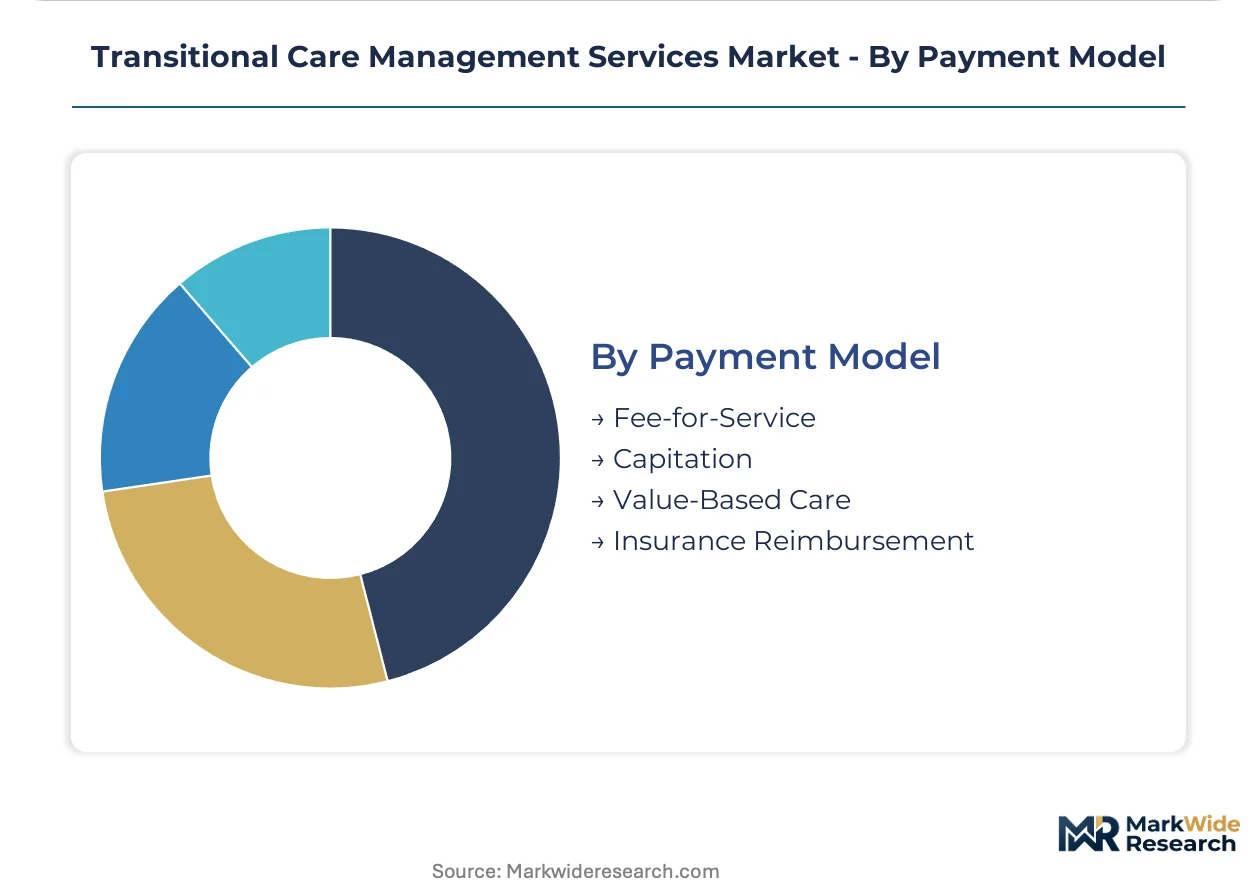
Payment Model:
Reimbursement mechanics determine margin stability and documentation burden across service lines.
- Fee-for-Service:Billing under CPT codes 99495 and 99496 with precise timestamping requirements. Audit exposure from interactive contact and face-to-face visit documentation.
- Capitation:Per-member-per-month payments in Medicare Advantage plans. CMS reimbursement parity for TCM services pulls enrollment toward embedded benefit models.
- Value-Based Care:Shared savings and downside risk arrangements with quality thresholds. Expanding margin pools as CMS penalties for excess readmissions tighten.
- Insurance Reimbursement:Commercial payer contracts outside Medicare fee schedules. Prior authorization requirements create administrative friction.
Fee-for-Service dominates transaction volume; Value-Based Care shows steepest expansion trajectory as risk assumption spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in transitional care management favors jurisdictions with mature Medicare Advantage penetration and permissive scope-of-practice rules, drawing vendor investment toward states with streamlined licensing reciprocity and capitated reimbursement density.
United States
Medicare Advantage enrollment exceeds fifty percent of eligible beneficiaries in Florida and Texas, concentrating demand for TCM services in capitated networks. CMS Hospital Readmissions Reduction Program penalties compress hospital margins and accelerate outsourcing to specialized vendors. Dallas-Fort Worth anchors the nation's densest cluster of post-acute technology platforms, where health systems bundle TCM into multi-year network agreements.
Germany
Aging demographics and statutory health insurance integration create demand for structured discharge protocols in Bavaria and North Rhine-Westphalia. The country's national pharmaceutical regulator enforces strict documentation standards for medication reconciliation that exceed HIPAA-equivalent frameworks. Berlin-Brandenburg hosts emerging digital health startups piloting AI-driven risk stratification for post-acute triage.
United Kingdom
NHS Integrated Care Systems consolidate purchasing authority for post-discharge services across England, concentrating procurement in London and the Southeast. MHRA oversight of remote patient monitoring devices shapes vendor compliance architecture. Greater Manchester demonstrates advanced social determinants data integration, capturing housing instability and food insecurity codes for risk-adjusted funding.
Japan
Super-aging prefectures in Kanto and Kansai drive demand for home-based transitional care as institutional bed capacity contracts. METI digital health subsidies accelerate telehealth infrastructure buildout in rural Tohoku regions. Osaka anchors specialized rehabilitation networks integrating post-discharge functional recovery protocols with community-based care coordination.
Australia
My Health Record interoperability mandates reduce friction in hospital-to-home data handoffs across New South Wales and Victoria. TGA clearance requirements for biometric monitoring devices constrain RPM vendor entry. Sydney hosts the Asia-Pacific headquarters of multinational post-acute platforms seeking regional expansion through Medicare Advantage-equivalent private insurance partnerships.
Transitional Care Management Services Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with health plan-affiliated platforms capturing expanding margin pools while point-solution vendors face displacement. The vendor base concentrates around three strategic archetypes: interoperability-anchored hospital workflow platforms, medication reconciliation specialists, and embedded EHR module providers. Consolidation accelerates through multi-year post-acute network bundling and health system captive buildouts of in-house TCM capabilities.
Within the interoperability-anchored tier, WellSky exemplifies platform consolidation through hospital-to-home workflow integration across multiple states. PharMerica Corporation occupies a position among medication reconciliation specialists reducing thirty-day readmission risk through pharmaceutical expertise. NextGen Healthcare sits within the embedded module archetype, representing ambulatory EHR vendors competing through care transition functionality.
| Leading Market Players |
|---|
| Rijuven Corp. |
| ACT Health Solutions |
| Humworld Inc. |
| Monogram Health |
| WellSky |
| NextGen Healthcare |
| CareVitality |
| Vivify Health |
| PharMerica Corporation |
| Others |
Cost & Logistics Intelligence
Platform-to-point-solution bifurcation in vendor capabilities separates interoperability-anchored workflow suites from standalone medication reconciliation modules, with pricing power concentrating in bundled multi-year agreements while supply chains fragment across registered nurse staffing networks, RPM device manufacturers, and EHR API infrastructure providers.
Pricing Analysis
Distributor margins in health system procurement compress standalone TCM vendors while platform players capture direct contracting premiums. Value-based care arrangements stratify across risk-assumption tiers, with capitated Medicare Advantage models commanding price premiums over fee-for-service billing. Pricing pressure stems from CMS readmission penalty tightening that squeezes hospital margins and forces cost-down negotiations. Community health centers exhibit highest price sensitivity; integrated delivery networks in the Upper Midwest demonstrate lowest sensitivity due to bundled purchasing authority.
Supply Chain Analysis
Registered nurse labor supply rests on domestic US staffing pools competing across acute and post-acute settings, with telehealth infrastructure drawing from FCC-mapped broadband providers and FDA-cleared RPM device manufacturers. HIPAA-compliant cloud architecture and encrypted EHR transmission protocols constitute critical technology dependencies. Single-source vulnerability concentrates in specialized nurse practitioner licensing reciprocity across Mountain West states. Distribution runs through health system procurement departments consolidating multi-year post-acute network agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in transitional care management services hinges on workforce substitution toward nurse practitioners and physician assistants under CMS scope-of-practice flexibilities, reducing labor cost intensity while premium-tier platforms capture bundled contracting premiums.
For Market Incumbents: Cement platform stickiness through deeper EHR API integration that locks hospital systems into hospital-to-home workflow continuity. Expand registered nurse staffing networks in Florida and Texas Medicare Advantage corridors to preempt labor scarcity. Defensive investment in AI-driven risk stratification counters emerging predictive analytics entrants.
For New Entrants and Emerging Players: Rural health clinics in broadband-deficient Mountain West census tracts present an underserved buyer archetype forced into costlier in-person staffing models. SNF-at-home waiver expansion in Massachusetts and California accountable care organizations opens white-space for community-based care coordination. Go-to-market through social determinants Z-code capture tools enables risk-adjusted premium revenue sharing with Medicare Advantage plans.
For Investors and Strategic Acquirers: Consolidation pressure builds where point-solution vendors face displacement by bundled platform procurement in Upper Midwest integrated delivery networks. Long-term viability favors interoperability-anchored workflow suites with multi-state hospital network penetration over standalone medication reconciliation specialists. Watch CMS rulemaking on telehealth parity and scope-of-practice uniformity as inflection indicators for workforce scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | WellSky's interoperability architecture anchors hospital-to-home workflows across multiple states. |
| Reimbursement Strategy | PharMerica's medication reconciliation services reduce thirty-day readmission risk under CMS penalties. |
| Hospital System Partnership | NextGen Healthcare embeds care transition modules within ambulatory EHR suites for physician group capture. |
| Software Companion Development | Vivify Health's remote patient monitoring integration enables continuous physiologic surveillance post-discharge. |
| Geographic Expansion | Monogram Health concentrates specialized post-acute services in Medicare Advantage-dense Florida and Texas corridors. |
Research Approach
Bottom-up patient volume modeling reconciled against top-down vendor capacity tracking forms the analytical core of this study. Primary interviews with care transition program directors, Medicare Advantage contracting officers, hospital procurement managers, and post-acute staffing agency executives combined with secondary validation against CMS Medicare data, hospital procurement databases, GPO contracts, and FDA 510(k) filings for RPM devices. Triangulation across these sources ensures cross-verified demand and supply estimates.
Historical trendline analysis of Medicare Advantage enrollment patterns and CMS readmission penalty expansion informs the projection framework. Segmentation modeling spans service type, delivery model, end user, and payment model dimensions across the analysis window. CAGRs derive from reconciling bottom-up patient flow projections with top-down reimbursement rate trajectories, incorporating FDA regulatory timelines for remote monitoring device clearances and FCC broadband infrastructure mapping.
Underlying measurement precision varies by segment; fee-for-service billing volumes carry tighter precision than emerging value-based care arrangements. Forecasts reflect assumptions on CMS rulemaking continuity, scope-of-practice legislative stability, and telehealth parity permanence. Regulatory shifts on nurse practitioner supervision requirements and information blocking enforcement constitute primary revision triggers warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market
Healthcare Services
Eastern Europe Online Pharmacy Market
Healthcare Services
US Care Services Market
Healthcare Services
US Cord Blood Banking Services Market
Healthcare Services
Medical Second Opinion Market
Healthcare Services
Vaccine Transport Carrier Market
Healthcare Services
Biopharmaceutical Third Party Logistics (3PL) Market
Healthcare Services
Hospice and Palliative Care Centers Market
Healthcare Services
Global Healthcare Services Market
Healthcare Services
Hair Transplant Services Market
Healthcare Services
US Hospice Care Market
Healthcare Services
Global Contract Sterilization Market
Healthcare Services
Global Offsite Medical Case Management Market
Healthcare Services
United States Pharmaceutical Logistic Services Market
Healthcare Services
Healthcare Logistics Market
Healthcare Services
Global Cord Blood Banking Services Market