
 United States Pharmaceutical Logistic Services Market | 2026-2036
United States Pharmaceutical Logistic Services Market Size, Share, and Industry Trends Forecast 2026-2036
United States Pharmaceutical Logistic Services Market Insights
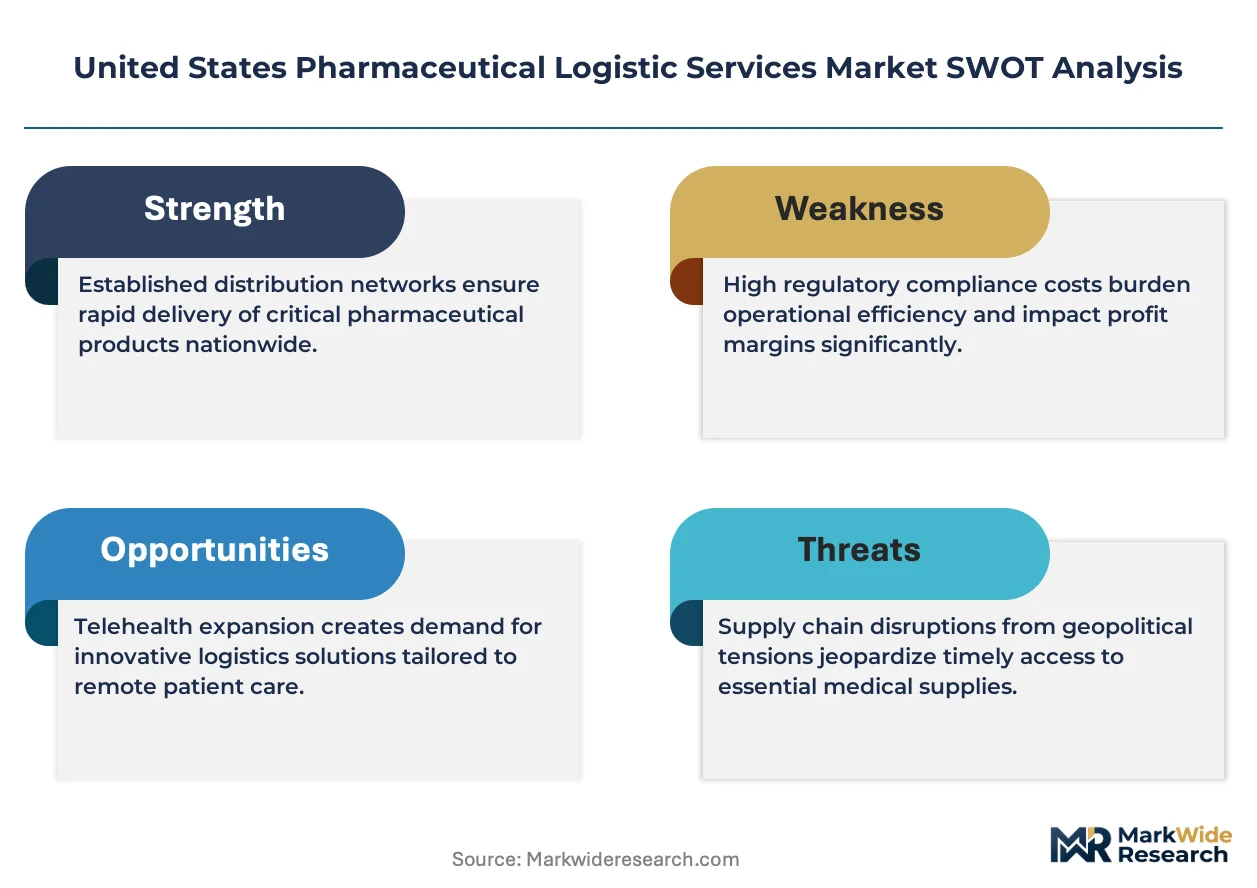
Biologics-grade cold chain infrastructure is hardening as the dominant cost layer in pharmaceutical logistics economics. FedEx Corporation sustains temperature-controlled network density through its SenseAware monitoring platform, while Lineage Logistics Holdings, LLC anchors national cold storage capacity with specialized pharmaceutical-grade facilities. Cardinal Health differentiates through integrated distribution services that span manufacturer direct-to-pharmacy channels.
Pharmaceutical logistic services encompass the specialized movement, storage, and handling of temperature-sensitive drug products, clinical trial materials, and active pharmaceutical ingredients under validated conditions typically ranging from 2°C to 8°C for standard cold chain and -60°C to -80°C for ultra-frozen biologics, ensuring product integrity from manufacturing through final patient administration. Transportation services, particularly air freight for time-critical biologics and last mile delivery for direct-to-patient models, command premium margins due to specialized handling requirements. Warehousing segments are consolidating around automated, GMP-compliant facilities with redundant backup power systems.
FDA enforcement of the Drug Supply Chain Security Act and Good Distribution Practice standards shapes facility investment and track-and-trace technology deployment across the sector. DEA controlled-substance scheduling requirements and state-level pharmacy board regulations add compliance layers that favor large-scale operators with dedicated regulatory affairs capabilities. Stakeholders must weigh capital allocation between owned cold chain infrastructure and third-party logistics partnerships as product portfolios shift toward cell and gene therapies with more extreme handling requirements.
Market Dynamics
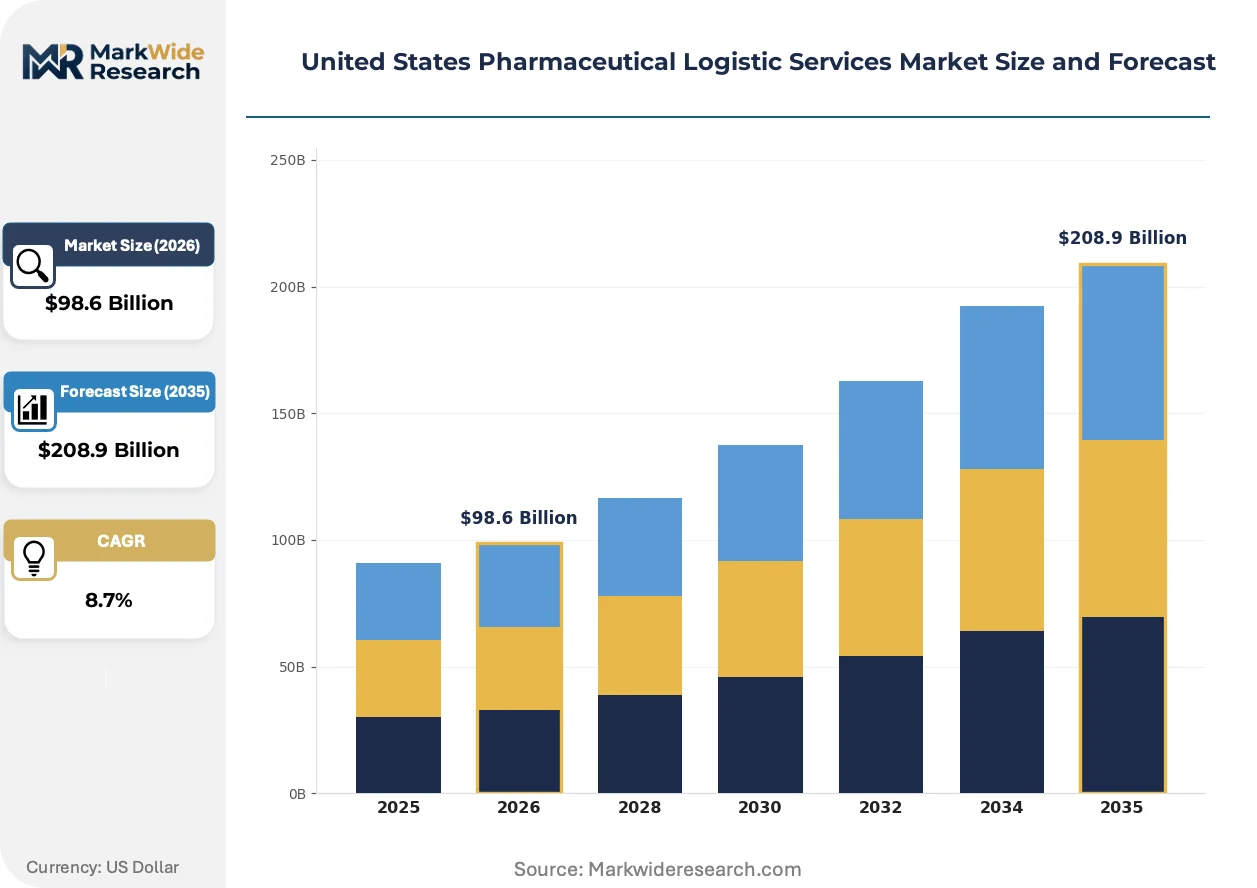
Biologics-grade cold chain requirements are hardening infrastructure economics across the United States pharmaceutical logistics sector. FDA Drug Supply Chain Security Act serialization mandates are accelerating capital deployment toward track-and-trace systems and validated temperature monitoring.
Growth Catalysts
- Cell and Gene Therapy Pipeline:CAR-T and gene editing treatments require cryogenic logistics at -150°C, pulling investment into specialized liquid nitrogen infrastructure and dedicated fleet capacity.
- IRA Price Negotiation Provisions:Medicare drug pricing reforms are compressing manufacturer margins and forcing logistics outsourcing to third-party cold chain specialists with scale efficiencies.
- Northeast Manufacturing Cluster Density:New Jersey and Pennsylvania pharmaceutical production concentration creates natural hub-and-spoke distribution economics that favor regional 3PL consolidation.
Market Restraints
- Dry Ice Supply Volatility:Carbon dioxide capture shortages and regional production gaps create input cost instability for -80°C shipment lanes.
- Qualified Personnel Scarcity:FDA Good Distribution Practice certification requirements and specialized cold chain handling expertise constrain workforce scalability.
- Ultra-Low Freezer Infrastructure Gap:Limited domestic manufacturing of -80°C storage equipment creates equipment lead times exceeding 18 months for new facility builds.
Strategic Opportunities
- Direct-to-Patient Distribution Models:Specialty pharmacy home infusion and patient-centric delivery channels bypass traditional wholesale intermediaries for high-value biologics.
- Real-Time Visibility Convergence:IoT sensor networks and blockchain traceability systems are merging to create immutable temperature excursion documentation for FDA audit readiness.
- Texas and Florida Manufacturing Migration:Emerging pharmaceutical production hubs in Sun Belt states lack mature cold chain infrastructure, creating greenfield 3PL development potential.
Industry Challenges
- DEA Controlled Substance Scheduling:Dual-licensed facilities for Schedule II-V pharmaceuticals face complex state-level pharmacy board reciprocity barriers that fragment national network coverage.
- Legacy Warehouse Management System Integration:ERP connectivity gaps between manufacturer inventory systems and 3PL platforms create data latency in serialized product tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Pharmaceutical Logistic Services Market |
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $208.9 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Order Fulfillment, Inventory Management Delivery Mode: Air Freight, Ground Transport, Ocean Freight, Last Mile Delivery Packaging Type: Temperature-Controlled, Secure Packaging, Standard Packaging, Specialized Packaging End User: Pharmaceutical Manufacturers, Distributors, Retail Pharmacies, Healthcare Providers |
| Companies Covered | United Parcel Service, Inc., FedEx Corporation, DHL Supply Chain & Global Forwarding, Lineage Logistics Holdings, LLC, Americold Realty Trust, Inc., Owens & Minor, Inc., C.H. Robinson Worldwide, Inc., SEKO Logistics, Inc., Cardinal Health, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Pharmaceutical Logistic Services Market Trends and Innovations
Digital twin modeling and predictive analytics are compressing temperature excursion response times across pharmaceutical distribution networks. These technologies enable proactive intervention before product integrity thresholds breach.
Passive thermal packaging systems with phase-change materials are converging with reusable container platforms to reduce single-use shipping waste. Large molecule biologics shippers are adopting these hybrid systems for lane qualification cost reduction. The technology is converging with circular economy mandates from ESG-focused pharmaceutical procurement teams.
FDA enforcement of the Drug Supply Chain Security Act is mandating unit-level serialization down to the salable unit by November 2024. This compels wholesale distributors to deploy aggregation software that reconciles case-level and pallet-level identifiers. Small and mid-sized 3PLs lacking IT infrastructure are exiting the market or seeking technology partnerships.
Hospital and health system consolidation is compressing vendor management overhead through preferred provider agreements with integrated distribution networks. Multi-hospital systems are consolidating pharmacy procurement under centralized specialty pharmacy entities. This concentration is most visible in the Northeast corridor where IDN mergers have reduced qualified 3PL panels to three or four approved partners per system.
United States Pharmaceutical Logistic Services Market Segmentation
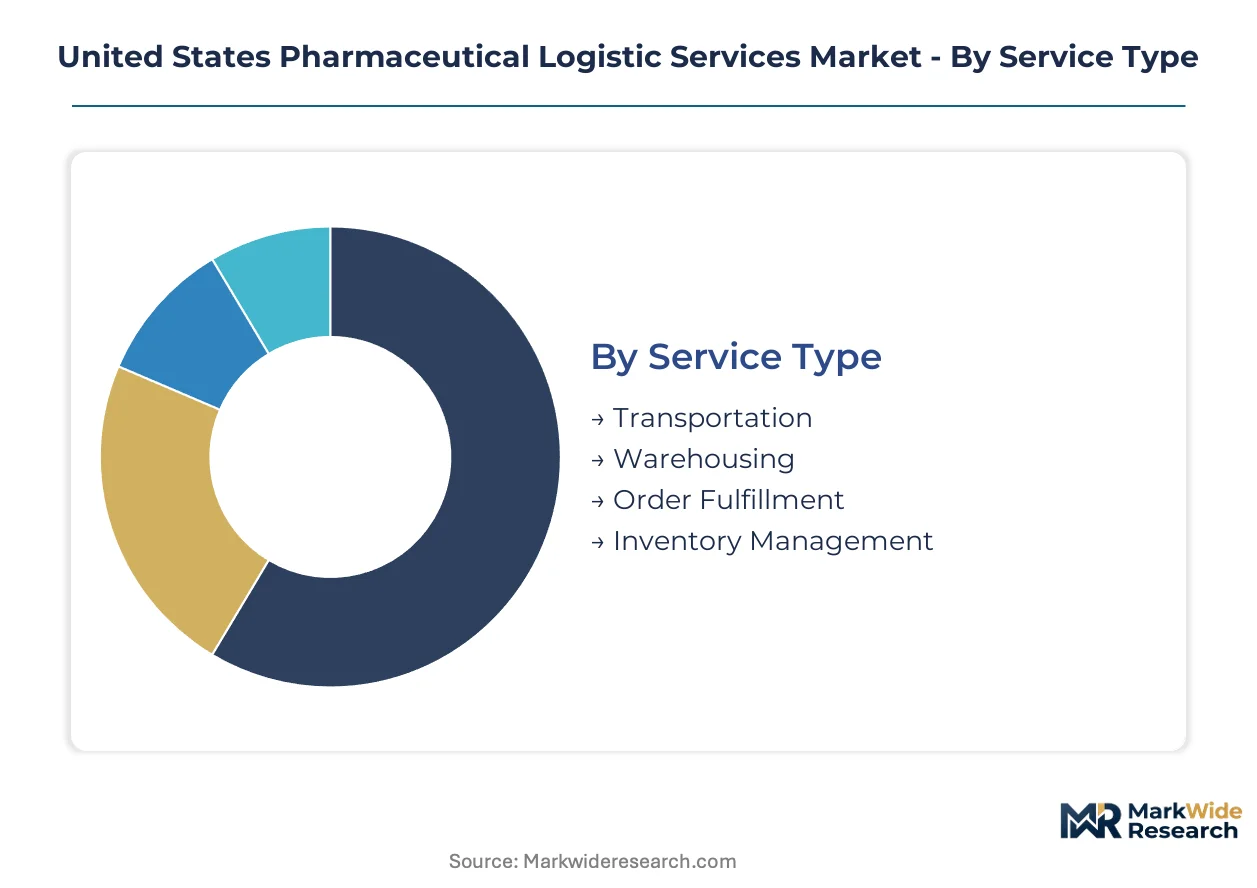
Pharmaceutical logistics segmentation reflects divergent compliance burdens and capital intensity across service modalities. FDA Good Distribution Practice requirements and DEA controlled-substance licensing create tiered barriers that concentrate market share among operators with multi-certification capabilities.
Service Type:
Cold chain validation protocols and serialization mandates impose distinct certification requirements across operational categories, with temperature-controlled segments demanding redundant infrastructure investments.
- Transportation:Active and passive thermal systems maintain 2°C to 8°C or cryogenic ranges through validated lane qualification studies. Biologics manufacturers in New Jersey and Pennsylvania cluster concentrate demand for dedicated fleet capacity with real-time temperature telemetry.
- Warehousing:GMP-compliant facilities with redundant backup power and automated storage and retrieval systems anchor regional distribution networks. Northeast pharmaceutical manufacturing density drives hub-and-spoke consolidation toward multi-tenant cold storage campuses.
- Order Fulfillment:Serialized picking and aggregation software reconcile unit-level identifiers for DSCSA compliance. Specialty pharmacy direct-to-patient channels require DEA-licensed fulfillment centers with controlled-substance vault infrastructure.
- Inventory Management:ERP integration platforms synchronize manufacturer production schedules with 3PL stock positioning. IRA price negotiation provisions are compressing manufacturer margins and accelerating outsourcing of inventory carrying costs.
Leading the category by volume: Transportation. Growing fastest: Order Fulfillment.
Delivery Mode:
Speed-to-patient requirements and product stability windows determine modal selection, with premium biologics commanding air freight while generics migrate toward cost-optimized ground networks.
- Air Freight:Time-critical biologics and clinical trial materials move through temperature-controlled cargo holds with dedicated pharmaceutical handling protocols. FedEx SenseAware and similar monitoring platforms provide continuous visibility for FDA audit documentation.
- Ground Transport:Refrigerated trucking serves regional distribution from Northeast manufacturing clusters to wholesale depots and specialty pharmacies. Lane density economics favor dedicated fleet deployment on high-frequency routes between New Jersey and Mid-Atlantic population centers.
- Ocean Freight:Bulk active pharmaceutical ingredients and stable small-molecule formulations move through temperature-monitored container units. Port congestion and customs clearance variability limit adoption for time-sensitive products.
- Last Mile Delivery:Direct-to-patient models bypass traditional wholesale channels for high-value specialty therapies. Home infusion and patient-centric delivery require HIPAA-compliant handling and signature capture protocols.
Air Freight commands the highest revenue per kilogram. Last Mile Delivery is expanding most quickly through specialty pharmacy consolidation.
Packaging Type:
Product thermal stability profiles and shipment duration dictate packaging investment, with reusable container platforms gaining traction under ESG procurement mandates.
- Temperature-Controlled:Phase-change material systems and active compressor units maintain validated temperature bands for biologics and vaccines. Reusable container fleets reduce single-use waste while requiring reverse logistics infrastructure.
- Secure Packaging:Tamper-evident seals and GPS tracking protect high-value controlled substances and anti-counterfeiting serialized products. DEA Schedule II-V requirements mandate dual-lock systems and chain-of-custody documentation.
- Standard Packaging:Ambient-stable small molecules and over-the-counter products utilize corrugated and blister packaging without thermal protection. Cost compression in generic distribution favors minimal packaging overhead.
- Specialized Packaging:Cryogenic liquid nitrogen dewars and dry ice shippers handle cell and gene therapies at -150°C to -80°C. Dry ice supply volatility creates input cost instability for ultra-cold shipment lanes.
Temperature-Controlled packaging dominates capital deployment. Specialized Packaging shows the steepest expansion trajectory as CAR-T pipeline volumes accelerate.
End User:
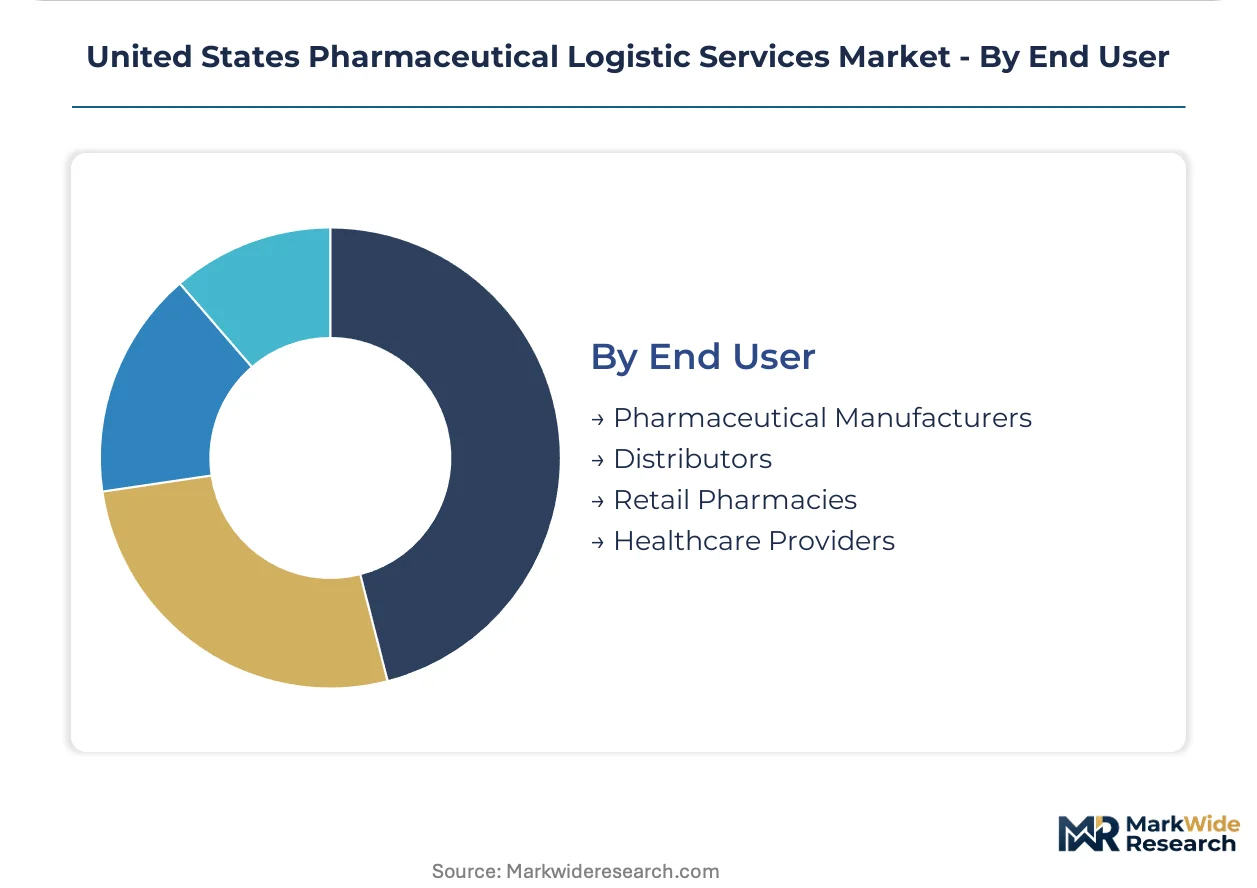
Procurement consolidation and vertical integration strategies are restructuring buyer power across the pharmaceutical supply chain, with integrated delivery networks capturing preferential 3PL relationships.
- Pharmaceutical Manufacturers:Brand and generic drug producers outsource distribution to gain DSCSA-compliant serialization infrastructure without captive capital investment. IRA pricing pressures are accelerating logistics outsourcing to variable-cost models.
- Distributors:Wholesale and specialty distributors operate as intermediaries with DEA licensing and cold chain capabilities that manufacturers lack. Cardinal Health and similar integrated networks span manufacturer direct-to-pharmacy channels.
- Retail Pharmacies:Chain and independent pharmacies receive just-in-time inventory replenishment from regional distribution centers. Centralized purchasing by multi-store operators compresses delivery frequency requirements.
- Healthcare Providers:Hospital and health system consolidation is compressing vendor panels to three or four approved 3PL partners per integrated delivery network. Specialty pharmacy entities within IDNs bypass wholesale intermediaries for high-value biologics.
Pharmaceutical Manufacturers represent the largest contract value. Healthcare Providers are gaining share fastest through IDN merger activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration in pharmaceutical manufacturing clusters drives logistics infrastructure deployment across the United States. Northeast corridor density creates hub-and-spoke distribution economics that favor regional 3PL consolidation. FDA Drug Supply Chain Security Act enforcement shapes facility investment patterns state by state.
Northeast Corridor
New Jersey and Pennsylvania pharmaceutical production concentration anchors the nation's largest cold chain logistics hub. FDA serialization mandates and DEA controlled-substance licensing requirements favor large-scale operators with dedicated regulatory affairs capabilities. The Interstate 95 corridor between Trenton and Philadelphia hosts the densest concentration of GMP-compliant warehousing capacity serving oncology clinics and specialty pharmacies.
Southeast
Florida and Georgia emerging pharmaceutical manufacturing migration creates greenfield 3PL development potential for temperature-controlled infrastructure. State pharmacy board reciprocity barriers fragment national network coverage for controlled substances. The Research Triangle Park area in North Carolina anchors clinical trial logistics demand with specialized courier services for investigational drug products.
Texas
Houston and Dallas-Fort Worth pharmaceutical production expansion outpaces mature cold chain infrastructure availability. The state's central location enables multi-day ground distribution reach to both coasts. Texas Medical Center concentration drives demand for cell and gene therapy cryogenic logistics at -150°C.
Midwest
Illinois and Ohio generic drug manufacturing clusters sustain high-volume ambient distribution networks. Chicago O'Hare air freight capacity supports time-critical biologics shipments to international markets. Interstate highway density enables cost-optimized refrigerated trucking to wholesale depots throughout the Great Lakes region.
West Coast
California biotech manufacturing in South San Francisco and San Diego generates specialized cold chain demand for monoclonal antibodies and recombinant proteins. Port of Los Angeles congestion limits ocean freight adoption for time-sensitive products. Seattle and Portland pharmaceutical distribution serves Pacific Northwest health system consolidation through centralized specialty pharmacy entities.
United States Pharmaceutical Logistic Services Market Competitive Landscape
Capacity expansion dominates the current landscape as operators deploy specialized liquid nitrogen infrastructure for cell and gene therapy pipelines. The vendor base concentrates around integrated distribution networks with multi-certification capabilities spanning FDA Good Distribution Practice and DEA controlled-substance licensing. Three archetypes define competitive positioning: asset-heavy cold storage specialists, integrated healthcare distributors, and express carriers with pharmaceutical-grade monitoring platforms. M&A activity and strategic partnerships represent the dominant competitive moves as scale efficiencies become critical under IRA price negotiation margin compression.
Among integrated healthcare distributors, Cardinal Health occupies a position spanning manufacturer direct-to-pharmacy channels. FedEx Corporation exemplifies the express carrier archetype with temperature-controlled network density. Lineage Logistics Holdings, LLC anchors the cold storage specialist tier with pharmaceutical-grade facilities. These three represent distinct strategic approaches to the sector's infrastructure economics.
| Leading Market Players |
|---|
| United Parcel Service, Inc. |
| FedEx Corporation |
| DHL Supply Chain & Global Forwarding |
| Lineage Logistics Holdings, LLC |
| Americold Realty Trust, Inc. |
| Owens & Minor, Inc. |
| C.H. Robinson Worldwide, Inc. |
| SEKO Logistics, Inc. |
| Cardinal Health |
| Others |
Pricing and Supply Chain Analysis
Integrated delivery network consolidation in the Northeast corridor compresses vendor panels to three or four approved 3PL partners per system, anchoring contract-based long-term offtake pricing with volume-commitment discounts.
Pricing Analysis
High-volume generic distribution runs on thin margins while specialty cold chain services capture premium returns. Three-tier pricing structure across DSCSA-compliant serialization, GMP-certified handling, and standard ambient storage separates service levels. Cost compression in generic segments intensifies because IRA price negotiation provisions squeeze manufacturer budgets. Retail pharmacy chains exhibit highest price sensitivity; cell and gene therapy sponsors show least.
Supply Chain Analysis
Dual-sourcing requirements from FDA Good Distribution Practice standards mandate pharmaceutical manufacturers qualify multiple cold chain providers for critical biologics. Equipment manufacturing for ultra-low freezers concentrates in the United States, Germany, and Japan. Dry ice supply draws from regional carbon dioxide capture facilities concentrated in the Gulf Coast and Midwest. Single-source vulnerability in liquid nitrogen infrastructure creates exposure. Distribution runs through hub-and-spoke networks anchored by New Jersey and Pennsylvania cold storage campuses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive cold storage assets is accelerating as IRA margin compression forces logistics cost control and FDA serialization mandates demand dedicated IT infrastructure.
For Market Incumbents: Hedge against dry ice supply volatility by securing long-term carbon dioxide offtake agreements with Gulf Coast industrial gas producers. Consolidate DEA dual-licensed facility networks to reduce state-level pharmacy board reciprocity fragmentation. Capacity addition in Texas and Florida manufacturing migration corridors captures greenfield demand before specialized infrastructure hardens. For New Entrants and Emerging Players: Specialty pharmacy direct-to-patient channels represent the most penetrable segment as home infusion bypasses wholesale intermediaries. Cryogenic logistics for CAR-T therapies at -150°C offers white-space opportunity with limited qualified competition. Go-to-market through technology partnerships with IoT sensor platforms accelerates FDA audit-ready temperature documentation without captive R&D investment. For Investors and Strategic Acquirers: The window for entry favors mid-scale cold storage specialists with GMP compliance and existing DEA licensing. Long-term viability hinges on scale efficiencies under manufacturer outsourcing acceleration. Watch dry ice supply stabilization as inflection indicator for ultra-cold shipment lane profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Nitrogen Infrastructure Deployment | CAR-T pipeline expansion requires -150°C cryogenic capacity with dedicated fleet investment. |
| DSCSA Aggregation Software Partnership | Small 3PLs lacking serialization IT infrastructure seek technology alliances for compliance survival. |
| Texas Cold Storage Campus Development | Pharmaceutical manufacturing migration outpaces mature cold chain availability in Sun Belt states. |
| Real-Time Visibility Platform Integration | IoT sensor networks merge with blockchain for immutable FDA temperature excursion documentation. |
| DEA Dual-Licensing Network Consolidation | State pharmacy board reciprocity barriers favor large operators with dedicated regulatory affairs capabilities. |
Research Methodology
Document review covered FDA Drug Supply Chain Security Act guidance documents, DEA controlled substance licensing databases, and pharmaceutical manufacturer 10-K logistics disclosures, complemented by interviews with cold chain operations directors, regulatory affairs leads at 3PLs, specialty pharmacy procurement managers, and integrated delivery network formulary directors. Secondary validation drew from ClinicalTrials.gov cryogenic logistics requirements, CMS Medicare drug pricing reports, and American Society of Health-System Pharmacists distribution surveys. Bottom-up facility capacity modeling and top-down pharmaceutical shipment value triangulation anchored market sizing.
Cross-reference between historical cold storage buildout patterns and expert panel input on cell and gene therapy pipeline logistics requirements shaped the analytical framework. Segmentation dimensions modeled include service type, delivery mode, packaging technology, and end-user vertical across the projection horizon. CAGRs derived from facility investment announcements, manufacturer outsourcing contract values, and temperature-controlled freight volume trends. IRA price negotiation implementation pace and CAR-T therapy approval velocity served as industry-specific forecast inputs.
Revisions become necessary when FDA enforcement intensity around DSCSA serialization shifts, dry ice supply volatility exceeds historical bands, or pharmaceutical manufacturing migration patterns deviate from Northeast corridor concentration. Deviation in IRA price negotiation provision expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Health Care Supply Chain Management Market
Healthcare Services
Blood Bank Market
Healthcare Services
Regulatory Affairs Outsourcing Market
Healthcare Services
Packaging and Labeling (Healthcare) Services Market
Healthcare Services
Tissue Banking Market
Healthcare Services
US Healthcare Staffing Market
Healthcare Services
Vaccine Logistics Market
Healthcare Services
Escort Bed Sharing Market
Healthcare Services
Global Hospital Services Market
Healthcare Services
Primary Care Physicians Market
Healthcare Services
Immunoassay CDMO Market
Healthcare Services
Western Europe Medical Recruitment Market
Healthcare Services
US Value-Based Healthcare Service Market
Healthcare Services
Medical Recruitment Market
Healthcare Services
Global Offsite Medical Case Management Market
Healthcare Services
Medical Second Opinion Market