
 Global Healthcare Virtual Assistants Market | 2026-2036
Global Healthcare Virtual Assistants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Virtual Assistants Market Foresight
Subscription-based access to natural language processing engines is shifting how healthcare virtual assistants reach clinical buyers. Nuance Communications leverages deep integration with electronic health record workflows to anchor its position in medical documentation. Microsoft competes through Azure-hosted AI services that extend cloud infrastructure into hospital IT environments. Suki AI specializes in voice-first physician assistants that reduce administrative burden during patient encounters.
Healthcare virtual assistants are software systems employing speech recognition, natural language understanding, and machine learning inference to interpret clinical queries, automate documentation, and guide patient interactions through conversational interfaces. These systems process audio or text inputs with latency thresholds under 300 milliseconds to maintain dialogue flow during live clinical use. Chatbots and voice-activated assistants currently occupy the largest share of deployed solutions, though AI-powered bots demonstrate the fastest expansion as large language models improve diagnostic reasoning accuracy. Cloud-based deployment dominates new installations, while hybrid architectures gain traction among nursing homes and diagnostic centers managing intermittent connectivity.
The FDA regulates software-as-medical-device classifications for diagnostic chatbots, while HIPAA mandates encryption standards for patient data processed through third-party NLP APIs. The EU AI Act imposes risk-tiered conformity requirements on symptom-checking algorithms deployed in European hospitals. Stakeholders must monitor how divergent validation standards between the FDA and EMA reshape development roadmaps and geographic launch sequencing for clinical-grade conversational AI.
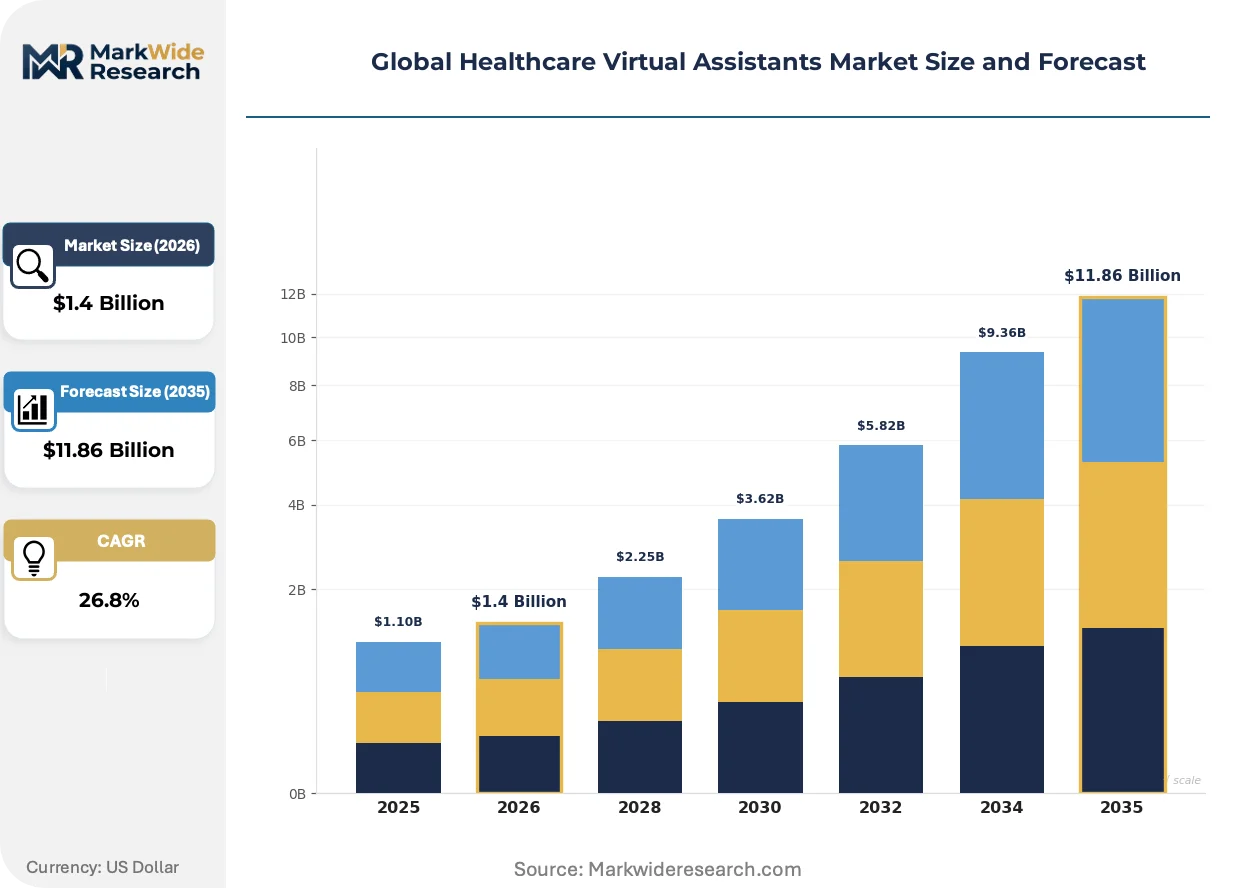
Market Dynamics
Large language model inference latency compression below 300 milliseconds is unifying real-time clinical dialogue with automated documentation workflows, forcing infrastructure redeployment across hospital IT stacks.
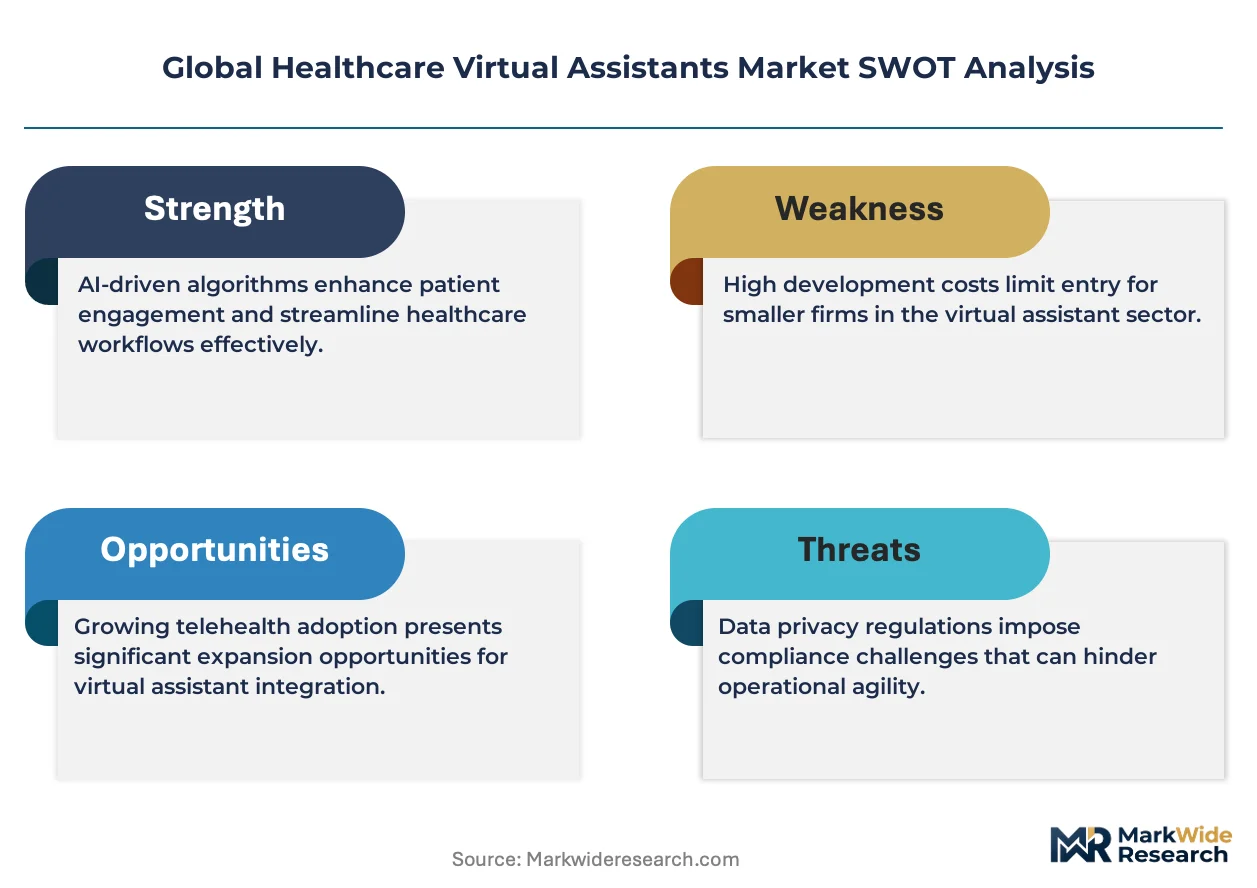
Growth Catalysts
- FDA Software-as-Medical-Device Pathway:The FDA's evolving classification framework for diagnostic chatbots accelerates commercialization timelines for clinical-grade conversational AI in US acute care settings.
- Cloud-Native Architecture Migration:Hospital systems are abandoning on-premise servers for Azure and AWS-hosted NLP engines, reducing capital barriers to voice-first assistant deployment.
- Physician Burnout Reduction Mandates:Administrative documentation consumes over 50% of clinician work hours, creating institutional urgency for ambient listening technologies that automate encounter notes.
Market Restraints
- GPU Compute Cost Volatility:Training and inference for large language models depends on NVIDIA H100 clusters, exposing vendors to semiconductor supply shocks and cloud pricing spikes.
- Interoperability Friction:Legacy electronic health record systems from Epic and Cerner resist API integration, forcing expensive middleware development for data exchange.
- EU AI Act Conformity Burden:Risk-tiered validation requirements for symptom-checking algorithms impose documentation costs that favor well-capitalized incumbents over emerging competitors.
Strategic Opportunities
- Japan's Super-Aging Society:METI's digital health infrastructure investments target nursing home voice assistants for medication adherence and fall detection in the world's oldest population.
- Ambient Clinical Intelligence Convergence:Multimodal AI combining voice biometrics with computer vision during telehealth visits enables continuous patient monitoring without wearable devices.
- Germany's Hospital Future Act:Federal funding for integrated care networks mandates interoperable digital tools, creating procurement windows for EHR-embedded virtual assistants.
Industry Challenges
- Clinical NLP Specialist Scarcity:Healthcare AI engineering requires rare expertise in both medical ontologies and transformer architecture optimization, constraining product development velocity.
- Multi-Jurisdiction Validation Timelines:Divergent FDA and EMA evidence standards for diagnostic chatbots force parallel clinical trials, stretching R&D budgets across geographically fragmented approval pathways.
- Legacy System Integration Complexity:Hospital IT environments running decades-old HL7 v2 interfaces demand costly customization to support real-time NLP API connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Virtual Assistants Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $11.86 Billion |
| CAGR (2026 – 2036) | 26.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chatbots, Voice-Activated Assistants, Text-Based Assistants, AI-Powered Bots, Intelligent Virtual Agents Application: Patient Engagement, Medical Documentation, Appointment Scheduling, Remote Monitoring, Symptom Checking End User: Hospitals, Clinics, Telemedicine Providers, Diagnostic Centers, Nursing Homes Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing |
| Companies Covered | Nuance Communications, Microsoft, IBM Watson Health, Amazon Web Services, Google Health, Suki AI, Sensely, Infermedica, Verint Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Virtual Assistants Market Shifts & Advancements
Foundation model fine-tuning for medical domain specificity is compressing development cycles while regulatory sandboxes in major markets accelerate validation of clinical-grade conversational systems.
Multimodal transformer architectures are unifying speech recognition, clinical entity extraction, and diagnostic suggestion generation into single inference pipelines. Academic medical centers in the United States and Germany are piloting these unified systems for emergency department triage. This compression is eliminating the middleware layer that previously connected separate ASR, NLU, and decision-support modules.
The EU AI Act's risk classification system for health-related AI imposes conformity assessment requirements on symptom-checking chatbots deployed in European hospitals. Manufacturers must maintain post-market surveillance systems and algorithmic change control protocols. High-risk system providers are restructuring quality management systems to satisfy notified body oversight.
Hospital procurement committees are consolidating vendor relationships around EHR-native solutions rather than standalone point products. Health systems in Japan and the United States are prioritizing assistants with pre-built Epic or Cerner connectors over best-of-breed alternatives. This preference shift favors infrastructure-integrated platforms and marginalizes independent software vendors lacking deep workflow embedding.
Global Healthcare Virtual Assistants Market Segmentation
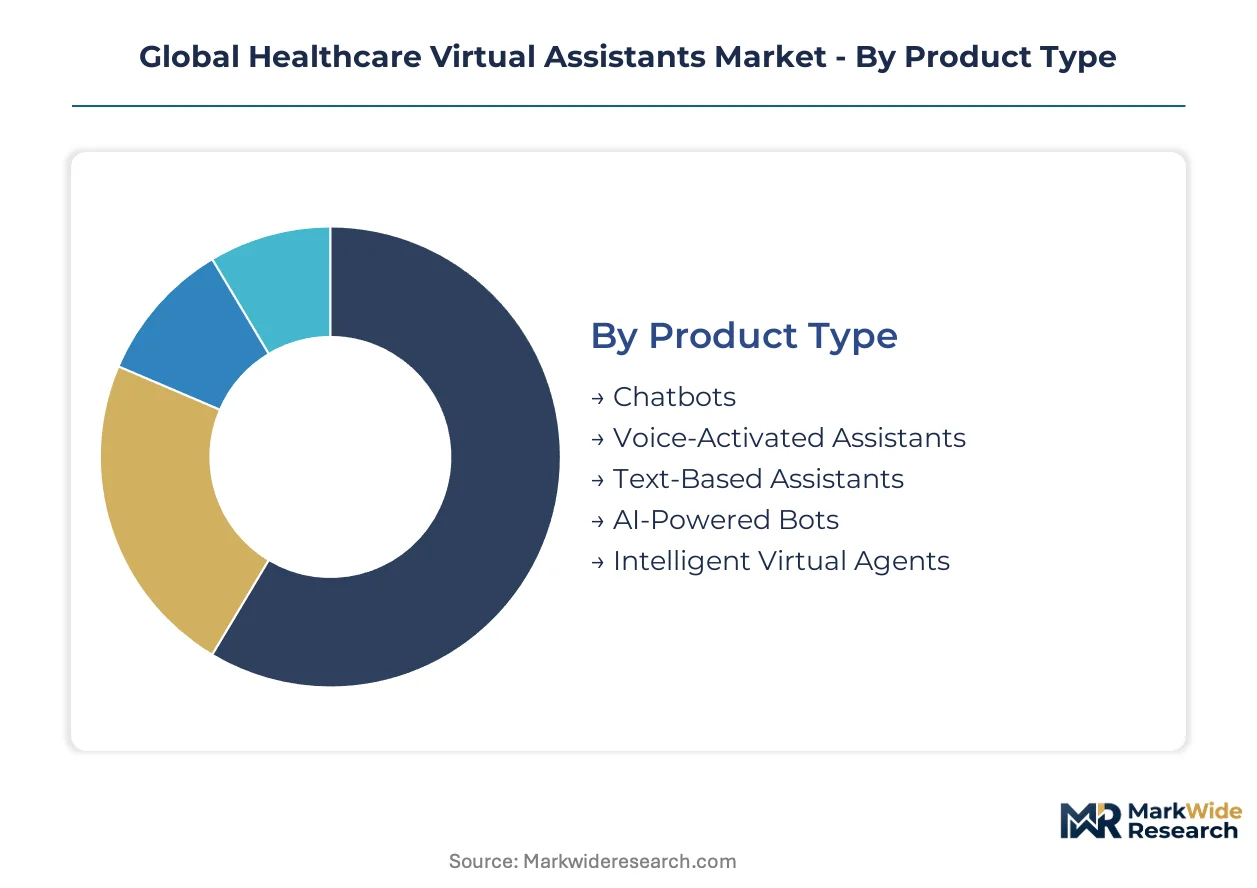
Healthcare virtual assistants fragment across interaction modalities, clinical workflows, and infrastructure architectures. Understanding these divisions reveals where capital concentrates and which deployment models capture institutional procurement budgets.
Product Type:
Chatbots dominate transaction volumes while AI-powered bots command premium pricing and fastest growth trajectories.
- Chatbots:Rule-based conversational interfaces handling appointment scheduling and billing inquiries through scripted dialogue trees. Hospitals in the United States deploy these at scale for patient portal navigation, constrained by limited diagnostic reasoning capabilities that restrict clinical use cases.
- AI-Powered Bots:Large language model-driven systems with medical domain fine-tuning for symptom assessment and care navigation. Germany's university hospitals pilot these for emergency triage, though FDA software-as-medical-device pathways delay US commercialization timelines.
- Voice-Activated Assistants:Speech-first interfaces processing natural language commands for hands-free clinical documentation. Surgical suites and radiology reading rooms in Japan represent concentrated demand.
- Text-Based Assistants:Asynchronous messaging platforms for medication adherence and post-discharge follow-up. Nursing homes favor these for asynchronous communication with limited English-proficiency residents.
- Intelligent Virtual Agents:Multimodal systems integrating voice, text, and visual inputs for complex clinical decision support. Academic medical centers evaluate these for multidisciplinary tumor board coordination.
Today's leader: Chatbots. Tomorrow's challenger: AI-Powered Bots.
Application:
Medical documentation absorbs the largest technology budgets while symptom checking attracts venture capital and regulatory scrutiny.
- Medical Documentation:Ambient listening technologies transcribing patient-physician encounters into structured EHR entries. Physician burnout reduction mandates from hospital administrators in the United States accelerate procurement, with Epic-integrated solutions preferred over standalone alternatives.
- Symptom Checking:Algorithmic assessment of patient-reported complaints with triage recommendations. EU AI Act risk-tiered conformity requirements impose documentation burdens that favor well-capitalized vendors over emerging competitors.
- Patient Engagement:Proactive outreach for preventive care reminders and chronic disease management. Telemedicine providers in Japan deploy these for hypertension monitoring in rural prefectures.
- Appointment Scheduling:Automated calendar management with insurance verification and waitlist optimization. Clinics leverage these to reduce front-desk staffing costs.
- Remote Monitoring:Continuous vital sign interpretation with alert escalation protocols. Diagnostic centers integrate these with wearable data streams for post-acute care surveillance.
Medical documentation captures current spending. Symptom checking faces the steepest expansion trajectory pending regulatory clarity.
End User:
Hospital procurement committees consolidate vendor relationships around EHR-native solutions, marginalizing point products.
- Hospitals:Integrated delivery networks requiring enterprise-grade scalability and HIPAA-compliant data governance. Academic medical centers in Germany pilot multimodal assistants under Hospital Future Act funding mandates.
- Telemedicine Providers:Virtual-first care platforms prioritizing low-latency NLP APIs for real-time consultation support. Cloud-native architectures dominate these deployments.
- Clinics:Smaller-scale implementations focusing on administrative automation rather than clinical decision support. Subscription pricing models reduce capital barriers.
- Diagnostic Centers:Imaging and laboratory facilities leveraging voice assistants for report dictation and critical result communication. HL7 v2 integration complexity constrains adoption.
- Nursing Homes:Long-term care facilities targeting medication adherence and fall detection through voice-activated monitoring. Japan's super-aging society drives METI-funded infrastructure investments.
Hospitals anchor procurement volume. Nursing homes climb fastest as aging demographics reshape care delivery models.
Deployment:
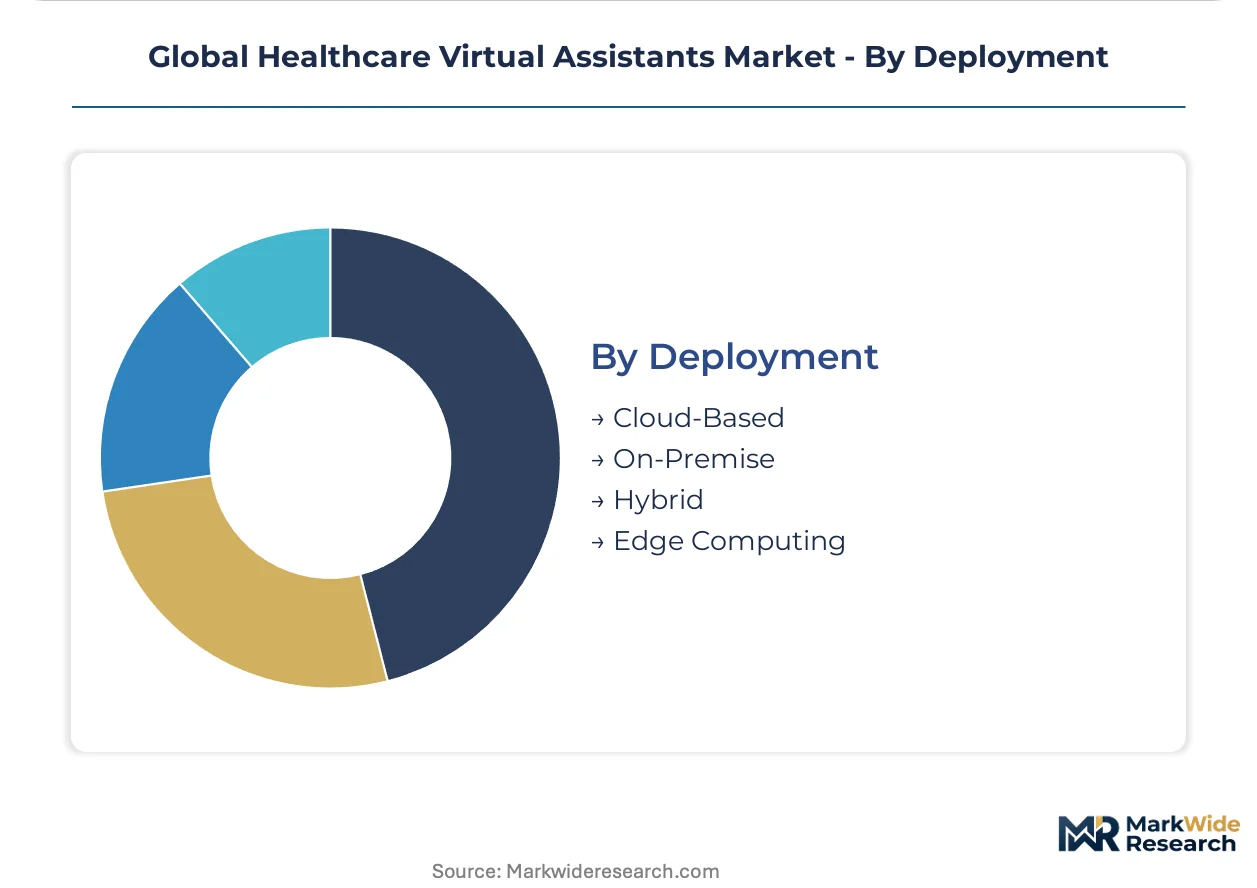
Cloud architectures capture new installations while hybrid models gain traction in connectivity-constrained environments.
- Cloud-Based:Azure and AWS-hosted NLP engines with automatic scaling and API-managed security updates. Hospital systems abandon on-premise servers to reduce IT capital expenditure.
- Hybrid:Local inference for latency-sensitive tasks with cloud fallback for model updates. Nursing homes and diagnostic centers managing intermittent connectivity favor this architecture.
- On-Premise:Air-gapped installations for maximum data sovereignty in military and government healthcare facilities. GPU compute cost volatility strains operational budgets.
- Edge Computing:Distributed processing at point-of-care devices for sub-100-millisecond response requirements. Ambient clinical intelligence pilots explore this for real-time patient monitoring.
Cloud-based deployment leads current adoption. Edge computing emerges as the technical frontier for latency-critical clinical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan deploys voice-first assistants in nursing homes at scale while Germany mandates EHR interoperability through federal hospital modernization programs, revealing how demographic pressure and regulatory design shape divergent national trajectories.
United States
Epic-integrated ambient documentation tools absorb the largest hospital IT budgets as physician burnout reduction becomes an administrative priority. FDA software-as-medical-device pathways accelerate commercialization timelines for diagnostic chatbots, though HIPAA encryption mandates constrain third-party NLP API architectures. Academic medical centers in Boston and the San Francisco Bay Area pilot multimodal assistants for emergency department triage.
Germany
The Hospital Future Act channels federal funding into integrated care networks requiring interoperable digital tools. EU AI Act conformity assessments impose documentation burdens on symptom-checking algorithms deployed in university hospitals. Berlin and Munich anchor development clusters where EHR-embedded virtual assistants undergo clinical validation.
Japan
METI's digital health infrastructure investments target nursing home voice assistants for medication adherence and fall detection. PMDA guidance on AI-enabled medical devices shapes product validation pathways for domestic vendors. The Kanto region around Tokyo concentrates pilot deployments for aging-in-place monitoring systems.
United Kingdom
NHS procurement frameworks prioritize cloud-native assistants with pre-built integration into electronic patient record systems. MHRA consultation on software-as-medical-device classifications creates regulatory uncertainty for diagnostic chatbot developers. London's health tech cluster attracts venture funding for ambient clinical intelligence pilots.
India
Telemedicine platforms drive demand for low-latency NLP APIs supporting multilingual patient interactions. CDSCO draft guidance on AI-based medical devices remains under consultation, slowing commercialization for domestic startups. Bangalore and Hyderabad host development centers fine-tuning large language models for clinical Hindi and regional language deployment.
Global Healthcare Virtual Assistants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with EHR-native platforms commanding premium pricing against standalone point products. The vendor base concentrates around three tiers: cloud infrastructure providers extending healthcare verticals, voice-first documentation specialists, and diagnostic reasoning engine developers. M&A activity targets ambient clinical intelligence capabilities, while strategic partnerships with Epic and Cerner determine hospital procurement access.
Within the cloud infrastructure tier, Microsoft and Amazon Web Services occupy positions anchoring hospital IT migration to Azure and AWS-hosted NLP engines. Nuance Communications exemplifies the voice-first documentation archetype through deep EHR workflow embedding. Suki AI represents the emerging specialist model targeting hands-free physician assistance during patient encounters.
| Leading Market Players |
|---|
| Nuance Communications |
| Microsoft |
| IBM Watson Health |
| Amazon Web Services |
| Google Health |
| Suki AI |
| Sensely |
| Infermedica |
| Verint Systems |
| Others |
Supply & Pricing Matrix
Hospital procurement committees consolidating vendor relationships around EHR-native solutions are forcing supply chain reconfiguration toward Epic and Cerner-integrated platforms, compressing margins for standalone point products while premium pricing accrues to workflow-embedded alternatives.
Pricing Analysis
Capacity additions in cloud infrastructure are reshaping price floors for NLP engine access as Microsoft Azure and AWS expand healthcare vertical offerings. Three-tier pricing structure across premium, standard, and economy levels segments by integration depth, with EHR-native commands commanding brand premiums over API-only alternatives. Pricing pressure stems from GPU compute cost volatility in NVIDIA H100 clusters, squeezing inference margins for mid-tier vendors. Telemedicine providers exhibit highest price sensitivity, while academic medical centers prioritize certification tier over unit cost.
Supply Chain Analysis
Direct-to-hospital channels handle hyperscale integrated delivery network demand, bypassing traditional health IT distributors. Component supply concentrates in Taiwan for semiconductor fabrication, South Korea for memory modules, and the United States for transformer architecture R&D. Raw material dependencies include NVIDIA GPU clusters, cloud storage infrastructure, and medical ontology datasets. Single-source vulnerability in H100 supply exposes vendors to semiconductor allocation shocks. Distribution runs through EHR vendor marketplaces and direct enterprise sales teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare virtual assistants constitute a late-cycle quality story as hospital procurement shifts toward FDA-validated, EHR-embedded platforms with ambient clinical intelligence capabilities, marginalizing best-of-breed alternatives lacking deep workflow integration.
For Market Incumbents: Lock in EHR-native positioning through exclusive Epic and Cerner partnership tiers before emerging voice-first specialists achieve comparable workflow embedding. Prioritize backward integration into medical ontology curation to reduce dependency on third-party clinical NLP datasets. Defensive consolidation around ambient listening patents will neutralize Suki AI and Nuance Communications expansion into diagnostic reasoning modules. For New Entrants and Emerging Players: Rural nursing homes in Japan's super-aging prefectures represent an underserved buyer archetype with METI-funded procurement windows and lower EHR integration barriers than acute care settings. Target diagnostic centers with HL7 v2 middleware simplification as the most penetrable segment, leveraging hybrid deployment architectures for connectivity-constrained environments. Go-to-market through regional health system GPOs rather than direct hospital sales. For Investors and Strategic Acquirers: Asymmetric upside sits with clinical NLP engineering teams possessing both medical informatics expertise and transformer optimization capabilities, a rare combination constraining product development velocity across the sector. Five-to-ten year viability favors platforms with FDA software-as-medical-device pre-submission pathways already initiated. Monitor EU AI Act notified body designation timelines as the critical inflection signal for European market access economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Submission | Accelerates commercialization timelines for diagnostic chatbots in US acute care. |
| Epic/Cerner Partnership Tier | Secures procurement committee preference over standalone point products. |
| Medical Ontology Curation Investment | Reduces third-party dependency for clinical entity extraction accuracy. |
| Hybrid Deployment Architecture | Captures nursing home and diagnostic center demand with intermittent connectivity. |
| EU AI Act Conformity Pathway | Unlocks university hospital procurement under risk-tiered validation requirements. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down cloud infrastructure capex tracking forms the analytical core of this study. Primary interviews with hospital purchasing committee chairs, biomedical informatics officers, GPO contracts managers, and clinical NLP engineering leads were validated against secondary sources including FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EHR vendor partnership disclosures. Triangulation across these inputs ensures segment-level precision without reliance on single-source estimates.
Historical trendline analysis of EHR integration spend and ambient clinical intelligence pilot deployments established baseline growth patterns across the projection horizon. The forecast framework segments by interaction modality, clinical workflow application, end-user institution type, and deployment architecture, with CAGRs derived from penetration rate modeling against physician burnout reduction mandate timelines. Inference latency compression trajectories and regulatory sandbox expansion rates served as healthcare-specific forecast inputs.
Underlying measurement precision varies by segment; medical documentation applications carry tighter precision than emerging multimodal diagnostic agents due to established procurement data availability. Forecasts reflect assumptions regarding FDA guidance finalization timelines and EU AI Act implementation sequencing, with periodic stress-testing of base assumptions recommended given regulatory uncertainty.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
AI in Telemedicine Market
Telemedicine
Asia-Pacific Telemedicine Market
Telemedicine
United States Telehealth Pre-Natal Services Market
Telemedicine
Telepathology Service Market
Telemedicine
India Telehealth Services Market
Telemedicine
North America Telemedicine Market
Telemedicine
Telemedicine Equipment Market
Telemedicine
ASEAN Telehealth Services Market
Telemedicine
Global Virtual Care Market
Telemedicine
Tele-Care Market
Telemedicine
US Virtual Care Market
Telemedicine
Global Tele Intensive Care Unit Market
Telemedicine
Remote Healthcare Market
Telemedicine
Telehealth Services Market
Telemedicine
Stroke Telemedicine Services Market
Telemedicine
Europe Telemedicine Market