
 Veterinary Palliative Care Management Market | 2026-2036
Veterinary Palliative Care Management Market Size, Share, and Industry Trends Forecast 2026-2036
Veterinary Palliative Care Management Market Analytics
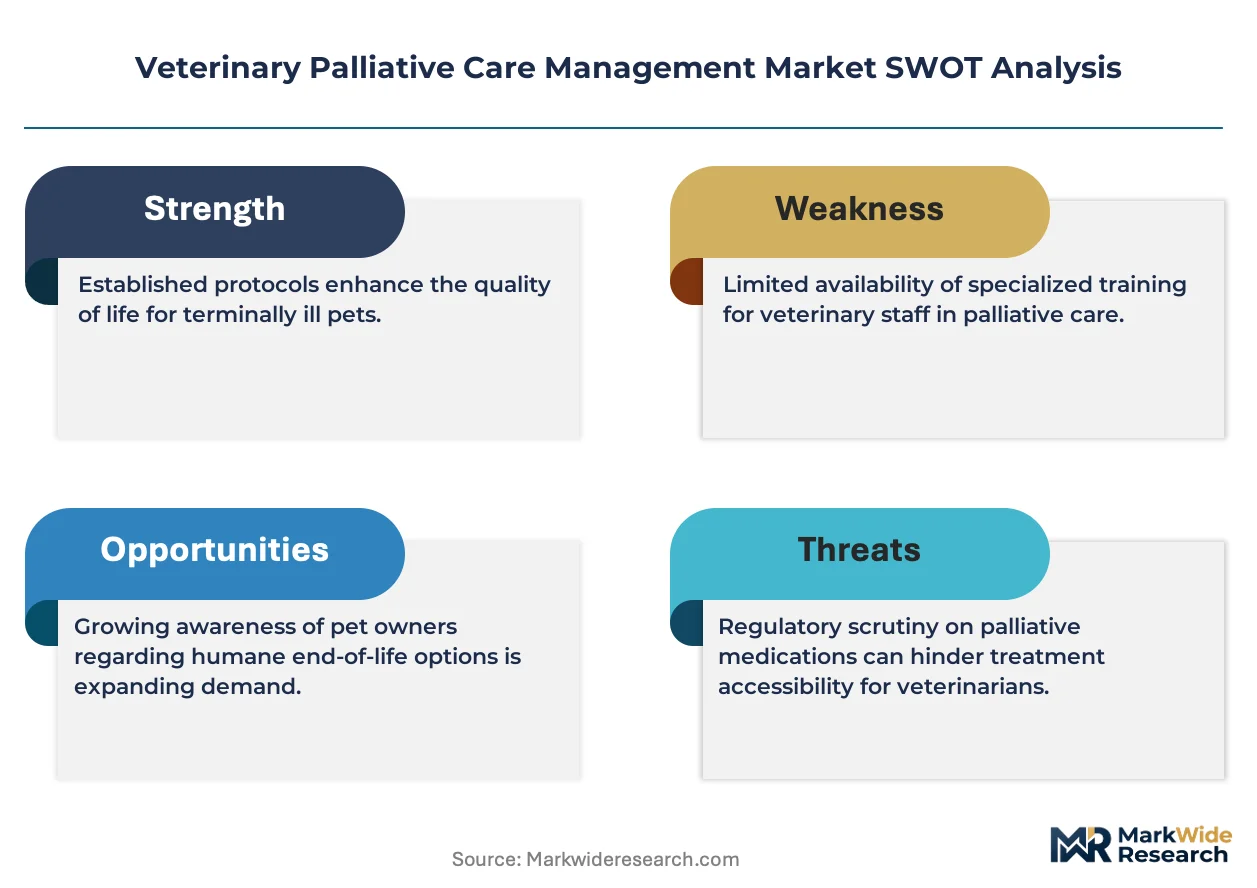
The FDA's expanded veterinary drug approval pathways is recalibrating the cost-of-entry calculus for pharmaceutical entrants into animal hospice therapeutics. Merck & Co., Inc. leverages its human-animal health crossover infrastructure to sustain development pipelines for analgesic formulations. Zoetis Inc. anchors its competitive stance through direct-to-veterinarian distribution networks. Vetoquinol S.A. differentiates via European manufacturing scale and regulatory familiarity across multiple jurisdictions.
Veterinary palliative care management encompasses pharmacological, nutritional, and comfort-oriented interventions designed to maintain quality of life in animals with terminal or chronic progressive conditions, typically administered through injectable, oral, or transdermal delivery systems calibrated to species-specific metabolism and pain thresholds. The field serves companion animal owners seeking to extend functional life without curative treatment. Pain management drugs currently occupy the largest product-type revenue pool, while home care providers represent the fastest-growing end-user channel as owners seek to minimize clinic-induced stress in terminal patients. Transdermal delivery modes are gaining structural traction for feline populations where oral administration compliance remains problematic.
The FDA Center for Veterinary Medicine and the EPA jointly govern pharmaceutical residues and environmental safety of disposed analgesics, while state veterinary medical boards regulate scope-of-practice for in-home euthanasia and hospice services. These layered frameworks elevate compliance costs but simultaneously create defensible positions for accredited service networks and audited manufacturing facilities. Stakeholders must monitor evolving state-level telemedicine permissions for hospice consultations, as remote diagnostic authority will reshape geographic service accessibility and competitive density in suburban markets.
Market Dynamics
Pet insurance penetration for end-of-life services in the United States is restructuring payment flows and compressing out-of-pocket cost sensitivity, enabling specialty animal hospitals to scale palliative protocols without owner price resistance.
Growth Catalysts
- FDA expanded veterinary drug approval pathways:The Center for Veterinary Medicine's streamlined IND-like processes for analgesic therapies are reducing time-to-market for novel formulations targeting species-specific metabolism.
- Home care provider channel expansion:Terminal companion animal owners are migrating from clinic-based administration to in-home services, minimizing stress-induced physiological deterioration in feline and canine patients.
- Transdermal delivery technology maturation:Feline populations with oral administration compliance failures are driving formulation innovation in patch-based analgesic systems calibrated to dermal absorption rates.
Market Restraints
- Active pharmaceutical ingredient concentration:North American and European manufacturing of veterinary-specific opioid alternatives remains concentrated among three contract development organizations, creating supply vulnerability.
- EPA pharmaceutical residue disposal mandates:Environmental safety requirements for discarded analgesics impose specialized waste-handling infrastructure costs on home care providers operating outside institutional settings.
- State veterinary medical board scope limitations:Inconsistent permissions for telemedicine hospice consultations across jurisdictions fragment service scalability in suburban markets.
Strategic Opportunities
- Underpenetrated Japanese companion animal market:METI's regulatory harmonization initiatives and aging pet demographics create entry pathways for palliative service networks in Tokyo and Osaka metropolitan clusters.
- Outcome-based reimbursement pilots:Private pet insurers in Germany and Switzerland are testing quality-of-life metric tied coverage models that reward extended functional life over procedure volume.
- Nutraceutical-palliative convergence:Formulation of condition-specific nutritional interventions with pain management protocols addresses cachexia in terminal oncology cases.
Industry Challenges
- Veterinary hospice certification timeline:The International Association for Animal Hospice and Palliative Care credentialing process requires 240 supervised clinical hours, constraining workforce expansion.
- Telemedicine-physical examination integration:Remote diagnostic authority limitations complicate pain assessment accuracy in non-verbal patients, requiring hybrid service model investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Veterinary Palliative Care Management Market |
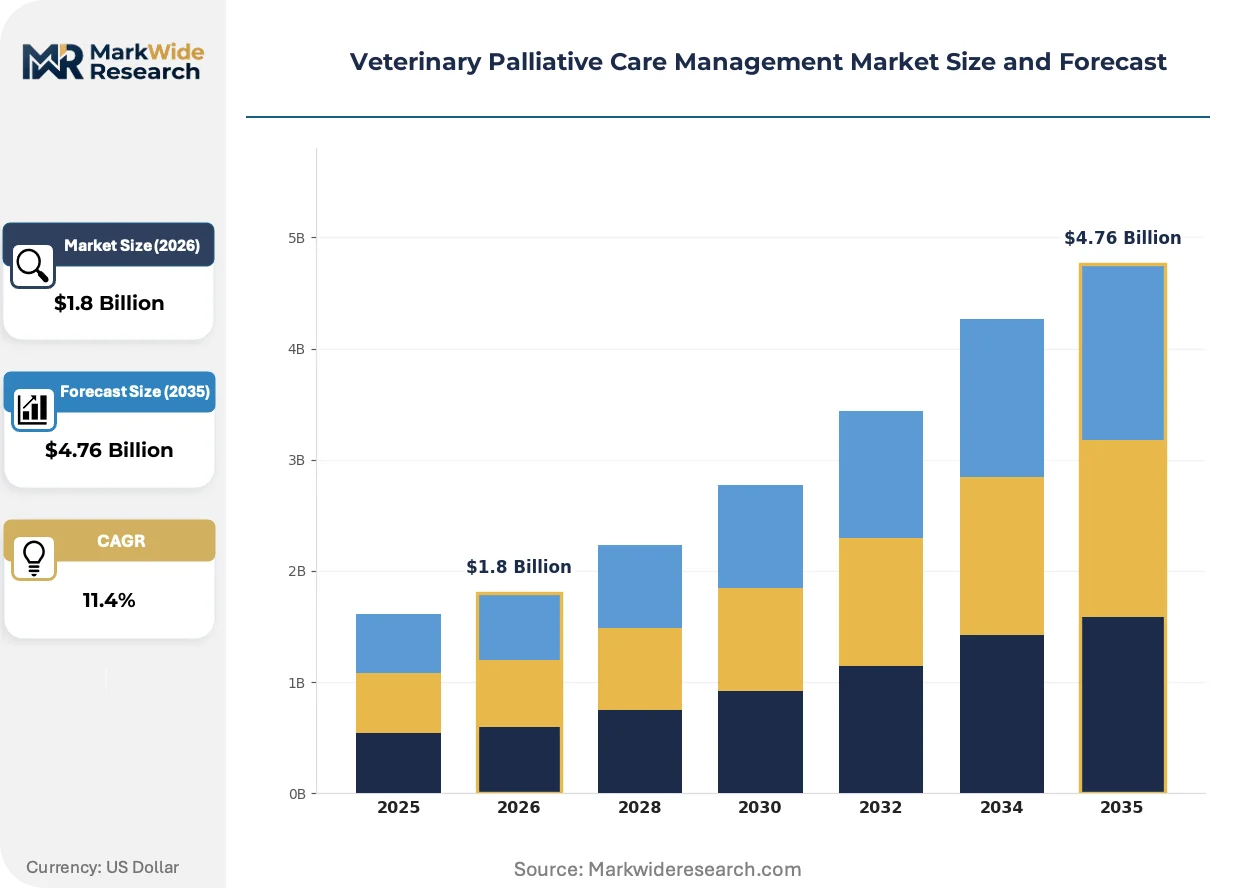
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pain Management Drugs, Nutritional Supplements, Comfort Devices, Therapeutic Equipment Delivery Mode: Injectable, Oral, Topical, Transdermal End User: Veterinarians, Animal Clinics, Animal Hospitals, Home Care Providers Service Type: Consultation Services, Hospice Care, Facility Services, Support Groups |
| Companies Covered | Merck & Co., Inc., Vetoquinol S.A., Lap of Love Veterinary Hospice, PetHospice, Paws Into Grace, Zoetis Inc., Bayer AG, Caring Pathways, Elanco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Veterinary Palliative Care Management Market Evolving Landscape
Delivery system miniaturization and species-specific formulation science are displacing one-size-fits-all human drug repurposing, while regulatory sandboxes for novel analgesic classes compress development cycles.
Transdermal fentanyl matrices calibrated to feline dermal thickness and absorption kinetics are expanding into specialty veterinary pharmacy compounding. Small-animal oncology practices in the United States and United Kingdom are adopting these systems at accelerating rates for chronic pain maintenance. The technology is expanding into home care protocols by eliminating parenteral administration requirements for non-compliant patients.
The FDA Center for Veterinary Medicine's expanded conditional approval pathway for minor use and minor species drugs is compressing analgesic development timelines for niche indications. Pharmaceutical sponsors now pursue veterinary-specific formulations without requiring full human-equivalent safety dossiers. Injectable long-acting NSAID categories for canine osteoarthritis management are benefiting most, with sponsors targeting conditional approval submissions for 2025-2026 review cycles.
Companion animal owners are consolidating purchasing decisions around accredited hospice networks that bundle pharmaceutical, nutritional, and euthanasia services under single continuity-of-care contracts. Independent veterinary clinics without palliative certification are losing terminal case referrals to specialty hospital systems. This consolidation is most visible in United States metropolitan statistical areas with pet insurance penetration exceeding 3% of insured households.
Veterinary Palliative Care Management Market Segmentation
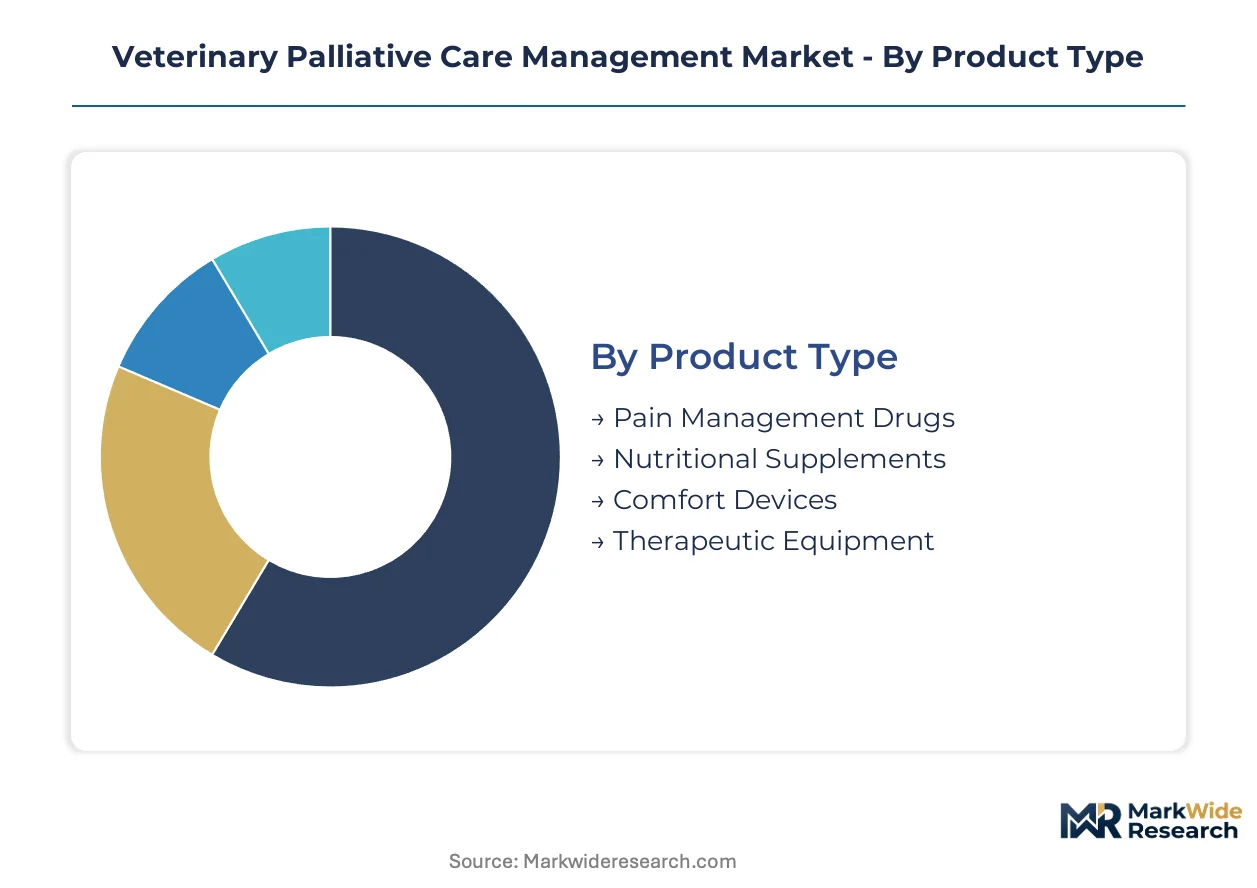
Segmentation in veterinary palliative care reveals how treatment complexity, patient compliance challenges, and care setting preferences fragment purchasing authority across distinct stakeholder groups. Understanding these divides enables targeted formulation development and distribution investments.
Product Type:
Cost tier differentiation separates commodity nutritional interventions from patented analgesic formulations requiring regulatory investment.
- Pain Management Drugs:Opioid alternatives and NSAIDs calibrated to species-specific metabolism dominate current prescribing patterns. Specialty animal hospitals in the United States drive demand concentration as pet insurance penetration for end-of-life services deepens, though API manufacturing concentration among limited contract development organizations creates supply vulnerability.
- Nutritional Supplements:Condition-specific formulations addressing cachexia in terminal oncology cases combine with pain protocols for integrated care. The nutraceutical-palliative convergence is gaining traction in German and Swiss outcome-based reimbursement pilots testing quality-of-life metric tied coverage models.
- Comfort Devices:Pressure-relief bedding and mobility assistance equipment support functional life extension in home settings.
- Therapeutic Equipment:Laser therapy and thermal regulation systems require clinical infrastructure investment limiting deployment to accredited facilities.
Volume sits with Pain Management Drugs; growth tilts toward Nutritional Supplements.
Delivery Mode:
Patient compliance failures in non-verbal populations dictate formulation innovation priorities across species.
- Transdermal:Fentanyl matrices calibrated to feline dermal thickness and absorption kinetics eliminate parenteral administration requirements. Small-animal oncology practices in the United States and United Kingdom are adopting these systems at accelerating rates for chronic pain maintenance in non-compliant patients.
- Oral:Palatability-enhanced formulations remain the default for canine populations with higher compliance rates than feline counterparts.
- Injectable:Long-acting NSAID categories for canine osteoarthritis management benefit from FDA conditional approval pathway compression.
- Topical:Localized analgesic gels address wound management and surface pain with minimal systemic absorption concerns.
Oral formulations retain volume leadership; transdermal systems are climbing the fastest as feline-specific innovation accelerates.
End User:
Service scalability constraints fragment purchasing between institutional settings and distributed home care networks.
- Home Care Providers:In-home administration minimizes stress-induced physiological deterioration in terminal patients. EPA pharmaceutical residue disposal mandates impose specialized waste-handling infrastructure costs on providers operating outside institutional settings.
- Animal Hospitals:Specialty hospital systems consolidate terminal case referrals through bundled pharmaceutical, nutritional, and euthanasia service contracts.
- Veterinarians:Independent practitioners without palliative certification face referral leakage to accredited networks.
- Animal Clinics:General practice facilities serve as initial diagnostic and referral gatekeepers without full hospice service capability.
Animal Hospitals capture current volume; Home Care Providers show the steepest expansion trajectory as owners seek clinic-stress reduction.
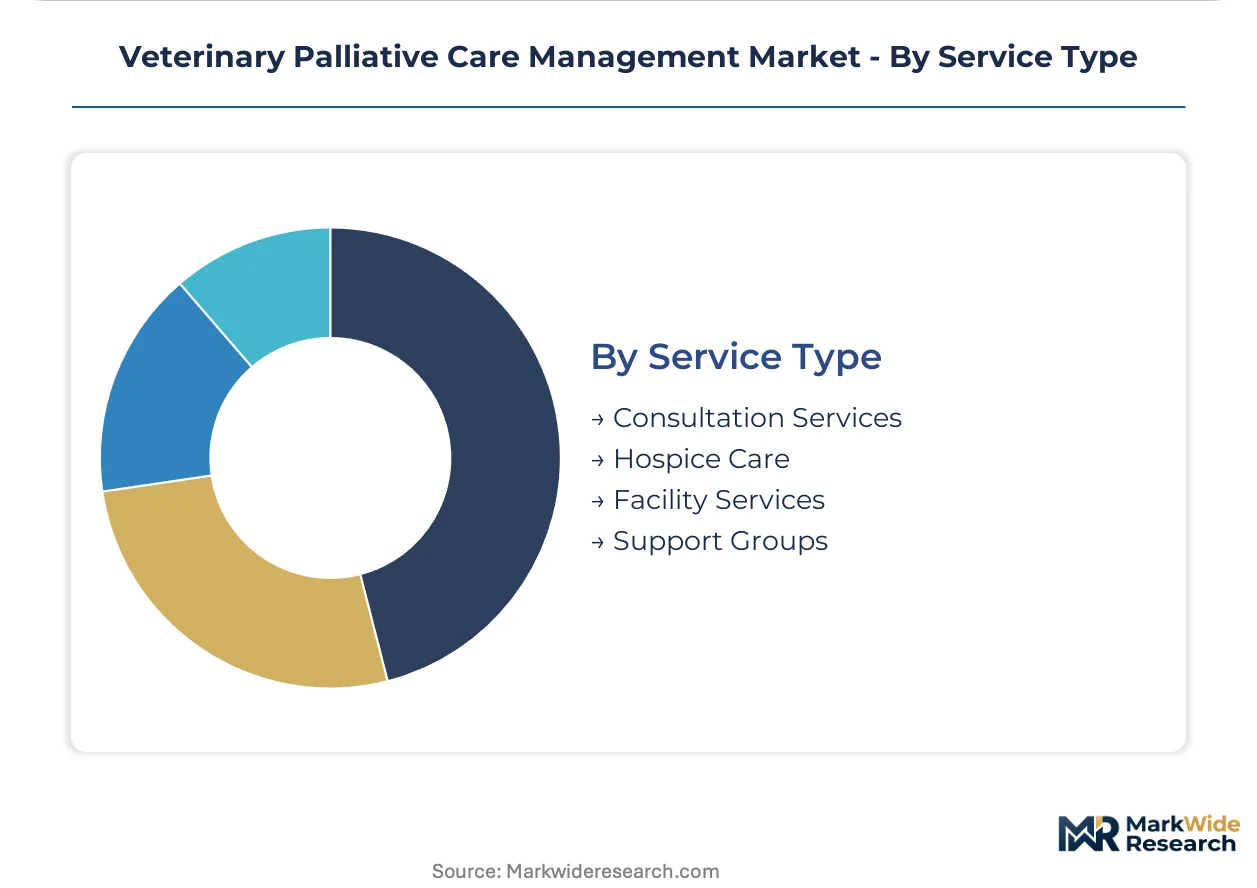
Service Type:
Credentialing requirements and reimbursement structure shape competitive density across service delivery models.
- Hospice Care:Continuous symptom management and end-of-life support requires 240 supervised clinical hours for International Association for Animal Hospice and Palliative Care certification, constraining workforce expansion.
- Consultation Services:Telemedicine permissions for remote hospice consultations vary across state veterinary medical boards, fragmenting geographic accessibility in suburban markets.
- Facility Services:Dedicated palliative wards within specialty hospitals enable intensive monitoring for unstable patients.
- Support Groups:Owner counseling and bereavement services complete continuity-of-care contracts for accredited networks.
Hospice Care anchors revenue concentration; Consultation Services are gaining share fastest as telemedicine regulatory clarity evolves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones for veterinary pharmaceutical manufacturing concentrate capacity in jurisdictions with streamlined regulatory pathways. Tax incentives for animal health R&D in the United States and Japan accelerate facility placement decisions. These zones reduce time-to-market for analgesic formulations serving terminal companion animal populations.
United States
Pet insurance penetration for end-of-life services exceeds 3% of insured households in major metropolitan statistical areas, restructuring payment flows for specialty animal hospitals. The FDA Center for Veterinary Medicine's expanded conditional approval pathway compresses development timelines for novel analgesic formulations. Small-animal oncology practices in Greater Boston and the Pacific Northwest adopt transdermal fentanyl matrices at accelerating rates for feline chronic pain maintenance.
Germany
Private pet insurers pilot quality-of-life metric tied coverage models that reward extended functional life over procedure volume. The country's national pharmaceutical regulator maintains stringent batch-release requirements for veterinary opioid alternatives. Veterinary service networks in Bavaria and North Rhine-Westphalia consolidate terminal case referrals through bundled pharmaceutical, nutritional, and euthanasia contracts.
Japan
Aging pet demographics in Tokyo and Osaka metropolitan clusters create demand concentration for palliative service networks. METI's regulatory harmonization initiatives reduce entry barriers for foreign pharmaceutical sponsors seeking veterinary drug approvals. Specialty animal hospitals in the Kanto region expand hospice ward capacity to accommodate rising terminal oncology caseloads.
United Kingdom
Small-animal oncology practices in London and Southeast England integrate transdermal delivery systems into home care protocols. The Veterinary Medicines Directorate maintains pharmacovigilance requirements for analgesic formulations administered in non-clinical settings. Accredited hospice networks in the Midlands consolidate independent practitioner referrals through certification-driven competitive differentiation.
Switzerland
Outcome-based reimbursement pilots test quality-of-life metric tied coverage models for terminal companion animal cases. Swissmedic's regulatory framework supports accelerated review pathways for species-specific analgesic formulations. Veterinary pharmaceutical manufacturing clusters in Basel-Stadt leverage cross-border distribution infrastructure to serve German and French metropolitan markets.
Veterinary Palliative Care Management Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation development and service delivery vectors. The market structure tilts toward consolidation as accredited hospice networks capture terminal case referrals from uncertified independent practitioners. Three archetypes dominate: human-animal health crossover pharmaceutical developers, European manufacturing-scale specialists, and direct-to-veterinarian distribution network operators. Competitive moves center on M&A activity targeting home care provider networks and strategic partnerships bundling pharmaceutical, nutritional, and euthanasia services.
Within the pharmaceutical developer tier, Merck & Co., Inc. and Zoetis Inc. occupy positions shaped by human-animal health crossover infrastructure. Vetoquinol S.A. represents the European manufacturing-scale archetype with multi-jurisdictional regulatory familiarity. These three entities anchor competitive dynamics as service networks and drug developers converge around integrated end-of-life care contracts.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Vetoquinol S.A. |
| Lap of Love Veterinary Hospice |
| PetHospice |
| Paws Into Grace |
| Zoetis Inc. |
| Bayer AG |
| Caring Pathways |
| Elanco |
| Others |
Value Network & Pricing Analysis
EPA pharmaceutical residue disposal mandates gate qualified supply and premium-tier pricing access for home care providers, as specialized waste-handling infrastructure costs separate accredited networks from uncertified competitors. Veterinary-specific opioid alternatives command price premiums calibrated to species-specific metabolism requirements, while generic nutritional interventions compete on volume scale.
Pricing Analysis
Short lead-time premiums apply to transdermal fentanyl matrices for feline populations, with spot inventory discounts for oral NSAID formulations nearing patent expiration. Three-tier pricing structure across premium, standard, and economy levels separates patented analgesic formulations from compounded alternatives and commodity supplements. Cost compression in the nutritional tier intensifies as German and Swiss insurers pilot outcome-based reimbursement models. Independent veterinary clinics exhibit highest price sensitivity; specialty animal hospital systems with pet insurance contracts demonstrate lowest elasticity.
Supply Chain Analysis
Domestic-content requirements in Japan's METI regulatory harmonization initiatives reshape sourcing toward local manufacturing partners for veterinary drug sponsors entering Tokyo and Osaka markets. Active pharmaceutical ingredient production concentrates in the United States, Germany, and Switzerland, drawing from concentrated contract development organization capacity. Supply chain vulnerability rests on single-source dependencies for fentanyl precursor chemicals. Distribution runs through direct-to-veterinarian networks anchored by Zoetis and Merck infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veterinary hospice certification bottlenecks constrain workforce expansion, propping pricing power for accredited service networks as uncertified independents face referral leakage.
For Market Incumbents: Cement market position through backward integration into transdermal manufacturing capacity and exclusive distribution agreements with specialty animal hospital systems. Acquire home care provider networks in United States metropolitan statistical areas with pet insurance penetration exceeding 3% to capture terminal case referral flows from independent practitioners lacking palliative certification. For New Entrants and Emerging Players: Enter via the underpenetrated Japanese companion animal market, leveraging METI regulatory harmonization to bypass lengthy approval timelines. Target Tokyo and Osaka metropolitan clusters with bundled pharmaceutical and home care service models. Pursue telemedicine-enabled consultation services as the most penetrable segment given evolving state-level permissions in suburban United States markets. For Investors and Strategic Acquirers: FDA conditional approval pathway submissions for injectable long-acting NSAIDs are the leading indicator that development timeline compression will reshape competitive positioning. Focus acquisition screening on European manufacturing-scale specialists with multi-jurisdictional regulatory familiarity. Monitor telemedicine regulatory clarity across United States state veterinary medical boards as the primary inflection signal for service scalability investments.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA conditional approval compresses analgesic development timelines for niche indications. |
| Backward Integration | In-house production of transdermal matrices secures supply for feline-specific formulations. |
| Acquisition of Specialist Firm | Home care provider networks extend geographic reach for accredited hospice services. |
| Strategic Partnership | Pet insurer collaborations bundle pharmaceutical and euthanasia coverage contracts. |
| Geographic Expansion | Tokyo and Osaka entry leverages METI harmonization for veterinary drug approvals. |
Research Methodology
Multi-period observation of FDA approval timelines, pet insurance penetration rates, and hospice certification completions anchored the trend analysis, supplemented by interviews with veterinary pharmaceutical development executives, regulatory affairs leads at animal health sponsors, specialty animal hospital procurement managers, and home care provider network operators. Secondary validation drew from FDA Center for Veterinary Medicine filings, EPA pharmaceutical residue guidelines, state veterinary medical board scope-of-practice regulations, and pet insurance coverage disclosures. Bottom-up service provider capacity modeling and top-down pharmaceutical revenue estimation enabled triangulation.
Input-output matrices structured demand projections across product type, delivery mode, end user, and service type dimensions throughout the forecast period. CAGRs derived from segment-level growth rate convergence analysis incorporating FDA approval velocity, telemedicine regulatory evolution, and pet insurance reimbursement expansion as veterinary-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under state telemedicine permission fragmentation and API supply disruption scenarios. Forecasts reflect assumptions regarding regulatory pathway efficiency and certification workforce expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Veterinary Medicine
US Veterinarians Market
Veterinary Medicine
Veterinary Biologics Market
Veterinary Medicine
Veterinary Anesthesia Machines Market
Veterinary Medicine
South Africa Veterinary Medicine Market
Veterinary Medicine
Global Brucellosis Vaccines Market
Veterinary Medicine
Veterinary Anti-Infectives Market
Veterinary Medicine
Veterinary Anesthesia Market
Veterinary Medicine
Over-The-Counter (OTC) Veterinary Drugs Market
Veterinary Medicine
Animal Drugs Market
Veterinary Medicine
Veterinary Wellness Market
Veterinary Medicine
US Veterinary Diagnostics Market
Veterinary Medicine
Veterinary Dental Elevators Market
Veterinary Medicine
US Veterinary Orthopedic Medicine Market
Veterinary Medicine
Global Companion Animal Pharmaceuticals Market
Veterinary Medicine
Global Veterinary/Animal Vaccines Market
Veterinary Medicine
Global Veterinary Eye Care Market