
 Medical Second Opinion Market | 2026-2036
Medical Second Opinion Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Second Opinion Market Analysis
Subscription-based telehealth financing is reshaping competitive entry in medical second opinions, lowering upfront infrastructure costs for new platforms. Teladoc Health leverages its enterprise licensing model to sustain recurring revenue from employer and payer contracts. Cleveland Clinic anchors its position through exclusive hospital network partnerships that limit competitor access to specialist labor pools. DoctorSpring competes on price-transparent, asynchronous consultations that appeal to uninsured and high-deductible patient segments.
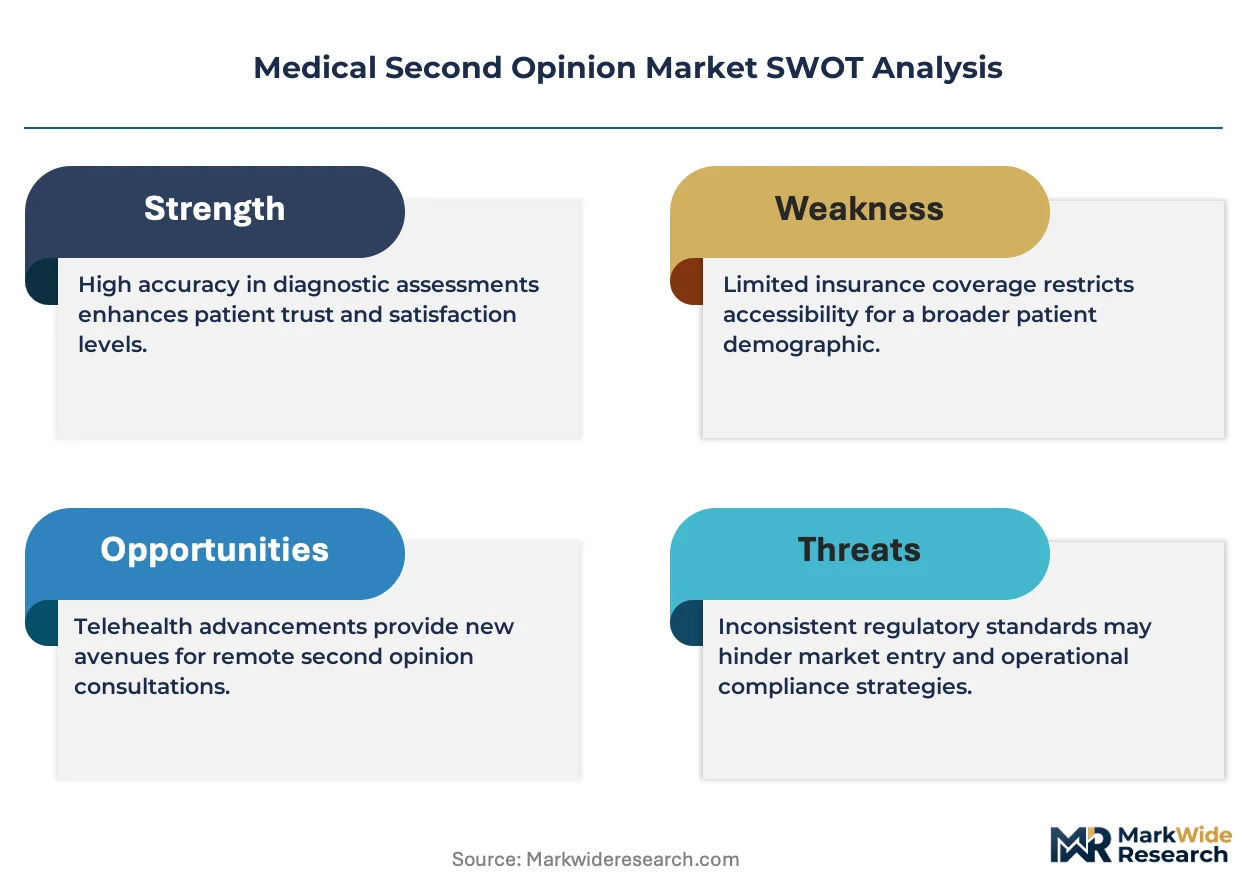
A medical second opinion constitutes an independent clinical review of a patient's diagnosis, treatment plan, or surgical recommendation by a qualified specialist unaffiliated with the original provider, typically delivered through synchronous video consultation, asynchronous image and record review, or AI-augmented preliminary analysis. Virtual consultation services dominate transaction volume due to lower per-case operational costs and faster turnaround times, while oncology specialty reviews command premium pricing given the complexity of staging protocols and the stakes of treatment selection. Telemedicine platforms and EHR integration together form the fastest-growing technology cluster, as health systems prioritize seamless data exchange to reduce administrative friction and duplicate testing.
FDA oversight of AI diagnostic algorithms and HIPAA security requirements for telehealth data transmission together elevate compliance costs for platform operators, creating regulatory moats that favor established providers with dedicated legal and clinical affairs teams. The EU AI Act's risk-classification framework for medical decision-support tools will force non-European platforms to reengineer algorithmic transparency features if they serve European patients. Stakeholders must monitor whether CMS expands reimbursement parity between virtual and in-person second opinions, as this policy shift would immediately restructure revenue models across the sector.
Market Dynamics
Insurance cost-containment protocols are restructuring demand patterns for medical second opinion services, as payers mandate pre-authorization reviews for high-cost procedures and steer patients toward virtual consultation networks to reduce unnecessary surgical utilization.
Growth Catalysts
- HIPAA Interoperability Mandates:The 21st Century Cures Act enforcement is accelerating platform certification requirements, forcing health systems to adopt standardized APIs that reduce friction in medical record exchange for remote consultations.
- Employer-Sponsored Plan Design:Large self-insured employers in the United States are embedding second opinion benefits as core plan features, creating guaranteed volume commitments for telehealth platforms serving oncology and orthopedic specialties.
- AI-Augmented Triage Tools:Machine learning algorithms for preliminary case stratification are compressing specialist review timelines from weeks to days, improving patient adherence to recommended pathways.
Market Restraints
- Specialist Labor Pool Concentration:Top-tier academic medical centers in Boston, Cleveland, and Houston control access to subspecialty expertise, limiting platform scalability beyond narrow clinical domains.
- State-Level Licensure Fragmentation:The patchwork of medical board requirements across 50 US jurisdictions creates compliance overhead that restricts cross-border consultation volume.
- Reimbursement Asymmetry:CMS maintains payment gaps between virtual and in-person second opinions, suppressing provider participation in asynchronous review models.
Strategic Opportunities
- Medicare Advantage Network Integration:MA plans represent the fastest-growing payer segment for mandatory second opinion protocols, offering platforms direct contracting pathways with minimal broker intermediation.
- EU AI Act Compliance Services:European risk-classification requirements for diagnostic decision-support tools create advisory revenue streams for platforms that reengineer algorithmic transparency features.
- High-Deductible Consumer Segment:Price-transparent cash-pay models for uninsured and underinsured patients in Texas and Florida markets remain underserved by incumbent hospital-affiliated programs.
Industry Challenges
- Credentialing Timeline Compression:Platform onboarding of new specialist consultants requires 90-120 day primary source verification cycles that constrain supply elasticity during demand surges.
- EHR Integration Complexity:Legacy health system IT architectures in community hospital networks resist seamless data exchange, forcing manual record retrieval that degrades patient experience metrics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Second Opinion Market |
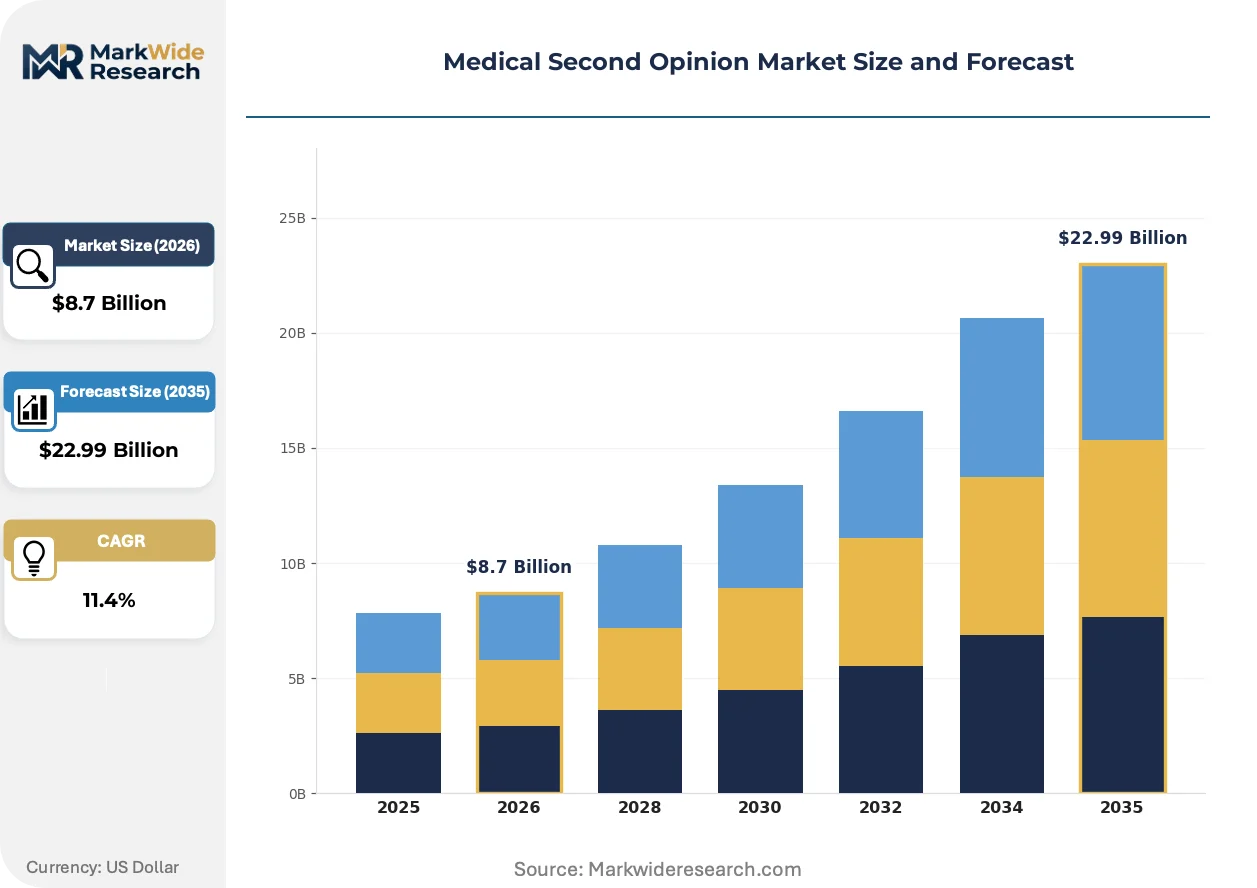
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Virtual Consultation, In-Person Consultation, Telehealth Services, AI Diagnosis End User: Patients, Healthcare Providers, Insurance Companies, Corporations Technology: Telemedicine Platforms, Mobile Health Apps, Video Conferencing Tools, EHR Integration Specialty: Oncology, Cardiology, Neurology, Orthopedics |
| Companies Covered | Johns Hopkins Medicine, Amradnet, Cleveland Clinic, SecondOpinionExpert, Inc., Teladoc Health, Best Doctors Inc., GrandOpinion, DoctorSpring, HCA Hospitals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Second Opinion Market Emerging Trajectories
Synchronous video infrastructure is yielding to asynchronous and AI-hybrid consultation models that reduce per-case operational costs while preserving clinical quality benchmarks. Three developments are compressing traditional service delivery timelines.
Natural language processing for clinical documentation is virtualizing the intake workflow for second opinion requests. Platforms serving employer populations are deploying these tools to auto-populate case summaries from unstructured EHR data. The technology is virtualizing the administrative layer that previously required dedicated nurse navigators for record compilation.
The EU AI Act's risk-classification framework for medical decision-support tools is forcing algorithmic transparency disclosures from platforms serving European patients. Developers must now document training data provenance and performance metrics across demographic subgroups. Oncology staging applications face the strictest conformity assessment requirements, with notified body involvement mandatory for high-risk diagnostic aids.
Employer benefits administrators are unbundling second opinion services from comprehensive telehealth contracts, creating direct procurement relationships with specialty-focused platforms. This disintermediation bypasses generalist telehealth intermediaries that previously captured margin through bundled pricing. The shift is most visible in self-insured manufacturing and technology sector employers with concentrated workforces in North Carolina and Washington state.
Medical Second Opinion Market Segmentation
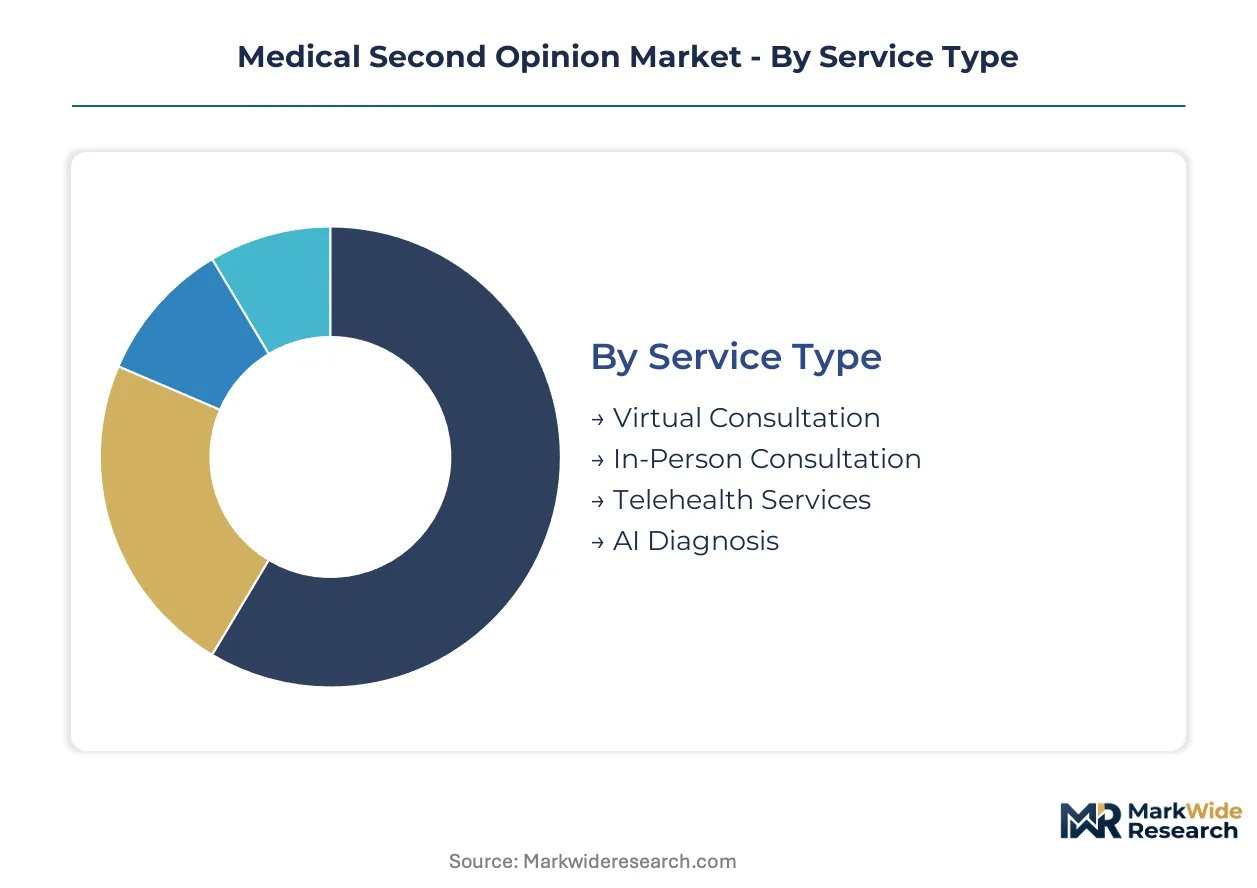
Medical second opinion platforms segment across service delivery modes, technology infrastructure, and clinical specialties. Each dimension carries distinct regulatory requirements and margin structures that shape competitive positioning.
Service Type:
Mature synchronous formats coexist with emerging asynchronous and AI-augmented models that compress delivery timelines and operational costs.
- Virtual Consultation:Synchronous video-based specialist reviews conducted through HIPAA-compliant platforms. Demand concentrates in employer-sponsored plans across the United States, where turnaround speed and lower per-case costs drive procurement decisions.
- Telehealth Services:Comprehensive remote care ecosystems bundling second opinions with ongoing care coordination. Medicare Advantage networks in Florida and Texas are mandating these services for high-cost surgical pre-authorization.
- In-Person Consultation:Physical visits to academic medical centers for direct examination and diagnostic workup.
- AI Diagnosis:Algorithmic preliminary analysis flagging cases for specialist escalation.
Virtual consultation handles the majority of throughput; AI diagnosis is gaining share fastest as FDA guidance clarifies validation pathways.
End User:
Cost tiers separate institutional purchasers with guaranteed volume commitments from individual consumers navigating high-deductible exposure.
- Insurance Companies:Payers mandating second opinions as cost-containment protocols for orthopedic and cardiac procedures. United States commercial insurers are expanding remote coverage to reduce unnecessary surgical utilization.
- Corporations:Self-insured employers embedding second opinion benefits as core plan features. Manufacturing and technology sector employers in North Carolina and Washington state are disintermediating generalist telehealth intermediaries.
- Patients:Individual consumers seeking independent validation of diagnosis or treatment plan.
- Healthcare Providers:Health systems procuring external specialist validation for complex cases.
Insurance companies anchor procurement volume; corporations are expanding most quickly as direct contracting bypasses traditional benefit brokers.
Technology:
Integration depth with existing health system infrastructure determines deployment friction and enterprise sales cycle length.
- Telemedicine Platforms:Dedicated second opinion workflows with specialist matching and case management. Enterprise licensing models sustain recurring revenue from employer and payer contracts.
- EHR Integration:Seamless data exchange reducing administrative friction and duplicate testing. The 21st Century Cures Act enforcement is accelerating standardized API adoption across United States health systems.
- Mobile Health Apps:Consumer-facing interfaces for case submission and physician communication.
- Video Conferencing Tools:Generic synchronous infrastructure repurposed for clinical consultation.
EHR integration commands premium pricing; telemedicine platforms deliver the steepest expansion trajectory as health systems prioritize interoperability.
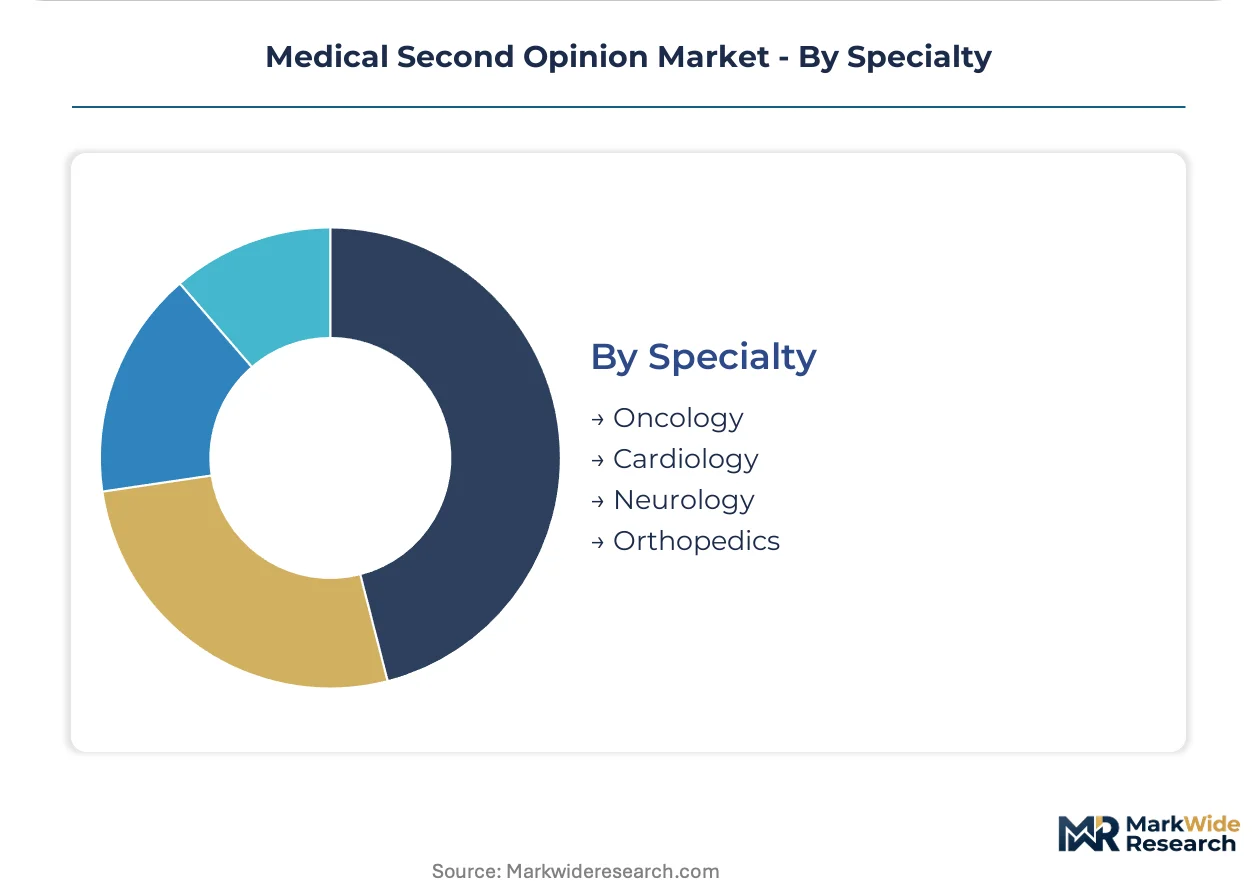
Specialty:
Clinical complexity and stakes of treatment selection create pricing stratification across disease domains.
- Oncology:Staging protocol reviews and treatment pathway validation for cancer diagnoses. Complexity of biomarker interpretation and immunotherapy selection supports premium pricing.
- Cardiology:Intervention decisions for coronary artery disease and structural heart conditions. Pre-authorization requirements from United States commercial payers are standardizing demand.
- Neurology:Diagnostic clarification for neurodegenerative conditions and surgical candidacy.
- Orthopedics:Surgical versus conservative management decisions for joint and spine conditions.
Oncology generates the highest revenue per case; cardiology is climbing the fastest as value-based contracts expand mandatory review protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare Advantage network mandates and employer-sponsored plan designs are reshaping demand geography for medical second opinion services. The United States dominates procurement volume through self-insured employers and commercial payer cost-containment protocols. European regulatory frameworks, particularly the EU AI Act, are creating compliance-driven market entry barriers that favor established platforms.
United States
Employer-sponsored health plans and Medicare Advantage networks mandate second opinion protocols for high-cost surgical procedures, concentrating demand in employer-heavy states. HIPAA interoperability rules and FDA guidance on AI-assisted diagnostics accelerate platform certification requirements. The Cleveland Clinic in Ohio and Johns Hopkins in Maryland anchor specialist labor pools that limit competitor access.
Germany
Statutory health insurance funds are piloting remote second opinion programs for oncology and cardiac interventions to reduce unnecessary surgical utilization. The EU AI Act's risk-classification framework for medical decision-support tools forces algorithmic transparency disclosures from platforms serving German patients. Berlin and Munich host emerging telehealth clusters focused on cross-border specialist consultations.
United Kingdom
NHS England's elective recovery programs are embedding virtual second opinions to reduce diagnostic backlogs and surgical wait times. MHRA oversight of AI diagnostic tools creates parallel compliance pathways to FDA requirements. London's academic medical centers control access to subspecialty expertise for complex oncology and neurology reviews.
Japan
PMDA guidance on software as a medical device is clarifying validation pathways for AI-augmented preliminary diagnostic analysis. METI initiatives promote telehealth infrastructure standardization to support aging population care delivery. Tokyo and Osaka medical districts concentrate specialist availability for remote consultation networks.
India
Price-transparent cash-pay models appeal to uninsured and high-deductible patient segments in metropolitan markets. CDSCO regulation of AI-based diagnostic tools remains less prescriptive than FDA or EMA frameworks, lowering entry barriers for algorithm developers. Bangalore and Hyderabad telehealth clusters serve domestic demand and medical tourism flows.
Medical Second Opinion Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Academic medical centers with captive specialist networks occupy the premium tier, while telehealth platforms with enterprise licensing models dominate volume contracting. Competitive moves center on EHR integration depth and Medicare Advantage direct contracting to bypass traditional benefit brokers.
Within the academic medical center tier, Johns Hopkins Medicine and Cleveland Clinic exemplify institutions leveraging exclusive specialist labor pools to limit competitor access. Teladoc Health occupies a position representing scaled telehealth platforms with recurring revenue from employer and payer enterprise contracts. These three anchors illustrate divergent archetypes: prestige-branded institutional expertise versus technology-enabled service aggregation.
| Leading Market Players |
|---|
| Johns Hopkins Medicine |
| Amradnet |
| Cleveland Clinic |
| SecondOpinionExpert, Inc. |
| Teladoc Health |
| Best Doctors Inc. |
| GrandOpinion |
| DoctorSpring |
| HCA Hospitals |
| Others |
Supply Flow & Price Mechanics
Specialist labor concentration in Boston, Cleveland, and Houston academic medical centers anchors premium pricing tiers for oncology and cardiac second opinions, while telehealth platforms compete on cost-transparent asynchronous models that compress margins in high-volume employer contracts.
Pricing Analysis
Certification level creates the primary spread across the Medical Second Opinion Market, with FDA-cleared AI diagnostic tools and HIPAA-compliant enterprise platforms commanding premium SaaS-tiered subscriptions against price-transparent cash-pay alternatives. Three-tier pricing structure separates academic medical center prestige brands from telehealth aggregators and direct-to-consumer asynchronous consults. Cost compression in virtual consultation tiers is intensifying because employer-sponsored plans mandate volume commitments that squeeze per-case economics. Uninsured patients navigating high-deductible exposure exhibit the greatest price sensitivity, while Medicare Advantage networks prioritize turnaround speed over unit cost.
Supply Chain Analysis
State-level licensure fragmentation across United States jurisdictions creates compliance overhead that restricts cross-border consultation volume and elevates platform operational costs. Supply draws from subspecialty neurologists and orthopedic surgeons concentrated in academic medical centers, algorithm developers in Bangalore and Hyderabad clusters, and EHR integration specialists serving health system IT architectures. Single-source vulnerability sits with top-tier oncology staging experts at Johns Hopkins and Cleveland Clinic who limit competitor access through exclusive network partnerships. Distribution runs through employer benefits administrators, Medicare Advantage direct contracting channels, and hospital system procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as employer benefits administrators disintermediate generalist telehealth intermediaries, creating direct procurement niches for specialty-focused platforms serving concentrated manufacturing and technology sector workforces.
For Market Incumbents: Build regulatory moats through preemptive FDA 510(k) submissions for AI diagnostic algorithms and HIPAA interoperability certifications that exceed minimum compliance thresholds. Deepen EHR integration partnerships with Epic and Cerner to embed second opinion workflows directly into clinician order entry systems. Defend against asynchronous platform entrants by accelerating credentialing timelines for subspecialty consultants through automated primary source verification. For New Entrants and Emerging Players: Texas and Florida high-deductible consumer segments remain the most penetrable white-space targets, with price-transparent cash-pay oncology and orthopedic consultations underserved by incumbent hospital-affiliated programs. Target self-insured employers in North Carolina manufacturing corridors through direct benefits administrator relationships that bypass traditional broker intermediation. Deploy AI-augmented triage tools to compress specialist review timelines from weeks to days as the primary go-to-market differentiator. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed telehealth platforms holding enterprise licensing contracts with Fortune 500 employers but lacking specialist network depth for premium clinical domains. Long-term viability hinges on Medicare Advantage direct contracting scale and algorithmic transparency compliance with EU AI Act requirements for cross-border European patient access. Watch CMS reimbursement parity expansion between virtual and in-person second opinions as the inflection signal that would immediately restructure revenue models and acquisition multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Cleveland Clinic and Johns Hopkins exclusive specialist networks limit competitor access to subspecialty labor pools. |
| FDA Submission Pathway | AI diagnostic algorithm clearance creates regulatory moats elevating compliance costs for platform operators. |
| Medicare Advantage Direct Contracting | MA plans represent the fastest-growing payer segment for mandatory second opinion protocols with minimal broker intermediation. |
| EHR Integration Development | Epic and Cerner embedded workflows reduce administrative friction and duplicate testing across health systems. |
| EU AI Act Compliance Program | Algorithmic transparency disclosures for European patients create advisory revenue streams and market entry barriers. |
Methodological Framework
A spread of perspectives from telehealth platform executives, hospital system chief medical officers, employer benefits administrators, Medicare Advantage plan directors, and AI diagnostic developers converged on the working assumptions driving this analysis. Primary interviews combined with secondary validation from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement contracts, and GPO pricing disclosures. Bottom-up specialist supply modeling and top-down payer demand triangulation anchored volume estimates.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon, with segmentation modeled by service delivery mode, technology infrastructure depth, clinical specialty complexity, and end-user procurement archetype. CAGRs derived from historical employer-sponsored plan adoption curves and Medicare Advantage network expansion patterns. Forecast inputs incorporated HIPAA interoperability mandate compliance timelines and FDA AI diagnostic guidance evolution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cash-pay asynchronous platforms or CMS reimbursement parity expansion would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
Global Urgent Care Center Market
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
Nutraceutical Contract Manufacturing Services Market
Healthcare Services
Global Acute Hospital Care Market
Healthcare Services
Primary Care Physicians Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
Asia-Pacific Healthcare Staffing Market
Healthcare Services
Immunoassay CDMO Market
Healthcare Services
India Senior Living Market
Healthcare Services
Medical Case Management Services Market
Healthcare Services
Ambulatory Healthcare Service Market
Healthcare Services
Hair Transplant Services Market
Healthcare Services
Healthcare Cold Chain Logistics Market
Healthcare Services
Canada Senior Living Market
Healthcare Services
US Healthcare Staffing Market
Healthcare Services
Funeral Products and Services Market