
 Global Pharmaceutical Contract Sales Outsourcing (CSO) Market | 2026-2036
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market Intelligence
Specialty pharma is restructuring the buyer profile for contract sales outsourcing as research-based pharma trims legacy primary care teams. IQVIA Inc. leverages its data analytics infrastructure to anchor large-scale field force deployments across multiple therapy areas. Syneos Health differentiates through integrated commercialization models that span clinical development through launch. CMIC HOLDINGS Co., Ltd. dominates Japan's CSO landscape with deep relationships with domestic research-based pharma and biotechnology firms.
Pharmaceutical contract sales outsourcing encompasses the delegation of sales force deployment, training, compliance oversight, and customer relationship management to third-party specialists who operate under the sponsor's brand or as transparent agents. Field force management typically involves territory mapping, physician targeting, call planning, and performance analytics against prescription volume benchmarks. Dedicated team engagement models command premium positioning due to long-term client integration and regulatory liability transfer, while project-based arrangements serve launch-phase biotechs with finite commercialization windows. Oncology therapy area outsourcing is expanding fastest as complex immuno-oncology portfolios require specialized scientific liaisons rather than traditional representatives.
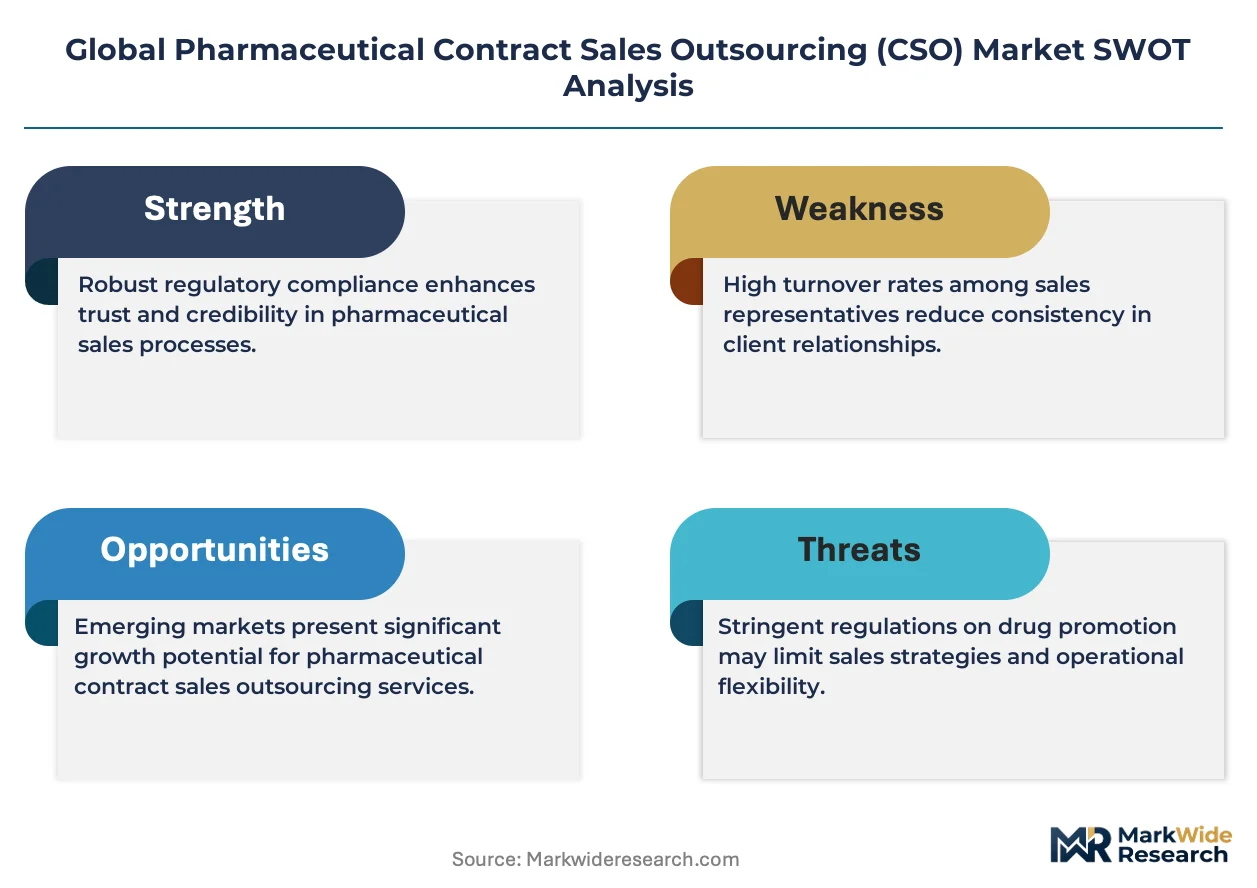
FDA promotional review standards, EMA transparency requirements under the Clinical Trials Regulation, and Japan's PMDA sales activity guidelines collectively elevate compliance monitoring to a non-negotiable service layer. These frameworks shape vendor selection criteria by mandating audit trails, adverse event reporting integration, and certified training documentation. Stakeholders must evaluate whether hybrid engagement models or full dedicated team structures align with evolving cross-border promotional oversight intensity.
Market Dynamics
Specialty pharmaceutical companies are dismantling in-house primary care field forces and replacing them with modular outsourced deployments, transferring fixed cost structures to variable engagement models that align spend with prescription velocity.
Growth Catalysts
- Specialty therapy commercialization:Oncology and rare disease portfolios require scientific liaisons with advanced therapeutic expertise that biotechs cannot build internally.
- EMA transparency mandates:The Clinical Trials Regulation compels sponsors to maintain auditable promotional records, elevating demand for third-party compliance infrastructure.
- Japan's PMDA guidelines:Strict documentation requirements for sales activity reporting drive domestic and foreign sponsors toward established CSO compliance frameworks.
Market Restraints
- Regulatory liability transfer limits:FDA promotional review standards create friction in contracting structures, as sponsors retain ultimate accountability for off-label communication.
- Talent pool concentration:Experienced medical science liaisons cluster in Boston, Basel, and Tokyo, creating regional wage premiums and deployment constraints.
- Data access restrictions:HIPAA constraints and EU GDPR limitations on physician-level prescription data reduce targeting precision for outsourced teams.
Strategic Opportunities
- Cell and gene therapy launches:One-time curative treatments require specialized patient identification and hub services that CSOs can integrate with field deployment.
- Germany's AMNOG process:Complex benefit assessment negotiations create demand for localized health economics expertise within outsourced teams.
- Digital engagement convergence:Hybrid face-to-face and remote detailing models enable territory coverage expansion without proportional headcount growth.
Industry Challenges
- Scientific credential scarcity:Advanced therapy areas require PhD-level field personnel, extending recruitment timelines and elevating training costs.
- Legacy CRM integration:Sponsor systems often lack API compatibility with CSO analytics platforms, complicating real-time performance tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Contract Sales Outsourcing (CSO) Market |
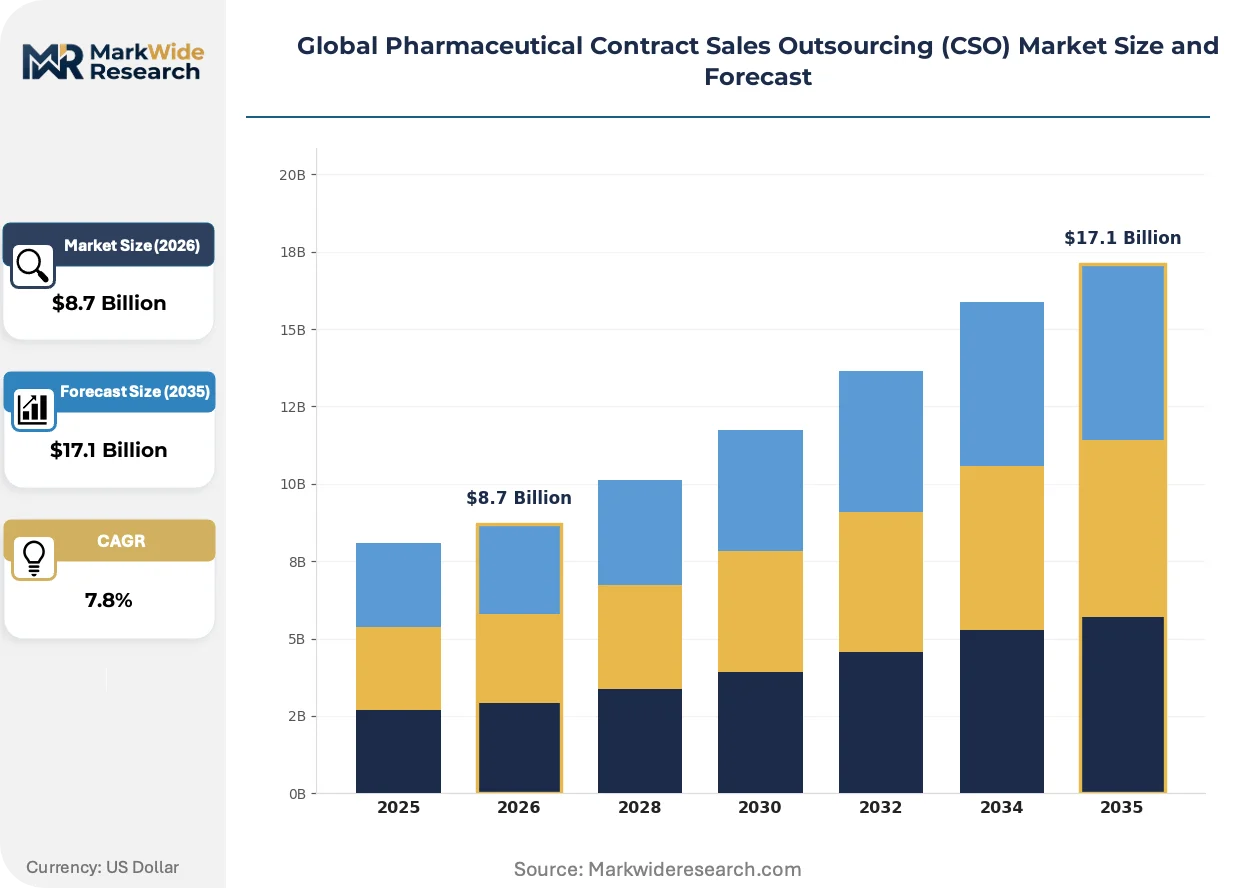
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Field Force Management, Sales Training, Compliance Monitoring, Lead Generation, CRM Services Client Type: Biotechnology Firms, Generic Drug Manufacturers, Specialty Pharma, Research-Based Pharma, Nutraceutical Companies Therapy Area: Oncology, Central Nervous System, Cardiovascular, Respiratory, Dermatology Engagement Model: Dedicated Team, Project-Based, Hybrid Model, Staff Augmentation |
| Companies Covered | ICON plc, CMIC HOLDINGS Co., Ltd., IQVIA Inc., Ashfield Medcomms, Amplity Health, Syneos Health, EVERSANA, Publicis Touchpoint Solutions, Parexel International Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market Strategic Shifts & Innovations
Artificial intelligence and real-world evidence platforms are compressing the cycle from physician targeting to message optimization, enabling outsourced teams to pivot faster than traditional field forces.
AI-driven next-best-action engines are expanding into territory planning and call sequencing for specialty sales representatives. Mid-sized biotech sponsors in immuno-oncology are deploying these tools within six-month launch windows. The technology is expanding into predictive churn modeling for at-risk prescriber relationships, reducing reliance on static segmentation.
EU MDR convergence with pharmaceutical promotional standards is elevating audit trail requirements for device-drug combination products. Sponsors must now maintain unified documentation across sales and post-market surveillance activities. Germany and France are witnessing the fastest CSO adoption of integrated medical device compliance modules.
Biotech procurement teams are unbundling launch services from long-term commercialization contracts, compressing vendor selection cycles and elevating project-based engagement models. Traditional dedicated team structures face displacement from modular service menus covering payer access, patient services, and field deployment. This pattern is most pronounced among Series C-funded companies in the United States.
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market Segmentation
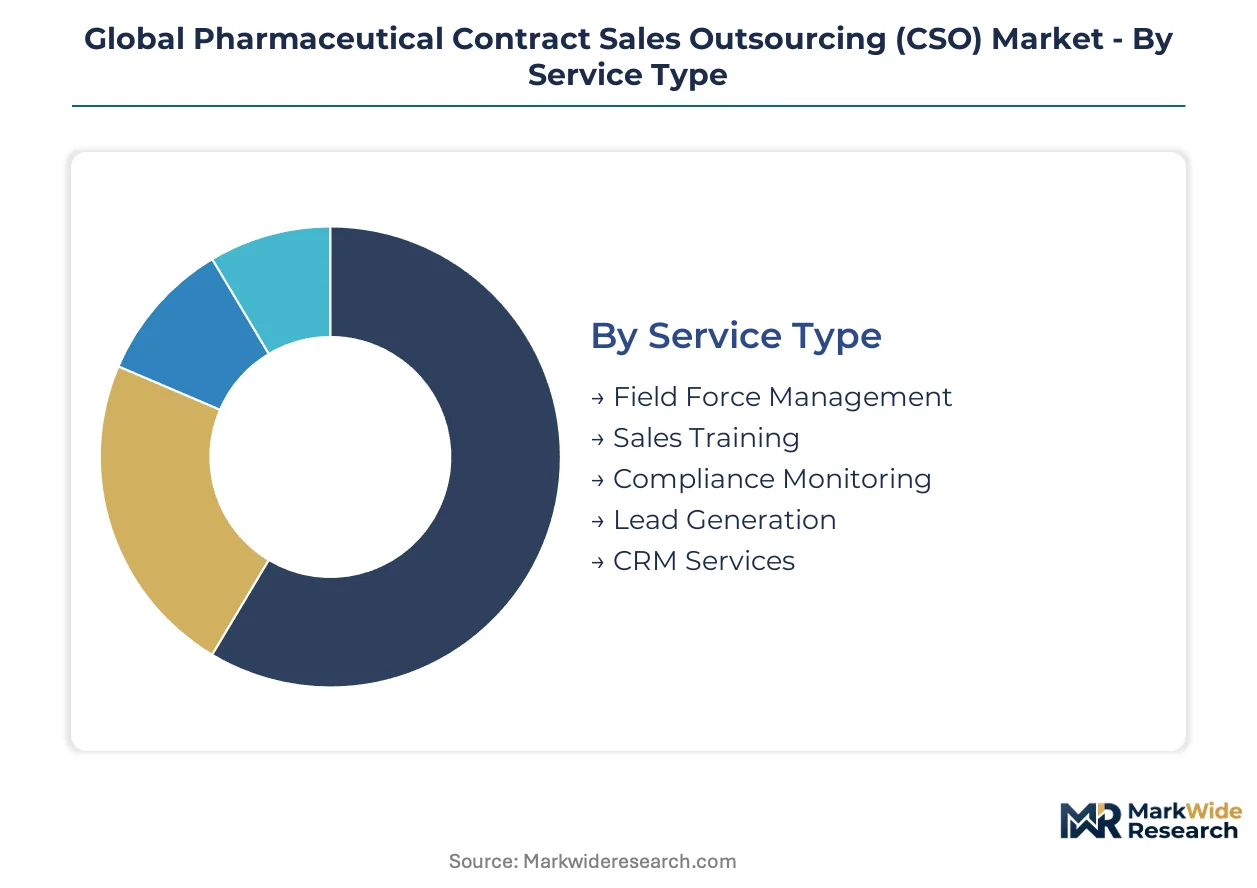
CSO procurement patterns diverge sharply across service architectures and client maturity levels. Biotechnology sponsors prioritize modular engagement models that preserve capital runway, while established research-based pharma favor integrated compliance infrastructure.
Service Type:
Technology sophistication separates premium service tiers from commoditized offerings.
- Field Force Management:Territory mapping, physician targeting, and call planning systems anchor large-scale deployments. Demand clusters in the United States and Germany where complex reimbursement pathways require localized expertise and real-time performance analytics against prescription benchmarks.
- Compliance Monitoring:Audit trail infrastructure, adverse event reporting integration, and certified training documentation address FDA promotional review standards and EMA transparency mandates. Sponsors in Japan's PMDA-regulated environment particularly require this service layer as regulatory liability transfer becomes non-negotiable.
- Sales Training:Scientific credentialing programs for medical science liaisons.
- Lead Generation:Physician identification and prioritization services for launch-phase products.
- CRM Services:Customer relationship platform management and data integration.
Mature deployment sits with Field Force Management. Newer deployment is concentrated in Compliance Monitoring.
Client Type:
Capital structure and pipeline composition dictate outsourcing intensity.
- Specialty Pharma:Niche therapy portfolios require scientific liaisons with advanced therapeutic expertise that internal teams cannot cost-effectively maintain. These sponsors in Boston and Basel transfer fixed cost structures to variable engagement models aligned with prescription velocity.
- Biotechnology Firms:Pre-commercial and launch-phase companies with finite commercialization windows favor project-based arrangements over dedicated teams. Series C-funded sponsors in the United States are unbundling launch services from long-term contracts, compressing vendor selection cycles.
- Research-Based Pharma:Legacy primary care field force dismantling creates demand for modular outsourced deployments.
- Generic Drug Manufacturers:Volume-driven sales operations with standardized representative requirements.
- Nutraceutical Companies:Consumer-facing promotional activities with lighter regulatory oversight.
Established procurement patterns persist with Research-Based Pharma. Experimental contracting models are emerging fastest among Biotechnology Firms.
Therapy Area:
Scientific complexity determines field personnel credential requirements and deployment cost structures.
- Oncology:Immuno-oncology portfolios demand PhD-level scientific liaisons rather than traditional representatives. Complex combination therapies and biomarker-driven patient identification in the United States and Japan require specialized expertise that extends recruitment timelines and elevates training costs.
- Central Nervous System:Psychiatry and neurology indications require longitudinal prescriber relationships and sophisticated messaging around trial endpoints. Germany's AMNOG benefit assessment process creates particular demand for localized health economics expertise within these teams.
- Cardiovascular:Established primary care detailing with mature compliance frameworks.
- Respiratory:Mixed specialist and primary care prescriber targeting.
- Dermatology:Aesthetic and medical indications with distinct promotional pathways.
Longstanding outsourcing relationships dominate Cardiovascular. Steepest expansion trajectory appears in Oncology.
Engagement Model:
Contract structure determines cost variability and regulatory liability allocation.
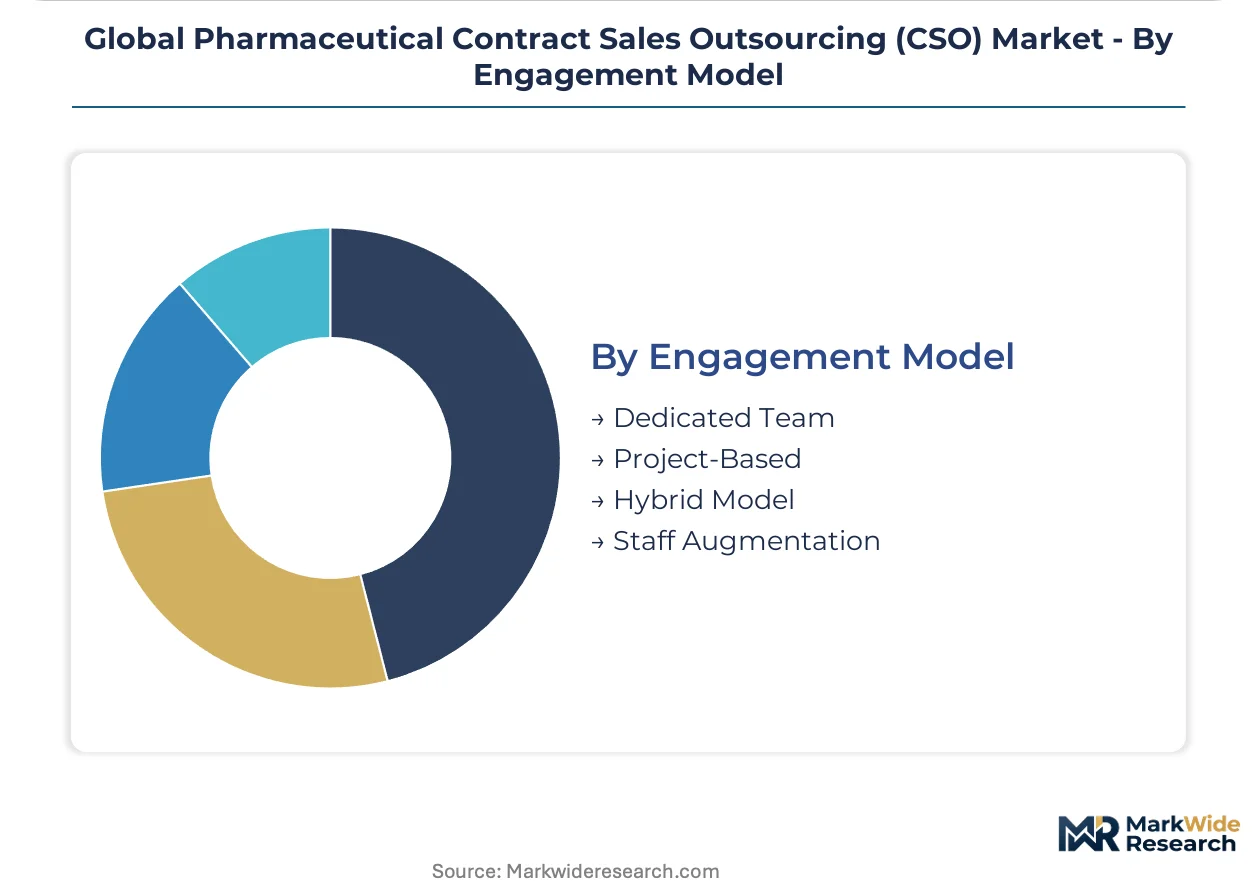
- Dedicated Team:Long-term client integration with full regulatory liability transfer commands premium positioning. Research-based pharma in Japan leverage CMIC HOLDINGS and similar domestic specialists for deep therapeutic area expertise embedded within sponsor operations.
- Project-Based:Finite commercialization windows for launch-phase biotechs enable capital-efficient market entry. These arrangements are displacing traditional dedicated structures among United States-based sponsors seeking to preserve runway.
- Hybrid Model:Blended face-to-face and remote detailing enabling territory coverage expansion.
- Staff Augmentation:Supplemental headcount for seasonal or geographic coverage gaps.
Stable revenue concentration rests with Dedicated Team structures. Fastest share gains are occurring in Project-Based arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States generates the majority of CSO consumption value, while vendor service delivery concentrates across multiple developed markets with specialized regulatory expertise. Production of outsourced sales infrastructure spans data analytics hubs, compliance training centers, and field force deployment networks rather than manufacturing facilities.
United States
FDA promotional review standards and complex reimbursement pathways drive demand for compliance-integrated CSO partnerships. The IRA's drug pricing provisions are accelerating biotech reliance on variable-cost outsourced models. Boston and San Francisco biotech clusters favor project-based arrangements with modular service unbundling.
Germany
The AMNOG benefit assessment process requires localized health economics expertise within outsourced field teams. EMA transparency mandates under the Clinical Trials Regulation compel auditable promotional record systems. The Frankfurt-Düsseldorf corridor hosts specialized CSO compliance infrastructure serving device-drug combination launches.
Japan
PMDA sales activity guidelines mandate strict documentation requirements that favor established domestic CSO frameworks. CMIC HOLDINGS anchors the market with deep relationships across research-based pharma and biotechnology firms. The Tokyo-Osaka corridor concentrates medical science liaison talent for oncology portfolio deployment.
Switzerland
Swissmedic promotional oversight and the Basel pharmaceutical cluster create demand for high-credential scientific liaison services. Complex immuno-oncology portfolios require PhD-level field personnel that sponsors source through specialized vendors. The Basel-Zurich axis concentrates vendor training infrastructure for rare disease commercialization.
United Kingdom
NICE technology appraisal processes necessitate outsourced teams with health technology assessment expertise. MHRA promotional standards align with evolving EMA transparency frameworks post-Brexit. The London-Cambridge biotech corridor drives experimental contracting models among venture-funded sponsors.
Global Pharmaceutical Contract Sales Outsourcing (CSO) Market Key Industry Players
Top-tier vendors anchor integrated commercialization platforms, while mid-tier specialists occupy therapy-area niches and regional compliance strongholds. The vendor base stratifies across data-anchored deployment networks, integrated clinical-to-commercial models, and geography-specific regulatory expertise. Three archetypes dominate: analytics-driven field force orchestrators, end-to-end commercialization integrators, and domestic regulatory compliance specialists. Competitive positioning depends on M&A-driven capability expansion and strategic partnerships with biotech launch sponsors.
Within the integrated commercialization tier, Syneos Health exemplifies the clinical-to-launch model spanning development through market entry. IQVIA Inc. occupies the data-anchored position, leveraging prescription analytics infrastructure to optimize physician targeting and territory planning. CMIC HOLDINGS Co., Ltd. represents the domestic specialist archetype, embedding deep PMDA compliance expertise within Japan's concentrated pharmaceutical ecosystem.
| Leading Market Players |
|---|
| ICON plc |
| CMIC HOLDINGS Co., Ltd. |
| IQVIA Inc. |
| Ashfield Medcomms |
| Amplity Health |
| Syneos Health |
| EVERSANA |
| Publicis Touchpoint Solutions |
| Parexel International Corporation |
| Others |
Cost & Logistics Intelligence
PhD-level medical science liaison concentration in Boston, Basel, and Tokyo creates labor-cost differentials that widen pricing-tier spreads between premium dedicated teams and project-based deployments. Variable engagement models compress margins for vendors serving capital-constrained biotech sponsors while compliance-integrated offerings command sustained premiums.
Pricing Analysis
Margin tightening in project-based arrangements reflects unbundled service menus displacing traditional dedicated team structures. Three-tier pricing structure across premium dedicated teams, hybrid engagement models, and economy project-based arrangements stratifies by certification level and therapeutic area complexity. Cost-down pressure on standard-tier offerings accelerates because Series C-funded sponsors prioritize capital preservation over long-term integration. Biotechnology firms exhibit highest price sensitivity, while research-based pharma in Japan demonstrate lowest sensitivity due to PMDA liability transfer requirements.
Supply Chain Analysis
Japan's PMDA documentation mandates and Germany's AMNOG localization requirements are reshaping talent sourcing toward domestic-content compliance frameworks. Workforce supply concentrates in the United States, Germany, and Japan, with recruitment pipelines drawing from specialized health economics programs, medical affairs fellowships, and regulatory science curricula. Single-source vulnerability sits with oncology scientific liaison talent pools tethered to the Boston-Tokyo-Basel corridor. Distribution runs through direct enterprise contracting with sponsor commercial operations teams rather than intermediary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as vendors pursue backward control over real-world evidence platforms and AI-driven targeting infrastructure to defend pricing power.
For Market Incumbents: Extend compliance infrastructure investments to capture EMA transparency mandate spend before modular competitors fragment the service stack. Anchor large-scale field force deployments with IQVIA-grade data analytics integration to raise switching costs for research-based pharma sponsors. Counter project-based displacement by embedding patient services and hub capabilities within dedicated team offerings.
For New Entrants and Emerging Players: AI-driven next-best-action engines for immuno-oncology launches offer a technology-first wedge into sponsor procurement cycles previously locked by established relationships. Target Germany's AMNOG process specialization and cell-and-gene therapy patient identification services as the most penetrable white-space segments. Pursue platform partnerships with Series C-funded biotechs seeking six-month launch windows rather than competing for mature dedicated team contracts.
For Investors and Strategic Acquirers: Re-rating potential sits with domestic regulatory compliance specialists given cross-border promotional oversight intensity and sponsor preference for liability transfer. Long-term viability favors vendors with integrated clinical-to-commercial models spanning trial execution through launch deployment. Monitor FDA promotional review standard enforcement actions as the inflection signal for compliance infrastructure valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Real-World Evidence Platform Integration | IQVIA-grade prescription analytics compress physician targeting cycles for oncology launches. |
| PMDA Compliance Infrastructure Buildout | Domestic Japanese vendors embed audit trail systems that foreign competitors cannot replicate. |
| Cell and Gene Therapy Hub Services | Specialized patient identification integrates with field deployment for one-time curative treatments. |
| Hybrid Face-to-Face and Remote Detailing | Territory coverage expansion without proportional headcount growth reshapes unit economics. |
| EU MDR Convergence Compliance Modules | Unified documentation across sales and post-market surveillance captures device-drug combination spend. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs before primary validation with commercial operations executives, medical affairs directors, formulary access specialists, and CSO procurement leads. FDA 483 observations, EMA inspection reports, ClinicalTrials.gov disclosures, and pharmaceutical sales force benchmarking databases supplied quantitative foundations. Bottom-up service line sizing reconciled against top-down sponsor spending estimates through iterative triangulation.
Reconciliation of prescription volume benchmarks, field force deployment metrics, and compliance infrastructure spend streams shaped the analytical framework across the analysis window. Segmentation dimensions modeled encompass service architecture, client maturity tier, therapy area scientific complexity, and engagement model liability structure. CAGRs derived from weighted regression of historical outsourcing penetration against pipeline composition forecasts, with immuno-oncology launch velocity and IRA pricing provision impacts as key sensitivity inputs.
Several conditions sit outside the modeled scope, including sponsor decisions to re-internalize field forces post-launch and unforeseen regulatory enforcement actions altering liability transfer economics. Forecasts reflect documented assumptions regarding biotech funding environment stability and specialty therapy approval trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
United States Pharmaceutical Logistic Services Market
Healthcare Services
Healthcare Physician Staffing Market
Healthcare Services
Surgical Fluid Disposal Market
Healthcare Services
Medical Case Management Services Market
Healthcare Services
US Value-Based Healthcare Service Market
Healthcare Services
Contract Research Organization (CRO) Services Market
Healthcare Services
Global Medical Affairs Outsourcing Market
Healthcare Services
US Integrated Delivery Network Market
Healthcare Services
Hospital Resource Management Market
Healthcare Services
Global Hospital Services Market
Healthcare Services
Medical Recruitment Market
Healthcare Services
Global Funeral Homes and Funeral Services Market
Healthcare Services
Hair Restoration Services Market
Healthcare Services
Healthcare Staffing Market
Healthcare Services
Global Value Based Healthcare Services Market
Healthcare Services
India Senior Living Market