
 Gas Station Equipment Market | 2026-2036
Gas Station Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Station Equipment Market Analysis
UL-listed and ATEX-certified equipment tiers is collapsing the gap between legacy mechanical dispensers and intelligent fueling systems. Dover Fueling Solutions leverages embedded telemetry to sustain its position in connected retail infrastructure. Gilbarco Veeder-Root anchors North American market presence through extensive service networks. Beijing Sanki Petroleum Technology Co. Ltd. competes aggressively on manufacturing scale for Asian markets.
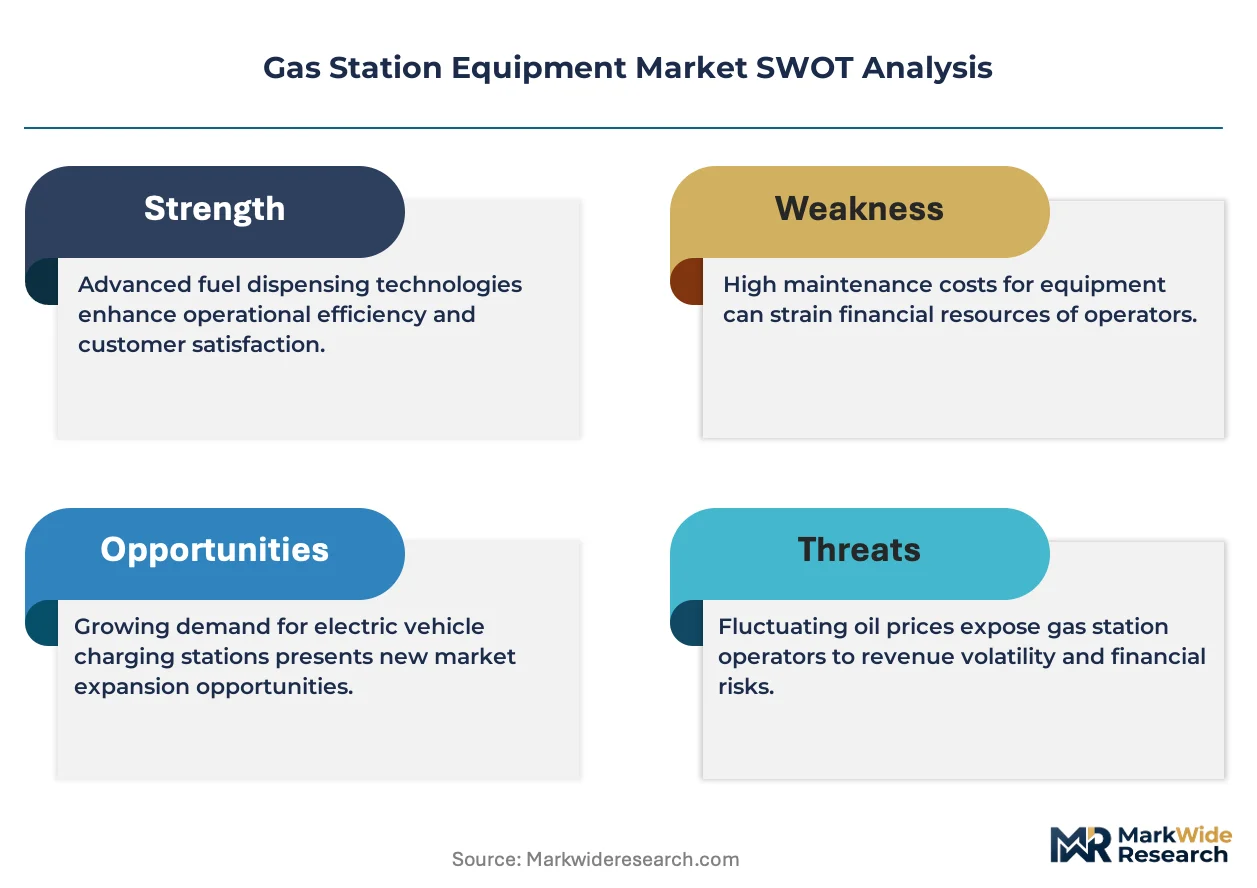
Gas station equipment comprises fuel dispensers, tank monitoring hardware, payment terminals, and environmental sensors engineered to handle hydrocarbon transfer rates, vapor recovery compliance, and multi-fuel compatibility. These systems enable safe retail fuel distribution while integrating inventory tracking and payment processing for commercial fleet and consumer transactions. Fuel Dispensers generate the dominant revenue pool as replacement cycles accelerate for legacy units, while IoT Connectivity commands expanding margin pools through recurring software and maintenance revenues. Cloud-Based Solutions within fuel management systems are attracting capital as operators seek centralized oversight across distributed retail networks.
EPA vapor recovery mandates and EU F-Gas Regulation dictate emissions-compliant equipment specifications, while UL and ATEX certification frameworks govern market access in North America and Europe respectively. China's GB standards and NMPA-equivalent fuel quality enforcement add compliance layers for equipment entering that market. Stakeholders must monitor regulatory divergence between low-emission equipment mandates in developed markets and cost-driven specification floors in emerging economies.
Market Dynamics
Connected fueling infrastructure is decomposing the traditional equipment replacement cycle into continuous software-driven upgrade streams, forcing capital allocation shifts across retail networks.
Growth Catalysts
- EPA Phase II Vapor Recovery Mandates:US retail operators must retrofit or replace non-compliant dispensers and Stage II systems, accelerating hardware turnover in the world's largest installed base.
- Contactless Payment Integration:EMV chip compliance and NFC terminal deployment are pulling payment hardware upgrades through European and North American service stations.
- Compressed Natural Gas Dispenser Deployment:Fleet operators in India and Brazil are expanding alternative fuel infrastructure, creating parallel equipment demand alongside conventional petroleum systems.
Market Restraints
- Stainless Steel and Electronics Cost Volatility:Input price swings for corrosion-resistant alloys and semiconductor components compress manufacturing margins on precision fueling hardware.
- Chinese Manufacturing Concentration:Submersible turbine pump and flow meter production clusters heavily in Zhejiang and Jiangsu provinces, exposing supply continuity to single-region logistics disruptions.
- Extended ATEX Certification Timelines:European explosive atmosphere compliance testing creates 8-14 month market entry delays for new dispenser platforms.
Strategic Opportunities
- Sub-Saharan Africa Network Modernization:Nigeria and Kenya are consolidating fragmented independent retail into branded operator networks requiring full equipment suites.
- Hydrogen Dispenser Pre-Positioning:Early station infrastructure deployment in Germany and Japan creates first-mover equipment installation contracts ahead of vehicle fleet scaling.
- API-First Fleet Management Convergence:Integration between fuel management systems and telematics platforms opens recurring software revenue streams for dispenser OEMs.
Industry Challenges
- Embedded Systems Cybersecurity Certification:IEC 62443 compliance for connected dispensers demands scarce industrial control security engineering talent.
- Legacy Tank Gauge Integration:1980s-era magnetostrictive probe infrastructure in North America complicates cloud-based monitoring system rollouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Station Equipment Market |
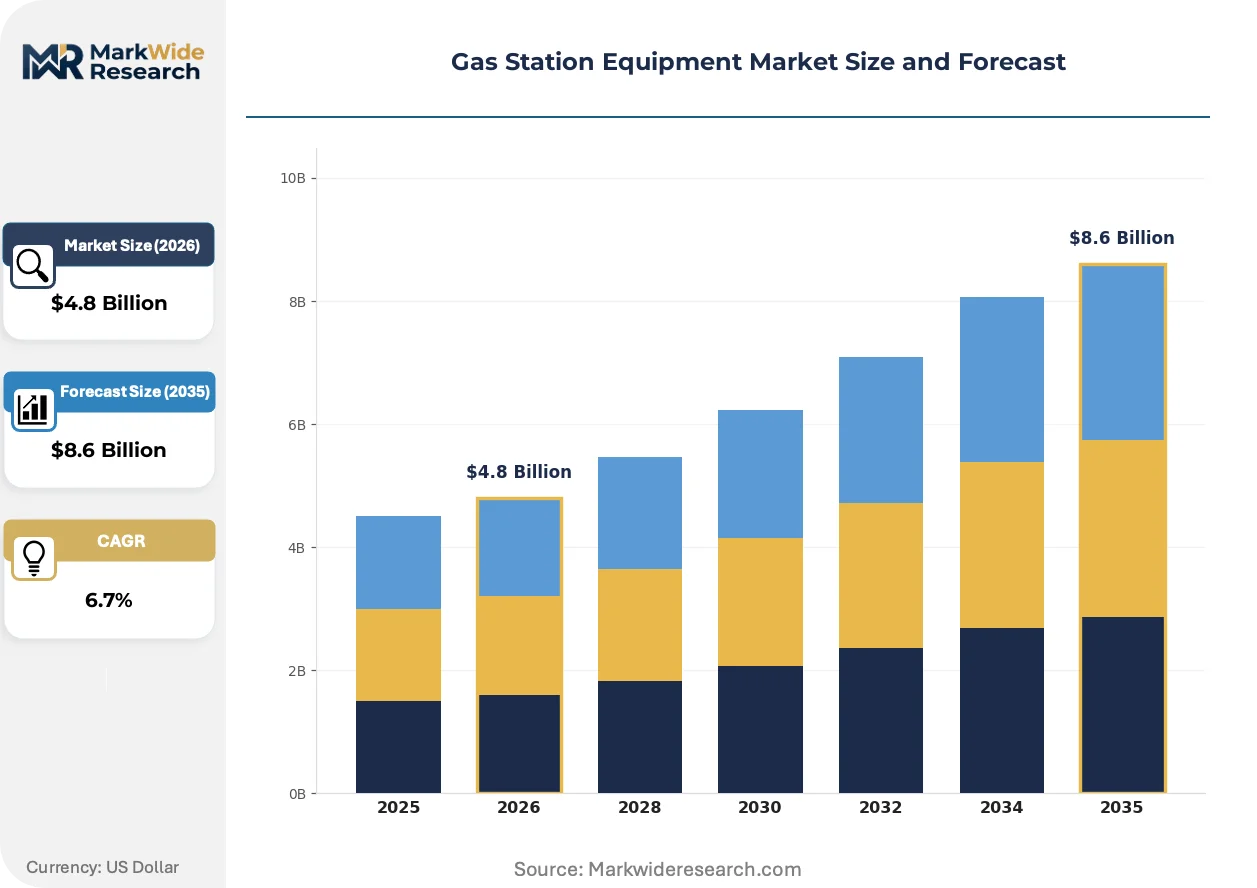
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fuel Dispensers, Payment Terminals, Tank Monitoring Systems, Fuel Management Systems Technology: Automatic Identification, IoT Connectivity, Cloud-Based Solutions, RFID Technology End User: Retail Outlets, Commercial Fleets, Oil Companies, Service Stations Application: Fuel Dispensing, Payment Processing, Inventory Management, Environmental Monitoring |
| Companies Covered | Censtar Science and Technology Corp. Ltd., Dover Fueling Solutions, Gilbarco Veeder-Root, Bennett Pump Company, Tokheim Group, Wayne Fueling Systems, Scheidt & Bachmann GmbH, Beijing Sanki Petroleum Technology Co. Ltd., Tatsuno Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Station Equipment Market Emerging Trajectories
Intelligence migration from central site systems to edge devices is redefining competitive differentiation in fuel retail infrastructure. Equipment vendors now compete on data architecture rather than mechanical reliability alone.
Edge computing modules embedded directly within fuel dispensers are decomposing the traditional site controller architecture. Major retail operators in Germany and the United Kingdom are piloting distributed transaction processing that reduces latency for payment authorization. This topology is compressing hardware BOM costs while elevating software maintenance contract values.
The EU F-Gas Regulation is accelerating refrigerant leak detection sensor deployment across European retail networks. Equipment suppliers must integrate infrared sensing hardware into canopy and storage area monitoring systems. French and Italian operators face the steepest compliance deadlines, driving concentrated procurement waves through 2027.
Fleet card program consolidation is reshaping B2B procurement patterns for high-volume dispensers. Integrated fuel management platforms from oil majors are displacing standalone equipment vendor relationships at commercial trucking depots. This concentration is most pronounced in Brazil's agricultural belt and Australia's mining corridors, where fleet density supports dedicated high-flow installation contracts.
Gas Station Equipment Market Segmentation
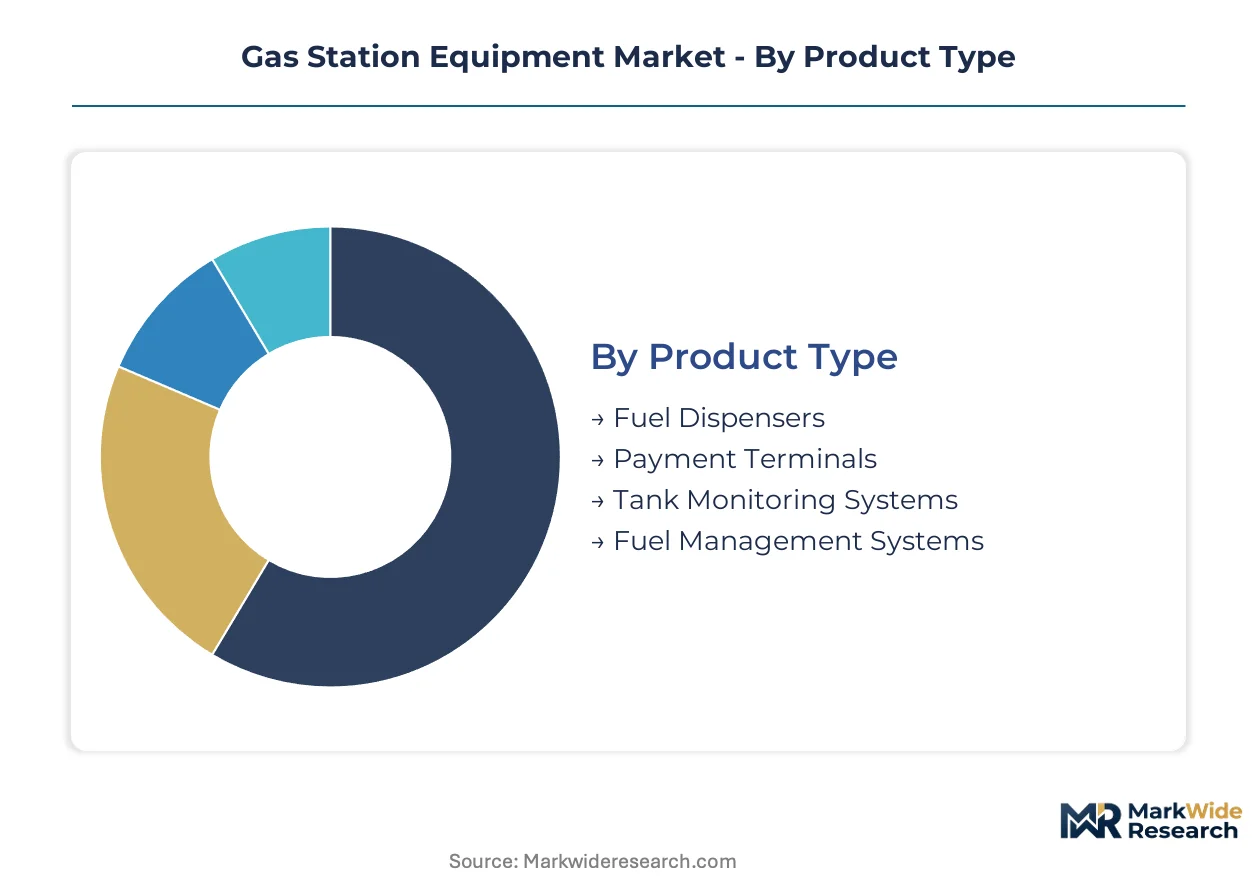
Equipment segmentation in fuel retail infrastructure reveals how capital allocation splits between mechanical hardware replacement cycles and digital upgrade streams. Vendors must calibrate portfolio depth across legacy dispenser refurbishment, connected system deployment, and emerging alternative fuel interfaces.
Product Type:
Fuel Dispensers face the most acute substitution pressure as intelligent pumping systems displace mechanical units across regulatory compliance deadlines.
- Fuel Dispensers:These units integrate vapor recovery hardware, multi-fuel nozzles, and telemetry modules for hydrocarbon transfer at retail sites. Demand concentrates in China and India where network modernization programs mandate replacement of legacy mechanical infrastructure under tightening emissions enforcement.
- Payment Terminals:EMV-compliant and NFC-enabled transaction hardware processes fleet cards and consumer payments at the pump. European service stations are pulling hardware upgrades through contactless mandate deadlines, compressing procurement cycles for terminal OEMs.
- Tank Monitoring Systems:Magnetostrictive probe arrays and ultrasonic sensors track fuel inventory levels and leak detection in underground storage. Brazil's expanding branded retail networks are deploying integrated gauge systems for centralized inventory oversight.
- Fuel Management Systems:Site controllers and back-office software coordinate dispenser authorization, price management, and reporting functions. Commercial fleet depots in Australia's mining corridors are consolidating standalone systems into oil-major integrated platforms.
Fuel Dispensers anchors the volume base while Fuel Management Systems gains share at the steepest rate.
Technology:
Cost tier stratification separates premium edge-computing architectures from budget connectivity modules in technology adoption patterns.
- Automatic Identification:License plate recognition and driver authentication systems validate fleet transactions without manual card presentation. Indian agricultural cooperatives are deploying camera-based identification to reduce transaction friction at high-volume rural pumps.
- IoT Connectivity:Embedded cellular and mesh radio modules transmit dispenser status, transaction logs, and diagnostic alerts to central monitoring platforms. Recurring software and maintenance revenues from connected infrastructure are expanding margin pools for equipment vendors.
- Cloud-Based Solutions:Centralized fuel management dashboards aggregate data across distributed retail networks for inventory optimization and pricing coordination. German retail operators are piloting distributed edge architectures that reduce latency while preserving cloud analytics integration.
- RFID Technology:Short-range wireless tags enable hands-free fleet vehicle identification and automated billing reconciliation. Brazil's trucking corridors are standardizing RFID readers at high-flow dispensers for agricultural and logistics fleet contracts.
IoT Connectivity commands the installed base while Cloud-Based Solutions climbs the fastest.
End User:
Customer type fragmentation splits procurement authority between centralized oil-major technical standards and independent operator price sensitivity.
- Retail Outlets:Branded and independent fuel retailers operate consumer-facing pump islands with integrated payment and loyalty systems. Nigeria's network consolidation programs are converting fragmented independent sites into equipment-standardized branded operations.
- Commercial Fleets:Dedicated high-flow installations serve agricultural, mining, and logistics operators with fleet card integration and bulk dispensing capability. Australia's mining belt supports specialized high-volume contracts with telematics platform convergence.
- Oil Companies:Integrated majors specify equipment standards across owned and dealer-operated sites with centralized procurement and maintenance contracts. Technical specifications from these buyers drive industry-wide certification and connectivity requirements.
- Service Stations:Multi-brand fuel retail locations with convenience retail and quick-service food operations require extended payment terminal ecosystems and canopy monitoring integration. Kenya's urban network upgrades are incorporating refrigerant leak detection under EU F-Gas Regulation-aligned standards.
Retail Outlets anchors the volume base while Commercial Fleets expands most quickly.
Application:
Application maturity varies from commoditized fuel transfer to emerging environmental compliance monitoring with diverging margin profiles.
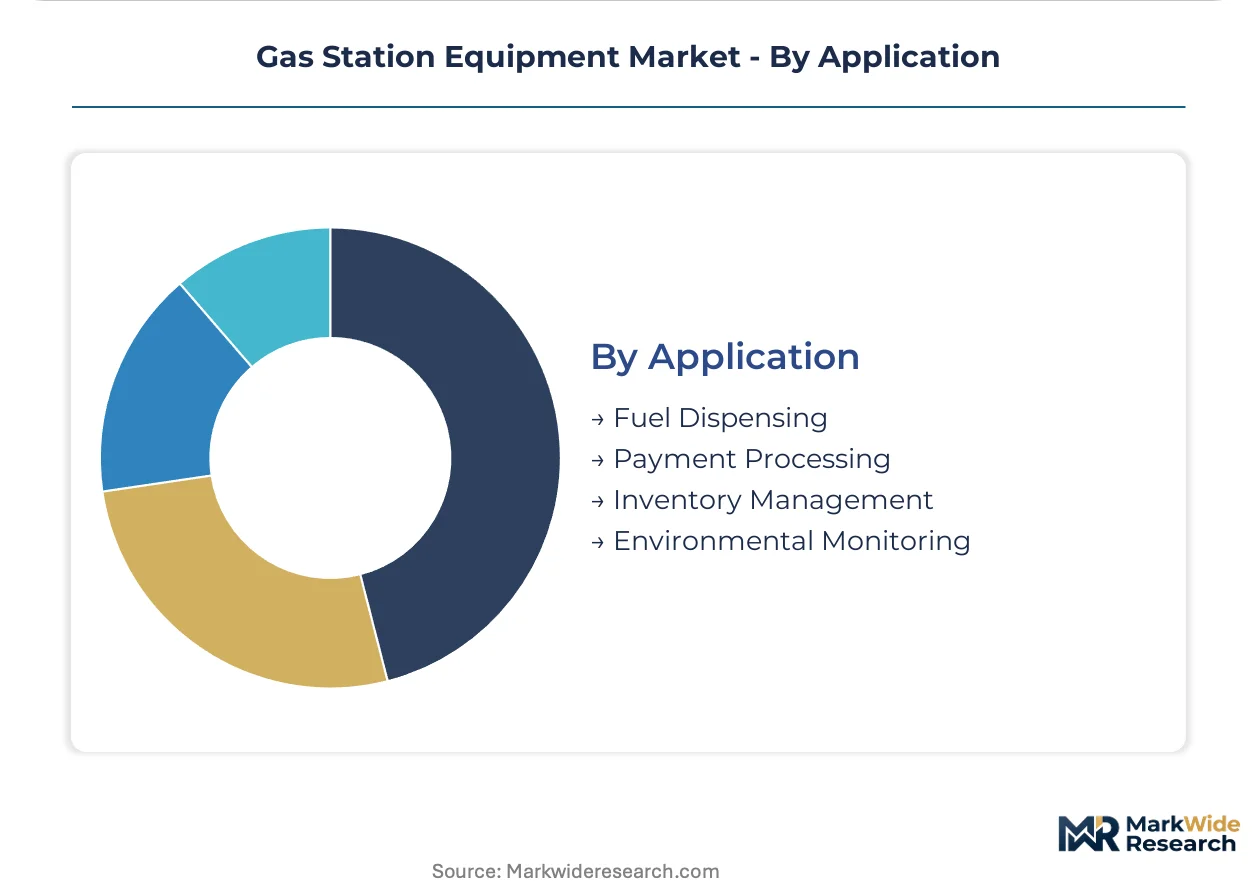
- Fuel Dispensing:The core function of hydrocarbon measurement, vapor recovery, and nozzle control at retail pump islands. Regulatory mandates in the US and EU are accelerating replacement cycles for non-compliant legacy dispenser hardware.
- Payment Processing:Transaction authorization, EMV compliance, and fleet card integration at the point of fueling. Contactless mandate deadlines in European markets are forcing terminal hardware refresh cycles.
- Inventory Management:Real-time tank level monitoring, delivery scheduling optimization, and loss prevention analytics. Cloud-based aggregation across distributed sites is attracting capital from multi-site retail operators.
- Environmental Monitoring:Vapor recovery verification, refrigerant leak detection, and groundwater protection sensor networks. EU F-Gas Regulation deadlines are driving concentrated procurement waves through French and Italian retail networks.
Fuel Dispensing anchors the volume base while Environmental Monitoring gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese equipment exports flow predominantly to Southeast Asian retail modernization programs and African network consolidation projects. India and Brazil serve as secondary manufacturing hubs supplying regional demand corridors. Equipment certification requirements diverge sharply between EPA-governed North American markets and EU F-Gas regulated European installations.
United States
EPA Phase II vapor recovery mandates are accelerating dispenser replacement cycles across the nation's largest installed base. State-level enforcement variations in California and Texas create procurement timing differentials for retail operators. The Gulf Coast refining corridor supports dense service infrastructure for tank monitoring system deployments.
China
GB standards enforcement and NMPA-equivalent fuel quality regulations are mandating intelligent dispenser upgrades across provincial retail networks. Zhejiang and Jiangsu provinces concentrate submersible turbine pump manufacturing capacity for domestic and export markets. Shanghai-based system integrators are piloting edge-computing architectures for distributed transaction processing.
Germany
EU F-Gas Regulation deadlines are driving refrigerant leak detection sensor procurement waves through 2027. KBA certification requirements for explosive atmosphere equipment create extended market entry timelines for new dispenser platforms. The Ruhr industrial region hosts specialized testing facilities for ATEX-compliant fuel management systems.
Brazil
Compressed natural gas dispenser deployment is expanding alongside conventional petroleum infrastructure for agricultural and logistics fleet operators. ANVISA-equivalent fuel quality enforcement is tightening equipment specification requirements for branded network consolidation. São Paulo state's retail modernization programs are converting independent sites into standardized operator networks.
India
Contactless payment integration mandates are pulling EMV-compliant terminal upgrades through urban and rural service stations. Agricultural cooperatives in Punjab and Haryana are deploying camera-based fleet identification systems to reduce transaction friction. The Delhi-Mumbai Industrial Corridor supports manufacturing scale for domestic dispenser production.
Gas Station Equipment Market Vendor Landscape
Listed leaders compete with private specialists across certification depth and service network reach. The vendor base stratifies between integrated platform providers and component-focused fabricators. Three archetypes dominate: telemetry-embedded system architects, manufacturing-scale cost optimizers, and regional service network anchors. M&A activity concentrates on connected infrastructure capabilities, while geographic expansion targets African and Southeast Asian network modernization programs.
Within the telemetry-embedded tier, Dover Fueling Solutions and Gilbarco Veeder-Root exemplify platform providers competing on recurring software revenue streams. Beijing Sanki Petroleum Technology Co. Ltd. occupies a position among manufacturing-scale specialists serving Asian cost-optimization requirements. Scheidt & Bachmann GmbH anchors the European precision-engineering segment with ATEX certification depth. These three represent distinct competitive vectors: connected retail infrastructure, production scale efficiency, and regulatory compliance specialization.
| Leading Market Players |
|---|
| Censtar Science and Technology Corp. Ltd. |
| Dover Fueling Solutions |
| Gilbarco Veeder-Root |
| Bennett Pump Company |
| Tokheim Group |
| Wayne Fueling Systems |
| Scheidt & Bachmann GmbH |
| Beijing Sanki Petroleum Technology Co. Ltd. |
| Tatsuno Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term equipment procurement contracts with take-or-pay clauses lock in submersible turbine pump access from Zhejiang manufacturers while anchoring price visibility against stainless steel alloy volatility. Oil majors leverage these structures to secure ATEX-certified dispenser allocations ahead of EU F-Gas compliance deadlines, insulating retail networks from spot-market electronics cost swings.
Pricing Analysis
Next-generation edge-computing dispensers command substantial premiums over legacy mechanical units and basic IoT retrofit modules. Three-tier pricing structure across premium intelligent systems, standard connected hardware, and economy mechanical tiers reflects UL/ATEX certification grade and embedded software depth. Pricing pressure stems from semiconductor component shortages compressing margins on telemetry-embedded platforms. Independent retail operators exhibit acute price sensitivity, while oil majors prioritize certification compliance and service bundling over unit economics.
Supply Chain Analysis
Port congestion along Shanghai-Ningbo corridors elevates inbound logistics costs for European-bound ATEX testing equipment and North American vapor recovery hardware. Manufacturing concentrates in China, Germany, and the United States, with submersible turbine pump fabrication anchored in Zhejiang and Jiangsu provinces. Supply chains draw from stainless steel alloys, semiconductor components, and corrosion-resistant polymers. Single-region concentration in Chinese pump production exposes continuity to logistics disruptions. Distribution runs through oil-major procurement consortiums and regional equipment distributors serving independent retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gas station equipment market sits at a platform-economics inflection where dispenser OEMs compete on API interoperability rather than hardware specifications alone. Fleet management system convergence with telematics platforms is redrawing competitive boundaries around data architecture dominance.
For Market Incumbents: Fortify connected infrastructure moats by embedding edge-computing modules deeper into dispenser architectures, displacing standalone site controllers. Accelerate backward integration into submersible turbine pump manufacturing to reduce exposure to Zhejiang supply concentration. Invest in IEC 62443 cybersecurity certification pipelines to capture scarce industrial control security talent ahead of regulatory mandates.
For New Entrants and Emerging Players: Post-warranty service coverage gaps in Sub-Saharan Africa present immediate white-space opportunity where branded network consolidation outruns incumbent service infrastructure. Target Nigeria and Kenya with localized maintenance partnerships and cloud-based remote diagnostics. Pursue hydrogen dispenser pre-positioning contracts in Germany and Japan through joint development agreements with automotive OEMs ahead of fleet scaling.
For Investors and Strategic Acquirers: Telemetry-embedded mid-tier specialists with proven API integration capabilities represent the highest-conviction acquisition archetype for platform consolidation plays. Long-term viability hinges on recurring software revenue attachment rates displacing transactional hardware margins. Monitor fleet card program consolidation velocity in Brazil's agricultural belt and Australia's mining corridors as inflection signal for B2B procurement pattern shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Module Integration | Dispenser OEMs compress hardware BOM costs while elevating software maintenance contract values across German retail pilots. |
| Backward Integration into Pump Manufacturing | Vertical control over submersible turbine production reduces Zhejiang supply concentration exposure for North American market leaders. |
| IEC 62443 Certification Pipeline Investment | Cybersecurity compliance for connected dispensers captures scarce industrial control engineering talent ahead of regulatory deadlines. |
| Hydrogen Dispenser Pre-Positioning Partnerships | Early infrastructure deployment in Germany and Japan secures first-mover installation contracts before vehicle fleet scaling. |
| API-First Fleet Management Convergence | Integration between fuel management systems and telematics platforms opens recurring software revenue streams for dispenser OEMs. |
Methodological Framework
The analysis maps fuel dispenser hardware, tank monitoring systems, payment terminal ecosystems, and fuel management software, each validated through equipment procurement directors at oil majors, aftermarket service heads at regional distributors, and regulatory compliance officers at certification bodies. Primary interviews with retail network operators and fleet depot managers combined with secondary validation from EPA enforcement databases, EU F-Gas Regulation filings, and customs trade records. Bottom-up unit shipment modeling triangulates against top-down retail network modernization expenditure tracking.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework segments by product type, technology tier, end-user procurement authority, and application maturity, with regional regulatory divergence as an overlay dimension. CAGRs derive from replacement cycle acceleration curves and alternative fuel infrastructure deployment trajectories. Forecast inputs incorporate EPA Phase II mandate enforcement timing and EU F-Gas Regulation compliance deadlines without year-specific anchoring.
Forecasts assume regulatory continuity in EPA vapor recovery regimes and EU F-Gas enforcement; material policy shifts would require re-modeling. Supply disruption scenarios in Chinese manufacturing clusters and semiconductor availability constraints represent specific revision triggers. Recalibration cycles align with material shifts in fleet electrification pace and hydrogen infrastructure commitment levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Steel and Rubber Tracks Market
Vehicle Components
Fuel Sensor Market
Vehicle Components
Forestry Trailers Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
Motorcycle Side Box Market
Vehicle Components
2 Wheeler Fuel Tank Market
Vehicle Components
Global Automotive Carbon Monocoque Chassis Market
Vehicle Components
Piston Market
Vehicle Components
Electric Vehicle High Voltage Connector System Market
Vehicle Components
Refrigerated Trailer Door Lock Market
Vehicle Components
Bicycle Chain Market
Vehicle Components
Bicycle Chain Device Market
Vehicle Components
Steering Column Cowls Market
Vehicle Components
Steer-by-Wire Road Wheel Actuator Modules Market
Vehicle Components
Wheel Loaders Market