
 Trailer Terminal Tractor Market | 2026-2036
Trailer Terminal Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Trailer Terminal Tractor Market Analysis
Steel is decoupling from chassis economics as high-strength aluminum alloys reduce unladen weight in next-generation terminal tractors. Kalmar leverages its port equipment integration expertise to anchor electrified tractor-to-crane workflows. Konecranes sustains technology leadership through automated guided tractor development. Terberg Special Vehicles dominates niche applications with its multi-fuel platform specialization.
A trailer terminal tractor is a purpose-built low-speed vehicle with a fifth-wheel coupling, typically rated for 30–50 ton gross combination weight, designed for shunting semi-trailers within confined freight terminals and distribution yards. Diesel configurations retain the largest installed base, though electric variants represent the fastest-expanding vehicle type segment as port operators face zero-emission mandates. Heavy-duty capacity classes command the strongest margin pools due to specialized axle and driveline requirements. Automated operation mode adoption is accelerating at greenfield logistics sites where warehouse and shipping end users seek labor optimization.
EPA emission standards for off-road diesel engines and EU Green Deal port decarbonization targets are tightening product certification requirements across North America and Europe. China's MIIT dual carbon goals and GB standards for new energy commercial vehicles are redirecting procurement toward battery-electric platforms in Asia. Stakeholders must monitor regulatory phase-in timelines and charging infrastructure readiness before committing to fleet electrification strategies.
Market Dynamics
Port electrification mandates are forcing terminal operators to retire diesel yard tractors ahead of scheduled replacement cycles, compressing fleet turnover timelines and redirecting capital toward charging infrastructure and battery-electric platforms.
Growth Catalysts
- EU Green Deal port decarbonization targets:European terminal operators face binding emission reduction deadlines that accelerate procurement of zero-emission yard equipment. Battery-electric terminal tractors satisfy compliance requirements while maintaining operational uptime in high-throughput container terminals.
- Automated container handling infrastructure:Greenfield port developments in China integrate autonomous tractor-to-crane workflows that demand electrified drivetrains for precise speed control and telematics integration.
- High-strength aluminum chassis alloys:Reduced unladen weight extends electric range and payload capacity, improving total cost of ownership calculations for fleet managers evaluating platform conversions.
Market Restraints
- Lithium-ion battery supply concentration:Cathode material processing and cell manufacturing cluster in China, exposing non-Chinese terminal operators to geopolitical supply disruption and input cost volatility.
- EPA Tier 4 Final compliance costs:Remaining diesel platform development requires exhaust aftertreatment systems that erode margin pools on low-volume specialty chassis production.
- Charging infrastructure capex intensity:Megawatt-class shore power connections and on-yard fast-charging stations demand grid upgrades that strain port authority capital budgets.
Strategic Opportunities
- India port modernization:Jawaharlal Nehru Port Trust and Mundra Port expansion projects create first-mover advantage for electric terminal tractor suppliers establishing local assembly partnerships.
- Battery-as-a-service procurement models:Fleet operators lease battery packs separately from chassis assets, transferring degradation risk to energy suppliers and smoothing capital expenditure profiles.
- Automated guided tractor convergence:Integration of lidar-based navigation with electric drivetrains enables nighttime and low-visibility operations at distribution yards seeking labor optimization.
Industry Challenges
- High-voltage technician scarcity:Maintenance organizations lack certified personnel for 600V+ battery pack diagnostics and repair, extending downtime events and inflating service contract costs.
- Homologation timeline compression:Dual certification for on-road and off-road operation in multiple jurisdictions delays product launches and fragments engineering resources across regulatory variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trailer Terminal Tractor Market |
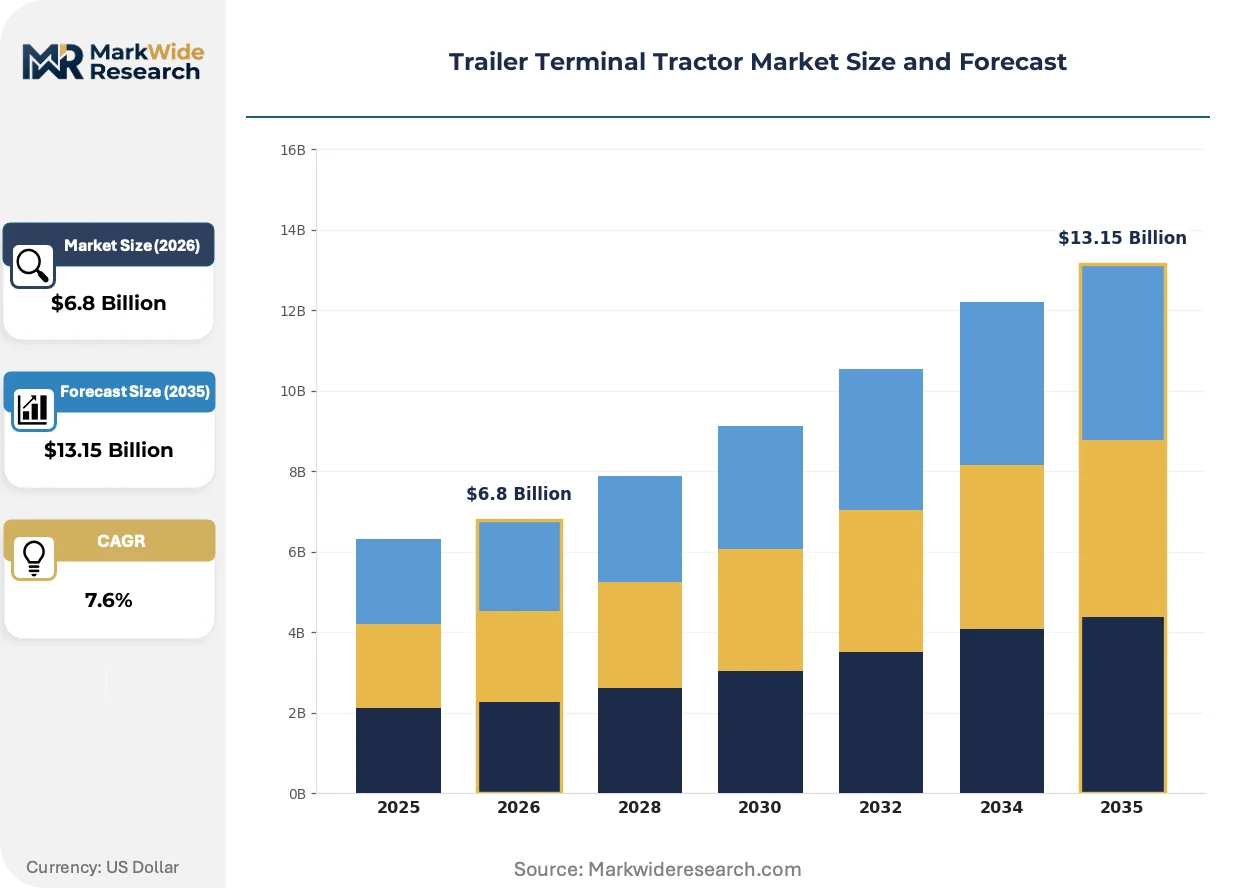
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Electric, Diesel, Hybrid, LPG Operation Mode: Manual, Automated, Semi-Automated, Remote-Controlled End User: Logistics, Warehousing, Shipping, Distribution Capacity: Light-Duty, Medium-Duty, Heavy-Duty, Super Heavy-Duty |
| Companies Covered | Kalmar, Konecranes, Terberg Special Vehicles, Capacity Trucks, TICO Tractors, MAFI Transport-Systeme, Linde Material Handling, Autocar, BYD Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trailer Terminal Tractor Market Emerging Trajectories
Electrification is rewriting terminal tractor architecture as battery pack placement and thermal management displace legacy engine bay layouts. Three convergent developments are reshaping product roadmaps and procurement criteria.
High-voltage battery-electric drivetrains are consolidating around standardized 350V and 800V architectures that simplify component sourcing and service training. European port operators in Rotterdam and Hamburg lead adoption, with North American terminals at Los Angeles and Long Beach following under CARB pressure. This voltage standardization is consolidating supplier tiers as Tier 2 component houses merge or exit rather than engineer for fragmented power levels.
China's MIIT dual carbon goals and GB standards for new energy commercial vehicles mandate zero-emission yard equipment procurement at state-controlled port clusters. Domestic manufacturers gain preference in Shenzhen and Ningbo-Zhoushan tenders, compressing market access for foreign chassis suppliers. Heavy-duty capacity classes face the steepest compliance thresholds, accelerating local content requirements and joint venture formation.
Fleet managers now specify telematics-enabled predictive maintenance contracts that unbundle hardware procurement from uptime guarantees. Third-party logistics providers at Memphis and Chicago intermodal yards favor outcome-based service agreements over traditional capital purchase models. This contracting evolution is most advanced in North American distribution centers where labor cost pressure and chassis utilization tracking justify subscription economics.
Trailer Terminal Tractor Market Segmentation
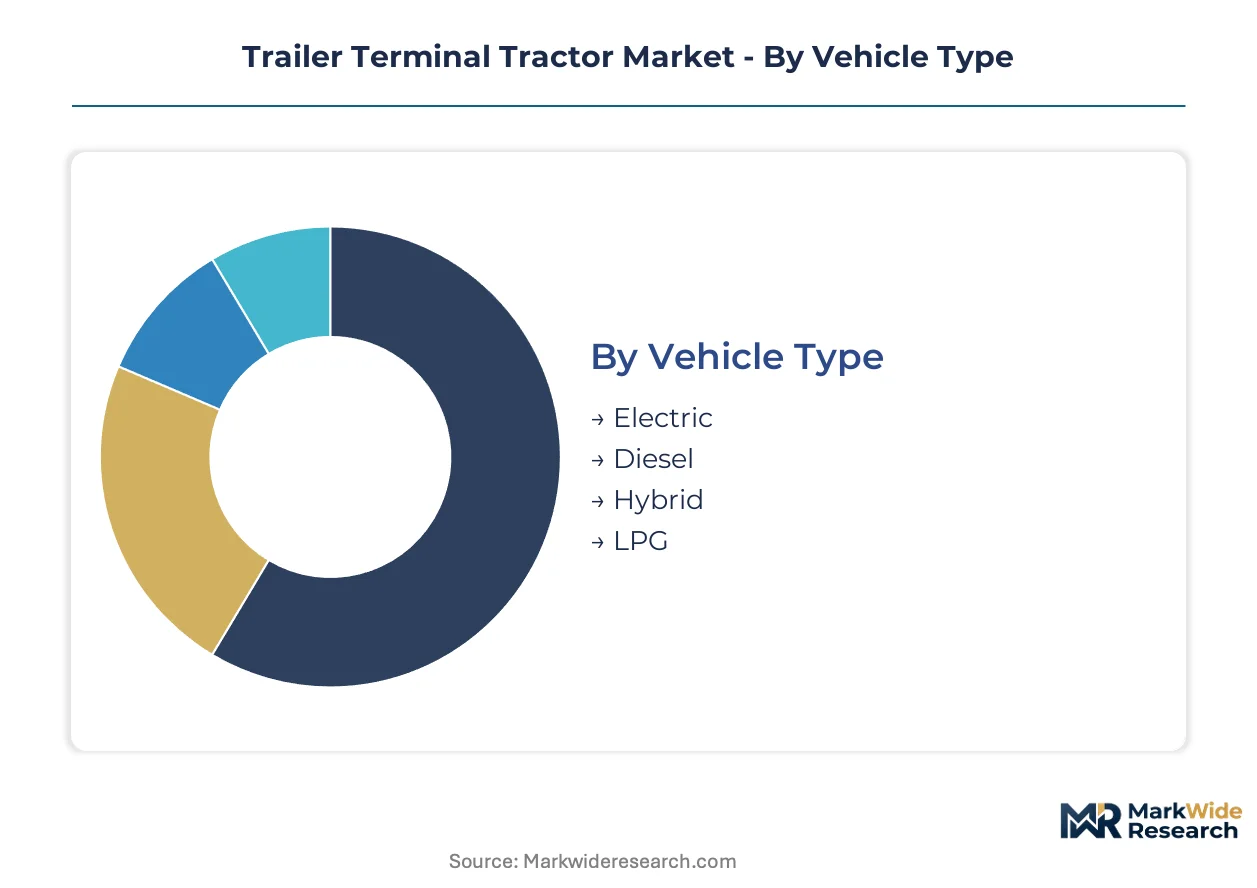
Terminal tractor procurement decisions hinge on powertrain selection, operational automation level, and capacity class. Fleet managers balance upfront capital requirements against total cost of ownership across divergent duty cycles and regulatory environments.
Vehicle Type:
Capital-intensity varies sharply across powertrain architectures, with electric platforms demanding the highest upfront investment for battery packs and charging infrastructure.
- Electric:High-voltage battery-electric drivetrains utilize 350V or 800V architectures with lithium-ion packs mounted beneath the cab or along the chassis rails. Demand concentrates at Rotterdam, Hamburg, Los Angeles, and Long Beach terminals facing binding zero-emission mandates from EU Green Deal and CARB regulations; fleet operators absorb elevated chassis premiums to avoid future retrofit costs and secure port access permits.
- Diesel:Compression-ignition engines with EPA Tier 4 Final or Euro Stage V aftertreatment systems retain dominance at inland distribution yards lacking megawatt-class shore power. Procurement persists where charging infrastructure capex strains capital budgets and where duty cycles exceed electric range envelopes.
- Hybrid:Diesel-electric parallel architectures capture intermittent-duty applications at mid-sized ports transitioning toward full electrification.
- LPG:Liquefied petroleum gas conversions serve niche markets seeking moderate emission reductions without grid dependency.
Most installed capacity flows through Diesel. Expansion is steepest in Electric.
Operation Mode:
Automation intensity determines software stack complexity and sensor integration costs, with fully autonomous systems requiring the most engineering investment per unit.
- Manual:Human-operated tractors with conventional cab layouts and mechanical controls constitute the baseline configuration. Demand persists at smaller warehousing and distribution facilities where labor availability remains adequate and automation capex cannot be justified against utilization rates; operators prioritize proven reliability over technology risk.
- Automated:Lidar and camera-based autonomous navigation enables unmanned tractor-to-crane workflows at greenfield container terminals. Adoption concentrates at Shenzhen and Ningbo-Zhoushan port clusters where MIIT dual carbon goals and GB standards mandate integrated electrified automation.
- Semi-Automated:Driver-assist features including automated hitching and precision docking reduce operator fatigue at high-throughput logistics hubs.
- Remote-Controlled:Teleoperation architectures address hazardous cargo handling and nighttime operations with reduced on-site staffing.
Manual operation retains the largest fleet share. Automated systems are gaining share fastest.
End User:
Application environment shapes specification requirements, with shipping terminals demanding the most ruggedized chassis and corrosion-resistant components.
- Shipping:Marine-grade terminal tractors face salt spray exposure and continuous heavy-load cycling at container berths. Procurement concentrates at Jawaharlal Nehru Port Trust and Mundra Port expansion projects in India, where modernization programs seek electric platforms for compliance with emerging port authority emission guidelines.
- Logistics:Intermodal yard operations at Memphis and Chicago rail hubs prioritize rapid trailer exchange and telematics-enabled fleet tracking.
- Warehousing:Indoor and adjacent-yard duties favor compact turning radii and low-noise electric configurations.
- Distribution:E-commerce fulfillment centers specify high-uptime contracts with predictive maintenance unbundled from hardware purchase.
Shipping terminals deploy the most units. Distribution centers are expanding fleet orders most aggressively.
Capacity:
Axle and driveline specialization drives manufacturing cost escalation, with super heavy-duty platforms commanding the steepest engineering premiums.
- Heavy-Duty:30–50 ton gross combination weight ratings with reinforced fifth-wheel couplings and multi-axle configurations dominate container terminal specifications. Demand concentrates in China where state-controlled port clusters scale automated handling infrastructure and where domestic manufacturers gain preference through local content requirements under MIIT procurement guidelines.
- Super Heavy-Duty:Specialized chassis for oversized loads and abnormal cargo configurations serve project cargo terminals and heavy manufacturing logistics.
- Medium-Duty:Reduced axle ratings address lighter container weights and shorter haul distances at regional distribution facilities.
- Light-Duty:Compact tractors for single-axle trailers and urban freight consolidation points prioritize maneuverability over raw pulling capacity.
Heavy-Duty capacity classes carry the largest installed base. Super Heavy-Duty applications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Ningbo-Zhoushan port cluster anchors terminal tractor procurement volume as state-controlled terminals scale automated container handling infrastructure under MIIT dual carbon mandates. Fleet electrification timelines compress across major economies as port decarbonization regulations harden.
United States
Los Angeles and Long Beach terminals drive electric tractor adoption under CARB zero-emission mandates for drayage equipment. EPA Tier 4 Final compliance costs burden remaining diesel platform development. Memphis and Chicago intermodal yards prioritize telematics-enabled fleet tracking for rapid trailer exchange operations.
Germany
Hamburg and Bremerhaven container terminals anchor European electrification demand under EU Green Deal port decarbonization targets. ECHA chemical registration requirements shape battery material sourcing protocols. Industrial clusters along the North Sea coast integrate shore power connections for megawatt-class charging infrastructure.
China
Shenzhen and Ningbo-Zhoushan port clusters scale automated tractor-to-crane workflows under MIIT dual carbon goals and GB standards for new energy commercial vehicles. Domestic manufacturers gain procurement preference through local content requirements. Heavy-duty capacity classes face the steepest compliance thresholds.
India
Jawaharlal Nehru Port Trust and Mundra Port expansion projects create demand concentration for electric terminal tractors as emerging port authority guidelines tighten emission standards. BIS certification requirements for commercial vehicle imports shape supplier qualification timelines. Western coastal logistics corridors prioritize modernization funding.
Netherlands
Rotterdam terminal operators lead European battery-electric adoption under binding EU Green Deal emission reduction deadlines. REACH chemical regulations govern battery pack material compliance. The Randstad logistics cluster integrates predictive maintenance contracts unbundled from hardware procurement.
Trailer Terminal Tractor Market Vendor Landscape
Portfolio diversification dominates the current landscape as incumbents restructure around electrified drivetrains and automation software stacks. The vendor base organizes into three tiers: integrated port equipment specialists, chassis-focused fabricators, and battery-electric technology entrants. Strategic archetypes include full-stack automation integrators, multi-fuel platform specialists, and regional assembly partners. M&A activity concentrates on charging infrastructure assets and autonomous navigation software. Geographic expansion through joint ventures accelerates in China and India to satisfy local content mandates.
Among integrated port equipment specialists, Kalmar and Konecranes occupy positions that exemplify the automation-anchored archetype, leveraging crane-to-tractor workflow integration. Terberg Special Vehicles represents the multi-fuel platform specialization tier, serving niche duty cycles with flexible powertrain configurations. BYD Company Limited anchors the battery-electric technology entrant segment, bringing high-volume cell manufacturing scale to terminal tractor applications.
| Leading Market Players |
|---|
| Kalmar |
| Konecranes |
| Terberg Special Vehicles |
| Capacity Trucks |
| TICO Tractors |
| MAFI Transport-Systeme |
| Linde Material Handling |
| Autocar |
| BYD Company Limited |
| Others |
Supply Flow & Price Mechanics
EU Green Deal port decarbonization mandates are compressing fleet replacement cycles and forcing terminal operators toward battery-electric platforms, which concentrates procurement power among chassis suppliers capable of integrating high-voltage drivetrains and charging infrastructure partnerships. This demand-side specification shift is redrawing margin pools across supplier tiers as legacy diesel fabricators absorb Tier 4 Final compliance costs while electrification specialists capture premium positioning.
Pricing Analysis
Input-cost pass-through from lithium-ion cathode materials and high-strength aluminum chassis alloys is intensifying pricing pressure on electric platform tiers. Battery-electric terminal tractors command three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by automation software integration and fast-charging capability certification. Cost compression in standard-tier diesel configurations is eroding margins due to EPA aftertreatment system requirements. Shipping terminals show lowest price sensitivity given compliance-driven procurement urgency, while inland distribution yards retain higher elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cathode material processing and cell manufacturing clusters, which anchor global lithium-ion supply for terminal tractor battery packs. Manufacturing concentration in China, South Korea, and Japan feeds downstream assembly operations in Germany and the United States. Raw material dependencies span lithium carbonate, nickel sulfate, and high-grade aluminum billet. Tariff exposure on Chinese battery components presents structural risk. Distribution runs through port equipment OEM direct sales channels and regional dealer networks serving terminal operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in terminal tractors rests on aluminum chassis weight reduction and predictive maintenance contract unbundling, which shifts revenue toward recurring service streams and defends pricing power against commodity battery cost volatility.
For Market Incumbents: To counter BYD's cell manufacturing scale and domestic procurement preference in China, Kalmar and Konecranes should deepen backward integration into autonomous navigation software stacks while securing megawatt-class charging infrastructure joint ventures at Rotterdam and Los Angeles port clusters. Certification investment in EU Green Deal compliance pathways preserves access to Hamburg and Bremerhaven tenders. For New Entrants and Emerging Players: Digital-channel routes through telematics-enabled fleet management platforms offer the most penetrable entry vector for mid-sized intermodal yards at Memphis and Chicago seeking subscription-based uptime guarantees. White-space targets include battery-as-a-service procurement models for capital-constrained Indian port operators at Jawaharlal Nehru Port Trust, plus automated guided tractor retrofits for existing manual fleets. For Investors and Strategic Acquirers: Asymmetric upside sits with autonomous navigation software specialists capable of lidar-based yard automation integration. Long-term viability favors targets with demonstrated port equipment workflow integration rather than pure chassis fabricators. The signal to watch is CARB zero-emission mandate enforcement intensity at California terminals, which would accelerate electric platform conversion timelines and revalue charging infrastructure assets.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures lithium-ion cell allocation from CATL or LG Energy Solution for 800V platform production. |
| Charging Infrastructure Partnership | Establishes megawatt-class shore power connections at Rotterdam and Long Beach terminal clusters. |
| Autonomous Navigation Acquisition | Integrates lidar-based yard automation software for unmanned tractor-to-crane workflows. |
| Joint Venture Formation | Satisfies MIIT local content requirements for Ningbo-Zhoushan and Shenzhen port tenders. |
| Predictive Maintenance Platform Launch | Unbundles hardware procurement from uptime guarantees for Memphis distribution center operators. |
Methodological Framework
Multiple input streams — terminal operator procurement directors, port authority infrastructure planners, battery system engineering leads, and aftermarket service heads — were reconciled against customs trade data, EPA certification filings, and EU Green Deal implementation trackers. Secondary validation drew from MIIT policy bulletins, CARB regulatory dockets, and container terminal automation project disclosures. Bottom-up chassis shipment estimates and top-down port capital expenditure analysis were triangulated to anchor volume projections.
Data-stream reconciliation across powertrain architecture, operational automation level, and capacity class segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from fitted adoption curves incorporating regulatory phase-in schedules and charging infrastructure deployment timelines. Industry-specific forecast inputs included port electrification mandate compliance deadlines and battery pack cost learning curves.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for electric range specifications and charging infrastructure capex requirements. Forecasts reflect assumptions regarding lithium supply expansion and aluminum alloy processing capacity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
Bicycle Frames Market
Vehicle Components
High Security Registration Plates Market
Vehicle Components
Intelligent Rubber Tracks Market
Vehicle Components
Russia Automotive Composites Market
Vehicle Components
Railroad Equipment Manufacturing Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Hydraulic Actuators Market
Vehicle Components
Saudi Arabia Car Rental and Leasing Market
Vehicle Components
Charge Air Coolers Market
Vehicle Components
Passenger Car Sensors Market
Vehicle Components
Latin America Automotive Connectors Market
Vehicle Components
Steel and Rubber Tracks Market
Vehicle Components
Locomotive Pantographs Market
Vehicle Components
Crash Lock Box Market
Vehicle Components
Bicycle Brake Cable Market