
 Oil Filter Elements Market | 2026-2036
Oil Filter Elements Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Filter Elements Market Analytics
Asset-light leasing models for filtration infrastructure is reconfiguring competitive entry barriers across the oil filter elements supply base. Mann+Hummel Group leverages captive R&D campuses in Germany to sustain technology leadership in synthetic media formulations. Donaldson Company anchors its position through backward integration into pleated media manufacturing, controlling raw material quality from fiber to finished element. MAHLE GmbH specializes in compact cartridge architectures designed for downsized powertrains, occupying a premium niche among European automakers.
Oil filter elements are cylindrical or disc-shaped porous media assemblies, typically constructed from resin-bonded cellulose, synthetic microfibers, or sintered metal meshes with nominal micron ratings between 10 and 40, engineered to remove particulate contaminants from lubricating oil circuits in internal combustion engines and industrial hydraulic systems. The cartridge product type leads unit volume globally due to OEM preference for serviceable designs that reduce metal waste versus spin-on alternatives. Synthetic material formulations represent the fastest-expanding segment as fleet operators demand extended drain intervals and thermal stability under turbocharged engine loads. The large size category commands disproportionate margin contribution from mining and marine applications where custom housing dimensions and high dirt-holding capacity justify premium positioning.
The EPA enforces filtration efficiency benchmarks for heavy-duty on-highway engines under its evolving emission control framework, while ISO 4548-12 governs laboratory validation of lubricating oil filter performance across international supply chains. In Europe, the EU Green Deal's circular economy requirements are pressuring manufacturers to design cartridge elements with separable metal and polymer components for end-of-life recycling. Stakeholders must monitor how regulatory divergence between EPA and EU Green Deal filtration mandates reshapes product platform standardization and regional manufacturing footprint decisions.
Market Dynamics
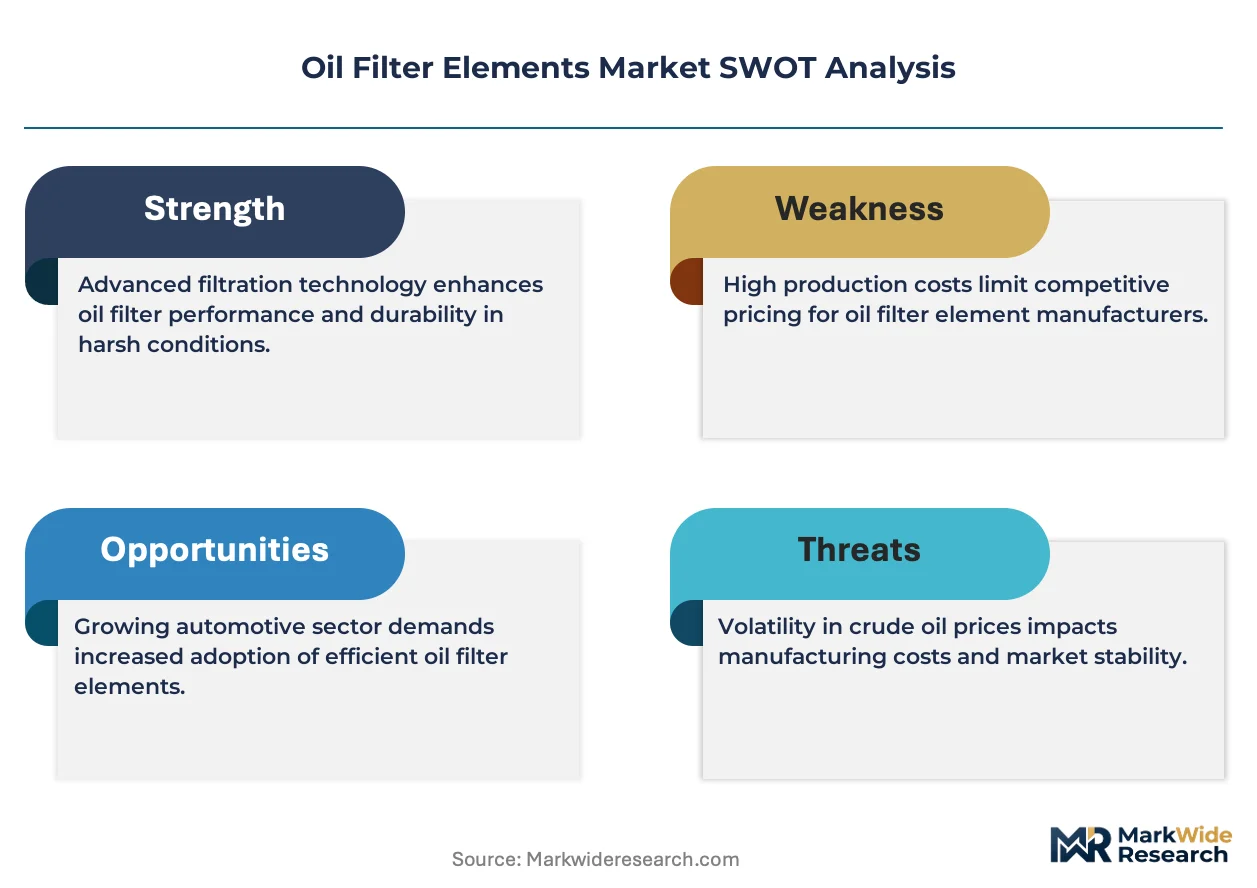
Fleet operators in North America and Europe are compressing oil change intervals while simultaneously demanding higher dirt-holding capacity, forcing filter manufacturers to reconcile contradictory performance specifications without passing cost burdens downstream.
Growth Catalysts
- EPA heavy-duty emission standards:Tightening filtration efficiency mandates for on-highway engines are compelling OEMs to specify higher-performance synthetic media, expanding addressable premium volume.
- Turbocharged engine penetration:Thermal loads from forced induction systems degrade conventional cellulose faster, accelerating fleet migration toward thermally stable synthetic formulations.
- German automotive supplier density:Concentration of OEM engineering centers in Stuttgart and Munich creates specification pull-through that radiates across European procurement networks.
Market Restraints
- Cellulose fiber cost volatility:Pulp price swings tied to Nordic forestry harvest cycles compress margin predictability for commodity-grade filter producers.
- Single-source pleated media concentration:Three specialized nonwoven producers control majority supply of high-efficiency synthetic substrate, creating bottleneck risk.
- Extended drain interval engineering:OEM lubricant formulations achieving 50,000+ mile service life directly reduce per-vehicle filter consumption velocity.
Strategic Opportunities
- Indian commercial vehicle aftermarket:Underpenetrated service infrastructure and accelerating freight corridor development create whitespace for cartridge-format education and distribution buildout.
- EU Green Deal circular economy mandates:Separable-component design requirements favor manufacturers with advanced polymer-metal separation capabilities, rewarding early compliance investment.
- Condition-monitoring integration:Convergence of IoT pressure sensors with filter housings enables predictive maintenance bundling, shifting revenue from product to service.
Industry Challenges
- ISO 4548-12 validation timelines:Extended laboratory certification cycles for new media formulations delay product launch windows and tie up R&D capital.
- Legacy housing dimensional fragmentation:Proprietary cartridge interfaces across OEM platforms prevent economies of scale in mold tooling and inventory pooling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Filter Elements Market |
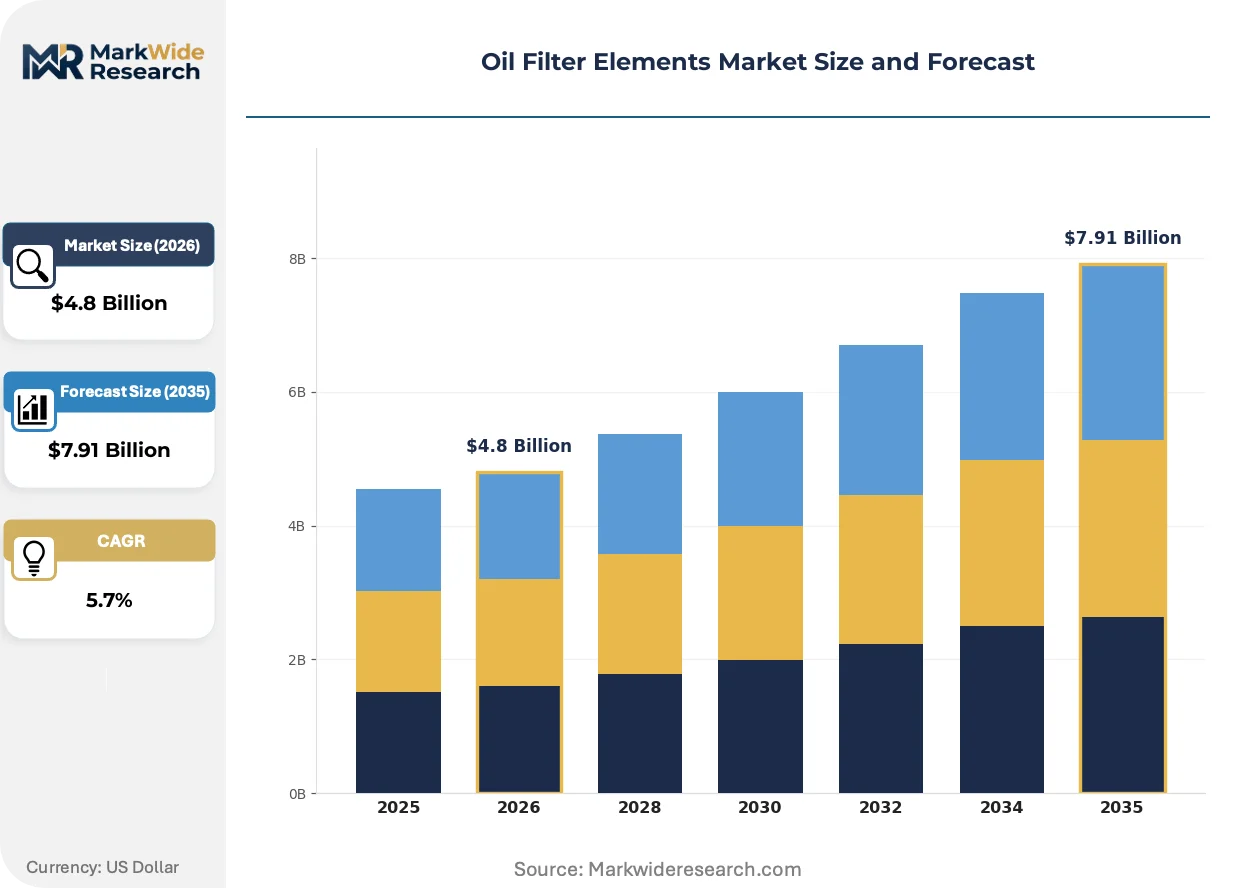
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cartridge, Spin-On, Remote, Magnetic End User: Automakers, Oil Change Services, Fleet Operators, Maintenance Shops Material: Paper, Synthetic, Metal, Fiberglass Size: Compact, Standard, Large, Custom |
| Companies Covered | Mann+Hummel Group, MAHLE GmbH, Donaldson Company, Inc., Ahlstrom Corporation, Sogefi SpA, Hengst SE & Co. KG, FRAM Group, Denso Corporation, Parker Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Filter Elements Market Evolving Landscape
Material science advances and embedded intelligence are reconfiguring how filter performance is validated, monetized, and integrated into broader vehicle health ecosystems. These developments favor suppliers with captive testing infrastructure and software development capabilities.
Multilayer synthetic media is hybridizing cellulose and glass microfiber substrates to achieve gradient density structures that capture finer particles without flow restriction penalties. Mining operators in Western Australia are specifying these constructions for hydraulic systems operating in high-silica environments. The technology is hybridizing traditional commodity filter categories into application-specific premium tiers that command specification-based rather than price-based procurement.
EU Green Deal circular economy requirements are mandating separable metal-polymer construction for end-of-life recycling, forcing redesign of cartridge architectures that previously relied on permanent bonding. Manufacturers with advanced disassembly tooling and material traceability systems capture preferential supplier status from German and French OEMs. Heavy-duty applications face the steepest compliance cost due to larger metal housings and specialized seal compounds.
Fleet maintenance departments are unbundling filter procurement from bundled service contracts, establishing direct relationships with specialized distributors for high-volume categories. This disintermediation compresses distributor margins while rewarding manufacturers with configure-to-order capability and regional logistics density. The pattern is most pronounced among North American Class 8 truck operators with centralized procurement functions and standardized maintenance protocols.
Oil Filter Elements Market Segmentation
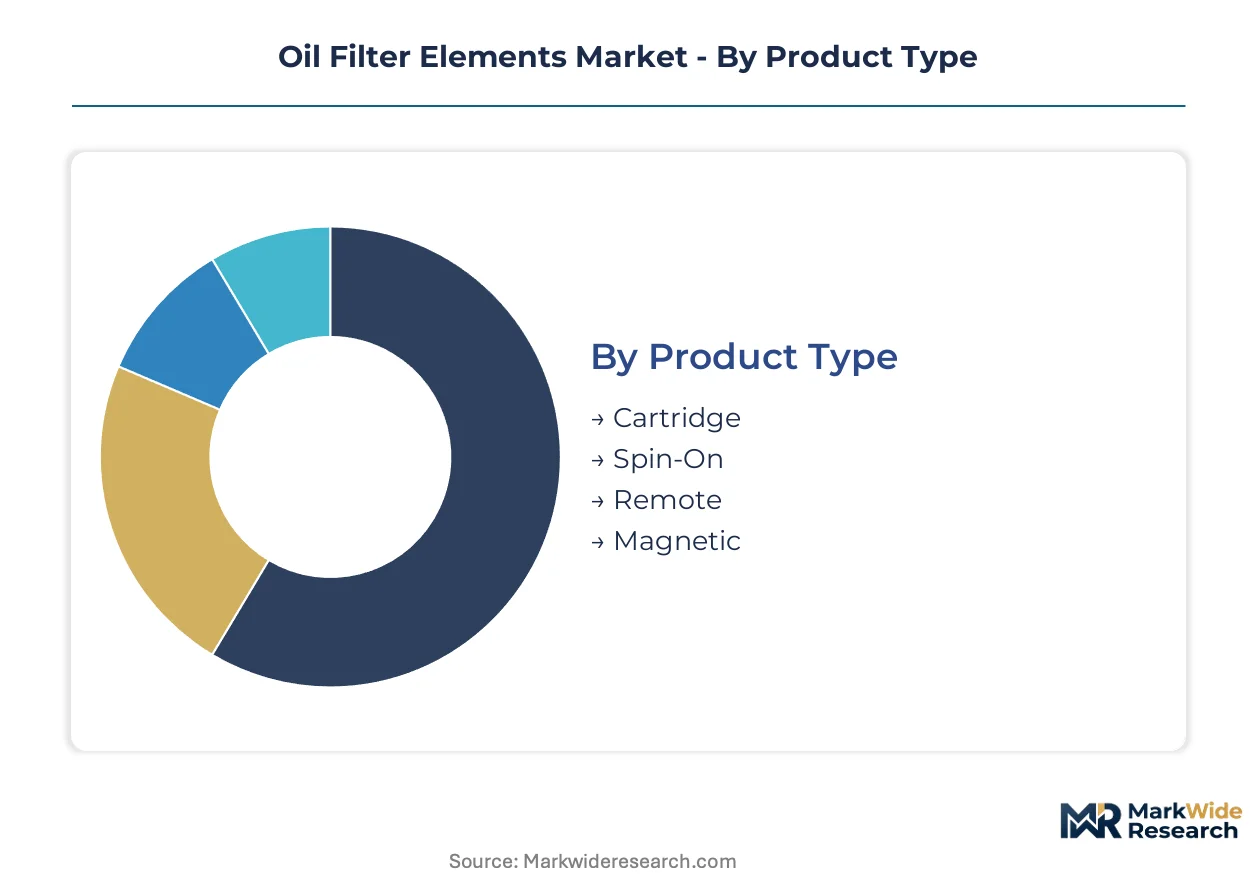
Segmentation in the oil filter elements market reveals how procurement patterns diverge between OEM specification chains and fragmented aftermarket channels. Understanding these splits enables manufacturers to align R&D investment with the service intensity and margin structure of each customer cluster.
Product Type:
After-sales service intensity varies sharply across product formats, with cartridge designs demanding higher technical support than sealed spin-on alternatives.
- Cartridge:Serviceable cylindrical media assemblies with separable housings dominate OEM fitment for passenger vehicles. Fleet operators in Germany specify these designs to reduce metal waste and comply with EU Green Deal circular economy mandates for end-of-life recycling.
- Spin-On:Self-contained metal-canister units with integral sealing gaskets prevail in quick-lube service bays across the United States. The EPA's heavy-duty emission standards are tightening filtration efficiency requirements for these formats in on-highway applications.
- Remote:Externally mounted filter housings connected by hydraulic lines serve specialized industrial and marine installations.
- Magnetic:Ferrous particle capture elements extend primary filter life in high-wear mining equipment operating in Western Australia.
By volume, Cartridge leads. By growth pace, Remote is climbing the fastest as hydraulic system complexity increases in off-highway machinery.
End User:
Cost tier stratification separates specification-bound OEM supply from price-sensitive independent aftermarket procurement.
- Automakers:Vehicle manufacturers mandate exacting media performance validated to ISO 4548-12 protocols for factory fill and authorized service networks. Stuttgart-based engineering centers specify synthetic formulations for downsized turbocharged powertrains.
- Fleet Operators:Centralized procurement functions at North American Class 8 truck carriers compress oil change intervals while demanding extended dirt-holding capacity. These buyers disintermediate traditional distributors to establish direct manufacturer relationships.
- Oil Change Services:Quick-lube chains prioritize inventory velocity and standardized SKUs across high-volume service locations.
- Maintenance Shops:Independent repair facilities balance part availability against margin compression from bundled service pricing.
By revenue contribution, Automakers capture the premium tier. By expansion trajectory, Fleet Operators are gaining share fastest through procurement centralization.
Material:
Application severity and thermal load dictate material selection across passenger, commercial, and industrial duty cycles.
- Synthetic:Glass microfiber and polymer-blend substrates achieve gradient density structures for fine particle capture without flow restriction. Mining hydraulic systems in high-silica environments specify these constructions for extended service intervals.
- Paper:Resin-bonded cellulose remains the cost baseline for standard passenger vehicle applications. Nordic pulp price volatility compress margin predictability for commodity-grade producers dependent on this feedstock.
- Metal:Sintered stainless steel meshes withstand extreme thermal cycling in performance and racing applications.
- Fiberglass:Borosilicate microfiber layers provide chemical resistance in specialized industrial process equipment.
By installed base, Paper dominates. By technology transition, Synthetic is expanding most quickly as turbocharged engine penetration accelerates fleet migration.
Size:
Margin concentration correlates with dimensional customization requirements and dirt-holding capacity specifications.
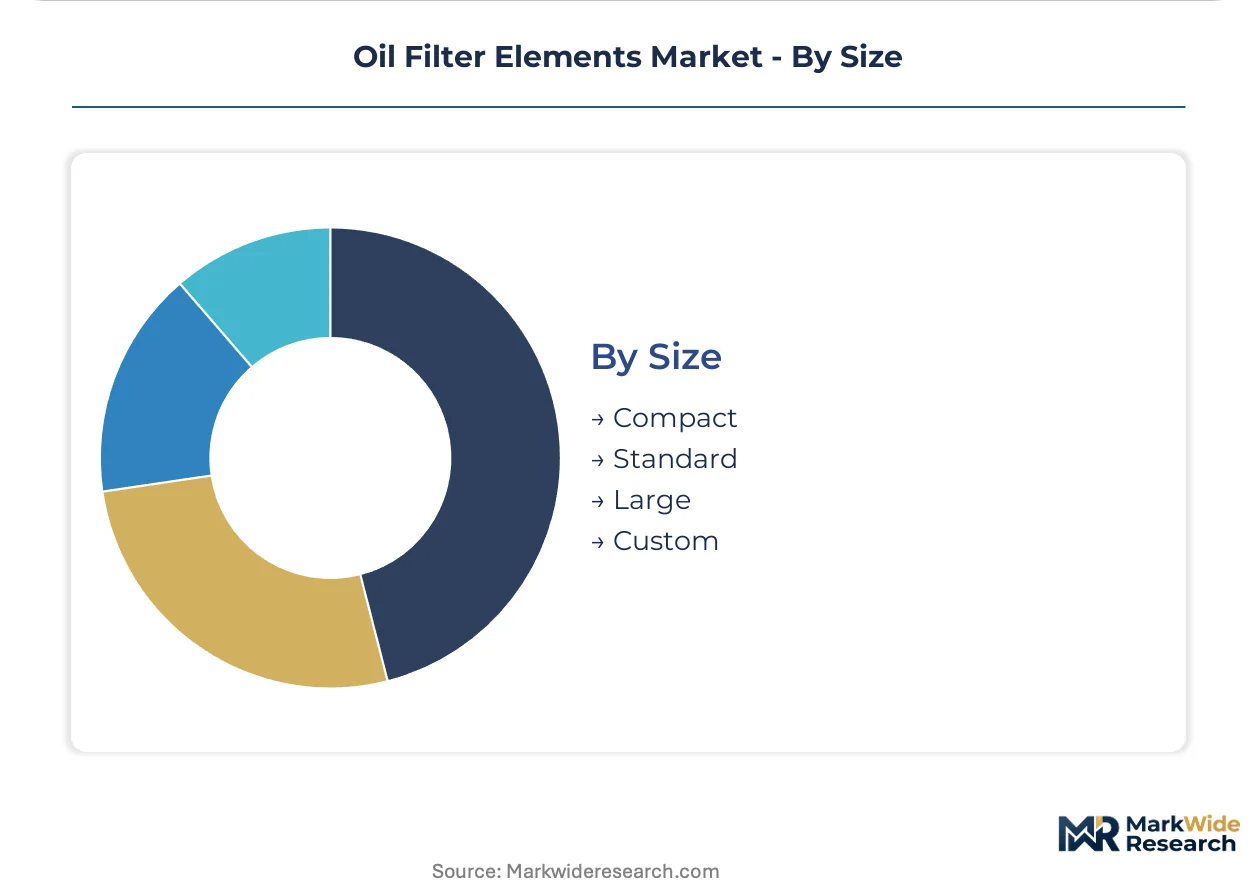
- Large:Custom-diameter cartridges for mining haul trucks and marine propulsion systems command premium positioning due to specialized housing dimensions and high contaminant capacity. Western Australian iron ore operators specify these for hydraulic circuits exposed to abrasive silica.
- Compact:Reduced-diameter designs accommodate downsized powertrain packaging in European passenger vehicles. MAHLE GmbH specializes in these architectures for premium German automakers.
- Standard:Conventional dimensions serve the broad aftermarket replacement demand across light-duty vehicle parc.
- Custom:Proprietary interfaces for specific OEM platforms prevent cross-application inventory pooling.
By unit volume, Standard leads. By margin contribution, Large is ahead due to engineering intensity and low price elasticity in resource extraction applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emission mandates and EU circular economy directives are redrawing procurement specifications across major automotive manufacturing clusters. Fleet operators in industrialized markets compress service intervals while demanding higher dirt-holding capacity from filter suppliers.
United States
Class 8 truck fleet operators centralize procurement functions to negotiate direct manufacturer relationships, bypassing traditional distribution tiers. EPA heavy-duty engine emission standards tighten filtration efficiency benchmarks for on-highway applications. Detroit-based engineering centers specify synthetic media formulations for turbocharged powertrains serving North American freight corridors.
Germany
OEM specification density around Stuttgart and Munich creates procurement pull-through across European supplier networks. EU Green Deal circular economy mandates require separable metal-polymer cartridge designs for end-of-life recycling compliance. Mann+Hummel Group operates captive R&D campuses near Ludwigsburg to sustain technology leadership in synthetic media formulations.
China
Commercial vehicle production scale and domestic mining equipment demand drive consumption of large-diameter hydraulic filter elements. National emission standards for heavy-duty diesel engines align filtration efficiency requirements with international benchmarks. Yangtze River Delta manufacturing clusters concentrate pleated media conversion capacity for both domestic fitment and export supply.
India
Underpenetrated aftermarket service infrastructure and accelerating freight corridor development create education opportunities for cartridge-format adoption. Bureau of Indian Standards certification requirements for automotive filters establish minimum performance thresholds for imported and domestic products. Maharashtra-based commercial vehicle hubs generate concentrated demand from fleet operators transitioning from unorganized to branded maintenance practices.
Japan
Downsized turbocharged engine penetration in domestic passenger vehicle production accelerates specification shifts toward thermally stable synthetic media. METI industrial standards govern lubricating oil filter performance validation for factory-fit and replacement markets. Kanto region automotive engineering centers coordinate specification alignment with global OEM platform strategies.
Oil Filter Elements Market Competitive Landscape
On the supply side, the industry is structured around three distinct capability tiers rather than consolidated scale dominance. Synthetic media formulation expertise and captive testing infrastructure separate premium-positioned suppliers from commodity-grade competitors. Strategic archetypes include integrated media-to-element manufacturers, specialized cartridge architects, and diversified filtration conglomerates with cross-industry portfolios. Capacity expansion in high-efficiency pleated media and backward integration into fiber substrate production represent the dominant competitive moves reshaping cost positions.
Within the integrated manufacturing tier, Mann+Hummel Group and Donaldson Company exemplify archetypes built on captive control of raw material quality from fiber through finished element. MAHLE GmbH occupies a distinct position as a specialist in compact cartridge architectures designed for European OEM downsized powertrain programs. These three anchors illustrate how technology leadership, manufacturing integration, and application-specific design capability define sustainable differentiation in specification-bound supply relationships.
| Leading Market Players |
|---|
| Mann+Hummel Group |
| MAHLE GmbH |
| Donaldson Company, Inc. |
| Ahlstrom Corporation |
| Sogefi SpA |
| Hengst SE & Co. KG |
| FRAM Group |
| Denso Corporation |
| Parker Hannifin Corporation |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta manufacturing clusters concentrate pleated media conversion capacity, creating asymmetric pricing power for synthetic substrate producers over downstream element assemblers. Cost compression in cellulose-grade segments intensifies as Nordic pulp volatility feeds through to commodity filter margins.
Pricing Analysis
Certification level creates the primary spread between premium synthetic formulations and standard cellulose alternatives. Three-tier pricing structure separates ISO 4548-12 validated synthetic media from paper-grade commodities and unbranded aftermarket alternatives. Pricing pressure stems from fleet procurement centralization demanding volume discounts on high-efficiency categories. Oil change services exhibit highest price sensitivity due to inventory velocity requirements, while mining operators show lowest elasticity given downtime cost exposure.
Supply Chain Analysis
Single-source pleated media concentration between Germany, China, and the United States creates bottleneck vulnerability for high-efficiency synthetic substrate. Raw material dependencies center on Nordic wood pulp, borosilicate glass microfiber, and specialized resin binders. Tariff exposure between North American and European markets fragments regional sourcing strategies. Distribution runs through captive OEM supply chains for factory fill, with independent distributors serving fragmented aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat. ISO validation timelines and EPA emission mandates create switching costs that protect specification-bound incumbents from price-based disruption.
For Market Incumbents: Build certification moats by accelerating ISO 4548-12 validation pipelines for next-generation gradient-density formulations. Deepen backward integration into glass microfiber substrate production to secure raw material quality from fiber to finished element. Channel control through direct fleet relationships counters distributor disintermediation threats from centralized Class 8 procurement functions.
For New Entrants and Emerging Players: Indian commercial vehicle aftermarket underpenetration offers whitespace for cartridge-format education and distribution buildout. Target Maharashtra-based fleet operators transitioning from unorganized to branded maintenance practices. Quick-lube chain partnerships provide volume scale without competing for OEM specification slots.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because synthetic media formulation expertise concentrates in three integrated manufacturers with captive R&D infrastructure. Target acquisition archetype: mid-cap specialists with advanced polymer-metal separation capabilities for EU Green Deal compliance. Monitor EPA heavy-duty emission standard revision timing as inflection signal for specification upgrade cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Substrate | Captive control of glass microfiber quality secures margin against Nordic pulp volatility. |
| EU Green Deal Compliance Investment | Separable-component design capabilities unlock preferential supplier status with German OEMs. |
| Condition-Monitoring Sensor Integration | IoT pressure sensor bundling shifts revenue model from product transaction to predictive service. |
| Indian Distribution Network Buildout | Cartridge-format education captures fleet operators transitioning from unorganized maintenance. |
| ISO 4548-12 Validation Acceleration | Compressed certification timelines defend specification slots against emerging synthetic media entrants. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with fleet procurement directors, OEM platform engineers, aftermarket distributors, and pleated media technical specialists; and secondary validation against EPA regulatory filings, ISO standard documentation, vehicle production databases, and customs trade records. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the projection horizon.
Forecast inputs incorporated product type evolution, material substitution rates, end-user procurement centralization patterns, and regional regulatory divergence between EPA and EU Green Deal mandates. CAGRs derived from segment-level volume builds and value-per-unit trajectories across cartridge, spin-on, and remote format categories. Analysis weighted turbocharged engine penetration and extended drain interval engineering as demand-modifying variables.
Practitioners should monitor pulp price cycles, synthetic substrate capacity expansion announcements, and EPA emission standard revision timelines for early signals of margin compression or specification upgrade windows. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
Global Wheel Tractor Scraper Market
Vehicle Components
Global Bicycle Wheels Market
Vehicle Components
Gas Station Equipment Market
Vehicle Components
South Africa Automotive Thermoplastic Polymer Composites Market
Vehicle Components
Truck Suspension System Market
Vehicle Components
Trailer Landing Gear Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Hydraulic Actuators Market
Vehicle Components
Portable Truck Access System Market
Vehicle Components
Vehicle Pillar Market
Vehicle Components
Global Automotive Rain, Light, Humidity Sensor Market
Vehicle Components
Forklift Seats Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Intelligent Rubber Tracks Market
Vehicle Components
Saudi Arabia Car Rental and Leasing Market