
 Car Sunshade Market | 2026-2036
Car Sunshade Market Size, Share, and Industry Trends Forecast 2026-2036
Car Sunshade Market Insights
Smart material integration is reshaping how car sunshades deliver thermal performance, with phase-change coatings and electrochromic layers replacing static reflective films. Inalfa Roof Systems Group B.V. leverages its OEM supply relationships to anchor retractable sunroof-integrated shading solutions. WeatherTech sustains its position through Made-in-USA manufacturing scale and direct-to-consumer channel control. EcoNour differentiates via aggressive digital marketing and budget-tier pricing that occupies the Amazon marketplace.
A car sunshade is a vehicle interior accessory engineered from polyester, nylon, or aluminum-composite substrates to block solar radiation, reduce cabin temperatures, and protect dashboards and upholstery from UV degradation. Reflective technology leads the technology segment due to its low cost and proven efficacy, while UV-blocking coatings command premium pricing in fleet and luxury channels where interior preservation drives total cost of ownership calculations. The retractable product type dominates OEM fitment, whereas magnetic variants represent the fastest-growing aftermarket segment as clip-free installation gains traction among rental services seeking damage prevention.
The EPA regulates volatile organic compound emissions from automotive interior materials, compelling manufacturers to reformulate adhesives and coatings used in sunshade production. The EU REACH framework restricts certain phthalates and flame retardants in textile automotive accessories, creating compliance barriers for Asian exporters targeting European dealerships. Stakeholders must monitor evolving cabin air quality standards across multiple jurisdictions, as regulatory divergence between the EPA and ECHA threatens to fragment material specifications and inflate certification costs for global suppliers.
Market Dynamics
Fleet thermal management mandates and EPA interior air quality guidelines are forcing material reformulation across the supply base, compressing margins for manufacturers dependent on legacy adhesive chemistries.
Growth Catalysts
- Sun Belt Fleet Procurement:Commercial vehicle operators in Texas, Arizona, and Florida are mandating UV-blocking cabin shades to reduce idle-time cooling costs and extend dashboard service life.
- REACH Material Compliance:The EU framework's restrictions on phthalates and flame retardants in textile accessories are accelerating substitution toward bio-based polymer substrates certified for dealership channels.
- Electrochromic Layer Adoption:Smart glass integration with variable-opacity films is creating pull-through demand for retractable shading systems in luxury OEM fitments.
Market Restraints
- Petrochemical Input Volatility:Polyester and nylon substrate costs fluctuate with crude oil derivatives, compressing margin stability for manufacturers without backward integration into polymer production.
- Asian Supply Concentration:Woven aluminum-composite manufacturing clusters in Zhejiang and Guangdong provinces create single-source vulnerability for Western brands seeking rapid replenishment.
- Static Film Performance Ceiling:Conventional reflective technologies face hard physics limits on thermal rejection, capping premium pricing power against emerging phase-change alternatives.
Strategic Opportunities
- Indian Aftermarket Penetration:Rising vehicle ownership in Maharashtra and Karnataka combined with extreme heat exposure creates unmet demand for budget-tier magnetic sunshade formats.
- IRA Clean Manufacturing Credits:U.S. domestic production incentives for low-carbon automotive components are subsidizing facility relocation for sunshade assemblers using recycled PET substrates.
- Subscription Fleet Services:Rental and car-sharing operators are adopting damage-preventing clip-free magnetic variants through direct vendor partnerships, bypassing traditional retail markup.
Industry Challenges
- Adhesive Chemist Talent Scarcity:Reformulating low-VOC bonding agents that meet both EPA guidelines and durability standards requires specialized polymer science expertise concentrated at a handful of suppliers.
- Dual Certification Timelines:Simultaneous EPA and ECHA compliance testing extends product launch cycles by 8-14 months, freezing working capital in inventory awaiting clearance.
- Legacy ERP Integration:Smart material inventory tracking for phase-change coatings demands IoT-enabled warehouse systems that many mid-tier manufacturers lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Sunshade Market |
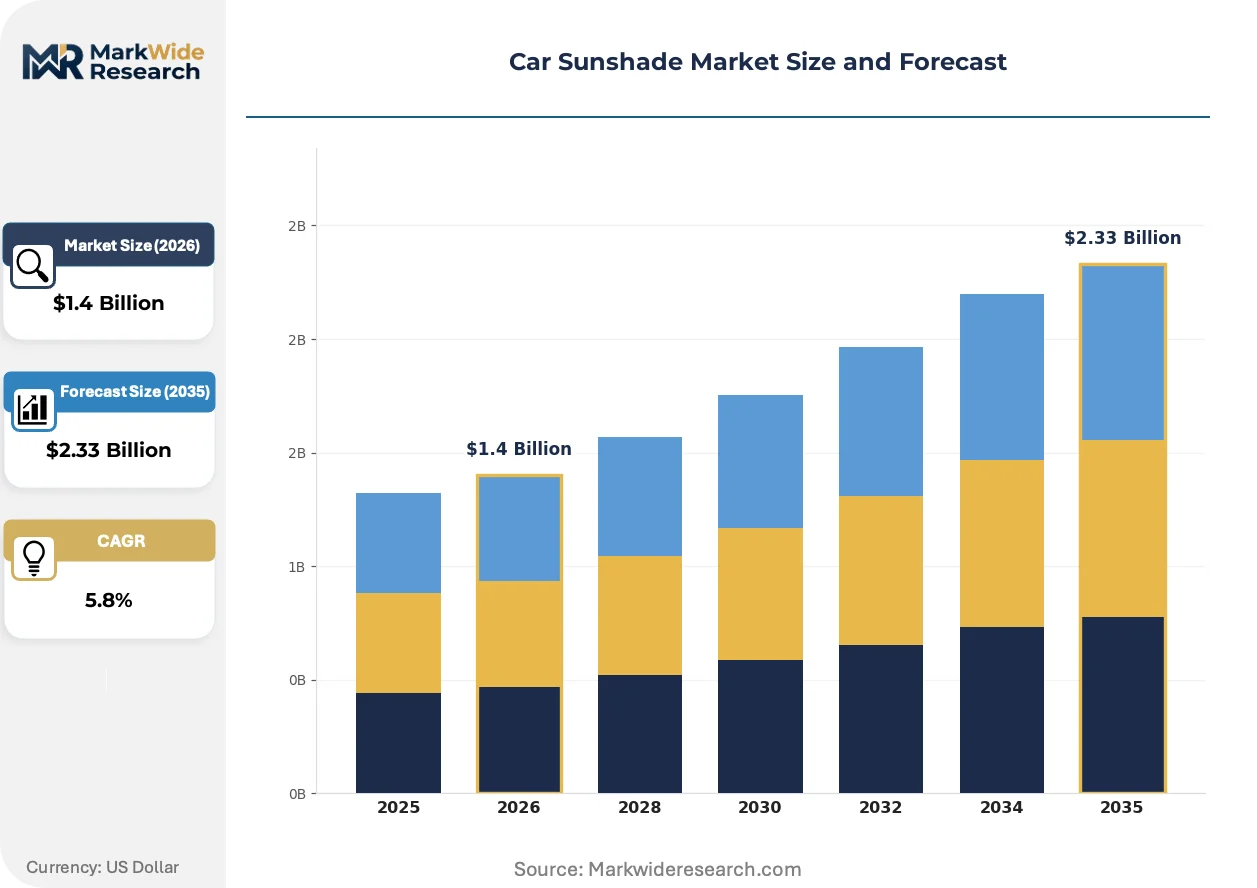
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Retractable, Accordion, Fixed, Magnetic Material: Polyester, Cotton, Nylon, Aluminum Technology: Reflective, UV-Blocking, Insulative, Heat-Resistant End User: Individual Car Owners, Car Rental Services, Dealerships, Fleets |
| Companies Covered | Inalfa Roof Systems Group B.V., HeatShield, WeatherTech, Steisone, EcoNour, Covercraft, Intro-Tech Automotive, Shyu Fuu, Ashimori Industry Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Sunshade Market Trends and Innovations
Material science convergence and regulatory fragmentation are splitting the competitive landscape into two tracks: premium smart-system integration for OEM channels and cost-optimized compliance for aftermarket volume.
Phase-change thermal coatings are hybridizing static sunshade functionality with dynamic temperature buffering. These microencapsulated paraffin wax layers absorb excess cabin heat during peak solar exposure and release it during cooldown periods. Luxury fleet operators in Nevada and central California are piloting retrofits at 3x standard pricing. The technology is hybridizing aftermarket expectations, forcing reflective-film suppliers to reposition on total cost of ownership rather than upfront unit economics.
EPA vehicle interior air quality guidelines are pressuring adhesive suppliers to eliminate formaldehyde-releasing crosslinkers from sunshade lamination processes. Manufacturers serving U.S. dealership networks must reformulate bonding chemistries or risk delisting from approved vendor programs. California-based fleet managers are now specifying third-party VOC certification as a mandatory bid requirement, compressing qualification timelines for non-compliant imports.
Direct-to-consumer channel capture is displacing traditional auto parts distributor relationships. Amazon-native brands are leveraging review velocity algorithms and same-day fulfillment infrastructure to own search visibility for "windshield sunshade" queries. This pattern concentrates most visibly in suburban Texas and Florida markets where heat-driven purchase intent spikes correlate with weather app notifications.
Car Sunshade Market Segmentation
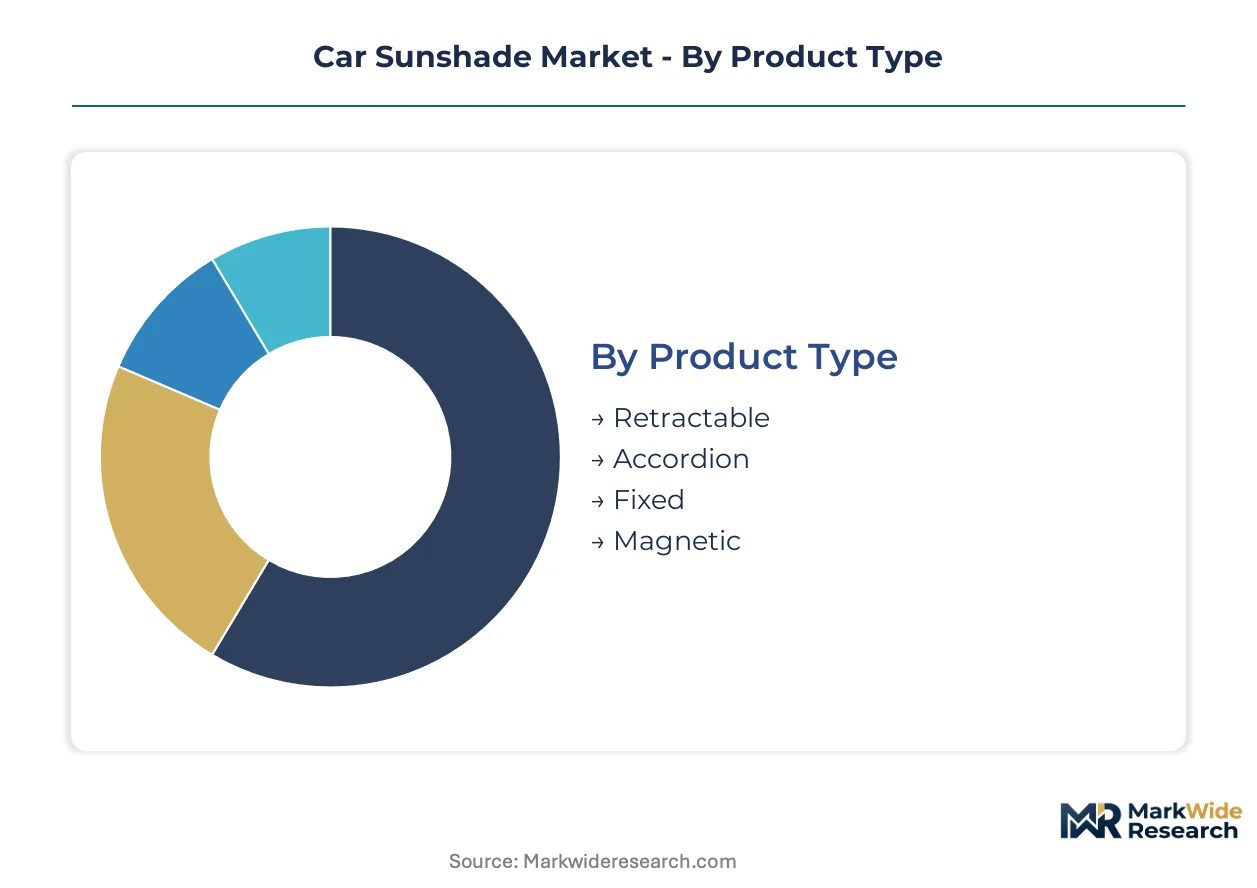
Car sunshade segmentation reveals divergent engineering priorities across OEM integration, aftermarket convenience, and fleet durability requirements. Material and technology choices increasingly bifurcate between premium smart-system channels and cost-optimized volume plays.
Product Type:
Mature retractable formats dominate OEM fitment while emerging magnetic variants capture aftermarket share through installation simplicity.
- Retractable:Mechanically deployed shading systems integrate with sunroof assemblies and side windows through embedded track systems. Inalfa Roof Systems supplies retractable formats to European and Japanese automakers seeking seamless cabin aesthetic integration.
- Accordion:Foldable cardboard or fabric panels collapse for compact storage behind seats. Demand concentrates among individual owners in Texas and Florida seeking low-cost UV protection without permanent installation.
- Fixed:Rigid panels mount via suction cups or static clips for semi-permanent windshield coverage. Fleet operators in Arizona specify fixed formats for parking-lot durability during extended idle periods.
- Magnetic:Clip-free attachment systems use perimeter magnets to secure mesh or film substrates to window frames. Rental services in California and Nevada are standardizing magnetic variants to eliminate clip-related interior damage claims.
Retractable systems handle the majority of OEM throughput; magnetic formats are expanding most quickly in aftermarket channels.
Material:
Cost tier stratification separates petrochemical substrates from metal-composite alternatives with divergent thermal performance profiles.
- Polyester:Woven polyethylene terephthalate substrates dominate volume production due to dyeability, dimensional stability, and compatibility with reflective coatings. WeatherTech manufactures polyester-based shades at its Illinois facility for Made-in-USA certification compliance.
- Cotton:Natural fiber constructions appeal to eco-conscious segments seeking biodegradable alternatives, though moisture absorption limits thermal performance in humid climates.
- Nylon:Polyamide substrates offer superior abrasion resistance for retractable mechanisms requiring repeated flex cycles. Japanese OEMs specify nylon for sunroof-integrated applications demanding 10-year durability.
- Aluminum:Laminated foil-composite substrates deliver maximum thermal rejection through radiant barrier physics. Manufacturing clusters in Zhejiang province supply aluminum-composite materials to Western brands seeking cost-competitive reflective performance.
Polyester commands the volume base; aluminum-composite materials are climbing the fastest on fleet procurement specifications.
Technology:
Application context determines whether static performance or dynamic responsiveness drives technology selection.
- Reflective:Metallized film layers bounce solar radiation before absorption occurs. Budget-tier suppliers in Guangdong province optimize reflective formulations for Amazon marketplace price points.
- UV-Blocking:Spectrally selective coatings transmit visible light while absorbing ultraviolet wavelengths. California fleet managers now mandate third-party UV-blocking certification as a mandatory bid requirement.
- Insulative:Multi-layer substrates trap air pockets to reduce conductive heat transfer. Phase-change microencapsulation is hybridizing insulative technology with dynamic thermal buffering capability.
- Heat-Resistant:High-temperature polymer matrices maintain structural integrity above 85°C dashboard exposure. Nevada and central California luxury fleet operators pilot heat-resistant retrofits at premium pricing multiples.
Reflective technology anchors the installed base; UV-blocking coatings are gaining share fastest on interior preservation economics.
End User:
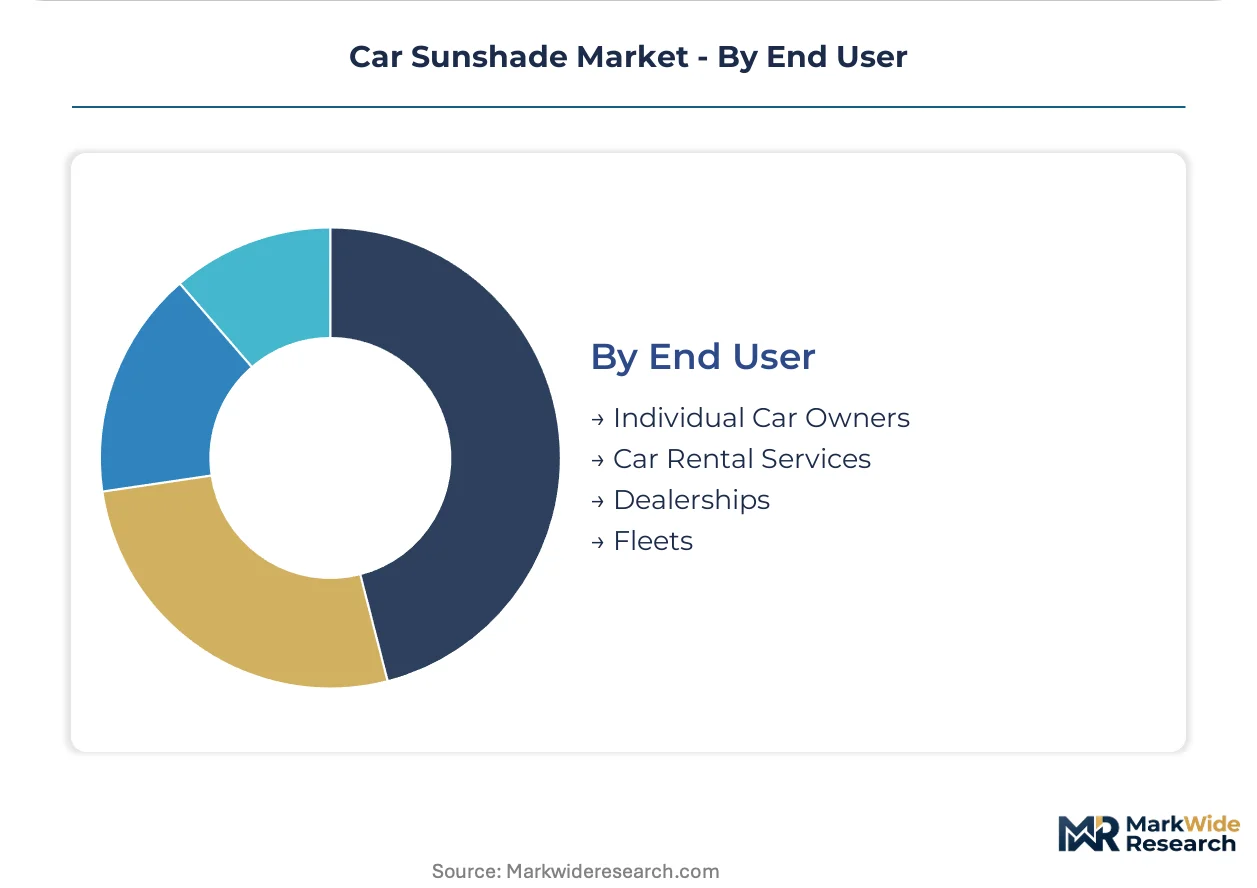
Customer type segmentation aligns procurement scale with durability specifications and channel access requirements.
- Individual Car Owners:Fragmented demand across suburban Texas and Florida markets correlates with weather-driven purchase intent spikes. Amazon-native brands capture this segment through review velocity algorithms and same-day fulfillment infrastructure.
- Car Rental Services:Damage prevention priorities drive standardization on clip-free magnetic formats. Enterprise and Hertz procurement teams specify magnetic variants through direct vendor partnerships bypassing retail markup.
- Dealerships:Accessory profit centers depend on low-VOC certification compliance for EPA vehicle interior air quality guidelines. Manufacturers serving U.S. dealership networks must reformulate bonding chemistries or risk delisting from approved vendor programs.
- Fleets:Total cost of ownership calculations prioritize dashboard service life extension and idle-time cooling cost reduction. Sun Belt commercial operators in Texas, Arizona, and Florida mandate UV-blocking cabin shades as standard equipment.
Fleets generate the highest per-account revenue concentration; car rental services are scaling fastest on standardization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet procurement managers in the United States Sun Belt drive the highest volume concentration, while German OEM supply chains and Chinese manufacturing clusters shape upstream material flows.
United States
Commercial fleet operators in Texas, Arizona, and Florida mandate UV-blocking cabin shades to cut idle-time cooling costs and extend dashboard service life. EPA vehicle interior air quality guidelines pressure manufacturers toward low-VOC adhesive reformulations. Manufacturing facilities in Illinois and Michigan produce polyester-based shades for domestic certification compliance.
Germany
Automotive OEM supply relationships anchor retractable sunroof-integrated shading demand from luxury manufacturers. ECHA REACH restrictions on phthalates and flame retardants accelerate bio-based polymer substitution in textile accessories. Industrial clusters in Bavaria and Baden-Württemberg host lamination facilities serving European dealership networks.
China
Woven aluminum-composite production concentrates in Zhejiang and Guangdong provinces, supplying cost-competitive reflective substrates to Western brands. The country's national environmental regulator enforces volatile organic compound emission standards for automotive interior materials. Manufacturing hubs in the Pearl River Delta face compliance cost pressures from dual carbon reduction targets.
Japan
Automakers specify nylon substrates for sunroof-integrated applications demanding decade-long durability cycles. METI industrial standards govern material specifications for cabin thermal management components. Nagoya-based suppliers coordinate with domestic OEMs on retractable mechanism engineering.
India
Rising vehicle ownership in Maharashtra and Karnataka combines with extreme heat exposure to create unmet aftermarket demand for budget-tier magnetic formats. The Bureau of Indian Standards maintains voluntary certification protocols for automotive textile accessories. Manufacturing activity clusters around Pune and Chennai serving domestic fleet retrofit programs.
Car Sunshade Market Competitive Landscape
Channel-controlling players compete with product-specialist players across bifurcated OEM and aftermarket pathways. The market structure organizes around three tiers: integrated OEM suppliers, direct-to-consumer brands, and contract manufacturers serving private-label programs. Strategic archetypes include Made-in-USA certification holders, Amazon-native digital marketers, and Asian substrate specialists. Dominant competitive moves center on supply chain relocation for regulatory compliance and direct vendor partnerships bypassing traditional distribution.
Among integrated OEM suppliers, Inalfa Roof Systems Group B.V. and Ashimori Industry Co. Ltd. occupy positions anchoring retractable format engineering for sunroof assemblies. WeatherTech represents the domestic manufacturing archetype with Illinois-based production facilities. EcoNour exemplifies the digital-native challenger model through marketplace channel control and review velocity optimization.
| Leading Market Players |
|---|
| Inalfa Roof Systems Group B.V. |
| HeatShield |
| WeatherTech |
| Steisone |
| EcoNour |
| Covercraft |
| Intro-Tech Automotive |
| Shyu Fuu |
| Ashimori Industry Co. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Petrochemical input volatility determines both the spread between economy and premium pricing tiers and the geographic shape of manufacturing footprints, as polyester and nylon substrate costs fluctuate with crude oil derivatives and compress margin stability for manufacturers lacking backward integration into polymer production.
Pricing Analysis
Cost-plus contracts with crude oil indexation dominate raw material procurement, embedding petrochemical volatility directly into unit economics. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with UV-blocking certified products commanding substantial premiums over reflective alternatives. Cost compression in the economy tier is intensifying because Amazon-native brands optimize for review velocity at minimal margin. Fleet procurement teams exhibit the lowest price sensitivity due to total cost of ownership calculations, while individual car owners in suburban markets drive the highest elasticity.
Supply Chain Analysis
Contract manufacturing capacity concentrates with Zhejiang and Guangdong province specialists who supply woven aluminum-composite substrates to Western brands. The supply chain draws from polyester resin, metallized film laminates, and neodymium magnet assemblies as critical inputs. Single-source vulnerability from Asian supply concentration creates replenishment risk for brands seeking rapid restocking. Distribution runs through Amazon marketplace fulfillment centers for direct-to-consumer channels and traditional auto parts distributors for dealership networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized adhesive chemistry expertise functions as the binding constraint across this market, with low-VOC formulation capabilities concentrated at a handful of suppliers and dual certification timelines freezing working capital for non-compliant manufacturers.
For Market Incumbents: Pre-empt regulatory delisting by accelerating EPA-compliant adhesive reformulation ahead of fleet procurement mandate expansion. Secure captive supply of bio-based polymer substrates through direct partnerships with European lamination facilities, insulating margin position from REACH-driven material substitution costs. For New Entrants and Emerging Players: Establish a beachhead in the Indian aftermarket through budget-tier magnetic formats targeting Maharashtra and Karnataka vehicle owners. Bypass traditional retail markup by securing direct vendor partnerships with subscription fleet services standardizing on clip-free installation systems. For Investors and Strategic Acquirers: The market sits at a compliance-transition phase that favors manufacturers with in-house low-VOC formulation capabilities and multi-jurisdiction certification infrastructure. Acquisition targets should demonstrate established EPA and ECHA testing relationships. The signal to watch is fleet procurement mandate expansion beyond the Sun Belt into interior air quality-sensitive jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Low-VOC Adhesive Reformulation | EPA vehicle interior air quality guidelines are pressuring manufacturers toward compliant bonding chemistries to avoid dealership delisting. |
| Backward Integration into Polymer Production | Captive polyester substrate supply insulates margin stability from crude oil derivative volatility affecting woven material costs. |
| Direct Fleet Vendor Partnerships | Enterprise and Hertz procurement teams are standardizing magnetic variants through bypass relationships eliminating retail markup. |
| Phase-Change Coating R&D Investment | Nevada luxury fleet operators pilot dynamic thermal buffering retrofits at premium pricing multiples above static alternatives. |
| Multi-Jurisdiction Certification Buildout | Simultaneous EPA and ECHA compliance testing capability compresses product launch cycles and unlocks transatlantic dealership access. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet procurement managers, automotive accessory distributors, adhesive chemistry specialists, and OEM platform engineers, validated against secondary sources including EPA vehicle interior air quality filings, ECHA REACH substance restrictions, customs trade data for polyester and aluminum-composite imports, and automotive production databases. Bottom-up and top-down triangulation cross-validated volume estimates across product type, material, technology, and end user segmentation.
Calibration against historical fleet procurement patterns and petrochemical price indices anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product format, substrate material, thermal rejection technology, and customer archetype. CAGRs were derived from trend extrapolation adjusted for regulatory mandate timing and smart material adoption curves, with phase-change coating penetration and magnetic format standardization serving as key industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in crude oil prices, freight rates, or automotive production volumes would shift the trajectory. Forecasts reflect assumptions about regulatory enforcement continuity and fleet electrification timelines affecting cabin thermal management priorities. Quarterly review of EPA guideline updates, ECHA substance restriction proposals, and Sun Belt fleet procurement mandate expansions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Driveline Systems for Electric Vehicle Market
Vehicle Components
Throttle Cable Market
Vehicle Components
Vehicle Trailer Hitch Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Latin America Two-Wheeler Components Market
Vehicle Components
2 Wheeler Fuel Injection System Market
Vehicle Components
Engine Valve Market
Vehicle Components
Forestry Trailers Market
Vehicle Components
Transmission Components Market
Vehicle Components
Chassis Sensors Market
Vehicle Components
Motorcycle Monoshock Suspension Market
Vehicle Components
Garbage Collection Vehicle Market
Vehicle Components
Gas-Powered Chainsaw Market
Vehicle Components
Air Suspension Market
Vehicle Components
Grille Guard Market
Vehicle Components
Global Undercarriage Components Market