
 Bicycle Bottom Bracket Market | 2026-2036
Bicycle Bottom Bracket Market Size, Share, and Industry Trends Forecast 2026-2036
Bicycle Bottom Bracket Market Insights
The bicycle bottom bracket market is recalibrating around a widening performance gap between premium ceramic-bearing assemblies and commodity steel units. Shimano Inc anchors the mid-to-premium tier through its integrated Hollowtech II ecosystem and extensive OEM partnerships. SRAM LLC differentiates via its DUB platform, which standardizes spindle diameters across road and mountain applications. Chris King Precision Components occupies the artisanal niche with domestically manufactured threaded units that command sustained aftermarket loyalty.
A bicycle bottom bracket is the rotating spindle-and-bearing assembly that connects the crankset to the frame, typically machined to tolerances within 0.05 millimeters to ensure efficient power transfer from rider to drivetrain. Threaded bottom brackets, the longest-serving design standard, retain dominant aftermarket share due to universal frame compatibility and service simplicity. Press Fit configurations are gaining fastest in carbon fiber road bike production where shell molding favors larger diameter, threadless interfaces. Carbon Fiber material grades are capturing margin pools as frame manufacturers specify matched component stiffness to preserve ride quality targets.
ISO 4210 fatigue testing standards govern bottom bracket structural validation for consumer safety in major export markets, while REACH compliance in Europe restricts certain bearing lubricants and surface coatings. The EPA oversees waste stream regulations affecting metalworking facilities in the United States, influencing domestic manufacturing location decisions. Stakeholders must monitor evolving frame standards from the three largest bicycle-producing countries to anticipate which interface formats will command tooling investment and inventory commitment.
Market Dynamics
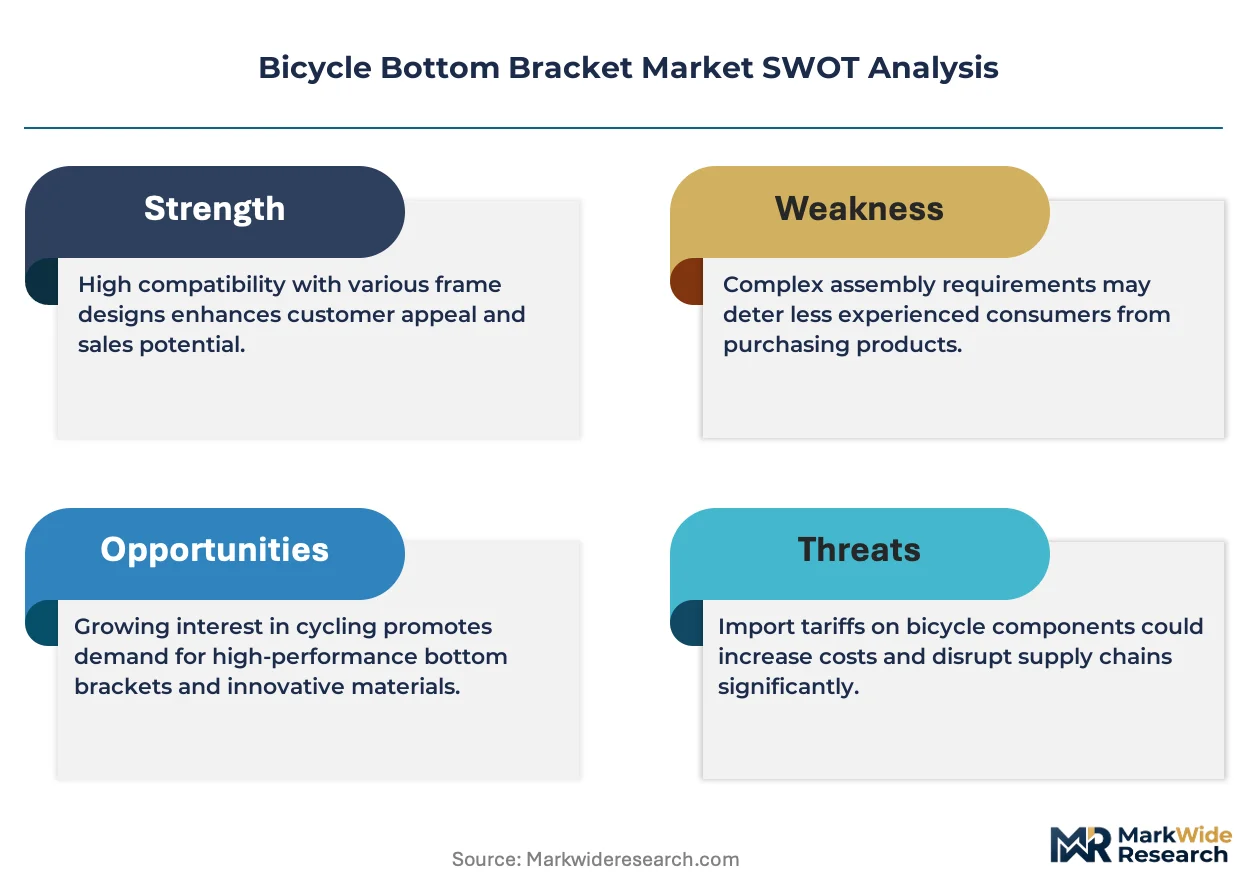
The bicycle bottom bracket market is recalibrating around frame standard fragmentation, where competing shell interfaces—BSA, T47, BB86, PF30—force manufacturers to maintain redundant tooling and inventory positions across incompatible specifications.
Growth Catalysts
- E-Bike Motor Integration:Mid-drive motor systems require reinforced bottom bracket shells with higher load ratings, pulling replacement demand from the installed base of legacy frames across Germany, Netherlands, and Denmark.
- EU Green Deal Active Mobility Funding:Infrastructure investment in protected bike lanes across member states is extending bicycle useful life and triggering component refresh cycles at independent bicycle dealers.
- Ceramic Bearing Adoption:Reduced friction coefficients in hybrid ceramic-steel bearing assemblies are penetrating performance road and gravel segments where watt-savings justify premium positioning.
Market Restraints
- Raw Material Cost Volatility:Chromium steel and 7075 aluminum billet pricing fluctuates with energy-intensive European smelter output, compressing margin on mid-tier threaded units.
- Frame Standard Proliferation:Press Fit shell tolerances vary by carbon fiber mold supplier, creating compatibility headaches and warranty exposure for aftermarket installers.
- Substitution by Integrated Motor Units:Bosch and Shimano mid-drive systems incorporate proprietary spindle interfaces that bypass traditional bottom bracket categories entirely.
Strategic Opportunities
- Service-Contract Bundling:Independent bicycle dealers in France and Belgium are packaging annual bearing inspection with drivetrain cleaning, locking in recurring component replacement revenue.
- Modular Adapter Systems:Thread-to-Press Fit conversion cups allow frame builders to specify single shell designs while accommodating multiple crank spindle standards.
- Carbon Fiber Frame Repair Integration:Specialized collision repair shops in Italy are sourcing matched bottom bracket shells as part of structural frame restoration workflows.
Industry Challenges
- ISO 4210 Fatigue Testing Bottlenecks:Third-party certification queues at European testing houses extend product launch timelines by four to six months for new shell designs.
- Skilled Frame Alignment Labor Scarcity:Bottom bracket shell facing and chasing requires precision machining expertise that retiring toolmakers in the UK and Germany are not replenishing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bicycle Bottom Bracket Market |
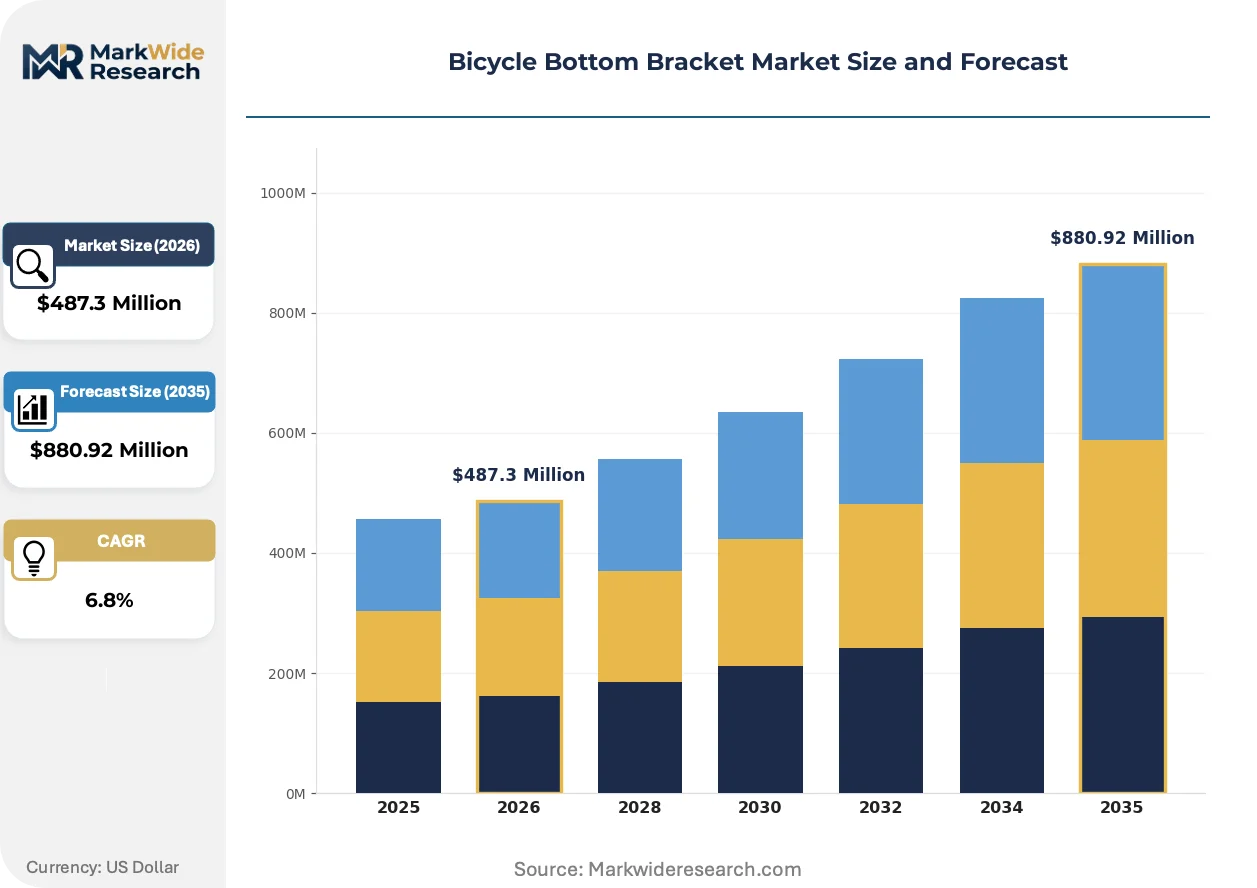
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Threaded, Press Fit, External, Integrated Material: Aluminum, Steel, Carbon Fiber, Plastic Application: Road Bikes, Mountain Bikes, Hybrid Bikes, BMX Bikes End User: Consumer, OEM, Retailer, Distributor |
| Companies Covered | Shimano Inc, SRAM LLC, Campagnolo S.r.l., Full Speed Ahead (FSA), Chris King Precision Components, Hope Technology Ltd., Token Products, Rotor Bike Components, CeramicSpeed A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bicycle Bottom Bracket Market Trends and Innovations
Bottom bracket engineering is pivoting from static hardware toward adaptable interface systems that accommodate multiple crank standards without frame modification. This shift reflects pressure from frame builders seeking to reduce SKU complexity while preserving consumer upgrade flexibility.
T47 threading is modularizing the interface between legacy BSA dimensions and larger-diameter spindle requirements. Titanium and steel frame manufacturers in the United States and Italy are specifying T47 shells to accommodate 30mm spindles without Press Fit creaking issues. The standard is compressing the historical trade-off between serviceability and stiffness-to-weight targets.
REACH Annex XVII restrictions on perfluorinated lubricants are forcing bearing suppliers to reformulate greases for European market access. The regulation is accelerating adoption of ionic liquid and ceramic-particle lubrication systems that previously commanded niche positioning. Road bike OEMs sourcing from Taiwan and China are now requiring REACH-compliant documentation as a condition of purchase order acceptance.
Direct-to-consumer wheel and component brands are unbundling bottom bracket selection from frame purchase, forcing riders to self-specify interface types. This pattern concentrates technical support burden on chat-based customer service teams and increases return rates for mismatched orders. The phenomenon is most visible in North American gravel bike sales, where frame-up builds represent over one-third of unit volume.
Bicycle Bottom Bracket Market Segmentation
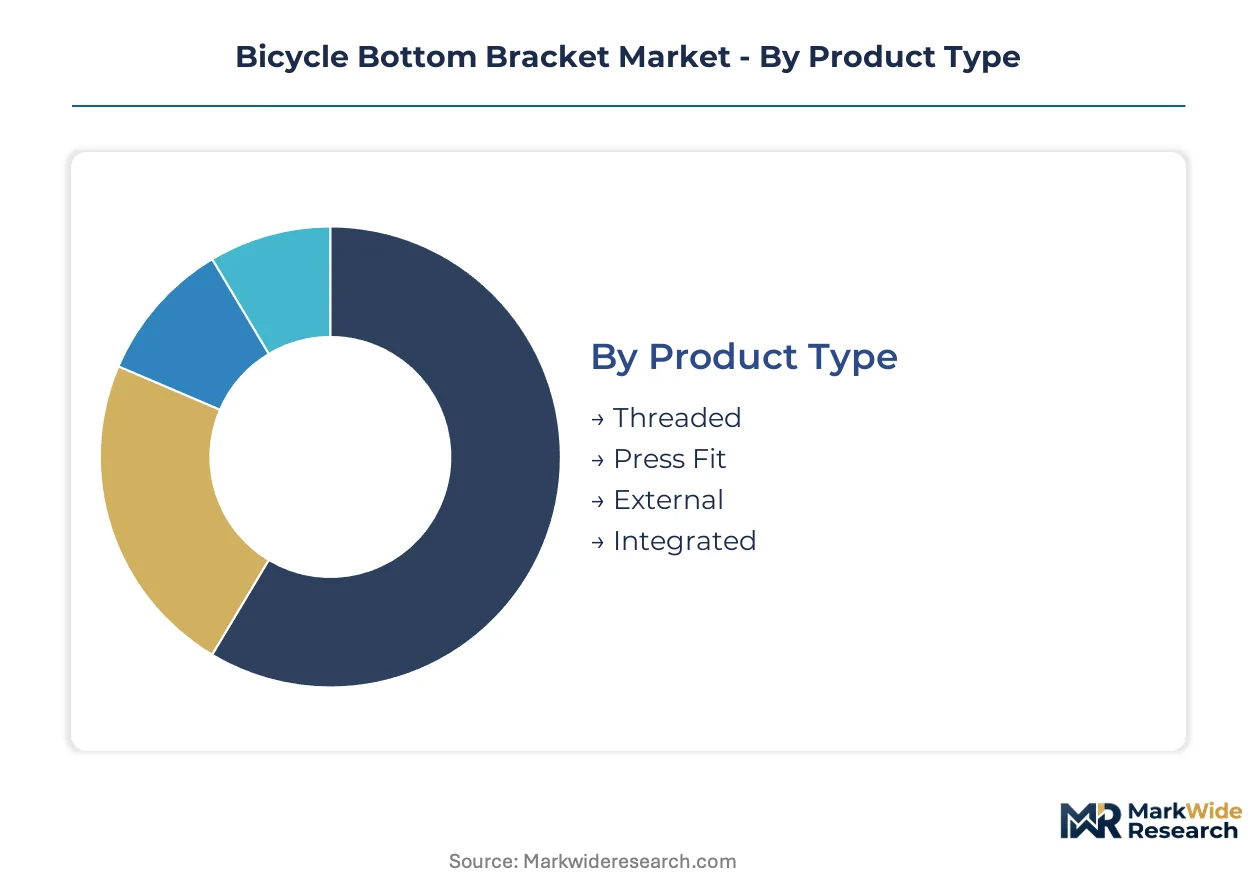
Bottom bracket procurement patterns diverge sharply across interface standards and frame materials, forcing suppliers to maintain parallel tooling configurations. Segmentation clarity enables inventory positioning against incompatible shell specifications and bearing grade requirements.
Product Type:
Capital intensity concentrates in Press Fit and Integrated variants, where carbon fiber shell molding and spindle-bearing integration demand precision machining infrastructure.
- Threaded:BSA and T47 threading specifications dominate aftermarket service channels due to universal frame compatibility and field-serviceable bearing replacement. Demand concentrates in Germany and Italy where steel and titanium frame builders specify traditional shell interfaces for durability and repair accessibility.
- Press Fit:BB86, PF30, and BB30 shell formats require tight-tolerance carbon fiber molding and installer-facing tools for proper alignment. Demand clusters in Taiwanese OEM production for North American and European road bike brands seeking stiffness-to-weight optimization without threading complications.
- External:Outboard bearing configurations extend spindle support beyond the shell width, accommodating larger diameter spindles on legacy BSA frames.
- Integrated:Spindle-bearing units fused to crank arms eliminate separate bracket procurement entirely, capturing share in complete drivetrain bundles.
Most installed capacity flows through Threaded. Expansion is steepest in Press Fit.
Material:
Cost tier stratification separates aerospace-grade alloys from commodity stampings, with margin pools concentrating in stiffness-matched assemblies.
- Aluminum:7075-T6 billet shells and cups deliver strength-to-weight ratios suitable for mid-tier road and mountain applications. Demand concentrates in Taiwanese forging houses supplying European OEMs with REACH-compliant surface treatments.
- Steel:Chromoly and stainless steel variants retain dominance in threaded shells and bearing races for fatigue resistance under cyclical loading. Demand localizes in German and Italian aftermarket channels where mechanics prioritize service longevity over gram savings.
- Carbon Fiber:Reinforced polymer cups and shell inserts match frame stiffness characteristics in high-end road and gravel builds.
- Plastic:Injection-molded composite cups reduce cost in entry-level Press Fit installations with limited load requirements.
Steel commands the largest production volume. Carbon Fiber is climbing the fastest.
Application:
Volume concentration tracks bicycle category production schedules, with road and mountain segments driving incompatible spindle diameter requirements.
- Road Bikes:Stiffness-centric 30mm spindle standards and ceramic bearing specifications dominate performance-oriented builds. Demand concentrates in Italian and Spanish assembly facilities exporting to German and Benelux retail networks.
- Mountain Bikes:Impact-resistant sealed bearings and wider shell spacing accommodate suspension kinematics and mud contamination. Demand clusters in Colorado and Pacific Northwest design houses specifying enduro and downhill durability standards.
- Hybrid Bikes:Commuter-oriented service intervals prioritize sealed cartridge longevity over friction reduction.
- BMX Bikes:Compact 19mm and 22mm spindle formats with reinforced socket drives withstand repetitive impact loading.
Road Bikes absorb the majority of premium bearing shipments. Mountain Bikes are gaining share fastest.
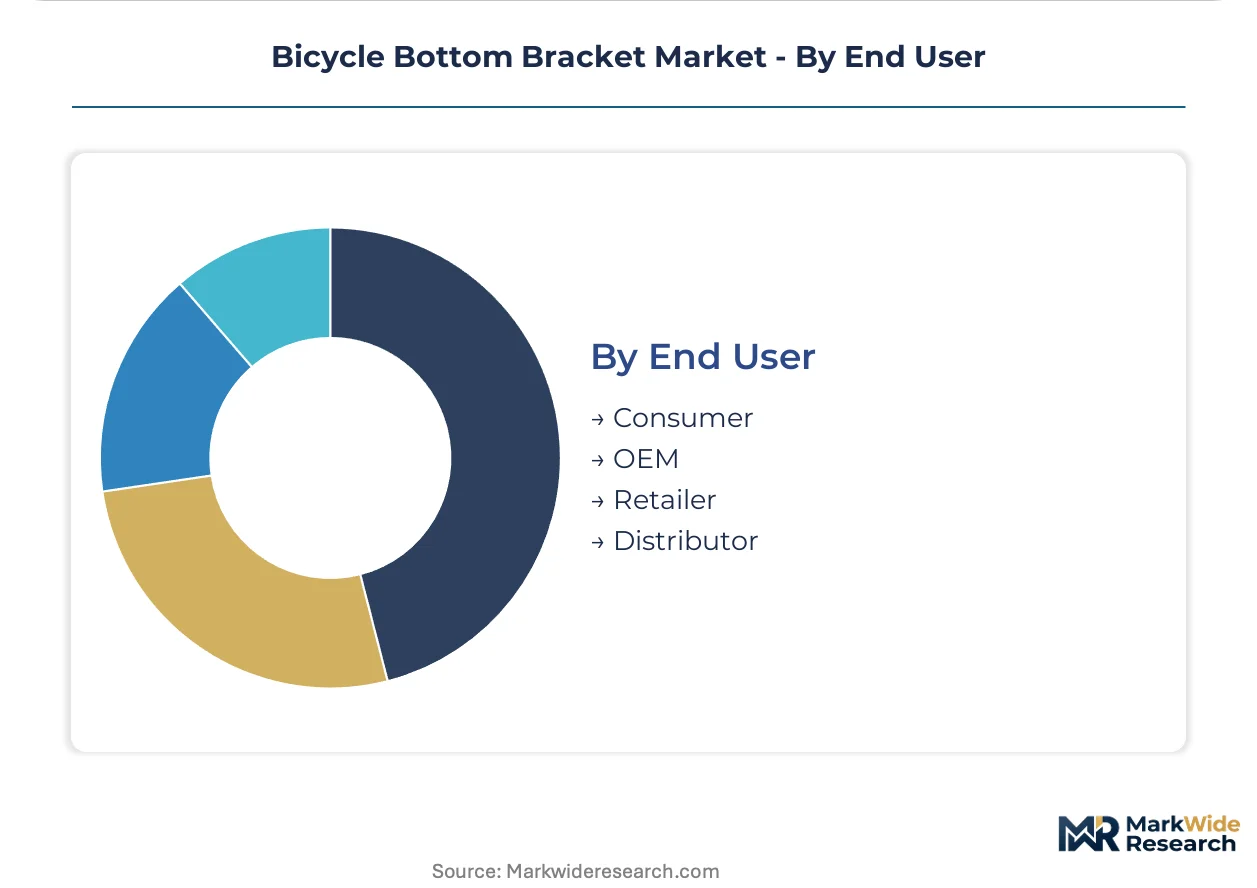
End User:
Customer type determines technical support burden and margin structure, with direct-to-consumer channels fragmenting specification expertise.
- Consumer:Enthusiast self-installers drive aftermarket ceramic bearing upgrades and T47 retrofit demand through French and Belgian independent bicycle dealers offering service-contract bundling.
- OEM:Frame and complete bike manufacturers specify matched shell standards in volume procurement agreements with Taiwanese and Chinese forging houses.
- Retailer:Independent bicycle dealers stock threaded inventory breadth while outsourcing Press Fit installation to certified mechanics.
- Distributor:Regional wholesalers buffer inventory across incompatible shell standards for just-in-time dealer replenishment.
OEM procurement commands the highest volume throughput. Consumer direct purchasing is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German toolmaking expertise and Taiwanese forging capacity anchor the bicycle bottom bracket supply chain, with skilled machinists in Baden-Württemberg and Taichung technicians driving precision manufacturing standards.
Germany
Urban bike lane expansion in Berlin and Hamburg accelerates component refresh cycles at independent bicycle dealers. The EU Green Deal channels infrastructure investment into protected cycling networks across North Rhine-Westphalia. Stuttgart-based frame builders specify T47 threaded shells for steel and titanium road bikes, prioritizing serviceability over press-fit tolerances.
United States
Gravel bike frame-up builds concentrate demand for modular adapter systems in Colorado and the Pacific Northwest. The EPA oversees metalworking waste stream regulations affecting domestic manufacturing location decisions. Portland and Boulder design houses specify enduro-grade sealed bearings for mountain bike durability standards.
Italy
Carbon fiber frame repair shops in Milan and Tuscany source matched bottom bracket shells for structural restoration workflows. REACH Annex XVII restrictions on perfluorinated lubricants force bearing suppliers to reformulate greases for European market access. The Lombardy region hosts assembly facilities exporting performance road bikes to German and Benelux retail networks.
China
Taiwanese forging houses in Taichung supply 7075-T6 billet shells with REACH-compliant surface treatments to European OEMs. The country's national standards body governs export certification requirements for bicycle component manufacturing. Guangdong and Zhejiang provinces concentrate injection-molded composite cup production for entry-level press-fit installations.
France
Independent bicycle dealers in Paris and Lyon package annual bearing inspection with drivetrain cleaning, locking in recurring component replacement revenue. The EU Green Deal's active mobility funding extends protected bike lane networks into secondary cities. The Auvergne-Rhône-Alpes region hosts ceramic bearing upgrade demand from enthusiast cyclists retrofitting higher-grade components.
Bicycle Bottom Bracket Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the bicycle bottom bracket market, with integrated forging houses maintaining captive aluminum billet supplies while specialist machine shops outsource bearing procurement. The vendor base stratifies around three tiers: multinational drivetrain ecosystems, precision component specialists, and regional forging contractors. Dominant competitive moves include backward integration into raw material processing and strategic partnerships with carbon fiber frame manufacturers for co-developed shell specifications.
Within the multinational drivetrain tier, Shimano Inc and SRAM LLC exemplify platform-centric strategies that standardize spindle interfaces across road and mountain applications. Chris King Precision Components occupies the artisanal machining niche, with domestically manufactured threaded units commanding sustained aftermarket loyalty among service-oriented mechanics. These three anchors illustrate the market's divergence between scale-driven ecosystem plays and craft-focused durability positioning.
| Leading Market Players |
|---|
| Shimano Inc |
| SRAM LLC |
| Campagnolo S.r.l. |
| Full Speed Ahead (FSA) |
| Chris King Precision Components |
| Hope Technology Ltd. |
| Token Products |
| Rotor Bike Components |
| CeramicSpeed A/S |
| Others |
Pricing and Supply Chain Analysis
A widening performance gap between ceramic-bearing premium assemblies and commodity steel units bifurcates the bicycle bottom bracket market into service-bundled aftermarket channels and transactional OEM procurement. This divergence concentrates pricing power with precision machinists in Baden-Württemberg and Taichung forging houses while compressing margins on injection-molded entry-level cups sourced from Guangdong.
Pricing Analysis
Bundled annual service contracts at French and Belgian independent bicycle dealers capture recurring ceramic bearing replacement revenue, while unbundled direct-to-consumer sales concentrate price sensitivity among gravel bike self-installers mismatching interface specifications. Three-tier pricing structure across premium, standard, and economy levels reflects bearing grade, shell material, and ISO 4210 certification status. Pricing pressure stems from raw material cost volatility in European chromium steel and 7075 aluminum billet markets. OEM procurement teams exhibit lowest price sensitivity due to volume commitments and co-development agreements, whereas enthusiast self-installers in North American direct-to-consumer channels drive hardest bargain hunting.
Supply Chain Analysis
ISO 4210 fatigue testing certification and REACH Annex XVII lubricant compliance function as gating mechanisms that filter Taiwanese and Chinese suppliers from premium European OEM procurement. Manufacturing gravity centers on Germany for precision threaded shells, Taiwan for 7075-T6 billet forging, and China for injection-molded composite entry-level cups. Raw material dependencies encompass chromium steel bearing races, aerospace-grade aluminum billet, and ceramic bearing blanks. Single-source vulnerability concentrates in European third-party testing house queues extending product launch timelines. Distribution runs through regional wholesalers buffering incompatible shell standard inventories for just-in-time dealer replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bicycle bottom bracket market has entered a late-cycle quality phase where enthusiast upgrade demand toward ceramic-bearing specifications and T47 threaded retrofits sustains premium pricing despite commodity tier compression.
For Market Incumbents: Acquire precision machining expertise in T47 threading and ceramic-bearing assembly to anchor service-contract relationships with German and Italian frame builders. Defensive priorities center on backward integration into 7075-T6 billet supply and ISO 4210 certification capacity expansion, countering substitution pressure from Bosch and Shimano integrated mid-drive motor systems that bypass traditional bracket categories entirely. For New Entrants and Emerging Players: The premium-to-economy price-point gap in ceramic-bearing road bike upgrades offers entry through modular adapter systems serving frame-up build channels in Colorado and the Pacific Northwest. White-space targets include collision repair integration with Italian carbon fiber restoration shops and direct-to-consumer technical support services reducing return rates from mismatched interface orders. A go-to-market angle emphasizing REACH-compliant lubricant documentation unlocks European OEM procurement. For Investors and Strategic Acquirers: Consolidation pressure builds where frame standard fragmentation forces redundant tooling investments across BSA, T47, BB86, and PF30 specifications. Long-term viability favors precision component specialists with captive forging capacity and established OEM co-development relationships. The signal to watch is mid-drive motor system market share penetration in German and Dutch e-bike segments, which would accelerate displacement of traditional bracket categories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Billet Supply | Captive 7075-T6 sourcing insulates margin from European smelter energy cost volatility. |
| ISO 4210 Certification Capacity Expansion | In-house fatigue testing bypasses third-party queue bottlenecks at European testing houses. |
| Service-Contract Bundling with Dealers | Annual bearing inspection packages lock recurring replacement revenue in France and Belgium. |
| Modular Adapter System Development | Thread-to-Press Fit conversion cups reduce frame builder SKU complexity across incompatible standards. |
| REACH-Compliant Lubricant Reformulation | Ionic liquid and ceramic-particle greases secure European market access under Annex XVII restrictions. |
Research Methodology
Multiple input streams — primary interviews with frame builders, independent bicycle dealer service managers, and OEM procurement leads; secondary validation through customs trade data, bicycle industry association production statistics, and regulatory filing databases — were reconciled through bottom-up and top-down triangulation. Primary fieldwork encompassed stakeholders at Taiwanese forging houses, German precision machinists, and Italian carbon fiber repair specialists. Secondary sources included EU Green Deal infrastructure funding disclosures, EPA metalworking waste stream regulations, and ISO 4210 testing protocol documentation.
Data-stream reconciliation across the projection horizon applied analytical frameworks modeling interface standard adoption curves, bearing grade penetration rates, and e-bike motor integration displacement effects. Segmentation dimensions encompassed shell format, material grade, bicycle category, and end-user channel. CAGRs were derived from installed base refresh cycle analysis and infrastructure investment flow-through effects. Industry-specific forecast inputs captured EU Green Deal active mobility funding disbursement trajectories and mid-drive motor system market share assumptions.
Caveats apply where raw material cost volatility, frame standard proliferation, or substitution by integrated motor units could materially shift the outlook. Forecasts reflect assumptions regarding certification queue durations, skilled machinist labor availability, and REACH enforcement consistency. Deviation in e-bike motor system penetration rates or European smelter energy pricing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Mining Vehicle AC Kits Market
Vehicle Components
Mechanical Control Cables Market
Vehicle Components
Vehicle Radiator Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Fuel Sensor Market
Vehicle Components
Navigation Light Market
Vehicle Components
Wheel Seals Market
Vehicle Components
Vehicle Air Deflector Market
Vehicle Components
Bicycle Chain Tensioner Market
Vehicle Components
China Automotive Carbon Fiber Composites Market
Vehicle Components
Automotive Steering Shaft Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Car Sunshade Market
Vehicle Components
Automotive Air Flow Sensors Market
Vehicle Components
Railway Vehicle Coupler Market
Vehicle Components
Global Automotive Steering Torque Sensor Market