
 Engine Valve Market | 2026-2036
Engine Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Engine Valve Market Insights
The EU Green Deal is rebalancing material specifications across the engine valve supply chain, forcing foundries to reduce carbon intensity in steel alloy production. Eaton leverages captive metallurgy operations to secure nickel alloy supply for high-temperature exhaust valves. MAHLE anchors European OEM relationships through its Stuttgart engineering center. BorgWarner competes on hollow stem valve designs that trim reciprocating mass for turbocharged engines.
An engine valve is a precision-machined poppet that seals combustion chambers against cylinder pressure exceeding 150 bar, typically forged from austenitic steel or gamma titanium aluminide and finished by centerless grinding to micron tolerances. Its commercial purpose spans throttling intake charge, venting exhaust gas, and sustaining valve train durability across millions of cycles. Poppet valves dominate automotive applications due to mature sealing geometry and compatible mass production, while titanium intake valves claim the fastest expansion as OEMs pursue thermal efficiency and reduced valve train inertia. Reed valves retain niche positions in two-stroke motorcycles and small marine outboards where simplicity outweighs peak performance. The material split shows steel alloys commanding volume in commercial vehicles, with nickel alloys capturing margin in heavy-duty exhaust positions subject to EGR and aftertreatment thermal loads.
EPA tailpipe standards and the EU F-Gas Regulation shape product roadmaps by mandating lower methane and refrigerant leakage, which tightens sealing requirements on engine valves integrated into natural gas and CO2 heat pump compressor systems. China's MIIT enforces GB standards on fuel consumption that push domestic automakers toward lighter valve materials. Stakeholders must monitor how Euro 7 implementation timing and EPA Tier 4 final rules for off-road equipment redirect R&D spending between combustion optimization and electrification hedges.
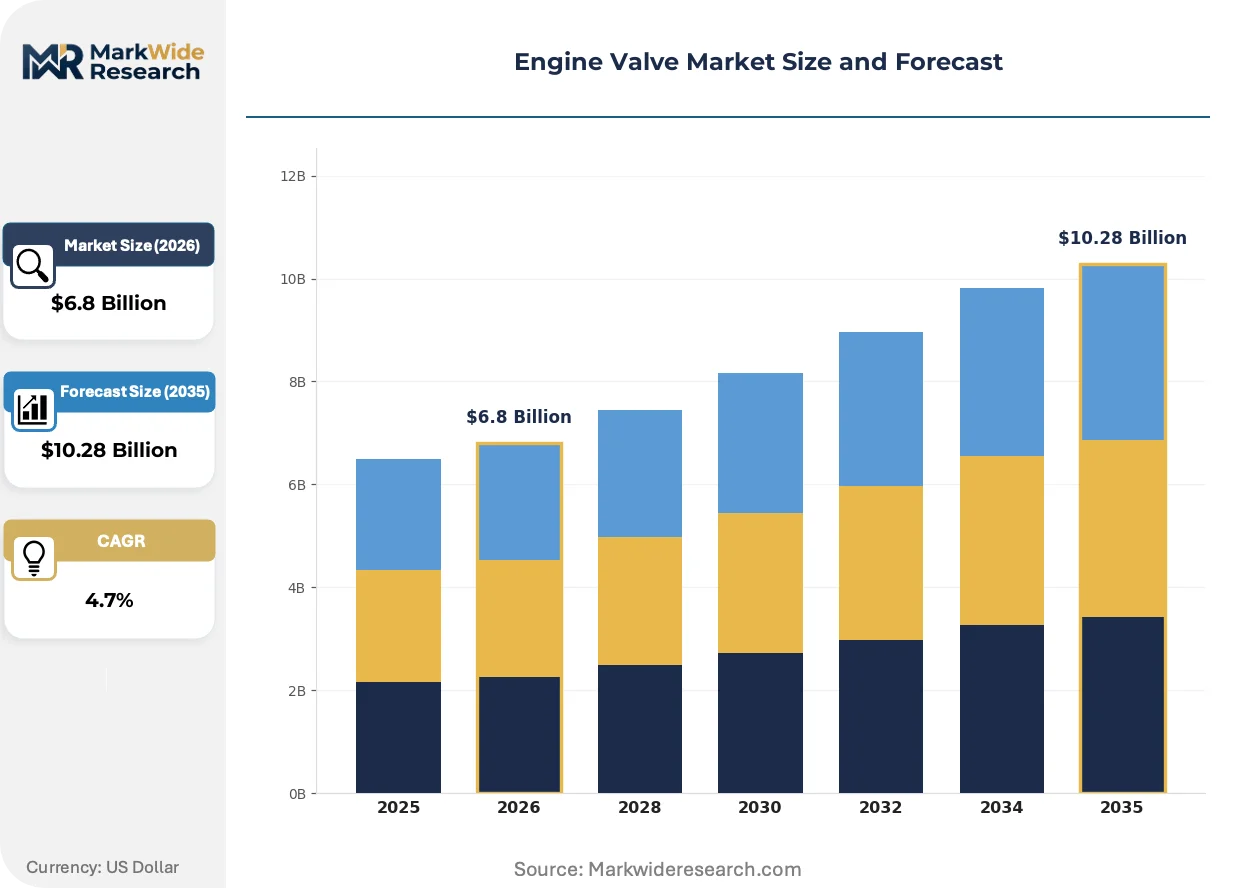
Market Dynamics
Titanium intake valves are compressing the material mix across passenger vehicle architectures as OEMs chase thermal efficiency gains and valve train mass reduction. Euro 7 and China's Stage VI regulations are simultaneously tightening exhaust valve performance specifications, forcing simultaneous lightweighting and durability investments.
Growth Catalysts
- Lightweighting mandates:OEM procurement teams are specifying gamma titanium aluminide for intake positions to cut reciprocating mass and improve fuel economy across turbocharged engine portfolios.
- Euro 7 emission standards:The EU's tightened NOx and particulate limits are extending exhaust valve service intervals and accelerating nickel alloy adoption for high-temperature EGR compatibility.
- China Stage VI regulations:Domestic automakers are upgrading valve sealing geometries and materials to meet GB standards on fuel consumption and tailpipe emissions, expanding precision manufacturing demand.
Market Restraints
- Nickel price volatility:Inconel and other nickel superalloys face input cost swings that compress margin on heavy-duty exhaust valves for commercial vehicles.
- Foundry concentration:Precision steel alloy forging capacity clusters in Germany, Japan, and the United States, creating geographic supply risk for tier-1 suppliers diversifying procurement.
- Electrification substitution:Battery electric powertrains eliminate valve train entirely, capping long-term addressable market in passenger vehicle segments where BEV penetration accelerates.
Strategic Opportunities
- Hydrogen internal combustion:Hydrogen-fueled engines require specialized exhaust valve materials resistant to high-temperature water vapor corrosion, opening premium material specifications.
- Natural gas commercial fleets:EPA methane regulations and EU F-Gas compliance are tightening sealing requirements for engine valves in CNG and LNG compressor systems serving transport and stationary power.
- Aftermarket service unbundling:Independent repair networks are capturing valve replacement demand as OEMs extend powertrain warranties, creating direct-to-workshop distribution channels.
Industry Challenges
- Centerless grinding skill scarcity:Micron-tolerance finishing operations require specialized machinist expertise that foundries struggle to recruit and retain against semiconductor and aerospace competition.
- Dual certification timelines:Suppliers must simultaneously validate valve designs against Euro 7, EPA Tier 4 final, and China Stage VI protocols, stretching engineering resources and delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engine Valve Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intake Valve, Exhaust Valve, Reed Valve, Poppet Valve, Rotary Valve Material: Steel Alloy, Titanium, Stainless Steel, Nickel Alloy, Bronze Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Agricultural Equipment, Marine Engines End User: OEMs, Engine Rebuilders, Aftermarket Suppliers, Agricultural Manufacturers, Marine Equipment Providers |
| Companies Covered | Eaton, MAHLE, DENSO, BorgWarner, Continental, Robert Bosch, Tenneco, Fuji Oozx, Rane Engine Valve, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engine Valve Market Trends and Innovations
Hollow stem geometries and advanced coatings are redefining valve performance envelopes as thermal loads escalate from downsized turbocharged engines. Material science breakthroughs and regulatory precision requirements are converging to accelerate specification changes across OEM supply chains.
Additive manufacturing is integrating conformal cooling channels into valve head designs previously impossible through conventional forging. Tier-1 suppliers are prototyping these geometries for racing and aerospace derivative applications where thermal management exceeds steel alloy limits. The technology is integrating rapid iteration cycles into valve development timelines, compressing traditional 18-month validation windows.
EPA Tier 4 final rules for off-road equipment are mandating exhaust gas recirculation rates that push valve seat temperatures beyond conventional martensitic steel tolerance. Engine manufacturers are responding with stellite-facing and plasma-transferred wire arc coatings to extend service life in construction and agricultural machinery. North American off-road OEMs are accelerating nickel alloy qualification programs to meet compliance deadlines without sacrificing engine-out emissions performance.
Fleet operators are consolidating valve procurement through long-term service agreements that bundle replacement scheduling with predictive maintenance analytics. Commercial vehicle leasing companies are displacing transactional parts purchasing with lifecycle cost contracts covering valve train refresh intervals. This pattern is most visible in German and US long-haul trucking segments where uptime guarantees dominate total cost of ownership calculations.
Engine Valve Market Segmentation
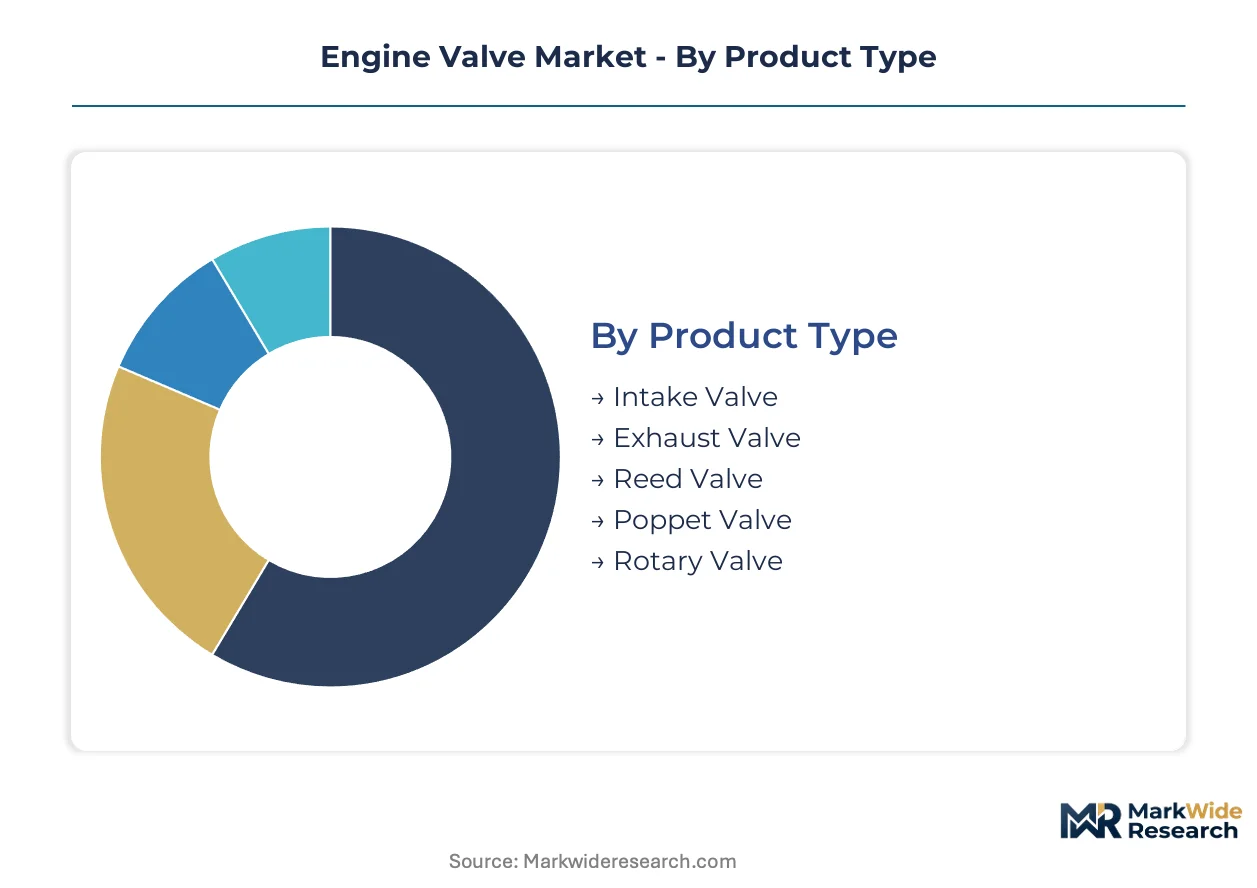
Engine valve segmentation reveals divergent capital requirements across manufacturing footprints. Material selection and application intensity determine foundry investment thresholds, with premium alloys demanding specialized metallurgy infrastructure that reshapes competitive entry barriers.
Product Type:
Capital intensity peaks with precision-forged poppet geometries requiring multi-stage heat treatment and micron-tolerance grinding centers.
- Intake Valve:Gamma titanium aluminide variants dominate passenger vehicle procurement where reciprocating mass reduction improves thermal efficiency. German and Japanese OEMs specify these for turbocharged portfolios chasing fuel economy targets.
- Exhaust Valve:Inconel-surfaced heads withstand EGR thermal loads exceeding 800°C in heavy-duty cycles. Nickel alloy specifications absorb the highest material cost premiums across commercial vehicle platforms.
- Reed Valve:Thin-spring steel flappers serve two-stroke motorcycles and marine outboards where manufacturing simplicity offsets peak performance limitations.
- Poppet Valve:Mature sealing geometry supports mass production across 90% of automotive combustion architectures.
- Rotary Valve:Specialized sleeve mechanisms persist in racing derivatives and experimental engine programs.
Poppet valves absorb the bulk of installed capacity; titanium intake valves are expanding most quickly.
Material:
Raw material sourcing concentration determines working capital intensity, with nickel superalloy procurement tying up inventory value against volatile commodity benchmarks.
- Steel Alloy:Austenitic and martensitic grades anchor commercial vehicle volume through established forging networks in Germany and Japan. EPA Tier 4 thermal limits are accelerating stellite-facing investments to extend service intervals.
- Titanium:Gamma titanium aluminide commands 3-4x steel pricing but delivers 50% mass reduction for intake positions. Precision machining requirements restrict qualified supplier pools to aerospace-adjacent foundries.
- Stainless Steel:Corrosion-resistant grades serve marine and agricultural equipment where salt exposure accelerates conventional steel degradation.
- Nickel Alloy:Inconel and Nimonic variants capture premium exhaust positions in EGR-heavy architectures.
- Bronze:Phosphor bronze retains niche applications in small-engine valve guides and bushings.
Steel alloys retain the deepest installed base; titanium specifications are climbing the fastest.
Application:
Engine load cycles and duty severity differentiate tooling amortization schedules, with commercial vehicle platforms demanding hardened valve seat inserts and extended-life coatings.
- Passenger Vehicles:Downsized turbocharged engines drive hollow-stem geometries and titanium adoption for mass reduction. OEM warranty extensions are compressing replacement intervals and shifting volume toward captive service networks.
- Commercial Vehicles:Long-haul trucking accumulates 1.5 million kilometers between overhauls, necessitating nickel alloy exhaust valves and plasma-transferred wire arc coatings. Fleet leasing companies are bundling valve train refresh into lifecycle cost contracts.
- Motorcycles:High-RPM sportbike engines specify titanium intake valves; commuter segments prioritize cost-optimized steel.
- Agricultural Equipment:EPA Tier 4 final compliance is pushing exhaust gas recirculation rates beyond conventional steel tolerance.
- Marine Engines:Salt-air corrosion resistance prioritizes stainless specifications in outboard and inboard propulsion.
Commercial vehicles command the heaviest unit content per engine; passenger vehicle lightweighting is gaining share fastest.
End User:
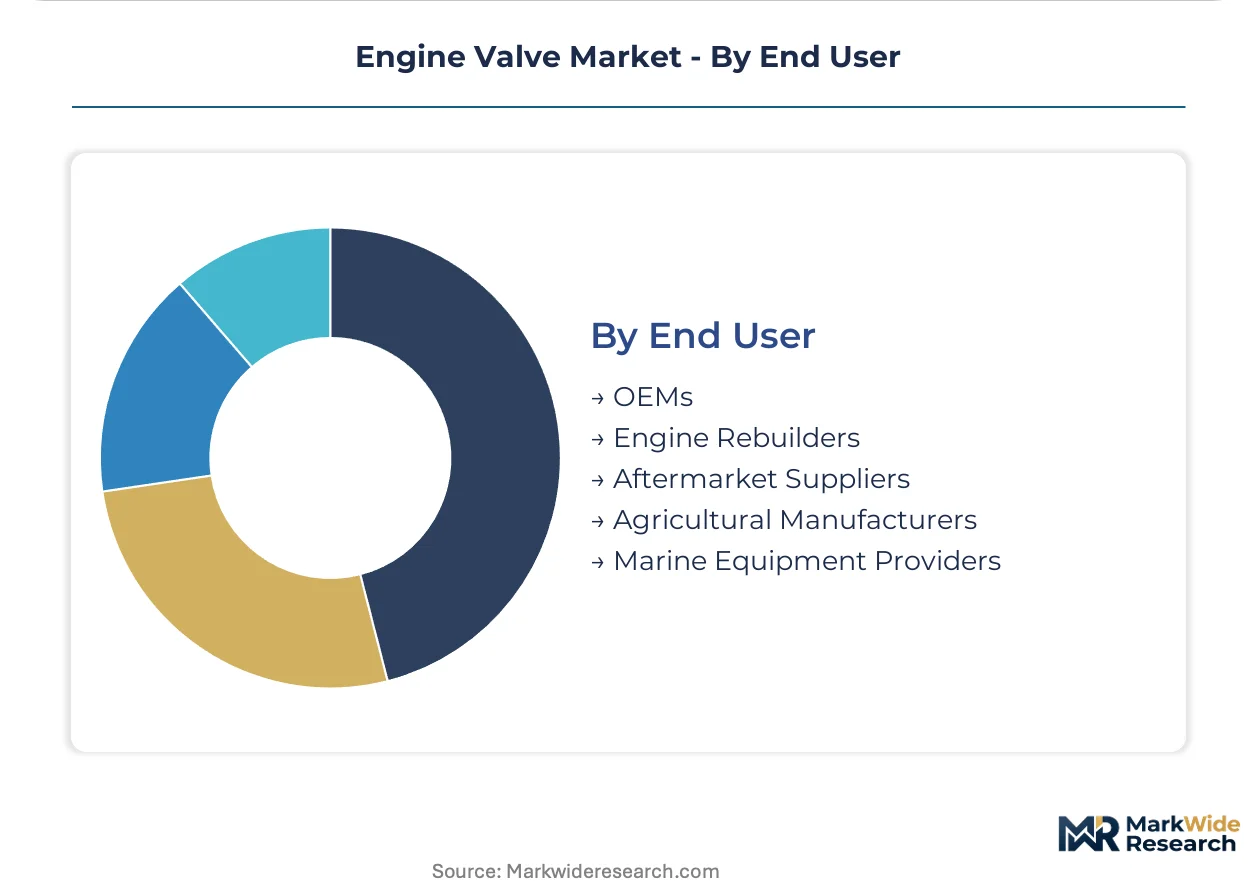
Procurement authority fragmentation shapes pricing power, with OEM captive supply agreements constraining independent aftermarket access to original specifications.
- OEMs:Volkswagen, Toyota, and Ford direct valve specifications through approved supplier lists requiring dual certification against Euro 7 and EPA protocols. Eaton and MAHLE anchor these relationships through captive metallurgy and regional engineering centers.
- Engine Rebuilders:Independent remanufacturers source replacement valves through distributor networks, facing specification gaps as OEMs restrict access to proprietary alloy grades.
- Aftermarket Suppliers:Workshop-direct channels are capturing warranty-extension service demand through predictive maintenance bundling.
- Agricultural Manufacturers:Deere and CNH Industrial specify hardened exhaust valves for construction and harvest equipment EGR compliance.
- Marine Equipment Providers:Mercury Marine and Volvo Penta prioritize corrosion-resistant specifications for saltwater operating environments.
OEMs concentrate procurement volume; aftermarket suppliers are expanding most quickly through service unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors precision manufacturing for automotive engine valves, hosting engineering centers that translate Euro 7 specifications into production protocols for tier-1 suppliers across Germany, Japan, and the United States.
Germany
Baden-Württemberg's automotive corridor drives titanium intake valve adoption for downsized turbocharged engines. KBA enforces Euro 7 pre-certification timelines that compress supplier validation windows. Stuttgart's captive metallurgy operations secure nickel alloy supply chains for high-temperature exhaust positions.
Japan
Tokyo-Nagoya industrial belt concentrates hollow-stem valve manufacturing for hybrid powertrain portfolios. METI coordinates JIS standard revisions that align with EPA Tier 4 final protocols for export equipment. Toyota City suppliers integrate gamma titanium aluminide specifications into mass production lines.
United States
Michigan's powertrain engineering cluster serves Detroit Three procurement for commercial vehicle exhaust valves. EPA Tier 4 final rules mandate EGR rates that exceed conventional steel tolerance, accelerating stellite-facing investments. Ann Arbor technical centers prototype hydrogen combustion valve materials for future OEM programs.
China
Yangtze River Delta foundries scale precision forging capacity for domestic automakers upgrading to Stage VI compliance. MIIT enforces GB standards on fuel consumption that push lightweight valve material adoption. Shanghai engineering centers localize titanium machining expertise previously imported from aerospace suppliers.
Engine Valve Market Competitive Landscape
The competitive structure tilts toward integrated metallurgy specialists with captive forging capacity. Supplier concentration clusters around three strategic archetypes: diversified automotive component conglomerates with valve divisions, dedicated valve manufacturers with precision grinding specialization, and materials-science-forward players leveraging aerospace alloy expertise. Dominant competitive moves include backward integration into nickel alloy supply and regional engineering center establishment to anchor OEM relationships.
Among diversified automotive suppliers, Eaton, MAHLE, and BorgWarner occupy positions that exemplify the integrated-metallurgy archetype. Eaton represents the captive supply chain model through in-house alloy production. MAHLE anchors European OEM relationships through regional engineering presence. BorgWarner exemplifies hollow-stem design specialization for mass-reduction applications. These three entities collectively illustrate how competitive positioning depends on material science depth and geographic proximity to precision manufacturing clusters.
| Leading Market Players |
|---|
| Eaton |
| MAHLE |
| DENSO |
| BorgWarner |
| Continental |
| Robert Bosch |
| Tenneco |
| Fuji Oozx |
| Rane Engine Valve |
| Others |
Pricing and Supply Chain Analysis
Nickel price volatility on the London Metal Exchange cascades through engine valve supply chains into three distinct pricing tiers: gamma titanium aluminide for passenger vehicle intake positions, nickel superalloy specifications for heavy-duty exhaust valves, and commodity steel alloys anchoring commercial vehicle volume procurement.
Pricing Analysis
Uptime guarantees in commercial vehicle fleet contracts anchor value-based pricing for premium exhaust valve specifications. Three-tier pricing structure across premium, standard, and economy levels separates nickel alloy EGR-compatible valves from stellite-faced steel variants and uncoated commodity grades. Cost compression in the steel tier is intensifying because foundries compete for shrinking ICE procurement volume as OEMs extend powertrain warranties. Independent engine rebuilders exhibit highest price sensitivity, while captive OEM supply agreements show lowest elasticity due to qualification lock-in.
Supply Chain Analysis
Euro 7 pre-certification timelines and EPA Tier 4 final protocols gate supplier qualification, restricting precision forging capacity to established players with validated heat treatment protocols. Geographic concentration clusters in Germany, Japan, and the United States for austenitic steel forging, with gamma titanium aluminide machining capacity tethered to aerospace-adjacent foundries in these same markets. Raw material dependencies center on nickel superalloy ingots, gamma titanium aluminide feedstock, and specialty stellite facing rods. Single-source vulnerability persists for Inconel supply through concentrated metallurgy operations. Distribution runs through tier-1 automotive supplier networks into OEM assembly plants, with aftermarket channels displacing direct procurement through predictive maintenance bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Euro 7 emission standards construct a cost-of-compliance moat that favors incumbent suppliers with validated dual-certification capabilities against EPA and China Stage VI protocols, raising capital barriers for unqualified entrants.
For Market Incumbents: Cement captive metallurgy advantages through backward integration into nickel alloy supply for high-temperature exhaust positions, while expanding hollow-stem valve production capacity in Stuttgart and Nagoya engineering corridors. Electrification substitution in passenger vehicles threatens long-term volume; defend through hydrogen combustion valve R&D programs and natural gas fleet service contracts. For New Entrants and Emerging Players: Begin with aftermarket service unbundling for commercial vehicle valve train refresh intervals, where independent repair networks capture demand from OEM warranty extensions. Agricultural equipment EGR compliance presents the most penetrable application segment given EPA Tier 4 final thermal load requirements exceeding conventional steel tolerance. Pursue direct-to-workshop distribution partnerships bypassing tier-1 supplier gatekeeping. For Investors and Strategic Acquirers: The window for entry favors materials-science-forward players with aerospace alloy expertise transferable to gamma titanium aluminide valve specifications. Long-term viability hinges on positioning for hydrogen internal combustion and natural gas commercial fleet transitions rather than pure ICE volume exposure. Monitor BEV penetration rates in passenger vehicle segments as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Supply | Eaton's captive metallurgy secures Inconel feedstock against LME price volatility for EGR-heavy exhaust positions. |
| Hollow-Stem Valve Design Specialization | BorgWarner's mass-reduction geometries capture turbocharged engine procurement from German and Japanese OEMs. |
| Regional Engineering Center Establishment | MAHLE's Stuttgart presence anchors Euro 7 specification translation for tier-1 automotive relationships. |
| Hydrogen Combustion Material Qualification | Ann Arbor technical centers prototype corrosion-resistant exhaust alloys for future OEM powertrain programs. |
| Predictive Maintenance Service Bundling | Fleet operators consolidate valve procurement through lifecycle cost contracts covering million-kilometer refresh intervals. |
Research Methodology
Trade databases, SEC filings from automotive component suppliers, and vehicle production registries formed the secondary backbone, cross-referenced with primary interviews involving tier-1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and foundry operations directors. Bottom-up and top-down triangulation validated segment-level volume estimates against aggregate market sizing.
Bottom-up modeling of valve content per vehicle by propulsion architecture and application intensity converged with top-down macroeconomic drivers across the analysis window. Segmentation dimensions included material grade, product type, application severity, and end-user procurement authority. CAGRs derived from regression analysis of historical production data and regulatory compliance timelines, incorporating nickel price index trajectories and OEM lightweighting procurement patterns as industry-specific inputs.
Electrification substitution rates, nickel commodity volatility, and Euro 7 implementation delays are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on BEV penetration curves and thermal efficiency investment priorities. A model refresh is warranted upon material change in hydrogen combustion commercialization timelines or EPA Tier 4 final enforcement stringency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Sideloaders Market
Vehicle Components
Idler Arm Market
Vehicle Components
Piston Market
Vehicle Components
Ambulance Vehicles Market
Vehicle Components
Automotive Composite Suspension Components Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Railroad Equipment Manufacturing Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
High Security Registration Plates Market
Vehicle Components
EGR Valve Market
Vehicle Components
Russia Automotive Glass Fiber Composites Market
Vehicle Components
Intake-Air Temperature Sensor Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
Automotive Aftermarket Shock Absorbers Market
Vehicle Components
Steel and Rubber Tracks Market
Vehicle Components
Suction Road Sweeper Market