
 Steel and Rubber Tracks Market | 2026-2036
Steel and Rubber Tracks Market Size, Share, and Industry Trends Forecast 2026-2036
Steel and Rubber Tracks Market Insights
Subscription-based telematics and predictive maintenance programs are pivoting how fleet operators procure track systems, shifting capital expenditure into operational contracts. Bridgestone Corporation leverages its integrated rubber compounding expertise to control material quality from compound formulation to finished track. Camso anchors North American distribution through dense dealer networks serving construction and agriculture segments. Titan International competes on manufacturing scale, operating dedicated steel track forging facilities that supply mining-class undercarriage.
Steel and rubber tracks are reinforced continuous belt structures, typically incorporating embedded steel cables, rubber elastomer compounds, and molded tread patterns, designed to distribute vehicle weight across soft or uneven terrain while providing tractive force. The primary purpose is converting machine power into ground mobility for equipment operating in conditions where wheeled configurations would sink or lose grip. Rubber track types command premium positioning in compact equipment where surface damage minimization determines jobsite access, while steel variants dominate mining applications where abrasion resistance and load-bearing capacity define lifecycle economics. Application segmentation shows construction absorbing the largest volume base, though agriculture is registering the fastest replacement frequency as seasonal intensity accelerates wear rates.
EPA emission regulations in the United States constrain undercarriage weight budgets, compelling track suppliers to optimize steel-to-rubber ratios without sacrificing durability. ISO 10265 and SAE J1116 establish dimensional and performance baselines that govern interchangeability and safety certification across OEM platforms. Stakeholders must monitor how EU machinery directives and emerging carbon-border adjustments reshape material sourcing decisions for steel-cored track production.
Market Dynamics
Subscription-based telematics programs are compressing replacement cycles and shifting fleet procurement from capital expenditure to operational contracts, forcing track suppliers to restructure pricing and service bundling.
Growth Catalysts
- EPA Tier 4 Final emission standards:These United States regulations mandate lighter undercarriage designs that favor composite rubber track technologies over conventional steel configurations in compact equipment.
- Soybean mechanization in Brazil's agricultural heartland:Intense seasonal field operations accelerate wear rates and drive aftermarket track consumption at replacement frequencies exceeding construction applications.
- Embedded steel cable reinforcement systems:Advanced cable geometries distribute dynamic loads across rubber matrices, extending service intervals in high-impact mining environments.
Market Restraints
- Natural rubber price volatility:Concentrated sourcing from Southeast Asian plantations exposes compounders to supply shocks that compress margin structures without corresponding pricing power.
- Steel forging capacity concentration:Mining-class track production depends on a limited base of specialized forging facilities, creating bottlenecks during demand surges.
- Technical limitation in heat dissipation:Continuous high-speed operation degrads rubber elastomer bonds faster than steel link alternatives, restricting rubber track penetration in long-haul applications.
Strategic Opportunities
- Underpenetrated precision agriculture in Eastern Europe:Poland and Ukraine show accelerating tractor fleet modernization that outpaces established dealer service networks for track conversion.
- EU Green Deal carbon-border adjustment mechanisms:These policies will penalize carbon-intensive steel production, creating first-mover advantage for suppliers with low-emission forging partnerships.
- Convergence of IoT sensors with predictive algorithms:Real-time tread wear monitoring enables just-in-time replacement scheduling, locking fleet operators into integrated hardware-software contracts.
Industry Challenges
- ISO 10265 and SAE J1116 certification timelines:Interchangeability testing protocols require 18-24 month validation cycles that delay new product launches behind competitor entries.
- Compound formulation expertise scarcity:The specialized knowledge bridging polymer science and terrain-specific tread design concentrates among retiring chemist cohorts in Japanese and German supplier bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel and Rubber Tracks Market |
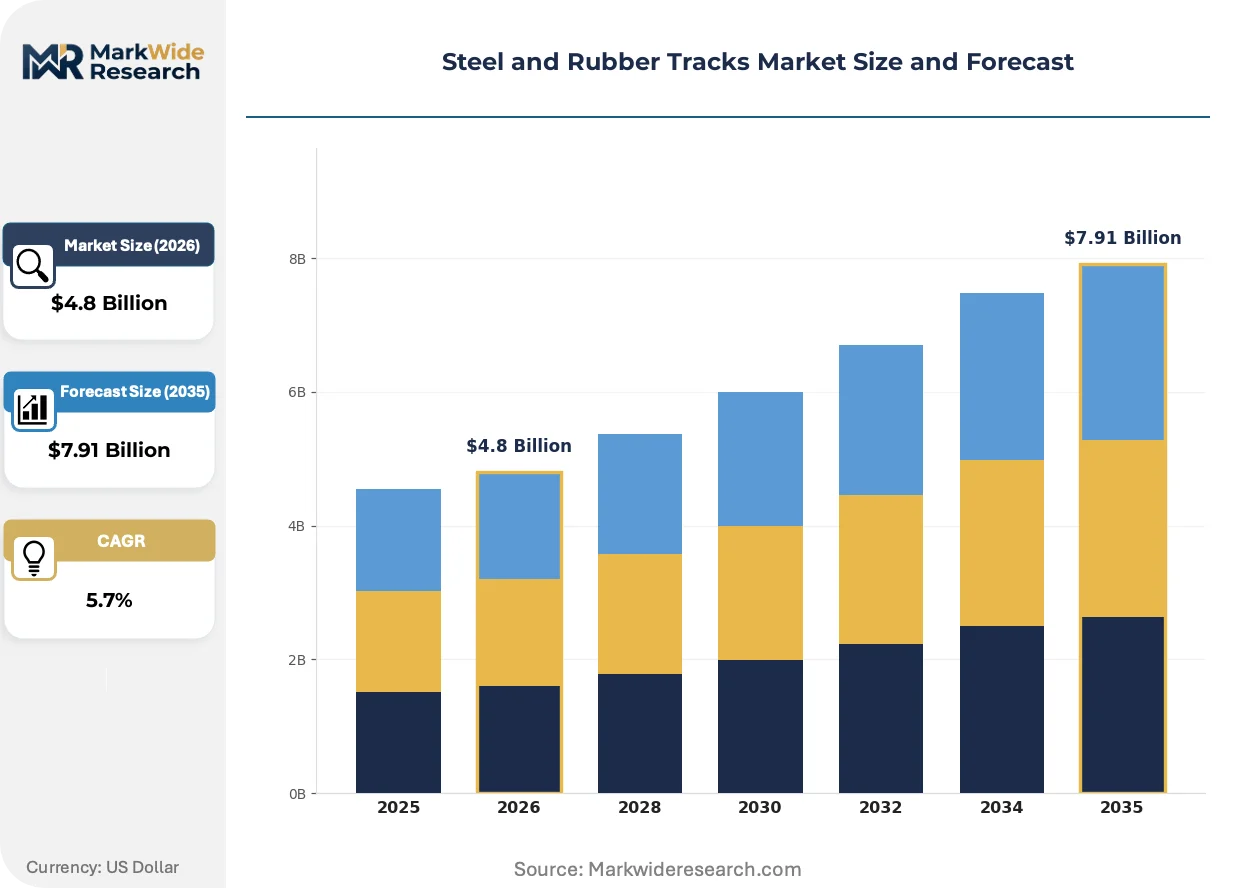
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Track Type: Rubber, Steel, Hybrid, Composite Application: Construction, Agriculture, Mining, Forestry Vehicle Type: Excavators, Bulldozers, Agricultural Tractors, Compact Track Loaders End User: Contractors, Farmers, Mining Companies, Forestry Operators |
| Companies Covered | Bridgestone Corporation, Camso, Continental AG, Titan International, Trelleborg AB, Soucy, McLaren Industries Inc., Global Track Warehouse, Mattracks Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel and Rubber Tracks Market Trends and Innovations
Track system architecture is fragmenting into interchangeable subassemblies that separate tread, carcass, and drive components, enabling field-level customization without full replacement.
Continuous belt manufacturing is modularizing around discrete drive lug and tread segment attachment systems. Compact track loader OEMs in North America are specifying these configurations for rapid field reconfiguration between soft-terrain and abrasive-surface operations. The approach is modularizing supplier ecosystems by decoupling carcass producers from tread pattern specialists.
REACH substance restrictions in Europe are phasing out specific aromatic oil plasticizers used in rubber compounding. Compounders must reformulate traction elastomers using alternative process oils that meet SVHC thresholds without sacrificing cold-climate flexibility. Agricultural track suppliers serving Nordic markets face accelerated reformulation deadlines that compress R&D resource allocation.
Fleet operators are unbundling track procurement from machine purchase decisions, treating undercarriage as separate lifecycle cost centers. Construction rental companies in Germany and Austria now specify track replacement reserves in operating lease structures, displacing traditional OEM captive parts programs. This behavioral shift concentrates purchasing authority with specialized aftermarket distributors possessing technical service capabilities.
Steel and Rubber Tracks Market Segmentation
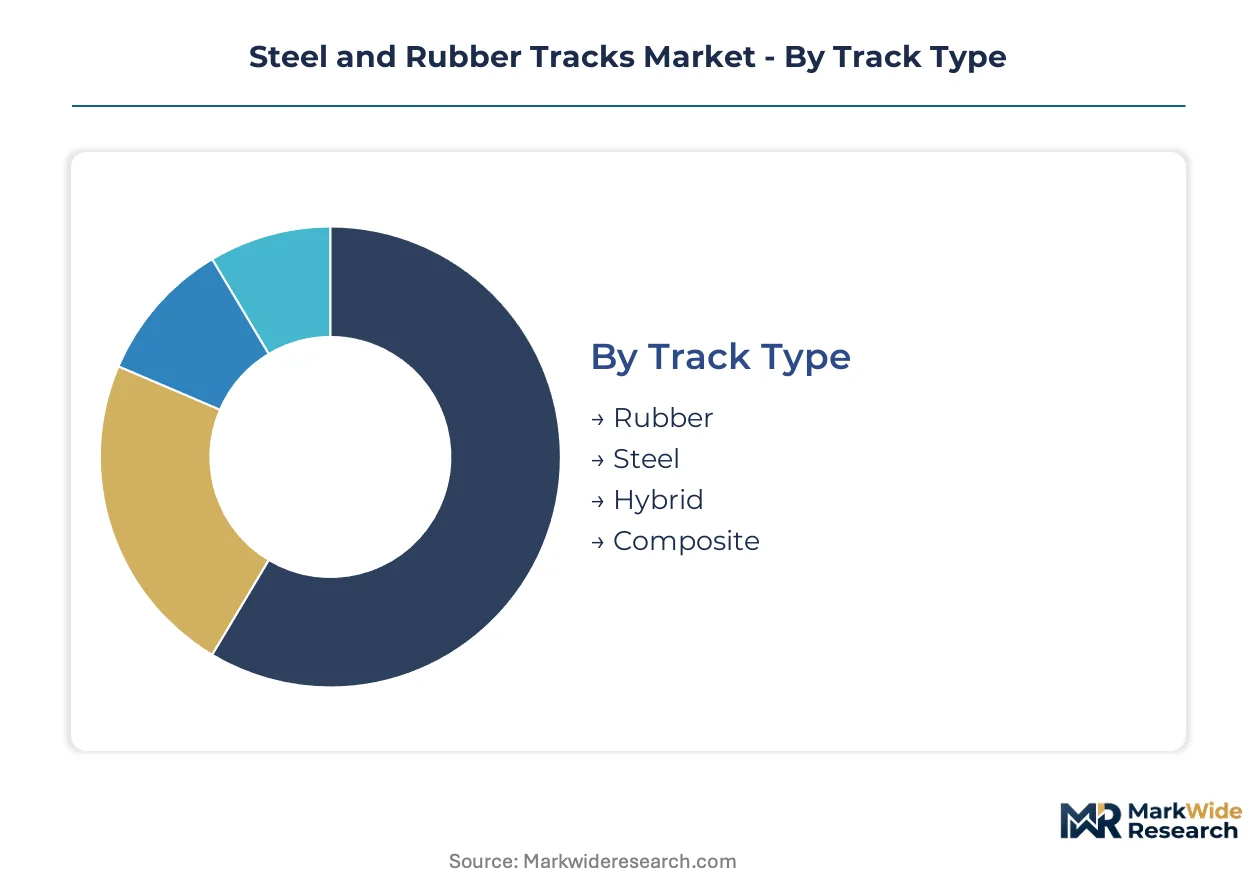
Segmentation in the Steel and Rubber Tracks Market reveals how material composition, equipment integration, and operator economics create distinct competitive arenas. Each dimension carries different margin structures, replacement cycles, and supplier capability requirements.
Track Type:
Rubber variants command premium positioning in volume terms, while steel configurations anchor the value base through mining-class durability requirements.
- Rubber:Continuous elastomer belts with embedded steel cable reinforcement distribute weight across soft terrain without surface damage. Demand concentrates in North American compact track loader fleets where commercial landscaping jobsite access depends on minimal ground disturbance.
- Steel:Forged link assemblies with hardened bushings and pins deliver abrasion resistance in high-impact extraction environments. Mining operations in Western Australia and Chile's Atacama deploy these configurations where lifecycle cost economics override acquisition price sensitivity.
- Hybrid:Combines rubber carcass with steel tread segments for intermediate duty cycles in mixed-terrain construction.
- Composite:Advanced polymer matrices with discontinuous fiber reinforcement target EPA Tier 4 Final weight reduction mandates in compact equipment.
Mature deployment sits with Steel in mining extraction. Newer deployment is concentrated in Composite formulations responding to emission-driven undercarriage lightweighting.
Application:
Construction absorbs the largest installed base, though agriculture generates replacement revenue fastest due to seasonal intensity compressing wear intervals.
- Construction:Earthmoving and grading operations drive rubber track consumption in urban infill projects where surface preservation determines equipment selection. Japanese and German rental fleets specify rapid-tread-change configurations to minimize downtime between asphalt and dirt assignments.
- Agriculture:Tractor and harvester applications in Brazil's Mato Grosso and Goiás states experience replacement frequencies exceeding construction by 40% due to extended seasonal operating hours and abrasive soil conditions.
- Mining:Surface extraction equipment in South Africa's platinum belt and Canada's oil sands demands forged steel undercarriage with 10,000+ hour service intervals.
- Forestry:Forwarder and harvester tracks in Nordic markets prioritize cold-climate rubber compound flexibility per REACH-compliant plasticizer formulations.
Volume leadership resides with Construction. Steepest expansion trajectory belongs to Agriculture as precision farming mechanization accelerates in Eastern Europe and South America.
Vehicle Type:
Excavators dominate unit shipments, while compact track loaders represent the fastest-growing integration platform for rubber track systems.
- Excavators:Crawler-mounted hydraulic machines from 1.5 to 800 metric tons deploy both rubber and steel configurations depending on mobility requirements. Urban utility contractors in the United States favor rubber-belted mini-excavators for sidewalk and backyard access.
- Bulldozers:High-horsepower earthmovers in mining and heavy civil applications require segmented steel track with elevated sprocket designs for undercarriage protection in rock and debris.
- Agricultural Tractors:Row-crop and specialty tractors in India's Punjab and Haryana states convert from wheeled to tracked configurations for paddy field flotation.
- Compact Track Loaders:Skid-steer alternatives with rubber over-the-tire tracks command premium pricing in North American landscaping and material handling where surface damage liability constrains wheeled equipment deployment.
Replacement part concentration aligns with Excavators. Fastest-growing integration opportunity centers on Compact Track Loaders as commercial landscaping fleet operators accelerate adoption.
End User:
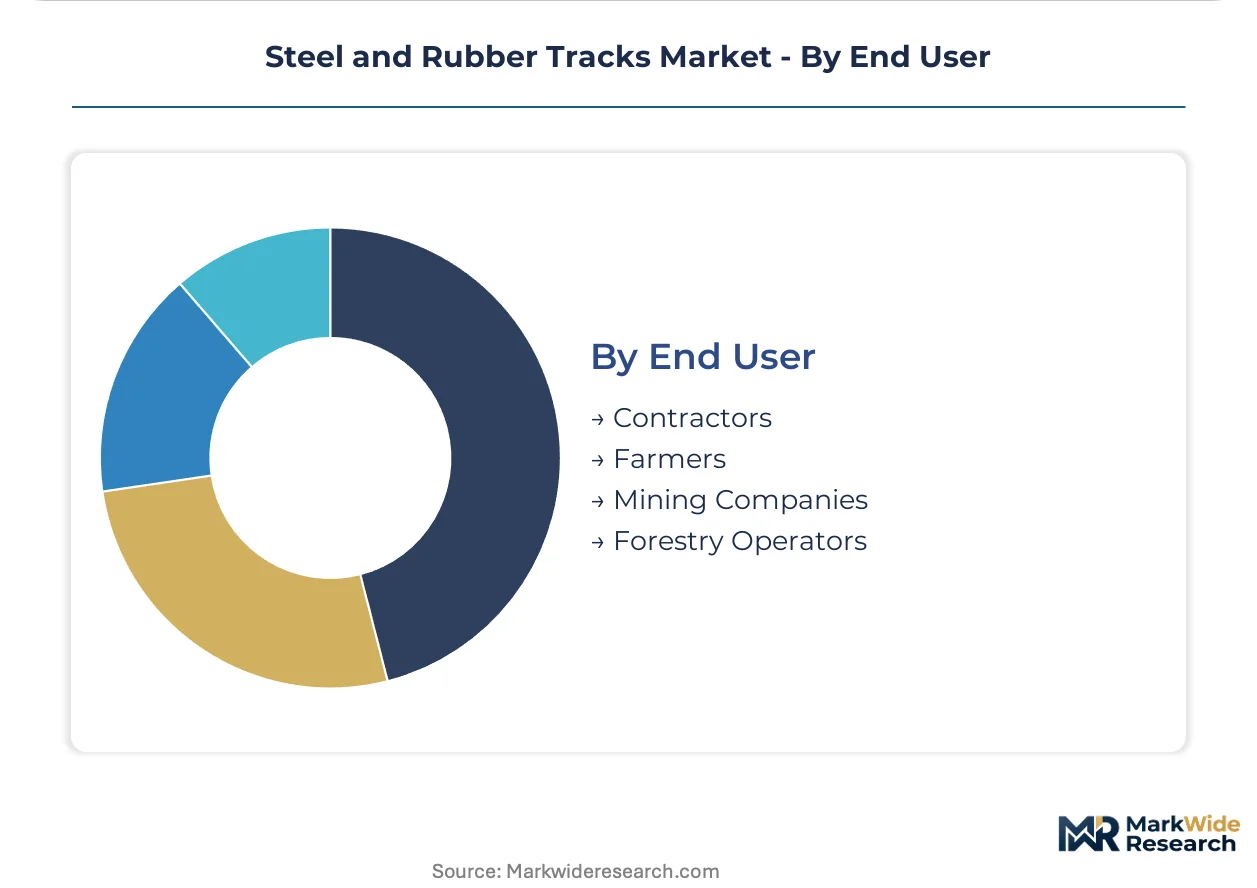
Contractors and farmers split procurement authority, with mining companies consolidating purchasing through integrated maintenance contracts.
- Contractors:General and specialty construction firms in Australia's Queensland and Victoria operate mixed fleets with segmented track procurement strategies. Rental company consolidation in Germany and Austria shifts purchasing toward aftermarket distributors with technical service capabilities.
- Farmers:Individual and cooperative agricultural operators in Ukraine's Poltava and Vinnytsia oblasts modernize tractor fleets faster than dealer service networks can provision track conversion expertise.
- Mining Companies:Integrated operators in Peru's copper belt and Indonesia's nickel concessions negotiate lifecycle cost contracts directly with forging specialists, bypassing traditional OEM parts channels.
- Forestry Operators:Mechanized harvesting contractors in Finland and Sweden face accelerated REACH reformulation deadlines for cold-climate rubber compounds.
Consolidated procurement authority rests with Mining Companies. Fragmented decision-making characterizes Farmers, creating aftermarket distributor opportunity in underpenetrated service territories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany, Japan, and the United States where forging and compounding capabilities anchor supply. Consumption spreads across construction and agricultural belts in Brazil, Australia, and Eastern Europe where fleet replacement cycles drive aftermarket demand.
United States
Compact track loader fleets in commercial landscaping accelerate rubber track replacement cycles. EPA Tier 4 Final emission standards constrain undercarriage weight budgets, favoring composite formulations. Dealer networks in Texas and the Midwest anchor distribution for construction aftermarket segments.
Brazil
Soybean mechanization in Mato Grosso and Goiás drives aftermarket track consumption at frequencies exceeding construction applications. ANVISA regulates industrial chemical inputs for rubber compounding. Agricultural equipment clusters in Ribeirão Preto and Sorocaba concentrate dealer service capacity for track conversion.
Germany
Construction rental companies in Bavaria and North Rhine-Westphalia unbundle track procurement from machine purchases. REACH substance restrictions phase out aromatic oil plasticizers in rubber compounding. Industrial machinery manufacturers in Baden-Württemberg specify rapid-tread-change configurations for mixed-terrain operations.
Australia
Surface extraction operations in Western Australia's Pilbara region demand forged steel undercarriage with extended service intervals. The country's national mining safety regulator mandates interchangeability certification for track system replacements. Equipment maintenance hubs in Perth and Mackay consolidate procurement through integrated lifecycle contracts.
Poland
Precision agriculture mechanization accelerates tractor fleet modernization faster than dealer networks can provision track conversion expertise. EU machinery directives govern safety certification and dimensional interchangeability. Agricultural cooperatives in Greater Poland and Lower Silesia drive demand for flotation track systems in row-crop applications.
Steel and Rubber Tracks Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the value chain. Integrated rubber compounders and forging specialists anchor the supply base, while regional distributors and service networks fragment downstream channels. Three archetypes dominate: integrated material-science conglomerates controlling compound formulation, specialized forging operators serving mining-class durability requirements, and aftermarket distributors bundling technical service with replacement logistics. Competitive moves center on captive supply of raw materials and predictive maintenance software integration.
Within the integrated-materials tier, Bridgestone Corporation exemplifies backward integration into rubber compounding, while Continental AG and Trelleborg AB occupy positions bridging polymer science with terrain-specific tread design. Among North American distributors, Camso anchors dense dealer networks serving construction and agriculture segments. At the scale-driven end, Titan International represents manufacturing concentration through dedicated steel track forging facilities. Soucy and McLaren Industries Inc. sit within the aftermarket-specialist archetype, bundling technical service capabilities with replacement track logistics.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Camso |
| Continental AG |
| Titan International |
| Trelleborg AB |
| Soucy |
| McLaren Industries Inc. |
| Global Track Warehouse |
| Mattracks Inc. |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up aftermarket distributors in North America and Europe anchor pricing discipline through consolidated procurement pools that extract volume concessions from compounders and forging specialists alike. Their financing structures reward inventory turns over margin capture, compressing supplier pricing power while concentrating distribution leverage in fewer hands.
Pricing Analysis
Margin tightening in rubber track tiers reflects natural rubber price volatility from Southeast Asian plantations, while steel configurations hold firmer due to forging capacity scarcity. Three-tier pricing structure across OEM-captive, premium aftermarket, and economy replacement levels separates warranty-backed installations from dealer-service bundles and direct-import alternatives. Cost-down pressure on economy tiers accelerates because Brazilian and Polish farmers prioritize acquisition price over service intervals. Mining companies show least price sensitivity, accepting lifecycle cost contracts that amortize premium steel track across extended operating hours.
Supply Chain Analysis
Regional distribution centers in Texas, São Paulo state, and Germany's Rhine-Ruhr corridor maintain 30-60 day forward cover against rubber price swings and forging lead time variability. Supply concentrates in Japan, Germany, and the United States for steel cable reinforcement and specialized forging; Thailand, Indonesia, and Vietnam for natural rubber latex. Raw material dependencies span carbon black from US Gulf Coast refiners, specialty alloy steels from German and Japanese mills, and aromatic oil plasticizers now restricted under REACH. Tariff exposure on Chinese steel components creates supply chain risk for North American aftermarket distributors. Distribution runs through dense dealer networks for construction and agriculture, direct procurement contracts for mining, and e-commerce channels for small fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Forging capacity scarcity for mining-class steel track props pricing power among integrated producers, creating supply-constrained conditions that favor incumbents with captive metallurgical capabilities.
For Market Incumbents: Hedge against REACH-compliant plasticizer reformulation costs by securing alternative process oil partnerships before Nordic forestry deadlines compress R&D budgets. Defensive consolidation of Eastern European dealer networks in Poland and Ukraine blocks new entrant access to precision agriculture conversion demand. Backward integration into rubber compounding, following Bridgestone's captive supply model, protects margin structures from Southeast Asian latex price shocks. For New Entrants and Emerging Players: The price-point gap between premium OEM-captive and economy direct-import tiers opens white-space for mid-market distributors bundling technical service with replacement logistics. Poland's accelerating tractor fleet modernization outpaces established dealer service capacity, creating the most penetrable geography for track conversion expertise. Target agricultural cooperatives in Greater Poland and Lower Silesia with flotation track systems priced between premium and economy alternatives, emphasizing field-level installation support. For Investors and Strategic Acquirers: Brazilian soybean mechanization intensifying replacement cycles is the leading indicator that aftermarket track consumption will sustain above-construction growth rates through the projection horizon. Long-term viability frames around compound formulation expertise scarcity as retiring chemist cohorts in Japanese and German supplier bases concentrate knowledge. Acquisition target archetype: regional distributors with dense service networks in underpenetrated agricultural territories. Watch for EU carbon-border adjustment implementation signaling low-emission forging partnership premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Captive control over REACH-compliant formulations secures margin protection against Southeast Asian supply shocks. |
| Dealer Network Consolidation in Eastern Europe | Dense service coverage in Poland and Ukraine captures precision agriculture track conversion demand faster than OEM expansion. |
| Low-Emission Forging Partnership Formation | EU Green Deal carbon-border adjustments will penalize carbon-intensive steel, rewarding early low-emission supply agreements. |
| Predictive Maintenance Software Integration | IoT-enabled tread wear monitoring locks fleet operators into recurring revenue contracts with just-in-time replacement scheduling. |
| Rapid-Tread-Change Configuration Development | Modular subassembly architectures separate carcass from tread, enabling field customization without full replacement for mixed-terrain contractors. |
Research Methodology
Document review covered SEC 10-K filings from forging and rubber compounding specialists, trade customs data from Brazil's MDIC and Germany's Destatis, and OEM technical specifications, complemented by interviews with aftermarket distribution heads, agricultural equipment procurement managers at Brazilian cooperatives, mining maintenance directors in Western Australia, and compact track loader fleet operators in Texas and the Midwest. Secondary validation drew from EPA regulatory filings on Tier 4 Final implementation, ANVISA chemical input registrations, and ISO 10265 interchangeability certification records. Bottom-up unit shipment estimates from regional dealer networks were triangulated against top-down OEM production data.
Segment-level outputs across the projection horizon reflect modeled demand for rubber, steel, hybrid, and composite track types by construction, agriculture, mining, and forestry applications, further disaggregated by excavator, bulldozer, tractor, and compact track loader vehicle classes. CAGRs were derived from replacement cycle analysis calibrated to seasonal operating intensity and soil abrasion indices. Industry-specific forecast inputs incorporated soybean planting density trends in Mato Grosso, EPA emission standard phase-in schedules, and REACH substance restriction timelines affecting cold-climate compound flexibility.
Inputs from distributor inventory systems and OEM production schedules were available through the study window; gaps in real-time fleet telematics penetration rates introduce uncertainty bands around predictive maintenance adoption curves. Forecasts reflect documented assumptions on rubber price elasticity and forging capacity expansion plans. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Heavy Vehicles Suspension Anti-Vibration Components Market
Vehicle Components
Portable Wheel Jack Market
Vehicle Components
Automotive Exhaust Gas Sensor Market
Vehicle Components
Truck Suspension System Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Two Wheeler Footrest Market
Vehicle Components
Automotive Brake Valves Market
Vehicle Components
Canada Automotive Carbon Fiber Composites Market
Vehicle Components
North America Forklift Rental Market
Vehicle Components
Automotive Displacement Sensor Market
Vehicle Components
Vehicle Air Deflector Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
Motorcycle Connectors Market
Vehicle Components
Saudi Arabia Refrigerated Trailer Market
Vehicle Components
Passenger Car Sensors Market