

4x4 Vehicle Parts and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
4x4 Vehicle Parts and Accessories Market Insights
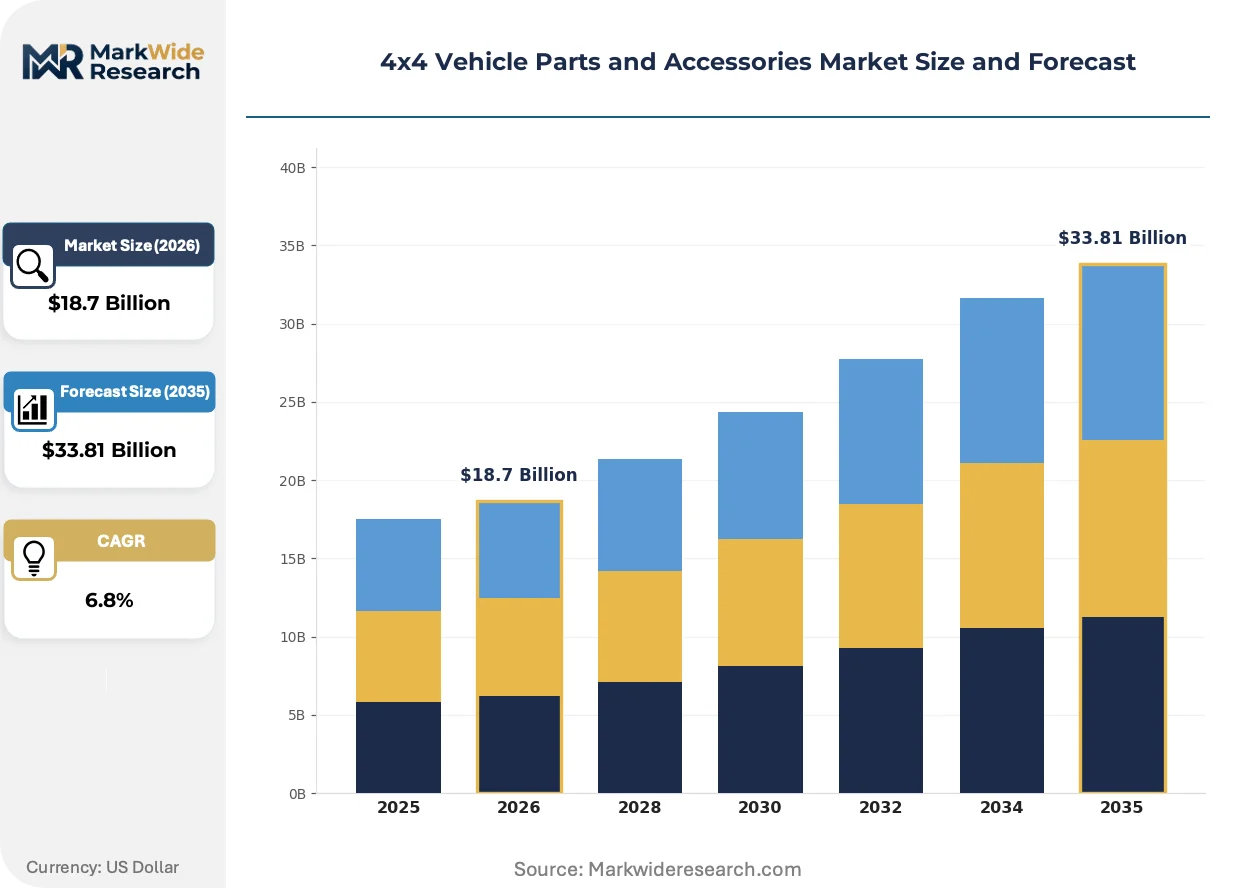
The capital-intensity divergence between integrated drivetrain suppliers and specialty accessory makers is collapsing as modular electric axle platforms lower barriers to entry. Robert Bosch leverages its mechatronics portfolio to supply integrated all-wheel-drive control units that anchor OEM relationships across multiple vehicle platforms. Continental competes through tire and chassis electronics bundling, while Warn Industries specializes in winch systems that dominate the recovery equipment segment among overlanding enthusiasts.
4x4 vehicle parts and accessories encompass engineered components designed for vehicles with dual-axle torque distribution, typically featuring locking differentials, elevated ground clearance exceeding 200 mm, and reinforced suspension geometries rated for dynamic loads beyond standard passenger specifications. These products enable traction across low-friction surfaces, protect underbody systems from impact, and extend operational range in unimproved terrain for commercial, military, and recreational operators. Tires command the largest margin pool due to compound formulation complexity and size-specific mold requirements, while suspension kits represent the fastest-growing product category as lift configurations and adaptive damping penetrate the aftermarket. Among end users, aftermarket retailers capture the broadest SKU breadth, whereas fleet operators concentrate volume in predictable replacement cycles for utility and rescue vehicle pools.
The EPA enforces emissions compliance for modified exhaust systems under the Clean Air Act, forcing aftermarket suppliers to certify catalytic converter retention or face distribution restrictions in the United States. NHTSA Federal Motor Vehicle Safety Standards govern lighting photometry and bumper impact resistance, creating product development gatekeepers that favor suppliers with in-house testing laboratories. ISO 9001 and IATF 16949 quality frameworks further shape supplier qualification for OEM channels, particularly among Japanese and German vehicle assemblers with stringent sub-tier requirements. Stakeholders must monitor evolving electrification architectures, as dual-motor torque-vectoring systems in battery-electric platforms threaten traditional mechanical four-wheel-drive component demand.
Market Dynamics
Modular electric axle platforms are collapsing the capital-intensity gap between integrated drivetrain suppliers and specialty accessory makers, enabling new entrants to compete across previously segmented product tiers.
Growth Catalysts
- Overlanding self-sufficiency builds:Recreational operators in Australia and South Africa are equipping vehicles with extended-range fuel systems and onboard power generation, expanding addressable SKU counts for aftermarket retailers.
- ISO 9001 and IATF 16949 adoption:Quality framework penetration among Japanese and German assemblers is qualifying tier-two suppliers for OEM channel access previously restricted to integrated majors.
- Dual-motor torque-vectoring architectures:Battery-electric platforms are creating demand for electronic control modules that manage axle torque distribution without mechanical differentials.
Market Restraints
- EPA Clean Air Act enforcement:Catalytic converter retention mandates for modified exhaust systems are forcing aftermarket suppliers to absorb certification costs or exit US distribution channels.
- Compound formulation concentration:Tire margin pools depend on specialized rubber chemistry controlled by a narrow supplier base in Southeast Asia, exposing buyers to input cost volatility.
- NHTSA Federal Motor Vehicle Safety Standards:In-house testing laboratory requirements for lighting photometry and bumper impact resistance favor incumbents with established certification infrastructure.
Strategic Opportunities
- Remote-area utility fleet electrification:Mine operators and agricultural contractors in South Africa require ruggedized electric axle conversions for underground and off-grid deployment.
- Adaptive damping technology convergence:Integration of sensor networks with adjustable shock absorbers enables real-time terrain response for overlanding vehicles.
- Direct-to-consumer channel expansion:Specialty winch and recovery equipment manufacturers are bypassing traditional distributor networks through platform-integrated configurators.
Industry Challenges
- Mechatronics skill scarcity:Supplier engineering teams lack cross-trained talent capable of bridging mechanical four-wheel-drive systems with electronic control architectures.
- Multi-standard certification timelines:Simultaneous EPA, NHTSA, and OEM qualification pathways extend product launch cycles by 18-24 months for exhaust and lighting components.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4x4 Vehicle Parts and Accessories Market Trends and Innovations
Electrification architectures are fragmenting the traditional mechanical four-wheel-drive supply base while regulatory tightening compresses product development timelines for emissions-critical components.
Mechanical locking differentials are decomposing as primary traction devices as fleet operators and recreational buyers adopt software-controlled brake-based torque vectoring. Commercial utility pools in Australia are retrofitting existing chassis with electronic stability programs that eliminate differential replacement cycles. This shift is compressing aftermarket demand for gear-based traction units while expanding addressable markets for control module suppliers.
REACH substance restrictions in Europe are phasing out specific rubber plasticizers and tire additives, forcing compound reformulation across winter and all-terrain product lines. German testing laboratories are certifying alternative polymer blends that maintain cold-weather elasticity without restricted phthalate content. Tire manufacturers serving EU markets are accelerating mold investments to accommodate these reformulated compounds ahead of 2025 enforcement windows.
Buyer concentration among overlanding specialty retailers is consolidating procurement leverage, compressing supplier margins across winch, lighting, and recovery equipment categories. Australian and South African distributor networks are demanding exclusive territory arrangements and volume rebate structures that mirror OEM fleet contract terms. This pattern is most visible in Perth and Johannesburg, where regional retail chains now account for majority share of premium accessory throughput.
4x4 Vehicle Parts and Accessories Market Segmentation
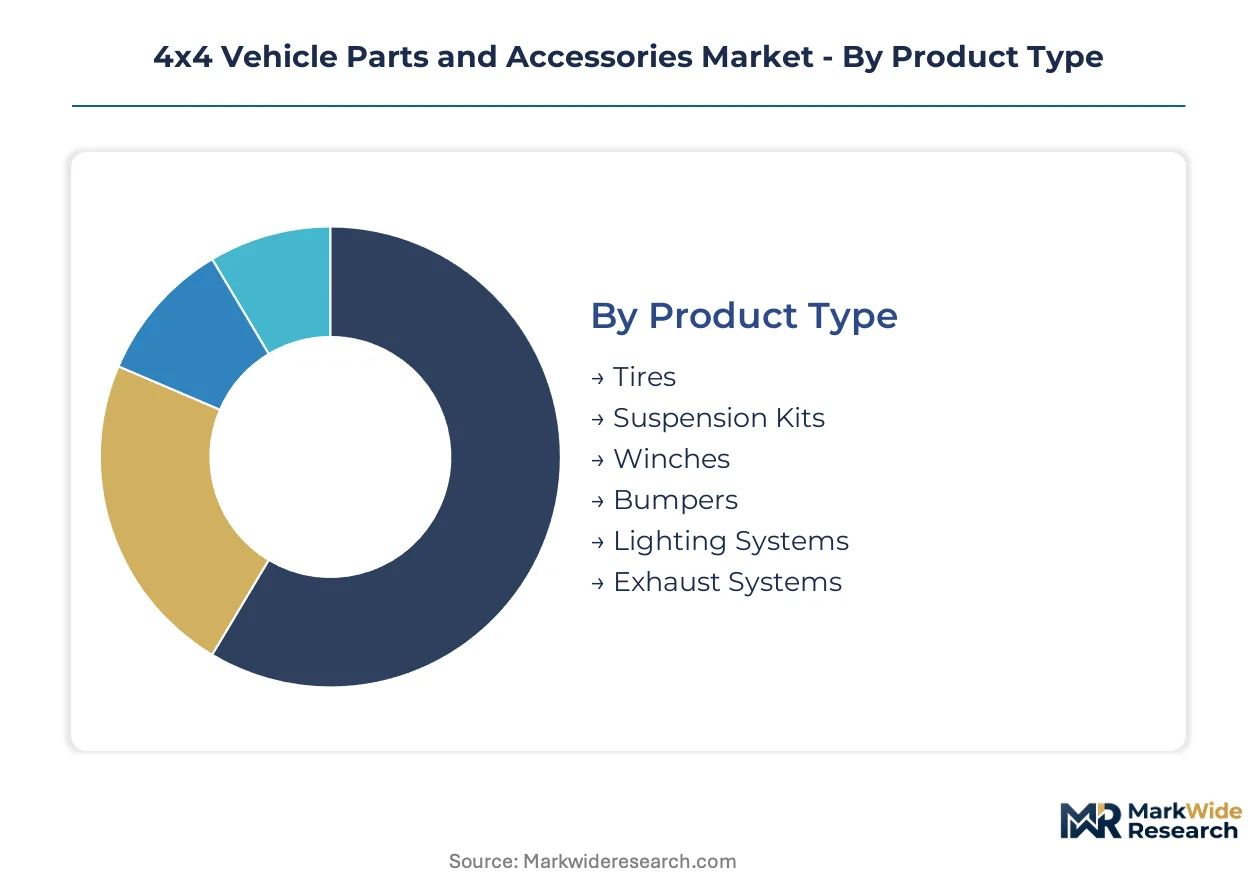
4x4 vehicle parts and accessories fragment across multiple demand axes, each with distinct procurement rhythms and margin profiles. Tires and suspension kits anchor volume, while specialized recovery equipment and expedition-grade lighting command premium positioning. Understanding these segment boundaries reveals where capital efficiency concentrates and where new entrants face steepest barriers.
Product Type:
Tires and suspension kits flow through export-heavy supply chains anchored in Southeast Asian compound manufacturing and European adaptive damping engineering, while winches and bumpers cluster in domestic North American and Australian production nodes serving regional overlanding cultures.
- Tires:Multi-layer carcass constructions with silica-enhanced tread compounds rated for sub-zero elasticity and high-heat desert endurance. Australian mining fleets and South African agricultural contractors drive bulk procurement of all-terrain specifications, though REACH-mandated plasticizer reformulation in Europe is compressing margin visibility for suppliers serving dual markets.
- Suspension Kits:Coilover assemblies and long-travel leaf spring packages with nitrogen-charged remote reservoirs enabling 300+ mm wheel articulation. Demand concentrates among recreational upgraders in Perth and Johannesburg retail networks, where lift configurations above 75 mm trigger local roadworthiness inspection requirements that vary by state jurisdiction.
- Winches:Planetary gear reduction systems with synthetic rope spooling rated for 4,500-12,000 lb pull capacity. Warn Industries and domestic Australian manufacturers dominate recovery equipment procurement for remote-area utility operators.
- Bumpers:Steel and aluminum bash plate integrations with integrated winch mounts and recovery point anchoring. South African and Australian aftermarket retailers specify high-clearance designs for game reserve and outback deployment.
- Lighting Systems:LED and HID auxiliary arrays with IP67 ingress protection and spot-flood combo beam patterns. NHTSA photometry compliance for US distribution forces dual-SKU strategies across regulatory jurisdictions.
- Exhaust Systems:Stainless steel cat-back configurations with mandrel-bent tubing and retained catalytic converter positioning. EPA Clean Air Act enforcement restricts modified system distribution to certified configurations retaining OEM emissions control hardware.
Tires hold the largest share; momentum sits with suspension kits as adaptive damping penetrates mid-tier aftermarket builds.
Application:
Utility work and rescue operations concentrate procurement in fleet contract structures with predictable replacement cycles, while overlanding and expedition applications fragment across individual enthusiast budgets with higher margin capture potential.
- Off-Roading:Competitive rock crawling and desert racing formats requiring reinforced driveline components and competition-legal roll cage integration. Australian and South African club-level racing sustains specialty fabrication demand.
- Overlanding:Extended-duration remote travel with self-sufficient power generation, water storage, and extended-range fuel systems. Perth and Johannesburg specialty retailers are consolidating procurement leverage across this segment with exclusive territory arrangements.
- Utility Work:Mine site, agricultural, and forestry operations requiring daily reliability under load. Fleet operators in South Africa's platinum belt and Australia's Pilbara region drive predictable high-volume replacement cycles for underbody protection and drivetrain components.
- Recreational Driving:Weekend trail use and camping access with moderate modification intensity. This segment bridges OEM accessory packages and aftermarket upgrade pathways.
- Rescue Operations:State emergency services and volunteer rural fire brigades requiring winch-equipped vehicles with standardized interoperability. Australian state fleet contracts specify common recovery point and lighting mount standards.
- Expedition:Long-haul international overland travel with extreme self-sufficiency requirements. Vehicle builds in this category integrate the broadest SKU breadth across all product categories.
Utility work represents the steadiest volume base; expedition applications are climbing the fastest as international route documentation and platform-integrated configurators lower planning barriers.
End User:
OEMs and fleet operators concentrate engineering validation resources and procurement scale, while aftermarket retailers and specialty garages fragment across individualized build specifications with higher service attachment potential.
- OEMs:Vehicle assemblers specifying tier-one and tier-two supplier qualification under IATF 16949 frameworks. Japanese and German manufacturers maintain the most stringent sub-tier requirements for drivetrain integration partners.
- Aftermarket Retailers:Specialty stores and online platforms curating SKU breadth for enthusiast self-installation. Australian and South African regional chains now account for majority share of premium accessory throughput through volume rebate structures.
- Fleet Operators:Utility, mining, and emergency service pools with centralized procurement and scheduled maintenance protocols. Predictable replacement cycles favor suppliers with inventory positioning near operational clusters.
- Vehicle Upgraders:Individual owners executing staged modifications across multiple purchase events. This segment exhibits highest price sensitivity and research intensity before transaction.
- Specialty Garages:Installation-focused workshops with fabrication capabilities and regulatory compliance expertise. Certification requirements for modified vehicle roadworthiness vary by Australian state and South African province.
Aftermarket retailers command the broadest SKU breadth; fleet operators deliver the most predictable volume concentration.
Distribution Channel:
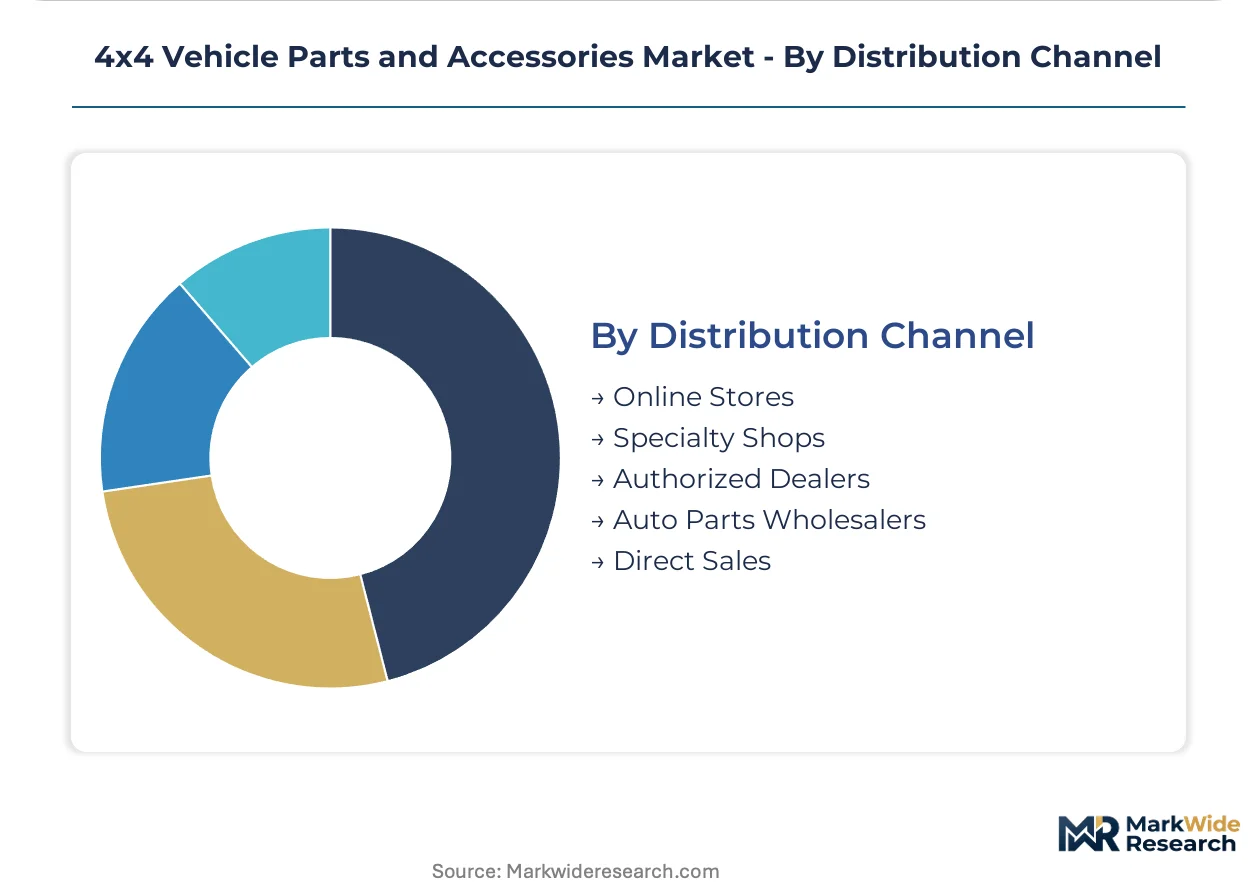
Online stores and direct sales compress distributor margin capture while accelerating configurability, whereas specialty shops and authorized dealers retain installation service attachment and warranty mediation value.
- Online Stores:Platform-integrated configurators enabling specification comparison and compatibility verification. Direct-to-consumer channel expansion is most advanced among winch and recovery equipment manufacturers bypassing traditional networks.
- Specialty Shops:Staffed by enthusiast personnel with firsthand product testing experience and installation troubleshooting capability. Perth and Johannesburg retail clusters concentrate premium accessory throughput.
- Authorized Dealers:OEM-aligned distribution with warranty integration and factory-trained technician access. Japanese and German vehicle assemblers restrict aftermarket component warranty coverage to dealer-installed configurations.
- Auto Parts Wholesalers:Volume distributors serving independent repair facilities and smaller retail accounts. This channel concentrates commodity replacement components with lower margin profiles.
- Direct Sales:Manufacturer-owned channels for specialized expedition builds and fleet conversion contracts. Remote-area utility electrification projects in South Africa increasingly route through direct specification and engineering engagement.
Specialty shops retain the largest share in premium segments; online stores are gaining share fastest as platform integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Australian and South African buyers absorb premium pricing for expedition-grade builds, while US consumers face regulatory cost compression on emissions-critical components.
United States
Overlanding culture in the Mountain West and Southwest sustains demand for self-sufficient vehicle configurations. EPA Clean Air Act enforcement restricts modified exhaust distribution to catalytic-retaining designs. Specialty retailers in Denver and Phoenix clusters consolidate procurement leverage through volume rebate structures.
Australia
Mining fleet operators in the Pilbara and agricultural contractors in Queensland drive predictable high-volume replacement cycles. TGA and state roadworthiness authorities enforce varying lift-height inspection thresholds. Perth retail chains now account for majority share of premium accessory throughput with exclusive territory arrangements.
South Africa
Platinum belt mine operators and game reserve vehicles require ruggedized underbody protection and recovery equipment. The country's national automotive regulator enforces homologation standards for modified vehicle configurations. Johannesburg specialty retailers mirror Australian procurement consolidation patterns.
Germany
REACH substance restrictions are phasing out specific tire plasticizers, forcing compound reformulation across winter and all-terrain lines. KBA certification requirements govern lighting photometry and bumper impact resistance. Testing laboratories in Baden-Württemberg certify alternative polymer blends for EU market access.
Japan
OEM assemblers maintain stringent IATF 16949 sub-tier requirements for drivetrain integration partners. METI industrial standards shape supplier qualification pathways. Tier-two manufacturers in the Chubu industrial corridor leverage quality framework penetration for channel access previously restricted to integrated majors.
4x4 Vehicle Parts and Accessories Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a two-speed competitive dynamic. Integrated majors anchor OEM relationships through mechatronics portfolios and tire-chassis electronics bundling. Specialists dominate recovery equipment and expedition-grade accessories through enthusiast channel cultivation. Competitive moves concentrate on portfolio diversification into electrification-ready components and geographic expansion through distributor network consolidation.
Within the integrated tier, Robert Bosch and Continental exemplify the mechatronics-to-drivetrain control trajectory, while Warn Industries anchors the specialist recovery equipment archetype. These three occupy positions that illustrate the capital-intensity divergence now collapsing as modular electric axle platforms lower barriers across previously segmented product tiers.
| Leading Market Players |
|---|
| ARB Corporation |
| Robert Bosch |
| Continental |
| Denso |
| Magna International |
| ZF Friedrichshafen |
| Fox Factory Holding |
| Warn Industries |
| Polaris |
| Others |
Pricing and Supply Chain Analysis
Silica-enhanced tread compounds replacing conventional carbon-black formulations in all-terrain tire production are simultaneously shifting compound sourcing toward Southeast Asian petrochemical hubs and compressing margin visibility for suppliers serving dual EU and Asia-Pacific markets. This substitution dynamic reconfigures both input cost structures and geographic procurement leverage across the tire segment.
Pricing Analysis
After-sales service and replacement cycle bundling drives lifetime value capture across fleet operator accounts. Three-tier pricing structure across premium, standard, and economy levels segments the aftermarket, with ISO 9001 and IATF 16949 certification tiers commanding measurable premiums in OEM channels. Pricing pressure stems from REACH-mandated compound reformulation costs that suppliers cannot fully pass to concentrated Australian and South African retail chains. Vehicle upgraders exhibit highest price sensitivity, while expedition-grade overlanding buyers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Inventory positioning near operational clusters in Australia's Pilbara region and South Africa's platinum belt compresses lead times for utility fleet replacement cycles. Manufacturing concentration spans Thailand and Indonesia for tire compounds, Germany for adaptive damping systems, and domestic Australian nodes for winch and bumper fabrication. Raw material dependencies include natural rubber from Southeast Asian plantations, rare earth elements for electronic control modules, and high-grade steel for recovery equipment. Single-source vulnerability concentrates in specialized rubber chemistry controlled by narrow Southeast Asian supplier bases. Distribution runs through specialty retailer networks in Perth and Johannesburg that now demand exclusive territory arrangements mirroring OEM fleet contract terms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 4x4 vehicle parts and accessories market sits in a cyclical recovery phase as mining capital expenditure rebounds across Australia's resource belt and South Africa's extractive sectors, driving predictable replacement demand for underbody protection and drivetrain components.
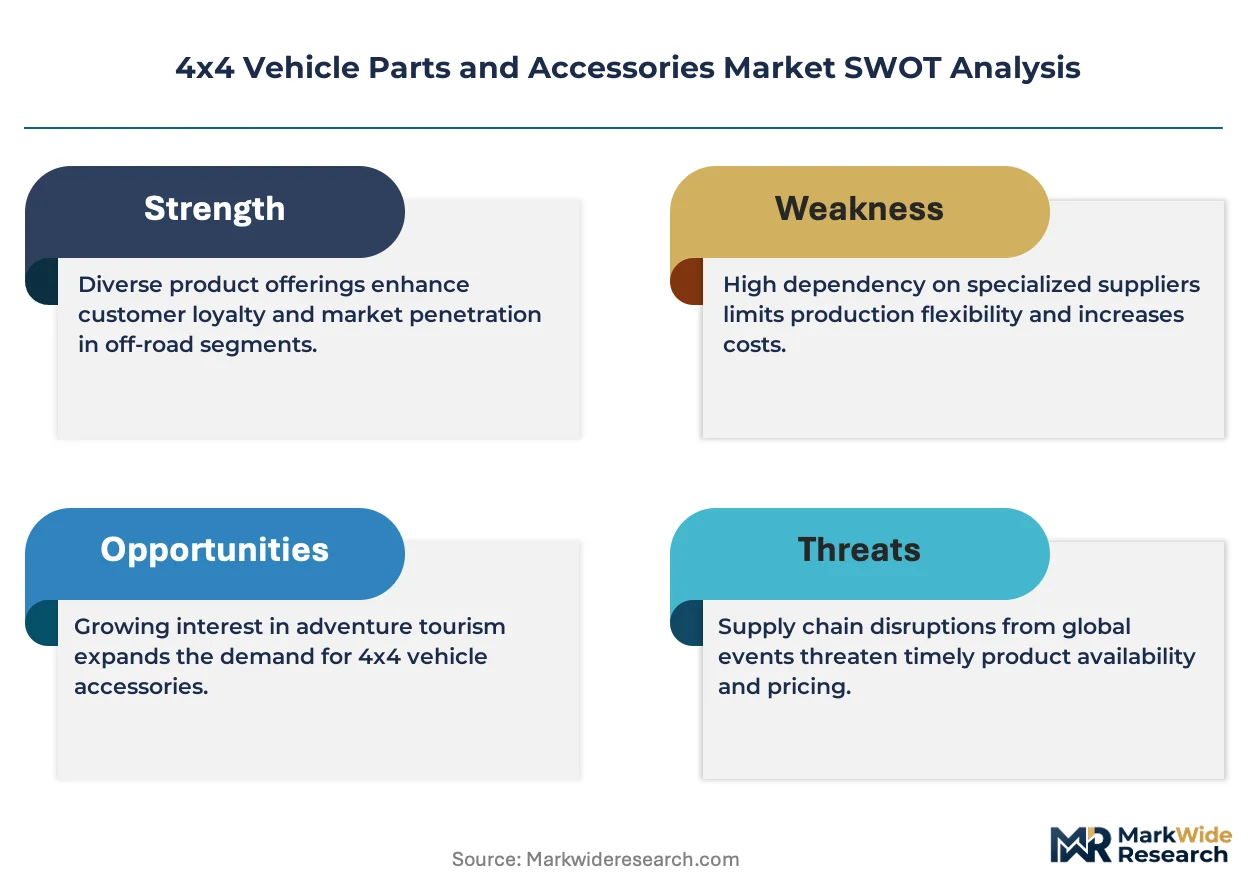
For Market Incumbents: Compound defensive positioning through backward integration into electronic control module production as dual-motor torque-vectoring architectures displace mechanical differential demand. Lock in long-term compound supply agreements with Southeast Asian petrochemical suppliers before REACH-mandated reformulation tightens input availability. Prioritize certification investment in EPA-compliant exhaust configurations and NHTSA lighting photometry to defend US distribution access against regulatory gatekeeping. For New Entrants and Emerging Players: Installation service gaps in specialty garage networks across Australian states with varying roadworthiness inspection requirements present white-space entry points. Target adaptive damping retrofit opportunities among mid-tier overlanding enthusiasts priced out of factory-integrated systems. Pursue direct-to-consumer platform configurators for winch and recovery equipment, bypassing consolidated Perth and Johannesburg distributor networks that now extract volume rebates comparable to OEM fleet terms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty garage chains and regional winch manufacturers that consolidated during the last downturn. Five-to-ten year viability hinges on electrification-readiness across product portfolios, particularly ruggedized electric axle conversions for remote-area utility deployment. Monitor EPA enforcement intensity against uncertified exhaust modifiers as an inflection signal for aftermarket supplier margin compression and consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Electric Axle Platform Development | Enables tier-two suppliers to compete across previously segmented drivetrain and accessory tiers. |
| REACH-Compliant Compound Reformulation | Secures EU market access ahead of 2025 enforcement windows for tire manufacturers. |
| Direct-to-Consumer Configurator Launch | Bypasses consolidated Australian and South African distributor networks extracting OEM-comparable rebates. |
| In-House Testing Laboratory Investment | Satisfies NHTSA photometry and bumper impact requirements that gate US distribution access. |
| Adaptive Damping Technology Integration | Captures fastest-growing suspension kit demand among mid-tier overlanding enthusiasts. |
Research Methodology
The analysis maps tires, suspension kits, winches, bumpers, lighting systems, and exhaust configurations, each validated through procurement directors at mining fleet operators, aftermarket retail category managers, specialty garage owners, and tier-one supplier engineering leads. Primary interview findings triangulate against vehicle production databases, customs and trade flow records, EPA certification filings, NHTSA FMVSS compliance registries, and REACH substance restriction updates. Bottom-up SKU-level demand modeling reconciles with top-down OEM platform production forecasts across the analysis window.
Consistency checks against external benchmarks validate volume and value outputs across the projection horizon. The analytical framework segments by product type, application intensity, end-user procurement structure, and distribution channel, with propulsion architecture and regional regulatory cluster as cross-cutting dimensions. CAGRs derive from fitted growth curves adjusted for electrification displacement risk in mechanical four-wheel-drive components and regulatory tightening timelines for emissions-critical systems. Forecast inputs include mining fleet utilization rates, overlanding vehicle registration patterns, and OEM electrification platform rollout schedules.
Forecasts assume regulatory continuity in EPA Clean Air Act enforcement, NHTSA FMVSS application, and REACH substance restriction timelines; material policy shifts would require re-modeling. Commodity price volatility in natural rubber and rare earth elements, plus trade flow disruptions affecting Southeast Asian compound manufacturing, constitute specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.