
 Canada Automotive Carbon Fiber Composites Market | 2026-2036
Canada Automotive Carbon Fiber Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Automotive Carbon Fiber Composites Market Outlook
Modular sub-assembly bundling is shifting how Tier-1 suppliers procure carbon fiber components for automotive platforms. Mitsubishi Chemical Carbon Fiber and Composites Inc anchors its position through captive precursor supply and integrated compounding operations across North American facilities. Solvay differentiates via high-performance resin systems tailored to automotive cure cycles. Hexcel Corporation competes on aerospace-derived quality systems adapted for high-volume automotive qualification.
Canada automotive carbon fiber composites are fiber-reinforced polymer materials consisting of carbon filaments embedded in thermoset or thermoplastic matrices, typically achieving tensile strengths exceeding 1,500 MPa with densities below 1.6 g/cm³, engineered primarily to reduce vehicle mass while maintaining crashworthiness and structural rigidity. Prepreg formats dominate premium structural applications where precise resin control justifies higher material costs, while sheet molding compound serves cost-sensitive body panel programs targeting cycle time reduction. Continuous fiber architectures lead chassis applications demanding directional strength optimization, with braid configurations gaining traction in complex geometric hollow sections.
Transport Canada enforces motor vehicle safety standards under the Motor Vehicle Safety Act that increasingly incorporate mass-reduction incentives, while Environment and Climate Change Canada administers greenhouse gas emission regulations under the Canadian Environmental Protection Act that penalize fleet-average weight. Health Canada and the Canadian Environmental Protection Act jointly govern volatile organic compound emissions from composite manufacturing processes, shaping resin chemistry selection and curing infrastructure investment. Stakeholders must monitor evolving federal clean fuel regulations and provincial zero-emission vehicle mandates to anticipate which vehicle platforms will command carbon fiber content premiums.
Market Dynamics
Transport Canada's fleet-average weight penalties under the Canadian Environmental Protection Act are forcing structural material substitution decisions at the platform-engineering stage, compressing qualification timelines for carbon fiber-intensive architectures.
Growth Catalysts
- Emissions Regulation Stringency:Environment and Climate Change Canada's greenhouse gas emission regulations impose escalating penalties on heavier fleets, compelling OEMs to adopt mass-reduction strategies anchored by carbon fiber structural members.
- Electric Vehicle Platform Proliferation:Battery-electric vehicle architectures require counterbalancing battery mass with lightweight body structures, concentrating carbon fiber demand in Ontario's EV assembly corridor.
- Prepreg Automation Advances:Automated fiber placement and resin transfer molding technologies are reducing cycle times for complex structural components, expanding addressable volume beyond hand-layup limitations.
Market Restraints
- Acrylonitrile Feedstock Volatility:Carbon fiber precursor costs track petrochemical indices with limited hedging instruments available to Tier-1 converters, compressing margin buffers during input price spikes.
- Precursor Supply Concentration:Polyacrylonitrile precursor manufacturing concentrates among a handful of multinational chemical producers, exposing Canadian converters to allocation risk during supply disruptions.
- Thermoplastic Substitution Threat:Long-fiber thermoplastic composites offer comparable weight savings at lower processing temperatures and faster cycle times, capturing cost-sensitive body panel applications.
Strategic Opportunities
- Quebec Hydropower-Adjacent Manufacturing:Carbon fiber production's energy intensity aligns with Quebec's low-carbon electricity grid, creating scope for green-premium positioning in export markets.
- Recycled Fiber Integration:Pyrolysis-based carbon fiber reclamation technologies are maturing, enabling circular material flows that satisfy OEM sustainability scorecard requirements.
- Provincial Zero-Emission Vehicle Mandates:British Columbia and Quebec's ZEV sales targets are accelerating EV platform launches that specify carbon fiber-intensive architectures from program inception.
Industry Challenges
- Composite Repair Technician Scarcity:Collision repair networks lack certified technicians trained in carbon fiber damage assessment and bonded repair protocols, limiting aftermarket service capacity expansion.
- Automotive Qualification Timelines:OEM material approval cycles spanning 24-36 months delay revenue realization for new composite formulations, straining development-stage cash flows.
- Multi-Material Joining Complexity:Dissimilar material interfaces between carbon fiber and aluminum or steel require specialized adhesive and mechanical fastening expertise that remains concentrated among aerospace-derived suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Automotive Carbon Fiber Composites Market |
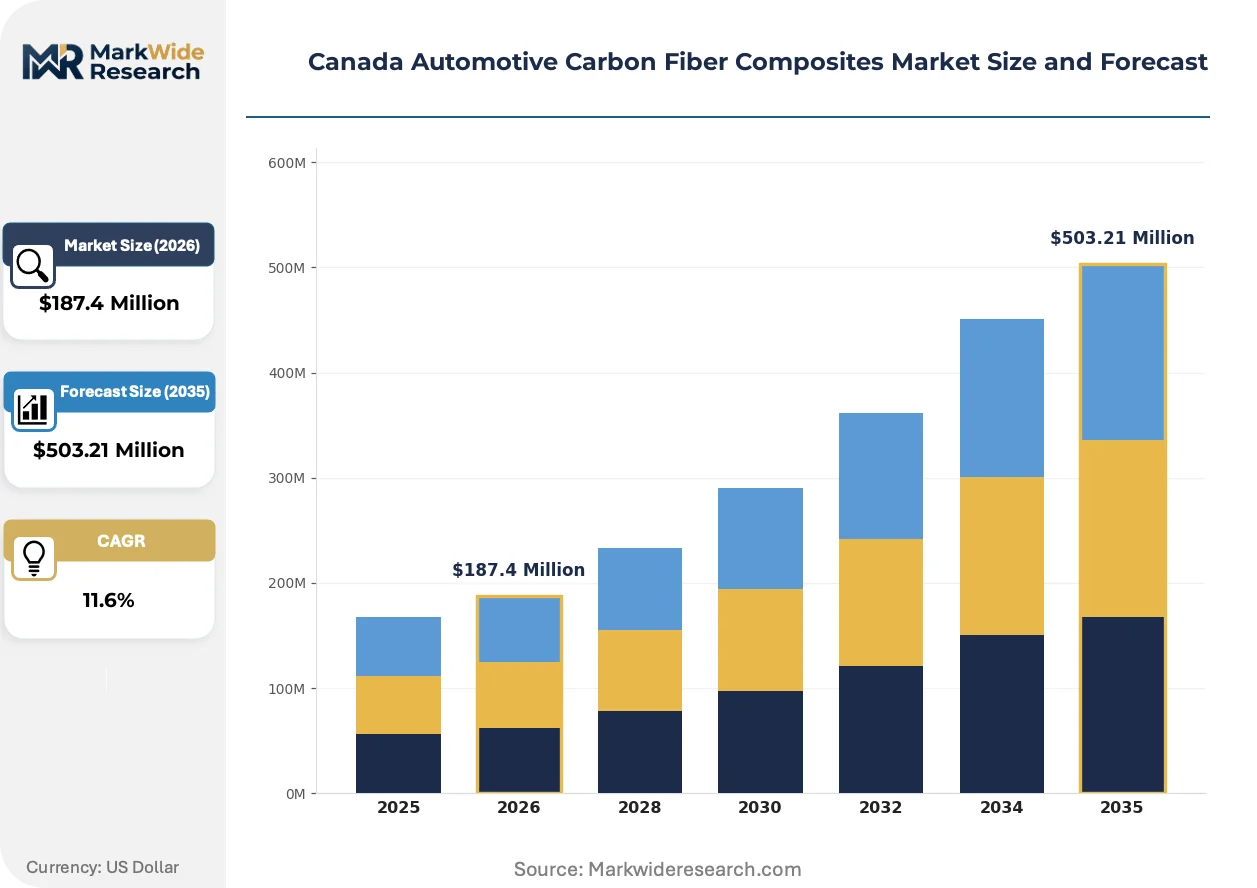
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet Molding Compound, Continuous Fiber, Prepreg, Braid End User: Passenger Vehicles, Commercial Vehicles, OEMs, Tier-1 Suppliers Application: Structural Parts, Interior Components, Body Panels, Chassis Manufacturing Stage: Mass Production, Custom Fabrication, Prototyping, Assembly |
| Companies Covered | Mitsubishi Chemical Carbon Fiber and Composites Inc, Solvay, Toray Industries, Sigmatex, Toho Tenex, Hexcel Corporation, Teijin Limited, BASF, SGL Carbon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Automotive Carbon Fiber Composites Market Strategic Shifts
Automotive carbon fiber processing is pivoting from aerospace-derived batch methods toward continuous-flow manufacturing systems capable of supporting million-unit annual vehicle programs without quality degradation.
Thermoplastic resin systems are integrating into structural automotive applications previously reserved for thermoset epoxies. BMW's i-series platforms and emerging Canadian EV architectures specify thermoplastic composites for crash-critical components. The shift is integrating in-situ consolidation processes that eliminate autoclave bottlenecks, compressing capital requirements for high-volume qualification.
Transport Canada's evolving Motor Vehicle Safety Act amendments incorporate mass-reduction incentive structures that recognize advanced material crash performance equivalency. The regulatory framework permits lighter vehicle designs without compromising occupant protection ratings. Premium EV platforms in Ontario's manufacturing corridor are responding with expanded carbon fiber passenger cell specifications.
Buyer concentration among Detroit-Windsor OEM engineering centers is compressing supplier qualification pathways. Tier-1 converters face consolidated technical approval gates rather than distributed regional validation. The consolidation is most visible in Ontario's supplier park networks, where single-source platform engineering decisions determine multi-year material allocation commitments across entire vehicle lines.
Canada Automotive Carbon Fiber Composites Market Segmentation
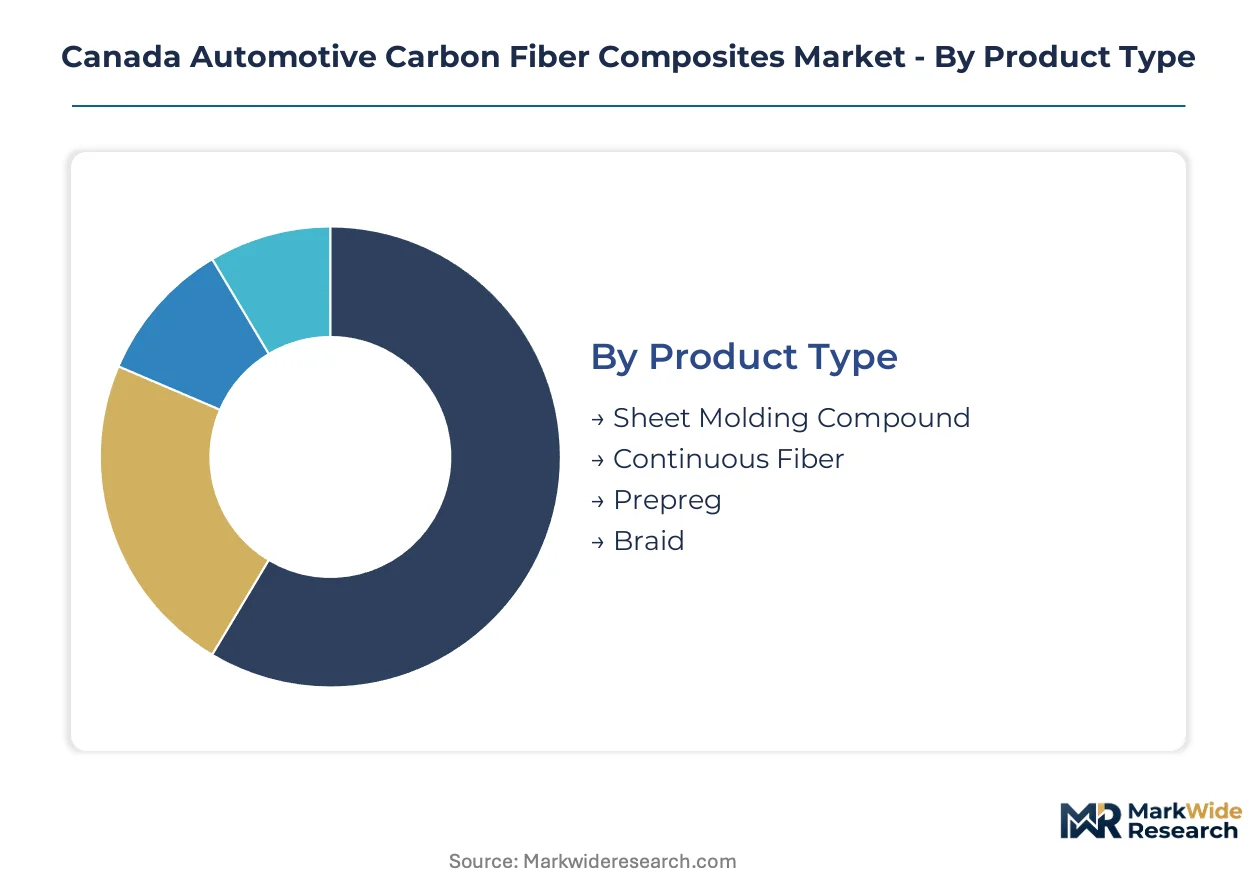
Carbon fiber composite procurement in Canada varies sharply by processing format and vehicle integration point. Buyers prioritize cycle time compatibility with assembly line speeds and crash performance certification under Transport Canada protocols.
Product Type:
OEM engineering teams select formats based on part complexity, production volume, and resin control requirements.
- Prepreg:Pre-impregnated fiber sheets with precisely controlled resin content deliver consistent mechanical properties for structural safety-critical components. Ontario EV platforms specify prepreg for passenger cell reinforcements where Transport Canada crashworthiness standards demand predictable energy absorption.
- Continuous Fiber:Unidirectional or multi-axial fiber architectures optimize directional strength-to-weight ratios for load-bearing members. Chassis applications in Windsor-Toronto corridor assembly plants favor continuous fiber for longitudinal rails and cross-members subject to bending and torsional loads.
- Sheet Molding Compound:Discontinuous fiber in thermoset matrices enables compression molding cycle times under three minutes for body panel programs.
- Braid:Interlaced fiber sleeving conforms to complex hollow geometries without seam joints, gaining traction in suspension links and steering columns.
Volume sits with Sheet Molding Compound; growth tilts toward Prepreg.
End User:
Procurement authority and technical specification control determine supplier relationship structures across the value chain.
- OEMs:Original equipment manufacturers hold final material approval authority and platform-level architecture decisions. Ford, GM, and Stellantis engineering centers in Detroit-Windsor corridor dictate carbon fiber specifications for entire vehicle programs.
- Tier-1 Suppliers:Magna, Linamar, and Martinrea procure composite materials under directed-buy arrangements, converting raw formats into finished modules for OEM assembly lines.
- Passenger Vehicles:Premium battery-electric platforms in Ontario integrate carbon fiber body structures to offset battery mass penalties.
- Commercial Vehicles:Transit bus and vocational truck manufacturers specify composite panels for corrosion resistance and fuel economy gains.
Procurement volume concentrates with Tier-1 Suppliers; specification control rests with OEMs.
Application:
Functional performance requirements and crash safety classification determine material grade selection.
- Structural Parts:B-pillars, roof bows, and frame rails require high-modulus carbon fiber with tensile strengths exceeding 3,000 MPa to maintain occupant cell integrity.
- Chassis:Suspension cradles and subframes demand fatigue-resistant fiber architectures capable of withstanding cyclic loading over 15-year vehicle lifespans.
- Body Panels:Class-A surface quality requirements drive smooth-molded composite selection for hoods, roofs, and decklids.
- Interior Components:Decorative trim and seating structures utilize lower-modulus grades where cosmetic finish outweighs structural loading.
Revenue concentrates in Structural Parts; expansion accelerates in Chassis.
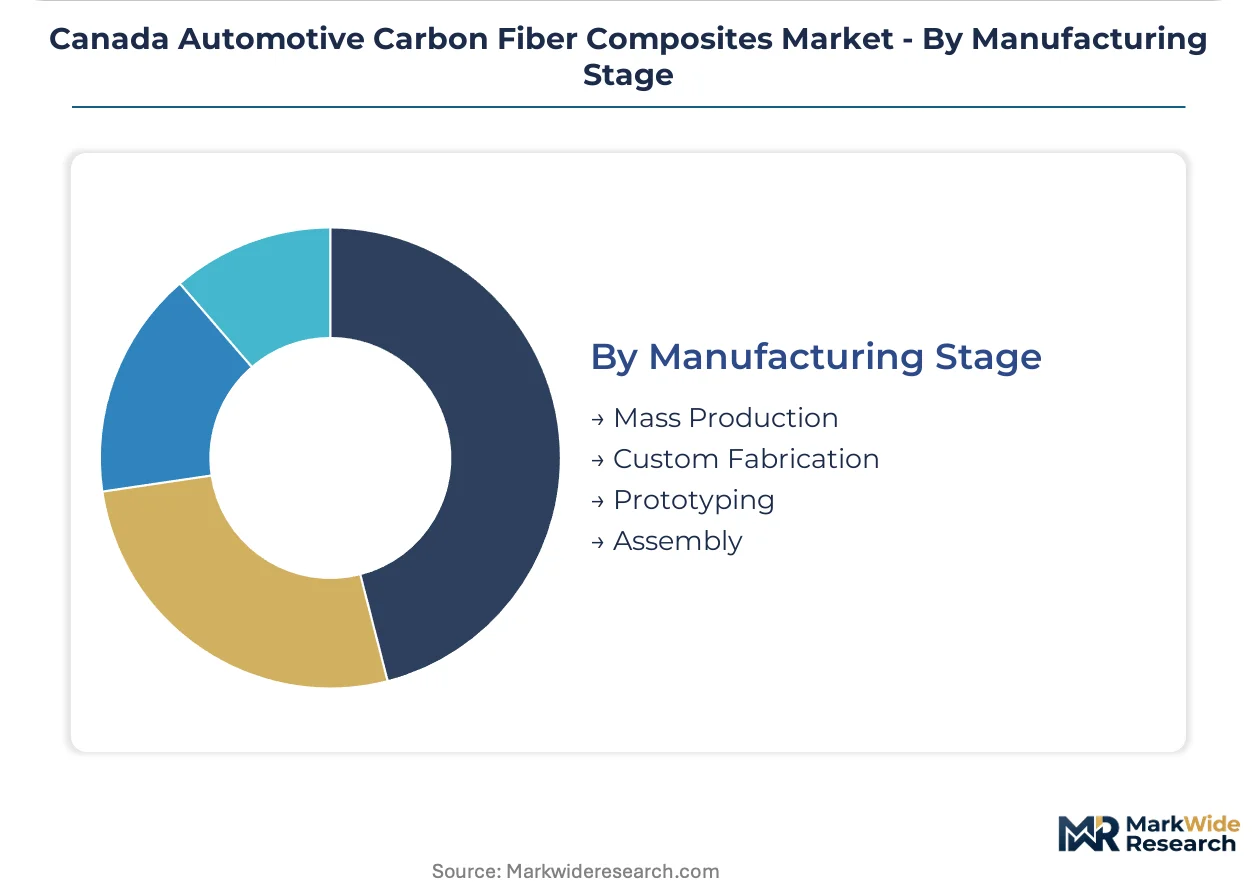
Manufacturing Stage:
Capital deployment and process validation timelines segment converter capabilities.
- Mass Production:Automated fiber placement and resin transfer molding lines serving 100,000-plus annual vehicle programs require 24-36 month qualification cycles.
- Assembly:Bonding and fastening operations integrate composite modules with mixed-material vehicle architectures.
- Custom Fabrication:Low-volume specialty vehicles and motorsport applications tolerate hand-layup methods with longer cycle times.
- Prototyping:Tool-less manufacturing methods validate design concepts before hard tooling investment.
Investment flows toward Mass Production; margin capture favors Custom Fabrication.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian carbon fiber composite consumption exceeds domestic precursor manufacturing capacity, creating import dependence on Japanese and European suppliers while Ontario's automotive corridor drives demand concentration.
Ontario
Windsor-Toronto assembly plants specify carbon fiber for battery-electric vehicle architectures to offset battery mass penalties. Transport Canada's Motor Vehicle Safety Act amendments recognize advanced material crash performance equivalency, enabling lighter vehicle designs. The Detroit-Windsor supplier corridor anchors North American EV platform engineering decisions.
Quebec
Low-carbon hydropower availability attracts energy-intensive carbon fiber conversion investments seeking green-premium export positioning. The Canadian Environmental Protection Act governs manufacturing emissions, shaping resin chemistry selection for facilities near Montreal and Quebec City. Pyrolysis-based fiber reclamation technologies mature in provincial research clusters.
British Columbia
Provincial zero-emission vehicle mandates accelerate EV platform launches specifying lightweight composite structures from program inception. Environment and Climate Change Canada administers greenhouse gas regulations penalizing fleet-average weight. Vancouver-area clean technology ventures pilot recycled fiber integration for circular material flows.
Alberta
Petrochemical feedstock proximity supports acrylonitrile precursor supply chain development for eventual backward integration. Health Canada and the Canadian Environmental Protection Act jointly govern volatile organic compound emissions from composite manufacturing. Calgary-based materials research centers explore thermoplastic resin systems for automotive cure cycles.
Canada Automotive Carbon Fiber Composites Market Competitive Environment
The competitive structure tilts toward multinational chemical conglomerates with captive precursor supply and integrated compounding operations. Tier-1 automotive suppliers consolidate procurement authority through directed-buy arrangements with converters. Three archetypes dominate: aerospace-derived quality system adapters, petrochemical-integrated precursor producers, and specialized automotive resin formulators. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification timelines compress.
Among Japanese-origin suppliers, Mitsubishi Chemical Carbon Fiber and Composites Inc exemplifies the petrochemical-integrated archetype through captive precursor control, while Toray Industries occupies a parallel position with aerospace-derived quality systems adapted for automotive volume. Solvay represents the European resin formulation specialist tier, differentiating through high-performance thermoset and thermoplastic systems tailored to automotive cure cycles.
| Leading Market Players |
|---|
| Mitsubishi Chemical Carbon Fiber and Composites Inc |
| Solvay |
| Toray Industries |
| Sigmatex |
| Toho Tenex |
| Hexcel Corporation |
| Teijin Limited |
| BASF |
| SGL Carbon |
| Others |
Value Chain & Pricing Dynamics
Automated fiber placement and resin transfer molding adoption across Ontario's EV assembly corridor simultaneously compresses per-part labor costs and concentrates procurement authority among Detroit-Windsor engineering centers. This technological pivot reshapes supplier pricing power by rewarding capital-intensive converters with qualification-track records while marginalizing hand-layup operations.
Pricing Analysis
Cost-down pressure on prepreg formats accelerates as Magna and Linamar consolidate directed-buy arrangements under multi-year platform contracts. Three-tier pricing structure across aerospace-qualified, automotive-grade, and industrial-specification levels differentiates suppliers. Tier-1 procurement teams exhibit highest price sensitivity on body panel programs where sheet molding compound competes with long-fiber thermoplastics, while OEM engineering centers prioritize crash-performance certification over unit cost for passenger cell reinforcements.
Supply Chain Analysis
Composite technician certification gaps in Windsor-Toronto manufacturing zones constrain converter expansion despite available precursor supply. Polyacrylonitrile fiber draws from Japanese and European precursor producers, with acrylonitrile feedstock anchored in Alberta's petrochemical corridor. Single-source vulnerability concentrates in Toray Industries and Mitsubishi Chemical's captive precursor networks. Distribution runs through Tier-1 supplier park logistics hubs co-located with Stellantis and GM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive precursor supply and in-house compounding operations represent the decisive vertical-integration lever as qualification timelines compress and raw material allocation risk intensifies.
For Market Incumbents: Deploy pyrolysis-based fiber reclamation capabilities to satisfy OEM sustainability scorecards and preempt recycled-content mandates. Consolidate technical approval relationships with Detroit-Windsor platform engineering centers before competitor qualification cycles complete. Long-fiber thermoplastic substitution threatens cost-sensitive body panel revenue streams. For New Entrants and Emerging Players: Small-series EV manufacturers and motorsport converters represent underserved buyers tolerant of longer lead times and premium pricing. Quebec's hydropower-adjacent industrial zones offer green-premium positioning for export-oriented production. Pursue joint development agreements with British Columbia clean technology ventures to bypass incumbent qualification barriers. For Investors and Strategic Acquirers: Re-rating potential sits with specialized automotive resin formulators given thermoplastic cure-cycle breakthroughs and OEM platform standardization. Five-to-ten-year viability hinges on securing multi-program qualification tracks before incumbent capacity expansion saturates addressable volume. Monitor Transport Canada Motor Vehicle Safety Act amendment timelines as inflection signals for crash-performance equivalency recognition.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Mitsubishi Chemical's captive acrylonitrile control insulates margin buffers from petrochemical volatility. |
| Quebec Hydropower Manufacturing Footprint | Low-carbon electricity access enables green-premium carbon fiber positioning in European export markets. |
| Recycled Fiber Integration Partnership | Pyrolysis reclamation technologies satisfy Stellantis and GM sustainability procurement scorecard requirements. |
| Thermoplastic Resin System Qualification | Solvay's automotive cure-cycle formulations bypass autoclave bottlenecks for high-volume EV platforms. |
| Tier-1 Supplier Park Co-location | Magna-directed buy arrangements compress logistics costs and accelerate just-in-sequence delivery compliance. |
Study Parameters
Transport Canada regulatory filings, Environment and Climate Change Canada greenhouse gas enforcement data, and vehicle production databases formed the secondary backbone. Primary interviews with OEM platform engineers, Tier-1 procurement directors, composite manufacturing plant managers, and aftermarket repair network operators validated demand assumptions. Bottom-up and top-down triangulation reconciled converter capacity announcements with OEM platform carbon fiber content specifications.
Bottom-up modeling aggregated individual program content-per-vehicle estimates across propulsion architecture, vehicle class, and structural application dimensions. Top-down validation cross-checked aggregate demand against precursor import volumes and resin system sales disclosures. CAGRs derived from weighted platform launch schedules and regulatory compliance deadline impacts. Forecast inputs incorporated Transport Canada fleet-average weight penalty phase-ins and provincial zero-emission vehicle mandate trajectories.
Revisions become necessary when acrylonitrile feedstock price volatility exceeds historical bands, thermoplastic substitution accelerates beyond chassis applications, or repair technician certification programs fail to scale. Forecasts reflect assumptions about OEM platform standardization continuity and Quebec hydropower cost competitiveness. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Passenger Car Sensors Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
HCV Axles Market
Vehicle Components
4-Wheeled Containers Market
Vehicle Components
Towing Equipment Market
Vehicle Components
Global Bearings Market
Vehicle Components
Global Car Accessories Market
Vehicle Components
Vehicle Pillar Market
Vehicle Components
Saudi Arabia Car Rental and Leasing Market
Vehicle Components
Car Diffuser Market
Vehicle Components
Towing Ropes Market
Vehicle Components
Saudi Arabia Refrigerated Trailer Market
Vehicle Components
Portable Truck Access System Market
Vehicle Components
Self Loading Trailer Market
Vehicle Components
Trailer Surge Brake Market
Vehicle Components
Tipper Body Equipment Market