
 Traditional TV and Home Video Market | 2026-2036
Traditional TV and Home Video Market Size, Share, and Industry Trends Forecast 2026-2036
Traditional TV and Home Video Market Intelligence
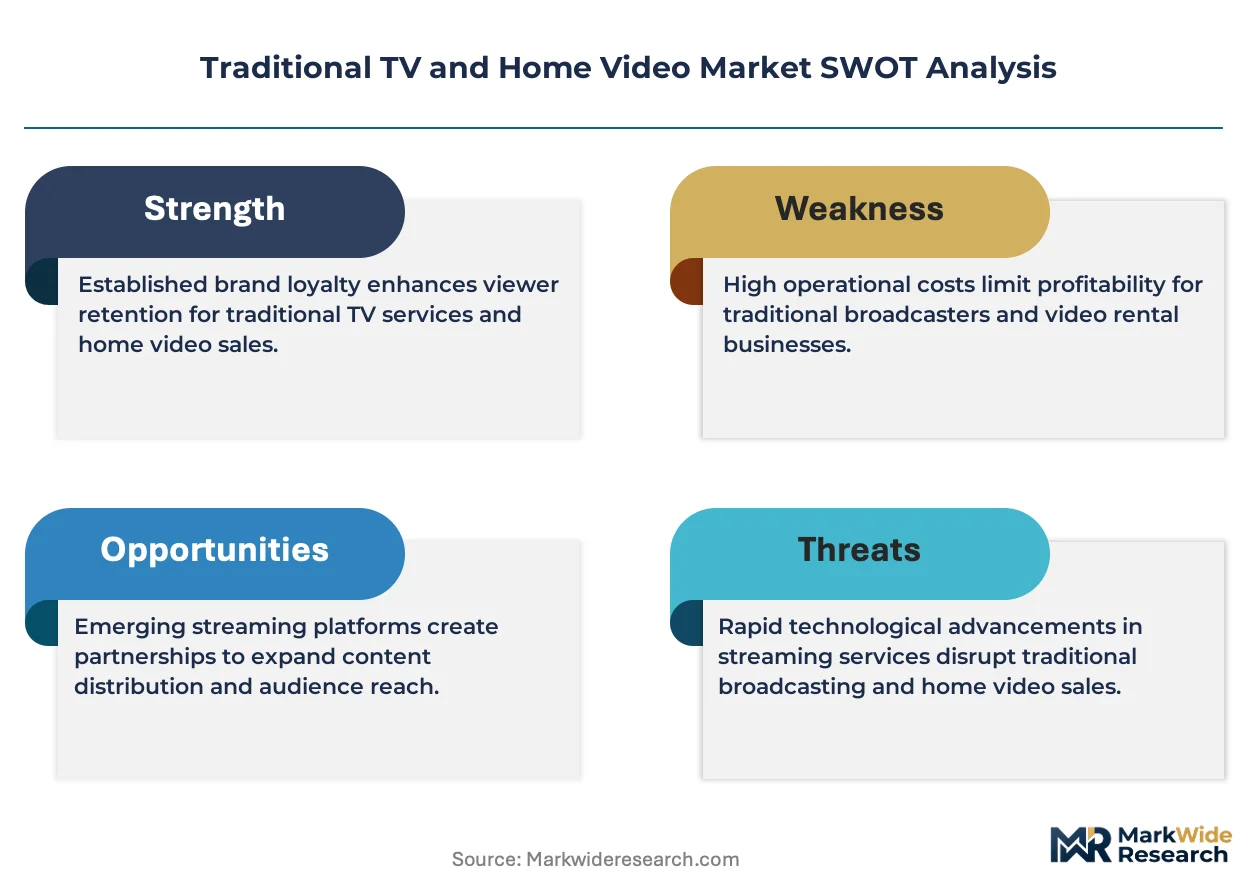
A divergence in fiber optic infrastructure investment versus satellite delivery is repositioning the market into distinct premium and value-oriented tiers. Comcast leverages its extensive cable and fiber network to offer high-value bundles with integrated streaming options in the United States. In contrast, Dish Network specializes in satellite services, targeting rural and underserved areas with different service packages. In Canada, Rogers Communications competes by integrating television with its broad telecommunications and media assets.
Traditional television and home video encompasses the one-to-many distribution of scheduled, linear programming through terrestrial broadcast, coaxial cable, or satellite signals. These systems use transmission standards like ATSC 3.0 for broadcast or QAM for cable to deliver content to fixed receivers. The Cable and Satellite product types represent mature segments, with revenue highly dependent on subscription-based distribution channels. Within content, live sports and major news events (categorized under Drama and Documentaries) sustain premium value, particularly for the Families consumer segment.
Market access and content obligations are governed by national authorities such as the FCC in the United States and the CRTC in Canada. These bodies set rules for broadcasting licenses, must-carry provisions, and local content requirements, directly shaping service provider offerings. Navigating the high fixed costs of legacy infrastructure while securing exclusive rights to premium content is the central strategic challenge for incumbent providers.
Market Dynamics
The central structural force shaping the market is the tension between the high fixed costs of maintaining legacy broadcast infrastructure and the escalating expense of securing exclusive rights for premium content, which is necessary to retain subscribers.
Growth Catalysts
- Local Content Quotas:Mandates from regulators like Canada's CRTC and the UK's Ofcom require a certain percentage of programming to be locally produced, creating a steady, government-supported demand for content creation and distribution within national markets.
- Seniors Consumer Segment:Persistent viewing habits among the senior demographic provide a stable and predictable revenue base for linear broadcast and satellite providers, particularly for news and scheduled entertainment programming.
- Broadcast Standard Upgrades:The adoption of transmission standards such as ATSC 3.0 allows terrestrial broadcasters to deliver higher quality video, interactive features, and mobile reception, enhancing the value proposition of free over-the-air television.
Market Restraints
- Legacy Infrastructure Costs:The substantial, ongoing capital and operational expenditures required to maintain extensive coaxial cable networks, satellite fleets, and terrestrial transmission towers create a high barrier to entry and limit providers' financial flexibility.
- Direct Substitution Threat:The proliferation of on-demand streaming video services offers a direct and often lower-cost substitute for traditional subscription television, leading to subscriber attrition known as cord-cutting.
- Must-Carry Regulatory Friction:In the United States, FCC must-carry rules obligate cable and satellite operators to transmit local broadcast stations, consuming valuable bandwidth that could otherwise be used for more profitable channels or services.
Strategic Opportunities
- Underserved Rural Markets:Satellite television providers can target geographic areas where terrestrial cable and fiber optic infrastructure are not economically viable, offering a critical service for entertainment and information access.
- Hybrid Service Integration:Combining linear television with integrated access to third-party streaming applications within a unified guide and billing system creates a simplified, high-value proposition for consumers overwhelmed by content fragmentation.
- Live Event Expansion:Broadening the definition of premium live content beyond sports to include exclusive, large-scale cultural events, political debates, and breaking news can create new appointment-viewing occasions that drive viewership.
Industry Challenges
- Content Rights Escalation:The intense bidding wars for exclusive broadcasting rights to premier sports leagues and other major live events create significant financial pressure and risk for providers, making profitability on these deals difficult.
- Legacy System Integration:Operators face considerable technical complexity in integrating modern, IP-based video delivery platforms with decades-old QAM-based cable or satellite distribution systems, often leading to operational inefficiencies.
- Network Upgrade Cycles:The high capital expenditure required to upgrade cable networks to fiber or to replace aging satellite assets presents a constant challenge, forcing difficult decisions about where and when to invest.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Traditional TV and Home Video Market |
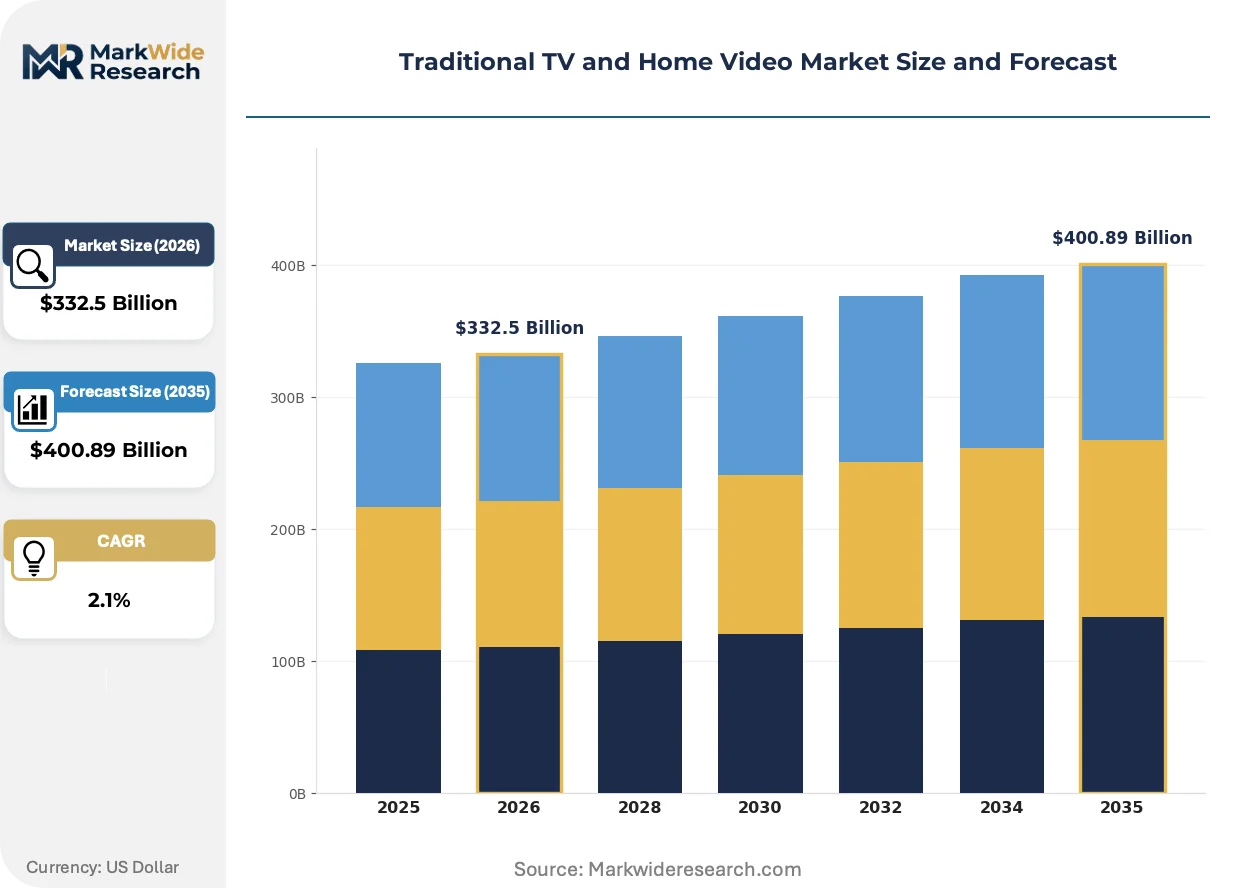
| Market Size in 2026 | $332.5 Billion |
| Market Size in 2035 | $400.89 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broadcast, Cable, Satellite, Streaming Content Type: Drama, Comedy, Reality Shows, Documentaries Distribution Channel: Direct Sales, Retail, Online, Subscription Consumer Segment: Families, Young Adults, Seniors, Students |
| Companies Covered | Comcast (Xfinity), AT&T (DirecTV), Charter Communications (Spectrum), Dish Network, Verizon Communications (Fios), Cox Communications, BT Group (BT TV), Rogers Communications, Bell Canada (Bell TV), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Traditional TV and Home Video Market Strategic Shifts & Innovations
The market is undergoing a strategic re-tiering, driven by infrastructure capabilities and content bundling. This bifurcation separates premium, fiber-enabled integrated bundles from value-oriented satellite or basic cable services, redefining competitive positions for incumbent providers.
Advanced Broadcast Capabilities
Hybrid broadcast broadband technologies, often abbreviated as HbbTV, combine over-the-air signal delivery with internet connectivity. Broadcasters and television manufacturers are adopting these standards to enrich the linear viewing experience with interactive features and access to on-demand content libraries. This technology is unifying the separate realms of scheduled broadcasting and internet streaming into a single, cohesive interface on the television.
Regulatory Focus on Prominence
Ofcom's updated Media Act rules in the United Kingdom mandate that on-demand apps from public service broadcasters must be given prominence on connected TV interfaces. This policy ensures that services like BBC iPlayer and ITVX remain easily discoverable for viewers, directly supporting national media against global streaming platforms. The traditional broadcast sector is most affected, as it gains a significant regulatory advantage in the digital shelf-space competition.
Shift Toward Service Unbundling
A notable behavioral shift is the consumer movement away from large, one-size-fits-all programming packages toward smaller, more tailored "skinny bundles." This trend directly challenges the traditional distribution model, where less popular channels are subsidized by their inclusion in broad tiers. This pattern is most pronounced in the North American market, where it pressures cable and satellite operators to offer more flexible and customizable service options.
Traditional TV and Home Video Market Segmentation
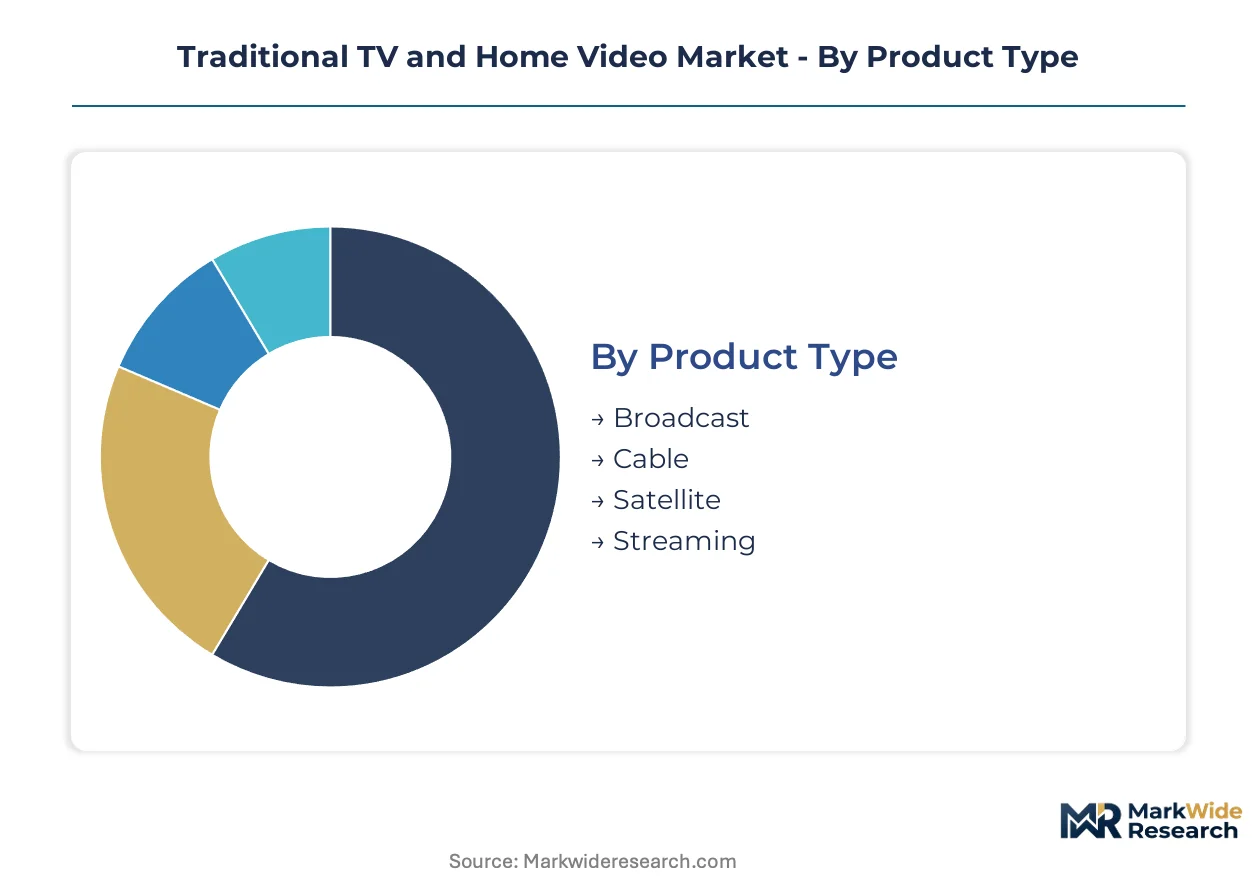
Understanding the Traditional TV and Home Video Market through segmentation reveals how consumer preferences and technological advancements shape service delivery. This granular analysis helps providers tailor offerings and content strategies to specific user groups and distribution models. It highlights areas of stability and emerging opportunities within a dynamic media landscape.
Product Type:
Consumer choice regarding how content is delivered profoundly influences the market's product type segmentation.
- Broadcast:Terrestrial broadcast relies on over-the-air signals using standards like ATSC 3.0, delivering free content to antennas. Demand remains stable among seniors in regions like Japan, valuing reliable, scheduled news and local programming.
- Cable:Coaxial cable systems transmit scheduled programming and on-demand services, often bundled with internet and phone. This product type sees significant revenue from subscription models in urban and suburban areas, particularly in the United States, where Comcast leverages extensive networks.
- Satellite:Satellite television delivers programming via dish antennas, serving geographic areas where terrestrial infrastructure is less developed.
- Streaming:While often considered separate, integrated streaming options are now bundled with traditional TV services, offering on-demand libraries.
Cable leads on scale; Streaming leads on momentum.
Content Type:
The intrinsic value proposition of content types dictates their appeal across various consumer demographics and market tiers.
- Drama:Scripted dramatic series and films attract broad audiences, driving subscription retention and advertising revenue through serialized storytelling. This content type sustains premium value for families globally, especially when exclusive rights are secured.
- Documentaries:Non-fiction programming explores real-world subjects, appealing to intellectually curious viewers seeking educational or insightful narratives. This segment sees consistent demand from seniors and students, particularly for historical or nature-focused series.
- Comedy:Humorous programming, including sitcoms and stand-up specials, offers entertainment and escapism for diverse audiences.
- Reality Shows:Unscripted programming featuring real people in unscripted situations garners significant viewership due to its accessible and often dramatic nature.
Live sports content, though not explicitly listed, drives the steepest expansion trajectory within premium offerings.
Distribution Channel:
The market's distribution channels highlight the varied pathways through which traditional TV and home video content reaches end-users.
- Subscription:Revenue from recurring payments for access to content bundles or specific channels forms the bedrock of the traditional TV model. This channel dominates in established markets like Canada and the United States, supporting extensive infrastructure and content acquisition.
- Direct Sales:Providers directly market and sell their services to consumers, often involving in-person sales or direct-to-consumer campaigns. This channel is crucial for acquiring new subscribers in competitive urban markets, where personalized pitches increase conversion rates.
- Online:Digital platforms facilitate content access, often complementing traditional services with on-demand libraries or streaming versions of linear channels.
- Retail:Physical stores or authorized dealers offer traditional TV and home video packages, particularly in areas where direct online sign-ups are less prevalent.
Subscription models contribute the highest revenue to the market.
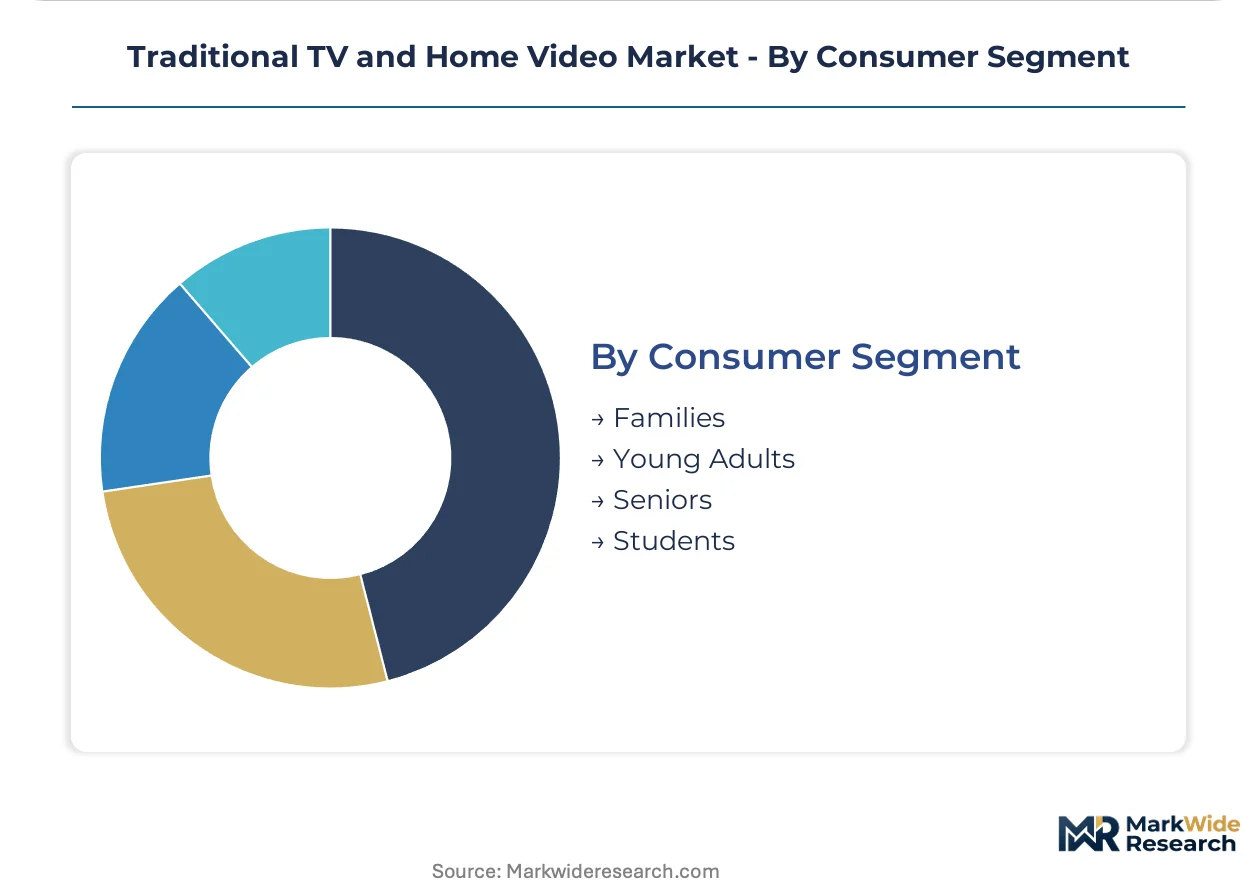
Consumer Segment:
Distinct consumer behaviors and media consumption habits define the segmentation across various demographic groups.
- Seniors:This demographic exhibits persistent viewing habits for linear broadcast content, valuing scheduled programming and news. Their stable engagement provides a predictable revenue base for providers, particularly in markets like Japan.
- Families:Households with children seek diverse content suitable for all ages, often driving demand for bundled services that include both linear and on-demand options. This segment values live sports and family-friendly entertainment, contributing significantly to premium content subscriptions.
- Young Adults:This segment increasingly favors on-demand and streaming content, challenging traditional linear viewing models.
- Students:Students often prioritize flexible, cost-effective content access, frequently relying on digital platforms or shared subscriptions.
Seniors form the largest stable consumer base, while Young Adults represent a challenging demographic for traditional providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The media production workforce in the United States anchors significant innovation for traditional television and home video markets. This talent concentration drives content creation and technological advancements across diverse platforms. This ensures a robust supply of programming for both domestic and international audiences.
United States
Strong demand for subscription-based bundles and live sports events characterizes the United States market. The FCC governs broadcasting licenses and must-carry provisions, shaping service provider offerings. New York City's extensive media hub drives content development and distribution for major networks.
Canada
Local content quotas and integrated telecommunications bundles drive demand in Canada. The CRTC mandates local content requirements, influencing programming strategies for providers like Rogers Communications. Toronto's vibrant media industry supports significant local content production and telecommunications integration.
Japan
Persistent viewing habits among the senior demographic sustain the traditional TV market in Japan. National authorities ensure market stability and regulate content distribution for terrestrial broadcasters. Tokyo's advanced broadcast centers maintain traditional viewing habits and infrastructure for a significant population.
United Kingdom
Public service broadcasting and the adoption of hybrid broadcast broadband technologies create demand in the United Kingdom. Ofcom's updated Media Act rules mandate prominence for public service broadcaster apps on connected TV interfaces. London's dynamic media sector drives innovation in HbbTV and integrated digital services for consumers.
Germany
Mature cable and satellite markets, alongside demand for high-quality drama, characterize Germany's landscape. The Federal Network Agency oversees broadcasting infrastructure and spectrum allocation. Munich's robust media production houses contribute to premium content and broadcast technology advancements.
Traditional TV and Home Video Market Key Industry Players
Top-tier vendors anchor the integrated telecommunications and media bundles, while satellite specialists focus on value-oriented services. The market exhibits a tiered structure, with established cable operators, satellite providers, and emerging hybrid service integrators forming distinct archetypes. Strategic moves involve securing exclusive premium content rights and continuous investment in hybrid service integration to retain subscribers.
Among integrated telecommunications providers, Comcast and Rogers Communications exemplify the strategy of leveraging extensive network infrastructure. These companies occupy positions offering high-value bundles that combine traditional television with internet and streaming options, catering to urban and suburban markets. Dish Network, conversely, represents the specialized satellite provider archetype, anchoring services for rural and underserved areas. This firm focuses on different service packages designed for regions where terrestrial infrastructure is less viable, providing critical access to entertainment and information. AT&T, with its DirecTV offering, also sits within the broader telecommunications landscape, navigating the transition between traditional satellite and bundled services.
| Leading Market Players |
|---|
| Comcast (Xfinity) |
| AT&T (DirecTV) |
| Charter Communications (Spectrum) |
| Dish Network |
| Verizon Communications (Fios) |
| Cox Communications |
| BT Group (BT TV) |
| Rogers Communications |
| Bell Canada (Bell TV) |
| Others |
Cost & Logistics Intelligence
Local content sustainability mandates, such as those from Canada's CRTC, gate qualified supply and premium-tier pricing access for local programming. This regulatory framework ensures continued investment in domestic content creation and distribution channels.
Pricing Analysis
The bundled-vs-unbundled service split drives price differentiation within the Traditional TV and Home Video Market. Subscription models remain the dominant pricing structure, generating significant revenue for providers. Content exclusivity, particularly for live sports, and network quality, exemplified by fiber-optic infrastructure, dictate premium pricing. Pricing softness stems from the direct substitution threat posed by streaming services, particularly impacting providers targeting Young Adults. Seniors demonstrate the least price sensitivity, valuing stable, scheduled programming.
Supply Chain Analysis
Workforce availability in key media production geographies, including the United States, anchors the content supply chain for traditional television. Geographic supply concentration for content production primarily resides in the US, Canada, and the UK. Raw material dependencies include exclusive premium content rights and the extensive fiber optic and satellite infrastructure. Content rights escalation presents a structural risk for providers. Distribution runs through subscription-based models, which form the bedrock of the traditional TV ecosystem.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a margin-expansion story, justified by the strategic shift towards hybrid service integration to capture higher-value consumer segments.
For Market Incumbents: Hedge against the direct substitution threat from streaming services by actively integrating third-party streaming applications into unified guides. Secure exclusive rights for premium live events, expanding beyond sports to include cultural and news programming. Leverage extensive network infrastructure through continuous fiber upgrades to deliver superior service quality and retain high-value subscribers.
For New Entrants and Emerging Players: A price-point gap between premium fiber-optic bundles and value-oriented satellite services offers entry opportunities. Target underserved rural markets where terrestrial infrastructure is not economically viable, offering essential entertainment and information access. A compelling go-to-market angle involves flexible "skinny bundles" tailored to the price-sensitive Young Adults segment, providing a clear alternative to traditional large packages.
For Investors and Strategic Acquirers: Roll-up economics work for regional cable operators because of fragmented local infrastructure and the high fixed costs of legacy systems. Long-term viability rests on the stable revenue base provided by the Seniors consumer segment and the essential service provided in rural areas. The signal to watch is the successful integration of hybrid services and the sustained growth of premium live event viewership.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Service Integration | Unifies linear and streaming content, simplifying consumer experience and increasing perceived value. |
| Content Rights Acquisition | Secures exclusive access to premium live events, driving subscriber retention and attracting new viewers. |
| Network Infrastructure Upgrade | Enhances broadcast quality and interactive features through standards like ATSC 3.0, improving competitive positioning. |
| Rural Market Expansion | Extends service reach to underserved areas, leveraging satellite technology where fiber is not viable. |
| Regulatory Compliance Optimization | Ensures adherence to local content quotas and prominence rules, maintaining market access and goodwill. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. The analysis incorporated perspectives from broadcast executives, content acquisition managers, telecommunication engineers, and regulatory compliance officers. Secondary data sources included FCC filings, CRTC reports, Ofcom publications, and company annual reports, triangulating findings through bottom-up and top-down approaches.
Comparable historical periods anchored the forecast window, establishing a baseline for future projections. The analytical framework modeled key segmentation dimensions, including product type, content type, distribution channel, consumer segment, and regional dynamics. Compound annual growth rates were derived through regression analysis and expert consensus, incorporating industry-specific inputs such as subscriber churn rates and evolving content licensing costs across the analysis window.
Caveats apply where rapid technological disruption or unforeseen regulatory shifts could materially shift the outlook. Forecasts reflect assumptions regarding market evolution and competitive dynamics. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Cable Television Networks Market
Television
Pay TV Operator Market
Television
Holographic TV Market
Television
Television and Set Top Box Market
Television
Free-To-Air (FTA) Service Market
Television
HDTV Market
Television
Cloud Television (TV) Market
Television
Print Newspapers and Magazines Market
Television
Pay TV Services Market
Television
Curved Television Market
Television
Mobile TV Market
Television
Broadcasting and Cable TV Market
Television
Television Advertising Market
Television
Pay TV Market
Television
Global Broadcast Equipment Market
Television
Television Market