
 Holographic TV Market | 2026-2036
Holographic TV Market Size, Share, and Industry Trends Forecast 2026-2036
Holographic TV Market Analysis
Photopolymer materials are displacing conventional liquid crystal modulators, and this substitution is broadening the addressable cost curve for holographic panel production. Sony Corporation leverages captive semiconductor fabrication to control light engine supply chains. Samsung Electronics Co., Ltd. anchors its position through volumetric display R&D investments in Suwon. Light Field Lab Inc. specializes in modular tile architectures that scale beyond fixed-screen formats.
A holographic TV renders three-dimensional imagery through interference-pattern reconstruction without wearable eyewear, typically employing spatial light modulators with sub-micron pixel pitch to generate parallax-correct views across multiple angles. The technology serves immersive home entertainment, surgical planning, and military simulation where depth perception carries operational value. Light field display technology captures premium positioning among the technology segments due to its accommodation-friendly viewing experience. Medical facilities represent the fastest-growing end user category as radiology departments adopt holographic visualization for tumor mapping and preoperative rehearsal.
FCC electromagnetic emissions standards govern holographic TV broadcast equipment in the United States, while CE marking under the EU's Radio Equipment Directive shapes product compliance for European distribution. China's MIIT enforces GB standards for laser safety in volumetric projection systems, directly limiting brightness thresholds for consumer-facing installations. Stakeholders must weigh regulatory divergence against platform standardization bets as regional certification timelines diverge.
Market Dynamics
Photopolymer material substitution is compressing holographic panel production costs while broadcasters in South Korea deploy volumetric studios for live sports transmission, creating dual pressure on supply chains to scale manufacturing and content pipelines simultaneously.
Growth Catalysts
- Smart retail installations:Tier-one cities in China drive commercial procurement of holographic displays for immersive product visualization and customer engagement.
- Medical visualization adoption:Radiology departments deploy holographic systems for tumor mapping and preoperative surgical rehearsal, accelerating clinical validation cycles.
- Light field display patents:Samsung Electronics and Qualcomm patent portfolios are restructuring royalty frameworks across the ecosystem.
Market Restraints
- Laser brightness thresholds:China's MIIT GB standards cap luminance for consumer-facing volumetric projection systems, constraining outdoor and large-venue deployment.
- Spatial light modulator supply:Sub-micron pixel pitch SLM fabrication concentrates among captive semiconductor foundries, creating input bottlenecks.
- Conventional LCD substitution:Premium flat-panel displays retain cost advantages for non-immersive applications, limiting holographic TV addressable market expansion.
Strategic Opportunities
- Military simulation contracts:Defense procurement for depth-perception training systems offers stable, long-dated demand outside consumer cyclicality.
- Modular tile architectures:Scalable screen formats beyond fixed dimensions enable rental and event-based revenue models for display infrastructure.
- EU CE marking harmonization:Radio Equipment Directive compliance pathways create first-mover advantages for European distribution channel establishment.
Industry Challenges
- Optical engineering talent scarcity:Light field computation and interference-pattern algorithm development require specialized skill sets with limited academic pipeline output.
- Multi-regional certification timelines:Divergent FCC electromagnetic emissions standards, EU CE marking requirements, and China MIIT laser safety protocols force parallel compliance investments.
- Legacy broadcast infrastructure integration:Holographic transmission protocols require signal chain reconfiguration at production facilities and distribution headends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Holographic TV Market |
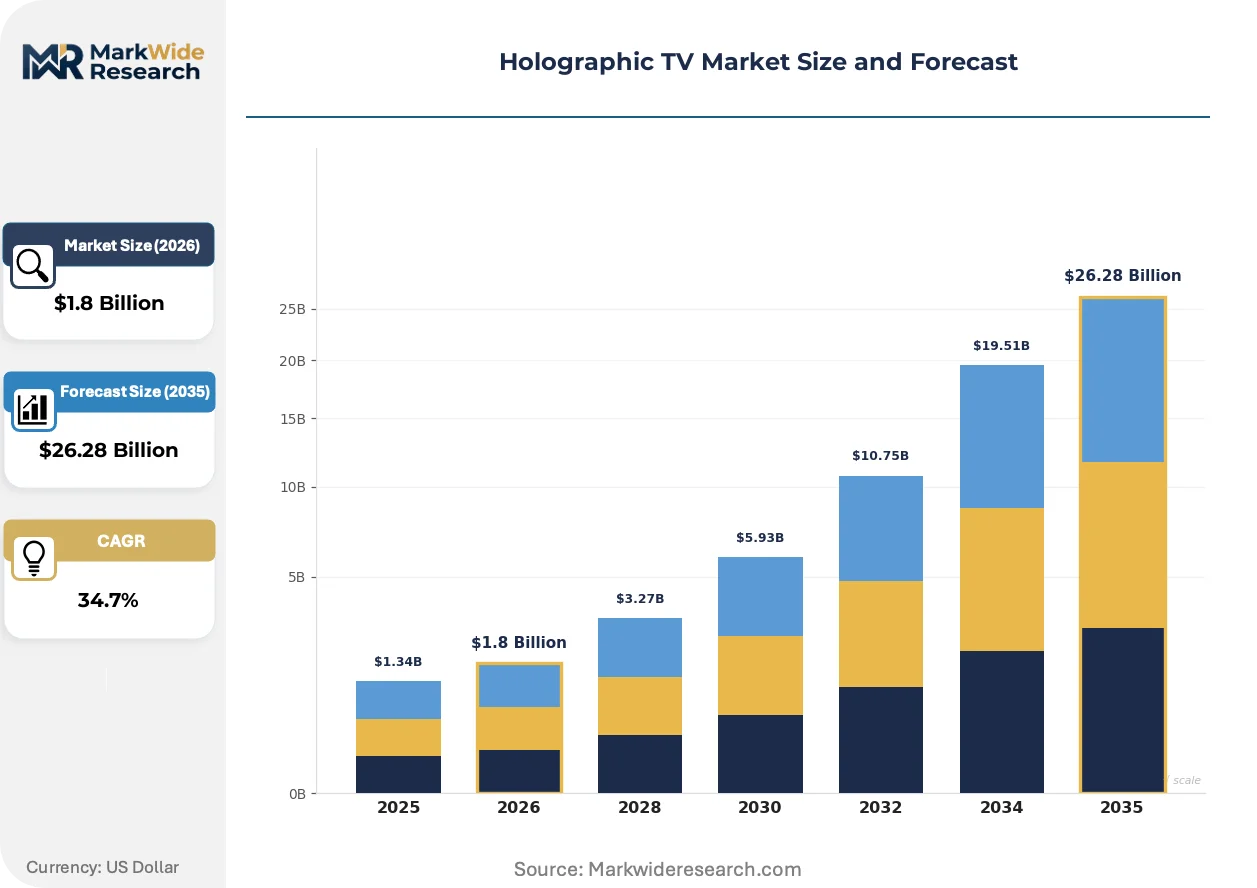
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Active Holography, Passive Holography, Volumetric Display, Light Field Display Market Type: Consumer Electronics, Broadcasting, Advertising, Medical Visualization Application: Home Entertainment, Education, Simulation, Gaming End User: Residential, Commercial, Educational Institutions, Medical Facilities |
| Companies Covered | Sony Corporation, Samsung Electronics Co., Ltd., Qualcomm Technologies, Inc., Looking Glass Factory Inc., RealFiction Holding AB, MDH Hologram Ltd., Holoxica Ltd., Musion Das Hologram Ltd., Light Field Lab Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Holographic TV Market Emerging Trajectories
Active patent litigation around light field reconstruction algorithms is accelerating technology diffusion while reshaping competitive entry barriers across the holographic display value chain.
Photopolymer materials are overtaking liquid crystal modulators as the dominant recording medium for holographic panels. Medical imaging departments in tertiary hospitals are adopting photopolymer-based systems at accelerated procurement cycles. This material transition is overtaking conventional semiconductor-based approaches in cost-sensitive commercial segments.
CE marking under the EU's Radio Equipment Directive is tightening electromagnetic compatibility requirements for holographic broadcast equipment. Manufacturers must redesign power supply and RF shielding subsystems to maintain European market access. Medical device manufacturers integrating holographic visualization face additional MDR compliance layers for surgical planning applications.
Hospital procurement departments are consolidating holographic visualization contracts under multi-year equipment leasing arrangements rather than capital purchase models. Radiology and surgical departments bundle display hardware with software maintenance and content update services. This financing shift is most pronounced in China's tier-one hospital networks and South Korean medical centers.
Holographic TV Market Segmentation
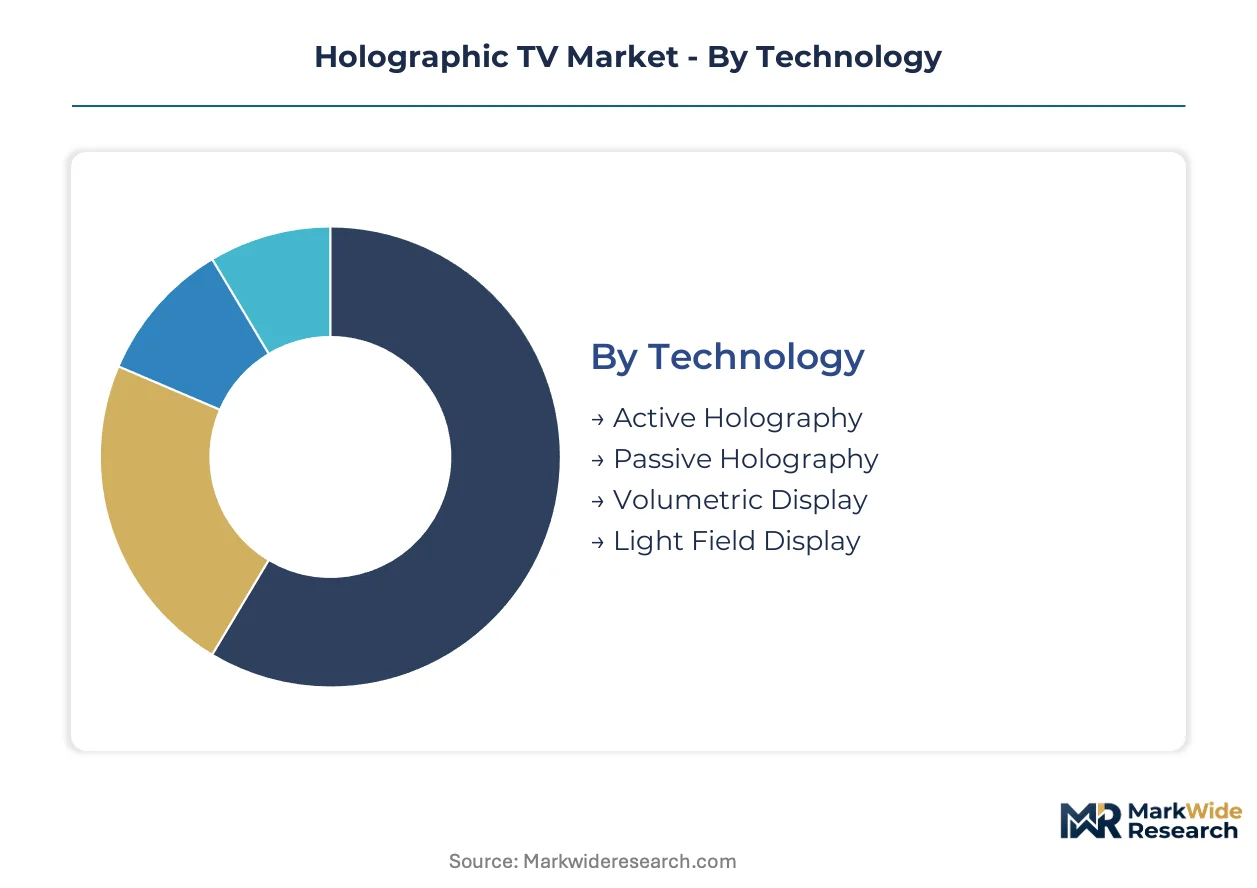
Technology heterogeneity in holographic TV creates divergent manufacturing footprints and content requirements across the value chain. Each segment category carries distinct procurement cycles, regulatory exposure, and margin profiles that reshape competitive positioning.
Technology:
Customization intensity varies sharply across this category, from fully proprietary light engine architectures to commoditized projection subsystems.
- Light Field Display:Photopolymer-based modulation arrays reconstruct accommodation-correct depth cues without eyewear. Samsung Electronics and Qualcomm patent portfolios dominate this space, with medical visualization departments in tertiary hospitals driving premium procurement.
- Volumetric Display:Swept-volume or static volumetric techniques generate true 3D imagery viewable from 360 degrees. South Korean broadcasters deploy these systems for live sports transmission, though China's MIIT laser brightness caps constrain outdoor scaling.
- Active Holography:Real-time interference pattern generation via spatial light modulators with sub-micron pixel pitch. Captive semiconductor foundries control SLM supply chains, creating input bottlenecks for non-integrated manufacturers.
- Passive Holography:Pre-recorded holographic content replayed through fixed optical assemblies. Lower computational overhead suits archival and educational content distribution.
Most installed capacity flows through Light Field Display. Expansion is steepest in Volumetric Display.
Market Type:
Customer sophistication and procurement authority separate institutional buyers from consumer-facing channels.
- Medical Visualization:Radiology departments deploy holographic systems for tumor mapping and preoperative surgical rehearsal. China's tier-one hospital networks and South Korean medical centers favor multi-year equipment leasing over capital purchase.
- Broadcasting:Live volumetric transmission requires signal chain reconfiguration at production facilities. South Korean broadcasters lead deployment, creating reference architectures for regional adoption.
- Consumer Electronics:Home entertainment applications compete against premium flat-panel LCD cost advantages. Smart retail installations in China's tier-one cities currently outpace residential demand.
- Advertising:Immersive product visualization drives commercial procurement for customer engagement deployments.
Revenue concentration sits with Medical Visualization. Customer acquisition costs run highest in Consumer Electronics.
Application:
Use case maturity determines whether deployments require bespoke content pipelines or leverage existing media libraries.
- Simulation:Military depth-perception training systems generate stable, long-dated demand outside consumer cyclicality. Defense procurement contracts favor modular tile architectures for scalable deployment.
- Home Entertainment:Immersive viewing without eyewear remains the consumer value proposition, though addressable market expansion faces conventional LCD substitution pressure.
- Gaming:Real-time parallax rendering demands substantial computational infrastructure. Light field reconstruction algorithms remain subject to active patent litigation.
- Education:Institutional procurement cycles align with academic budget calendars, creating predictable but lumpy demand patterns.
Simulation commands the highest average selling prices. Volume deployment concentrates in Home Entertainment.
End User:
Facility type dictates installation complexity, maintenance requirements, and financing structure preferences.
- Medical Facilities:Tertiary hospitals bundle display hardware with software maintenance and content update services. EU CE marking under the Radio Equipment Directive adds electromagnetic compatibility compliance layers.
- Commercial:Smart retail installations prioritize customer engagement metrics over technical specifications. China's tier-one cities drive regional procurement concentration.
- Educational Institutions:Budget constraints favor passive holography systems with lower computational overhead. Procurement aligns with fiscal year cycles.
- Residential:Cost sensitivity and content availability limitations suppress near-term adoption. FCC electromagnetic emissions standards govern US market equipment certification.
Medical Facilities generate the highest margins per installation. Commercial end users provide the largest addressable unit base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suwon anchors the global holographic TV production ecosystem through Samsung Electronics' volumetric display R&D investments. Medical visualization demand in Seoul's tertiary hospital networks and broadcast studio deployments across Gyeonggi Province concentrate procurement authority in this corridor.
United States
FCC electromagnetic emissions standards govern holographic TV broadcast equipment certification for distribution headends. Defense procurement contracts for military simulation systems generate stable demand outside consumer cyclicality. California-based Light Field Lab Inc. specializes in modular tile architectures for scalable screen formats.
China
MIIT enforces GB standards for laser safety in volumetric projection systems, capping brightness thresholds for consumer-facing installations. Smart retail installations in Shanghai, Beijing, and Shenzhen drive commercial procurement concentration. Tier-one hospital networks in these cities favor multi-year equipment leasing over capital purchase models.
South Korea
Broadcasters deploy volumetric studios for live sports transmission, creating reference architectures for regional adoption. The country's national telecommunications regulator shapes electromagnetic compatibility requirements for holographic broadcast infrastructure. Seoul Capital Area hospitals accelerate clinical validation cycles for tumor mapping applications.
Japan
METI industrial policy frameworks support light field display technology development through targeted R&D incentives. Sony Corporation leverages captive semiconductor fabrication to control light engine supply chains. Kanto region medical centers adopt holographic visualization for preoperative surgical rehearsal.
Germany
CE marking under the EU's Radio Equipment Directive tightens electromagnetic compatibility requirements for holographic broadcast equipment. Medical device manufacturers integrating holographic visualization face additional MDR compliance layers. Bavaria-based industrial clusters concentrate optical engineering talent for interference-pattern algorithm development.
Holographic TV Market Vendor Landscape
Global majors compete with regional champions across patent portfolio depth and captive semiconductor fabrication capabilities. The vendor base stratifies between integrated electronics conglomerates with in-house light engine production and specialized holographic display developers dependent on external spatial light modulator supply. Three archetypes dominate: semiconductor-integrated conglomerates, modular architecture specialists, and volumetric content system providers. Competitive moves concentrate on strategic patent licensing and backward integration into photopolymer material supply.
Within the semiconductor-integrated tier, Sony Corporation and Samsung Electronics Co., Ltd. exemplify captive fabrication strategies that insulate light engine supply chains from external bottlenecks. Qualcomm Technologies, Inc. occupies a position as a patent portfolio anchor whose licensing frameworks reshape royalty structures across the ecosystem. Light Field Lab Inc. represents the modular architecture specialist archetype, with its tile-based designs enabling rental and event-based revenue models beyond fixed-screen formats.
| Leading Market Players |
|---|
| Sony Corporation |
| Samsung Electronics Co., Ltd. |
| Qualcomm Technologies, Inc. |
| Looking Glass Factory Inc. |
| RealFiction Holding AB |
| MDH Hologram Ltd. |
| Holoxica Ltd. |
| Musion Das Hologram Ltd. |
| Light Field Lab Inc. |
| Others |
Supply Flow & Price Mechanics
China's MIIT GB laser safety standards gate both qualified photopolymer supply and premium-tier pricing access for consumer-facing volumetric systems, compressing margins for manufacturers unable to meet brightness thresholds while rewarding certified suppliers with pricing power in medical and broadcast segments.
Pricing Analysis
Photopolymer material costs pass through directly to panel pricing, with three-tier pricing structure across premium, standard, and economy levels separating medical-grade systems from commercial retail installations and educational deployments. Price differentiation rests on certification tier—CE marking and FDA-equivalent clinical validation command substantial premiums over uncertified commercial units. Pricing pressure stems from conventional LCD substitution in non-immersive applications, forcing holographic vendors to bundle software maintenance services. Medical facilities show least price sensitivity due to reimbursement-adjacent procurement authority, while educational institutions face acute budget constraints.
Supply Chain Analysis
Freight costs for spatial light modulator substrates concentrate supply chain leverage among captive semiconductor foundries in South Korea, Japan, and Taiwan. Photopolymer resins and sub-micron pixel pitch SLM wafers constitute critical input dependencies, with light engine assemblies drawing from Sony's in-house fabrication and Samsung's Suwon operations. Single-source vulnerability runs through specialized optical coating suppliers serving interference-pattern reconstruction modules. Distribution runs through direct hospital procurement in medical segments and systems integrators for commercial smart retail deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: manufacturers can exploit South Korea's broadcast infrastructure investments against China's stricter MIIT brightness caps by dual-certifying products for premium medical export channels.
For Market Incumbents: Lock in photopolymer supply agreements before material substitution accelerates cost compression. Sony Corporation and Samsung Electronics should expand captive semiconductor fabrication for spatial light modulators to neutralize input bottlenecks. Defensive patent licensing around light field reconstruction algorithms blocks emerging modular architecture specialists from royalty-free market entry. For New Entrants and Emerging Players: Enter via China's tier-one smart retail installations where procurement cycles favor new vendors over entrenched medical certification holders. White-space targets include modular tile architectures for event-based rental revenue and passive holography systems for educational institutions with predictable budget calendars. Go-to-market positioning should emphasize CE marking harmonization for European channel establishment ahead of FCC certification complexity. For Investors and Strategic Acquirers: Roll-up economics work for modular architecture specialists because fixed-screen format limitations create acquisition synergies for scalable tile-platform consolidation. Five-to-ten year viability hinges on clinical validation cycles in radiology departments converting from capital purchase to multi-year leasing models. Acquisition target archetype: optical engineering firms with interference-pattern algorithm IP and existing hospital procurement relationships. Signal to watch: South Korean broadcaster reference architectures achieving regional adoption velocity outside domestic deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Photopolymer Supply Agreement | Captive material sourcing insulates Samsung and Sony from liquid crystal modulator displacement costs. |
| CE Marking Harmonization | EU Radio Equipment Directive compliance creates first-mover distribution advantages against FCC-tethered competitors. |
| Modular Tile Platform Launch | Light Field Lab's scalable architectures enable rental revenue models beyond fixed-screen limitations. |
| Hospital Leasing Partnership | Multi-year equipment financing shifts procurement authority from capital committees to radiology department budgets. |
| Volumetric Broadcast Studio Deployment | South Korean live sports transmission creates reference architectures for regional broadcaster adoption. |
Methodological Framework
Multiple input streams—primary interviews with optical engineering directors, hospital procurement managers, and broadcast technology leads; secondary validation through MIIT GB standard filings, FCC electromagnetic emissions databases, and patent portfolio disclosures from Samsung Electronics and Qualcomm—were reconciled through bottom-up manufacturing capacity modeling and top-down demand segmentation across medical, broadcast, and commercial end-use categories.
Cross-referencing historical volumetric display shipment patterns against panel expert projections anchored CAGRs across the analysis window. Segmentation dimensions modeled include technology type (light field, volumetric, active holography, passive holography), end-user facility category (medical, commercial, educational, residential), and regional regulatory cluster (FCC-governed, CE-marking, MIIT-regulated). Industry-specific forecast inputs incorporated photopolymer material substitution curves and spatial light modulator foundry utilization rates.
Inputs from hospital procurement databases and broadcaster capital expenditure disclosures were available through the study window; gaps in volumetric content pipeline investment data introduce uncertainty bands around consumer adoption trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Mobile TV Market
Television
Curved Television Market
Television
Television Advertising Market
Television
Print Newspapers and Magazines Market
Television
Pay TV Operator Market
Television
Broadcasting and Cable TV Market
Television
Pay TV Services Market
Television
HDTV Market
Television
Cloud TV Market
Television
Global Broadcast Equipment Market
Television
Cable Television Networks Market
Television
Global Digital Terrestrial Television Market
Television
TV Advertising Market
Television
Traditional TV and Home Video Market
Television
Television Broadcasting Services Market
Television
Television Market