
 Free-To-Air (FTA) Service Market | 2026-2036
Free-To-Air (FTA) Service Market Size, Share, and Industry Trends Forecast 2026-2036
Free-To-Air (FTA) Service Market Analysis
IP-based content delivery is broadening the economic base of FTA operations beyond traditional spectrum-dependent models. British Broadcasting Corporation leverages its public funding structure to sustain high production values across multiple distribution channels. RTL Group anchors its competitive position through diversified European broadcasting assets and cross-border content syndication. ProSiebenSat.1 Media SE differentiates via entertainment-focused programming that competes effectively against subscription streaming alternatives.
Free-To-Air (FTA) Service denotes television and radio content distributed without subscription fees, typically transmitted via terrestrial towers, satellites, or digital platforms using standards such as DVB-T2 for ground-based signals and DVB-S2 for satellite uplinks, with primary purpose of maximizing audience reach through advertiser-funded business models. Broadcast Services still occupy the largest revenue pool in mature markets where spectrum allocation and transmitter infrastructure create durable barriers to entry. Streaming Services represents the fastest-expanding segment as hybrid FTA platforms integrate catch-up and live digital delivery to retain younger demographics. Satellite Broadcasting sustains critical importance in regions with limited terrestrial infrastructure, where geostationary coverage delivers universal access without ground network dependency.
Ofcom in the United Kingdom, the FCC in the United States, and the European Union's Audiovisual Media Services Directive collectively shape FTA market access through content quotas, advertising rules, and spectrum licensing frameworks that determine operational economics. India's TRAI and China's SAMR impose additional localization requirements that influence foreign content penetration and domestic production investment. Stakeholders must monitor evolving must-carry regulations and spectrum reallocation decisions that could redistribute competitive advantage between terrestrial, satellite, and internet-delivered FTA channels.
Market Dynamics
The Free-To-Air Service Market confronts a fundamental tension between spectrum-dependent broadcasting economics and IP-based delivery models that fragment audience attention across platforms. Digital terrestrial transition mandates are compressing legacy infrastructure timelines while hybrid platforms force capital reallocation toward streaming-capable architectures.
Growth Catalysts
- DVB-T2 Infrastructure Mandates:India's TRAI-enforced digital switchover compels terrestrial network upgrades that expand addressable households beyond analog coverage limits.
- Rural Satellite Penetration:Geostationary DVB-S2 deployments in Brazil's Amazon basin and India's northeastern states deliver universal video access without ground fiber dependency.
- Advertising Yield Optimization:Programmatic ad insertion technology is integrating with broadcast playout systems to narrow the revenue gap between FTA and addressable streaming inventory.
Market Restraints
- Spectrum Scarcity:Ofcom and FCC reallocation of UHF bands to mobile broadband operators shrinks available terrestrial multiplex capacity in the United Kingdom and United States.
- Transponder Cost Volatility:Geostationary satellite bandwidth leasing rates fluctuate with launch schedule delays and orbital slot congestion over Asia-Pacific orbital arcs.
- Subscription Streaming Substitution:Netflix and Disney+ original content investments pull younger demographics away from appointment-based FTA viewing patterns.
Strategic Opportunities
- Freemium Hybrid Models:Australia's Freeview Plus and the United Kingdom's YouView demonstrate how broadcaster-led streaming platforms capture digital-native audiences without paywall friction.
- Localized Content Quotas:China's SAMR domestic production requirements and India's TRAI localization mandates create protected demand for indigenous FTA programming.
- 5G Broadcast Convergence:3GPP Release 16 FeMBMS specifications enable mobile network operators to carry FTA signals alongside unicast traffic, opening handset-native distribution channels.
Industry Challenges
- Legacy Playout Integration:Broadcasters operating SDI-based master control rooms face forklift upgrade costs to IP-based SMPTE ST 2110 infrastructure.
- Cross-Platform Measurement:Nielsen and BARB audience metrics remain siloed between linear and digital consumption, complicating unified ad sales.
- Skillset Transition:RF engineering expertise for terrestrial transmission maintenance ages out faster than IP networking and cloud orchestration talent enters the workforce.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Free-To-Air (FTA) Service Market |
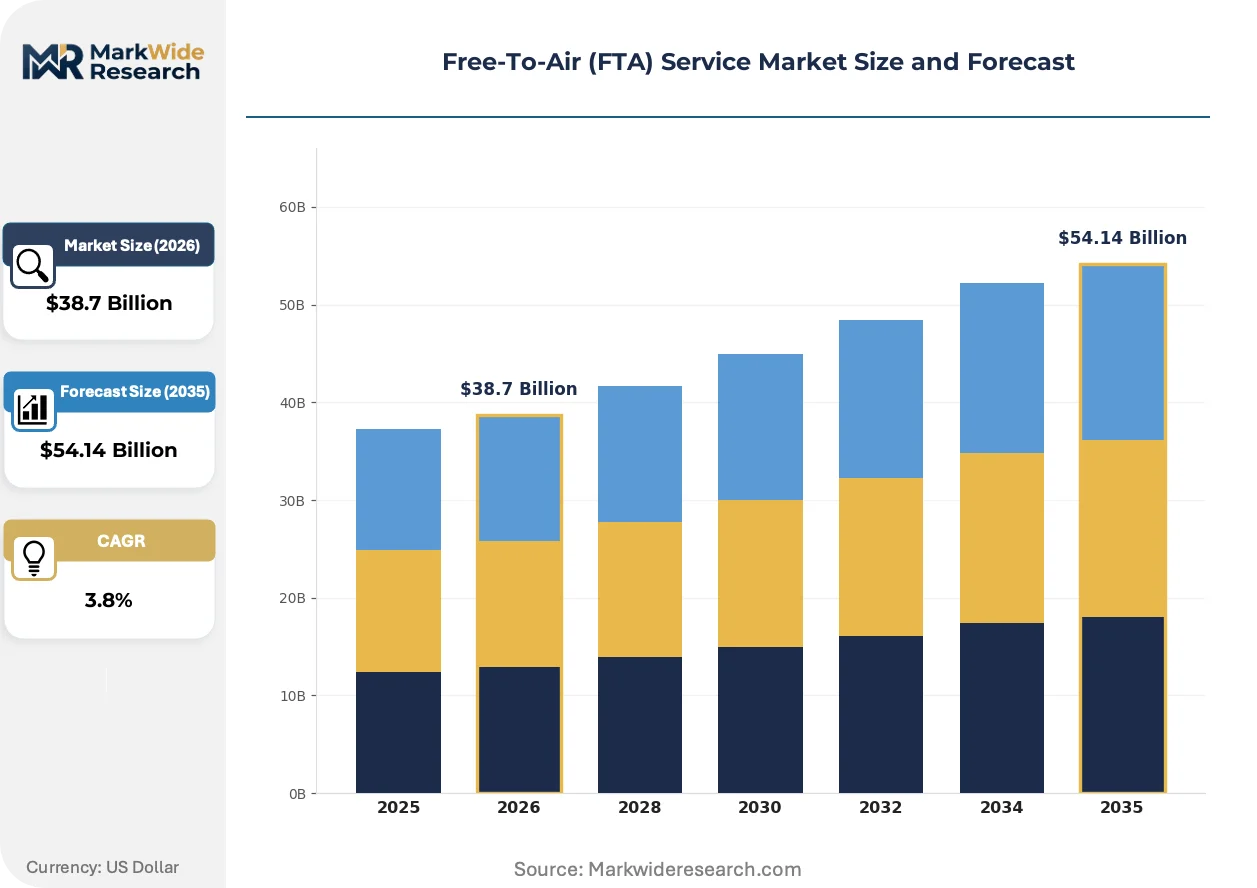
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $54.14 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Broadcast Services, Streaming Services, Mobile Broadcasting, Satellite Broadcasting Content Type: News, Sports, Entertainment, Educational Technology: DVB-T, ATSC, ISDB-T, DVB-S2 End User: Households, Public Institutions, Educational Institutions, Commercial Venues |
| Companies Covered | British Broadcasting Corporation, RTL Group, AMC Networks, Inc., Eutelsat S.A., ITV plc, ProSiebenSat.1 Media SE, Australian Broadcasting Corporation, China Central Television, Deutsche Telekom AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Free-To-Air (FTA) Service Market Emerging Trajectories
Technology convergence and regulatory compression are simultaneously expanding distribution channels and constraining operational economics for FTA operators. The sector's innovation trajectory centers on hybrid architectures that preserve spectrum assets while capturing digital audience behaviors.
ATSC 3.0 NextGen TV is integrating internet-delivered enhancement layers with terrestrial broadcast cores to enable targeted advertising and interactive services. Broadcasters in the United States, led by early deployments from Sinclair Broadcast Group and Pearl TV consortium members, are rolling out market-by-market. The technology is integrating broadcast reliability with broadband flexibility, compressing the historical trade-off between reach and personalization.
The European Union's Audiovisual Media Services Directive revision imposes platform accountability rules that extend to FTA broadcaster streaming extensions. Content quota enforcement now covers on-demand catalogues, not just linear schedules. FTA operators in Germany, France, and Italy are responding by front-loading domestic production investments to lock compliance ahead of 2025 reporting deadlines.
Viewer aggregation behavior is fragmenting across device types and consumption contexts, with younger cohorts discovering FTA content through social media clips rather than electronic program guides. Broadcasters are responding with short-form vertical video strategies on TikTok and Instagram Reels that funnel toward full-length catch-up platforms. This pattern is most visible in the United Kingdom and South Korea, where public service broadcasters have established dedicated digital content studios.
Free-To-Air (FTA) Service Market Segmentation
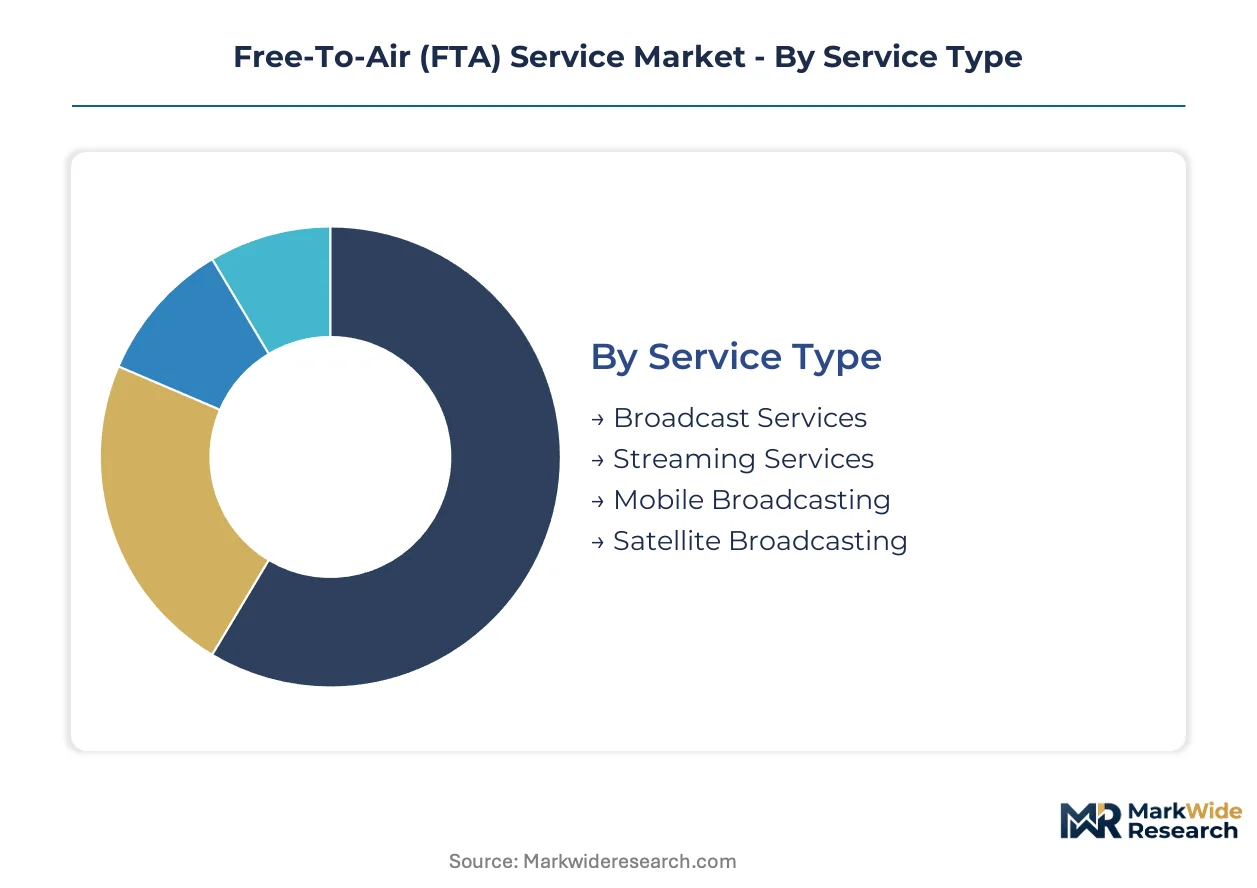
FTA service segmentation reveals divergent infrastructure economics across delivery modes. Each category reflects distinct capital intensity, regulatory exposure, and audience monetization pathways that shape competitive positioning.
Service Type:
Supply concentration clusters around terrestrial infrastructure in populous markets where spectrum licensing creates durable incumbency, while satellite capacity distributes more evenly across orbital slot holders.
- Broadcast Services:Terrestrial transmission via DVB-T2 and ATSC 3.0 standards delivers mass reach through fixed transmitter networks. India's TRAI-mandated digital switchover and Brazil's SBTVD-T standardization concentrate demand in emerging economies where spectrum scarcity limits new entrants.
- Streaming Services:IP-delivered FTA platforms integrate catch-up functionality and live simulcasts to retain demographics migrating from appointment viewing. Australia's Freeview Plus and the United Kingdom's YouView demonstrate broadcaster-led aggregation models that capture digital-native audiences without subscription friction.
- Mobile Broadcasting:3GPP FeMBMS specifications enable carrier-agnostic distribution to handsets, though deployment remains fragmented across mobile network operator strategies.
- Satellite Broadcasting:Geostationary DVB-S2 deployments serve rural and remote geographies beyond terrestrial fiber reach.
Today's leader: Broadcast Services. Tomorrow's challenger: Streaming Services.
Content Type:
Production cost structures and advertising yield vary dramatically across content verticals, with live formats commanding premium inventory pricing.
- News:Public service obligations and regulatory must-carry rules sustain 24-hour operations. The BBC and ARD-ZDF networks anchor investment levels that commercial rivals struggle to match.
- Sports:Live event rights concentrate audience attention during fixed windows, delivering irreplaceable advertising inventory. India's IPL cricket and Brazil's Campeonato Brasileiro command domestic FTA exclusivity fees that reshape broadcaster balance sheets.
- Entertainment:Scripted and unscripted formats face direct substitution from Netflix and Disney+ original productions.
- Educational:Government procurement and public service mandates sustain niche distribution, particularly in India's state-run DD Gyan Darshan channels.
Sports and news lock in recurring audiences; entertainment formats face the steepest streaming substitution pressure.
Technology:
Standard adoption curves determine equipment replacement cycles and backward compatibility burdens across transmitter and receiver ecosystems.
- DVB-T:Legacy terrestrial standard retains installed base in markets delaying T2 migration.
- ATSC:North American standard evolves through 3.0 NextGen TV deployments integrating broadband enhancement layers. Sinclair Broadcast Group and Pearl TV consortium members lead United States market rollouts.
- ISDB-T:Japanese-developed standard with integrated mobile reception capabilities dominates Brazil and the Philippines through SBTVD-T regional variants.
- DVB-S2:Satellite transmission standard enables high-efficiency modulation for bandwidth-constrained transponder leases.
ATSC 3.0 and DVB-T2 are gaining share fastest among upgrade cycles; legacy DVB-T faces accelerated obsolescence timelines.
End User:
Procurement authority and viewing context fragment addressable markets across consumer, institutional, and commercial deployment scenarios.
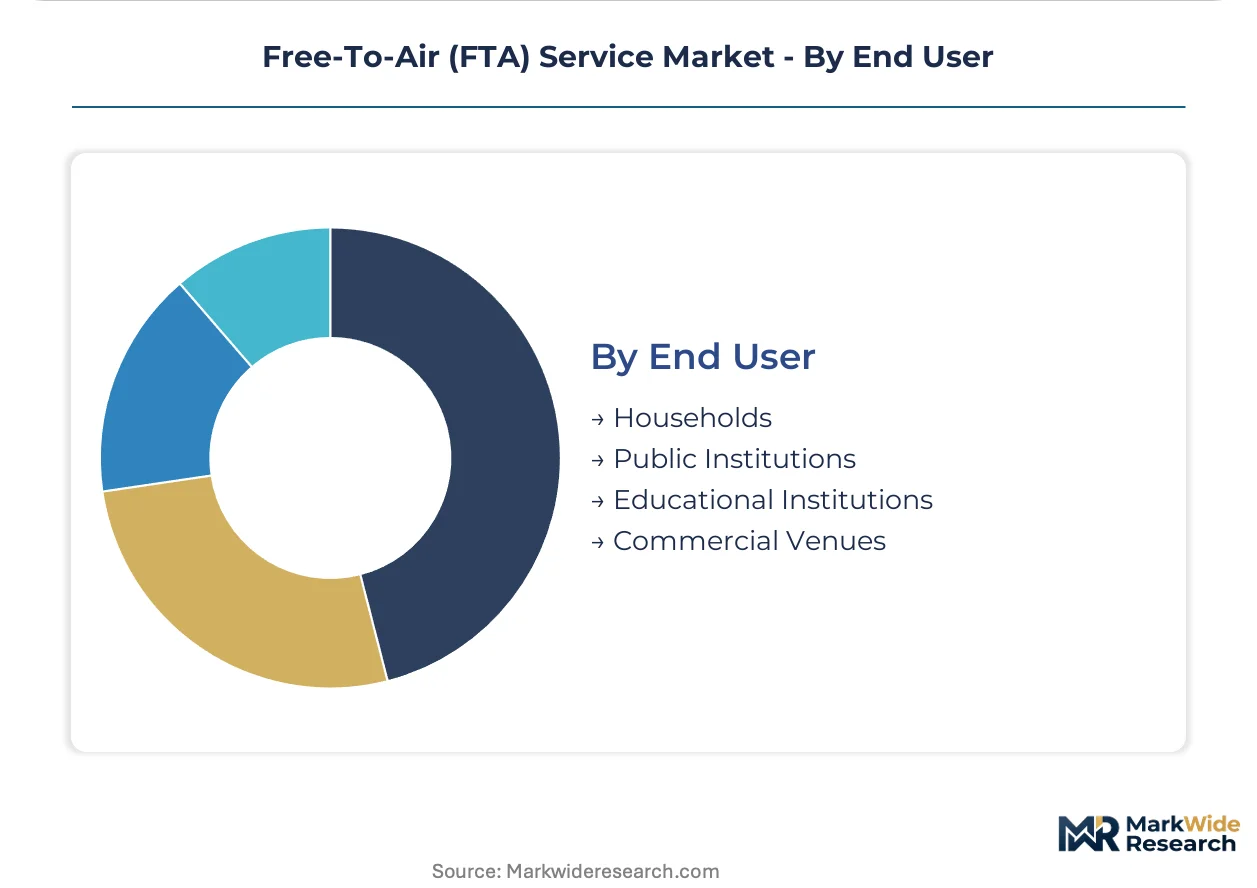
- Households:Residential consumption drives advertising revenue models through individual and family viewing aggregates. India's rural electrification and Brazil's satellite subsidy programs expand addressable households beyond urban fiber footprints.
- Public Institutions:Government buildings, healthcare facilities, and transport hubs require always-on information displays with minimal maintenance overhead.
- Educational Institutions:Schools and universities leverage FTA for curriculum support and campus-wide distribution without licensing complexity.
- Commercial Venues:Retail, hospitality, and workplace deployments prioritize low-cost background content with minimal subscription management.
Households anchor revenue; commercial venues offer untapped programmatic advertising integration potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's rural electrification programs and digital terrestrial mandates anchor the largest expansion corridor for FTA services, with regulatory-driven infrastructure upgrades reshaping household access patterns across multiple continents.
India
Rural satellite adoption and TRAI-mandated DVB-T2 switchover drive household penetration beyond analog coverage zones. The government's Prasar Bharati infrastructure investments expand terrestrial multiplex capacity into northeastern states. Mumbai and Delhi production clusters dominate content origination for nationwide distribution.
United States
Sinclair Broadcast Group and Pearl TV consortium deployments of ATSC 3.0 NextGen TV integrate targeted advertising capabilities with terrestrial reach. FCC spectrum reallocation decisions compress available UHF capacity in major metropolitan markets. Los Angeles and New York anchor national network origination and affiliate operations.
Brazil
Amazon basin geostationary DVB-S2 deployments deliver universal video access without ground fiber dependency. Anatel's SBTVD-T standardization mandates accelerate transmitter network modernization across underserved regions. São Paulo's broadcasting complex concentrates domestic production and satellite uplink facilities.
United Kingdom
Ofcom's platform accountability rules under the revised Audiovisual Media Services Directive extend compliance obligations to streaming extensions. YouView and Freeview Plus demonstrate broadcaster-led digital aggregation without subscription friction. London's Soho production district sustains high-value content origination for multi-platform distribution.
Germany
ARD-ZDF public service networks anchor investment levels that commercial rivals struggle to match for news and cultural programming. The EU's content quota enforcement now covers on-demand catalogues ahead of 2025 reporting deadlines. Cologne and Munich broadcasting centers concentrate sports rights negotiations and entertainment production.
Free-To-Air (FTA) Service Market Vendor Landscape
Global majors compete with regional champions across spectrum allocation and content origination capabilities, producing a tiered structure where public service broadcasters coexist with commercial groups and satellite infrastructure providers. The vendor base separates into three strategic archetypes: publicly funded national broadcasters sustaining high production values, pan-European commercial groups leveraging cross-border syndication, and orbital slot operators monetizing geostationary capacity. Dominant competitive moves include portfolio diversification into streaming platforms and strategic partnerships for sports rights consolidation.
Within the public service archetype, British Broadcasting Corporation and Australian Broadcasting Corporation represent state-funded models sustaining multi-platform distribution without commercial advertising dependency. Among commercial broadcasters, RTL Group and ProSiebenSat.1 Media SE exemplify European diversified groups competing through entertainment-focused programming against subscription streaming alternatives. These entities occupy positions defined by regulatory environment and geographic licensing scope rather than pure market share metrics.
| Leading Market Players |
|---|
| British Broadcasting Corporation |
| RTL Group |
| AMC Networks, Inc. |
| Eutelsat S.A. |
| ITV plc |
| ProSiebenSat.1 Media SE |
| Australian Broadcasting Corporation |
| China Central Television |
| Deutsche Telekom AG |
| Others |
Supply Flow & Price Mechanics
RF engineering talent concentration in Germany's broadcast technology corridor widens labor-cost differentials between European equipment vendors and Asian manufacturing alternatives, compressing pricing-tier spreads for transmitter infrastructure and satellite ground systems.
Pricing Analysis
Input-cost pass-through from geostationary transponder leasing and semiconductor component sourcing shapes FTA equipment pricing structures. Three-tier pricing structure across premium, standard, and economy levels separates broadcast-grade transmitters with ATSC 3.0 capability from legacy DVB-T hardware and basic satellite reception kits. Pricing pressure stems from mobile broadband operators bidding for UHF spectrum reallocation in the United States and United Kingdom. Rural satellite households in India and Brazil exhibit highest price sensitivity, while public service broadcasters in Germany and the United Kingdom demonstrate lowest sensitivity due to state funding mechanisms.
Supply Chain Analysis
Certification gating through FCC equipment authorization and CE marking requirements constrains transmitter and set-top box supplier pools. Manufacturing concentrates in China, South Korea, and Taiwan for RF components and consumer reception devices. Supply chains draw from gallium nitride semiconductors, high-power vacuum tubes, and precision antenna substrates. Single-source vulnerability sits with geostationary orbital slot holders over Asia-Pacific arcs. Distribution runs through national broadcast infrastructure contractors and direct procurement by public service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Free-To-Air Service Market functions as a stable compounder anchored by regulatory-mandated infrastructure refresh cycles that guarantee replacement demand regardless of economic cycles.
For Market Incumbents: Anchor spectrum portfolio value through accelerated ATSC 3.0 and DVB-T2 transmitter deployments ahead of regulatory deadlines. Secure exclusive sports rights in India and Brazil to lock advertising inventory against Netflix and Disney+ substitution. Invest in cloud-native playout infrastructure to compress legacy SDI migration costs.
For New Entrants and Emerging Players: Enter via 5G broadcast convergence partnerships with mobile network operators seeking differentiated content offerings. Target rural satellite households in Brazil's Amazon basin and India's northeastern states where terrestrial infrastructure gaps persist. Deploy freemium streaming platforms with broadcaster aggregation to capture digital-native audiences without spectrum licensing barriers.
For Investors and Strategic Acquirers: Satellite operators and telecommunications infrastructure funds are the most active acquirers in this space, consolidating orbital slot assets and ground station networks. The five-to-ten-year viability window favors platforms with hybrid broadcast-streaming architectures. Acquisition target archetypes include regional sports rights aggregators and cloud playout technology specialists. The signal to watch is spectrum reallocation decisions by the FCC and Ofcom that could compress terrestrial multiplex economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Platform Integration | Freeview Plus and YouView demonstrate broadcaster-led streaming aggregation capturing digital-native demographics without paywall friction. |
| Sports Rights Consolidation | IPL cricket and Campeonato Brasileiro exclusivity fees reshape balance sheets for Indian and Brazilian broadcasters. |
| 5G Broadcast Deployment | 3GPP FeMBMS specifications enable mobile network operators to distribute FTA signals alongside unicast traffic. |
| Cloud Playout Migration | IP-based SMPTE ST 2110 infrastructure replaces SDI master control rooms to enable programmatic ad insertion. |
| Localized Content Investment | China's SAMR and India's TRAI mandates create protected demand for indigenous programming production. |
Methodological Framework
Bottom-up household penetration modeling reconciled against top-down spectrum licensing and transponder capacity tracking forms the analytical core. Primary interviews with broadcast technology procurement officers, satellite operator sales directors, regulatory affairs leads at public service networks, and RF engineering consultants were validated against secondary sources including FCC licensing databases, TRAI consultation papers, Eutelsat capacity disclosures, and Ofcom spectrum auction records. Triangulation between demand-side household surveys and supply-side infrastructure deployment data ensures segmentation integrity.
Historical trendline analysis across digital switchover completion rates and streaming platform adoption curves informed projection frameworks. The analysis window spans infrastructure investment cycles, regulatory compliance deadlines, and technology substitution patterns. Segmentation dimensions modeled include delivery mode, content vertical, transmission standard, and end-user context. CAGR derivation rests on equipment replacement timelines and advertising yield trajectories. Industry-specific forecast inputs incorporate DVB-T2 migration schedules and ATSC 3.0 market-by-market rollout pacing.
Inputs from spectrum regulators and satellite operators were available through the study window; gaps in rural household survey coverage introduce uncertainty bands for emerging market penetration forecasts. Forecasts reflect documented assumptions regarding infrastructure investment continuity and advertising market stability. Regulatory reversal on digital switchover mandates or accelerated spectrum reallocation could materially revise projections. A model refresh is warranted upon material change in spectrum allocation policy or 5G broadcast deployment commitments by major mobile network operators.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Cable Television Networks Market
Television
Pay TV Services Market
Television
TV Advertising Market
Television
Television and Set Top Box Market
Television
Digital TV Market
Television
Television Broadcasting Services Market
Television
Pay TV Market
Television
Curved Television Market
Television
Mobile TV Market
Television
HDTV Market
Television
Pay TV Operator Market
Television
Global Broadcast Equipment Market
Television
Cloud TV Market
Television
Television Advertising Market
Television
Print Newspapers and Magazines Market
Television
Television Services Market