
 Curved Television Market | 2026-2036
Curved Television Market Size, Share, and Industry Trends Forecast 2026-2036
Curved Television Market Intelligence
The margin premium for curved form factors over standard flat-panel displays is narrowing as manufacturing processes mature and scale. Samsung Electronics leverages its significant R&D investment and vertical integration in OLED and QLED panel production. LG Electronics differentiates through its proprietary display technologies and strong global distribution network. Chinese manufacturers like TCL Technology and Hisense Group compete on price and feature sets, particularly in the 65-inch category.
A curved television is a display device featuring a concave screen with a specific radius of curvature, such as 4200R. This design aims to create a more immersive viewing field by matching the natural curve of human vision and reducing peripheral distortion. The 65-inch screen size segment currently accounts for a substantial portion of sales volume. While 4K remains the dominant resolution, the emerging 8K category offers higher margins, primarily within the premium QLED and OLED product types.
Manufacturers must adhere to a complex web of regional and international standards that govern electronics. Compliance with FCC regulations in the United States, CE marking and RoHS directives in Europe, and China's GB standards is mandatory for market access. These rules dictate everything from power consumption to the use of specific materials. The strategic decision for panel makers and OEMs now centers on allocating R&D between perfecting curved displays and advancing next-generation form factors.
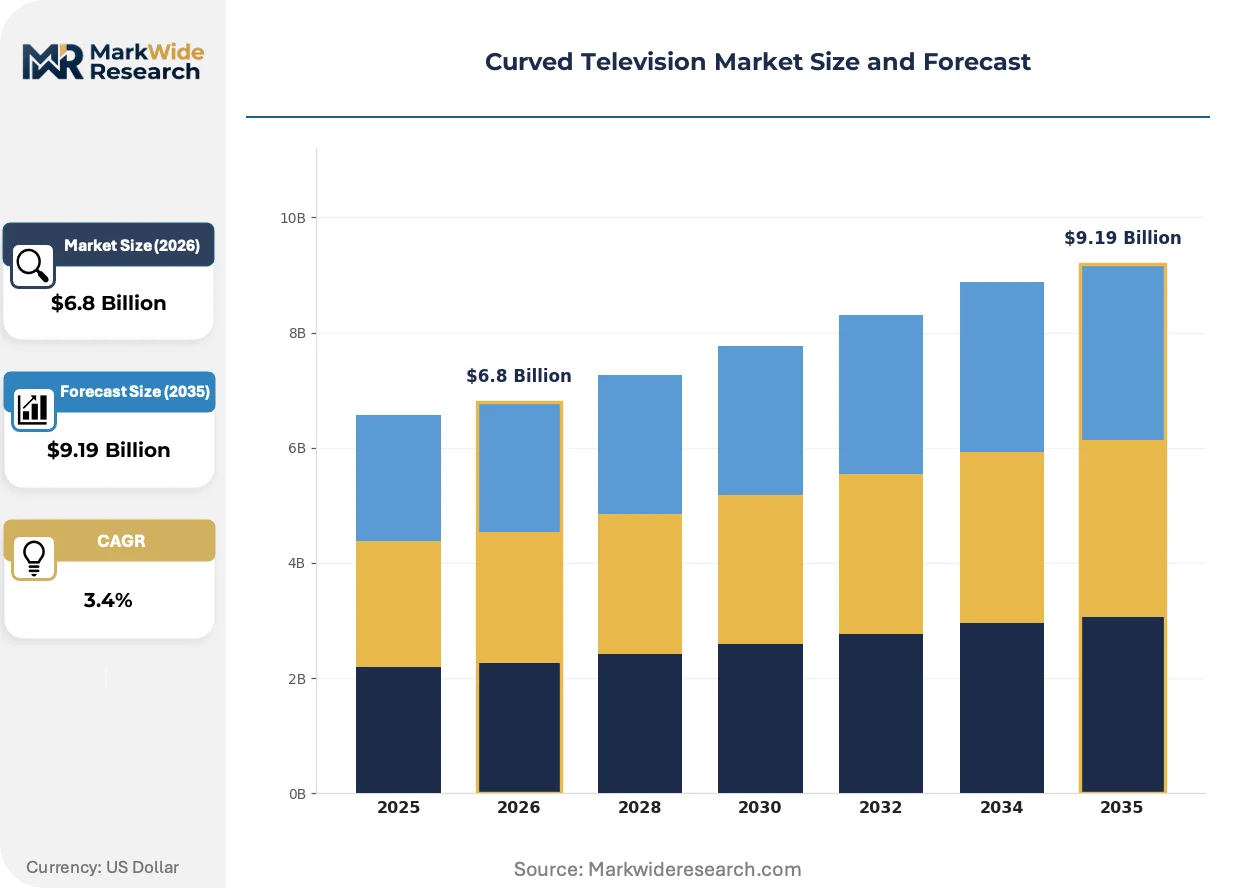
Market Dynamics
The market's central dynamic involves the strategic allocation of capital between optimizing mature curved panel manufacturing for cost efficiency and funding R&D for next-generation form factors like foldable or transparent displays, which promise higher margins.
Growth Catalysts
- MicroLED Technology:Advancements in MicroLED display fabrication enable thinner, more vibrant, and nearly bezel-less curved screens, stimulating demand within the premium home theater and commercial display segments.
- Hospitality Sector Investment:Hotels and resorts are increasingly installing curved televisions in suites and lounges to create a more immersive and luxurious guest experience, providing a stable source of B2B demand.
- South Korean Manufacturing Ecosystem:The concentration of display panel production and R&D in South Korea creates supply chain efficiencies and accelerates innovation, supporting market stability and technological leadership.
Market Restraints
- Substitution from Flat Panels:The narrowing price gap between large-format curved and flat-panel 4K televisions diminishes the perceived value of the curved form factor for many mainstream consumers.
- Viewing Angle Limitations:Curved screens possess an optimal viewing "sweet spot," which can result in geometric distortion for viewers positioned off-center, limiting their suitability for larger family viewing environments.
- Higher Production Costs:Manufacturing a concave screen, particularly with delicate OLED substrates, involves complex processes for glass bending and lamination that are inherently more costly than producing flat panels.
Strategic Opportunities
- Gaming and Simulation Niches:There is an opportunity to target high-end PC gaming setups and professional simulation systems, where the wide, immersive field of view offers a distinct functional advantage over flat displays.
- Smart Home Integration:Developing curved displays that serve as interactive smart home hubs, featuring transparent information overlays or ambient content, can create new value propositions beyond media consumption.
- Luxury Residential Markets:Targeting high-end residential and hospitality projects in affluent markets like the UAE and Saudi Arabia can capture demand from buyers prioritizing premium aesthetics and cutting-edge technology.
Industry Challenges
- Logistical Complexity:The fragility and non-stackable shape of large curved screens increase the complexity, cost, and risk of damage during shipping and handling compared to conventional flat-panel televisions.
- Energy Efficiency Compliance:Adhering to increasingly stringent power consumption regulations, such as the EU's Ecodesign Directive, requires continuous redesign of backlighting and power supply components.
- Intellectual Property Navigation:Securing licenses and avoiding infringement within the dense patent landscape surrounding OLED, QLED, and MicroLED technologies presents a significant hurdle for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Curved Television Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.19 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OLED, LED, QLED, MicroLED Screen Size: 55 Inch, 65 Inch, 75 Inch, 85 Inch Resolution: 4K, 8K, Full HD, Ultra HD End User: Residential, Commercial, Hospitality, Education |
| Companies Covered | Samsung Electronics, LG Electronics, Sony Corporation, Haier Group, Hisense Group, TCL Technology, Panasonic Corporation, Sharp Corporation, Sichuan Changhong Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Curved Television Market Strategic Shifts & Innovations
The evolution of curved televisions is now defined less by the novelty of the form factor itself and more by deeper software integration, stricter environmental compliance, and changing consumer use cases that extend beyond traditional media viewing.
Advanced image processing, driven by on-device artificial intelligence, dynamically optimizes picture settings based on ambient light and on-screen content. Premium segment buyers and home theater enthusiasts are the primary adopters seeking this automated picture perfection. This on-device processing is virtualizing the need for expensive professional calibration, making high-fidelity viewing more accessible out of the box.
Updated RoHS (Restriction of Hazardous Substances) directives in the European Union are forcing supply chain adjustments. These rules compel manufacturers to phase out specific flame retardants and plasticizers commonly used in television chassis and internal components. This shift most directly impacts component suppliers, who must invest in R&D and certification for alternative, compliant materials to maintain access to the European market.
A significant behavioral shift sees consumers prioritizing a television's integration into a broader smart home ecosystem over its standalone technical specifications. This disrupts traditional retail sales models that focused on resolution and screen size, shifting the emphasis toward platform compatibility with systems like Apple HomeKit or Google Home. The trend is most pronounced in North American and European markets with high smart home device penetration.
Curved Television Market Segmentation
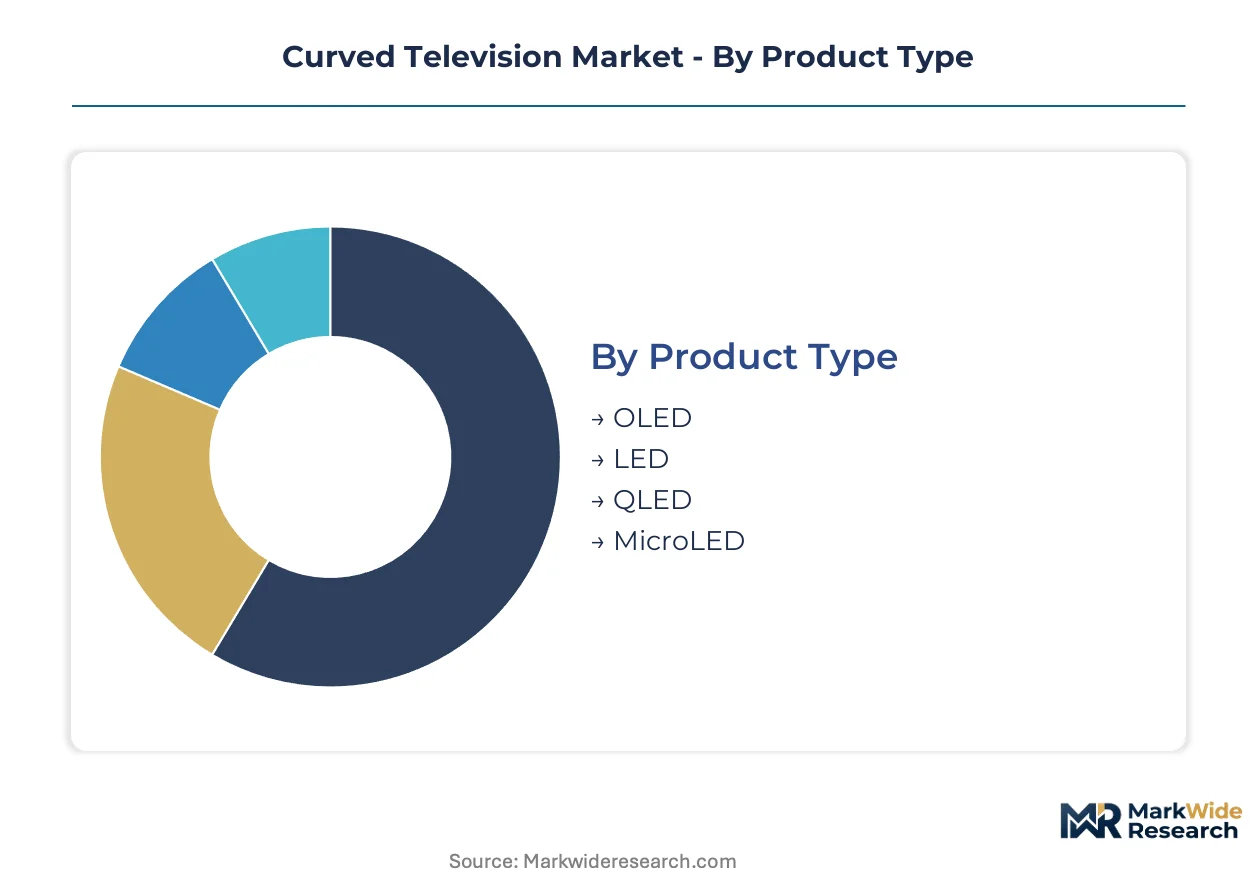
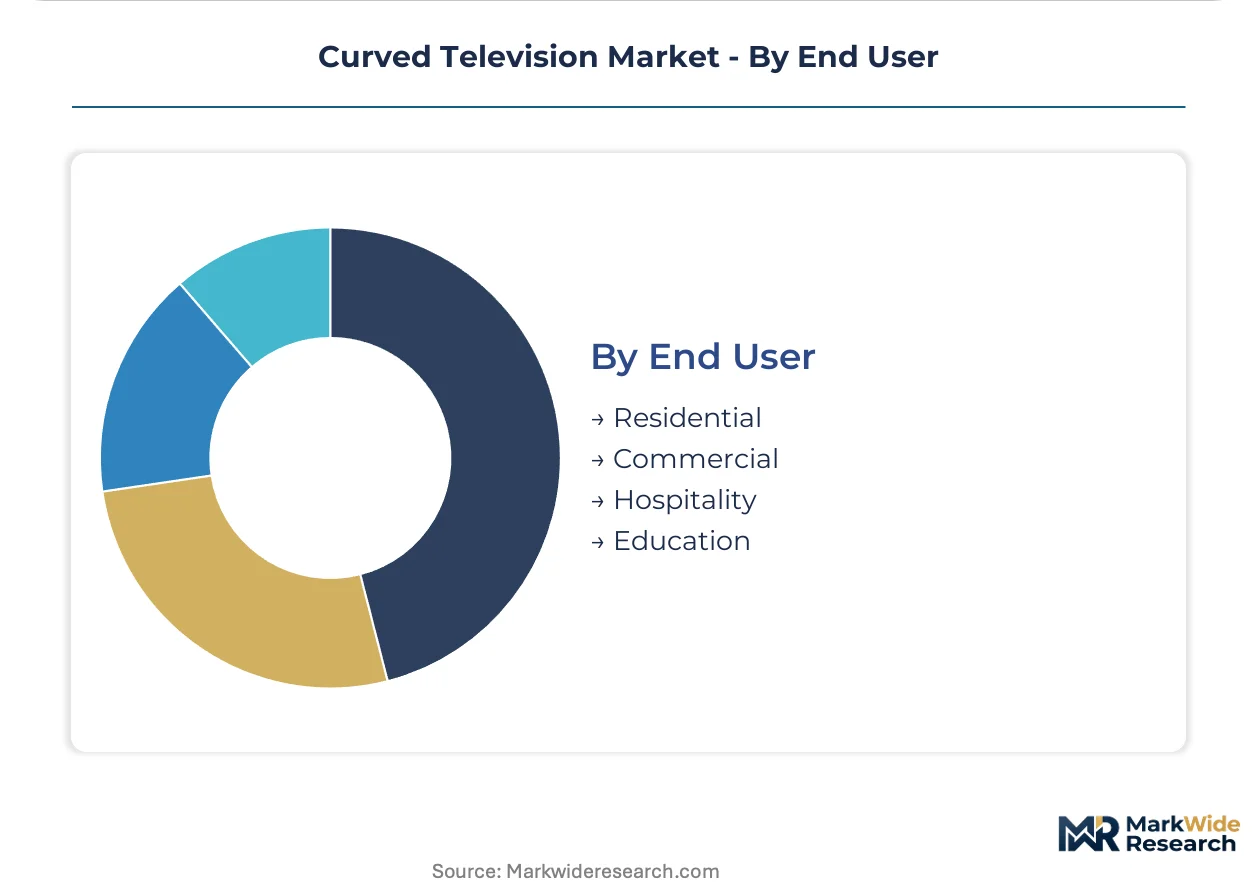
The Curved Television Market exhibits distinct segmentation across key product attributes and end-user applications. Understanding these segments provides clarity on demand drivers and competitive dynamics within the industry. This granular analysis highlights where value accrues and where innovation concentrates.
Product Type:
The market for curved televisions differentiates by core display technology, influencing visual performance and manufacturing cost structures.
- OLED:These displays utilize organic light-emitting diodes, allowing for individual pixel illumination and perfect blacks, creating superior contrast and color accuracy. Demand concentrates in premium home theater setups and luxury residential projects, driven by discerning consumers seeking cinematic visual quality.
- QLED:Quantum Dot Light Emitting Diode technology enhances traditional LED backlighting with quantum dots to produce brighter, more vibrant colors and improved contrast. This technology targets high-end consumers who prioritize brightness and color volume, particularly in well-lit viewing environments.
- LED:Light Emitting Diode displays represent a mature technology, offering cost-effective production and reliable performance through backlighting.
- MicroLED:This emerging technology employs microscopic LED arrays for direct pixel illumination, promising superior brightness, longevity, and modularity for future large-scale applications.
LED commands the established base. The steepest expansion runs through MicroLED.
Screen Size:
Consumer preference and installation space dictate screen size adoption, reflecting diverse viewing environments from personal setups to communal areas.
- 65 Inch:This screen size represents a substantial portion of sales volume, balancing immersive viewing with practical room integration for many residential consumers. Its popularity stems from a sweet spot between visual impact and affordability for mainstream premium buyers.
- 75 Inch:These larger displays offer an expanded, more enveloping viewing experience, increasingly favored by home theater enthusiasts and in larger living spaces. The demand for 75-inch screens is also rising within hospitality suites for enhanced guest immersion.
- 55 Inch:A foundational screen size, 55-inch curved televisions cater to smaller living areas or secondary viewing rooms, offering an entry point.
- 85 Inch:Positioned at the ultra-premium end, 85-inch curved televisions target luxury residential installations and high-impact commercial signage.
Larger format screens are gaining share fastest within the segment.
Resolution:
Visual fidelity requirements tier the market by display resolution, influencing picture clarity and content compatibility for viewers.
- 4K:This resolution, also known as Ultra High Definition, provides four times the pixel count of Full HD, delivering sharp, detailed images that are now standard across most premium curved televisions. It remains the dominant resolution for media consumption and gaming.
- 8K:Offering sixteen times the pixels of Full HD, 8K resolution provides unparalleled image clarity, primarily targeting early adopters and luxury segments where visual immersion is paramount. Content availability is an evolving constraint for this premium tier.
- Full HD:Representing 1080p resolution, Full HD curved televisions provide standard high-definition picture quality for budget-conscious or smaller screen size offerings.
- Ultra HD:This term is largely synonymous with 4K resolution, denoting a display with at least 3840x2160 pixels, common for high-resolution curved screens.
Premium resolutions are climbing the fastest, driven by technological advancements.
End User:
The application of curved displays varies significantly across end-user segments, each with distinct purchasing criteria and usage patterns.
- Residential:This segment encompasses individual households purchasing curved televisions for personal entertainment, driven by desires for immersive viewing, aesthetics, and smart home integration. Demand is influenced by disposable income and adoption of home theater systems.
- Hospitality:Hotels and resorts are increasingly deploying curved televisions in guest rooms and common areas to elevate the guest experience, providing a luxurious and technologically advanced amenity. This sector values durability and seamless integration with property management systems.
- Commercial:Commercial applications include corporate lobbies, retail displays, and advertising, where curved screens offer dynamic visual engagement and aesthetic appeal.
- Education:The education sector utilizes curved displays for interactive learning environments and specialized training simulations, enhancing engagement.
The hospitality sector is expanding most quickly, driven by luxury amenity upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for curved televisions varies significantly by geography, with some regions prioritizing luxury and immersive experiences while others focus on technological leadership and manufacturing prowess. This differentiation shapes demand patterns and regulatory adherence across key markets globally. Specific national regulations and consumer preferences influence market penetration and product development.
South Korea
Demand in South Korea is driven by early technology adoption and a strong domestic preference for high-end display innovations. The country's Ministry of Trade, Industry and Energy (MOTIE) supports display technology R&D through various initiatives. Paju and Asan serve as major display manufacturing hubs, fostering continuous advancements in OLED and MicroLED panel production.
United States
Residential consumers in the United States seek immersive home theater experiences and seamless smart home integration. The Federal Communications Commission (FCC) regulates electronic device emissions and ensures product safety for market access. Silicon Valley and other tech centers drive software integration and content delivery innovations for premium display devices.
Germany
Luxury residential projects and professional simulation systems drive demand for curved displays in Germany. Compliance with CE marking and the EU's Ecodesign Directive is mandatory for all electronics sold within the European Union. Bavaria and Baden-Württemberg host engineering firms and automotive companies exploring advanced display applications.
China
The Chinese market exhibits strong demand for large-format screens, balancing price competitiveness with feature sets, particularly in the 65-inch category. Adherence to China's GB standards is essential for all electronic products entering the vast domestic market. Shenzhen and other Pearl River Delta cities concentrate display manufacturing and drive rapid product iteration.
United Arab Emirates
High-net-worth individuals and the burgeoning hospitality sector in the United Arab Emirates prioritize curved televisions for luxury aesthetics and guest experience. The Emirates Authority for Standardization and Metrology (ESMA) sets product safety and energy efficiency standards. Dubai and Abu Dhabi lead in high-end residential and commercial installations, reflecting a strong luxury market.
Curved Television Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a dynamic competitive landscape in the curved television market. The market exhibits a tiered structure, with established display manufacturers at the premium end and emerging players competing on value. Strategic archetypes include technology innovators, mass-market producers, and niche specialists. Dominant competitive moves involve continuous R&D investment in display technologies and strategic partnerships for distribution.
On the premium-tier vector, South Korea-based Samsung Electronics Co., Ltd. and LG Electronics Inc. exemplify leadership in OLED and QLED panel production through extensive research and development. These companies occupy a position defined by proprietary display technologies and global distribution networks. Chinese manufacturer TCL Technology Group Corporation, by contrast, anchors the value-oriented segment, competing effectively on price and feature sets, especially within the 65-inch screen size category.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Sony Corporation |
| Haier Group |
| Hisense Group |
| TCL Technology |
| Panasonic Corporation |
| Sharp Corporation |
| Sichuan Changhong Electric |
| Others |
Cost & Logistics Intelligence
Regulatory chokepoints, such as the EU's Ecodesign Directive, determine both pricing tier spreads and the global supply chain shape for curved televisions. These compliance requirements add costs, influencing market access and product differentiation.
Pricing Analysis
Contract-based pricing governs large-volume B2B installations for hospitality projects, while per-unit transactional models dominate residential sales channels. Price differentiation stems from proprietary display technologies like MicroLED and comprehensive after-sales service bundles for commercial clients. Pricing softness arises from the narrowing price gap with flat-panel alternatives, particularly for 4K resolution models. Mainstream residential consumers exhibit high price sensitivity, contrasting with the lower sensitivity of luxury residential and high-end hospitality buyers.
Supply Chain Analysis
Upstream feedstock for curved televisions draws heavily from specialized display panel components, including delicate OLED substrates and advanced MicroLED arrays. South Korea and China concentrate significant display manufacturing capabilities for these critical inputs. A primary supply chain risk involves the logistical complexity of shipping fragile, non-stackable large curved screens, increasing transit damage potential. Downstream distribution runs through established global retail networks for residential sales and specialized B2B integrators for hospitality and commercial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
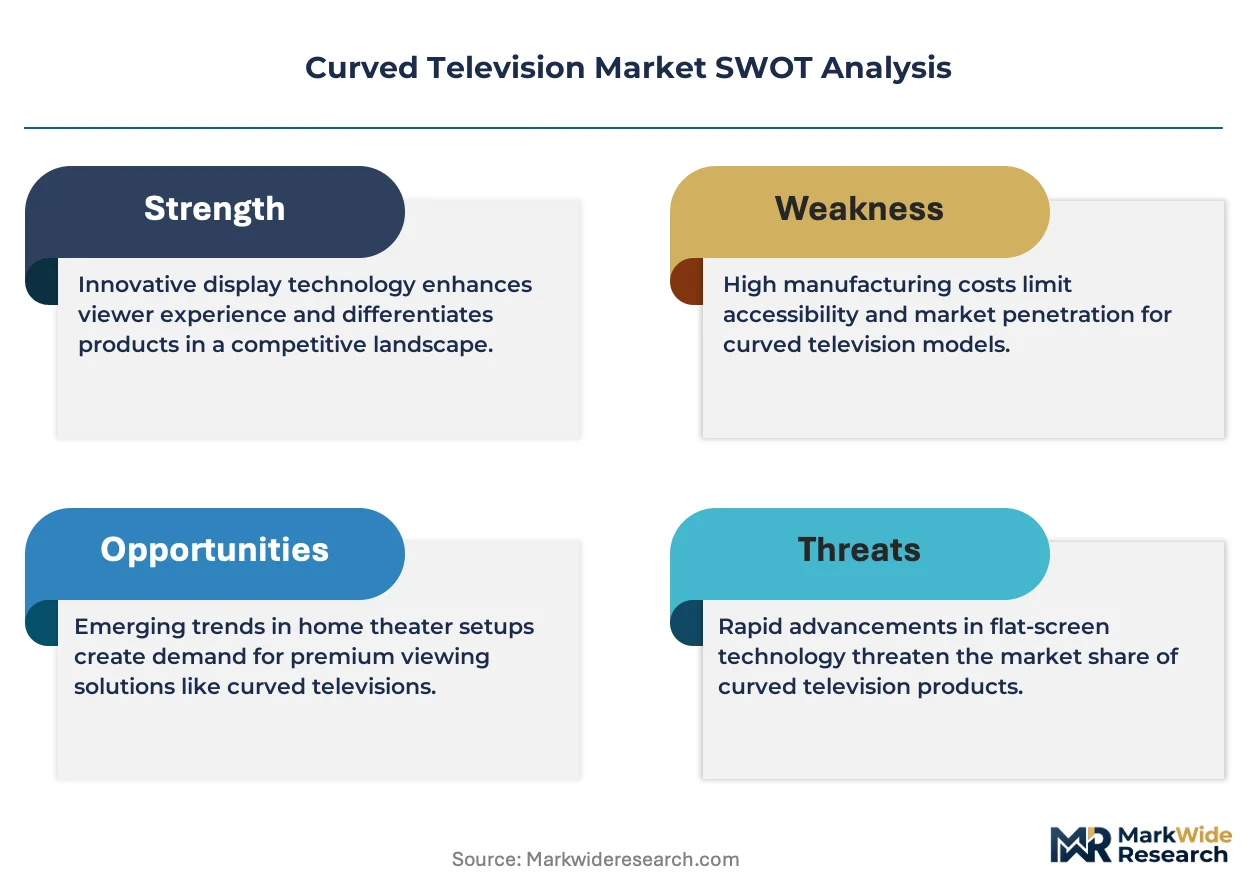
The curved television market requires a robust substitution defense against increasingly competitive flat-panel displays. Incumbents must navigate the narrowing price gap and evolving consumer preferences to maintain market share.
For Market Incumbents: Pre-empt further market share erosion by intensifying R&D into next-generation MicroLED curved displays. Deepen vertical integration in OLED panel production to control costs and enhance product differentiation against flat-panel substitution. Focus on the luxury residential and high-end hospitality segments, leveraging premium aesthetics and immersive experiences. This strategy defends against the pricing pressure from mainstream flat-panel competitors and value-oriented Chinese manufacturers.
For New Entrants and Emerging Players: High-end PC gaming setups and professional simulation systems represent highly penetrable white-space opportunities for curved displays. Developing smart home-integrated curved displays with transparent information overlays offers another distinct value proposition beyond media consumption. Market entry can focus on specific B2B channels, emphasizing functional advantages like immersive field of view for niche applications. Target affluent markets like the UAE and Saudi Arabia for luxury residential projects.
For Investors and Strategic Acquirers: The market sits at a maturing phase that favors specialized technology providers with strong intellectual property in next-generation display technologies. Long-term viability over the next 5-10 years depends on sustained demand from premium segments and B2B applications. Acquisition targets should include firms with advanced MicroLED fabrication capabilities or established distribution in luxury residential markets. Watch for significant breakthroughs in MicroLED production efficiency as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in MicroLED R&D | Accelerates development of thinner, more vibrant curved screens for premium home theater segments. |
| Expand Hospitality Sector Partnerships | Secures stable B2B demand by installing curved televisions in luxury hotel suites and lounges. |
| Enhance Smart Home Integration | Creates new value propositions by developing curved displays as interactive smart home hubs compatible with Google Home. |
| Target Gaming and Simulation Niches | Captures high-margin demand from PC gaming and professional simulation systems seeking immersive viewing fields. |
| Strengthen Supply Chain Compliance | Ensures market access in Europe by adhering to RoHS directives for material use and Ecodesign for energy efficiency. |
Research Approach
The analysis maps OLED, QLED, and MicroLED sub-sectors alongside residential and hospitality end-user applications, each validated through primary interviews with display panel manufacturing executives and smart home integrators. Secondary data from SEC filings, display industry association reports, and government trade statistics provided market context. This approach combined bottom-up data collection with top-down market sizing, ensuring robust data triangulation.
Economic stability and technological progression in display manufacturing were held fixed across the analysis window, while consumer disposable income and B2B investment varied. The analytical framework modeled market dynamics across product type, screen size, resolution, end-user, and regional regulatory adherence. Compound annual growth rates were derived from historical adoption trends and projected technology diffusion. Key forecast inputs included MicroLED production cost curves and global smart home device penetration rates.
Practitioners should monitor geopolitical trade policies and advancements in competing display technologies for early signals of market shifts. Forecasts reflect current assumptions, but supply chain disruptions or rapid shifts in consumer preferences could revise projections. Cross-checking against external market intelligence reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Television Services Market
Television
HDTV Market
Television
TV Advertising Market
Television
Holographic TV Market
Television
Cloud Television (TV) Market
Television
Pay TV Market
Television
Television Advertising Market
Television
Mobile TV Market
Television
Television and Set Top Box Market
Television
Print Newspapers and Magazines Market
Television
Pay TV Operator Market
Television
Traditional TV and Home Video Market
Television
Digital TV Market
Television
Television Market
Television
Broadcasting and Cable TV Market
Television
Cable Television Networks Market