
 Global Broadcast Equipment Market | 2026-2036
Global Broadcast Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Broadcast Equipment Market Intelligence
Multi-source procurement for core broadcast infrastructure is shifting toward vertically integrated technology stacks. Harmonic Inc. anchors its position through in-house video delivery systems and software-defined platforms. Sony Corporation dominates professional camera and switcher manufacturing with proprietary imaging sensors. Cisco Systems leverages networking hardware to control IP-based broadcast workflows across major television networks.
Broadcast equipment encompasses the integrated hardware and software systems used to capture, process, transmit, and distribute audiovisual content to mass audiences, operating across radio frequency bands from VHF through microwave and satellite links with signal latency requirements typically below 40 milliseconds for live production. Cameras and switchers command the largest product-type revenue pools due to perpetual refresh cycles in studio and field production environments. IP-based and cloud broadcast technologies represent the fastest-expanding technology segments as media organizations retire baseband SDI routing in favor of packet-switched infrastructure. Live sports applications generate disproportionate capital expenditure compared to other application categories because of multi-camera synchronization demands and real-time graphics integration requirements.
The Federal Communications Commission in the United States mandates spectrum repacking and ATSC 3.0 next-generation broadcast standards, forcing transmitter and encoder upgrades across local television stations. The European Union's Electronic Communications Code harmonizes cross-border media distribution rules while REACH restricts hazardous substances in broadcast hardware manufacturing. China's National Radio and Television Administration enforces domestic encryption and transmission protocols that shape product certification requirements for foreign suppliers. Stakeholders must monitor regulatory divergence between IP-native standards and legacy broadcast compliance frameworks when allocating R&D budgets across geographic markets.
Market Dynamics
The migration from SDI baseband to IP packet-switched infrastructure constitutes the dominant structural force reshaping capital allocation across broadcast equipment procurement cycles.
Growth Catalysts
- ATSC 3.0 mandates:The Federal Communications Commission's spectrum repacking and next-generation broadcast standard adoption compels transmitter and encoder replacements across United States local television stations.
- Live sports production intensity:Multi-camera synchronization requirements and real-time graphics integration for major sporting events drive disproportionate capital expenditure in camera and switcher categories.
- Cloud-native workflows:Media organizations in Germany and China are retiring on-premise hardware stacks in favor of software-defined platforms that reduce physical infrastructure footprints.
Market Restraints
- Semiconductor supply concentration:Proprietary imaging sensors and broadcast-grade processing chips depend on concentrated East Asian foundry capacity, creating input volatility for camera manufacturers.
- Legacy SDI sunk costs:Existing baseband routing investments in established television networks create technical friction against full IP migration timelines.
- Regulatory fragmentation:China's National Radio and Television Administration enforces domestic encryption protocols that complicate certification pathways for foreign encoder and transmitter suppliers.
Strategic Opportunities
- Remote production expansion:Distributed production models using IP connectivity enable broadcasters to cover events with reduced on-site crew footprints, opening cost-efficient coverage of secondary sports and regional news.
- India's terrestrial digitization:The country's national broadcast regulator continues analog switch-off mandates that accelerate transmitter and set-top box demand across South Asian markets.
- AI-driven content automation:Machine learning integration with switcher and graphics systems enables automated highlight generation and personalized ad insertion for streaming platforms.
Industry Challenges
- IP networking expertise scarcity:Broadcast engineering teams require retraining in packet-switched network architecture and multicast configuration, extending deployment timelines for hybrid SDI-IP facilities.
- Interoperability certification complexity:The Society of Motion Picture and Television Engineers' ST 2110 suite and proprietary vendor implementations create integration testing burdens for multi-supplier installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Broadcast Equipment Market |
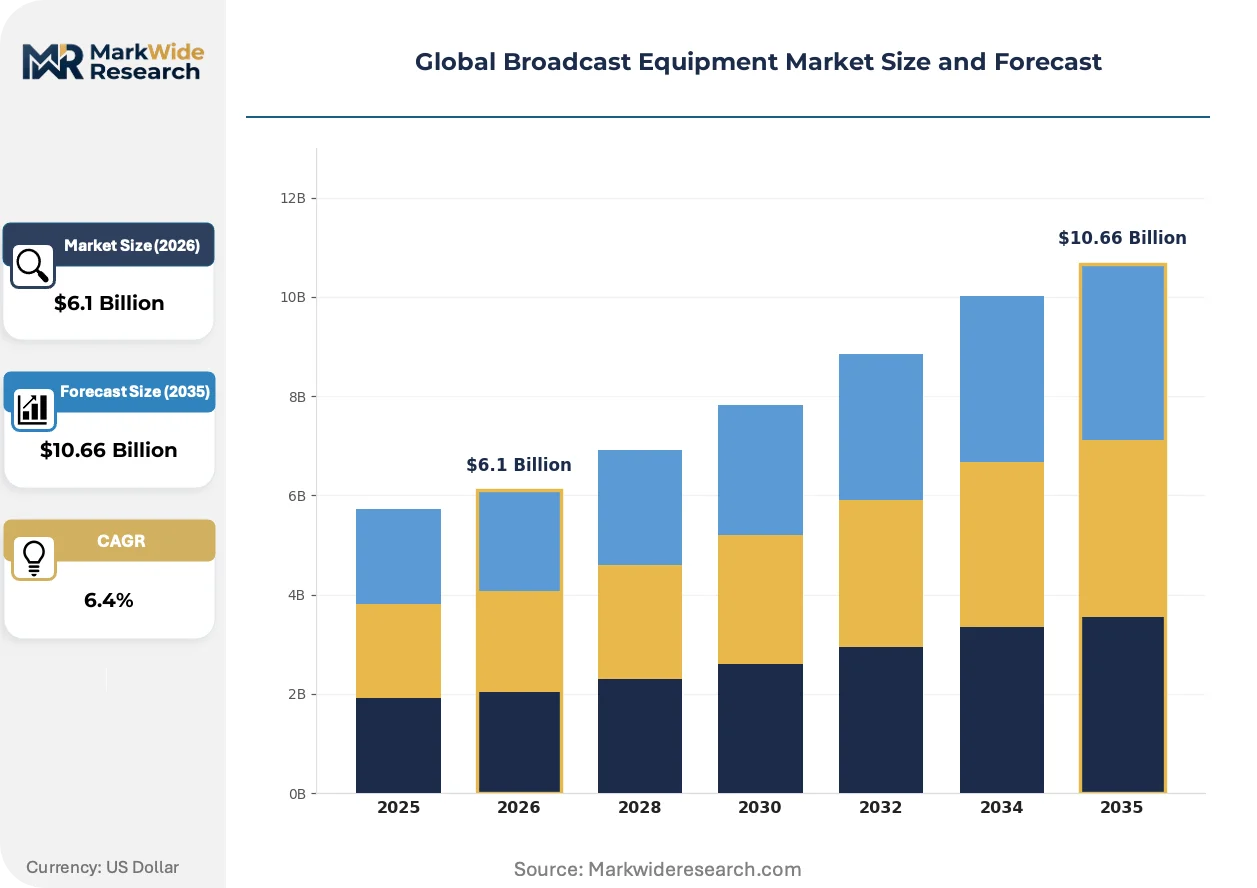
| Market Size in 2026 | $6.1 Billion |
| Market Size in 2035 | $10.66 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmitters, Mixers, Encoders, Cameras, Switchers, Audio Processors Technology: HD, 4K UHD, IP-based, Cloud Broadcast, SDR, HDR Application: Live Sports, News Broadcasting, Entertainment Shows, Educational Programs, Corporate Communications, Religious Broadcasts End User: Television Networks, Cable Operators, OTT Service Providers, Production Studios, Educational Institutions |
| Companies Covered | Harmonic Inc., EVS Broadcast Equipment, CommScope, Telefonaktiebolaget LM Ericsson, Global Invacom Group Limited, Cisco Systems, Grass Valley, Sony Corporation, Evertz Microsystems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Broadcast Equipment Market Strategic Shifts & Innovations
Software-defined architectures and edge computing distribution are compressing traditional hardware refresh cycles while enabling new consumption models across broadcast value chains.
IP-based production infrastructures are integrating studio and field operations through standardized packet transport protocols. Major sports networks in the United States and Germany are deploying these systems for live event coverage. This convergence is integrating audio, video, and metadata into unified workflows that collapse previously separate engineering silos.
REACH restrictions on hazardous substances in electronic equipment manufacturing are tightening material compliance requirements for broadcast hardware producers. The European Chemicals Agency's substance candidate list now captures additional flame retardants and plasticizers used in cable assemblies and enclosure materials. Encoder and camera manufacturers serving European broadcasters are reformulating supply chains to maintain market access.
Subscription-based equipment access models are displacing traditional capital purchase arrangements for regional broadcasters and emerging streaming operators. Managed service providers in the United Kingdom and Nordic markets now bundle switcher, encoder, and transmission capacity as operational expenditures. This shift concentrates purchasing influence among fewer integrators while extending vendor-customer relationships across multi-year service terms.
Global Broadcast Equipment Market Segmentation
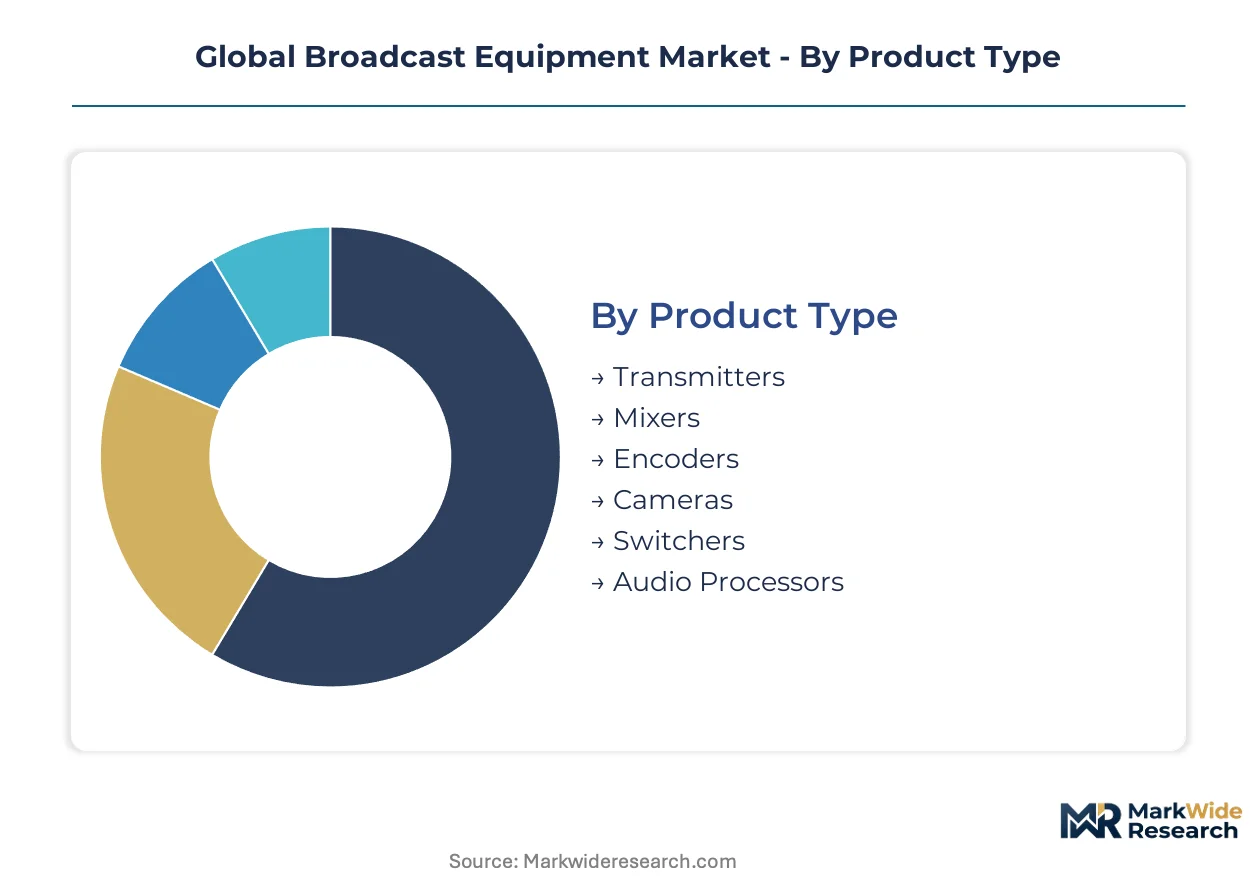
Equipment segmentation in broadcast infrastructure reveals how capital allocation priorities diverge between premium live production environments and cost-optimized distribution networks. Procurement patterns track closely against content monetization intensity, with sports and news commanding specialized hardware configurations distinct from general entertainment workflows.
Product Type:
Customization intensity spans from commoditized transmission hardware to precision-engineered imaging systems requiring sensor-level proprietary differentiation.
- Cameras:Professional imaging systems integrate proprietary CMOS sensors with broadcast-specific color science and multi-format output capabilities. Demand concentrates in United States sports networks and German public broadcasters modernizing studio infrastructure for UHD production.
- Switchers:Hardware and software platforms manage real-time video source selection, effects processing, and graphics integration with sub-frame latency requirements. Live sports production in China and the United States drives disproportionate capital allocation for multi-camera synchronization capabilities.
- Transmitters:RF amplification systems for terrestrial and satellite signal distribution with power efficiency and spectral compliance specifications.
- Mixers:Audio signal routing and processing hardware integrating with video workflows for synchronized broadcast output.
- Encoders:Compression systems converting baseband video to distribution-ready formats across ATSC, DVB, and streaming protocols.
- Audio Processors:Loudness management and spatial audio rendering equipment for compliance with regional broadcast standards.
Leading the category by volume: Transmitters. Growing fastest: IP-native switchers and cameras displacing SDI-reliant predecessors.
Technology:
Resolution and infrastructure paradigms segment procurement by production vintage and distribution channel economics.
- IP-based:Packet-switched infrastructure replaces coaxial SDI routing with Ethernet-based signal transport using SMPTE ST 2110 protocols. Television networks in Germany and the United States prioritize these systems for facility-wide integration and remote production flexibility.
- Cloud Broadcast:Software-defined processing and storage delivered via managed service models reduces on-premise hardware footprints. OTT service providers in China and Nordic markets adopt these platforms for elastic capacity scaling during peak viewership events.
- 4K UHD:Ultra-high-definition production formats with expanded color gamut and high dynamic range capabilities for premium content tiers.
- HD:Established high-definition standards maintaining dominant installed base across regional broadcasters with constrained upgrade budgets.
- HDR:High dynamic range imaging technologies extending luminance range for enhanced visual fidelity in compatible displays.
- SDR:Standard dynamic range legacy formats persisting in downstream distribution chains and cost-sensitive production environments.
Volume concentration: HD infrastructure. Steepest expansion trajectory: Cloud Broadcast and IP-based systems.
Application:
Content genre determines synchronization complexity, graphics integration depth, and redundancy requirements across production workflows.
- Live Sports:Multi-camera coverage with real-time replay, augmented graphics, and low-latency distribution demands the most capital-intensive equipment configurations. United States broadcasters and Chinese streaming platforms allocate disproportionate budgets for these productions.
- News Broadcasting:Rapid turnaround production with automated studio systems and field connectivity requirements drives investment in portable IP workflows and centralized control systems.
- Entertainment Shows:Scripted and unscripted programming with post-production flexibility permits less stringent real-time hardware specifications.
- Corporate Communications:Internal broadcast and event streaming with moderated quality requirements and cost-optimized procurement patterns.
- Educational Programs:Institutional content production with emphasis on accessibility compliance and multi-platform distribution.
- Religious Broadcasts:Specialized production for faith-based networks with dedicated transmission infrastructure and community-focused distribution.
Revenue leadership: Live Sports. Fastest equipment refresh cycles: News Broadcasting.
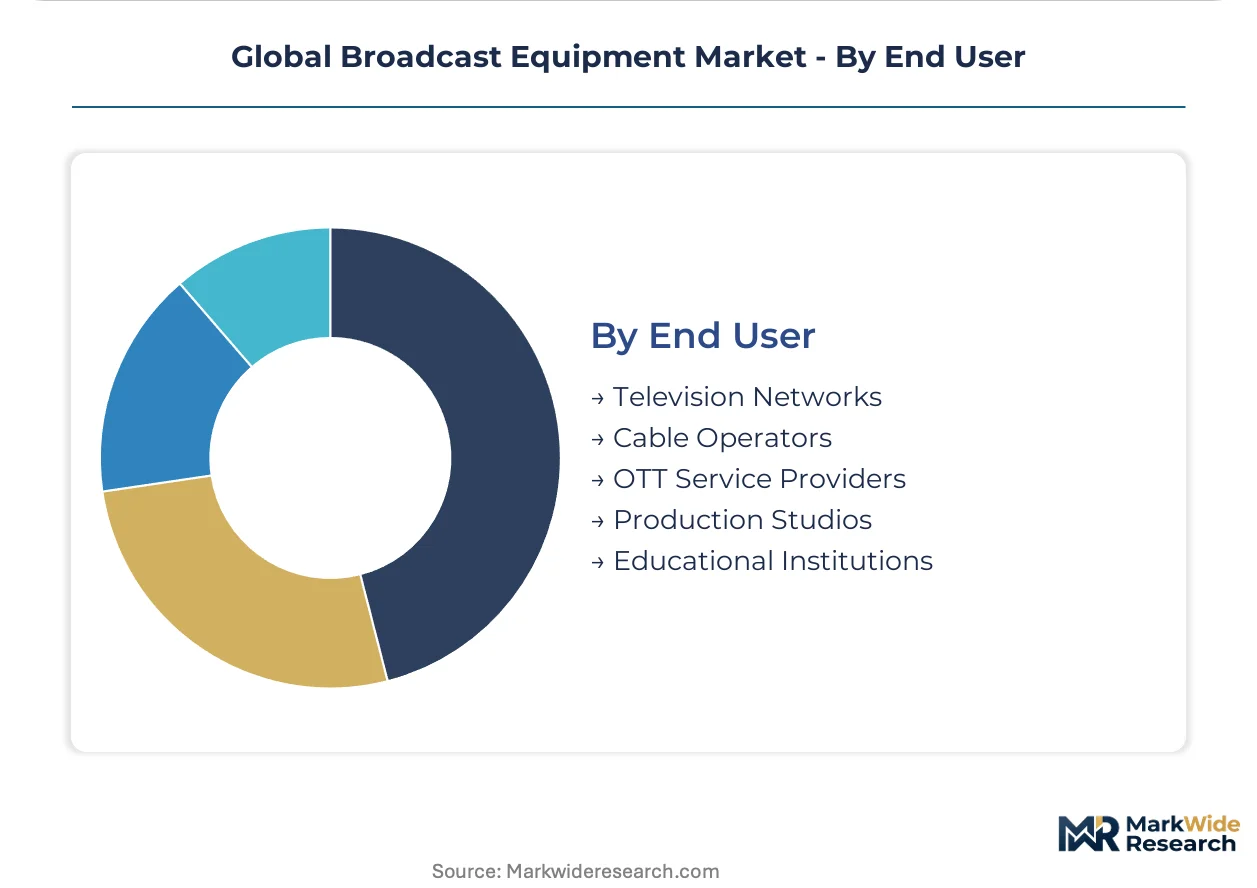
End User:
Customer scale and business model differentiation shape procurement authority and vendor relationship structures.
- Television Networks:National and regional broadcasters with legacy infrastructure investments and regulatory compliance obligations driving systematic upgrade cycles. FCC mandates in the United States and NRTA protocols in China structure their capital planning.
- OTT Service Providers:Streaming-first platforms with cloud-native architectures and elastic capacity requirements distinct from traditional broadcast capital models.
- Cable Operators:Multi-system operators managing hybrid fiber-coaxial networks with headend equipment refresh requirements.
- Production Studios:Independent content creators and facility operators serving multiple client engagements with versatile equipment portfolios.
- Educational Institutions:Universities and training facilities with constrained budgets and instructional rather than commercial production priorities.
Equipment volume: Television Networks. Procurement innovation: OTT Service Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication clusters in Taiwan and South Korea supply the imaging sensors and processing chips that anchor broadcast equipment manufacturing. These upstream inputs concentrate in East Asian foundries before downstream integration into cameras, switchers, and transmission systems across major consuming markets.
United States
FCC spectrum repacking mandates and ATSC 3.0 next-generation broadcast standards compel transmitter and encoder replacements across local television stations. The Federal Communications Commission enforces strict emission compliance timelines that structure capital expenditure cycles. Los Angeles and New York media clusters drive premium camera and switcher procurement for sports network production facilities.
China
Domestic OTT platform expansion and national broadcast infrastructure modernization generate sustained equipment demand from streaming operators and state media. The National Radio and Television Administration enforces domestic encryption protocols that shape certification requirements for foreign suppliers. Beijing and Shanghai production hubs concentrate cloud-native workflow adoption and IP-based facility upgrades.
Germany
Public broadcaster UHD studio modernization and commercial sports network remote production investments sustain premium equipment procurement. REACH restrictions on hazardous substances in electronic equipment manufacturing tighten material compliance requirements for hardware producers. Bavaria and North Rhine-Westphalia host major broadcast technology engineering centers and systems integration facilities.
India
National terrestrial digitization mandates accelerate transmitter and set-top box demand across analog switch-off schedules. The Telecom Regulatory Authority of India structures licensing frameworks for broadcast distribution networks. Maharashtra and Karnataka clusters concentrate regional broadcaster facility upgrades and emerging streaming operator infrastructure deployment.
Japan
Professional imaging sensor manufacturing and broadcast-specific semiconductor design sustain upstream component supply to global equipment vendors. METI industrial standards guide domestic broadcast technology development and export certification protocols. Tokyo and Osaka metropolitan areas concentrate broadcast engineering R&D and precision manufacturing of camera subsystems.
Global Broadcast Equipment Market Key Industry Players
Global majors compete with regional champions across technology integration depth and geographic service proximity. The vendor base organizes into three tiers: diversified electronics conglomerates with captive broadcast divisions, specialized broadcast technology pure-plays, and regional systems integrators with managed service capabilities. Strategic differentiation centers on software-defined platform development and multi-year service contract structures.
Within the diversified technology tier, Sony Corporation exemplifies upstream imaging sensor control integrated with downstream professional camera manufacturing. Harmonic Inc. and Cisco Systems occupy positions spanning video delivery infrastructure and IP networking hardware for broadcast workflow migration. These three anchors represent distinct competitive vectors: proprietary sensor technology, software-defined video processing, and enterprise networking integration.
| Leading Market Players |
|---|
| Harmonic Inc. |
| EVS Broadcast Equipment |
| CommScope |
| Telefonaktiebolaget LM Ericsson |
| Global Invacom Group Limited |
| Cisco Systems |
| Grass Valley |
| Sony Corporation |
| Evertz Microsystems |
| Others |
Cost & Logistics Intelligence
REACH restrictions on hazardous substances in electronic equipment manufacturing gate qualified supplier status and premium-tier pricing access for broadcast hardware producers serving European markets. The European Chemicals Agency's substance candidate list captures additional flame retardants and plasticizers used in cable assemblies and enclosure materials, forcing encoder and camera manufacturers to reformulate supply chains or forfeit market access.
Pricing Analysis
Warranty and multi-year service bundling separate premium-tier vendors from transactional equipment suppliers in broadcast infrastructure procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales support depth. Cost compression in the economy tier is intensifying because regional broadcasters in India and Southeast Asia prioritize capital expenditure minimization over feature depth. OTT service providers exhibit the lowest price sensitivity due to elastic capacity requirements and software-defined architecture preferences.
Supply Chain Analysis
China's domestic encryption protocol requirements and India's phased manufacturing program reshape sourcing strategies for foreign encoder and transmitter suppliers. Imaging sensors and broadcast-grade processing chips draw from concentrated foundry capacity in Taiwan and South Korea. Proprietary CMOS sensors, RF amplification modules, and precision-machined enclosure materials constitute critical input dependencies. Single-source vulnerability in advanced semiconductor nodes threatens equipment delivery timelines. Distribution runs through systems integrators and managed service providers rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Broadcast equipment supply remains constrained by advanced semiconductor foundry capacity, propping pricing power for vendors with secured wafer allocations. This bottleneck justifies sustained premium positioning for qualified suppliers.
For Market Incumbents: Anchor market position through captive imaging sensor supply and in-house software-defined platform development. Sony Corporation's proprietary CMOS sensor control exemplifies defensive moat construction against modular competitors. Counter cloud-native entrants by embedding hardware-software integration depth that pure software vendors cannot replicate. Prioritize certification investment in China's NRTA domestic encryption protocols to maintain access against local champions. For New Entrants and Emerging Players: AI-driven content automation tools offer technology-first wedge opportunity against legacy switcher and graphics incumbents. Regional news broadcasters in India and Southeast Asia present the most penetrable segment due to constrained upgrade budgets and openness to disruptive pricing. Pursue subscription-based equipment access models that convert capital expenditure to operational expenditure, aligning with emerging streaming operator preferences. For Investors and Strategic Acquirers: FCC spectrum repacking completion is the leading indicator that transmitter and encoder replacement cycles will normalize, shifting vendor mix toward IP-native and cloud-capable suppliers. Long-term viability favors software-defined platform specialists with recurring revenue streams over hardware-centric legacy players. Target acquisition candidates with proven ST 2110 interoperability certification and established managed service relationships. Monitor ATSC 3.0 deployment velocity in United States local television stations as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Platform Development | Harmonic Inc. and Cisco Systems compete through video delivery infrastructure unification. |
| Proprietary Sensor Technology Investment | Sony Corporation controls upstream imaging supply for professional camera manufacturing. |
| Managed Service Model Transition | United Kingdom and Nordic integrators bundle switcher capacity as multi-year operational expenditure. |
| Remote Production Infrastructure Deployment | German sports networks reduce on-site crew footprints through IP connectivity expansion. |
| Regulatory Certification Acceleration | NRTA domestic encryption compliance determines market access for foreign encoder suppliers in China. |
Research Approach
Trade association filings, customs and import records, and SEC 10-K disclosures formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with broadcast engineering directors, television network procurement officers, OTT platform technology leads, and systems integration specialists validated demand assumptions and technology adoption timelines. Bottom-up equipment shipment analysis and top-down broadcaster capital expenditure triangulation anchored volume and value estimates.
Historical trendline analysis across camera, switcher, transmitter, and encoder categories established baseline growth patterns before forward projection. The analytical framework modeled product type, technology paradigm, application intensity, and end-user business model across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. ATSC 3.0 mandate compliance timelines and cloud-native workflow adoption curves constituted broadcast-specific forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen regulatory acceleration or delay, semiconductor supply disruption severity, and macroeconomic capital expenditure contraction. Forecasts reflect documented assumptions regarding technology substitution rates and geographic adoption patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Cable Television Networks Market
Television
Print Newspapers and Magazines Market
Television
Mobile TV Market
Television
Holographic TV Market
Television
Pay TV Operator Market
Television
Cloud TV Market
Television
Television Advertising Market
Television
Curved Television Market
Television
Pay TV Services Market
Television
Television Services Market
Television
Television and Set Top Box Market
Television
Global Digital Terrestrial Television Market
Television
Digital TV Market
Television
HDTV Market
Television
Television Broadcasting Services Market
Television
Free-To-Air (FTA) Service Market