
 Middle East Marketing and Advertising Agency Market | 2026-2036
Middle East Marketing and Advertising Agency Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Marketing and Advertising Agency Market Insights
UAE corporate sustainability disclosure requirements under the Dubai Supreme Council of Energy's green economy directives is consolidating procurement standards for agency partners serving state-linked enterprises. Impact BBDO leverages its Beirut-Dubai creative hub to anchor pan-Arab campaigns for regional FMCG clients. FP7 McCann competes through specialized healthcare storytelling capabilities across Gulf markets. Multiply Group PJSC controls Out-of-Home inventory via BackLite Media LLC, extending its influence over programmatic digital-out-of-home placement in premium Dubai locations.
Marketing and advertising agencies in the Middle East combine strategic communications planning, creative content production, media buying, and performance analytics to build brand equity and drive commercial outcomes for clients. These operations rely on multilingual talent pools, real-time data infrastructure, and compliance with local content censorship frameworks across jurisdictions. Digital Marketing services capture expanding budgets as platform algorithms demand continuous optimization, while Traditional Advertising retains scale through government and luxury sector spend. The Outsourced delivery model dominates among international brands seeking local expertise, though Hybrid arrangements are gaining traction as corporates build in-house analytics capabilities.
SFDA in Saudi Arabia regulates health claims in pharmaceutical advertising, tightening approval timelines for agency-produced medical content. The UAE's National Media Council content standards and Dubai's TECOM free-zone licensing framework shape operational requirements for creative firms. Egypt's Supreme Council for Media Regulation imposes localization quotas on imported advertising concepts. Stakeholders must monitor evolving data localization mandates and talent mobility agreements as Gulf states compete to attract creative professionals.
Market Dynamics
Gulf state content localization mandates and sovereign wealth entertainment investments are restructuring how agencies secure long-term retainers and talent pipelines.
Growth Catalysts
- Saudi Vision 2030 Cultural Mandates:Sovereign entertainment and tourism projects require integrated Arabic creative production, expanding agency scope beyond traditional media buying into experiential and content services.
- UAE Media Free-Zone Incentives:TECOM licensing frameworks attract multinational agency hubs, concentrating pan-Arab campaign production capacity in Dubai production facilities.
- Programmatic Digital-Out-of-Home:Data-driven placement technology enables real-time audience targeting across premium Dubai retail and transit inventory, capturing reallocated television budgets.
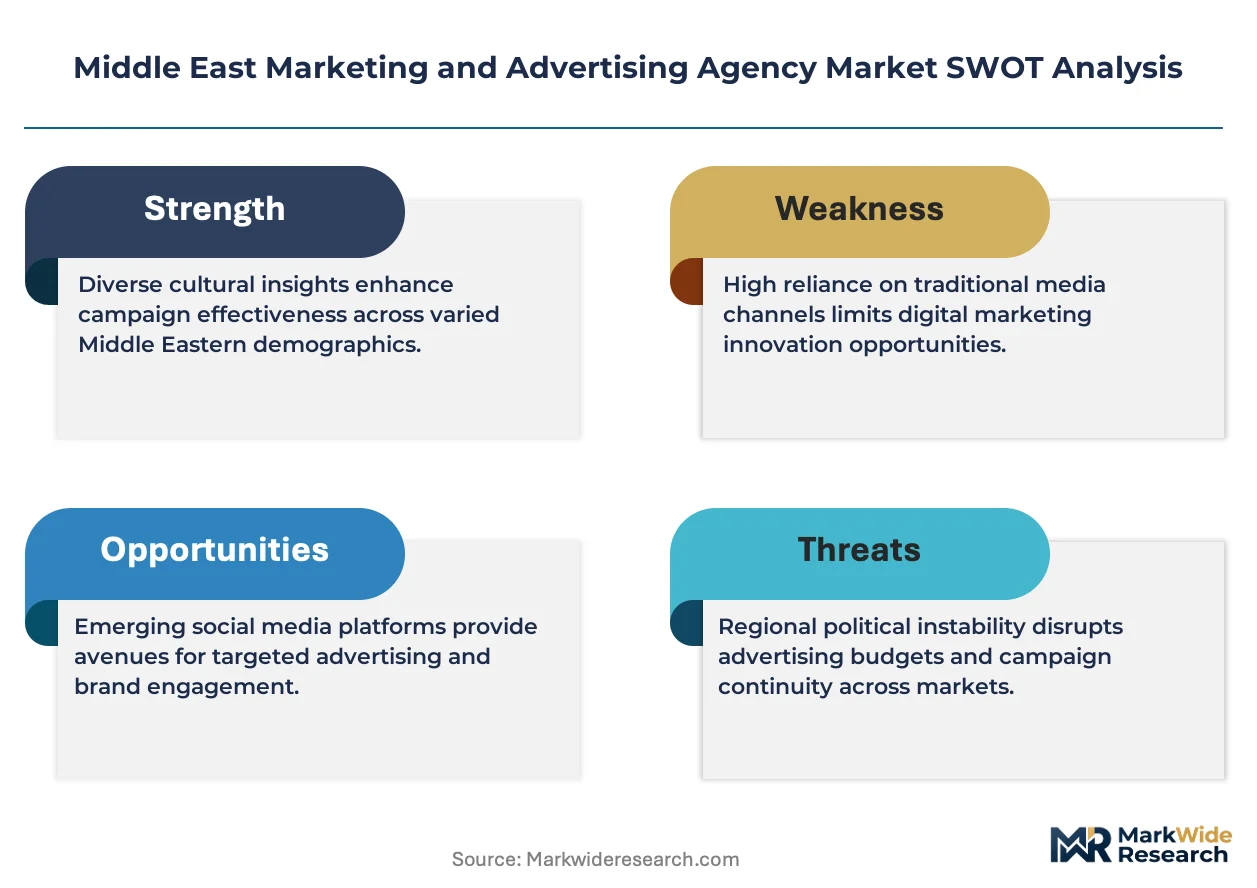
Market Restraints
- Multilingual Talent Scarcity:Shortage of Arabic-English creative directors and performance marketing specialists inflates compensation costs across Gulf agency clusters.
- Content Censorship Fragmentation:Divergent standards between Saudi SFDA health claims rules, UAE National Media Council guidelines, and Egyptian Supreme Council for Media Regulation localization quotas multiply compliance overhead.
- State-Linked Client Concentration:Heavy dependence on sovereign wealth-funded entertainment and tourism projects creates payment cycle volatility and procurement negotiation asymmetry.
Strategic Opportunities
- Egypt Production Cost Arbitrage:Cairo-based creative and post-production facilities offer 40-60% cost advantages for Arabic content adaptation serving Gulf markets.
- Healthcare Storytelling Specialization:SFDA regulatory complexity creates defensible expertise moats for agencies building pharmaceutical and medical device approval capabilities.
- In-House Analytics Hybrid Models:Corporates building internal data science teams seek agency partners for creative execution rather than full-service retainers, opening project-based revenue streams.
Industry Challenges
- Data Localization Compliance:Evolving Gulf state mandates restricting cross-border consumer data transfer force infrastructure duplication across Saudi, UAE, and Egyptian server deployments.
- Platform Algorithm Volatility:Continuous optimization demands for Meta, TikTok, and Snap advertising systems exhaust specialist talent and compress campaign planning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Marketing and Advertising Agency Market |
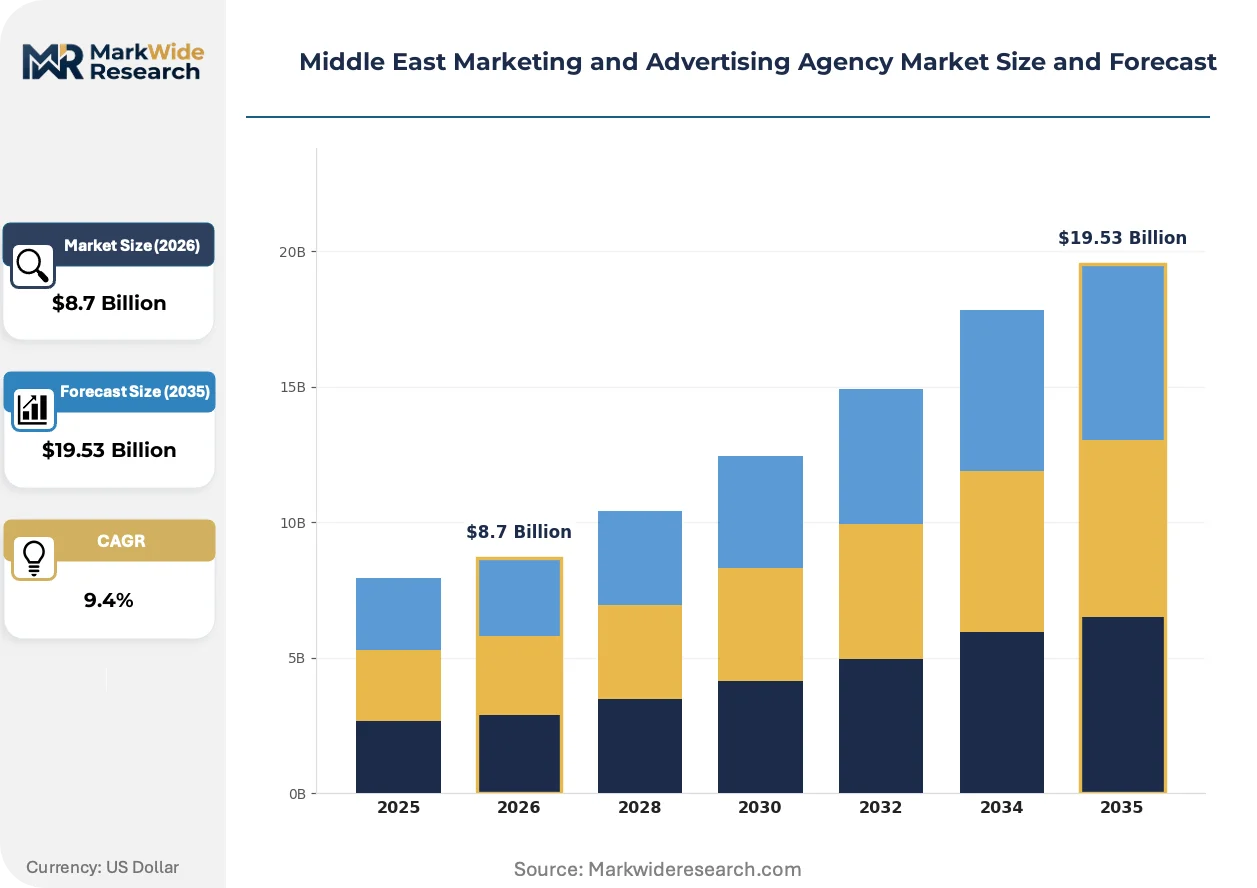
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Digital Marketing, Traditional Advertising, Social Media Management, Public Relations Client Type: SMEs, Corporates, NGOs, Startups Industry Vertical: Retail, Automotive, Healthcare, Education Delivery Model: In-house, Outsourced, Hybrid, Freelance |
| Companies Covered | Omnicom Group Inc. (TBWA\RAAD), Impact BBDO, FP7 McCann, Memac Ogilvy, Multiply Group PJSC (BackLite Media LLC), Tonic International, Dooha Media, Mars Media Group, Bates Pan Gulf, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Marketing and Advertising Agency Market Trends and Innovations
Generative artificial intelligence and immersive production technologies are compressing creative development cycles while Gulf regulatory fragmentation forces specialized compliance infrastructure investments.
AI-powered content generation tools are modularizing creative production workflows across Arabic-language adaptation, visual asset variation, and personalized video assembly. Mid-sized agencies serving Saudi retail and UAE real estate clients deploy these systems to reduce concept-to-delivery timelines from weeks to days. The technology is modularizing traditional art department hierarchies, enabling smaller teams to pitch competitive scope against established network agencies.
UAE green economy disclosure requirements under Dubai Supreme Council of Energy directives now mandate sustainability reporting for state-linked enterprise procurement. Agency partners must document carbon footprint methodologies and supply chain environmental credentials to retain government and quasi-sovereign client contracts. Creative firms serving Emirates airline, Emaar, and DEWA-linked accounts invest in carbon calculation platforms and third-party verification to maintain eligibility.
Brand procurement teams increasingly unbundle media buying from creative strategy, awarding separate contracts to specialized shops rather than integrated network retainers. Saudi Aramco, NEOM, and Red Sea Project procurement functions now run competitive pitches for creative concepting, production execution, and media placement as distinct workstreams. This pattern concentrates most visibly in Riyadh and Jeddah, where sovereign project marketing budgets exceed individual agency capacity and risk concentration limits drive vendor diversification mandates.
Middle East Marketing and Advertising Agency Market Segmentation
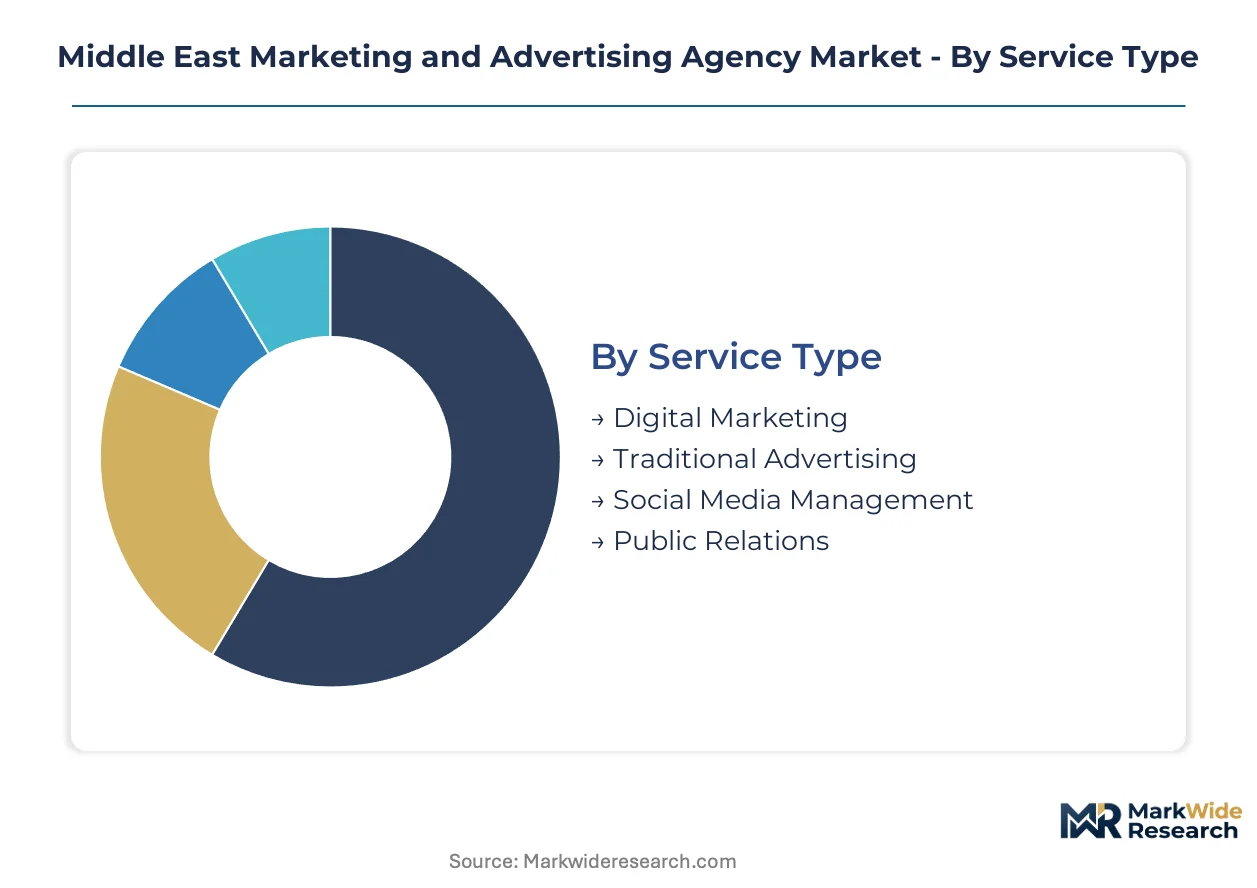
Agency procurement patterns across the Middle East diverge sharply by service complexity and client governance structure. Sovereign wealth-funded projects in Saudi Arabia and the UAE demand integrated capabilities that smaller Egyptian and Lebanese shops cannot replicate, fragmenting competitive dynamics across the value chain.
Service Type:
Digital Marketing commands the steepest talent premiums as platform algorithm volatility exhausts specialist capacity in Dubai and Riyadh. Traditional Advertising retains anchor tenancy through government and luxury sector procurement, while social media and PR functions face unbundling pressure.
- Digital Marketing:Search, programmatic display, and performance analytics services requiring continuous optimization against Meta, TikTok, and Snap algorithm shifts. Demand concentrates among UAE real estate developers and Saudi retail conglomerates seeking measurable conversion metrics. SFDA health claims rules and UAE National Media Council content standards multiply compliance overhead for pharmaceutical and medical device campaigns.
- Traditional Advertising:Television, print, radio, and static out-of-home production retains scale through sovereign wealth-funded entertainment and tourism projects. Saudi Vision 2030 cultural mandates require Arabic creative adaptation that Cairo-based post-production facilities supply at 40-60% cost advantage.
- Social Media Management:Community management, influencer coordination, and real-time content calendars for platform-native brand presence.
- Public Relations:Strategic communications, crisis management, and stakeholder engagement across multilingual media landscapes.
Today's leader: Digital Marketing. Tomorrow's challenger: Traditional Advertising.
Client Type:
Corporates drive procurement standardization as Dubai Supreme Council of Energy green economy disclosure requirements cascade to agency partners. SME and startup segments fragment across cost-sensitive Beirut and Cairo creative clusters.
- Corporates:Multinational subsidiaries and regional headquarters with formalized vendor qualification, sustainability reporting mandates, and multi-year retainer structures. Procurement teams at Emirates airline, Emaar, and Aramco-linked entities now unbundle creative concepting from media placement.
- SMEs:Mid-sized retailers, professional services firms, and family-owned conglomerates with project-based engagement preferences and price-sensitive RFP processes.
- NGOs:International development organizations and regional foundations requiring Arabic-English bilingual campaign execution.
- Startups:Venture-backed technology and fintech companies with growth-hacking methodologies and performance-based compensation structures.
Corporates anchor current revenue. SMEs are climbing the fastest as Egyptian production cost arbitrage democratizes access.
Industry Vertical:
Healthcare specialization creates defensible expertise moats as SFDA regulatory complexity lengthens approval timelines. Retail and automotive verticals concentrate spend in Dubai and Riyadh production facilities.
- Retail:Fashion, FMCG, and e-commerce clients with seasonal campaign velocity and influencer-dependent launch strategies. Saudi mall operators and UAE luxury distributors dominate regional spend.
- Automotive:OEM brand building and dealer network support across Gulf markets with high per-capita vehicle ownership.
- Healthcare:Pharmaceutical, medical device, and hospital system marketing governed by SFDA health claims validation and MOHAP licensing requirements.
- Education:University enrollment campaigns and edtech platform user acquisition across expatriate and national student segments.
Retail captures dominant share. Healthcare offers the steepest expansion trajectory through regulatory barrier construction.
Delivery Model:
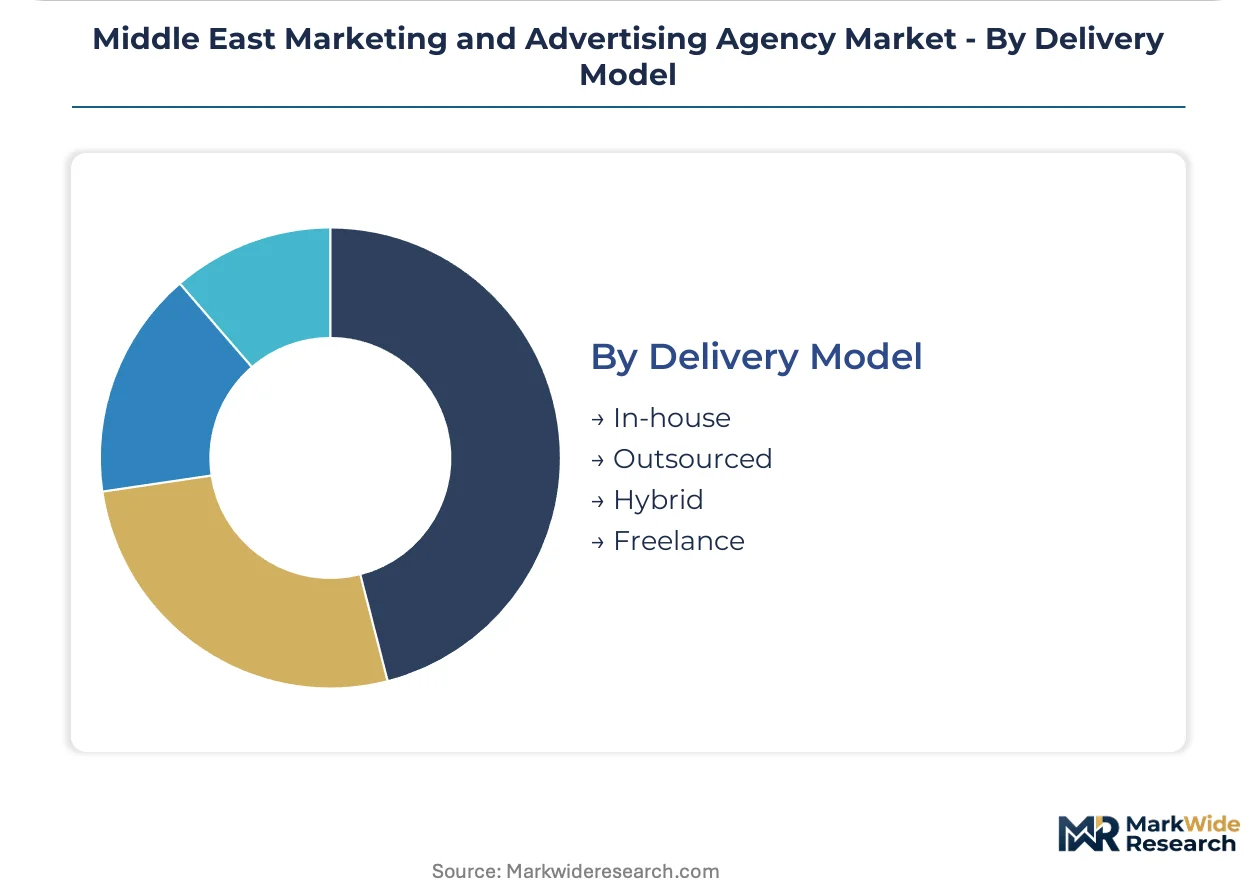
Hybrid arrangements gain traction as corporates build in-house analytics capabilities and retain agencies for creative execution alone. Freelance networks supply surge capacity for project-based sovereign entertainment budgets.
- Outsourced:Full-service agency retainers covering strategy, production, and media buying for international brands seeking localized expertise without dedicated Middle East infrastructure.
- Hybrid:Split accountability models with client-side data science teams and external creative partners, prevalent at NEOM and Red Sea Project procurement functions.
- In-house:Captive agency subsidiaries within holding companies or conglomerates, concentrated among Saudi sovereign wealth-funded entertainment ventures.
- Freelance:Individual specialist networks for Arabic copywriting, video production, and performance marketing optimization.
Outsourced models dominate present contracting. Hybrid structures are gaining share fastest as vendor diversification mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multilingual creative talent clusters in Dubai and Riyadh anchor regional production capacity, with Cairo and Beirut supplying cost-advantaged post-production services. Sovereign wealth-funded entertainment projects concentrate demand in Gulf capitals while regulatory fragmentation shapes operational requirements across jurisdictions.
United Arab Emirates
TECOM free-zone licensing frameworks attract multinational agency hubs to Dubai production facilities. Dubai Supreme Council of Energy green economy disclosure requirements mandate sustainability reporting for state-linked enterprise procurement. DIFC and Dubai Media City clusters concentrate pan-Arab campaign production capacity for regional FMCG and luxury clients.
Saudi Arabia
Sovereign entertainment and tourism projects under Vision 2030 require integrated Arabic creative production at scale. SFDA health claims regulations tighten approval timelines for pharmaceutical and medical device advertising content. Riyadh and Jeddah production facilities serve NEOM and Red Sea Project marketing budgets through hybrid procurement models.
Egypt
Cairo-based creative and post-production facilities offer cost advantages for Arabic content adaptation serving Gulf markets. Supreme Council for Media Regulation localization quotas impose adaptation requirements on imported advertising concepts. Greater Cairo media production clusters supply multilingual talent for regional campaign execution.
Lebanon
Beirut-Dubai creative hub configurations anchor pan-Arab campaign strategy for regional network agencies. Central Bank foreign exchange restrictions compress operational margins for locally-registered creative firms. Beirut production facilities maintain specialized Arabic copywriting and conceptual development capabilities.
Qatar
State-funded sports and entertainment infrastructure drives demand for experiential and content services. Qatar Media Corporation content standards shape operational requirements for creative firms serving sovereign project accounts. Lusail and Doha production clusters support FIFA World Cup legacy programming and hospitality sector marketing.
Middle East Marketing and Advertising Agency Market Competitive Landscape
Capital-heavy media inventory owners compete with asset-light creative boutiques for differentiated positioning in procurement processes. Market structure fragments across network agency retainers, independent creative shops, and technology-enabled production specialists. Three archetypes dominate: integrated network agencies with regulatory compliance infrastructure, independent creative boutiques with cost-advantaged production, and media asset owners with programmatic placement capabilities. Competitive dynamics center on unbundling pressure from procurement functions and vendor diversification mandates at sovereign project accounts.
Within the integrated network tier, Omnicom Group Inc. and Impact BBDO exemplify multinational infrastructure adapted for Gulf regulatory complexity. FP7 McCann occupies a position among healthcare-specialized storytellers building defensible expertise moats through SFDA approval capabilities. Multiply Group PJSC anchors the media-asset owner archetype through BackLite Media LLC inventory control, extending influence over programmatic digital-out-of-home placement in premium Dubai locations.
| Leading Market Players |
|---|
| Omnicom Group Inc. (TBWA\RAAD) |
| Impact BBDO |
| FP7 McCann |
| Memac Ogilvy |
| Multiply Group PJSC (BackLite Media LLC) |
| Tonic International |
| Dooha Media |
| Mars Media Group |
| Bates Pan Gulf |
| Others |
Pricing and Supply Chain Analysis
Arabic-English creative director scarcity in Dubai and Riyadh inflates Gulf labor costs to three times Cairo-based equivalents, widening spreads between premium network retainers and economy-tier production houses serving cost-sensitive SME segments.
Pricing Analysis
Project-based fee structures with outcome-based performance bonuses dominate sovereign wealth-funded entertainment accounts, while subscription retainers anchor multinational corporate relationships. Three-tier pricing separates integrated network agencies from independent boutiques from Egyptian post-production arbitrageurs. Pricing pressure stems from procurement unbundling at NEOM and Red Sea Project accounts fragmenting once-consolidated scopes. SME segments exhibit acute price sensitivity, whereas state-linked enterprises prioritize regulatory compliance infrastructure over rate negotiation.
Supply Chain Analysis
Direct-to-client channels handle sovereign project demand in Riyadh and Dubai, while Cairo and Beirut facilities feed Gulf markets through production outsourcing arrangements. Creative talent concentrates in UAE and Saudi Arabia, with post-production capacity anchored in Egypt and Lebanon. Raw material inputs span multilingual copywriting, video production equipment, and programmatic media inventory. Single-source vulnerability runs through Dubai Media City server infrastructure facing data localization mandates. Distribution runs through hybrid models combining in-house analytics with external creative execution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East marketing and advertising agency market compounds steadily as sovereign entertainment budgets under Vision 2030 and parallel UAE tourism initiatives generate recurring creative services demand with multi-year visibility.
For Market Incumbents: Anchor regulatory compliance capabilities as defensible moats against unbundling pressure from procurement functions at Aramco-linked and NEOM accounts. Deepen SFDA health claims expertise and Dubai Supreme Council of Energy sustainability certification to retain state-linked contracts. Build captive Arabic-English creative director pipelines through TECOM free-zone talent mobility agreements. For New Entrants and Emerging Players: Launch via Cairo-based post-production cost arbitrage serving Gulf market content adaptation demand at 40-60% rate discounts. Target Egyptian SME segments underserved by network agency infrastructure. Penetrate through healthcare storytelling specialization exploiting SFDA approval timeline complexity that incumbents have not fully captured. For Investors and Strategic Acquirers: Valuations sit cheapest among independent creative boutiques with established Cairo production facilities and existing Gulf client relationships. Long-term viability hinges on regulatory compliance infrastructure rather than scale alone. Watch procurement unbundling velocity at sovereign project accounts as inflection indicator for hybrid model adoption rates.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Regulatory Compliance Buildout | Pharmaceutical advertising approval capabilities unlock defensible revenue from Saudi healthcare vertical. |
| Cairo Production Facility Expansion | Cost-advantaged Arabic content adaptation captures unbundled creative execution workstreams from Gulf accounts. |
| Programmatic DOOH Technology Investment | Real-time audience targeting capabilities capture reallocated television budgets in premium Dubai retail locations. |
| In-House Analytics Hybrid Partnership | Creative-only retainers align with NEOM and Red Sea Project vendor diversification mandates. |
| Sustainability Certification Acquisition | Dubai Supreme Council of Energy disclosure compliance maintains eligibility for Emirates and Emaar-linked procurement. |
Research Methodology
Multiple input streams — creative agency executive interviews, procurement officer discussions at sovereign project accounts, and secondary validation — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged creative directors, media buying heads, regulatory affairs specialists at SFDA and UAE National Media Council, and procurement leads at state-linked enterprises. Secondary sources encompassed TECOM licensing disclosures, Dubai Supreme Council of Energy sustainability directives, Egyptian Supreme Council for Media Regulation filings, and customs data on media production equipment imports.
Data-stream reconciliation across the projection horizon modeled service type, client governance structure, industry vertical, and delivery model segmentation dimensions. CAGRs were derived from revenue trajectory analysis against sovereign budget allocation patterns. Forecast inputs incorporated platform algorithm volatility indices and talent mobility agreement expansion rates affecting multilingual creative supply.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated data localization mandates or sudden platform policy shifts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Middle East and Africa Sports Betting Market
Advertising and Marketing Media
Europe Digital OOH Advertising Market
Advertising and Marketing Media
Digital Out of Home (OOH) Advertising Market
Advertising and Marketing Media
Fashion Influencer Marketing Market
Advertising and Marketing Media
Latin America Programmatic Advertising Market
Advertising and Marketing Media
Indonesia Digital Advertising Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
Native Advertising Market
Advertising and Marketing Media
Global Advertising Software Market
Advertising and Marketing Media
Japan OOH and DOOH Market
Advertising and Marketing Media
South East Asia Digital Out-Of-Home (Dooh) Market
Advertising and Marketing Media
Philippines OOH and DOOH Market
Advertising and Marketing Media
South Korea OOH and DOOH Market
Advertising and Marketing Media
GCC OOH and DOOH Market
Advertising and Marketing Media
Chile OOH and DOOH Market
Advertising and Marketing Media
Russia OOH and DOOH Market