
 Broadcasting and Cable TV Market | 2026-2036
Broadcasting and Cable TV Market Size, Share, and Industry Trends Forecast 2026-2036
Broadcasting and Cable TV Market Intelligence
IP-based content delivery is reshaping how video reaches households, replacing legacy RF and coaxial infrastructure with packet-switched distribution. Disney Entertainment leverages its vertically integrated studio-to-streaming pipeline to control programming costs. Comcast Corporation anchors its position through hybrid fiber-coaxial plant upgrades and broadband bundling. Warner Bros. Discovery navigates the transition by consolidating HBO Max and Discovery+ into a unified streaming architecture.
Broadcasting and Cable TV encompasses the production, aggregation, and distribution of audiovisual content via terrestrial transmitters, satellite uplinks, coaxial or fiber networks, and internet protocol streams operating at bitrates from 2 Mbps to 50 Mbps depending on resolution and compression standard. Its primary commercial purpose is to monetize attention through subscription fees, advertising inventory, and content licensing to end users. Linear Broadcasting still generates the largest revenue pool among service types, though Streaming Services represent the fastest-expanding segment as cord-cutting accelerates and addressable advertising improves CPM yields. Over-the-top technology is displacing traditional Digital Terrestrial and Satellite delivery in urban markets where broadband penetration supports 4K and live streaming workloads.
The FCC governs spectrum allocation, local station ownership caps, and must-carry rules that determine which channels reach cable subscribers, while the EU's Audiovisual Media Services Directive shapes content quotas and platform accountability across member states. GDPR and emerging state privacy laws in California and Virginia constrain how viewer data fuels targeted advertising, forcing platform operators to rebuild ad-tech stacks around consent management. Stakeholders must monitor regulatory divergence between Washington and Brussels as data localization and content moderation mandates fragment the addressable market for global streaming platforms.
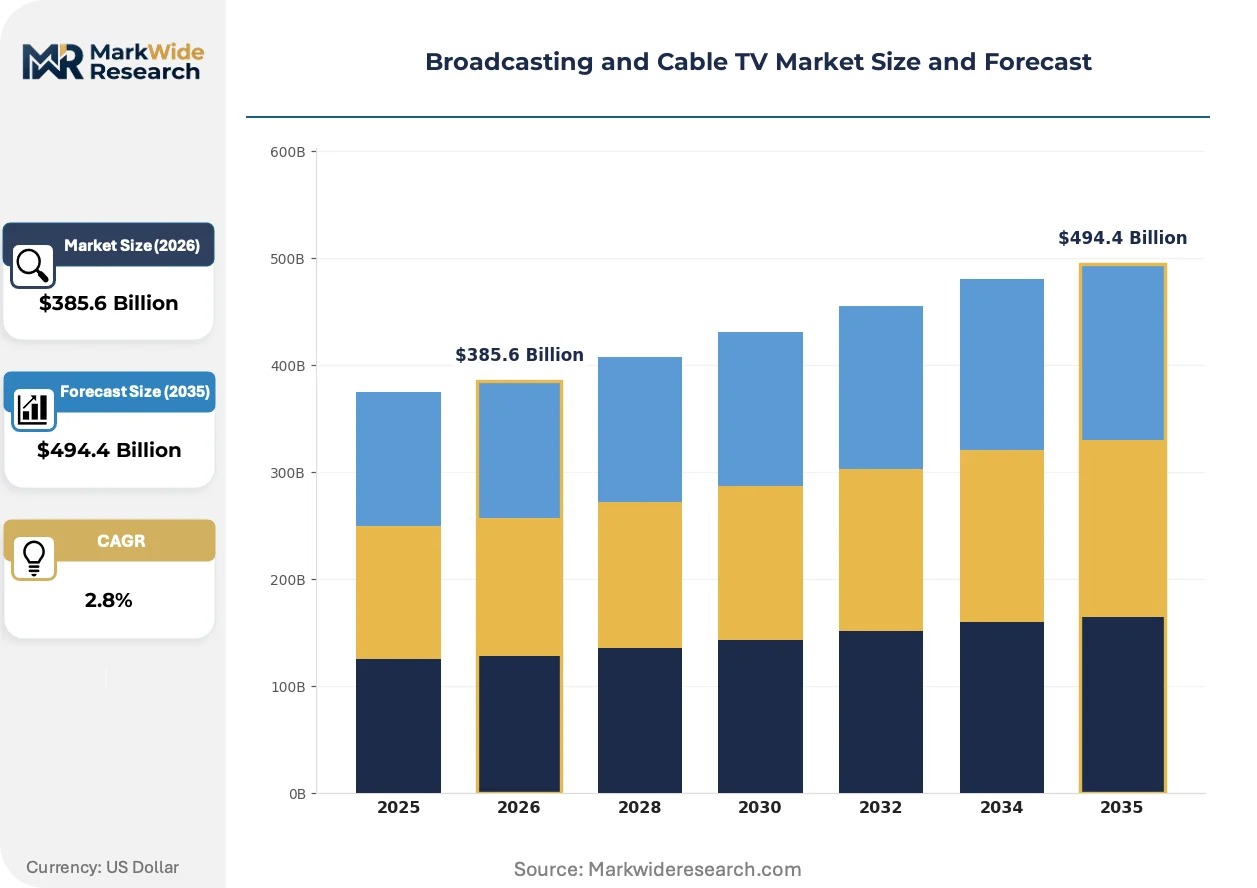
Market Dynamics
IP-based content delivery is compressing legacy distribution economics as broadband infrastructure displaces coaxial and satellite last-mile connectivity, forcing incumbents to rebuild revenue models around streaming subscriptions rather than channel bundles.
Growth Catalysts
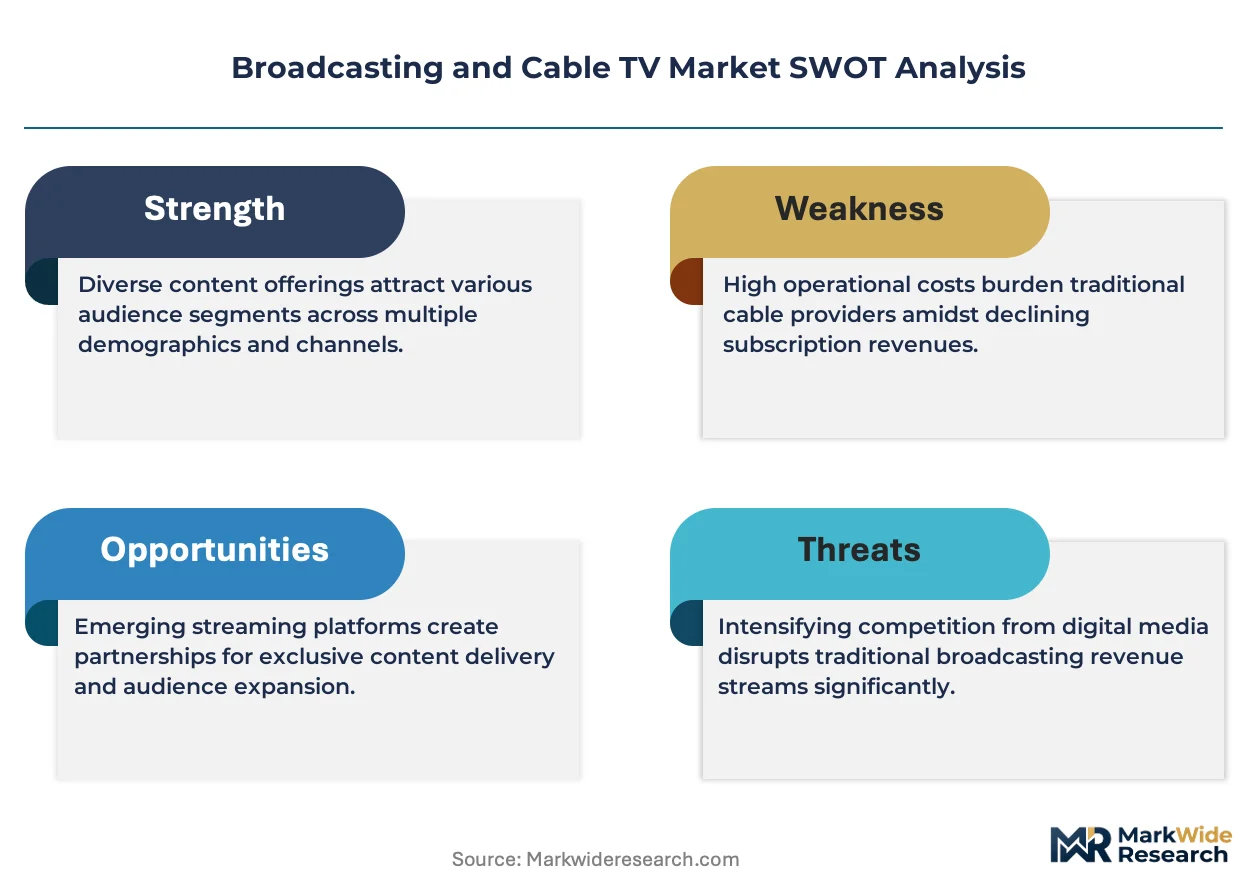
- Retransmission Consent Framework:The FCC's rules enable local broadcast stations to negotiate carriage fees from cable operators, creating a revenue floor for affiliate networks as linear audiences fragment.
- Addressable Advertising Technology:Household-level ad targeting through set-top boxes and connected TVs improves CPM yields for inventory that previously sold on demographic approximations.
- Broadband Penetration Thresholds:Urban and suburban markets where fiber-to-the-home exceeds 80 percent household coverage now support 4K live streaming without buffering degradation.
Market Restraints
- Content Cost Inflation:Exclusive licensing for live sports rights and premium scripted programming requires multi-billion dollar commitments that strain operating margins regardless of subscriber scale.
- Legacy Infrastructure Sunk Costs:Cable operators face stranded asset risk from hybrid fiber-coaxial plant that cannot be fully depreciated before subscriber migration to over-the-top alternatives.
- Spectrum Scarcity Constraints:The FCC's repackaging of UHF broadcast bands for wireless broadband reduces available terrestrial transmission capacity in major metropolitan markets.
Strategic Opportunities
- Rural Broadband Gaps:Unserved and underserved census blocks in the United States present addressable markets for fixed wireless and low-earth-orbit satellite delivery of streaming bundles.
- Advertising Technology Convergence:Integration of programmatic buying platforms with connected TV operating systems enables real-time auction mechanics previously limited to digital display.
- Smart Home Integration:Voice-activated content discovery through Amazon Alexa and Google Assistant ecosystems reduces friction in content selection and subscription management.
Industry Challenges
- Data Privacy Compliance:The California Consumer Privacy Act and Virginia Consumer Data Protection Act impose consent-management burdens on ad-tech stacks that previously operated on implied permission models.
- Interoperability Complexity:Proprietary digital rights management systems across Apple, Google, Roku, and Samsung smart TV platforms fragment technical standards and increase development overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Broadcasting and Cable TV Market |
| Market Size in 2026 | $385.6 Billion |
| Market Size in 2035 | $494.4 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Linear Broadcasting, Video on Demand, Interactive TV, Pay-per-view, Streaming Services Technology: Digital Terrestrial, Satellite, IPTV, Fiber Optic, Over-the-top Application: News Broadcasting, Sports Telecast, Entertainment Shows, Educational Programs, Infotainment Channels End User: Content Providers, Telecommunication Firms, Advertising Agencies, Platform Operators, Media Conglomerates |
| Companies Covered | Paramount Global, Disney Entertainment, Fox Corporation, The Liberty SiriusXM Group, Nexstar Media Group, Comcast Corporation, Warner Bros. Discovery, Sirius XM Holdings, NBCUniversal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Broadcasting and Cable TV Market Strategic Shifts & Innovations
Content monetization is pivoting from mass-audience advertising to precision-targeted subscription tiers and programmatic video commerce, compressing the value capture window for traditional intermediaries.
Cloud-native playout and encoding infrastructure is hybridizing broadcast reliability with internet scalability. Major network groups are migrating master control operations to AWS and Azure instances, reducing capital intensity for channel launches. This architecture is hybridizing the cost structure of linear and streaming operations into unified technical stacks.
The FCC's net neutrality restoration proceedings are creating regulatory uncertainty for internet service providers offering zero-rated streaming bundles. Tiered traffic treatment rules would force disclosure of paid prioritization agreements. Streaming platforms and broadband operators are most affected, with both sides lobbying for favorable interconnection and data cap exemptions.
Household viewing behavior is fragmenting across multiple simultaneous subscriptions with high churn tolerance. Consumers rotate through services monthly rather than maintaining year-round bundles, forcing platforms to front-load content releases and minimize seasonal gaps. This pattern is most visible in the United States, where average subscription tenure has compressed below six months for non-sports services.
Broadcasting and Cable TV Market Segmentation
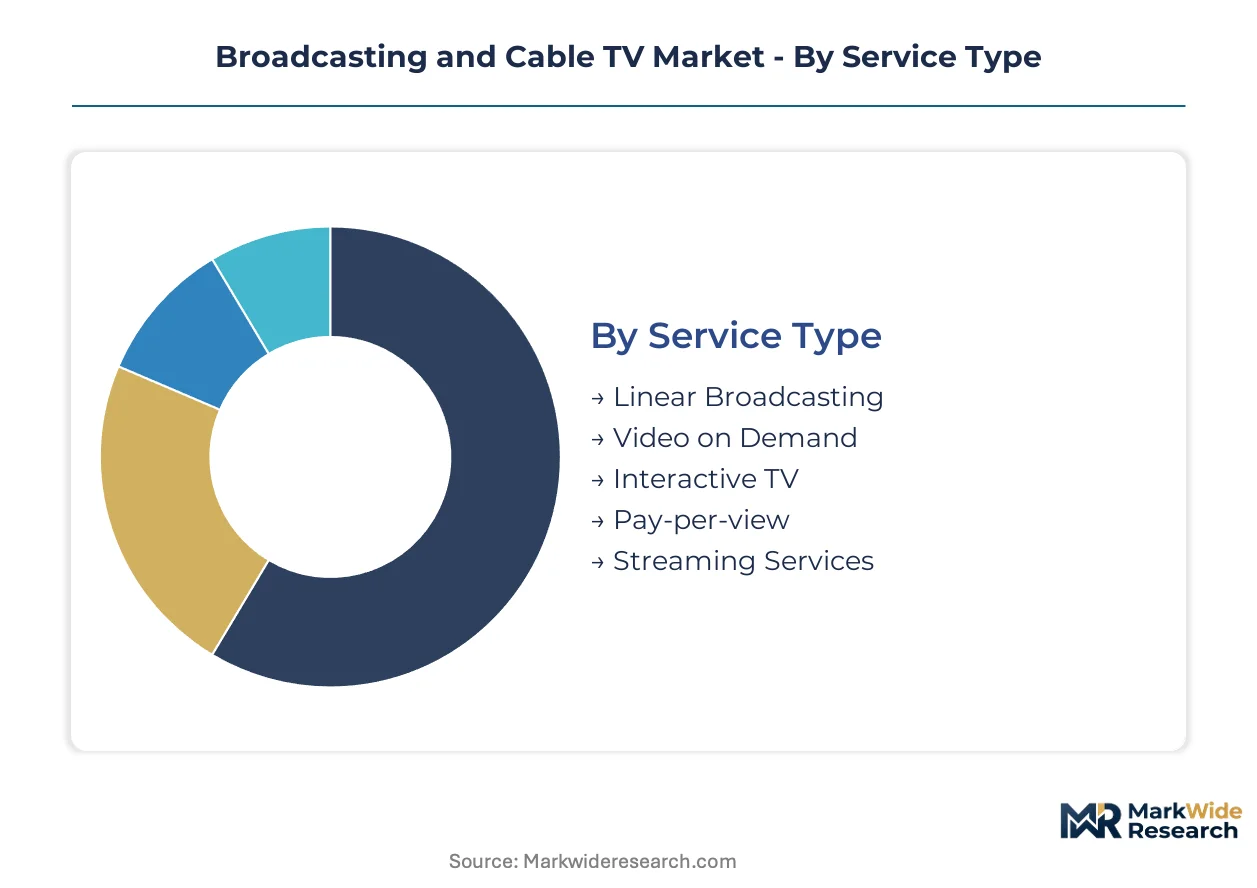
Segmentation in Broadcasting and Cable TV reveals how revenue pools fragment across delivery mechanisms and consumption patterns. Each dimension exposes different margin structures, infrastructure requirements, and regulatory exposure for stakeholders allocating capital across the value chain.
Service Type:
Cost tier differentiation separates legacy bundled offerings from direct-to-consumer alternatives, with pricing power concentrated in exclusive content windows.
- Linear Broadcasting:Scheduled programming delivered via terrestrial transmitters, satellite, or cable maintains the largest revenue pool through retransmission consent fees and national advertising avails. Demand concentrates among U.S. households aged 55+ and live sports viewers where appointment viewing persists. The FCC's must-carry rules preserve distribution floor for local affiliates.
- Streaming Services:On-demand libraries and live channels delivered over broadband infrastructure operate on subscription or ad-supported tiers. Demand concentrates in U.S. suburban markets with fiber-to-the-home penetration above 80 percent, driven by younger cohorts tolerating higher churn. Content cost inflation strains margins regardless of subscriber scale.
- Video on Demand:Transactional or subscription access to individual titles without linear scheduling.
- Interactive TV:Two-way services enabling viewer participation, voting, or personalized overlays.
- Pay-per-view:Event-based access to premium content, primarily live sports and entertainment specials.
Linear Broadcasting holds installed capacity. Streaming Services is rotating up the share rankings.
Technology:
Application maturity varies sharply across infrastructure generations, with packet-switched delivery displacing RF-based systems in addressable markets.
- Over-the-top:Internet-delivered video bypassing traditional broadcast and cable infrastructure operates on adaptive bitrate streaming from 2 Mbps to 50 Mbps. Demand concentrates in U.S. metropolitan areas where broadband competition suppresses data cap enforcement. GDPR and state privacy laws constrain addressable advertising yields.
- IPTV:Managed IP networks offering broadcast-quality reliability with interactive features. Demand concentrates from telecommunication firms bundling video with fiber broadband in suburban U.S. markets. Network investment cycles determine geographic rollout pace.
- Digital Terrestrial:UHF and VHF broadcast transmission using ATSC standards.
- Satellite:Direct-to-home and cable headend distribution via geostationary or low-earth-orbit constellations.
- Fiber Optic:Dedicated optical transport for cable plant backhaul and premium business services.
Digital Terrestrial holds installed capacity. Over-the-top is rotating up the share rankings.
Application:
Volume concentration in live programming creates pricing asymmetries, with scarcity events commanding premiums against commoditized library content.
- Sports Telecast:Live athletic competitions with exclusive territorial rights drive subscriber acquisition and advertising premiums. Demand concentrates in the United States where NFL, NBA, and NCAA rights command multi-billion dollar commitments. The FCC's retransmission consent framework enables broadcast stations to extract carriage fees for local team coverage.
- Entertainment Shows:Scripted and unscripted series, reality programming, and film content form the core subscription retention catalog. Demand concentrates from platform operators competing for exclusive windows, inflating production and licensing costs across Hollywood, Atlanta, and international production hubs.
- News Broadcasting:Scheduled and breaking news coverage across local, national, and international tiers.
- Educational Programs:Instructional and documentary content targeting schools, libraries, and direct-to-consumer segments.
- Infotainment Channels:Lifestyle, reality, and documentary programming blending information with entertainment formats.
News Broadcasting holds installed capacity. Sports Telecast is rotating up the share rankings.
End User:
Customer type determines procurement scale and technical requirements, with platform operators consolidating purchasing power across content categories.
- Platform Operators:Streaming services, cable systems, and virtual MVPDs aggregating content for household delivery. Procurement concentrates on exclusive windows and original production to reduce licensing dependency. Smart home integration through Alexa and Google Assistant ecosystems reduces subscriber friction.
- Media Conglomerates:Vertically integrated studios controlling production through distribution pipelines. Investment concentrates in cloud-native playout infrastructure on AWS and Azure to unify linear and streaming operations. GDPR consent management requirements fragment ad-tech stack architecture.
- Content Providers:Production studios, sports leagues, and rights holders licensing intellectual property.
- Telecommunication Firms:Broadband and wireless carriers bundling video with connectivity services.
- Advertising Agencies:Media buyers and programmatic platforms purchasing inventory across delivery systems.
Telecommunication Firms hold installed capacity. Platform Operators is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States exports streaming technology and content formats to European and Asian markets, while importing production labor from Canada and the United Kingdom. This trade corridor shapes infrastructure investment patterns and regulatory harmonization pressures across recipient economies.
United States
Demand concentrates in suburban markets with fiber-to-the-home penetration exceeding 80 percent, driven by younger cohorts adopting multiple simultaneous subscriptions. The FCC's retransmission consent framework preserves revenue floors for local broadcast affiliates as linear audiences fragment. Los Angeles and New York anchor production clusters where studios migrate master control operations to cloud-native AWS and Azure infrastructure.
United Kingdom
Platform operators compete for exclusive content windows amid high churn tolerance compressing average subscription tenure below six months. Ofcom's broadcasting codes and the EU's Audiovisual Media Services Directive shape content quotas and platform accountability obligations. London's Soho district houses post-production facilities serving both domestic broadcasters and international streaming clients.
Germany
Telecommunication firms bundle IPTV with fiber broadband in suburban markets where network investment cycles determine geographic rollout pace. The Interstate Broadcasting Treaty (Rundfunkstaatsvertrag) imposes must-carry obligations and local content quotas on platform operators. Cologne and Munich host broadcast technology clusters developing addressable advertising stacks for connected TV ecosystems.
South Korea
Smart home integration through voice-activated ecosystems reduces friction in content discovery and subscription management for tech-forward households. The Korea Communications Commission governs platform competition and net neutrality enforcement for streaming bundles. Seoul's Digital Media City concentrates encoding and playout infrastructure serving regional OTT platforms.
Japan
Household-level ad targeting through set-top boxes improves CPM yields for inventory previously sold on demographic approximations. METI's broadcasting policy frameworks shape spectrum allocation and 4K/8K transition timelines for terrestrial operators. Tokyo's Shibuya and Roppongi districts host streaming platform headquarters negotiating content licensing with domestic studios.
Broadcasting and Cable TV Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented tiers where no single operator commands decisive share. The vendor base stratifies between vertically integrated studios, broadband-anchored cable systems, and pure-play streaming aggregators. Three archetypes dominate: legacy broadcasters rebuilding around direct-to-consumer platforms, telecommunications firms bundling video with connectivity, and technology platforms operating smart TV operating systems. Competitive intensity centers on exclusive content licensing and cloud infrastructure consolidation rather than manufacturing scale or geographic expansion.
Among U.S.-based media conglomerates, Disney Entertainment, Comcast Corporation, and Warner Bros. Discovery exemplify contrasting strategic postures within the channel-control archetype. Disney Entertainment occupies a position emphasizing vertical integration from studio production through streaming distribution. Comcast Corporation anchors its competitive stance through hybrid fiber-coaxial infrastructure and broadband bundling relationships. Warner Bros. Discovery represents the consolidation-driven path, unifying previously separate streaming architectures under unified technical and content stacks. Each entity navigates the same regulatory constraints around retransmission consent and data privacy compliance, yet deploys capital toward different points in the value chain.
| Leading Market Players |
|---|
| Paramount Global |
| Disney Entertainment |
| Fox Corporation |
| The Liberty SiriusXM Group |
| Nexstar Media Group |
| Comcast Corporation |
| Warner Bros. Discovery |
| Sirius XM Holdings |
| NBCUniversal |
| Others |
Cost & Logistics Intelligence
Production studio concentration in Los Angeles and New York anchors content cost inflation, compressing margins for downstream platform operators who must bid against each other for exclusive licensing windows. This upstream bottleneck forces streaming services to absorb talent and production cost escalations while competing for subscriber retention in high-churn markets.
Pricing Analysis
Legacy coaxial infrastructure pricing faces compression against fiber-to-the-home and 5G fixed wireless alternatives, with broadband-anchored bundles commanding premiums over standalone video subscriptions. Three-tier pricing structure across premium ad-free, standard ad-supported, and economy FAST tiers separates Disney Entertainment's Hulu from Comcast's Peacock and Warner Bros. Discovery's Max. Pricing pressure stems from content cost inflation as sports rights and scripted programming commitments escalate regardless of subscriber scale. Price sensitivity concentrates among younger cohorts rotating through services monthly, while live sports viewers exhibit lowest elasticity.
Supply Chain Analysis
Extended payment terms from cloud infrastructure providers now stretch to 90-120 days for encoding and playout services, shifting working capital burdens onto content aggregators. Supply concentration spans the United States for studio production, South Korea for display panel and smart TV manufacturing, and Taiwan for semiconductor components powering set-top boxes. Raw material dependencies include optical fiber for broadband backhaul, rare earth elements for broadcast transmission equipment, and cobalt for consumer electronics batteries. Single-source vulnerability runs through AWS and Azure dominance in cloud-native playout infrastructure. Distribution runs through hybrid fiber-coaxial plant, direct-to-consumer apps, and retail electronics channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Streaming platform economics increasingly hinge on advertising technology attach rates, where connected TV ad insertion and programmatic auction layers expand faster than base subscription revenue. This service-attach dynamic restructures valuation frameworks around recurring ad-tech yield rather than subscriber acquisition cost alone.
For Market Incumbents: Harden cloud infrastructure redundancy across AWS and Azure regions to mitigate single-source concentration risk in master control operations. Consolidate fragmented streaming architectures into unified technical stacks that reduce encoding and storage overhead. Defend against FAST channel erosion by locking exclusive sports rights through retransmission consent leverage with local broadcast affiliates.
For New Entrants and Emerging Players: Establish a beachhead in rural broadband gaps where fixed wireless and low-earth-orbit satellite delivery remains underserved by incumbent cable operators. Target unserved census blocks in the United States where fiber-to-the-home penetration sits below 40 percent and streaming bundle penetration lags urban benchmarks. Deploy voice-activated content discovery integrations through Amazon Alexa and Google Assistant ecosystems to reduce subscriber acquisition friction.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional broadcast groups carrying stranded retransmission consent revenue streams as linear audiences fragment. Long-term viability across the analysis window depends on management teams pivoting ad inventory toward addressable CTV formats faster than demographic-based spot sales collapse. Watch for FCC net neutrality restoration proceedings as an inflection signal that would force disclosure of zero-rated streaming bundles and reshape ISP-platform economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Playout Migration | AWS and Azure infrastructure reduces capital intensity for channel launches while unifying linear and streaming operations. |
| Addressable Advertising Stack Integration | Programmatic buying platforms connected to connected TV operating systems enable real-time auction mechanics. |
| Exclusive Sports Rights Acquisition | NFL, NBA, and NCAA territorial rights drive subscriber acquisition and advertising premiums in fragmented markets. |
| Smart Home Ecosystem Partnership | Amazon Alexa and Google Assistant integrations reduce friction in content discovery and subscription management. |
| Rural Broadband Infrastructure Deployment | Fixed wireless and low-earth-orbit satellite delivery captures unserved census blocks beyond incumbent cable plant. |
Research Approach
Operator-level perspectives from streaming platform executives, cable system engineering directors, broadcast station general managers, and advertising technology product heads anchored the qualitative base. Primary interviews combined with secondary validation against FCC spectrum allocation records, SEC 10-K filings from publicly traded media conglomerates, retransmission consent agreement databases, and broadband deployment maps from the National Telecommunications and Information Administration. Bottom-up subscriber and advertising revenue estimates triangulated against top-down market sizing from content licensing transaction tracking.
Scenario-bracketing around FCC regulatory outcomes, sports rights renewal cycles, and broadband penetration trajectories shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, delivery technology, content application, and end-user archetype, with regional regulatory clusters treated as distinct adoption environments. CAGRs derived from historical cord-cutting velocity, streaming subscriber growth curves, and addressable advertising yield improvements. Forecast inputs incorporated cloud infrastructure capex disclosures from hyperscalers and retransmission consent fee escalations tracked through affiliate agreement filings.
Sensitivities concentrate around FCC net neutrality restoration, sports rights cost inflation trajectories, and GDPR-style privacy law expansion into additional U.S. states. Forecasts reflect documented assumptions regarding broadband penetration thresholds and content cost growth rates. Macroeconomic contraction, regulatory deviation, or technological disruption in compression standards would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Cloud TV Market
Television
Pay TV Market
Television
HDTV Market
Television
Global Digital Terrestrial Television Market
Television
Traditional TV and Home Video Market
Television
Television Broadcasting Services Market
Television
Digital TV Market
Television
Mobile TV Market
Television
Television Advertising Market
Television
TV Advertising Market
Television
Free-To-Air (FTA) Service Market
Television
Holographic TV Market
Television
Print Newspapers and Magazines Market
Television
Television and Set Top Box Market
Television
Cable Television Networks Market
Television
Pay TV Services Market