
 Print Newspapers and Magazines Market | 2026-2036
Print Newspapers and Magazines Market Size, Share, and Industry Trends Forecast 2026-2036
Print Newspapers and Magazines Market Intelligence
The shift toward premium, heavy-stock paper and high-fidelity color printing for special editions is bifurcating the market from standard newsprint. This move targets consumers willing to pay for a tactile, high-quality reading experience. The New York Times Company leverages its brand to command premium pricing for its core print offerings. Axel Springer SE specializes in a diverse range of formats across its European media assets, while Hearst Communications sustains a large portfolio of monthly lifestyle magazines.
Print newspapers and magazines are publications produced via processes like offset lithography on paper stock, typically ranging from 45 gsm newsprint to over 150 gsm for glossy magazine covers. Their primary purpose is the mass dissemination of news, feature stories, and advertisements to a broad readership. Subscription services represent the most stable revenue stream, providing predictable circulation figures for advertisers. Within product types, special interest publications demonstrate more resilience than daily newspapers, which face intense competition from digital media.
Regulatory frameworks governing advertising content, such as guidelines from the US Federal Trade Commission (FTC), directly impact revenue models. In Europe, postal service regulations and environmental directives like the EU Green Deal influence distribution costs and paper sourcing ethics. Publishers must decide how to balance investments in high-cost premium print products against the continued migration of advertising budgets to digital platforms.
Market Dynamics
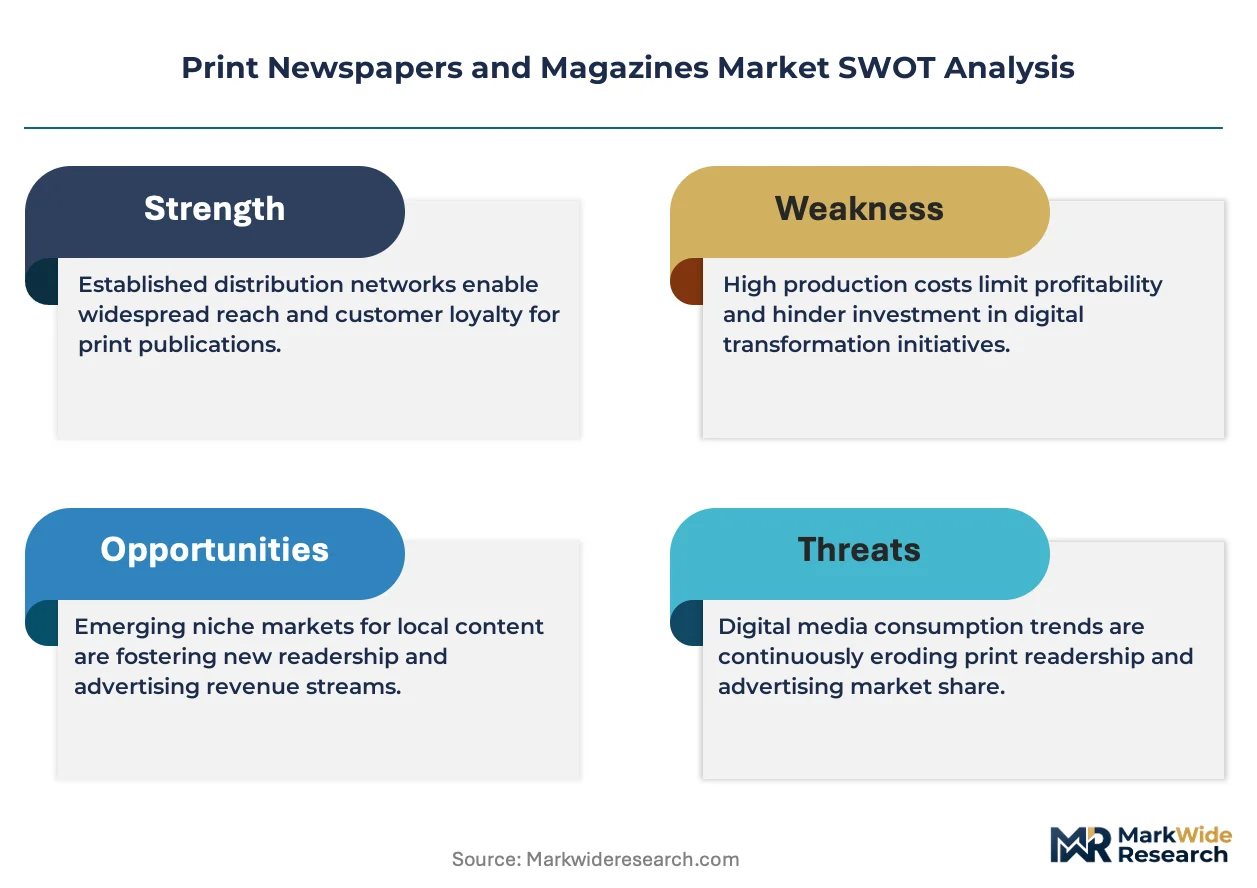
The primary structural force shaping the print newspaper and magazine market is the bifurcation of consumer demand. This split separates low-cost, mass-produced daily news from high-value, niche publications that command premium pricing for specialized content and superior physical quality.
Growth Catalysts
- Premium Materials Adoption:The use of heavy-stock paper and advanced color printing processes creates a tactile, high-quality experience, attracting consumers in hobbyist and luxury segments who value the physical product over digital alternatives.
- Special Interest Communities:Growth is concentrated in publications serving dedicated professional and enthusiast communities, such as finance, engineering, or classic cars, where demand for in-depth, curated content remains resilient against digital disruption.
- Sustainable Sourcing Mandates:Regulations like the EU's Corporate Sustainability Reporting Directive (CSRD) are pushing publishers toward certified, sustainable paper sources, creating a new value proposition for environmentally conscious readers and advertisers.
Market Restraints
- Input Cost Volatility:Publisher margins are constrained by unpredictable price fluctuations for essential raw materials, including paper pulp, printing inks, and the aluminum used for offset lithography plates.
- Digital Advertising Competition:The continued migration of advertising budgets to digital platforms, which offer precise targeting and performance metrics, erodes a primary revenue stream for traditional print publications, especially daily newspapers.
- Distribution Cost Pressures:National postal service regulations and rising fuel costs directly impact distribution expenses, particularly for publications with geographically dispersed subscriber bases, squeezing profitability.
Strategic Opportunities
- Niche Professional Content:There is an opportunity to launch highly specialized, subscription-based journals for professional communities in emerging markets where access to vetted, industry-specific information in print is limited.
- Interactive Print Technologies:Integrating QR codes or augmented reality (AR) triggers into print layouts can bridge the physical and digital divide, offering readers access to supplementary video content, tutorials, or e-commerce gateways.
- Direct-to-Consumer (DTC) Models:Publishers can develop exclusive, limited-run special editions or book-a-zines sold directly through their own websites, capturing higher margins and building direct relationships with their most loyal readers.
Industry Challenges
- Capital-Intensive Production:Maintaining a competitive edge in print quality requires significant capital investment in modern offset lithography presses and high-fidelity pre-press equipment, a major hurdle for smaller publishers.
- Supply Chain Reconfiguration:Shifting procurement from standard newsprint to ethically sourced and certified paper stocks requires qualifying new suppliers and adapting logistics, which can introduce friction and increase costs.
- Specialized Skills Gap:The industry faces a shortage of skilled labor, including experienced press operators, color management specialists, and graphic designers who understand the nuances of designing for high-quality print production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Print Newspapers and Magazines Market |
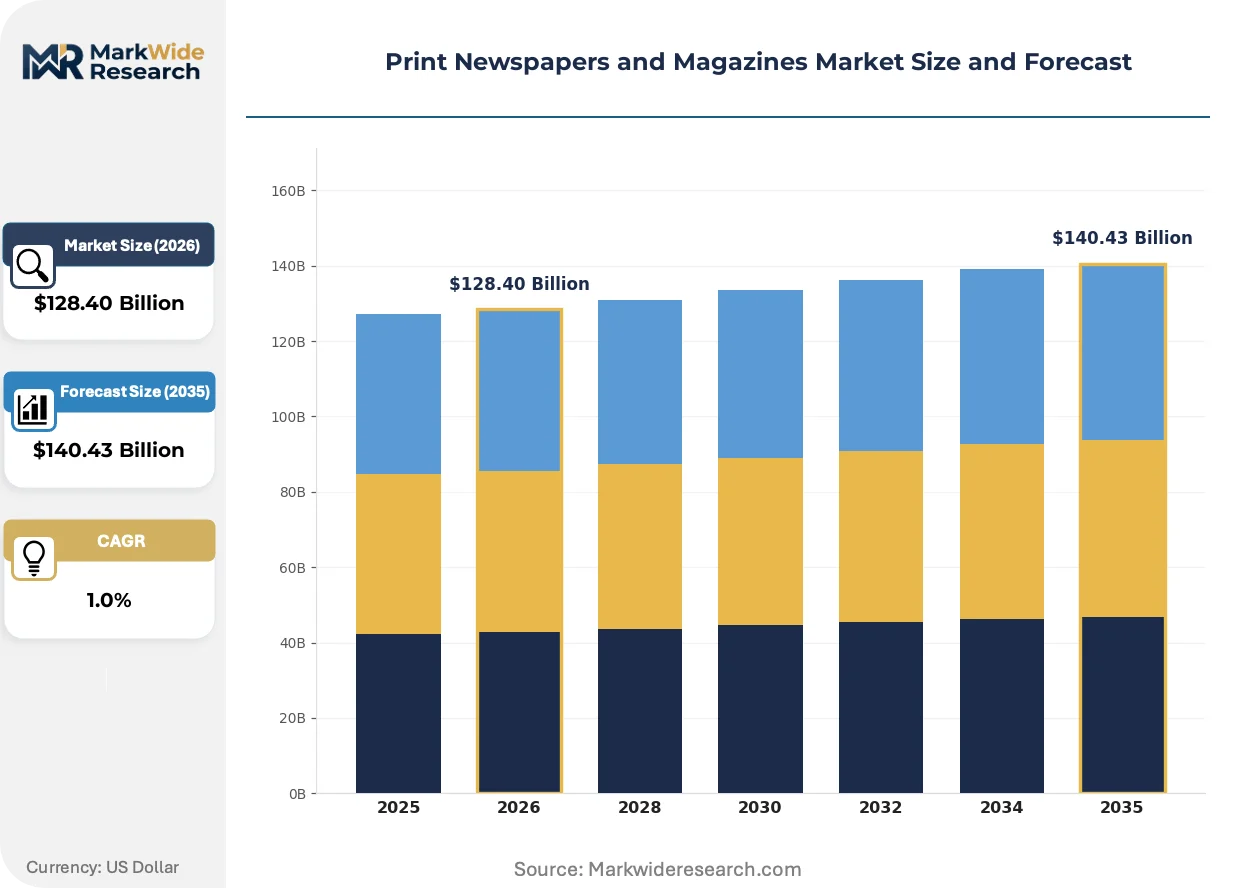
| Market Size in 2026 | $128.40 Billion |
| Market Size in 2035 | $140.43 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Daily Newspapers, Weekly Newspapers, Magazines, Special Interest Publications Distribution Channel: Retail Outlets, Newsstands, Subscription Services, Direct Sales Customer Type: Individuals, Businesses, Educational Institutions, Government Agencies Content Type: News Articles, Feature Stories, Advertisements, Reviews |
| Companies Covered | The New York Times Company, Gannett Co., Inc., News Corp, Hearst Communications, Axel Springer SE, Schibsted ASA, Advance Publications, Lee Enterprises, Reach PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Print Newspapers and Magazines Market Strategic Shifts & Innovations
Publishers are redefining the value of print by focusing on tangible quality and curated experiences. This strategic pivot emphasizes the physical object as a premium product, distinct from the ephemeral nature of digital media, to retain and attract subscribers.
Premiumization of Physical Media
The adoption of heavy-grammage paper stock and high-fidelity offset lithography serves to create a superior tactile and visual product. Niche publishers targeting collectors and affluent readers are leading this adoption for special editions and monthly magazines. This trend is bifurcating the market, separating premium, durable publications intended for retention from disposable, low-cost daily newsprint, thereby creating two distinct value propositions for consumers.
Advertising Content Regulation
Guidelines from bodies like the US Federal Trade Commission (FTC) regarding native advertising and influencer endorsements are tightening the rules for sponsored content. This forces publishers to implement clearer visual distinctions and explicit labels to separate editorial content from paid promotions. Lifestyle and special interest magazines, which rely heavily on advertorials, are most affected and must redesign layouts to maintain reader trust and regulatory compliance.
Consumption Pattern Shifts
A notable behavioral change is the move from recurring subscriptions to selective, single-issue purchases, particularly for high-value special editions. This disrupts the traditional newsstand and subscription-driven distribution model, favoring direct-to-consumer e-commerce platforms managed by the publishers themselves. This trend is highly visible within hobbyist segments in North America and Europe, where consumers purchase specific issues as collectible items.
Print Newspapers and Magazines Market Segmentation
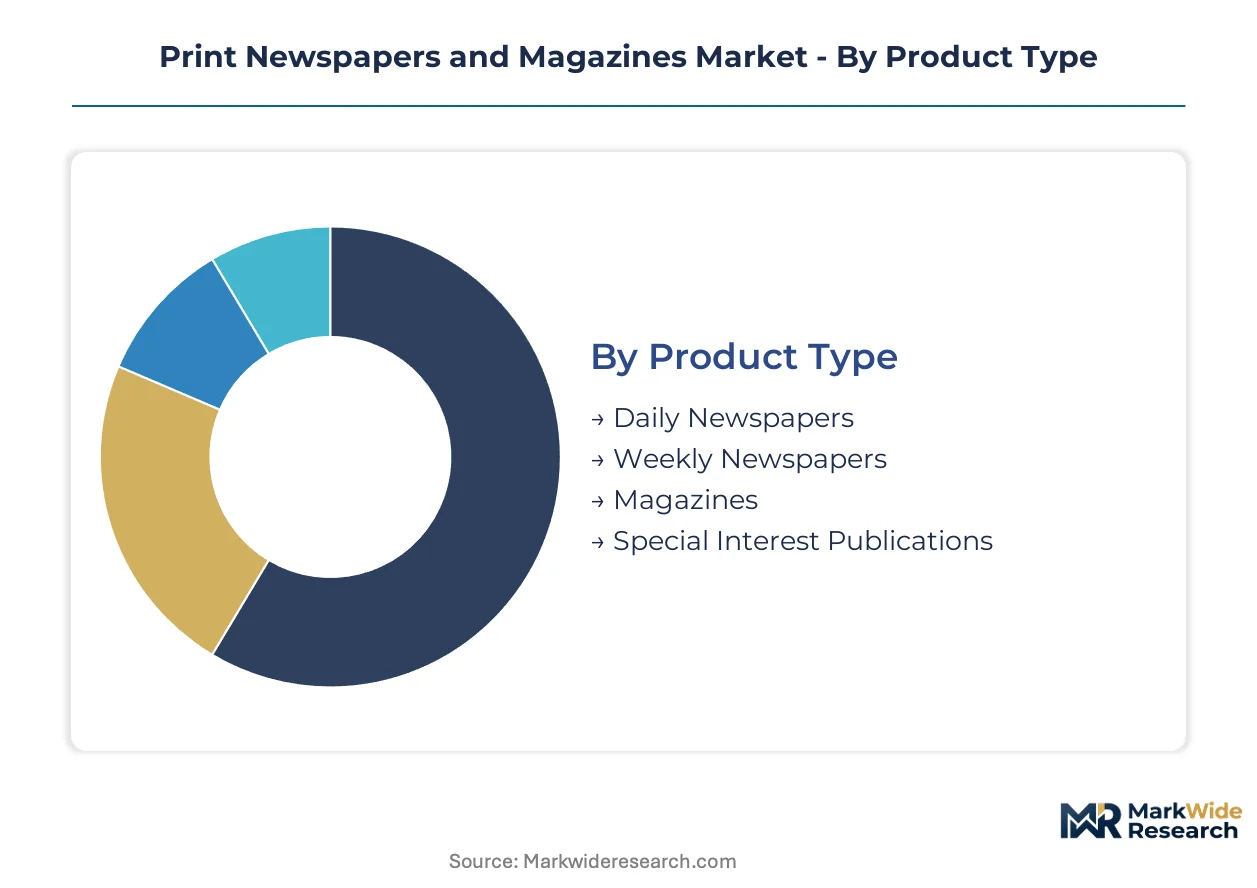
Understanding the distinct segments within the print newspapers and magazines market is crucial for publishers to tailor content, pricing strategies, and distribution models effectively. This market exhibits diverse reader preferences and advertising demands across its various product and customer categories.
Product Type:
Regulatory frameworks heavily influence product type differentiation within the print market.
- Magazines:These publications typically feature heavy-grammage paper stock and high-fidelity offset lithography, creating a superior tactile and visual experience. Demand concentrates in hobbyist and luxury segments who value the physical product over digital alternatives.
- Special Interest Publications:These cater to dedicated professional and enthusiast communities, offering in-depth, curated content in fields like finance or classic cars. Demand remains resilient against digital disruption due to the specialized nature of the information.
- Daily Newspapers:These provide mass dissemination of general news and current events, often produced on lighter newsprint.
- Weekly Newspapers:These focus on local community news and events, maintaining a strong connection with specific geographic areas.
Daily Newspapers handle the majority of throughput; Special Interest Publications are the fastest mover on share.
Distribution Channel:
Customer purchasing behaviors dictate the efficacy of various distribution channels.
- Subscription Services:This channel represents the most stable revenue stream, providing publishers with predictable circulation figures for advertisers. Demand comes from loyal readers seeking consistent, convenient delivery of their preferred publications.
- Direct Sales:Publishers use their own e-commerce platforms to sell exclusive, limited-run special editions or book-a-zines directly to consumers. Demand is high among collectors and niche enthusiasts who appreciate unique print offerings.
- Retail Outlets:These include supermarkets, convenience stores, and bookstores where single issues are purchased.
- Newsstands:Traditional points of sale for a wide variety of newspapers and magazines, often catering to impulse buys.
Subscription Services form the backbone of recurring revenue, while Direct Sales are capturing new consumer engagement.
Customer Type:
Margin structures vary significantly across different customer types.
- Individuals:This segment comprises the primary readership for consumer-focused newspapers and magazines, seeking news, entertainment, and specialized hobby content. Demand is influenced by personal interests and disposable income for premium print experiences.
- Businesses:Companies subscribe to industry-specific publications for market intelligence, competitive analysis, or bulk purchases for employees. Demand is also driven by the need for advertising placements to reach targeted professional audiences.
- Educational Institutions:Universities and schools utilize print publications for academic research, library resources, or student access to current events.
- Government Agencies:These entities subscribe to publications for policy monitoring, public information, or internal communication purposes.
Individual consumers drive the largest volume, whereas businesses contribute substantial advertising revenue.
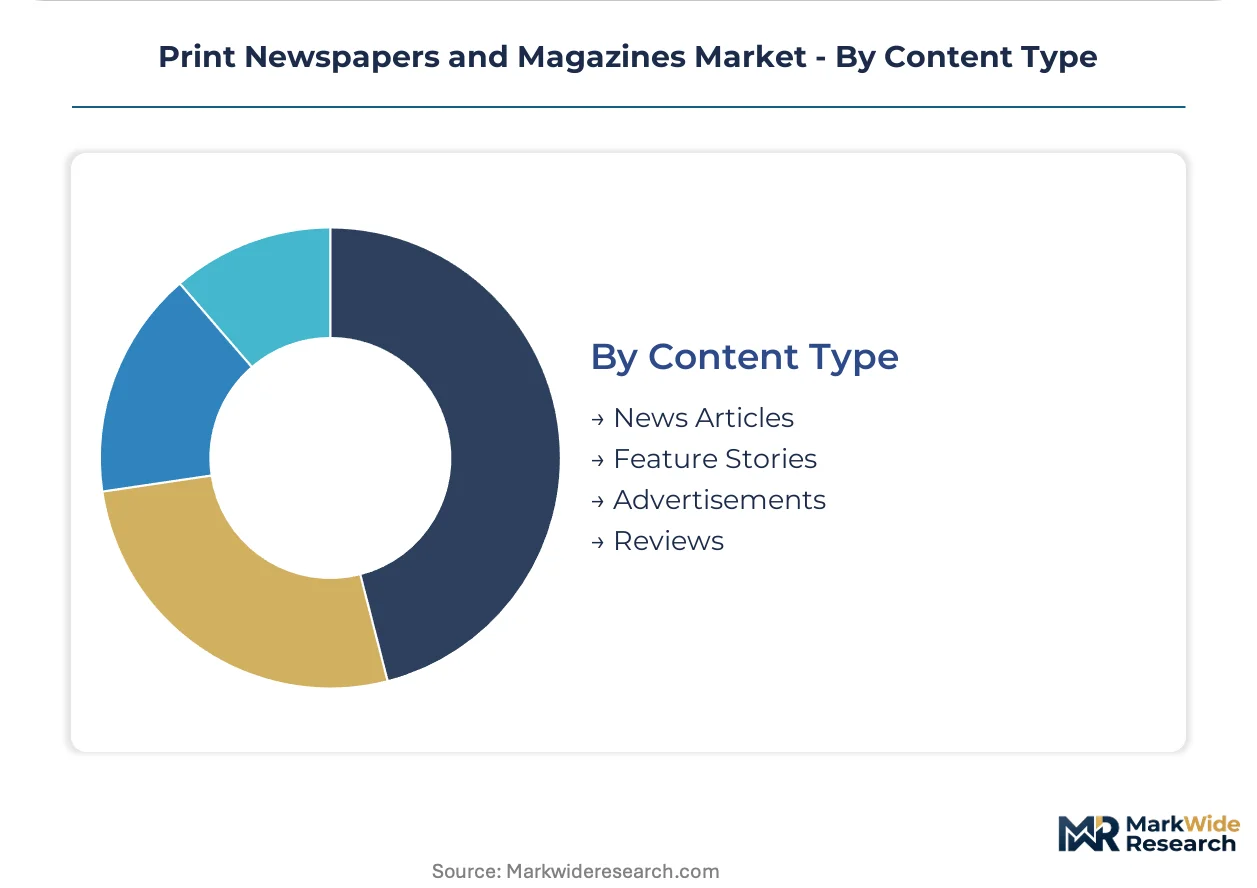
Content Type:
The application of content varies widely, influencing readership and revenue models.
- Advertisements:This content type generates significant revenue for publishers, often subject to regulatory guidelines from bodies like the US Federal Trade Commission (FTC). Demand comes from brands seeking to reach specific demographics through print media.
- Feature Stories:These provide in-depth narratives, investigations, or profiles that offer curated, specialized information beyond daily news. Demand is high among readers seeking comprehensive analysis and engaging long-form journalism.
- News Articles:These deliver timely information and reports on current events, forming the core of daily and weekly newspaper content.
- Reviews:Critical assessments of products, services, or cultural works, guiding consumer decisions and offering expert opinions.
News Articles represent foundational content, while Advertisements are critical for financial viability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The print newspapers and magazines market exhibits varied regional dynamics, influenced by local reading habits and regulatory environments. Premium print demand remains stable in mature economies, while emerging markets present opportunities for niche content. Supply-side concentration often aligns with historical media hubs and strong advertising markets.
United States
Demand for high-quality, special interest publications persists among niche hobbyist and professional communities. The US Federal Trade Commission (FTC) guidelines influence advertising content and revenue models. New York City remains a central hub for major publishing houses, driving innovation in direct-to-consumer models.
Germany
Premium print journalism maintains stable demand, particularly for specialized business and lifestyle magazines. The EU's Corporate Sustainability Reporting Directive (CSRD) influences paper sourcing standards for German publishers. Berlin's media cluster fosters diverse formats across European media assets.
Japan
A strong cultural appreciation for physical media supports stable demand for both newspapers and magazines. National postal service regulations impact distribution costs for publishers across the archipelago. Tokyo's publishing industry continues to innovate with high-fidelity color printing for collector's editions.
United Kingdom
Niche publications targeting specific professional communities show resilience against digital disruption. Environmental directives within Europe, even post-Brexit, influence sustainable sourcing practices for UK publishers. London serves as a significant center for lifestyle magazines and specialized content creation.
India
Growing literacy rates and a rising middle class drive demand for regional language newspapers and educational magazines. The country's national postal service facilitates widespread distribution, although costs are a factor. Mumbai's media houses are exploring local-specific content and subscription models for new readers.
Print Newspapers and Magazines Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the print newspapers and magazines market. The market exhibits a bifurcated structure, with large diversified media conglomerates coexisting with specialized niche publishers. Strategic archetypes include global brand-driven entities, regional content specialists, and local news providers. Key competitive moves involve portfolio diversification into digital assets and strategic partnerships for content distribution.
Within the global brand-driven archetype, The New York Times Company exemplifies leveraging a strong journalistic reputation to command premium pricing for core print offerings. Axel Springer SE, a European media group, represents a regional content specialist, diversifying formats across its extensive media assets. Hearst Communications, a US-based entity, occupies a position among large diversified media conglomerates, sustaining a substantial portfolio of monthly lifestyle magazines. These entities navigate evolving consumer preferences and advertising migration by emphasizing unique content and high-quality production.
| Leading Market Players |
|---|
| The New York Times Company |
| Gannett Co., Inc. |
| News Corp |
| Hearst Communications |
| Axel Springer SE |
| Schibsted ASA |
| Advance Publications |
| Lee Enterprises |
| Reach PLC |
| Others |
Cost & Logistics Intelligence
The shift from standard newsprint to certified, heavy-stock paper reconfigures the print market's supply geography while altering pricing economics. This substitution demands new supplier relationships and enables higher price points for premium publications.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure for print publications, influencing material costs for premium offerings. Pricing stratifies across premium, standard, and economy tiers, driven by paper quality and established brand premium. Pricing pressure stems from digital advertising competition, particularly for daily newspapers. Individual consumers for daily news exhibit high price sensitivity, while niche hobbyist and luxury segments demonstrate lower sensitivity for specialized content.
Supply Chain Analysis
Certified paper mill capacity underwrites the supply chain for premium print products, concentrating in Nordic countries and Central Europe. The market draws from specific raw materials like paper pulp, printing inks, and aluminum for offset plates. Commodity price volatility for these inputs represents a significant structural risk. Distribution runs through national postal services, retail outlets, and increasingly, direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The print newspapers and magazines market presents a fragmentation opportunity, driven by consumer demand for curated, high-quality content. This shift creates distinct niches for specialized publications.
For Market Incumbents:Compound investments in high-fidelity offset lithography to elevate product quality and justify premium pricing. Incumbents should leverage established brand reputation to expand direct-to-consumer channels, mitigating the threat from digital advertising migration. Diversify content portfolios into specialized digital subscriptions that complement print offerings. Control over paper sourcing and sustainable practices reinforces market position.
For New Entrants and Emerging Players:Eco-label certification fast-tracks market entry for new players targeting environmentally conscious readers. Focus on highly specialized, subscription-based journals for professional communities in emerging markets. North American hobbyist communities represent a penetrable segment for unique, collectible print items. Launch exclusive, limited-run special editions sold directly through publisher e-commerce platforms.
For Investors and Strategic Acquirers:The market sits at a consolidation phase that favors vertically integrated niche publishers with strong community ties. Long-term viability rests on stable demand for premium, specialized print products designed for retention. Target acquisition archetypes include publishers with proven direct-to-consumer models and high subscriber loyalty. Growth in premium subscription renewals indicates continued market resilience.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in advanced printing technology | Enhances tactile quality, attracting affluent readers and collectors. |
| Expand direct-to-consumer sales | Captures higher margins and strengthens direct reader relationships. |
| Develop niche professional content | Addresses resilient demand for curated, in-depth industry information. |
| Integrate interactive print features | Bridges physical and digital, offering supplementary rich media experiences. |
| Secure sustainable paper sourcing | Meets regulatory mandates and appeals to environmentally conscious consumers. |
Research Approach
Initial hypotheses were tested against primary input from publishers, advertisers, paper suppliers, and distribution channel managers, and refined through iterative analysis. This involved combining insights from these interviews with extensive secondary validation from industry association reports, government publications, and public company financial filings. The study employed both bottom-up and top-down triangulation to ensure data accuracy and consistency across all market segments.
Variance-decomposition modeling underpinned the analytical framework, disaggregating market growth across the analysis window. Segmentation dimensions included product type, distribution channel, customer type, content type, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical trends, expert projections, and identified market dynamics. Key industry-specific forecast inputs included paper pulp price fluctuations and digital advertising spend forecasts.
Decision-makers should treat outputs as directional under stable regulatory environments and predictable consumer preferences; material deviation would warrant model refresh. Forecasts reflect these underlying assumptions, acknowledging potential shifts from digital advertising dominance or paper supply chain cost volatility. Practitioners should keep alternative scenarios live as macroeconomic conditions and technological advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
HDTV Market
Television
Television Advertising Market
Television
Cloud TV Market
Television
Cloud Television (TV) Market
Television
TV Advertising Market
Television
Broadcasting and Cable TV Market
Television
Curved Television Market
Television
Pay TV Market
Television
Television Services Market
Television
Television Market
Television
Global Broadcast Equipment Market
Television
Digital TV Market
Television
Holographic TV Market
Television
Traditional TV and Home Video Market
Television
Cable Television Networks Market
Television
Pay TV Services Market