
 Mobile TV Market | 2026-2036
Mobile TV Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile TV Market Intelligence
The divergence between subscription-based, high-definition content and free, ad-supported services is repositioning the competitive landscape. Major telecom operators like Verizon Communications leverage their 5G infrastructure to offer premium live sports bundles. In contrast, SPB TV specializes in delivering free-to-air channels across multiple platforms. Bharti Airtel dominates in South Asia through affordable data-and-content packages tailored to regional audiences.
Mobile TV encompasses the broadcast or streaming of television content to portable devices like smartphones and tablets. The technology has evolved from dedicated broadcast signals, such as DVB-H, to IP-based delivery over cellular and Wi-Fi networks, enabling higher-quality video. Smartphones are the dominant device type, eclipsing tablets and portable media players. Within applications, live streaming of sports generates significant user engagement, while video on demand captures the largest share of viewing time.
Regulatory frameworks from the US Federal Communications Commission (FCC) and the Telecom Regulatory Authority of India (TRAI) govern spectrum allocation and service quality. Data privacy rules like the EU's GDPR impact how user data is used for personalized advertising in streaming apps. Future profitability depends on navigating complex content licensing agreements while optimizing advertising and subscription revenue models.
Market Dynamics
The fundamental shift from dedicated broadcast technologies like DVB-H to IP-based delivery over 5G cellular networks is the central force reshaping the market’s competitive structure. This technological transition underpins new service models and changes infrastructure requirements for operators.
Growth Catalysts
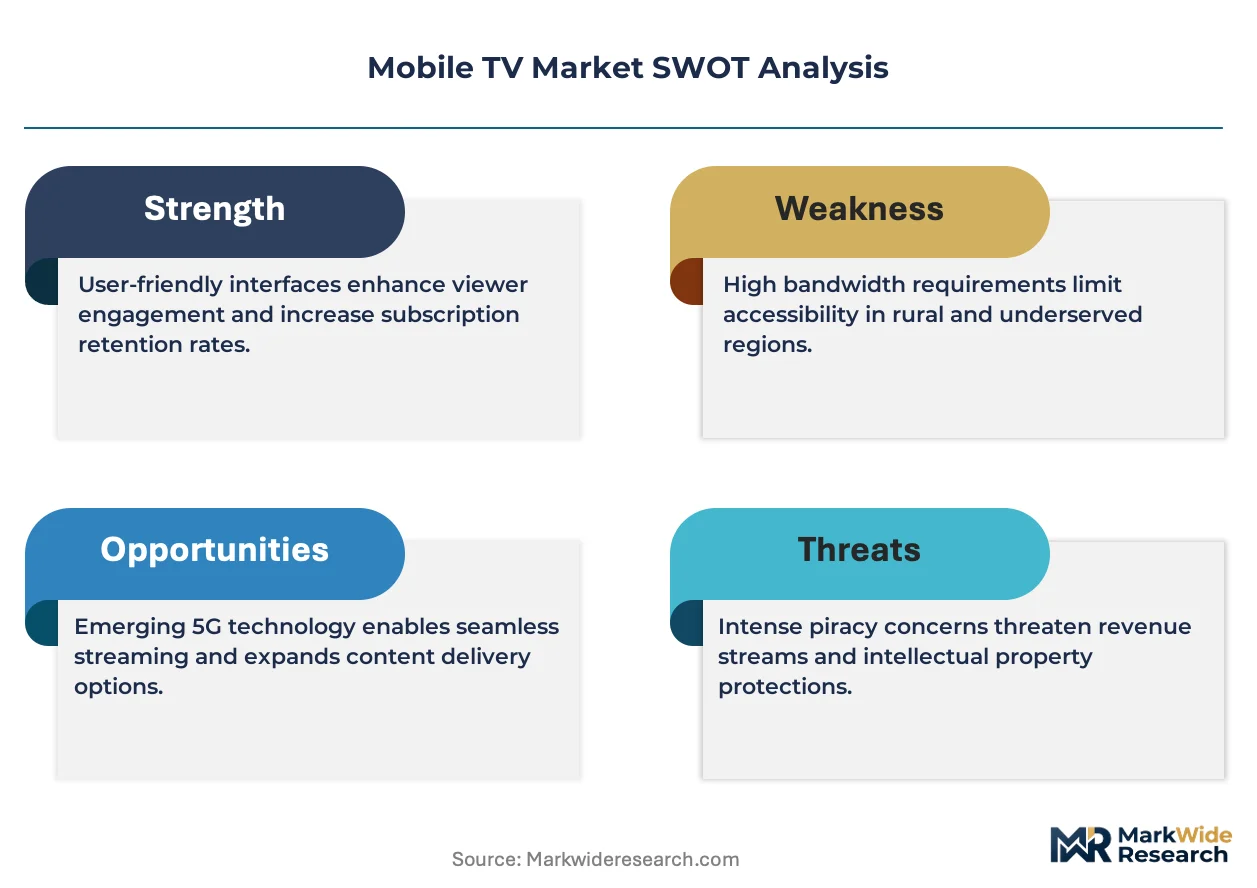
- 5G Network Expansion:The rollout of 5G infrastructure provides the high bandwidth and low latency required for reliable, high-definition mobile television streaming, particularly for live sports and interactive content.
- Affordable Data Bundling:Telecom operators, especially in South Asia, are bundling mobile TV subscriptions with data plans, making premium content accessible to a wider consumer base.
- Mobile Internet Penetration:Continued growth in smartphone ownership and mobile internet access in populous countries like India and Indonesia creates a constantly expanding addressable market for mobile TV services.
Market Restraints
- Content Licensing Costs:The high expense and complexity of securing broadcasting rights for premium content, such as major league sports and first-run movies, create significant financial barriers for new entrants.
- Network Congestion:In densely populated urban areas, network congestion during peak viewing times can degrade video quality and lead to buffering, negatively impacting the user experience.
- Data Privacy Regulations:Mandates like the EU's GDPR limit how operators can use viewer data for targeted advertising, constraining a key revenue stream for free, ad-supported mobile TV models.
Strategic Opportunities
- Interactive Content Formats:Integrating features like in-app betting, live polling, and social commentary into mobile TV streams presents an opportunity to increase user engagement and create new monetization avenues.
- Immersive Sports Viewing:The convergence of mobile TV with augmented reality can offer immersive experiences, such as displaying player statistics or multiple camera angles on a smartphone screen during a live game.
- Hyper-Local Content Platforms:Developing platforms focused on community-specific content, such as local news, municipal meetings, or regional sports, can capture niche audiences underserved by larger, national broadcasters.
Industry Challenges
- Fragmented Content Rights:Navigating the patchwork of exclusive content licensing agreements that vary by geography and platform type poses a significant operational challenge for services aiming for a global footprint.
- Ad Measurement Standardization:The absence of a universal standard for measuring viewership and ad performance across different mobile TV applications and devices complicates campaign validation for advertisers.
- Infrastructure Capital Expenditure:Supporting the growing demand for 4K and 8K streaming requires continuous and substantial investment in network capacity and content delivery network (CDN) infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile TV Market |
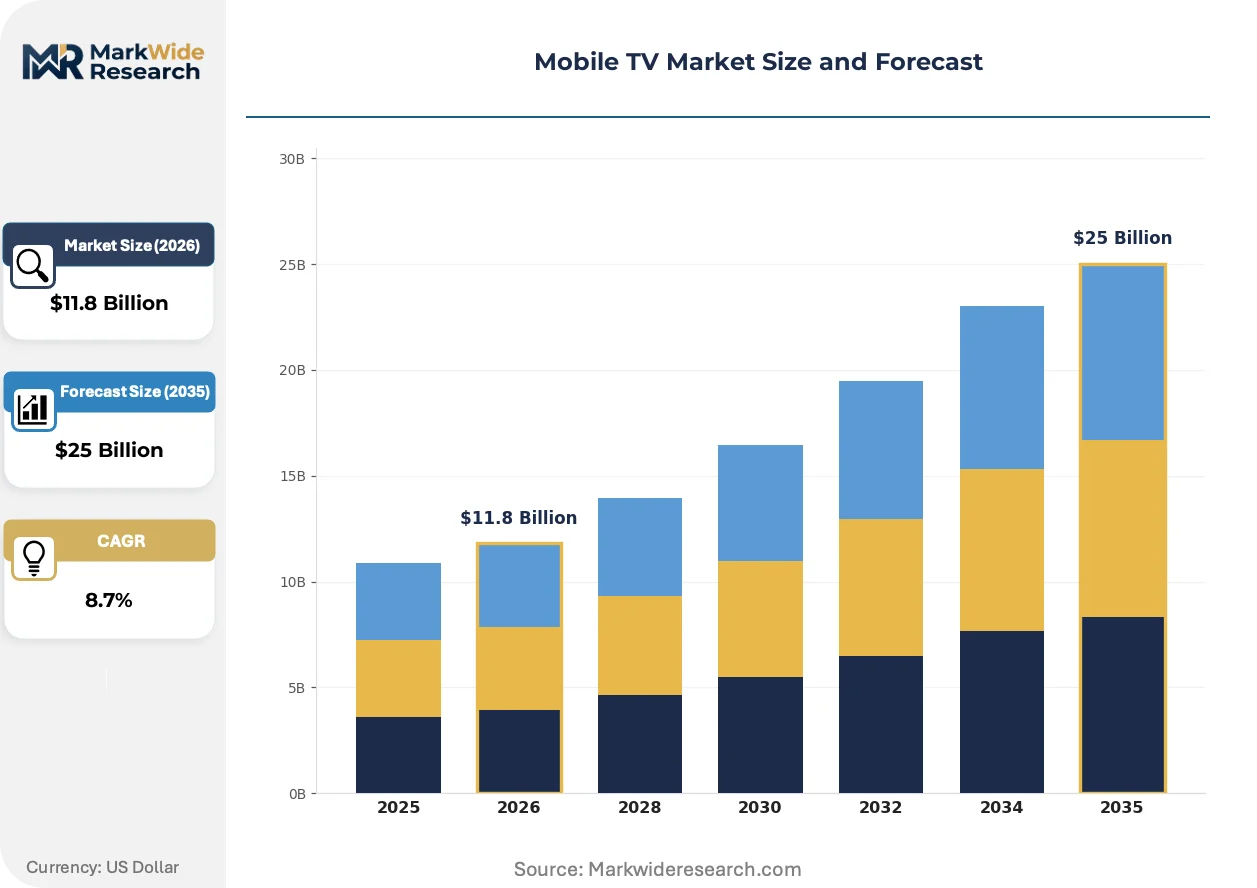
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $25 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: DVB-H, MediaFLO, T-DMB, Digital Video Broadcasting Satellite, Integrated Digital Enhanced Network, Others Device Type: Smartphones, Tablets, Laptops, Portable Media Players, Feature Phones, Others Application: Live Streaming, Video on Demand, News, Sports Broadcasting, Entertainment, Educational Content User Segment: Telecom Operators, Broadcasters, Content Aggregators, Advertising Agencies, End Consumers, Corporate Users |
| Companies Covered | AT&T, Comcast, SPB TV, Verizon Communications, Bell Canada, Bharti Airtel, Charter Communications, Cox Communications, MobiTV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile TV Market Strategic Shifts & Innovations
Personalization and interactivity are becoming the primary value differentiators for mobile TV services. The market is moving beyond simple content delivery to create more engaging and context-aware user experiences, driven by data analytics and enhanced network capabilities.
IP-based streaming technology enables the delivery of high-quality video over standard cellular and Wi-Fi networks. Content creators and telecom operators are rapidly adopting this method for its flexibility and scale. This technology is expanding into areas previously held by broadcast, such as delivering critical public safety alerts and hyper-local government channels.
Regulatory debates surrounding net neutrality principles influence how mobile TV services are delivered. In jurisdictions like the United States, rules set by the FCC can prevent internet service providers from prioritizing or throttling content from specific streaming apps. This policy environment primarily impacts telecom operators, who must innovate on content and service rather than creating tiered network access.
Viewing behavior is bifurcating between short, intense sessions for live events and long-form viewing for on-demand content. This shift disrupts monolithic advertising models, favoring live sponsorships over traditional ad breaks found in linear television. The trend is most visible in mature markets like the UK and South Korea, where premium sports and extensive VOD catalogs coexist.
Mobile TV Market Segmentation
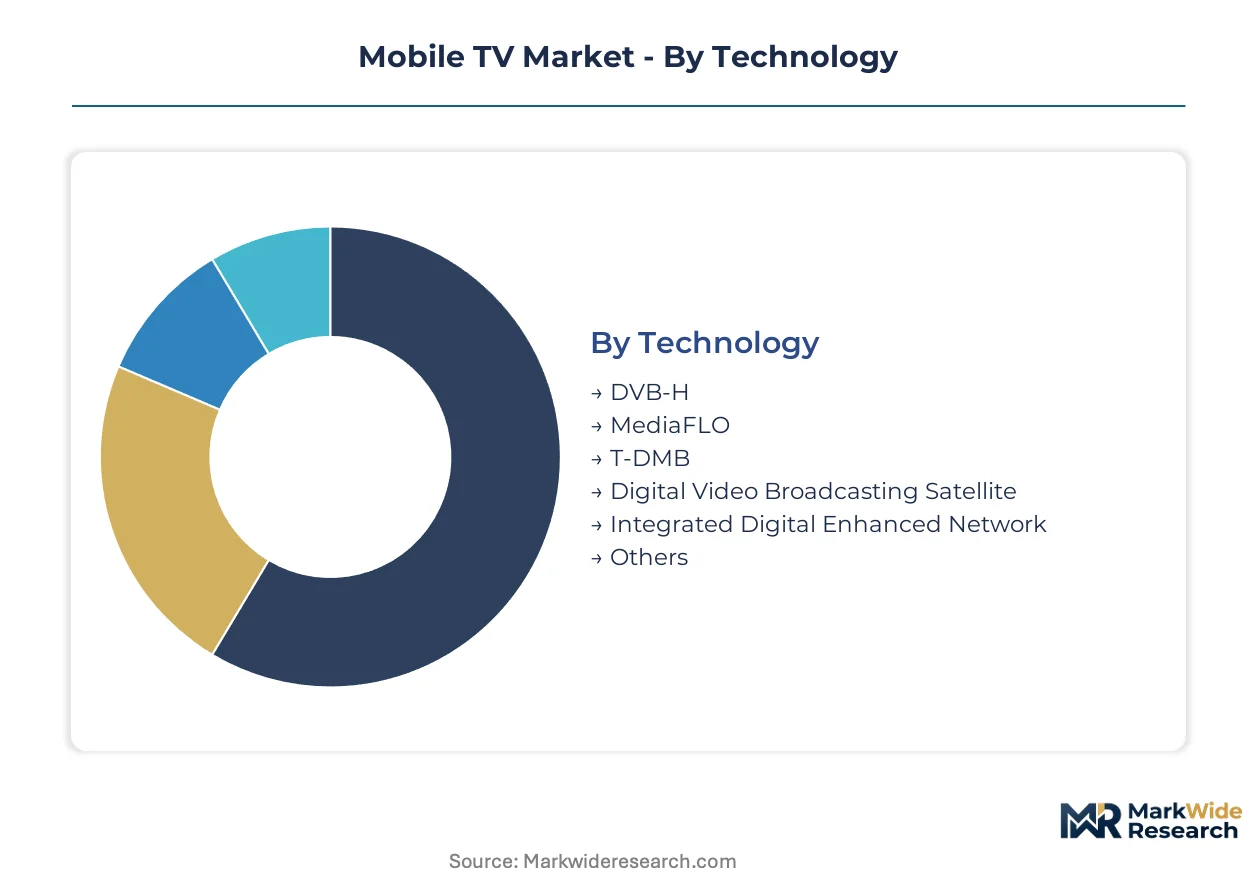
Mobile TV market segmentation clarifies the diverse technologies, devices, applications, and user groups shaping this dynamic industry. Understanding these distinctions is crucial for operators and content providers to tailor offerings and optimize infrastructure investments effectively.
Technology:
Supply concentration in mobile TV technology dictates service availability and quality, directly impacting market penetration and user experience across different regions.
- DVB-H:Digital Video Broadcast Handheld represents a terrestrial broadcasting standard specifically designed for mobile devices, offering dedicated spectrum. Demand concentrated in early mobile TV markets, but its decline is driven by the global shift to IP-based streaming over cellular networks.
- Digital Video Broadcasting Satellite:This technology delivers television content via satellite, enabling wide-area coverage and high-quality signal delivery to mobile receivers. Demand concentrates in remote areas or for specialized services where cellular networks are unreliable, driven by the need for robust, broadcast-grade signal delivery.
- MediaFLO:A proprietary mobile TV system, it focused on dedicated broadcast channels for subscription-based content delivery in specific markets.
- T-DMB:Terrestrial Digital Multimedia Broadcasting, a South Korean standard, provides digital radio and TV services to mobile devices.
- Integrated Digital Enhanced Network:This technology primarily supports voice communication but can carry low-bandwidth data, suitable for basic mobile TV services.
- Others:This category encompasses various niche or emerging mobile TV transmission methods and experimental broadcast standards.
Today's leader: DVB-H. Tomorrow's challenger: Digital Video Broadcasting Satellite.
Device Type:
Application focus heavily influences the design and feature sets of mobile TV device types, catering to diverse viewing habits and user preferences.
- Smartphones:These ubiquitous handheld devices serve as the primary platform for mobile TV consumption, leveraging high-resolution screens and cellular connectivity. Demand concentrates in India and Indonesia, driven by extensive mobile internet penetration and affordability.
- Tablets:Larger screen real estate makes tablets suitable for extended viewing sessions and multi-user experiences, often using Wi-Fi networks. Demand concentrates in developed markets, supported by a preference for higher-quality visual experiences and portability.
- Laptops:Portable computers offer full-browser streaming capabilities and larger displays, appealing to users seeking desktop-like experiences for mobile content.
- Portable Media Players:Dedicated devices for media playback, they typically offer offline viewing capabilities and specialized media handling features.
- Feature Phones:Basic mobile phones with limited internet access, they support simpler, low-bandwidth mobile TV services in emerging economies.
- Others:This includes smartwatches, in-car entertainment systems, and other specialized mobile screens integrated into various consumer electronics.
Smartphones currently dominate viewing hours, while tablets are gaining market share fastest for immersive content.
Application:
Cost tier considerations significantly differentiate mobile TV applications, influencing content accessibility and monetization strategies for providers.
- Live Streaming:This application delivers real-time video content, including sports and events, requiring low latency and high bandwidth for optimal performance. Demand concentrates among sports enthusiasts, driven by the immediacy and interactive potential of live broadcasts.
- Video on Demand:Users access a library of pre-recorded content at their convenience, often through subscription models, offering flexible viewing. Demand concentrates across all demographics, driven by flexibility, extensive content catalogs, and personalized recommendations.
- News:This category provides timely updates and journalistic content, often consumed in short, frequent sessions for information gathering.
- Sports Broadcasting:Dedicated channels and platforms offer live and on-demand coverage of athletic events globally, targeting specific fan bases.
- Entertainment:This broad segment includes movies, TV shows, and general interest programming, catering to diverse preferences and leisure viewing.
- Educational Content:Platforms offer learning materials, tutorials, and academic courses, often targeting specific knowledge acquisition and skill development.
The dominant usage pattern is Video on Demand, with Live Streaming showing the steepest expansion trajectory.
User Segment:
Geography significantly influences the operational models and service offerings of mobile TV user segments, reflecting regional market dynamics and regulatory environments.
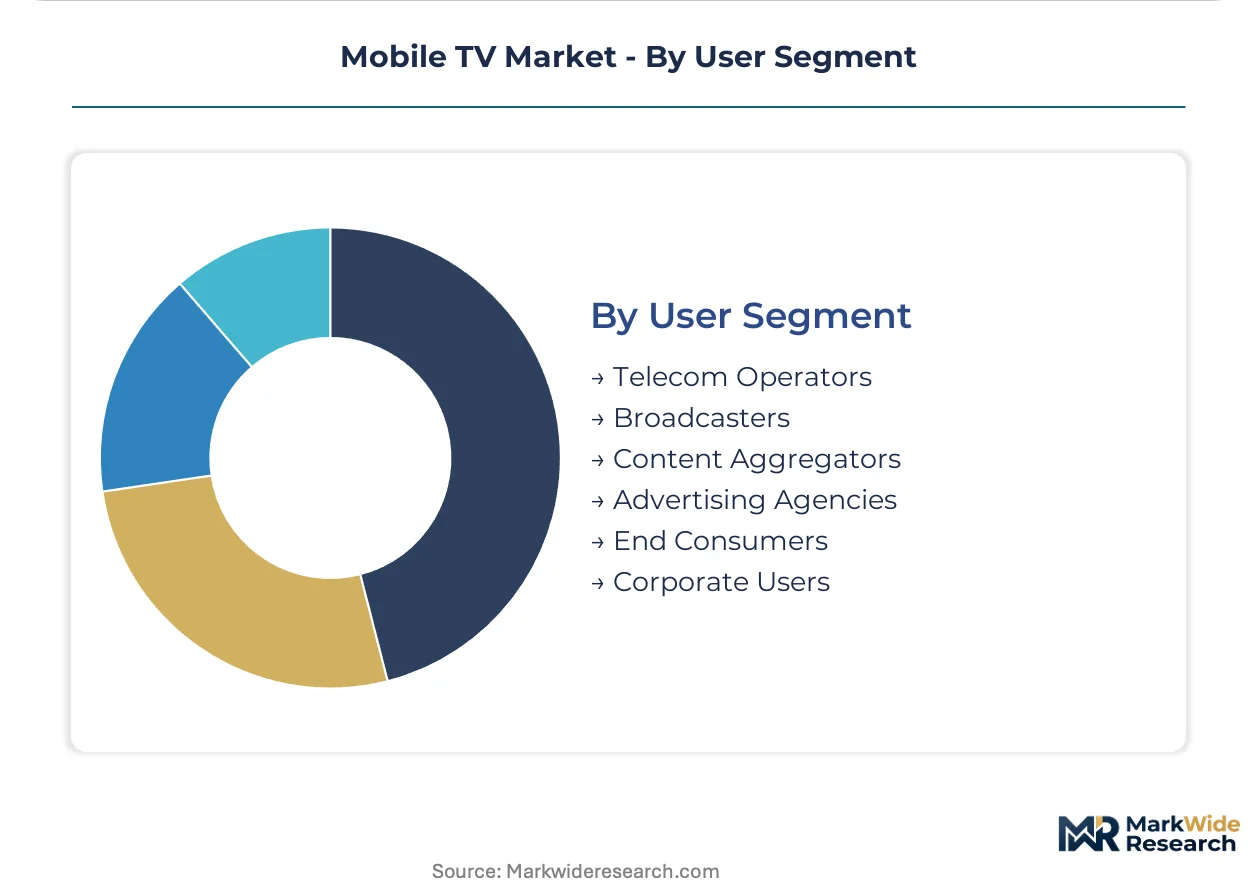
- Telecom Operators:These companies leverage their network infrastructure to bundle mobile TV services with data plans, creating new revenue streams and enhancing subscriber loyalty. Demand concentrates in markets with high mobile internet penetration, like India, driven by aggressive subscriber acquisition strategies.
- End Consumers:Individual users consume mobile TV content on their personal devices, driving overall market demand through subscriptions and ad-supported viewing. Demand concentrates in populous regions with widespread smartphone ownership, driven by accessibility and diverse content options.
- Broadcasters:Traditional television companies extend their reach by delivering content to mobile platforms, adapting to changing consumption habits.
- Content Aggregators:These entities compile and distribute content from various sources, offering curated mobile TV packages to diverse audiences.
- Advertising Agencies:They utilize mobile TV platforms for targeted ad placements, reaching specific viewer demographics and optimizing campaign effectiveness.
- Corporate Users:Businesses may use mobile TV for internal communications, training, or specialized content delivery to their employees or partners.
The primary value capture resides with Telecom Operators, while Advertising Agencies represent a critical support function.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's extensive mobile internet user base and aggressive telecom operator strategies anchor a significant portion of global mobile TV demand. This region's unique blend of affordability and content accessibility shapes service evolution. Operators prioritize tailored packages to capture this vast consumer segment.
India
Demand for mobile TV in India is driven by extensive mobile internet penetration and affordable data-and-content packages. The Telecom Regulatory Authority of India (TRAI) governs spectrum allocation and service quality for mobile services. Major telecom operators in cities like Mumbai and Delhi-NCR are expanding 5G coverage to support high-definition streaming.
United States
Verizon Communications leverages its 5G infrastructure to offer premium live sports bundles, driving demand for high-quality mobile streaming. The US Federal Communications Commission (FCC) regulates spectrum and ensures service quality for mobile TV platforms. Technology hubs such as Silicon Valley and New York City foster innovation in mobile content delivery.
United Kingdom
Mobile TV viewing in the United Kingdom is characterized by a mature market with significant demand for premium sports and extensive video-on-demand catalogs. Data privacy rules like the EU's GDPR impact how user data is utilized for personalized advertising in streaming apps. London serves as a central hub for media companies developing interactive mobile TV experiences.
South Korea
South Korea exhibits strong demand for mobile TV, stemming from its advanced 5G networks and historical adoption of standards like T-DMB. The Korea Communications Commission (KCC) oversees broadcasting and telecommunications policies, influencing service offerings. Seoul's vibrant tech ecosystem supports the development of innovative mobile content and immersive viewing experiences.
Mobile TV Market Key Industry Players
Top-tier vendors anchor the premium subscription segment, while a diverse array of specialized streaming services and content aggregators compete in the free-to-air and ad-supported tiers. The market structure exhibits a tiered consolidation, with major telecom operators leveraging their network infrastructure. Strategic archetypes include network-centric providers, content-focused platforms, and regional specialists. Key competitive moves involve bundling services with data plans and forming strategic content licensing partnerships.
Specialists in network-integrated mobile TV services include Verizon Communications, which leverages its extensive 5G infrastructure to provide premium content bundles, particularly for live sports. SPB TV represents a distinct archetype, focusing on delivering free-to-air channels across a multitude of devices and platforms globally. Bharti Airtel, a prominent South Asian telecom operator, exemplifies regional specialization by offering affordable data-and-content packages specifically tailored for local audiences. These companies collectively illustrate the diverse strategies and operational models employed across the mobile TV ecosystem, from premium subscriptions to ad-supported free services.
| Leading Market Players |
|---|
| AT&T |
| Comcast |
| SPB TV |
| Verizon Communications |
| Bell Canada |
| Bharti Airtel |
| Charter Communications |
| Cox Communications |
| MobiTV |
Cost & Logistics Intelligence
EU's GDPR compliance mandates gate qualified advertising supply for mobile TV services, directly influencing premium-tier pricing access. This regulatory framework shapes how providers monetize user data.
Pricing Analysis
The bundled versus unbundled service split defines mobile TV pricing structures, with telecom operators offering integrated data-and-content packages. Subscription-based models and ad-supported free services represent the dominant pricing structures. Content exclusivity and video quality tiers differentiate offerings, with premium live sports commanding higher prices. Pricing softness stems from intense competition among telecom operators, while end consumers in emerging markets exhibit high price sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with content licensing agreements, as exclusive rights for major sports or movies concentrate supply. Content acquisition often centers in major media markets like the United States and the United Kingdom. Key inputs include premium content rights and robust 5G network infrastructure. Fragmented content rights across geographies pose a significant operational risk, while distribution runs through direct-to-consumer app platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile TV market operates as a regulatory compounder, with initiatives like India's TRAI spectrum allocation driving demand for expanded services. This regulatory environment shapes the competitive landscape and service evolution.
For Market Incumbents: Deploy 5G infrastructure investments to enhance network capacity and deliver high-definition mobile TV streaming experiences. Integrate interactive features like live polling into existing sports bundles to increase engagement. Form strategic content licensing partnerships to secure exclusive premium content against emerging specialized streaming services. This protects market share from new entrants focused on niche content.
For New Entrants and Emerging Players: Hyper-local content platforms offer a viable digital-channel route for new entrants to capture underserved community-specific audiences. Focus on creating niche content such as regional sports or local news, particularly in emerging economies with high mobile internet penetration. Develop innovative monetization models beyond traditional subscriptions, like micro-transactions for specific events. Leverage social media integration for organic user acquisition.
For Investors and Strategic Acquirers: Roll-up economics work for content aggregators because fragmented content rights create opportunities for consolidation. The mobile TV market exhibits long-term viability, driven by sustained mobile internet adoption over the next decade. Target mid-sized platforms specializing in interactive or immersive viewing technologies. Watch for standardization in ad measurement across diverse mobile TV applications as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced 5G Network Capacity | Supports high-definition live streaming and reduces buffering for mobile TV users. |
| Interactive Content Development | Increases user engagement for live sports and creates new monetization avenues. |
| Hyper-Local Content Acquisition | Captures niche audiences underserved by larger national broadcasters. |
| Unified Ad Measurement Framework | Simplifies campaign validation for advertisers across mobile TV platforms. |
| Immersive AR/VR Integration | Offers advanced viewing experiences, like real-time player statistics during games. |
Research Approach
Multiple input streams — primary interviews, secondary research, and quantitative data analysis — were reconciled to build this comprehensive market view. Primary interviews engaged telecom executives, content creators, platform developers, and advertising agency leads. Secondary research leveraged FCC filings, TRAI reports, industry journals, and company financial disclosures. Bottom-up and top-down triangulation validated market sizing and growth projections.
Historical data sets were cross-referenced with expert panel input to project market trajectories over the projection horizon. A robust analytical framework integrated segmentation dimensions, including technology, device type, application, and user segment, alongside regional adoption patterns. Compound annual growth rates were derived from a multi-variant regression analysis. Key forecast inputs included 5G network expansion rates and mobile internet penetration.
The model assumes a particular technology adoption path; alternative pathways for IP-based streaming over 5G would alter the outlook. Forecasts reflect inherent assumptions regarding regulatory stability and content licensing evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Traditional TV and Home Video Market
Television
Curved Television Market
Television
Pay TV Operator Market
Television
Television Market
Television
Pay TV Services Market
Television
Global Broadcast Equipment Market
Television
Free-To-Air (FTA) Service Market
Television
HDTV Market
Television
TV Advertising Market
Television
Television Advertising Market
Television
Pay TV Market
Television
Cloud Television (TV) Market
Television
Digital TV Market
Television
Print Newspapers and Magazines Market
Television
Holographic TV Market
Television
Television Services Market