
 Television Market | 2026-2036
Television Market Size, Share, and Industry Trends Forecast 2026-2036
Television Market Intelligence
The proliferation of direct-to-consumer sales channels and e-commerce platforms is decoupling purchasing decisions from physical retail environments, shifting power to online aggregators. Samsung Electronics Co. Ltd. leverages its significant brand equity and expansive product portfolio to dominate premium segments. TCL Corporation competes aggressively on price and features, particularly in the mid-range smart TV category. Sony Corporation differentiates through proprietary image processing technology and deep integration with its PlayStation gaming ecosystem.
A television is an electronic device designed to receive and display broadcast, cable, or internet-based video signals. Modern units incorporate complex display panels, such as OLED or QLED, featuring refresh rates from 60Hz to 120Hz and advanced upscaling processors. OLED and QLED technologies command higher margins within the product type segmentation due to superior contrast and color accuracy. In terms of screen size, models 55 inches and larger represent the fastest-growing category, driven by consumer preference for immersive home cinema experiences.
Manufacturers must comply with a complex web of regional standards, including FCC Part 15 rules on emissions in the United States and the EU's mandatory energy labeling framework for electronic displays. In China, adherence to GB standards for performance and safety is a prerequisite for market access, while India's BIS certification is also critical. Navigating these varied compliance requirements while managing component costs remains a central strategic challenge for all market participants.
Market Dynamics
The central dynamic shaping the television market is the accelerated consumer replacement cycle, driven by the dual forces of advanced display technology adoption and the demand for larger, more immersive screen sizes for home entertainment.
Growth Catalysts
- Technology Upgrades:The transition toward 8K resolution and high dynamic range (HDR) formats stimulates demand from consumers seeking superior picture quality, shortening the typical device replacement timeline.
- Commercial Sector Demand:The hospitality sector is a significant source of volume growth, as hotels and resorts invest in upgrading in-room entertainment systems to enhance guest experiences and maintain a competitive edge.
- Emerging Market Expansion:In India, a combination of an expanding middle class, rising disposable incomes, and increased internet penetration for streaming services is driving first-time purchases and upgrades to smart TVs.
Market Restraints
- Panel Price Volatility:The market is sensitive to fluctuations in the cost of key components, particularly advanced OLED and QLED display panels, with supply concentration in South Korea and China creating price instability.
- Substitution from Personal Devices:The proliferation of smartphones and tablets for video consumption, especially among younger demographics, presents a substitution threat that can delay or defer large-screen television purchases.
- Regulatory Compliance Burden:A fragmented global regulatory landscape, including the US FCC Part 15 rules and China's GB standards, increases compliance costs and can delay market entry for new models.
Strategic Opportunities
- Smart Home Integration:Deeper integration with smart home platforms and voice assistants offers a path to differentiate products beyond picture quality, positioning the television as a central hub for connected living.
- Commercial Display Applications:Opportunities exist in expanding the use of large-format displays for commercial purposes, such as digital signage in retail environments and information boards in public transportation facilities.
- Gaming Ecosystem Synergy:Forging deeper technical and marketing integration with gaming consoles provides a high-margin opportunity, as gamers prioritize features like high refresh rates and low input lag.
Industry Challenges
- Logistical Complexity:The growing preference for screen sizes of 55 inches and larger creates significant logistical challenges, increasing shipping costs, warehouse space requirements, and the risk of damage during transit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Television Market |
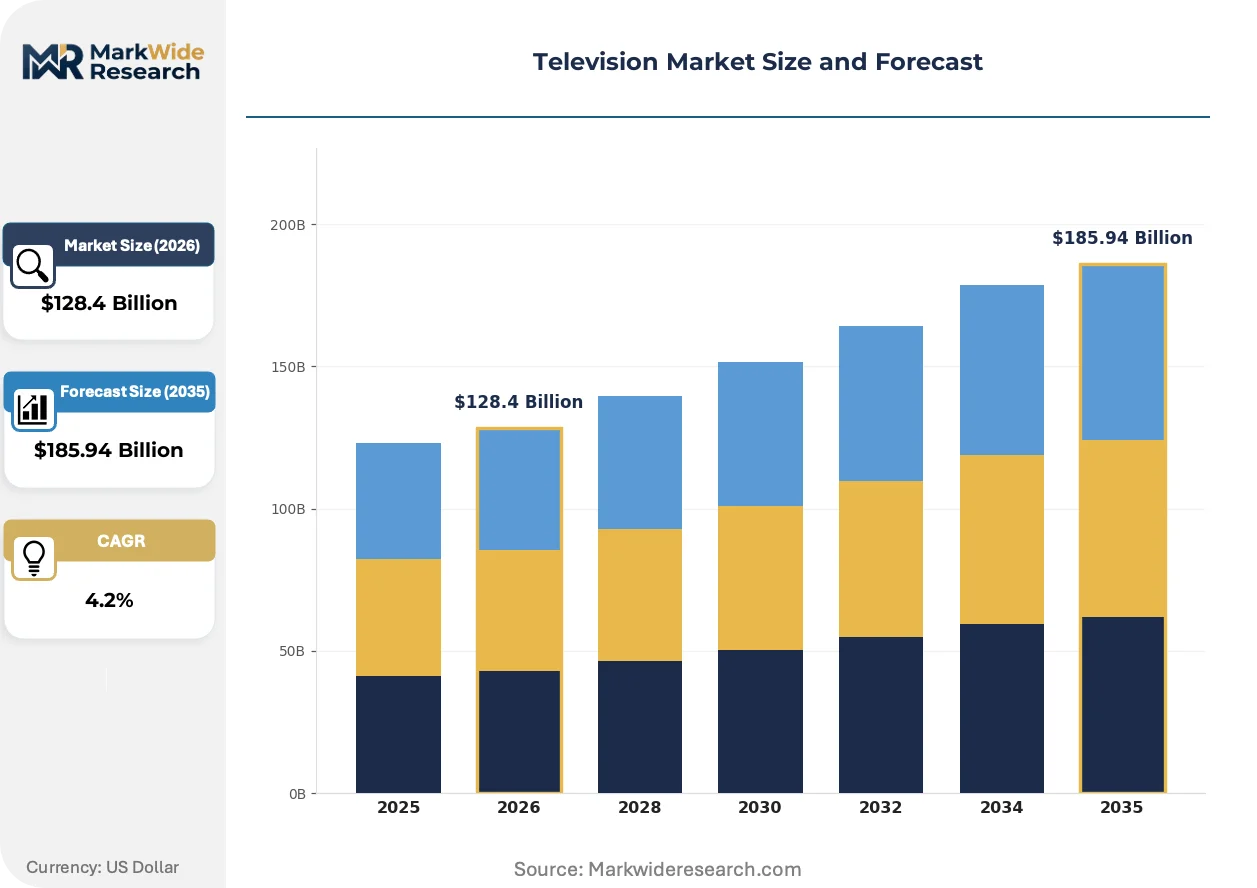
| Market Size in 2026 | $128.4 Billion |
| Market Size in 2035 | $185.94 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, QLED, LCD Screen Size: 32 inch, 42 inch, 55 inch, 65 inch Technology: Smart TV, 4K, 8K, HDR End User: Residential, Commercial, Educational, Hospitality |
| Companies Covered | Hisense Group Co. Ltd., Koninklijke Philips N.V., TCL Corporation, Vizio Inc., Sharp Corporation, Samsung Electronics Co. Ltd., Sony Corporation, Skyworth Group, LG Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Television Market Strategic Shifts & Innovations
Software and connectivity are defining the next frontier of product differentiation. The television's value proposition is shifting from a passive display device to an interactive entertainment hub, with operating systems and app ecosystems becoming as critical as panel hardware.
Onboard image processors, which utilize artificial intelligence for real-time picture and sound optimization, are a key area of innovation. Premium and mid-range market segments are rapidly adopting these processors to deliver superior upscaling of lower-resolution content. This advanced processing capability is converging with gaming-specific features like variable refresh rates to create a highly responsive and immersive experience.
The European Union's mandatory energy labeling framework for electronic displays is forcing design changes across the industry. This regulation directly influences research and development, pushing manufacturers toward more power-efficient panel technologies and power supply unit designs. The most-affected products are large, high-brightness televisions, which must now balance performance with stringent power consumption limits to be sold in the EU.
A significant consumer behavioral shift favors televisions with robust, easy-to-use smart operating systems over those with superior hardware but a poor user interface. This is disrupting traditional retail sales models, where specifications were paramount, and empowering platforms like Google TV, Roku, and Tizen. This trend is most visible in North America, where streaming service aggregation is a primary purchasing consideration.
Television Market Segmentation
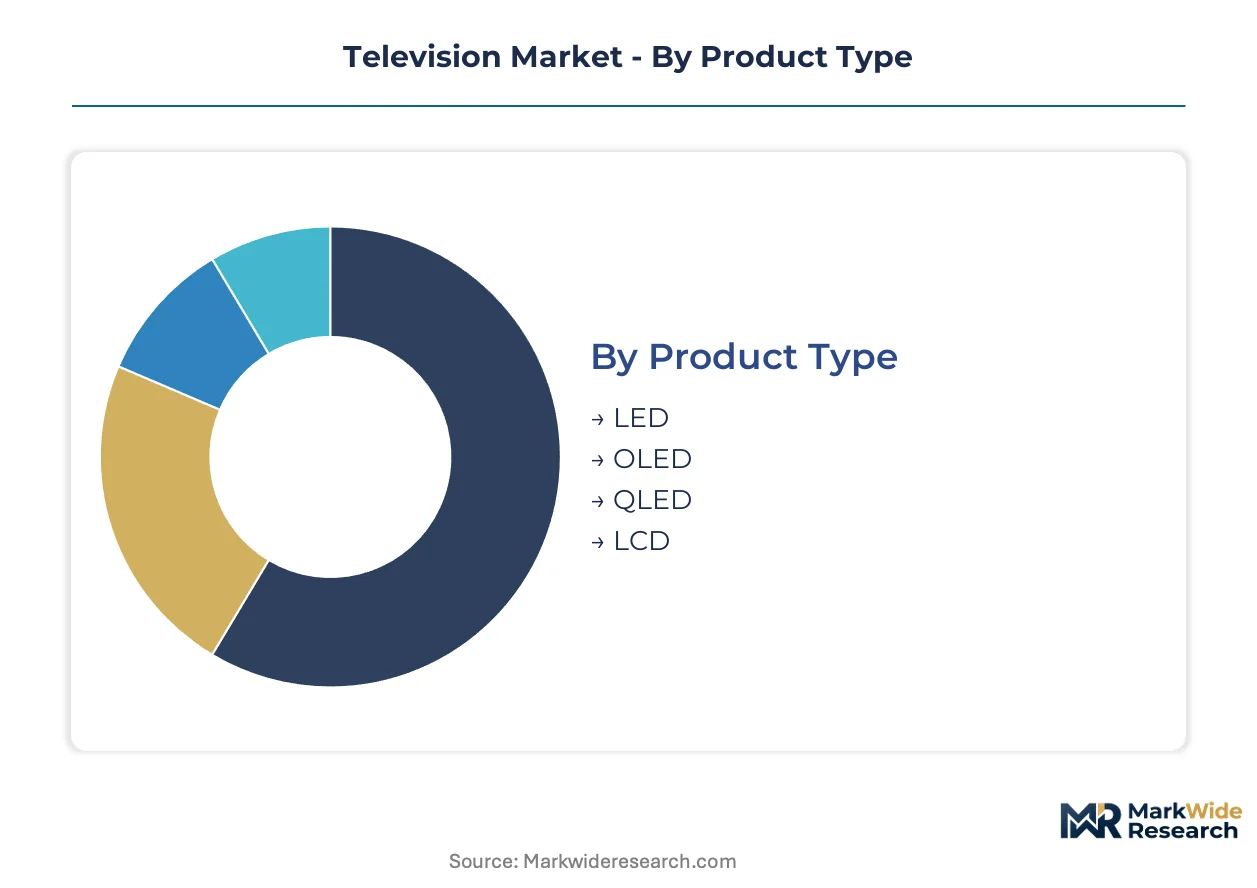
The television market's segmentation reveals distinct consumer preferences and technological adoption patterns across various product attributes. Understanding these categories is essential for manufacturers to tailor product development and market strategies. This granular view helps identify areas of concentrated demand and emerging opportunities.
Product Type:
Supply concentration in advanced display panels significantly influences product type availability and pricing across the market.
- OLED:These organic light-emitting diode displays offer superior contrast ratios and perfect blacks due to self-emissive pixels, providing exceptional picture quality. Demand for OLED technology is concentrating in premium home cinema setups, driven by consumers seeking the most immersive visual experiences.
- QLED:Quantum dot LED displays enhance color volume and brightness by using quantum dots to convert light, offering vibrant and accurate color reproduction. This technology sees strong demand in mid-to-high-end segments, particularly in regions like North America where bright, colorful displays are favored.
- LED:Light-emitting diode televisions utilize an LED backlight to illuminate liquid crystal displays, offering a balance of performance and affordability.
- LCD:Liquid crystal display televisions represent a foundational display technology, providing cost-effective solutions for entry-level market segments.
OLED absorbs the bulk of installed capacity for high-margin displays; QLED is expanding most quickly in the vibrant color segment.
Screen Size:
Volume metrics across different screen sizes reflect evolving consumer preferences for immersive viewing experiences in residential settings.
- 55 inch:This screen size represents a critical sweet spot for many consumers, balancing immersive viewing with practical room integration. Consumer preference for 55-inch models is concentrating in developed markets, driven by the desire for home cinema experiences in average-sized living spaces.
- 65 inch:Models at 65 inches and above deliver a highly immersive visual experience, making them ideal for dedicated home theaters and larger living rooms. Demand for these larger screens is accelerating, particularly among affluent households upgrading their primary entertainment systems.
- 32 inch:These compact televisions serve niche markets such as secondary rooms, kitchens, or hospitality applications requiring smaller footprints.
- 42 inch:Mid-sized 42-inch televisions offer a versatile option for bedrooms or smaller apartments, balancing display area with spatial constraints.
The largest screen sizes capture the most value; smaller formats maintain entry-level access for budget-conscious buyers.
Technology:
Customer type preferences for advanced features are increasingly shaping the adoption rates for various television technologies.
- Smart TV:These televisions integrate internet connectivity and operating systems, enabling access to streaming services, apps, and smart home ecosystems. Demand for Smart TVs is concentrating in North America, where streaming service aggregation is a primary purchasing consideration for households.
- 8K:Offering four times the resolution of 4K, 8K technology provides unparalleled detail and clarity, even on very large screens. Early adoption of 8K is observed among tech enthusiasts and early adopters seeking the absolute pinnacle of picture quality.
- 4K:Ultra High Definition (UHD) 4K televisions provide four times the pixel count of Full HD, delivering sharp and detailed images for mainstream consumers.
- HDR:High Dynamic Range technology enhances contrast and color accuracy, producing more lifelike images with greater depth and vibrancy across all content types.
Smart TV platforms define the core user experience; 8K resolution represents the premium frontier for visual fidelity.
End User:
Application-specific requirements drive distinct purchasing patterns and feature priorities across different end-user segments.
- Residential:This segment encompasses individual households purchasing televisions for personal entertainment and home cinema experiences. The residential sector represents the largest volume driver, with demand concentrated on larger screen sizes and integrated smart features.
- Hospitality:Hotels, resorts, and cruise lines fall into this category, requiring robust and often customized televisions for in-room entertainment and digital signage. The hospitality sector is a significant source of volume growth, as establishments upgrade systems to enhance guest experiences.
- Commercial:This segment includes televisions used in corporate offices, retail stores, and public spaces for presentations, advertising, or information display.
- Educational:Educational institutions utilize televisions for classroom instruction, digital whiteboards, and informational displays across campus facilities.
Residential consumption drives baseline demand; the hospitality sector is expanding its installed base for guest amenities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's expanding middle class and rising internet penetration drive significant television demand, anchoring a substantial portion of global volume growth. Developed markets like the United States prioritize immersive home cinema experiences with larger screens and advanced smart features. European Union countries increasingly focus on energy-efficient models due to stringent environmental regulations and consumer preferences.
India
An expanding middle class, rising disposable incomes, and increased internet penetration for streaming services accelerate smart TV upgrades across India. The Bureau of Indian Standards (BIS) certification is critical for market access, ensuring product quality and safety for consumers. Major consumer electronics retail hubs in Delhi-NCR and Mumbai drive significant sales volume.
United States
Demand for larger screen sizes and immersive home cinema experiences, coupled with streaming service aggregation, shapes purchasing decisions in the United States. Manufacturers must comply with FCC Part 15 rules on emissions for electronic devices sold domestically. Silicon Valley companies continue to innovate in smart home integration, positioning televisions as central hubs.
Germany
Consumer preferences for advanced display technology and energy efficiency stimulate demand in Germany's premium television segment. The European Union's mandatory energy labeling framework directly influences product design and market availability. Berlin's vibrant tech scene influences smart TV software development and user interface design across the region.
China
A vast domestic market, rapid urbanization, and high technology adoption rates contribute to China's substantial television consumption. Adherence to GB standards for performance and safety is a prerequisite for market entry and product sales. Shenzhen remains a major hub for television manufacturing and advanced component sourcing, influencing global supply chains.
South Korea
Early adoption of advanced display technologies, including OLED and QLED, characterizes the South Korean television market. The Korea Certification (KC) mark is mandatory for electronic products, ensuring compliance with national safety and electromagnetic compatibility standards. The Paju Display Cluster concentrates advanced display panel production, supplying global television manufacturers.
Television Market Key Industry Players
South Korean and Japanese producers anchor the premium and technology-driven segments, while Chinese manufacturers hold significant market share in value-oriented offerings. The market exhibits a tiered structure, with a few integrated giants dominating high-end innovation and numerous regional players competing on price and localized features. Key strategic archetypes include integrated display manufacturers, brand-focused assemblers, and software-centric smart TV platform providers. Companies pursue capacity expansion in advanced panel production and strategic partnerships for content aggregation.
On the premium-tier vector, South Korean-based Samsung Electronics Co. Ltd. exemplifies market leadership through brand equity and extensive product portfolios. Japanese-headquartered Sony Corporation differentiates through proprietary image processing technology and gaming ecosystem integration. Chinese-owned TCL Corporation competes aggressively in the mid-range smart TV category, balancing price and feature sets for mass market appeal.
| Leading Market Players |
|---|
| Hisense Group Co. Ltd. |
| Koninklijke Philips N.V. |
| TCL Corporation |
| Vizio Inc. |
| Sharp Corporation |
| Samsung Electronics Co. Ltd. |
| Sony Corporation |
| Skyworth Group |
| LG Electronics Inc. |
| Others |
Cost & Logistics Intelligence
The transition towards advanced OLED and QLED display technologies simultaneously reshapes cost economics and concentrates supply in a few specialized manufacturing hubs. This shift influences both premium pricing strategies and global component availability.
Pricing Analysis
Volume sales primarily occur in the mid-range and entry-level segments, where margins are compressed by aggressive competition. A per-unit transactional pricing model dominates, with significant price differentiation driven by display technology (OLED vs. LED) and brand premium. Pricing softness runs through the 4K segment due to widespread availability and fierce competition. Residential consumers in the entry-level market exhibit the highest price sensitivity, while premium home cinema enthusiasts prioritize features over cost.
Supply Chain Analysis
Dual-sourcing requirements for critical components mitigate risk, though advanced display panel production remains geographically concentrated. South Korea and China serve as primary manufacturing hubs for sophisticated OLED and QLED panels. The supply chain relies heavily on a few key raw material inputs, including rare earth elements for quantum dots and specialized glass substrates. Commodity price volatility for these materials poses a structural risk. Distribution runs through a hybrid model combining e-commerce platforms, direct-to-consumer channels, and traditional retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The television market is a consolidation play, as intense competition in the mid-range segment forces smaller manufacturers to exit or specialize. This dynamic will reshape the competitive landscape over the next decade.
For Market Incumbents:Cement market leadership by deepening integration with smart home ecosystems and proprietary content platforms. Invest strategically in advanced image processing R&D to differentiate beyond panel hardware, countering the threat of commoditization from value-oriented brands. Optimize large-format display logistics to manage increasing shipping costs and reduce transit damage.
For New Entrants and Emerging Players:Enter via niche segments like commercial display applications or specialized gaming monitors, where performance requirements justify premium pricing. Target underpenetrated mid-range smart TV categories in emerging markets like India, leveraging aggressive price-feature bundles. A go-to-market angle focused on robust, user-friendly smart operating systems can capture market share from hardware-focused competitors.
For Investors and Strategic Acquirers:Exit pathways concentrate in software-centric smart TV platform providers and specialized panel manufacturing capabilities over the long term. The market offers viable returns for entities with strong brand equity or proprietary technology. Acquisition targets should include innovators in AI-driven image processing or firms with established commercial display networks. A key signal to watch is the widespread consumer adoption of 8K content, which will drive the next wave of premium upgrades.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Panel Capacity Expansion | Secures critical supply for premium OLED and QLED models, stabilizing production costs. |
| Smart OS Ecosystem Development | Differentiates products by enhancing user experience and content aggregation capabilities. |
| Gaming Console Integration Partnership | Captures high-margin gaming segment demand through optimized display features. |
| Commercial Display Solutions Launch | Diversifies revenue streams beyond residential markets into B2B applications. |
| Energy Efficiency R&D Investment | Ensures compliance with European Union regulations and appeals to eco-conscious consumers. |
Research Approach
Document review covered SEC filings for major television manufacturers, national statistical agency reports from India and the United States, and European Union energy labeling directives, complemented by interviews with industry stakeholders. Primary research involved discussions with product managers, supply chain directors, retail buyers, and hospitality procurement specialists. This approach allowed for bottom-up data collection and top-down validation against published market figures.
Volume and value projections were generated by a quantitative model integrating historical data with future adoption curves for advanced display technologies. The analytical framework segmented the market by product type, screen size, end-user, and regional market. Compound annual growth rates were derived from consumer electronics spending and internet penetration rates. Forecast inputs included disposable income trends and smart TV feature adoption.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of extreme panel manufacturing disruptions or unforeseen global economic downturns. The projections reflect assumptions regarding technological progression and regulatory stability. Deviation in consumer purchasing power would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Broadcasting and Cable TV Market
Television
Traditional TV and Home Video Market
Television
HDTV Market
Television
Pay TV Market
Television
Global Broadcast Equipment Market
Television
Television Advertising Market
Television
Television and Set Top Box Market
Television
Curved Television Market
Television
Television Services Market
Television
TV Advertising Market
Television
Television Broadcasting Services Market
Television
Cable Television Networks Market
Television
Holographic TV Market
Television
Mobile TV Market
Television
Free-To-Air (FTA) Service Market
Television
Cloud Television (TV) Market