
 Global Audio Streaming Market | 2026-2036
Global Audio Streaming Market Size, Share, and Industry Trends Forecast 2026-2036
Global Audio Streaming Market Foresight
Lossless and hi-resolution audio tiers is redrawing competitive boundaries in the Global Audio Streaming Market. Spotify Technology S.A. leverages its podcast infrastructure to anchor exclusive content deals across multiple continents. Apple Inc. sustains hardware-software integration through spatial audio capabilities on its device ecosystem. Amazon.com, Inc. competes aggressively on bundling, folding music access into broader Prime membership value.
Audio streaming denotes the continuous transmission of compressed digital audio files from remote servers to end-user devices via internet protocol, typically employing adaptive bitrate algorithms ranging from 96 kbps to lossless 24-bit/192 kHz formats depending on network conditions and subscription tier. The technology serves commercial purposes spanning personal entertainment, background audio for retail environments, and integrated infotainment systems in connected vehicles. Smartphone-based consumption dominates volume across the device type dimension, while premium subscription models capture disproportionate margin pools relative to freemium bases. Podcast and audiobook segments within content type are expanding fastest as platforms diversify beyond music catalogs to reduce licensing cost exposure and extend listener session duration.
The EU AI Act and GDPR constrain automated recommendation engines and cross-border data flows for platforms operating across European member states. The FCC in the United States governs broadcast-to-digital transition frameworks affecting live radio streaming parity. China's SAMR and MIIT enforce content licensing and algorithmic transparency rules that shape market entry for foreign services. Stakeholders must monitor evolving royalty rate determinations by collective management organizations and anticipate how generative audio tools will challenge existing copyright clearance frameworks.
Market Dynamics
Automotive infotainment integration is compressing platform margins as OEMs demand native streaming stacks that bypass smartphone intermediaries, forcing services to rebuild ingestion pipelines for embedded silicon architectures.
Growth Catalysts
- EU AI Act compliance frameworks:Platforms investing in algorithmic transparency tools capture enterprise licensing opportunities from competitors facing retrofit delays.
- Connected vehicle penetration:Automotive OEMs in Germany, Japan, and South Korea now mandate streaming APIs as standard infotainment features.
- Spatial audio rendering pipelines:Binaural and object-based codecs are unlocking premium tier pricing power across headphone and automotive speaker systems.
Market Restraints
- Mechanical royalty rate volatility:Collective management organizations in the United States and United Kingdom are pursuing rate increases that compress gross margins on interactive streams.
- Cloud egress cost concentration:Three hyperscalers control essential content delivery network infrastructure for high-bitrate lossless tiers.
- Generative audio IP uncertainty:Training data licensing for synthetic voice and composition tools remains unresolved across major jurisdictions.
Strategic Opportunities
- India's smartphone-first listener base:Low-cost data plans and vernacular content gaps create white space for localized catalog investments.
- FCC broadcast parity mandates:Live radio streaming integration requirements are opening bundled distribution channels for digital-native platforms.
- Voice biometric authentication:Convergence of speech recognition and payment rails enables frictionless in-car subscription upgrades.
Industry Challenges
- MLops talent scarcity:Recommendation engine optimization requires scarce specialists who command compensation premiums exceeding media sector norms.
- Legacy automotive integration complexity:Embedded Linux variants and proprietary middleware stacks fragment development resource allocation across OEM programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Audio Streaming Market |
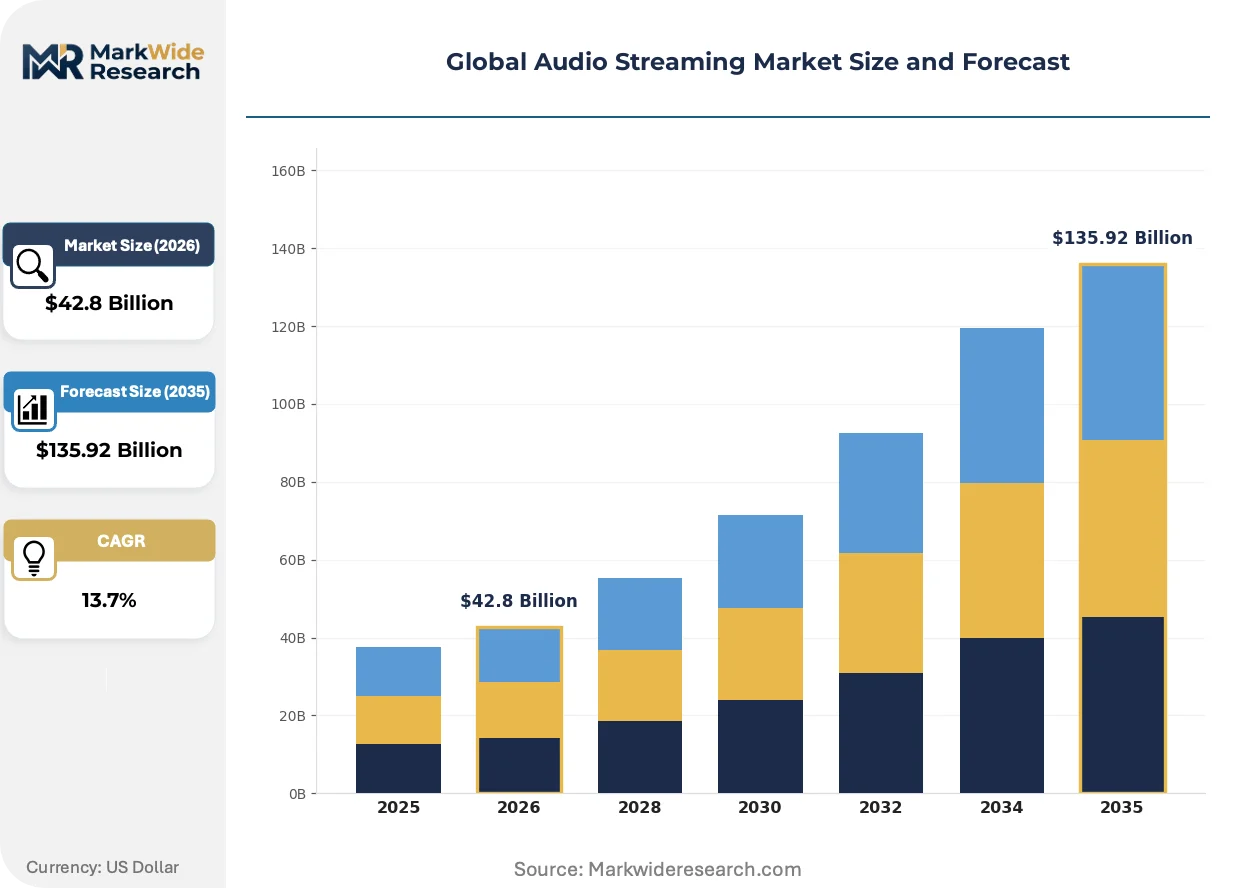
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $135.92 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smartphones, Smart Speakers, Computers, Tablets, Wearables Subscription Model: Freemium, Premium, Family Plan, Student Plan, Trial Content Type: Music, Podcasts, Audiobooks, Live Radio, News, Comedy End User: Individual Consumers, Content Creators, Educational Institutions, Corporate Clients, Event Organizers |
| Companies Covered | Spotify Technology S.A., Apple Inc., Amazon.com, Inc., Alphabet Inc., Tencent Music Entertainment Group, Deezer S.A., SoundCloud Global Limited & Co. KG, iHeartMedia, Inc., NetEase Cloud Music, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Audio Streaming Market Shifts & Advancements
Audio compression architectures and listener authentication methods are undergoing simultaneous reinvention as platforms balance fidelity claims against bandwidth economics and fraud prevention imperatives.
Lossless codec deployment is bifurcating platform technical roadmaps. Services now maintain parallel encoding ladders—compressed adaptive streams for mobile networks and fixed-bitrate PCM pipelines for Wi-Fi and automotive Ethernet. Audiophile subscriber segments in Japan and Germany are migrating to these tiers faster than projected, compressing the addressable market for standard-definition competitors.
GDPR Article 22 enforcement on automated decision-making is forcing recommendation engine redesigns. Platforms serving listeners in France and Spain must now expose logic pathways and enable human override options. Podcast and audiobook verticals face the steepest compliance costs due to longer content metadata requirements.
Consumption patterns in Brazil and Indonesia are rotating toward short-form audio and live social formats. Younger demographics are displacing album-oriented listening with creator-driven episodic content distributed through messaging app integrations. This channel shift is compressing traditional app store acquisition economics and forcing platform investment in lightweight SDK deployments.
Global Audio Streaming Market Segmentation
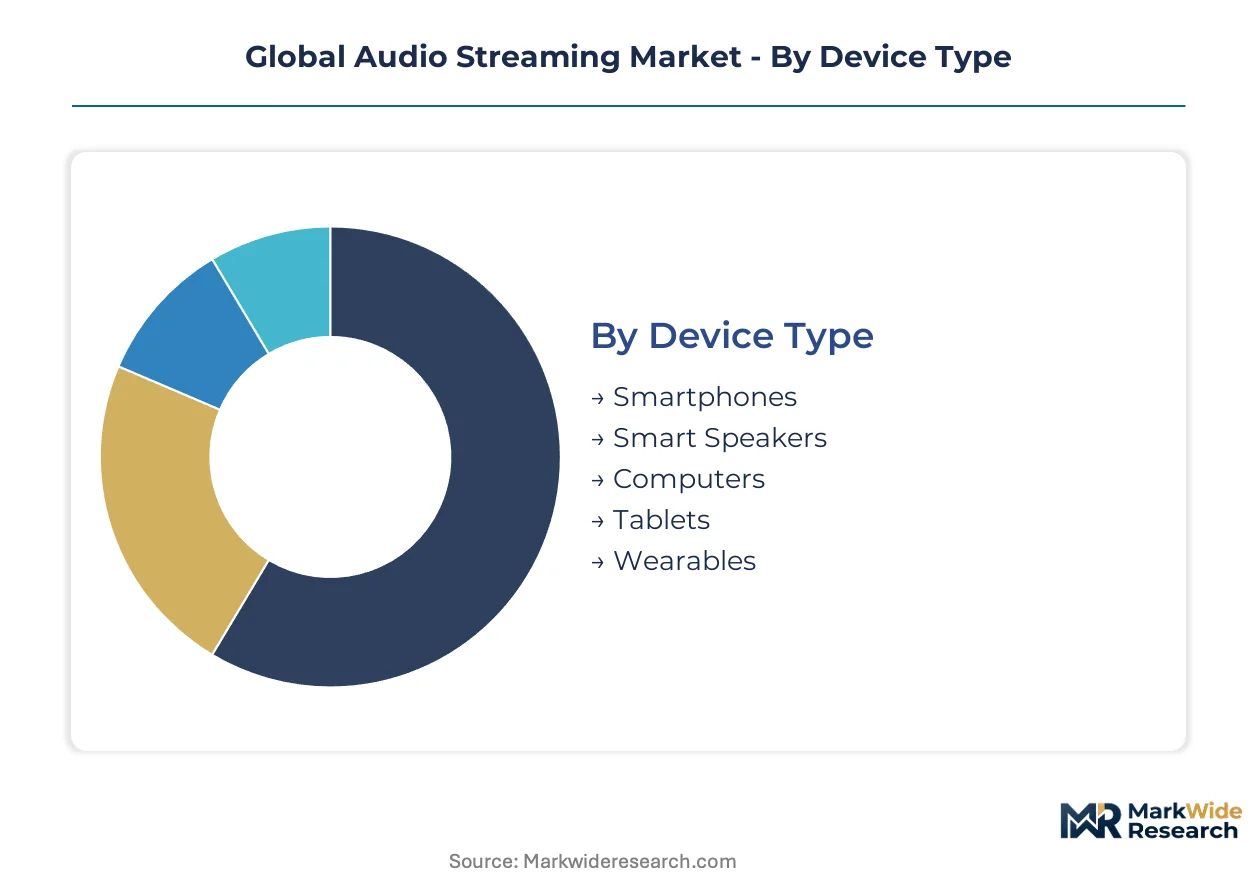
Streaming platforms architect their technical infrastructure and licensing strategies around distinct consumption modalities. Device capabilities, payment flexibility, content format, and user context each reshape server load patterns, royalty obligations, and customer lifetime value calculations differently.
Device Type:
Substitution pressure from automotive-native stacks is fragmenting smartphone dominance as OEMs bypass handset intermediaries.
- Smartphones:Adaptive bitrate algorithms scale from 96 kbps to lossless tiers based on cellular network conditions. Demand concentrates in India and Indonesia where low-cost data plans enable commuter consumption during mass transit hours.
- Smart Speakers:Far-field microphone arrays and voice-first interfaces shift query patterns toward ambient discovery rather than active search. Household penetration in Germany and Japan drives premium family plan attachment rates through multi-room audio synchronization.
- Computers:Desktop clients support hi-resolution PCM pipelines for audiophile segments. Professional use cases in content creation workflows sustain above-average session duration.
- Tablets:Larger screens enable synchronized lyric displays and video podcast consumption. Educational deployments in South Korean institutions drive institutional licensing growth.
- Wearables:Offline storage constraints and Bluetooth codec limitations compress available bitrates. Fitness-integrated applications in the United States expand through biometric-synced playlist generation.
Smartphones retain volume leadership; smart speakers hold the steepest expansion curve.
Subscription Model:
Payment tier architecture directly determines platform margin pools and content licensing leverage.
- Freemium:Ad-supported tiers monetize through programmatic audio insertion and display inventory. User acquisition economics in Brazil and Nigeria depend on telco-bundled data zero-rating agreements.
- Premium:Lossless and spatial audio capabilities justify price premiums in Japan and Germany. This segment commands disproportionate margin contribution relative to subscriber count.
- Family Plan:Multi-account provisioning reduces per-user revenue but extends household retention duration. Regulatory scrutiny from France's CNIL complicates geolocation verification for member eligibility.
- Student Plan:Verified enrollment discounts build brand preference before income maturation. University partnerships in the United Kingdom create direct billing relationships with educational institutions.
- Trial:Conversion rate optimization requires frictionless payment credential capture. Short trial windows in competitive markets like the United States compress onboarding funnel design cycles.
Premium tiers anchor profitability; family plans are climbing the fastest.
Content Type:
Format diversification reduces dependency on music licensing costs while extending session duration.
- Music:Interactive streaming mechanical royalties consume the majority of platform cost structures. Catalog depth requirements concentrate licensing negotiations with major labels in the United States and United Kingdom.
- Podcasts:Exclusive content deals and dynamic ad insertion unlock margin expansion. Creator-driven production in Brazil displaces album-oriented listening among younger demographics.
- Audiobooks:Per-title licensing models differ fundamentally from streaming economics. GDPR Article 22 compliance costs escalate due to extended content metadata requirements for recommendation transparency.
- Live Radio:FCC broadcast parity mandates in the United States open bundled distribution channels for digital-native platforms. Simulcast rights negotiations with terrestrial broadcasters vary by metropolitan market.
- News:Short-form episodic updates align with commute patterns and voice assistant queries. Publisher revenue-share arrangements in Germany face regulatory attention under EU copyright directives.
- Comedy:Stand-up catalogs and improvised formats build loyal repeat-listener cohorts. Live event ticketing integration creates ancillary revenue streams in the United Kingdom.
Music retains volume leadership; podcasts hold the steepest expansion curve.
End User:
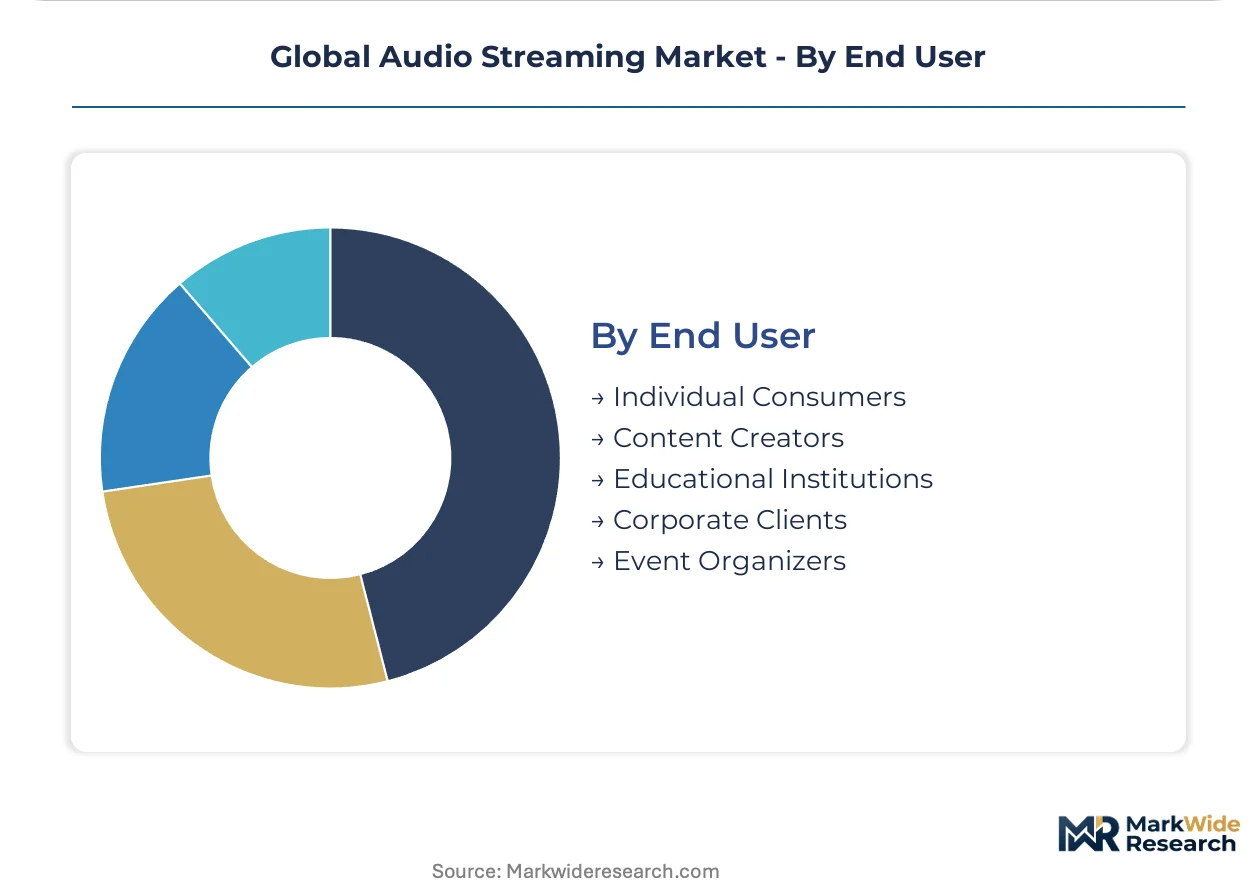
Customer context reshapes content curation, authentication requirements, and billing complexity.
- Individual Consumers:Personal listening histories drive recommendation engine training data accumulation. Privacy-conscious segments in France and Spain exercise GDPR-mandated human override options on automated playlists.
- Content Creators:Analytics dashboards and audience demographic tools support monetization optimization. Platform competition for exclusive podcast talent concentrates in the United States and United Kingdom.
- Educational Institutions:Curriculum-aligned catalog licensing and classroom management features require specialized contractual frameworks. Bulk pricing negotiations in South Korea and Japan follow fiscal year procurement cycles.
- Corporate Clients:Background music licensing for retail and hospitality environments operates under distinct performance rights structures. Mood-based playlist curation for brand alignment drives enterprise service tier development.
- Event Organizers:Temporary licensing for public performance and live streaming requires rapid rights clearance workflows. Festival applications in Brazil and Indonesia demand offline redundancy for connectivity-challenged venues.
Individual consumers retain volume leadership; educational institutions hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Swedish platforms export streaming infrastructure and licensing frameworks to Germany, the United Kingdom, and Brazil, establishing the primary trade-flow corridor for audio streaming technology and content distribution protocols.
United States
FCC broadcast parity mandates and exclusive podcast licensing wars drive platform consolidation. The IRA's digital infrastructure incentives support rural broadband expansion for streaming penetration. Los Angeles and New York anchor content production clusters where major labels negotiate interactive streaming mechanical rates.
Germany
Automotive OEMs in Stuttgart and Munich mandate native streaming APIs for infotainment systems. The KBA enforces data localization for connected vehicle telemetry affecting cross-border recommendation engines. Berlin's startup ecosystem concentrates voice biometric authentication development for in-car payment integration.
Japan
Hi-resolution audio adoption exceeds projections among audiophile subscribers in Tokyo and Osaka. METI's digital content export initiatives promote spatial audio codec licensing abroad. Kansai region manufacturing clusters supply automotive Ethernet hardware for lossless streaming pipelines.
Brazil
Short-form audio and creator-driven podcast formats displace album-oriented listening among younger demographics in São Paulo. ANVISA content classification rules intersect with streaming platform moderation workflows. Rio de Janeiro's creator economy clusters drive messaging app SDK integration for lightweight distribution.
India
Low-cost data plans and vernacular content gaps create white space for localized catalog investments in Mumbai and Bangalore. TRAI's net neutrality frameworks shape telco-bundled zero-rating agreements for freemium acquisition. Hyderabad's cloud infrastructure clusters support regional language recommendation engine training.
Global Audio Streaming Market Competitive Landscape
Listed leaders compete with private specialists across hardware-software integration and content exclusivity dimensions. The market exhibits tiered consolidation where scale-driven platforms, ecosystem-integrated technology giants, and regional specialists coexist. Three archetypes dominate: audio-first streaming pure-plays, device-anchored ecosystem providers, and commerce-integrated bundlers. Competitive moves concentrate on exclusive content licensing and automotive-native stack deployment.
Within the audio-first tier, Spotify Technology S.A. and Deezer S.A. exemplify platform-centric models dependent on subscription scale and podcast infrastructure investment. Apple Inc. and Amazon.com, Inc. occupy positions as ecosystem-anchored competitors leveraging hardware integration and membership bundling respectively. Tencent Music Entertainment Group represents the regional specialist archetype with concentrated presence in Chinese-language markets.
| Leading Market Players |
|---|
| Spotify Technology S.A. |
| Apple Inc. |
| Amazon.com, Inc. |
| Alphabet Inc. |
| Tencent Music Entertainment Group |
| Deezer S.A. |
| SoundCloud Global Limited & Co. KG |
| iHeartMedia, Inc. |
| NetEase Cloud Music |
| Others |
Supply & Pricing Matrix
Per-stream royalty licensing frameworks lock in content access costs while compressing margin visibility for platforms negotiating with collective management organizations. These contractual structures tether pricing power to mechanical rate determinations in the United States and United Kingdom, forcing services to rebuild cost models around unpredictable rights-holder negotiations.
Pricing Analysis
Lossless-tier pricing gaps separate current-generation hi-resolution subscriptions from standard compressed tiers and emerging spatial audio bundles. Three-tier pricing structure across premium, standard, and economy levels dominates subscription architecture, with spatial audio capabilities and automotive integration driving premium differentiation. Price differentiation hinges on codec quality certification and exclusive content licensing depth. Cost compression in freemium tiers is intensifying because programmatic audio ad rates face demand softness from brand safety concerns. Individual consumers in India and Indonesia exhibit highest price sensitivity, while audiophile segments in Japan and Germany accept substantial premiums for lossless fidelity.
Supply Chain Analysis
Just-in-time content delivery preferences dominate streaming infrastructure, with platforms maintaining minimal buffer inventory against real-time listener demand spikes. Hyperscaler concentration in the United States, Ireland, and Singapore anchors cloud egress capacity for high-bitrate tiers. Raw material dependencies center on semiconductor components for automotive Ethernet hardware, optical transmission equipment, and edge server deployments. Single-source vulnerability runs through three hyperscalers controlling essential CDN infrastructure. Distribution runs through direct-to-consumer app stores, OEM-embedded automotive stacks, and telco-bundled zero-rating partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of MLops specialists capable of optimizing recommendation engines under GDPR Article 22 constraints is reshaping competitive access. Platforms securing this talent pool gain decisive algorithmic transparency advantages.
For Market Incumbents: Consolidate exclusive podcast and audiobook catalogs to reduce mechanical royalty exposure while extending session duration. Deepen automotive integration partnerships with German and Japanese OEMs to secure native stack placement before smartphone bypass becomes universal. Lock in long-term cloud capacity reservations with hyperscalers to hedge egress cost volatility. For New Entrants and Emerging Players: Anchor in India's vernacular content gaps and Brazil's creator-driven podcast economy where incumbents maintain lighter catalog investments. Target educational institutional licensing in South Korea and Japan where procurement cycles favor specialized classroom management features. Pursue white-label SDK deployments for messaging app integrations capturing short-form audio consumption shifts. For Investors and Strategic Acquirers: The market sits at a platform consolidation phase that favors audio-first pure-plays with podcast infrastructure and regional specialists with localized recommendation engines. Long-term viability rests on automotive-native stack penetration and generative audio licensing clarity. Acquisition focus should center on voice biometric authentication specialists and spatial audio codec developers. Watch for inflection when EU AI Act enforcement costs trigger distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-Native Stack Deployment | Bypassing smartphone intermediaries secures OEM integration mandates from German and Japanese manufacturers. |
| Exclusive Content Licensing | Podcast and audiobook deals reduce mechanical royalty burden while extending listener session duration metrics. |
| Spatial Audio Codec Investment | Premium tier pricing power in Tokyo and Osaka audiophile segments justifies R&D allocation. |
| Algorithmic Transparency Tooling | GDPR Article 22 compliance creates enterprise licensing opportunities from competitors facing retrofit delays. |
| Vernacular Catalog Localization | Hyderabad-trained recommendation engines capture Mumbai and Bangalore listener bases underserved by global platforms. |
Research Methodology
Operator-level perspectives from streaming platform CTOs, automotive OEM infotainment architects, collective management organization licensing directors, and telco partnership executives anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, App Annie mobile engagement data, hyperscaler capex disclosures, and FCC broadcast parity regulatory records. Bottom-up subscriber and revenue modeling triangulated against top-down market sizing from trade flow analysis.
Sensitivity analysis tested forecast robustness across mechanical royalty rate scenarios, cloud egress cost inflation bands, and automotive penetration trajectories. Segmentation dimensions modeled include device type, subscription tier, content format, end-user context, and regional regulatory cluster across the analysis window. CAGRs derived from regression analysis of historical adoption curves adjusted for smartphone saturation effects and connected vehicle infotainment integration rates. Spatial audio codec deployment timelines and GDPR compliance cost curves served as industry-specific forecast inputs.
Material uncertainties — mechanical royalty rate determinations by United States and United Kingdom collective management organizations, generative audio training data licensing resolutions, and hyperscaler pricing power consolidation — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory enforcement intensity and automotive OEM integration timelines. Revision becomes warranted when cloud egress cost concentration crosses thresholds triggering platform margin collapse or when EU AI Act penalties force algorithmic architecture rebuilds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Media and Entertainment
Music Publishing Market
Media and Entertainment
Chile OOH and DOOH Market
Media and Entertainment
Performing Art Companies Market
Media and Entertainment
Podcast Hosting Services Market
Media and Entertainment
South Korea OOH and DOOH Market
Media and Entertainment
South East Asia Advertising Market
Media and Entertainment
3D Anaglyph Glasses Market
Media and Entertainment
Virtual Events Market
Media and Entertainment
Music Synthesizers Market
Media and Entertainment
Global Exhibition Market
Media and Entertainment
Metaverse Social Media Platforms Market
Media and Entertainment
North America Immersive Entertainment Market
Media and Entertainment
Global Programmatic Advertising Platform Market
Media and Entertainment
North America Online Gambling Market
Media and Entertainment
Global Electronic Table Games (ETG) Market
Media and Entertainment
Media Streaming Market