
 Digital Video Content Market | 2026-2036
Digital Video Content Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Video Content Market Intelligence
Studio-grade production capacity in South Korea is broadening the supply of K-drama and K-pop video content for global distribution. Netflix leverages its localized content strategy to sustain subscriber engagement across Latin America and Southeast Asia. The Walt Disney Company anchors its streaming portfolio through exclusive franchise rights and family-oriented programming libraries. Alphabet Inc. competes via YouTube's dual revenue engine combining creator monetization with programmatic advertising.
Digital video content encompasses encoded audiovisual media delivered through internet protocol networks, typically compressed using H.264, H.265, or AV1 codecs with adaptive bitrate streaming to optimize playback across variable bandwidth conditions. Its primary commercial purpose spans entertainment consumption, brand advertising, corporate communication, and educational instruction. OTT services occupy the highest-margin tier of platform type segmentation due to recurring subscription revenue and direct customer relationships. Ad-supported models dominate total viewership hours but command lower per-user monetization rates than subscription tiers. Live streaming represents the fastest-expanding content type as sports leagues, gaming tournaments, and real-time commerce events expand audience participation.
The Federal Communications Commission in the United States enforces closed captioning and accessibility standards that shape technical delivery requirements for domestic platforms. The EU Digital Services Act and GDPR collectively mandate algorithmic transparency and data protection protocols that increase operational complexity for services operating across European markets. India's Ministry of Information and Broadcasting exercises content oversight through intermediary guidelines that affect catalog availability and takedown procedures. Stakeholders must monitor evolving cross-border data localization rules and their impact on content delivery network architecture and licensing negotiations.
Market Dynamics
Enterprise training budgets are reallocating toward modular video formats as workforce upskilling mandates intensify, while the EU Digital Services Act imposes new content moderation obligations that reshape platform operating costs.
Growth Catalysts
- AV1 codec adoption:Streaming platforms deploy royalty-free compression to reduce bandwidth expenditure and improve playback quality across emerging markets with constrained infrastructure.
- India's regional language content surge:Domestic and international platforms accelerate subscriber acquisition through localized production in Hindi, Tamil, Telugu, and Malayalam.
- EU Digital Services Act compliance:Algorithmic transparency mandates create competitive differentiation for platforms investing in human moderation and explainable recommendation systems.
Market Restraints
- Content delivery network concentration:Three hyperscale cloud providers control critical edge infrastructure, creating single-point vulnerability for platform uptime and cost negotiation leverage.
- GDPR cross-border data friction:European data localization requirements complicate content licensing and subscriber data management for services operating across multiple jurisdictions.
- Live streaming infrastructure capex:Ultra-low latency encoding and edge processing demands strain platform capital allocation between technology and content acquisition.
Strategic Opportunities
- Real-time commerce integration:Live shopping formats in Southeast Asia demonstrate monetization models combining entertainment with transactional functionality.
- Accessibility mandate alignment:FCC closed captioning standards in the United States create exportable compliance frameworks for platforms entering regulated markets.
- AI-generated localization:Synthetic dubbing and automated subtitling reduce time-to-market for content distribution across linguistically fragmented subscriber bases.
Industry Challenges
- Moderation workforce scaling:Platform operators struggle to recruit and retain linguistically diverse content reviewers capable of handling regional nuance and cultural context.
- Legacy rights management system integration:Historical licensing databases lack API compatibility with modern subscription management platforms, creating billing and territorial enforcement errors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Video Content Market |
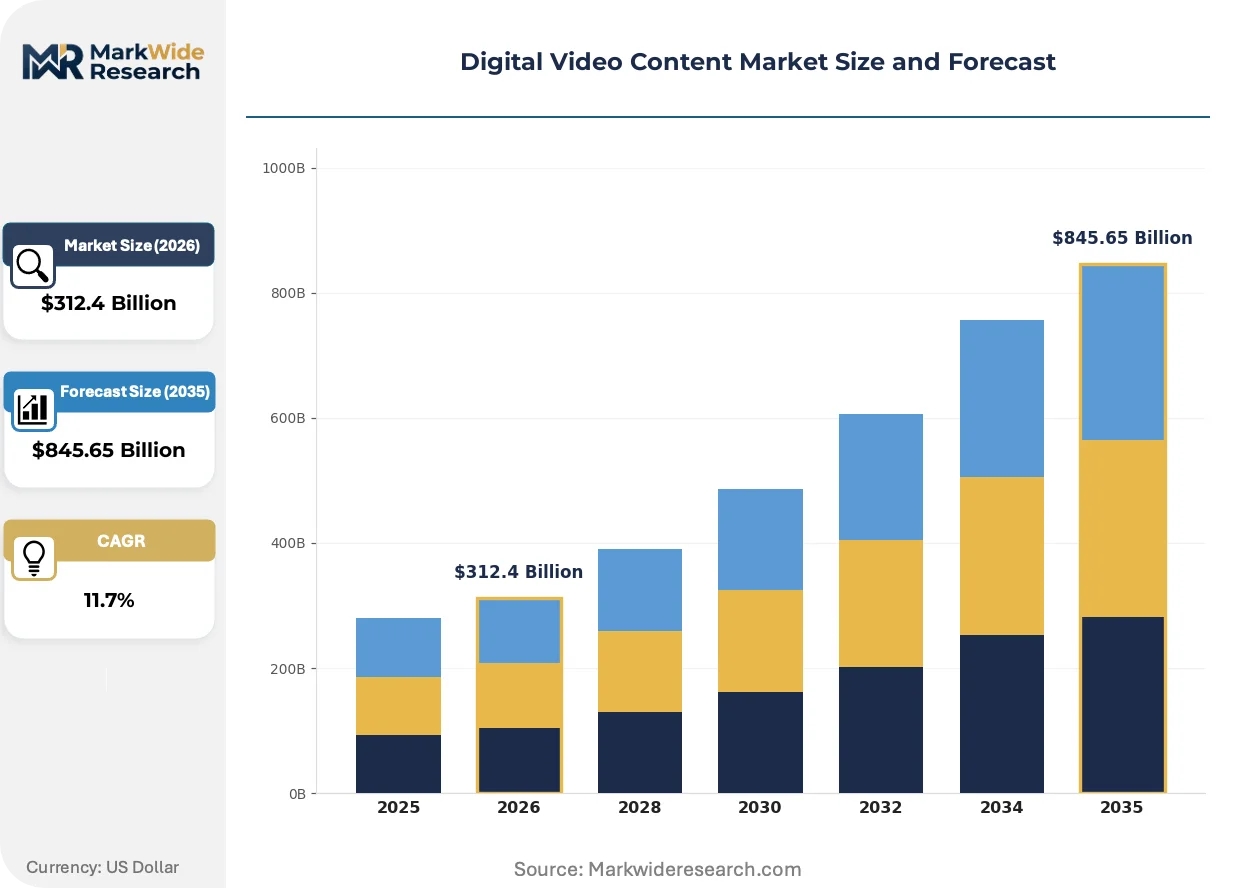
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $845.65 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Live Streaming, Video-on-Demand, Short Clips, User-Generated Content Platform Type: Social Media, OTT Services, Video Sharing Websites, E-Learning Platforms End User: Consumers, Advertisers, Marketers, Enterprises Monetization Model: Subscription, Ad-Supported, Pay-Per-View, Freemium |
| Companies Covered | Netflix, Amazon.com, Inc., Apple Inc., The Walt Disney Company, Alphabet Inc., Hulu, LLC, Comcast, Google LLC, Tencent Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Video Content Market Strategic Shifts & Innovations
Codec evolution and regulatory transparency mandates are compressing technical delivery costs while expanding addressable audience segments through accessibility and localization capabilities.
AV1 encoding is integrating across major streaming infrastructure as the royalty-free alternative to HEVC, reducing per-stream delivery costs for ad-supported tiers. Platform operators in Latin America and Southeast Asia adopt AV1 to maintain quality thresholds over variable mobile networks. This compression efficiency is integrating lower-bandwidth markets into viable subscriber acquisition territories previously excluded by infrastructure constraints.
The EU Digital Services Act mandates algorithmic transparency and risk assessment protocols for platforms exceeding threshold user bases. Content recommendation systems must now provide explanatory interfaces and audit trails for regulatory inspection. Video services operating across European markets restructure engineering teams to embed compliance documentation into product development cycles.
Subscription fatigue among entertainment consumers drives experimentation with hybrid monetization combining tiered access with transactional video-on-demand. Sports leagues and premium event producers lead this pivot, unbundling season-long commitments into per-match or per-tournament purchases. This behavioral shift concentrates in North American and Western European markets where household streaming expenditure has approached saturation thresholds.
Digital Video Content Market Segmentation
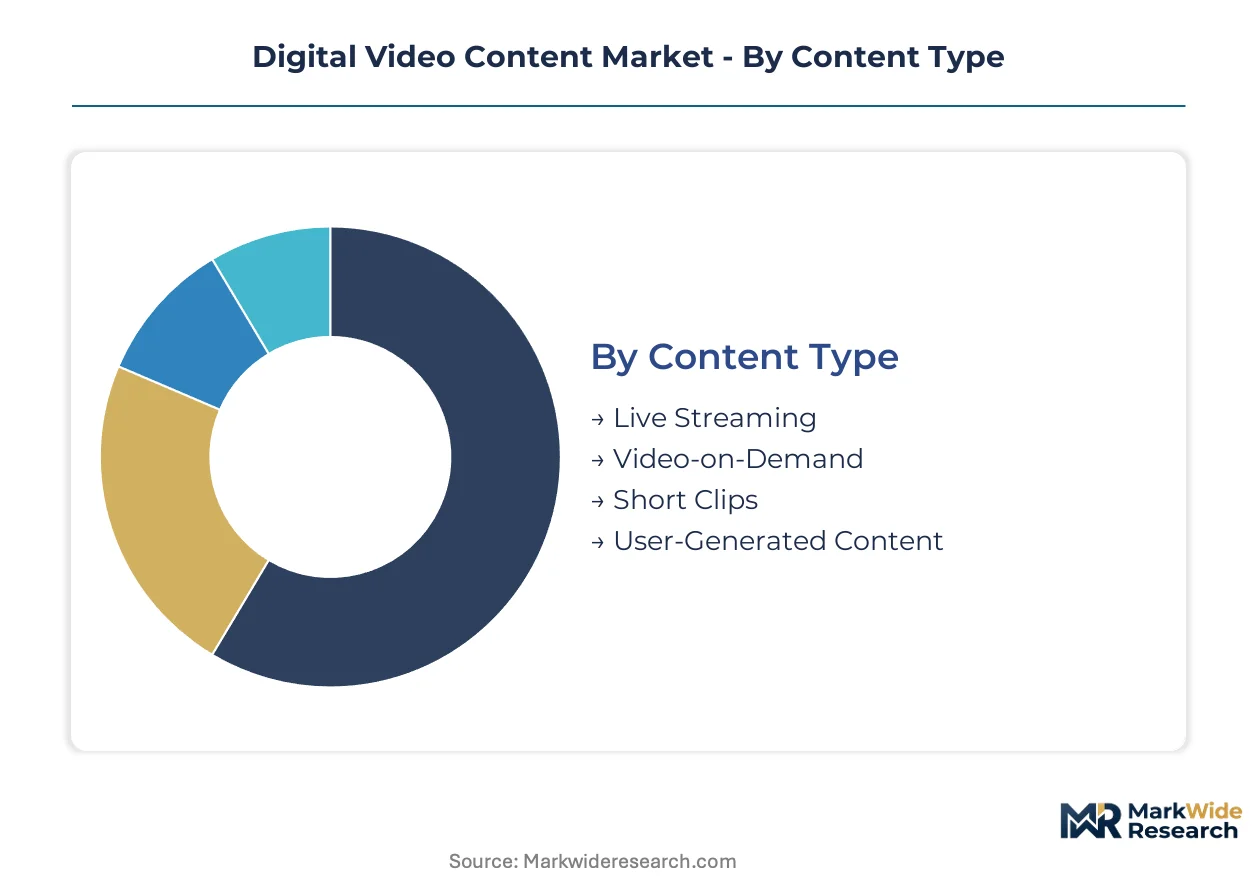
Segmentation in digital video content reveals how regulatory obligations, infrastructure requirements, and monetization mechanics fragment addressable markets. Platform operators must align technical architecture and compliance investments with the specific demands of each content and delivery category.
Content Type:
Certification burdens vary sharply across content categories, with live streaming triggering the most complex compliance obligations under FCC closed captioning mandates and EU Digital Services Act real-time moderation requirements.
- Live Streaming:Real-time audiovisual transmission demands ultra-low latency encoding infrastructure and immediate content moderation capabilities. Sports leagues and gaming tournaments in Brazil and Saudi Arabia drive demand, though bandwidth constraints in emerging markets limit addressable audience scale.
- Video-on-Demand:Pre-encoded libraries distributed through adaptive bitrate streaming optimize for variable network conditions. Subscriber acquisition concentrates in India, where regional language dubbing investments expand catalog accessibility beyond English-speaking urban centers.
- Short Clips:Sub-60-second formats optimized for mobile consumption and algorithmic recommendation feeds. Platform operators in Southeast Asia prioritize these for real-time commerce integration.
- User-Generated Content:Unscripted material uploaded by individual creators requires scalable moderation workflows and rights management systems. GDPR compliance complexity elevates operational costs for European market participation.
Video-on-Demand sits at the top of the volume ranking, with Live Streaming climbing the fastest.
Platform Type:
Margin structures diverge substantially across platform architectures, with recurring subscription revenue commanding premium valuations against advertising-dependent models.
- OTT Services:Direct-to-consumer subscription platforms with exclusive content licensing and proprietary recommendation algorithms. The Walt Disney Company and Netflix anchor this tier through franchise IP and localized production investments in South Korea and Mexico.
- Social Media:Algorithmic feeds integrating user-generated and professional content with programmatic advertising. Meta Platforms and ByteDance compete through engagement optimization and creator monetization tools.
- Video Sharing Websites:Open-upload repositories combining professional, amateur, and hybrid content formats. YouTube's dual revenue engine blends creator payments with advertiser demand.
- E-Learning Platforms:Structured instructional content delivered through modular video sequences. Corporate training budgets in Germany and the United States reallocate toward these formats as workforce upskilling mandates intensify.
OTT Services capture the highest margin tier, while E-Learning Platforms demonstrate the steepest expansion trajectory.
End User:
Customer procurement patterns split between individual consumption decisions and enterprise purchasing committees with extended vendor evaluation cycles.
- Consumers:Individual subscribers and ad-supported viewers making discretionary entertainment purchases. Subscription fatigue in North American households drives experimentation with hybrid monetization models.
- Advertisers:Brand and performance marketers purchasing inventory through programmatic auctions or direct deals. Demand concentrates among consumer packaged goods companies seeking measurable reach.
- Marketers:In-house and agency teams producing branded content and sponsorship integrations. Short-form vertical video commands premium placement fees for product demonstration.
- Enterprises:Organizations deploying video for internal communication, training, and external stakeholder engagement. Compliance documentation requirements elevate procurement scrutiny in regulated industries.
Consumers constitute the largest addressable base, with Enterprises gaining share fastest.
Monetization Model:
Revenue predictability and customer lifetime value calculations vary fundamentally across pricing architectures, shaping platform capital allocation between technology and content.
- Subscription:Recurring monthly or annual fees granting catalog access without advertising interruption. Churn management and price elasticity testing dominate operational priorities.
- Ad-Supported:Free or reduced-cost access funded by programmatic and direct-sold advertising. Lower per-user monetization rates require massive scale for profitability.
- Pay-Per-View:Transactional access to individual titles or events without ongoing commitment. Sports leagues unbundle season-long packages into per-match purchases.
- Freemium:Tiered access combining free advertising-supported entry with premium subscription upgrades. Conversion funnel optimization determines unit economics.
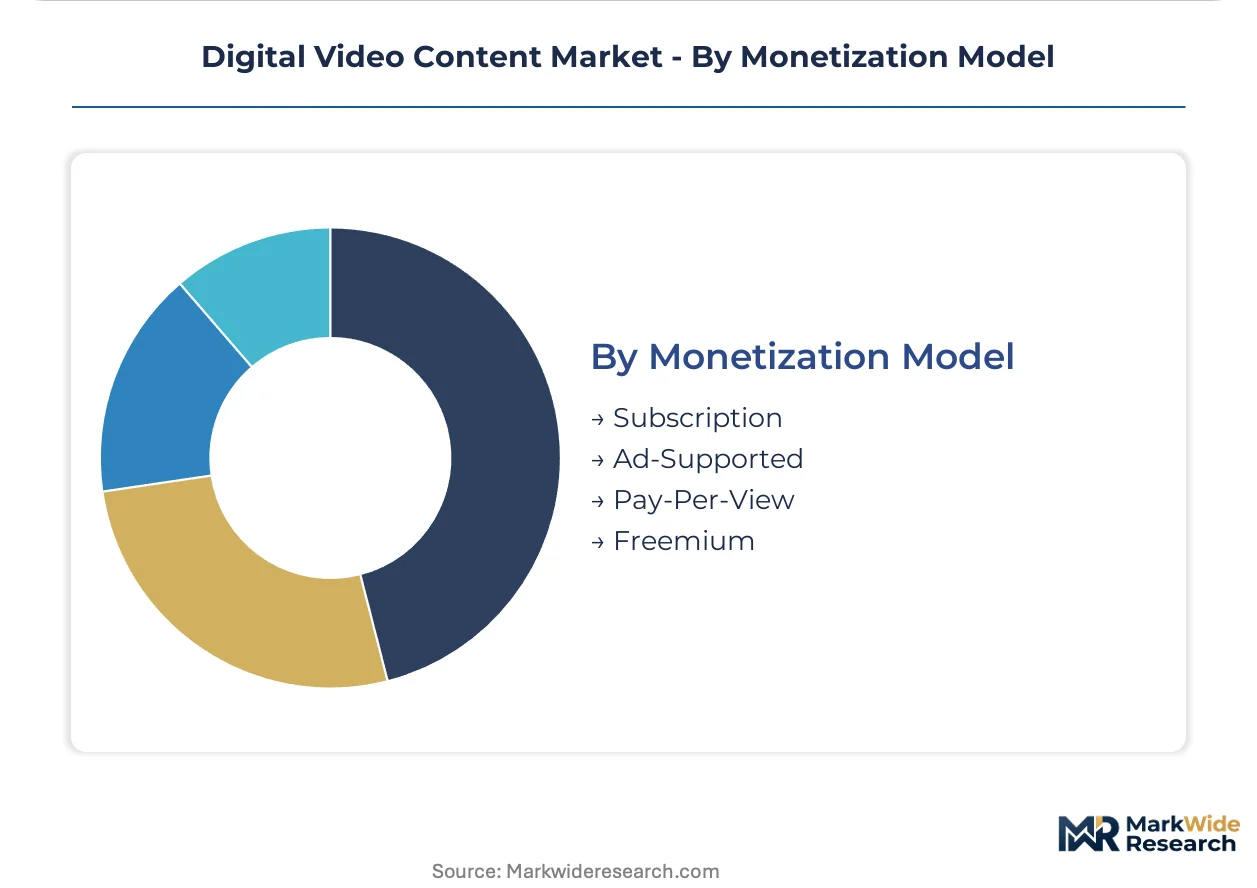
Ad-Supported models dominate total viewership hours, with Subscription demonstrating the most durable revenue expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping where video infrastructure investment concentrates, as platforms seek jurisdictions with moderate compliance burdens and robust connectivity ecosystems. Production capacity migrates toward markets offering streamlined content licensing frameworks and favorable data localization terms.
United States
Enterprise training procurement and sports streaming rights auctions drive platform revenue concentration. The FCC enforces closed captioning and accessibility standards that shape technical delivery requirements for domestic services. Los Angeles and New York anchor studio production clusters where franchise IP development and original content commissioning accelerate.
South Korea
K-drama and K-pop content exports sustain subscriber acquisition for global platforms seeking Asian-language catalog depth. The country's national broadcasting regulator maintains content rating systems that affect distribution windows. Seoul's Gangnam district concentrates post-production facilities and talent management agencies serving international co-production deals.
India
Regional language content creation in Hindi, Tamil, Telugu, and Malayalam accelerates subscriber growth for domestic and international platforms. The Ministry of Information and Broadcasting exercises content oversight through intermediary guidelines affecting catalog availability. Mumbai and Hyderabad host production hubs where localized original series command premium licensing fees.
Germany
Corporate e-learning procurement and public service broadcasting digitization sustain platform engagement. GDPR cross-border data requirements complicate subscriber data management for services operating across European markets. Berlin and Munich anchor technology development clusters where streaming infrastructure and compliance tooling converge.
Brazil
Live sports streaming and Portuguese-language original production attract platform investment despite bandwidth constraints in northern regions. The country's national telecommunications regulator oversees streaming quality standards and net neutrality enforcement. São Paulo concentrates advertising technology development and creator economy infrastructure serving Latin American markets.
Digital Video Content Market Key Industry Players
United States-based technology conglomerates anchor one tier through integrated hardware-software-content ecosystems; South Korean and Chinese specialists hold regional distribution advantages through localized production investments. Market structure tilts toward oligopoly with subscription platforms commanding premium valuations against advertising-dependent models. Three strategic archetypes dominate: vertically integrated entertainment conglomerates, algorithmic feed operators, and enterprise-focused training platforms. Competitive moves concentrate on exclusive content licensing and geographic expansion through localized production commitments.
Within the vertically integrated tier, Netflix and The Walt Disney Company exemplify archetypes built on franchise IP exclusivity and direct subscriber relationships. Alphabet Inc. occupies a position spanning both consumer entertainment and enterprise communication through dual revenue engines. Tencent Holdings Limited represents the regional platform model with distribution advantages in Chinese-language markets. These anchors illustrate how scale, localization depth, and regulatory compliance capabilities determine competitive positioning across fragmented national markets.
| Leading Market Players |
|---|
| Netflix |
| Amazon.com, Inc. |
| Apple Inc. |
| The Walt Disney Company |
| Alphabet Inc. |
| Hulu, LLC |
| Comcast |
| Google LLC |
| Tencent Holdings Limited |
| Others |
Cost & Logistics Intelligence
Bandwidth expenditure from content delivery networks flows through platform pricing tiers, compressing margins on ad-supported tiers while subscription services absorb infrastructure costs through recurring revenue predictability.
Pricing Analysis
Distributor margin layering separates OTT subscription tiers from ad-supported and transactional models. Three-tier pricing structure across premium, standard, and economy levels reflects content exclusivity and concurrent stream limits. Price differentiation hinges on 4K streaming certification and regional content library depth. Pricing pressure stems from AV1 codec adoption reducing delivery costs, forcing legacy platforms to match quality thresholds without subscription price increases. Ad-supported viewers exhibit highest price sensitivity, while enterprise training procurement demonstrates lowest elasticity due to compliance documentation requirements.
Supply Chain Analysis
Certification gating through FCC closed captioning and EU Digital Services Act compliance elevates vendor qualification barriers for encoding infrastructure providers. Supply concentrates in the United States, South Korea, and India for studio production and post-production services. Raw material dependencies span cloud compute instances, edge server hardware, and licensed music catalogs. Single-source vulnerability runs through three hyperscale cloud providers controlling critical edge infrastructure. Distribution runs through direct platform relationships with content creators and intermediary licensing aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital video content functions as a stable compounder, with enterprise training budgets and regional localization investments sustaining recurring revenue expansion across economic cycles.
For Market Incumbents: Lock in exclusive franchise IP through long-term licensing renewals and in-house production capacity in South Korea and Mexico. Deepen backward integration into cloud infrastructure to reduce hyperscale provider dependency. Counter emerging platform entrants by embedding EU Digital Services Act compliance documentation into product development cycles as a competitive moat.
For New Entrants and Emerging Players: EU Digital Services Act transparency mandates in Europe open a window for mid-tier platforms investing in explainable recommendation systems and human moderation workflows. Target India's regional language content segments in Tamil and Telugu where subscriber acquisition costs trail Hindi-language competition. Pursue white-label e-learning platform partnerships with German and US corporate training procurement committees.
For Investors and Strategic Acquirers: Consolidation pressure builds where legacy rights management systems lack API compatibility with modern subscription platforms. Position acquisition screening around targets with proprietary localization technology and established regulatory compliance documentation. Monitor AV1 codec integration milestones as inflection indicators for infrastructure cost compression and margin expansion potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Localized Content Production | Netflix and Disney sustain subscriber engagement through Korean and Mexican original series commissioning. |
| Codec Infrastructure Migration | AV1 adoption reduces bandwidth expenditure for platforms serving Latin American and Southeast Asian markets. |
| Regulatory Compliance Tooling | EU Digital Services Act mandates force restructuring of engineering teams for algorithmic transparency documentation. |
| Enterprise Training Platform Integration | E-learning modules capture reallocated workforce upskilling budgets in Germany and the United States. |
| Live Commerce Format Development | Southeast Asian platforms monetize real-time shopping events through transactional functionality embedded in streaming. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with streaming platform executives, content licensing directors, cloud infrastructure procurement leads, and regulatory compliance officers with secondary validation against SEC filings, FCC rulemaking dockets, EU Digital Services Act implementation guidance, and hyperscaler capex disclosures. Bottom-up subscriber and revenue estimates triangulated against top-down market sizing from trade data and platform financial disclosures.
Segment-weighting approaches distributed value across content type, platform architecture, end-user category, and monetization model dimensions. CAGRs derived from regression analysis against broadband penetration curves, smartphone adoption trajectories, and enterprise training expenditure trends. Forecast inputs incorporated codec adoption rates, regulatory implementation timelines, and regional content production capacity expansion.
Revisions become necessary when EU Digital Services Act enforcement intensity, cross-border data localization rulings, or hyperscale cloud provider pricing changes materialize outside modeled scenarios. A model refresh is warranted upon material change in AV1 codec hardware decoding penetration or enterprise training procurement centralization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Media
Wedding Photography Market
Digital Media
VFX Market
Digital Media
Video Player Market
Digital Media
Europe Animation Market
Digital Media
In Flight Entertainment Market
Digital Media
Middle East Movies and Entertainment Market
Digital Media
ACGN Subculture Market
Digital Media
Secondary Ticket Market
Digital Media
Global Location-Based Entertainment Market
Digital Media
Animation Services Market
Digital Media
Global Digital Painting Market
Digital Media
Naruto Around Market
Digital Media
Global Stock Video Market
Digital Media
Digital Music Content Market
Digital Media
Art App Market
Digital Media
Digital Media Market