
 Pay TV Operator Market | 2026-2036
Pay TV Operator Market Size, Share, and Industry Trends Forecast 2026-2036
Pay TV Operator Market Analytics
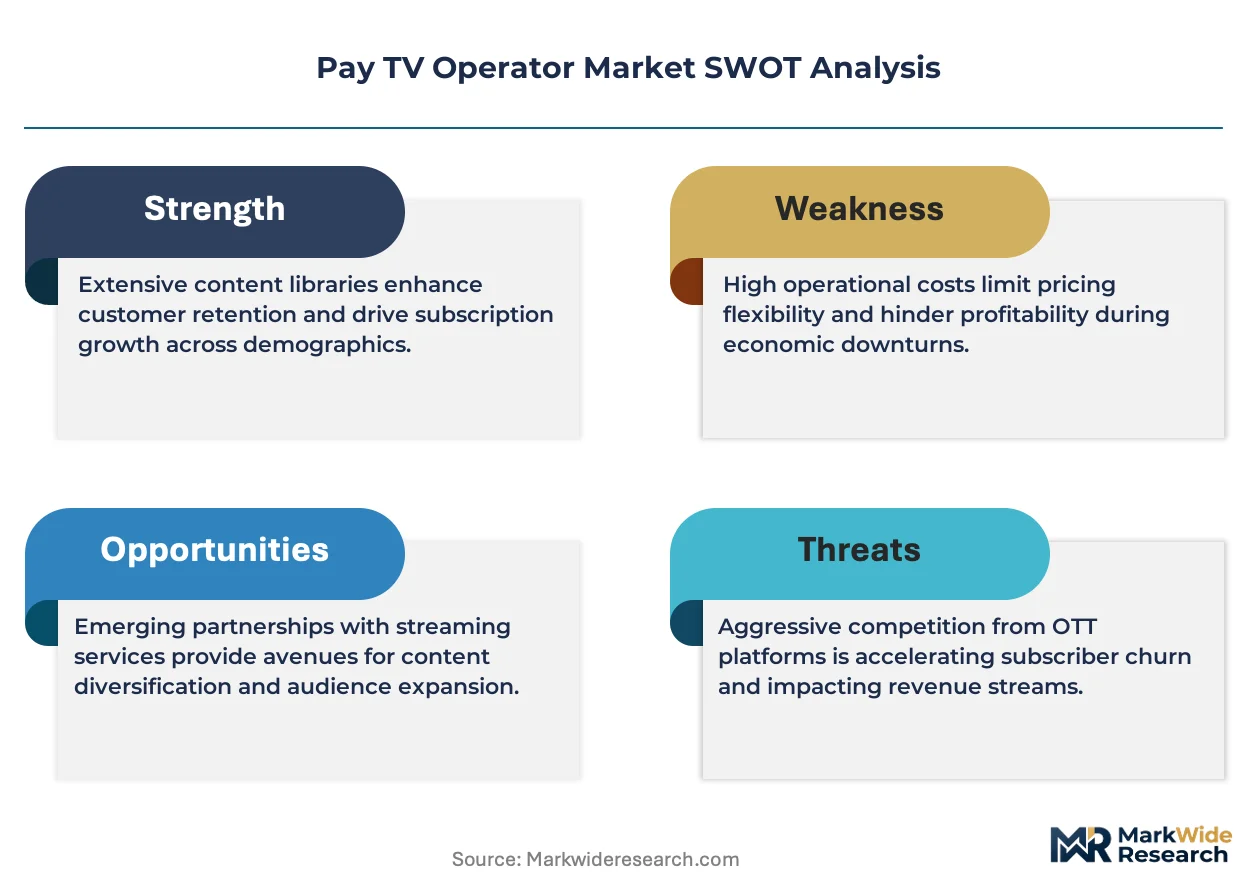
A shift from single-source linear carriage to multi-source streaming aggregation is pivoting how operators license programming. Comcast leverages its broadband infrastructure to anchor hybrid cable-streaming bundles. YouTube TV competes through nationwide sports rights and unlimited cloud DVR. Charter sustains regional dominance by controlling last-mile cable plant while layering streaming apps atop its pipe.
Pay TV operators distribute linear and on-demand video content to subscribers through managed networks or over-the-top delivery, typically requiring conditional access systems, content delivery networks, and set-top boxes or authenticated applications. The primary commercial purpose is aggregating programming from broadcasters, studios, and sports leagues into subscription packages that reduce consumer search and switching costs. Monthly subscription and bundled plans command the largest revenue pools as consumers prefer predictable billing over pay-per-view friction. Online streaming delivery captures the fastest structural growth as IPTV and vMVPD platforms displace legacy coaxial and satellite distribution. Live sports content type generates disproportionate subscriber retention despite escalating rights fees that compress operator margins.
The FCC governs retransmission consent negotiations and local station carriage obligations in the United States, while the FTC scrutinizes bundling practices and streaming joint ventures for anticompetitive effects. These frameworks determine which channels reach subscribers and at what wholesale cost, directly shaping operator profitability and package design. Stakeholders must monitor whether broadband-centric operators can maintain video subscriber economics as sports leagues increasingly explore direct-to-consumer bypass options.
Market Dynamics
The structural force reshaping Pay TV operators is the wholesale migration of video consumption from linear broadcast to IP-based streaming delivery, which collapses the traditional carriage fee economics that sustained bundled channel tiers for decades.
Growth Catalysts
- vMVPD Platform Adoption:Virtual multichannel video programming distributors aggregate broadcast and cable networks into cloud-delivered packages that retain sports and news while eliminating hardware rental fees, pulling former satellite households back into managed subscriptions.
- FCC Must-Carry Revisions:The Federal Communications Commission's updated retransmission consent framework creates negotiation leverage for operators seeking to trim redundant local broadcast duplicates from bloated basic tiers.
- Broadband Infrastructure Densification:Fiber-to-the-home and DOCSIS 3.1 upgrades in the United States enable 4K streaming to multiple screens simultaneously, removing the quality gap that once protected satellite distribution.
Market Restraints
- Sports Rights Fee Inflation:Live NFL, NBA, and MLB carriage costs consume 40-60% of programming budgets, compressing operator margins even as per-subscriber revenue flatlines.
- Content Owner Direct-to-Consumer Bypass:Disney, Paramount, and Warner Bros. Discovery operate standalone streaming apps that peel away exclusive programming from wholesale licensing deals.
- Linear Subscriber Depreciation:Legacy coaxial and satellite plant carry fixed maintenance costs across shrinking addressable bases, stranding capital in declining distribution modes.
Strategic Opportunities
- Rural Broadband-Video Bundling:USDA Rural Utilities Service grants and FCC Rural Digital Opportunity Fund subsidies enable operators to extend fiber plant into underserved counties where satellite previously held monopoly.
- Addressable Advertising Integration:Convergence of set-top box viewing data with programmatic ad platforms allows operators to compete for local advertising budgets previously captured by Google and Meta.
- Smart Home Service Layering:Security monitoring, energy management, and elder care applications ride the same in-home network infrastructure, diversifying revenue per household beyond video.
Industry Challenges
- Conditional Access System Migration:Replacing legacy CableCARD and satellite smart card security with cloud-based DRM requires simultaneous app development across iOS, Android, Roku, and proprietary set-top environments.
- Call Center Retraining Burden:Customer service workflows designed around channel lineup disputes and technician dispatch must pivot to streaming app troubleshooting and Wi-Fi diagnostics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pay TV Operator Market |
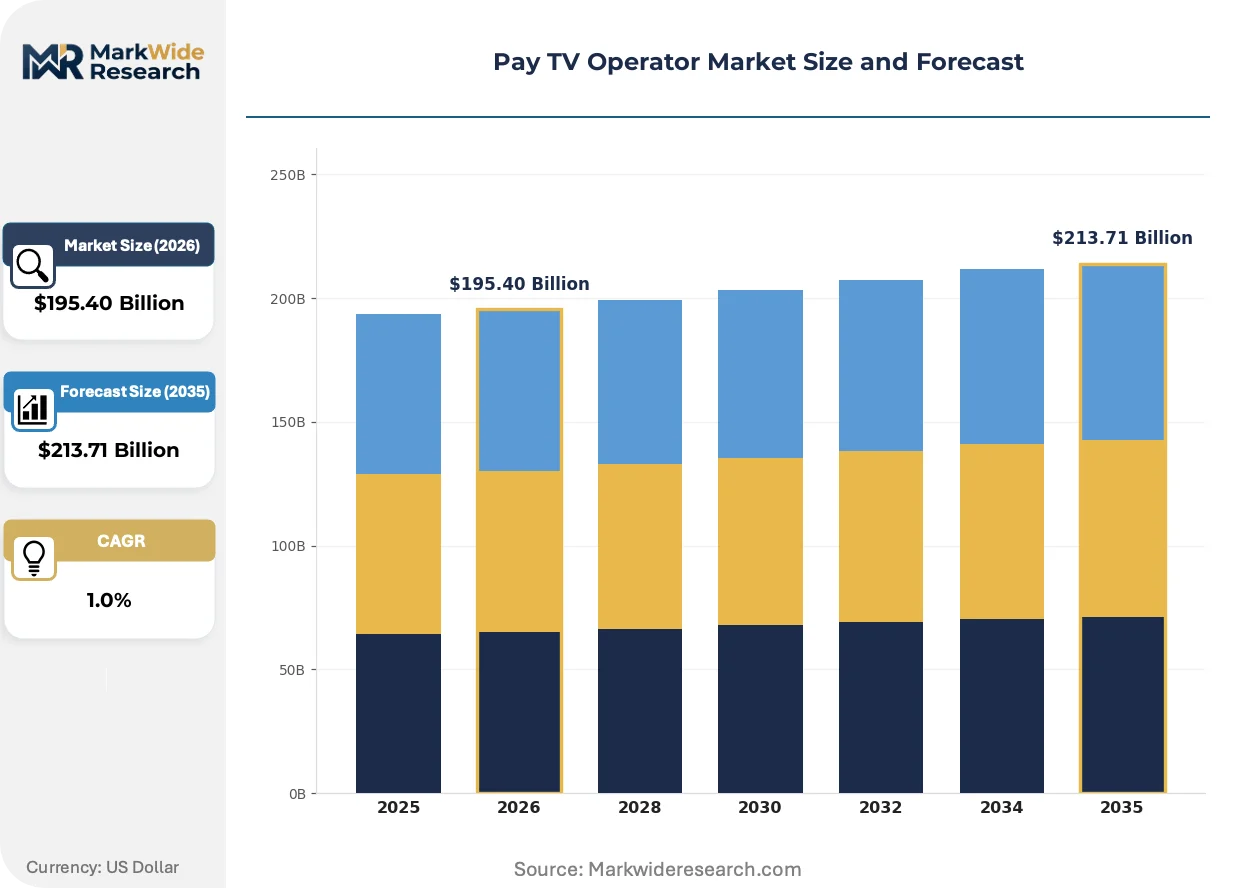
| Market Size in 2026 | $195.40 Billion |
| Market Size in 2035 | $213.71 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Subscription Model: Monthly Subscription, Annual Subscription, Pay-Per-View, Bundled Plans Content Type: Live Sports, Movies, News, Documentaries Delivery Method: Cable, Satellite, Online Streaming, IPTV End User: Residential, Commercial, Educational, Military |
| Companies Covered | Hulu + Live TV, FuboTV, YouTube TV, Dish Network, DirecTV, Charter, Sling TV, AT&T, Comcast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pay TV Operator Market Evolving Landscape
Active transformation in Pay TV centers on the dissolution of hardware-centric delivery models and the reconstitution of video services as software-defined, cloud-orchestrated experiences that operators can reconfigure without truck rolls.
Cloud DVR technology is converging with AI-powered content recommendation engines to replace physical set-top box storage with unlimited, geographically distributed recording capacity. Tier-1 operators in the United States now deploy these systems at scale, compressing capital expenditure per subscriber while enabling personalized channel lineups that fragment the traditional one-size-fits-all basic tier. This convergence is collapsing the distinction between live linear and on-demand consumption, forcing programmers to accept dynamic ad insertion as the price of carriage.
The FCC's 2023 net neutrality restoration order reclassifies broadband as a telecommunications service, subjecting traffic management practices to Title II scrutiny. This regulatory shift constrains operators' ability to zero-rate their own video streams or deprioritize competing OTT traffic. vMVPD providers and cable operators with vertically integrated streaming platforms face the most acute compliance pressure, responding by unbundling video from broadband pricing to demonstrate arm's-length treatment.
Household video procurement now favors annual prepaid commitments over month-to-month flexibility, reversing the post-2015 trend of subscription cycling. Sports-centric vMVPD bundles capture this preference by offering discounted yearly rates that lock in subscribers through championship seasons. This behavioral shift is most pronounced in the United States, where YouTube TV and Hulu Plus Live TV have normalized sports-season anchoring as the primary retention mechanism.
Pay TV Operator Market Segmentation
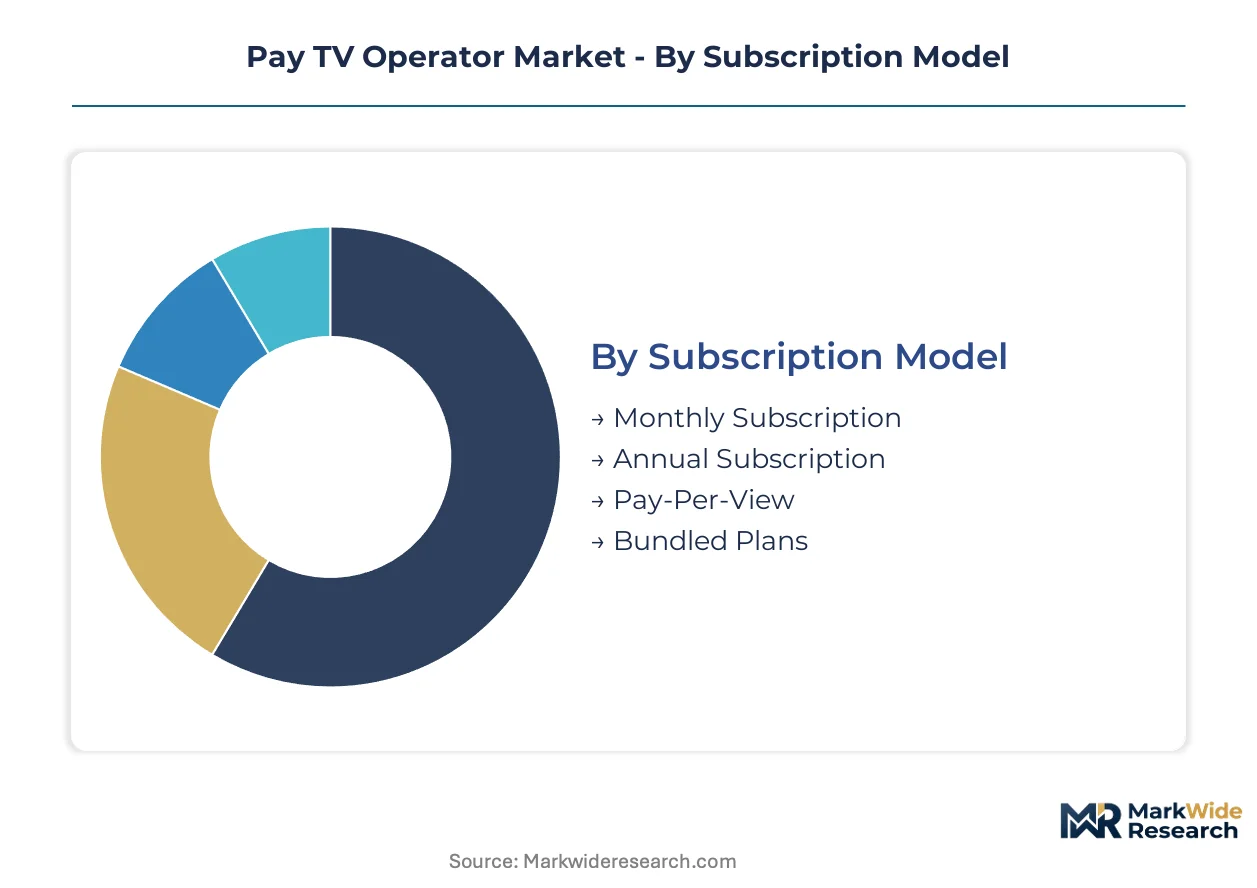
Pay TV operators configure service architectures around four distinct dimensions that determine capital deployment, content licensing strategy, and subscriber acquisition economics. Each segmentation axis carries unique regulatory exposure and margin profiles that reshape competitive positioning across distribution territories.
Subscription Model:
Content licensing agreements with ESPN, HBO, and regional sports networks impose minimum penetration guarantees that vary by billing structure, forcing operators to align package design with contractual revenue commitments.
- Monthly Subscription:Recurring billing cycles maximize subscriber liquidity and reduce churn through habitual payment patterns. Residential households in suburban United States markets prefer this structure for budget predictability despite higher per-month costs versus annual commitments.
- Annual Subscription:Prepaid twelve-month contracts lock in revenue visibility and reduce seasonal cancellation around sports off-seasons. Demand concentrates among NFL and NBA enthusiasts who bundle broadband and mobile services for discounted effective rates.
- Pay-Per-View:Event-based purchasing for championship boxing, UFC, and wrestling content carries premium per-unit pricing with minimal infrastructure overhead.
- Bundled Plans:Quadruple-play packaging of video, broadband, voice, and mobile services anchors customer lifetime value through service interdependence.
Leading the category by volume: Monthly Subscription. Growing fastest: Bundled Plans.
Content Type:
Programming acquisition costs diverge sharply across content categories, with live sports commanding exclusive carriage fees that reshape operator margin structures.
- Live Sports:NFL Sunday Ticket, NBA League Pass, and MLB Extra Innings packages generate disproportionate subscriber retention despite escalating rights inflation. Residential subscribers in Texas, Florida, and Ohio metropolitan markets demonstrate highest willingness-to-pay for regional team coverage.
- Movies:Premium channel tiers including HBO, Showtime, and Starz rely on theatrical windowing agreements that compress exclusive availability windows. Demand concentrates among households seeking ad-free libraries outside theatrical release cycles.
- News:National broadcast networks and cable news channels face carriage disputes that elevate retransmission consent costs.
- Documentaries:Niche factual programming attracts educated subscriber segments with lower churn propensity.
Live Sports commands the largest revenue pool. Documentaries are expanding most quickly through streaming aggregation.
Delivery Method:
Network infrastructure ownership determines delivery economics, with facility-based operators leveraging sunk plant investments against over-the-top competitors.
- Cable:Hybrid fiber-coaxial plant delivers linear and on-demand content through managed QAM and IP-based delivery. Charter and Comcast deploy DOCSIS 3.1 upgrades across Midwest and Southeast United States markets to sustain bandwidth competitiveness.
- Satellite:Direct broadcast satellite reaches rural and exurban households beyond cable footprint, though subscriber bases depreciate as fiber expansion accelerates.
- Online Streaming:vMVPD platforms including YouTube TV and Hulu Plus Live TV bypass physical infrastructure through public internet delivery.
- IPTV:Telco-delivered IP television from AT&T and Verizon leverages fiber-to-the-home plant for broadcast-quality streaming.
Cable retains the dominant volume position. Online Streaming shows the steepest expansion trajectory as cord-cutting stabilizes.
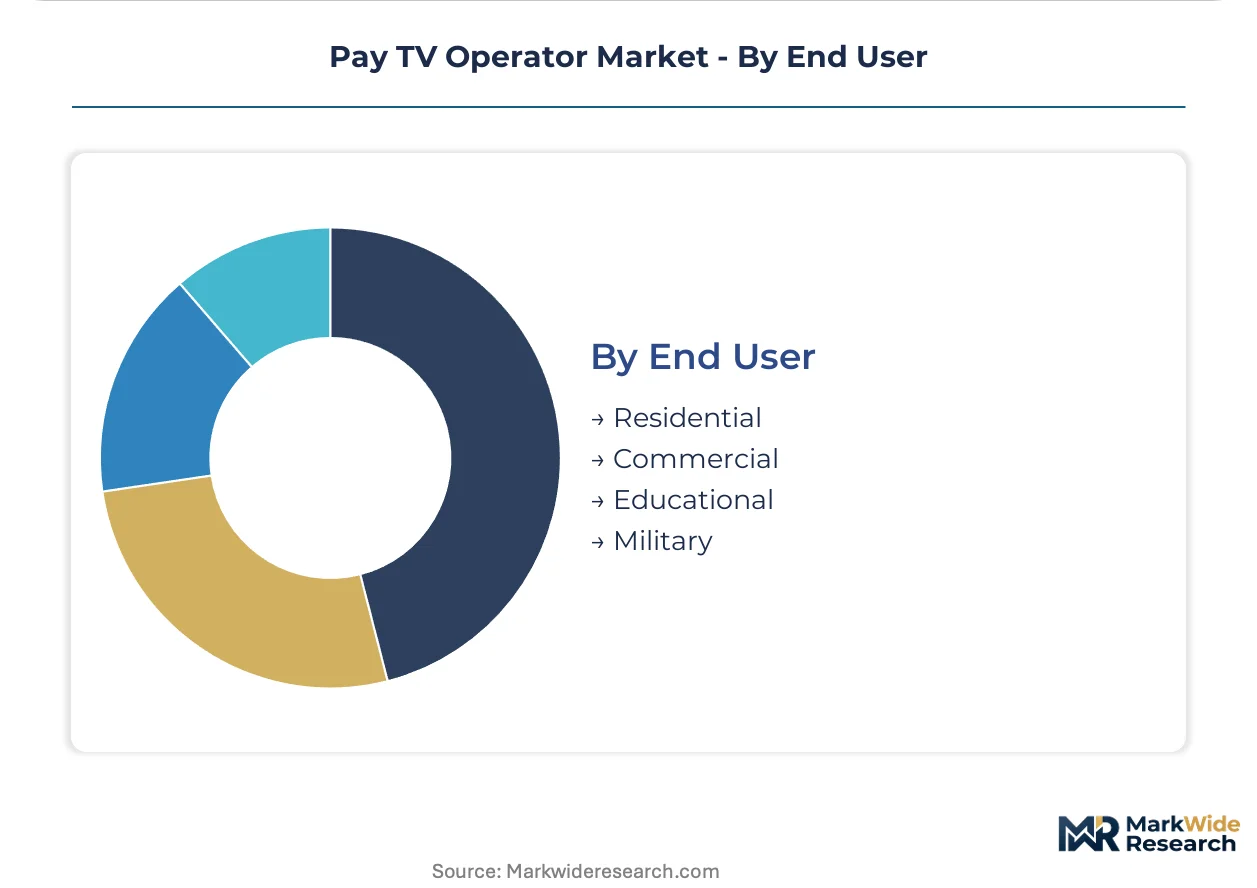
End User:
Subscriber environment dictates conditional access complexity, with commercial deployments requiring multi-screen management and educational institutions demanding content filtering capabilities.
- Residential:Single-family and multi-dwelling unit subscriptions constitute the core revenue base, with household penetration rates varying by income tier and urban density.
- Commercial:Hospitality, healthcare, and retail deployments require public performance licensing and centralized content management systems.
- Educational:K-12 and university contracts incorporate CIPA compliance filtering and classroom distribution rights.
- Military:Armed forces installations demand secure delivery infrastructure with blackout management for regional sports restrictions.
Residential dominates absolute volume. Commercial applications are climbing the fastest as addressable advertising penetrates out-of-home venues.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential subscriber demand concentrates in the United States, where cord-cutting stabilization and vMVPD bundle adoption reshape operator economics. The FCC's net neutrality restoration and must-carry rule revisions determine content licensing leverage across territories. Infrastructure ownership patterns vary sharply by country, with facility-based operators competing against over-the-top distributors.
United States
vMVPD platforms capture former satellite households through sports-centric bundles and unlimited cloud DVR. The FCC's 2023 net neutrality order reclassifies broadband under Title II, constraining zero-rating practices by vertically integrated operators. Comcast anchors hybrid cable-streaming packages across its Northeast and mid-Atlantic footprint, leveraging DOCSIS 3.1 plant upgrades.
Canada
Rural broadband expansion drives video-broadband bundling in provinces beyond dense urban corridors. The CRTC's wholesale internet access framework shapes how independent operators compete against incumbent telcos. Rogers Communications and Bell Canada dominate Ontario and Quebec markets through fiber-to-the-home infrastructure.
United Kingdom
Sky's satellite-to-IP transition accelerates as fiber broadband reaches exurban households previously dependent on dish installation. Ofcom's must-offer regulations govern access to premium sports content for competing distribution platforms. London and Southeast England concentrate vMVPD subscriber growth through high-speed fiber penetration.
Germany
Deutsche Telekom's MagentaTV platform exemplifies telco-led IPTV aggregation against cable incumbents. The Bundesnetzagentur oversees net neutrality enforcement affecting traffic management for streaming services. North Rhine-Westphalia and Bavaria host the densest fiber deployments enabling broadcast-quality IP delivery.
Japan
NTT Docomo's streaming bundles integrate mobile and fixed-line video consumption under unified billing. The Ministry of Internal Affairs and Communications regulates platform competition and content access obligations. Tokyo and Osaka metropolitan areas drive subscriber concentration through 5G-enabled multi-screen delivery.
Pay TV Operator Market Competitive Landscape
Strategic bundling dominates the current landscape as operators anchor customer lifetime value through service interdependence. The market structure consolidates around three tiers: facility-based cable and satellite incumbents with sunk infrastructure investments, telco-delivered IPTV platforms leveraging fiber plant, and asset-light vMVPD aggregators renting cloud capacity. Two archetypes define competitive positioning: broadband-centric operators layering video atop pipe ownership, and streaming-native distributors purchasing wholesale carriage rights. Portfolio diversification and geographic infrastructure densification represent the dominant competitive moves.
Among facility-based operators, Comcast and Charter exemplify the broadband-video bundling archetype through hybrid delivery models. YouTube TV occupies a position as the scale-driven vMVPD aggregator, competing through nationwide sports rights rather than physical infrastructure. These three entities represent the competitive spectrum from pipe ownership to content aggregation.
| Leading Market Players |
|---|
| Hulu + Live TV |
| FuboTV |
| YouTube TV |
| Dish Network |
| DirecTV |
| Charter |
| Sling TV |
| AT&T |
| Comcast |
| Others |
Value Network & Pricing Analysis
Programming rights index escalation cascades through operator supply chains into three-tier pricing structures across premium, standard, and economy levels. Wholesale carriage fee inflation feeds directly into subscriber tier differentiation as operators segment households by sports appetite and broadband bundling intensity.
Pricing Analysis
Volume concentration in bundled quadruple-play packages trades margin for retention, while standalone streaming tiers preserve profitability at lower scale. Price differentiation rests on sports rights inclusion and broadband speed tier anchoring. Cost compression in basic linear tiers is intensifying because of retransmission consent disputes with broadcast networks. Price-sensitive cord-cutter migrants favor vMVPD entry tiers, while least-sensitive subscribers anchor on premium sports-inclusive bundles with unlimited cloud DVR.
Supply Chain Analysis
FCC licensing and conditional access certification gating constrain which encoding vendors and set-top box manufacturers supply Tier-1 operators. Component sourcing concentrates in Taiwan, South Korea, and Mexico for semiconductor chipsets and assembly. Raw material dependencies span silicon wafers, fiber-optic cable, and lithium-ion battery cells for remote units. Single-source vulnerability pervades satellite transponder leasing and exclusive sports rights windows. Distribution runs through direct-to-consumer streaming apps and retail broadband bundling channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pay TV Operator Market sits in a technology-transition phase as cloud-based IP delivery displaces legacy QAM and satellite transmission infrastructure. This shift demands strategic repositioning across incumbent, entrant, and investor archetypes.
For Market Incumbents: To counter vMVPD sports rights poaching, Comcast and Charter should deepen fiber-to-the-home densification in exurban United States counties while consolidating conditional access vendors to reduce per-subscriber security costs. Broadband pipe ownership remains the defensive anchor as video margins compress.
For New Entrants and Emerging Players: Launch via rural broadband-video bundling enabled by USDA Rural Utilities Service grants to capture satellite-departing households before fiber overbuild reaches exurban markets. White-space targets include elder care smart home service layering and addressable advertising platforms for local political campaigns.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional cable operators with last-mile plant in Florida, Texas, and Ohio metropolitan markets where sports density sustains subscriber lifetime value. The signal to watch is ESPN direct-to-consumer pricing announcement as inflection indicator for wholesale carriage model viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud DVR Platform Migration | Unlimited storage eliminates capital-intensive set-top box hardware refresh cycles across Comcast and Charter footprints. |
| Addressable Advertising Integration | Set-top box viewing data convergence with programmatic platforms captures local ad budgets from Google and Meta. |
| Sports Rights Portfolio Rebalancing | Selective NFL and NBA package retention reduces programming budget exposure as leagues explore direct-to-consumer bypass. |
| Rural Broadband-Video Bundling | FCC Rural Digital Opportunity Fund subsidies extend fiber plant into counties where satellite previously held monopoly. |
| Smart Home Service Layering | Security monitoring and energy management applications diversify revenue per household beyond video subscription economics. |
Research Methodology
Document review covered FCC filings, retransmission consent databases, and sports rights agreements, complemented by interviews with network engineering executives, content licensing directors, broadband operations managers, and advertising platform specialists. Secondary validation drew from SEC 10-K disclosures, Nielsen audience measurement data, and streaming subscriber tracking services. Bottom-up subscriber counts by operator and top-down market sizing by revenue pool were triangulated for convergence.
Historical subscriber trajectory patterns were cross-referenced against panel input from distribution executives across cable, satellite, and vMVPD platforms. The analytical framework modeled segmentation across delivery method, content type, subscription model, and end-user category throughout the forecast period. CAGRs were derived from subscriber migration rates between linear and streaming delivery modes, weighted by average revenue per user by tier. Forecast inputs included sports rights fee escalation curves and broadband penetration saturation thresholds.
Retransmission consent disputes, sports league direct-to-consumer launch timing, and FCC broadband subsidy program modifications are the dominant revision risks to modeled projections. A model refresh is warranted upon material change in ESPN or NFL Sunday Ticket direct-to-consumer pricing strategy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Mobile TV Market
Television
Pay TV Services Market
Television
Free-To-Air (FTA) Service Market
Television
Cloud Television (TV) Market
Television
Television and Set Top Box Market
Television
Pay TV Market
Television
Digital TV Market
Television
Cable Television Networks Market
Television
TV Advertising Market
Television
Print Newspapers and Magazines Market
Television
Global Broadcast Equipment Market
Television
Broadcasting and Cable TV Market
Television
HDTV Market
Television
Television Advertising Market
Television
Television Market
Television
Cloud TV Market