
 Cloud Television (TV) Market | 2026-2036
Cloud Television (TV) Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Television (TV) Market Insights
The EU Green Deal's digital sustainability criteria is hardening expectations for energy-efficient streaming infrastructure across European broadcasters. Kaltura, Inc. leverages its open-source architecture to serve tier-one telecom operators with customizable cloud TV deployments. Brightcove, Inc. anchors its competitive stance through specialized video monetization tools for media publishers. Comcast Technology Solutions dominates the North American cable operator segment with managed cloud delivery services.
Cloud Television refers to television content delivery where encoding, storage, transcoding, and distribution run on virtualized server infrastructure rather than on-premises hardware, typically using adaptive bitrate streaming protocols such as HLS or DASH to match video quality to available bandwidth. Its primary commercial purpose is enabling service providers to launch and scale video offerings without capital-intensive broadcast headends while supporting multiscreen consumption. The Delivery Model dimension reveals that subscription-based and hybrid ad-supported tiers now capture the dominant margin pools as consumers resist pure advertising loads. Device Type segmentation shows smart TVs and mobile devices pulling ahead as primary consumption endpoints, with set-top boxes retreating to legacy replacement cycles in mature broadband markets.
The FCC governs net neutrality and broadband infrastructure rules that directly shape cloud TV traffic prioritization economics in the United States, while the EU AI Act and GDPR impose algorithmic transparency and data handling standards on personalized content recommendation engines. Content licensing frameworks from national regulators such as Ofcom in the United Kingdom and ARCEP in France further complicate cross-border cloud distribution rights. Stakeholders must monitor how emerging spectrum policy and AI governance converge to redefine platform compliance costs and competitive moats.
Market Dynamics
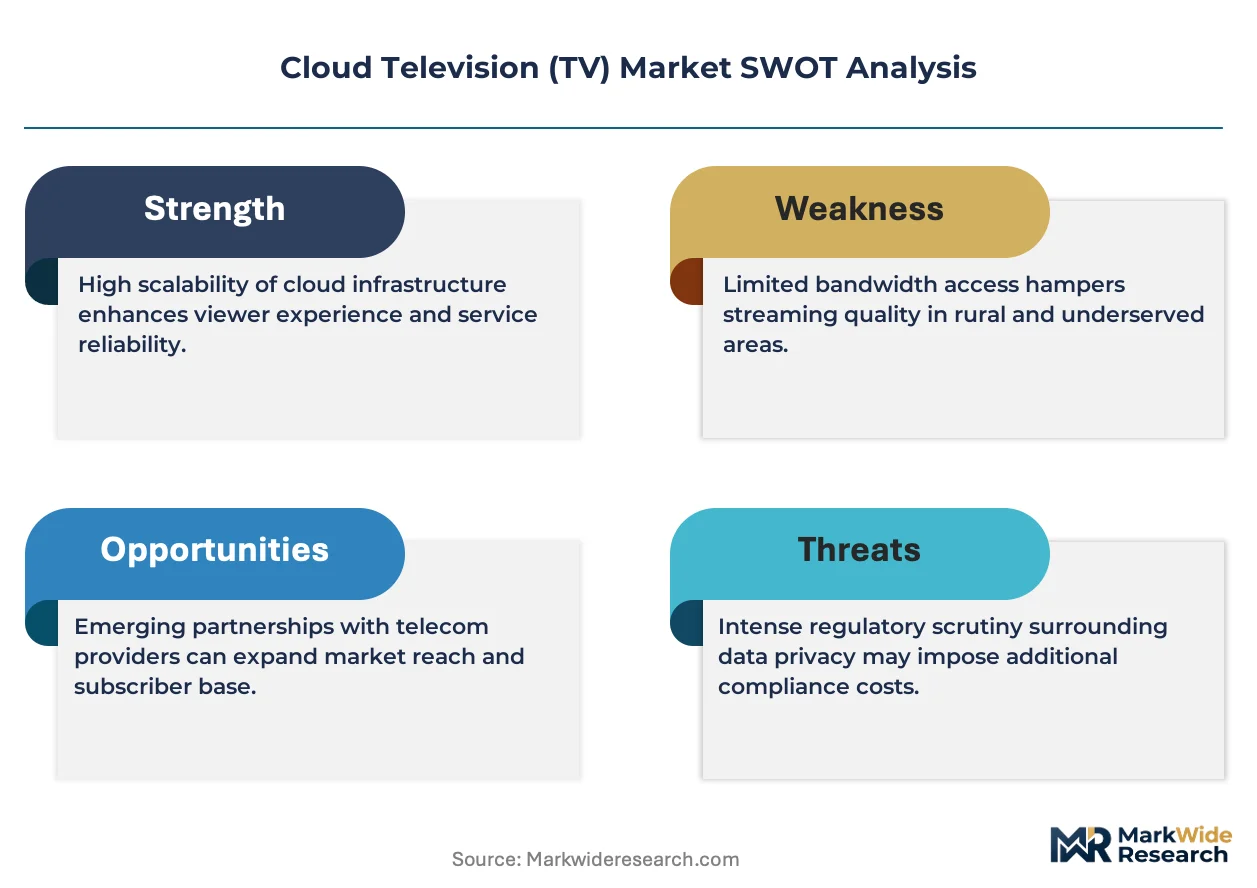
Telecom operators are abandoning capital-intensive broadcast headends for virtualized video infrastructure, compressing launch timelines from years to months while enabling multiscreen delivery at fractional cost.
Growth Catalysts
- 5G network densification:Mobile operators in South Korea and Japan are leveraging low-latency 5G cores to deliver broadcast-grade live video to handsets without dedicated spectrum, creating new addressable markets for cloud TV services.
- EU Green Deal digital sustainability criteria:European broadcasters face binding energy-efficiency mandates for streaming infrastructure, accelerating migration from on-premises encoding farms to shared cloud resources with renewable power purchasing agreements.
- Adaptive bitrate streaming protocols:HLS and DASH implementations now dominate technical specifications for smart TV certification programs, standardizing cloud-native delivery as the default architecture for OEM preloads.
Market Restraints
- Content licensing fragmentation:National regulators such as Ofcom in the United Kingdom and ARCEP in France impose divergent cross-border distribution rights frameworks, multiplying compliance costs for pan-regional cloud TV platforms.
- Edge computing infrastructure concentration:Hyperscaler cloud regions remain concentrated in North American and Western European metro zones, imposing latency penalties and egress cost burdens on operators serving emerging markets.
- Linear broadcast substitution ceiling:Demographic cohorts above age 55 in developed broadband markets retain residual loyalty to terrestrial and satellite delivery, capping near-term cloud TV penetration rates in aging societies.
Strategic Opportunities
- India rural broadband expansion:The country's PLI scheme for telecom equipment and BharatNet fiber rollout create first-mover openings for cloud TV operators to bypass legacy cable infrastructure entirely in unserved districts.
- AI-driven personalization engines:Convergence of machine learning-based content recommendation with real-time transcoding enables dynamic ad insertion at individual viewer level, opening hybrid monetization models beyond subscription fatigue zones.
- Smart TV OS consolidation:Tizen, webOS, and Android TV licensing frameworks are standardizing cloud TV app certification pathways, reducing per-platform development overhead for service providers targeting living-room endpoints.
Industry Challenges
- Legacy set-top box integration:Cable operators maintaining hybrid QAM/IP networks face complex middleware certification timelines when bridging cloud TV services to existing conditional access systems and remote control ecosystems.
- Video encoding specialist scarcity:Deep expertise in FFmpeg optimization, DRM key management, and low-latency HLS packaging remains concentrated among a narrow cohort of broadcast engineers, inflating compensation costs for platform buildouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Television (TV) Market |
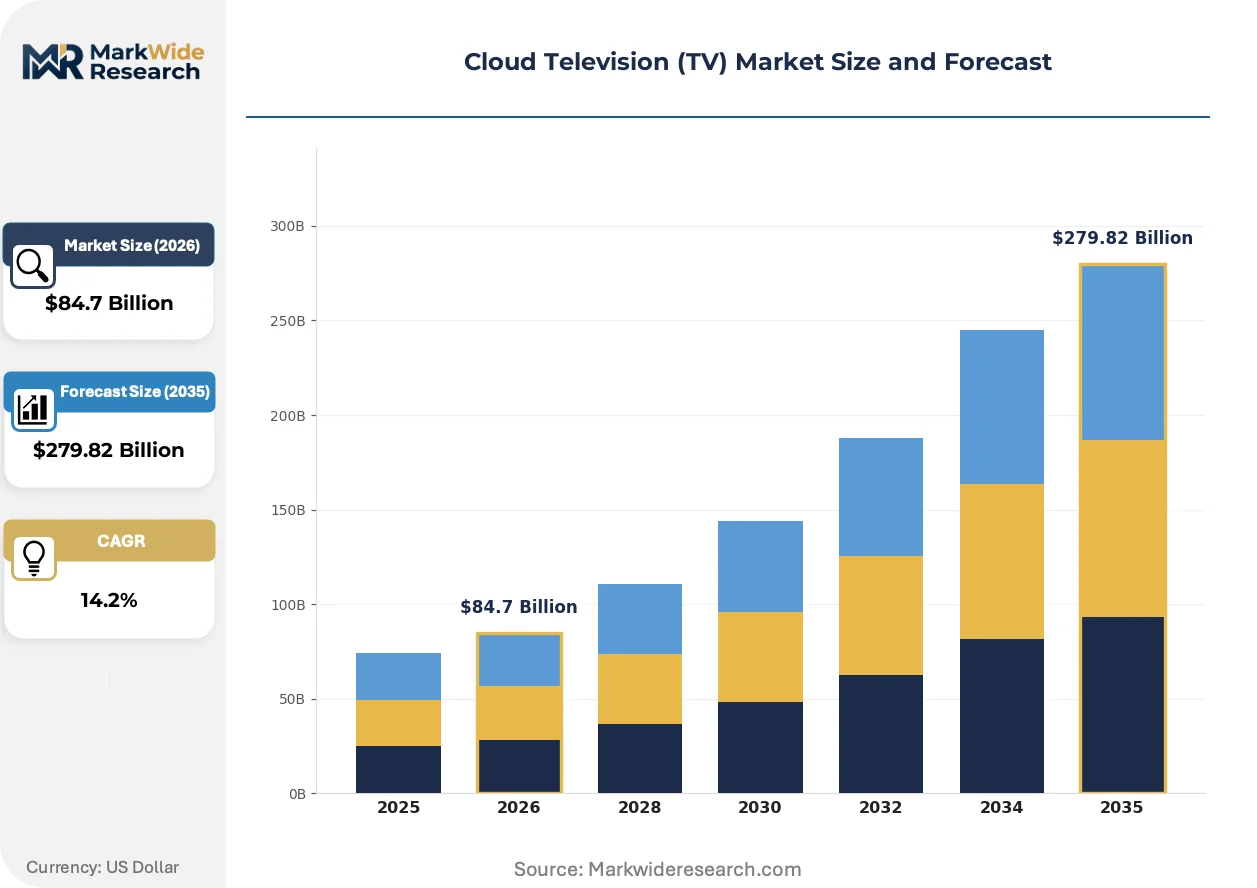
| Market Size in 2026 | $84.7 Billion |
| Market Size in 2035 | $279.82 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Content Type: Live Streaming, On-Demand, Video-on-Demand, Paid Subscription Delivery Model: Subscription-Based, Ad-Supported, Transactional Video, Hybrid User Type: Residential, Commercial, Educational, Government Device Type: Smart TV, Mobile Devices, Set-Top Boxes, Tablets |
| Companies Covered | Kaltura, Inc., Brightcove, Inc., Amino Technologies PLC, MatrixStream Technologies, Inc., IntelliMedia Networks, CSG Systems International, Inc., Minerva Networks, Inc., MediaKind, Comcast Technology Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Television (TV) Market Trends and Innovations
Codec efficiency breakthroughs and regulatory pressure on streaming energy consumption are compressing technical roadmaps while reshaping how service providers architect their delivery stacks.
AV1 royalty-free video coding is overtaking HEVC in premium tier deployments. Smart TV manufacturers including Sony and Samsung have embedded hardware AV1 decode in 2024 model year lineups. This compression efficiency is overtaking legacy licensing cost structures that burdened HEVC and VP9 adoption curves.
The EU AI Act algorithmic transparency mandates now apply to content recommendation engines processing viewer behavioral data. Broadcasters deploying cloud TV platforms must document training data provenance and enable human override of automated curation decisions. French and German operators are most affected, restructuring their data science teams to embed compliance checkpoints within continuous deployment pipelines.
Viewer tolerance for advertising loads has collapsed below twelve minutes per hour in North American and European markets. Subscription-fatigued households are rotating toward hybrid tiers with lighter ad payloads rather than pure ad-supported or premium ad-free extremes. This behavioral pivot is most visible among 25-34 demographic cohorts in the United States and United Kingdom, where churn rates between services now exceed forty percent annually.
Cloud Television (TV) Market Segmentation
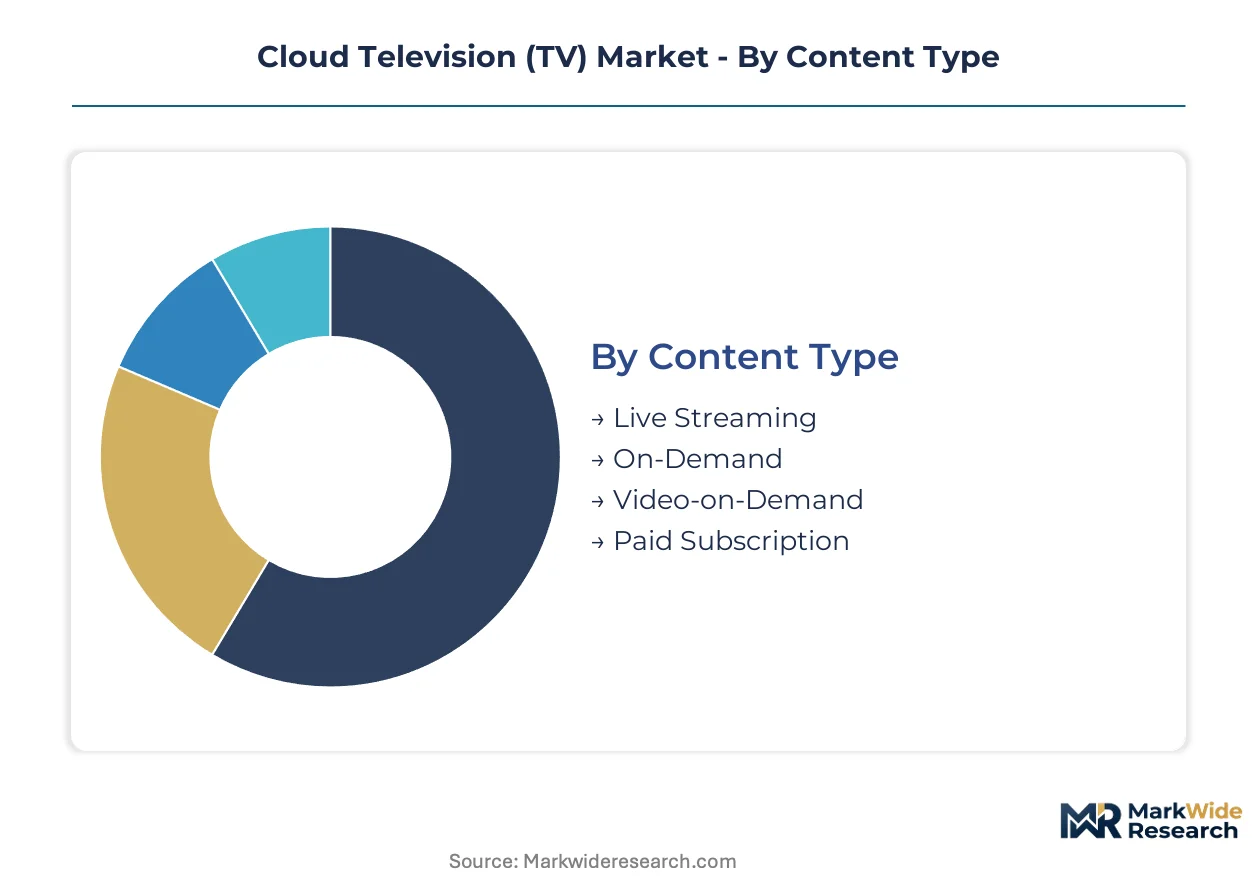
Cloud TV architectures must align with distinct consumption patterns, monetization mechanics, and endpoint capabilities. Segmentation reveals where infrastructure investments concentrate and which deployment models capture margin.
Content Type:
Upgrade cycles for encoding infrastructure differ sharply between real-time and file-based workflows, driving divergent capital allocation timelines among service providers.
- Live Streaming:Real-time encoding clusters process sports, news, and event programming with sub-three-second latency requirements. South Korean operators including KT Corporation have deployed nationwide live streaming at scale, leveraging 5G network cores to bypass traditional broadcast infrastructure entirely.
- On-Demand:Pre-encoded libraries utilize tiered storage architectures with hot-cache SSD layers for trending titles and cold-archive object storage for back-catalog content. European broadcasters migrating under EU Green Deal mandates favor on-demand workloads for their predictable, batch-optimizable energy consumption profiles.
- Video-on-Demand:Transactional and library-based models rely on just-in-time packaging to reduce storage duplication across DRM schemes.
- Paid Subscription:Exclusive original content drives premium tier differentiation with higher bitrate ladders and HDR mastering pipelines.
Volume placements concentrate in On-Demand; the faster expansion belongs to Live Streaming.
Delivery Model:
Monetization architecture determines customer acquisition economics and churn exposure, with hybrid structures emerging as the dominant response to subscription fatigue.
- Subscription-Based:Recurring revenue models fund sustained content investment and platform development. North American consumers above age 55 demonstrate higher retention rates in pure subscription tiers, insulating operators from demographic churn risks.
- Ad-Supported:Lower entry price points expand addressable markets but require sophisticated yield optimization. French operators under ARCEP oversight face additional consent-layer complexity when deploying personalized ad insertion.
- Transactional Video:Rental and purchase models capture event-driven demand without long-term subscriber commitments.
- Hybrid:Tiered offerings combine base ad-supported access with premium ad-free upgrades. United States and United Kingdom households aged 25-34 rotate most frequently between hybrid tiers, with annual churn exceeding forty percent.
Revenue concentration sits with Subscription-Based; hybrid configurations are climbing the fastest.
User Type:
Procurement authority and integration complexity vary across institutional contexts, reshaping sales cycle duration and support requirements.
- Residential:Mass-market households consume through retail broadband connections with self-service provisioning. Indian BharatNet fiber expansion targets rural residential segments for first-time cloud TV penetration.
- Commercial:Hospitality, healthcare, and retail verticals require managed service wrappers with SLA guarantees.
- Educational:Universities and K-12 districts demand authentication federation and content filtering.
- Government:Public sector deployments impose sovereign data residency and security certification requirements.
Deployment scale favors Residential; steepest expansion trajectory belongs to Commercial.
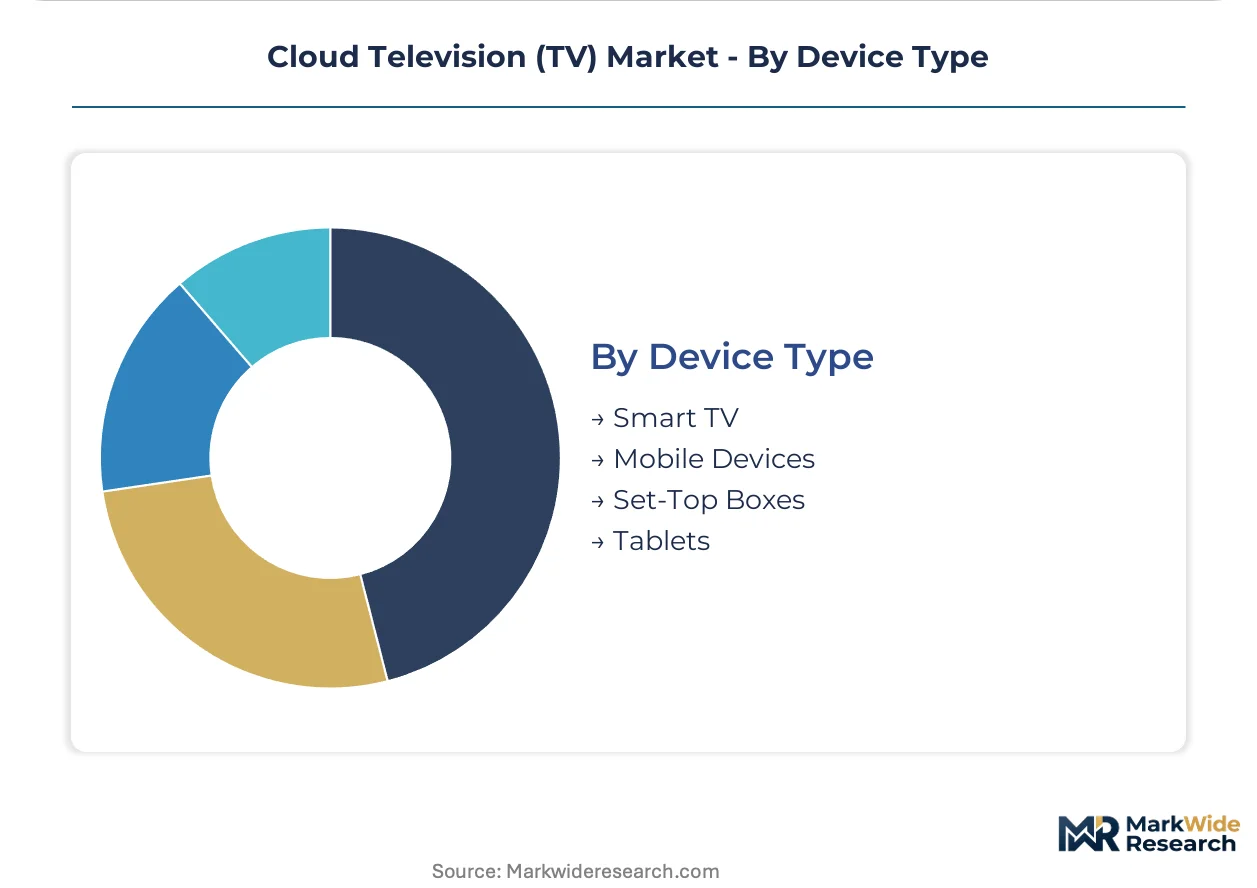
Device Type:
Certification pathways and encoding ladder optimization differ across endpoint categories, fragmenting development overhead for multi-platform operators.
- Smart TV:Tizen, webOS, and Android TV operating systems standardize cloud TV app certification with hardware AV1 decode in 2024 model year lineups from Sony and Samsung. Living-room consumption commands premium ad rates due to co-viewing and brand-safe context.
- Mobile Devices:Handset-optimized streams require lower bitrate floors and portrait-crop adaptations. Japanese mobile operators exploit 5G network densification to deliver broadcast-grade live video without dedicated spectrum allocation.
- Set-Top Boxes:Legacy QAM/IP hybrid networks persist in mature cable markets with extended replacement cycles.
- Tablets:Mid-size screens occupy niche use cases between mobile convenience and immersive viewing.
Primary consumption gravity centers on Smart TV; Mobile Devices are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors cloud TV infrastructure deployment through KT Corporation and SK Broadband's nationwide virtualized video platforms, establishing the metropolitan capital as the reference architecture for 5G-integrated broadcast replacement.
United States
FCC spectrum reallocation initiatives compel broadcasters to abandon terrestrial transmission hardware for cloud-native delivery models. The regulator's net neutrality frameworks govern traffic prioritization economics for streaming providers. Comcast Technology Solutions dominates managed cloud delivery from Philadelphia, serving cable operators with hybrid QAM/IP transition services.
South Korea
KT Corporation and SK Broadband have operationalized nationwide cloud TV services using low-latency 5G network cores. The country's spectrum policy enables mobile operators to deliver broadcast-grade live video without dedicated broadcast allocation. Seoul's Pangyo Techno Valley clusters encoding infrastructure specialists serving domestic deployment templates.
Germany
EU Green Deal digital sustainability criteria mandate energy-efficient streaming infrastructure across public and private broadcasters. The country's national media regulator enforces compliance documentation for algorithmic recommendation systems under EU AI Act transparency requirements. Berlin hosts MediaKind's European engineering operations for broadcast-to-cloud migration tooling.
France
ARCEP imposes consent-layer complexity on personalized ad insertion deployments, multiplying compliance architecture costs for hybrid monetization tiers. The national audiovisual regulator CNIL enforces GDPR-aligned data handling standards for viewer behavioral analytics. Paris-based operators restructure data science teams to embed algorithmic transparency checkpoints within continuous deployment pipelines.
India
BharatNet fiber rollout and PLI scheme incentives for telecom equipment create first-mover openings for cloud TV operators in unserved rural districts. TRAI's broadband infrastructure mandates accelerate fixed-line penetration in Tier-2 and Tier-3 cities. Maharashtra's Mumbai-Pune corridor concentrates streaming platform development talent for regional language content localization.
Cloud Television (TV) Market Competitive Landscape
The competitive structure tilts toward vertically integrated platform specialists with broadcast heritage and open-source architecture providers serving tier-one telecom operators. The vendor base separates into three strategic archetypes: managed service incumbents with cable operator relationships, independent software vendors with customizable middleware stacks, and hyperscaler-aligned video technology arms. Dominant competitive moves include strategic partnerships with smart TV OEMs for OS certification pathways and technology licensing agreements that reduce per-platform development overhead.
Within the open-source architecture tier, Kaltura, Inc. and Brightcove, Inc. exemplify contrasting positioning strategies—Kaltura occupying a position anchored in customizable deployments for telecom operators while Brightcove represents video monetization specialization for media publishers. Comcast Technology Solutions sits within the managed service incumbent archetype, leveraging North American cable infrastructure relationships. These three entities collectively illustrate how competitive differentiation fragments across deployment model flexibility, monetization tooling depth, and legacy operator integration capabilities.
| Leading Market Players |
|---|
| Kaltura, Inc. |
| Brightcove, Inc. |
| Amino Technologies PLC |
| MatrixStream Technologies, Inc. |
| IntelliMedia Networks |
| CSG Systems International, Inc. |
| Minerva Networks, Inc. |
| MediaKind |
| Comcast Technology Solutions |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up video infrastructure specialists anchor supply-side ownership patterns, compressing vendor margins through portfolio-company purchasing power while enforcing standardized SaaS pricing tiers across acquired platforms.
Pricing Analysis
Value-based pricing tied to subscriber throughput and platform uptime anchors enterprise cloud TV contracts. Three-tier pricing structure across premium, standard, and economy levels segments by encoding resolution, DRM scheme complexity, and after-sales support SLAs. Cost compression in ad-supported tiers is intensifying because hyperscaler egress fees consume disproportionate margin at lower ARPU levels. Tier-one telecom operators demonstrate lowest price sensitivity due to bundled broadband economics, while independent media publishers face acute margin pressure from subscription fatigue.
Supply Chain Analysis
Dual-sourcing requirements for encoding silicon and CDN capacity mandate multi-supplier qualification across AWS, Azure, and Google Cloud regions. Hardware supply concentrates in Taiwan for GPU acceleration, South Korea for memory components, and the United States for specialized video encoding ASICs. Raw material dependencies span advanced node semiconductors, rare earth elements for server magnets, and lithium-ion storage for edge caching. Single-source vulnerability runs through Taiwan Semiconductor Manufacturing's foundry capacity for AI inference chips. Distribution runs through hyperscaler marketplaces and direct OEM relationships with smart TV manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud TV infrastructure consolidation accelerates as FCC spectrum reallocation deadlines force broadcasters to abandon legacy capital equipment, squeezing mid-tier encoding vendors without managed service capabilities.
For Market Incumbents: Extend platform stickiness through deeper integration with Tizen and Android TV certification pathways, locking out competing middleware stacks. Acquire distressed encoding engineering teams in Seoul and Berlin to capture scarce FFmpeg optimization expertise before hyperscalers absorb talent. Vertical integration into edge caching hardware insulates margin from hyperscaler egress fee inflation. For New Entrants and Emerging Players: Rural Indian broadband providers represent an underserved buyer archetype with zero legacy QAM infrastructure and immediate demand for localized content delivery. Bypass established metro markets entirely. Target Maharashtra's Tier-2 cities with Marathi-language live streaming bundles delivered through BharatNet fiber backhaul. Partner with domestic smart TV assemblers qualifying under India's PLI scheme for preloaded app distribution. For Investors and Strategic Acquirers: Distressed-cycle entries favor open-source middleware specialists with telecom operator relationships in Germany and France, where EU AI Act compliance costs are forcing smaller vendors toward acquisition. Five-to-ten year viability hinges on embedded position within 5G network core deployments. Watch for AV1 hardware decode penetration rates in 2024 smart TV lineups as inflection signal for codec transition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Smart TV OS Certification Partnership | Samsung's Tizen and LG's webOS preloads reduce per-platform development overhead for service providers. |
| 5G Network Core Integration | KT Corporation's nationwide deployment validates low-latency live streaming without dedicated broadcast spectrum. |
| EU Green Deal Compliance Architecture | Renewable power purchasing agreements for encoding clusters satisfy binding energy-efficiency mandates on European broadcasters. |
| AI-Driven Personalization Engine Development | Machine learning recommendation systems enable dynamic ad insertion under GDPR and EU AI Act transparency requirements. |
| Rural Broadband Infrastructure Partnership | BharatNet fiber expansion creates first-mover openings for cloud TV operators bypassing legacy cable in unserved Indian districts. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by structured interviews with encoding infrastructure directors, cloud platform procurement leads at tier-one telecom operators, smart TV OEM integration engineers, and CDN capacity planners. FCC spectrum auction records, EU AI Act implementation guidance, TRAI broadband penetration statistics, and hyperscaler capex disclosures provided demand-side validation. Bottom-up service provider deployment counts triangulated against top-down addressable broadband subscriber estimates.
Granularity-level modeling segmented the market by content type, delivery model, user type, and device category at the country level, with additional dimensioning for 5G network availability and regulatory framework clusters. CAGRs were derived from fitted growth curves calibrated to historical migration patterns from broadcast headends to virtualized infrastructure. Forecast inputs included smart TV shipment projections by operating system, spectrum reallocation timelines, and fiber broadband rollout schedules.
Revisions become necessary when FCC net neutrality rulemaking shifts traffic prioritization economics, EU Green Deal criteria tighten beyond current renewable energy thresholds, or AV1 hardware decode penetration accelerates faster than replacement cycle timing. Deviation in hyperscaler egress pricing or 5G network densification capital commitment levels would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
TV Advertising Market
Television
Television Market
Television
Digital TV Market
Television
Global Broadcast Equipment Market
Television
Cable Television Networks Market
Television
Television Services Market
Television
Pay TV Services Market
Television
Pay TV Market
Television
Broadcasting and Cable TV Market
Television
Print Newspapers and Magazines Market
Television
HDTV Market
Television
Free-To-Air (FTA) Service Market
Television
Television Broadcasting Services Market
Television
Pay TV Operator Market
Television
Television Advertising Market
Television
Holographic TV Market