
 Pay TV Services Market | 2026-2036
Pay TV Services Market Size, Share, and Industry Trends Forecast 2026-2036
Pay TV Services Market Outlook
Satellite broadcast infrastructure across Latin America is recalibrating as operators redirect orbital capacity toward hybrid streaming-cable bundles. DIRECTV leverages its continental satellite footprint to sustain rural subscriber retention where terrestrial broadband remains sparse. Comcast anchors urban markets through coaxial-to-fiber upgrades that integrate broadband with linear channel packages. Charter Communications competes in mid-tier metros by positioning Spectrum as a single-contract alternative to fragmented streaming subscriptions.
Pay TV services deliver linear and on-demand video programming through cable, satellite, internet protocol, or over-the-top transmission systems, typically requiring conditional access encryption and set-top box or app-based decoding for content delivery. These services monetize through subscription fees, advertising insertion, and premium tier upsells while maintaining carriage agreements with content studios. Cable TV retains the largest revenue pool among service types due to entrenched broadband bundling, though IPTV captures the fastest expansion as fiber-to-the-home deployments accelerate. Residential customer type dominates absolute subscriber counts, while commercial and hospitality segments concentrate margin through volume-contract pricing and property-wide infrastructure deployments.
The Federal Communications Commission enforces must-carry and retransmission consent rules that govern how pay TV distributors negotiate local broadcast station carriage, directly influencing programming costs passed to subscribers. In parallel, the European Commission's Audiovisual Media Services Directive and national telecom regulators such as Ofcom in the United Kingdom impose content quota obligations and platform interoperability standards that shape cross-border service design. Stakeholders must monitor regulatory divergence between bandwidth allocation policies and content licensing frameworks as they evaluate capital deployment across delivery technologies.
Market Dynamics
Fiber-to-the-home mandates from national telecom regulators are compressing legacy coaxial infrastructure timelines while forcing simultaneous investment in IP-based delivery platforms.
Growth Catalysts
- TRAI's broadband infrastructure directives:India's telecom regulator mandates fiber optic deployment to underserved tier-2 cities, expanding addressable households for IPTV bundling.
- Conditional access encryption advancement:Next-generation DRM protocols reduce piracy losses and enable tiered subscription models across hybrid broadcast-broadband services.
- Brazilian middle-income household formation:São Paulo and Rio de Janeiro suburban corridors deepen pay TV penetration as mortgage accessibility improves.
Market Restraints
- Retransmission consent cost spiral:FCC-mandated local broadcast station negotiations escalate programming fees passed directly to subscriber bills.
- Orbital capacity scarcity:Latin American satellite operators face constrained Ku-band spectrum allocation, limiting high-definition channel expansion.
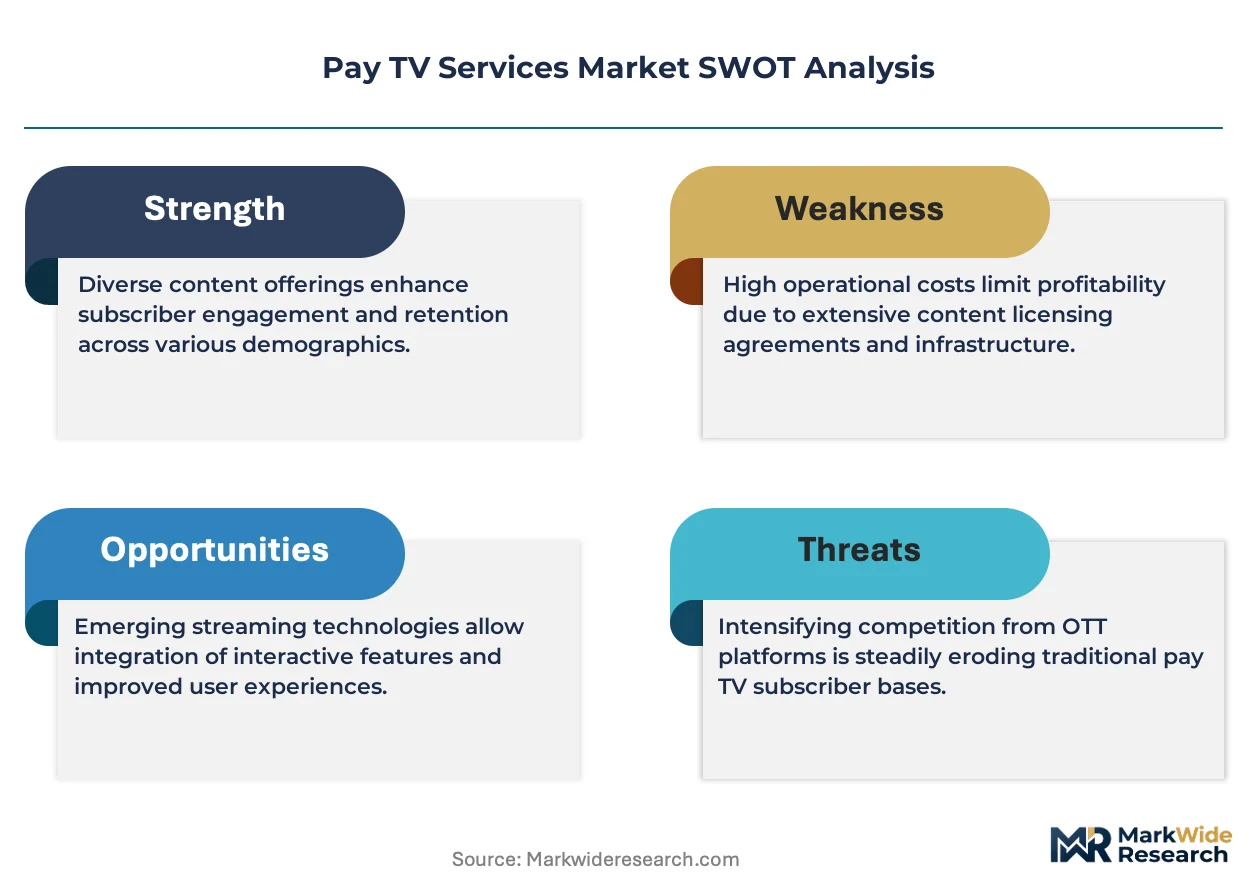
- Streaming substitution elasticity:Standalone OTT platforms fragment household entertainment budgets and compress linear TV time spent.
Strategic Opportunities
- Smart home integration convergence:IPTV set-top boxes function as home automation hubs, opening adjacent revenue from security and energy management services.
- Commercial property-wide deployments:Hospitality and multi-dwelling unit segments offer volume-contract pricing with captive infrastructure lock-in.
- Advertising insertion technology:Dynamic ad replacement capabilities enable addressable television campaigns competing with digital media CPM rates.
Industry Challenges
- Legacy billing system migration:Decades-old subscriber management platforms require multimillion-dollar replacement to support real-time usage-based pricing.
- Content licensing complexity:Sports rights fragmentation across regional broadcasters forces distributors to negotiate dozens of separate carriage agreements.
- Fiber technician shortage:Last-mile installation capacity constraints delay service activation timelines and increase customer acquisition costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pay TV Services Market |
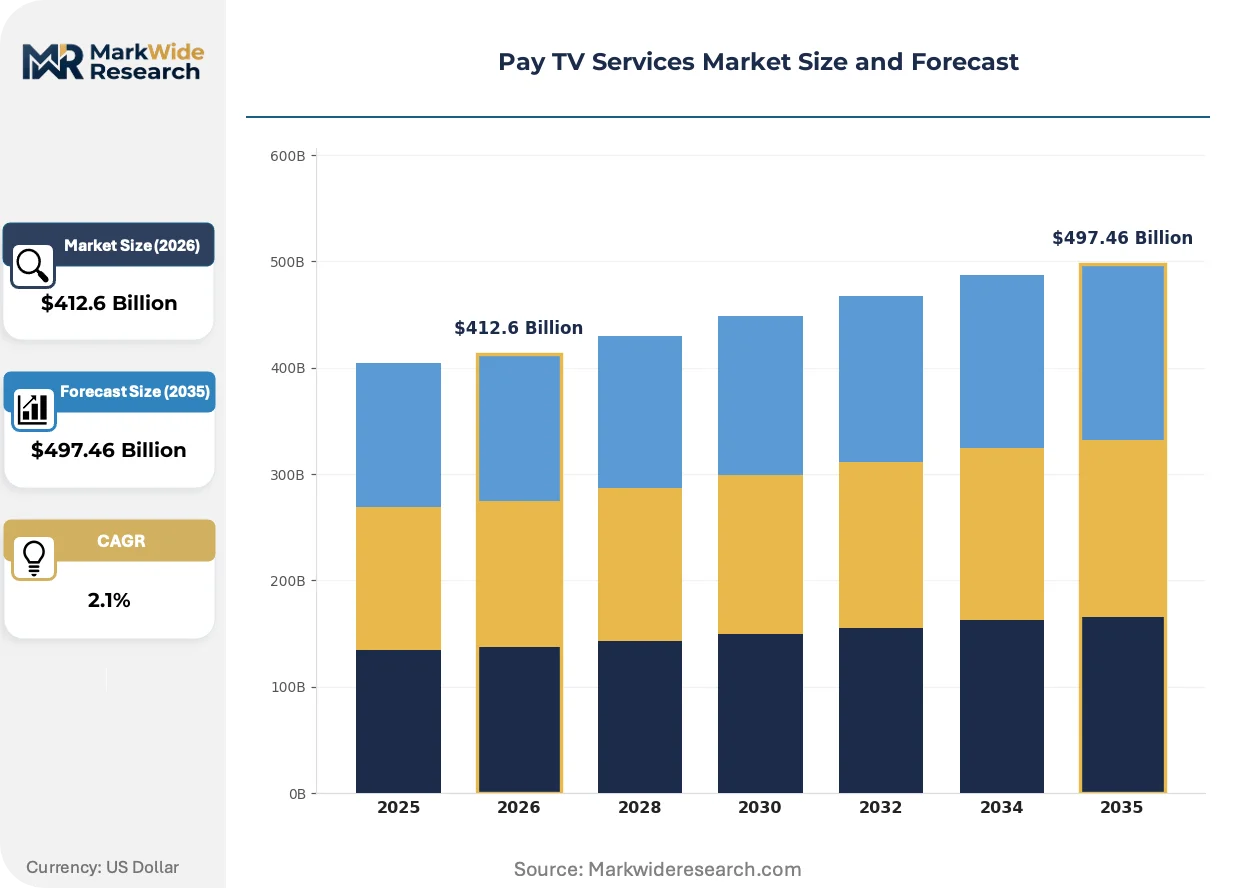
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $497.46 Billion |
| CAGR (2026 – 2036) | 2.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cable TV, Satellite TV, IPTV, OTT Customer Type: Residential, Commercial, Educational, Hospitality Content Type: Sports, Movies, News, Entertainment Subscription Model: Monthly, Annual, Pay-Per-View, Bundled |
| Companies Covered | DIRECTV, Verizon Fios, YouTube TV, Hulu + Live TV, Xfinity, Comcast, DISH, Spectrum, Charter Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pay TV Services Market Strategic Shifts
Delivery infrastructure is bifurcating between fiber-rich urban markets and satellite-dependent rural territories, with middleware platforms enabling unified subscriber experiences across both.
Cloud DVR functionality is converging with linear broadcast streams, allowing residential subscribers to pause live programming and access recordings across multiple household screens. Cable operators in suburban North America deploy this hybrid architecture to defend broadband bundling relationships. The technology is converging with mobile device casting protocols, compressing the distinction between in-home and out-of-home viewing rights.
Ofcom's platform interoperability standards under the United Kingdom's transposed Audiovisual Media Services Directive mandate open API access for third-party electronic program guides. This regulatory framework fragments subscriber data ownership between distributors and equipment manufacturers. Set-top box vendors must now license proprietary conditional access modules rather than manufacturing integrated solutions.
Households are unbundling premium channel tiers and rotating subscriptions monthly rather than maintaining annual contracts. This behavioral shift compresses average revenue per user and forces distributors to implement promotional pricing algorithms. The pattern is most visible in Indian metropolitan markets where digital payment wallets enable frictionless subscription suspension.
Pay TV Services Market Segmentation
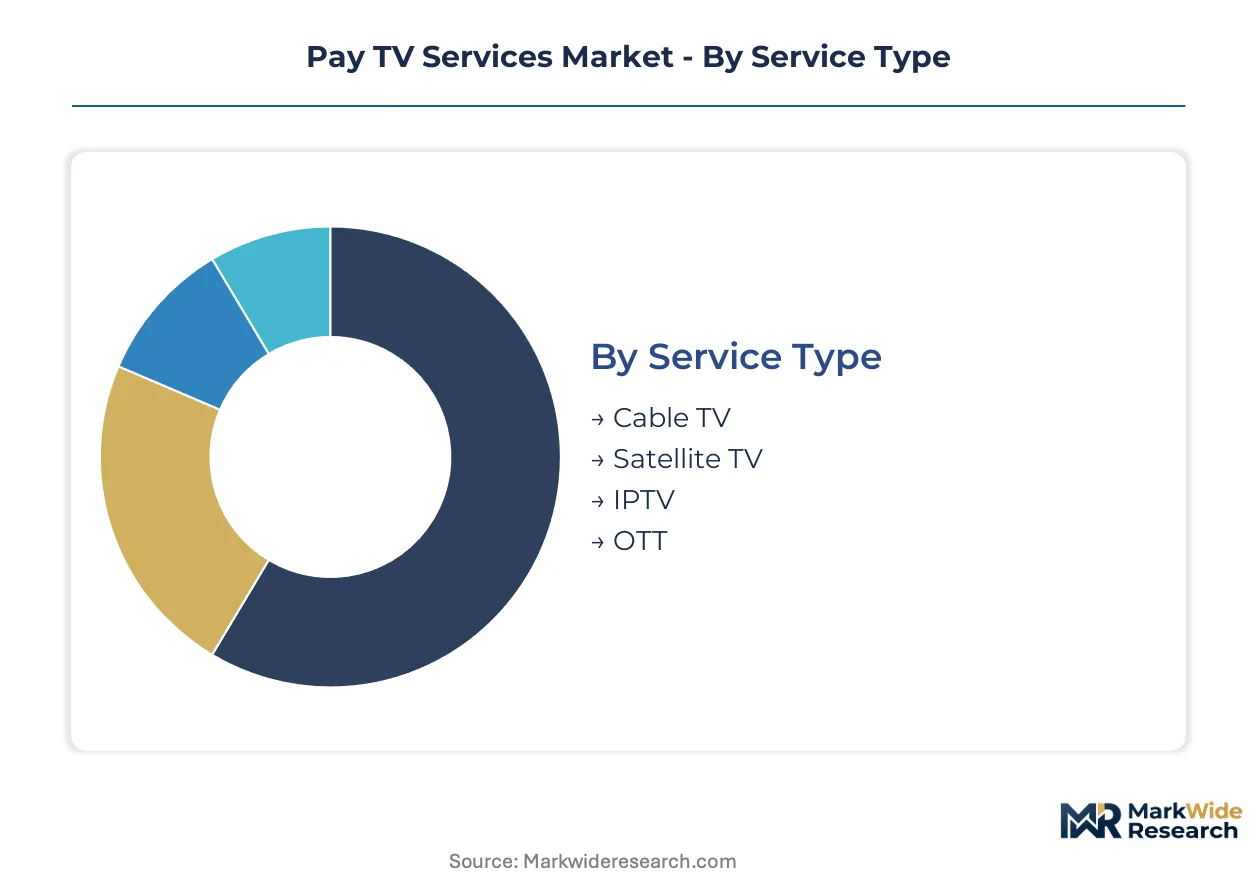
Pay TV market segmentation reveals how delivery infrastructure, customer economics, and content licensing frameworks create distinct operational requirements. Each category maps to specific regulatory burdens, capital intensity thresholds, and subscriber lifetime value profiles that shape distributor strategy.
Service Type:
Cable TV and IPTV carry distinct conditional access certification requirements under national telecom frameworks, while satellite operators face orbital licensing and spectrum coordination protocols.
- Cable TV:Hybrid fiber-coaxial infrastructure delivers encrypted linear channels through QAM modulation with DOCSIS broadband integration. Suburban North American households sustain this segment through triple-play bundling as Comcast and Charter upgrade last-mile plant. Conditional access modules must certify under FCC Part 76 rules and equivalent national cable regulations.
- Satellite TV:Ku-band and Ka-band transponder leases enable continental coverage without terrestrial infrastructure dependency. Rural Latin American markets depend on this delivery mode where fiber deployment remains uneconomical. Operators secure landing rights and orbital slot coordination through national telecom regulators and ITU filings.
- IPTV:Managed IP networks require fiber-to-the-home certification under TRAI directives in India and equivalent fiber mandates elsewhere. Middleware platforms must integrate with national emergency alert systems.
- OTT:Over-the-top delivery bypasses traditional conditional access hardware but faces content licensing complexity across territorial rights windows. DRM protocols require compliance with regional data protection frameworks.
Cable TV sits at the top of the volume ranking, with IPTV climbing the fastest as fiber-to-the-home mandates accelerate addressable household expansion.
Customer Type:
Residential contracts generate recurring revenue through individual subscriber relationships, while commercial and hospitality segments concentrate volume through property-wide infrastructure deployments with distinct procurement cycles.
- Residential:Individual household subscriptions drive absolute subscriber counts through bundled broadband relationships. São Paulo and Rio de Janeiro suburban corridors in Brazil deepen penetration as mortgage accessibility improves middle-income formation.
- Commercial:Office buildings and retail properties require multi-tenant distribution systems with centralized headend equipment and zoned channel lineups. Volume-contract pricing compresses per-subscriber margins but locks in infrastructure commitments.
- Educational:University campuses and K-12 districts negotiate site licenses with content filtering obligations and classroom-specific distribution requirements.
- Hospitality:Hotels and resorts deploy property-wide IPTV with guest room integration, on-demand billing systems, and multilingual interface mandates. Captive infrastructure creates switching costs that extend contract durations.
Residential dominates absolute volume, with hospitality delivering the steepest expansion trajectory through property development pipelines in Indian and Brazilian metro corridors.
Content Type:
Sports rights carry the most complex licensing burden with territorial fragmentation across regional broadcasters, while movies and entertainment face windowing restrictions that vary by distribution channel.
- Sports:Live event programming commands premium carriage fees with blackout restrictions and exclusive territorial windows. Retransmission consent negotiations escalate costs passed to subscriber bills under FCC-mandated frameworks.
- Movies:Studio output deals require pay-one window coordination with theatrical and streaming release calendars. Content quotas under EU Audiovisual Media Services Directive and national equivalents impose European works minimums.
- News:Must-carry obligations for local broadcast stations create regulatory compliance costs distinct from discretionary entertainment channels.
- Entertainment:Scripted and unscripted programming faces rotating subscription behavior as households unbundle premium tiers and suspend contracts monthly.
Sports sits at the top of the volume ranking, with entertainment climbing the fastest as on-demand libraries expand and seasonal subscription patterns normalize.
Subscription Model:
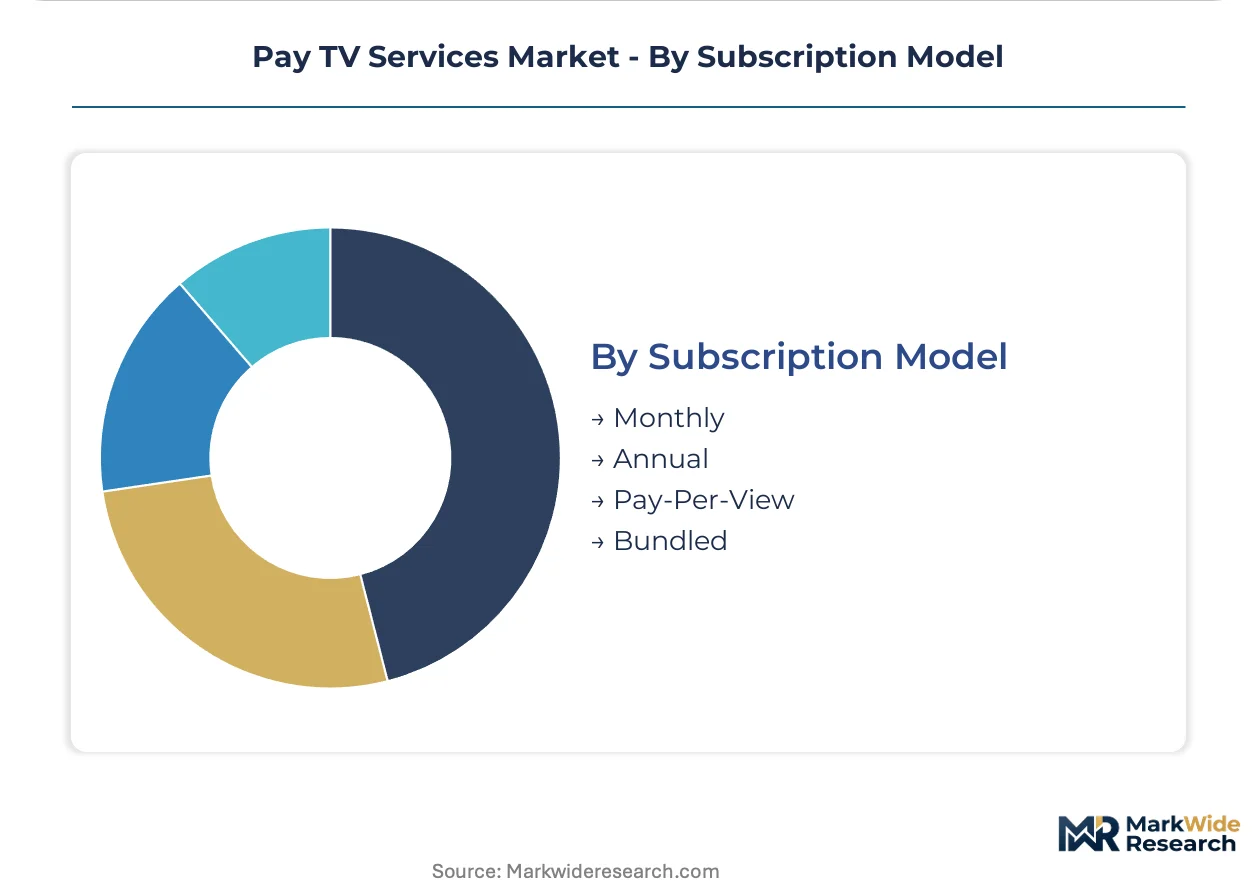
Monthly and annual contracts create predictable revenue recognition, while pay-per-view and bundled structures respond to event-driven demand spikes and broadband integration economics.
- Monthly:Recurring billing with promotional pricing algorithms responds to competitive pressure and churn reduction targets. Digital payment wallets in Indian metropolitan markets enable frictionless subscription suspension.
- Annual:Prepaid commitments improve cash flow visibility and reduce acquisition cost amortization periods. Early termination fees create switching friction.
- Pay-Per-View:Event-based transactions for premium sports and entertainment releases capture incremental revenue from non-subscribers. Dynamic ad replacement capabilities enable addressable campaigns competing with digital CPM rates.
- Bundled:Broadband-plus-video packages defend subscriber relationships against standalone streaming substitution. Fiber-to-the-home mandates compress legacy timelines while forcing IP platform investment.
Monthly contracts dominate absolute volume, with bundled offerings gaining share fastest as operators defend broadband relationships against fragmented streaming competition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping infrastructure deployment timelines as fiber mandates in India and Brazil compress legacy coaxial investment windows, while orbital licensing costs in Latin America push operators toward hybrid streaming models. Compliance cost gaps between terrestrial broadband regimes and satellite spectrum coordination protocols are redirecting capital toward markets with clearer deployment pathways.
United States
FCC must-carry and retransmission consent rules govern local broadcast negotiations, escalating programming fees that distributors pass to subscriber bills. Suburban corridors across Texas and Florida sustain cable TV bundling as Comcast and Charter upgrade hybrid fiber-coaxial plant. The Federal Communications Commission enforces conditional access certification under Part 76 rules that shape set-top box deployment economics.
Brazil
Middle-income household formation in São Paulo and Rio de Janeiro suburban corridors deepens pay TV penetration as mortgage accessibility improves subscriber bases. ANVISA and national telecom regulators coordinate landing rights for satellite operators while fiber-to-the-home mandates expand addressable households for IPTV bundling. São Paulo's metropolitan infrastructure anchors continental satellite capacity redistribution toward hybrid streaming-cable offerings.
India
TRAI broadband infrastructure directives mandate fiber optic deployment to underserved tier-2 cities, expanding addressable households for IPTV bundling across Maharashtra and Karnataka. The Telecom Regulatory Authority of India's fiber-to-the-home certification requirements compress legacy infrastructure timelines while forcing simultaneous IP platform investment. Bangalore and Hyderabad tech corridors concentrate middleware development for unified subscriber experiences across delivery modes.
United Kingdom
Ofcom's platform interoperability standards under the transposed Audiovisual Media Services Directive mandate open API access for third-party electronic program guides, fragmenting subscriber data ownership. The European Commission's content quota obligations impose European works minimums that shape cross-border service design. London's regulatory and financial infrastructure anchors conditional access module licensing rather than integrated set-top box manufacturing.
Germany
CE marking requirements and national telecom frameworks impose distinct conditional access certification burdens for cable and IPTV operators entering the market. KBA and federal regulators coordinate bandwidth allocation policies that influence content licensing negotiations across terrestrial and satellite delivery. Bavaria and North Rhine-Westphalia industrial clusters concentrate headend equipment manufacturing for multi-tenant distribution systems.
Pay TV Services Market Competitive Environment
Established producers occupy the standard tier through entrenched broadband bundling relationships; emerging entrants pursue hybrid streaming-cable convergence and smart home integration adjacencies. The vendor base stratifies across satellite footprint holders, fiber-rich cable operators, and IP-native platforms, with middleware specialists bridging delivery infrastructure gaps. Two archetypes dominate: orbital capacity landlords redirecting transponder leases toward rural retention, and fiber-upgrade operators defending urban triple-play relationships. Competitive moves concentrate on coaxial-to-fiber plant upgrades and dynamic ad replacement technology licensing.
Among United States-based distributors, Comcast and Charter Communications anchor the cable operator archetype through suburban infrastructure deployment, while DIRECTV represents the satellite footprint landlord model with continental orbital capacity. YouTube TV occupies a position within the IP-native streaming tier, exemplifying the hybrid broadcast-broadband convergence that middleware platforms enable across delivery modes.
| Leading Market Players |
|---|
| DIRECTV |
| Verizon Fios |
| YouTube TV |
| Hulu + Live TV |
| Xfinity |
| Comcast |
| DISH |
| Spectrum |
| Charter Communications |
| Others |
Value Chain & Pricing Dynamics
Captive fiber infrastructure ownership anchors both supply position and pricing power for tier-1 distributors, locking subscriber relationships through broadband bundling while compressing margins for satellite-dependent operators lacking terrestrial plant. This vertical integration pattern concentrates cost control with fiber-rich cable operators and forces satellite landlords toward hybrid streaming models to defend average revenue per user.
Pricing Analysis
Distributor margin compression runs through retransmission consent negotiations, where FCC-mandated local broadcast station carriage escalates programming fees passed directly to subscriber bills. Three-tier pricing structure across premium, standard, and economy levels differentiates by channel count and broadband speed tier, with volume scale driving enterprise and hospitality discounts. Price erosion intensifies in residential segments as households rotate streaming subscriptions monthly, while commercial property-wide deployments show lower price sensitivity due to captive infrastructure lock-in.
Supply Chain Analysis
Single-source vulnerability sits with Ku-band transponder capacity concentrated among Latin American orbital slot holders, creating bottleneck risk for rural satellite delivery. Set-top box manufacturing draws from China, Taiwan, and South Korea for conditional access modules and middleware chipsets, with fiber-optic cable sourcing anchored in Corning's US production and Chinese glass fiber imports. Tariff exposure on Chinese electronics components threatens hardware cost structures, while distribution runs through national telecom operators and regional system integrators rather than open retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Pay TV Services Market reads as a late-cycle quality story where subscriber retention now depends on premium broadband speeds rather than channel depth, with demand shifting toward gigabit-tier fiber bundles that anchor household connectivity spend.
For Market Incumbents: Hedge satellite footprint exposure by redirecting orbital capacity toward hybrid streaming-cable bundles in rural Latin American markets where terrestrial broadband remains sparse. Prioritize coaxial-to-fiber plant upgrades in suburban North American corridors to defend triple-play relationships against IP-native streaming substitution. Conditional access certification investment under FCC Part 76 rules and equivalent national frameworks preserves hardware-based subscriber lock-in against pure OTT disintermediation. For New Entrants and Emerging Players: Middleware platform vendors represent the most penetrable entry point, bridging legacy broadcast infrastructure with IP delivery for regional cable operators lacking in-house software development. Target tier-2 Indian cities where TRAI fiber mandates expand addressable households faster than incumbent IPTV deployment capacity. Go-to-market positioning as smart home integration hubs opens adjacent revenue from security and energy management services layered atop video delivery. For Investors and Strategic Acquirers: Roll-up economics work for regional fiber operators because national broadband subsidies and municipal franchise agreements create localized moats that resist national platform scaling. Long-term viability hinges on owning last-mile plant rather than content licensing relationships, with acquisition focus on mid-tier cable systems with upgradeable hybrid fiber-coaxial infrastructure. Watch fiber technician shortage severity as the inflection signal for service activation delays and customer acquisition cost spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Fiber-to-the-Home Deployment | TRAI mandates in India and FCC broadband subsidies compress legacy coaxial timelines while forcing IP platform investment. |
| Dynamic Ad Replacement Technology | Addressable television campaigns competing with digital media CPM rates unlock incremental revenue from existing subscriber bases. |
| Smart Home Integration Convergence | IPTV set-top boxes functioning as home automation hubs open adjacent revenue from security and energy management services. |
| Commercial Property-Wide Deployment | Hospitality and multi-dwelling unit segments offer volume-contract pricing with captive infrastructure lock-in extending contract durations. |
| Conditional Access Module Licensing | Ofcom platform interoperability standards fragment subscriber data ownership and mandate open API access for third-party electronic program guides. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pay TV distribution executives, fiber network engineers, content licensing directors, and hospitality technology procurement managers with secondary validation against FCC filings, TRAI regulatory notices, Ofcom market data, and operator subscriber disclosure reports. Bottom-up household penetration modeling triangulated against top-down revenue aggregation across service type segments.
Segment-weighting approaches applied differential growth assumptions to cable, satellite, IPTV, and OTT delivery modes, with cross-segment calibration against fiber deployment timelines and retransmission consent cost trajectories. CAGRs derived from subscriber count projections and average revenue per user trends across residential, commercial, educational, and hospitality customer types, with modeling incorporating conditional access encryption advancement curves and streaming substitution elasticity parameters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory divergence between bandwidth allocation policies and content licensing frameworks, orbital capacity scarcity in Latin American Ku-band spectrum, and legacy billing system migration timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Television Services Market
Television
Television Advertising Market
Television
Mobile TV Market
Television
Digital TV Market
Television
Cloud TV Market
Television
Print Newspapers and Magazines Market
Television
TV Advertising Market
Television
Holographic TV Market
Television
Pay TV Market
Television
Global Digital Terrestrial Television Market
Television
Cable Television Networks Market
Television
Television and Set Top Box Market
Television
Broadcasting and Cable TV Market
Television
Curved Television Market
Television
Global Broadcast Equipment Market
Television
Traditional TV and Home Video Market