
 Television Advertising Market | 2026-2036
Television Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Television Advertising Market Intelligence
Programmatic ad insertion is consolidating how television inventory gets monetized across linear and digital endpoints. Comcast leverages its cable infrastructure and streaming footprint to control national spot availability. Walt Disney anchors premium video ad placements through its sports and entertainment programming portfolio. Google competes for television budgets by extending its demand-side platform into connected TV auctions.
Television advertising comprises paid promotional content distributed via broadcast, cable, satellite, and internet-protocol television channels, typically delivered in fifteen-to-sixty-second spots with demographic targeting based on program context and viewer data. Its primary commercial purpose remains mass-reach brand awareness campaigns for consumer-facing industries. Video ads within the broadcast type segment dominate upfront commitments from automotive and pharmaceutical advertisers. Streaming services represent the fastest-expanding inventory pool as subscription-fatigued households accept ad-supported tiers. Cable maintains residual value for local market penetration by regional retailers.
The Federal Communications Commission enforces media ownership caps that limit how many stations a single entity controls in any designated market area, preserving competitive access for local advertisers. The Federal Trade Commission monitors truth-in-advertising standards across health and financial product claims shown on television. California's Consumer Privacy Act and evolving state-level data governance constrain how audience targeting data flows between platforms and advertisers. Stakeholders must weigh addressable targeting precision against regulatory fragmentation that threatens to segment national campaigns into incompatible compliance zones.
Market Dynamics
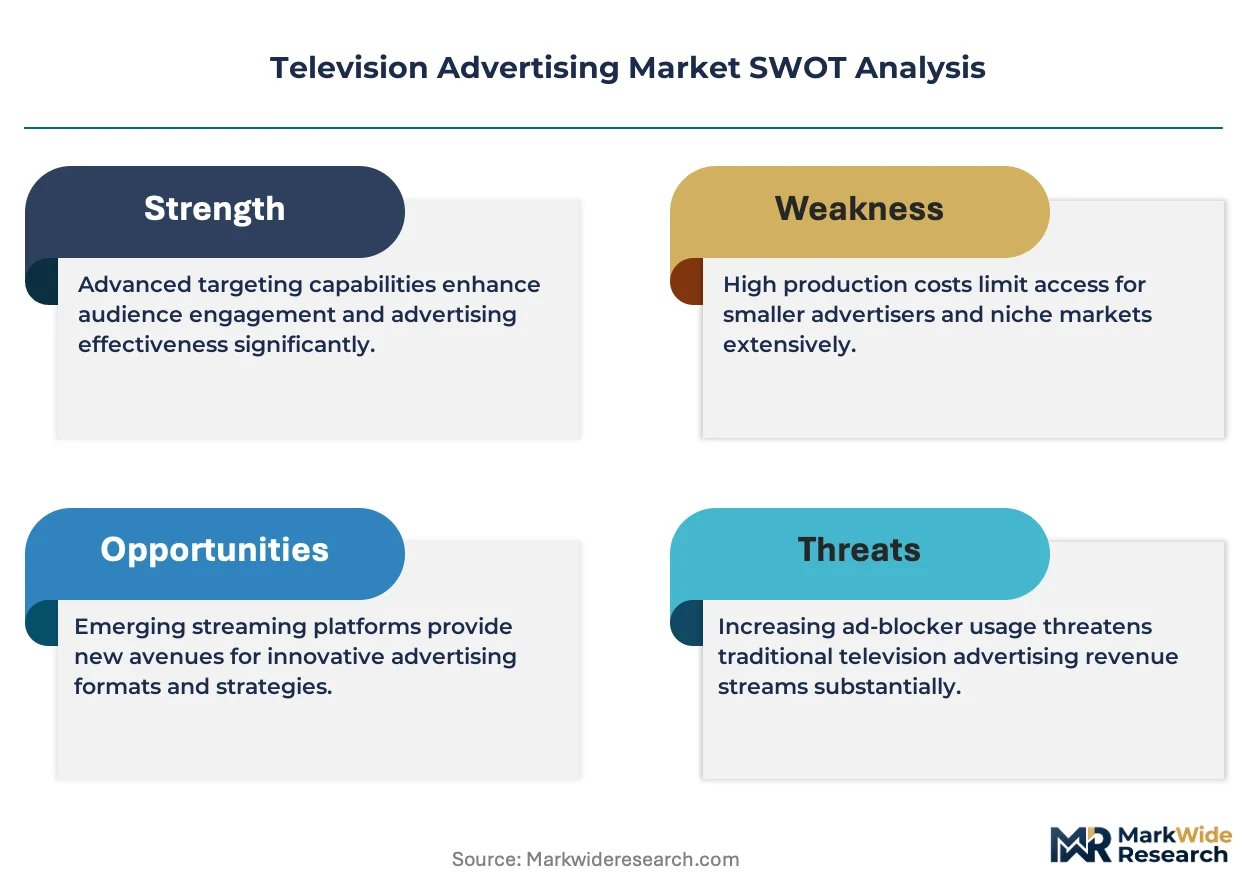
Addressable advertising technology is fragmenting national campaigns into household-level precision buys, forcing broadcasters to rebuild sales infrastructure around data management platforms rather than traditional upfront commitments.
Growth Catalysts
- Connected TV penetration:Subscription-fatigued households are accepting ad-supported streaming tiers, expanding addressable inventory pools for pharmaceutical and automotive advertisers seeking granular household targeting.
- FCC media ownership rules:Station ownership caps preserve competitive access for local advertisers in designated market areas, preventing national platform consolidation from suffocating regional spot markets.
- Programmatic infrastructure:Real-time bidding systems are collapsing the distinction between linear and digital video inventory, enabling unified campaign execution across broadcast and streaming endpoints.
Market Restraints
- Privacy framework fragmentation:California's Consumer Privacy Act and emerging state-level data governance create incompatible compliance zones that segment national campaigns into jurisdiction-specific executions.
- Linear inventory erosion:Cable subscriptions are declining as households cut the cord, compressing residual value for regional retailers dependent on local market penetration.
- Measurement standard gaps:Cross-platform audience verification lacks unified accreditation, forcing advertisers to reconcile incompatible metrics between Nielsen panels and digital ad servers.
Strategic Opportunities
- Retail media convergence:Walmart and Target are building closed-loop attribution systems that connect television exposure to in-store purchase data, creating differentiated inventory for FMCG brands.
- Live sports anchoring:Professional leagues are reserving streaming rights for dedicated platforms, concentrating premium video ad placements in events with demonstrated co-viewing resistance.
- Automatic content recognition:Smart TV manufacturers are deploying screen-level data capture that enables competitive conquesting based on what households watch on rival platforms.
Industry Challenges
- Data science talent scarcity:Broadcast sales organizations lack sufficient personnel trained in audience segmentation modeling and programmatic yield optimization.
- Legacy system integration:Traffic and billing platforms designed for linear schedules cannot ingest real-time impression data from connected TV auctions without expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Television Advertising Market |
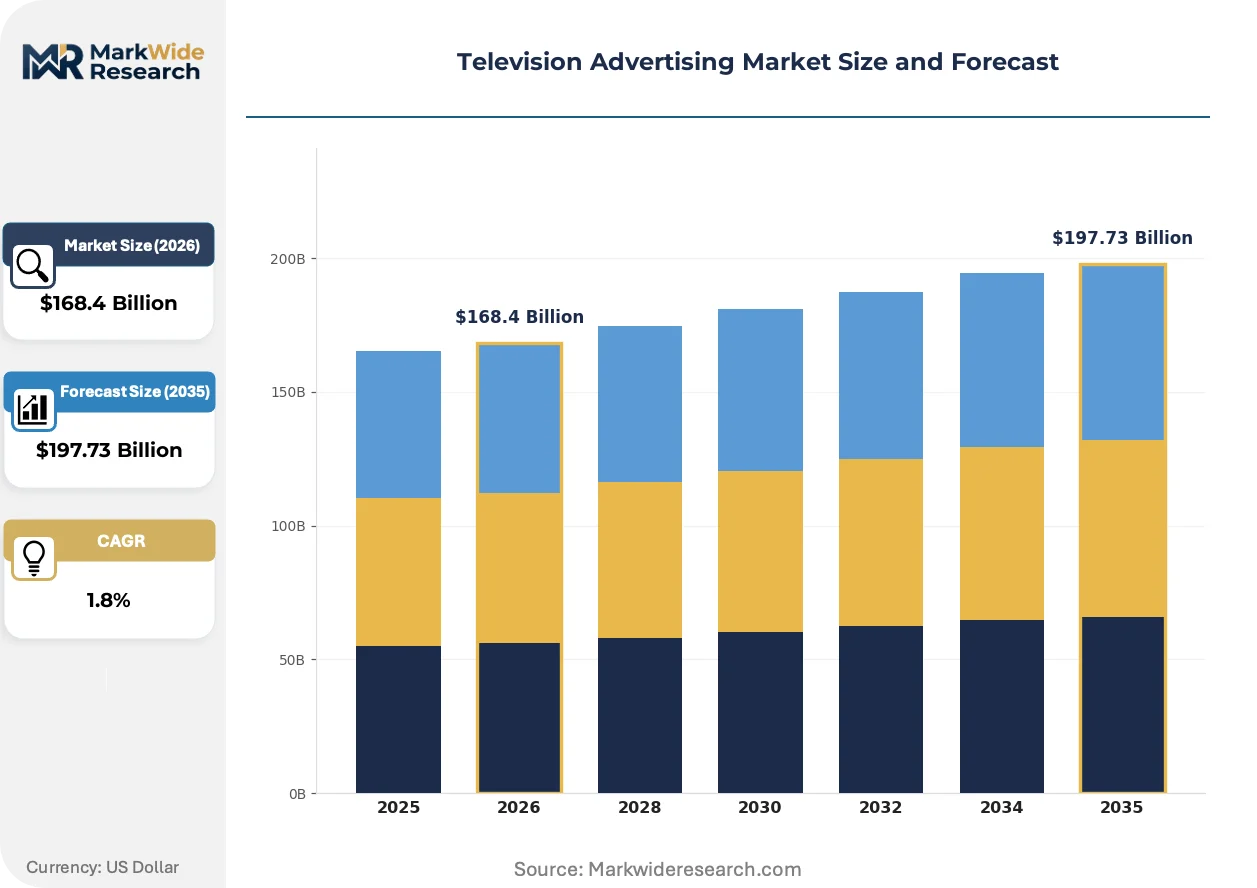
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $197.73 Billion |
| CAGR (2026 – 2036) | 1.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Video Ads, Infomercials, Sponsorships, Product Placements Target Audience: Families, Young Adults, Seniors, Kids Industry Vertical: Consumer Electronics, Automotive, FMCG, Pharmaceuticals Broadcast Type: Live Programming, On-Demand, Streaming Services, Cable |
| Companies Covered | Comcast, Walt Disney, AT&T, NBCUniversal, Fox Corporation, Amazon, Google, Netflix, ViacomCBS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Television Advertising Market Strategic Shifts & Innovations
Television advertising infrastructure is bifurcating between legacy upfront commitments and auction-based liquidity, with technology vendors racing to bridge operational workflows that were never designed to coexist.
Server-side ad insertion is consolidating how premium streaming inventory gets monetized, replacing client-side calls that ad blockers intercept. Broadcasters including NBCUniversal and Paramount Global are deploying this architecture for live events where latency tolerance is minimal. The technology is consolidating control over ad decisioning within platform infrastructure rather than exposing it to browser-level interference.
The FTC is intensifying truth-in-advertising enforcement against health product claims shown on connected TV, applying standards developed for broadcast to interactive formats where click-through creates additional liability. Pharmaceutical advertisers are responding by pre-clearing all creative through legal review processes that add two to three weeks to campaign launch timelines. This regulatory friction is most acute in direct-to-consumer drug marketing, where abbreviated risk disclosures face heightened scrutiny.
Advertisers are unbundling media buying from creative production, establishing in-house studios to generate dynamic creative optimization variants at scale. Automotive brands are deploying this capability to localize vehicle offers by dealership geography without incurring agency production fees. This operational shift is most visible in the United States, where dealer co-op funding structures incentivize hyper-local campaign execution.
Television Advertising Market Segmentation
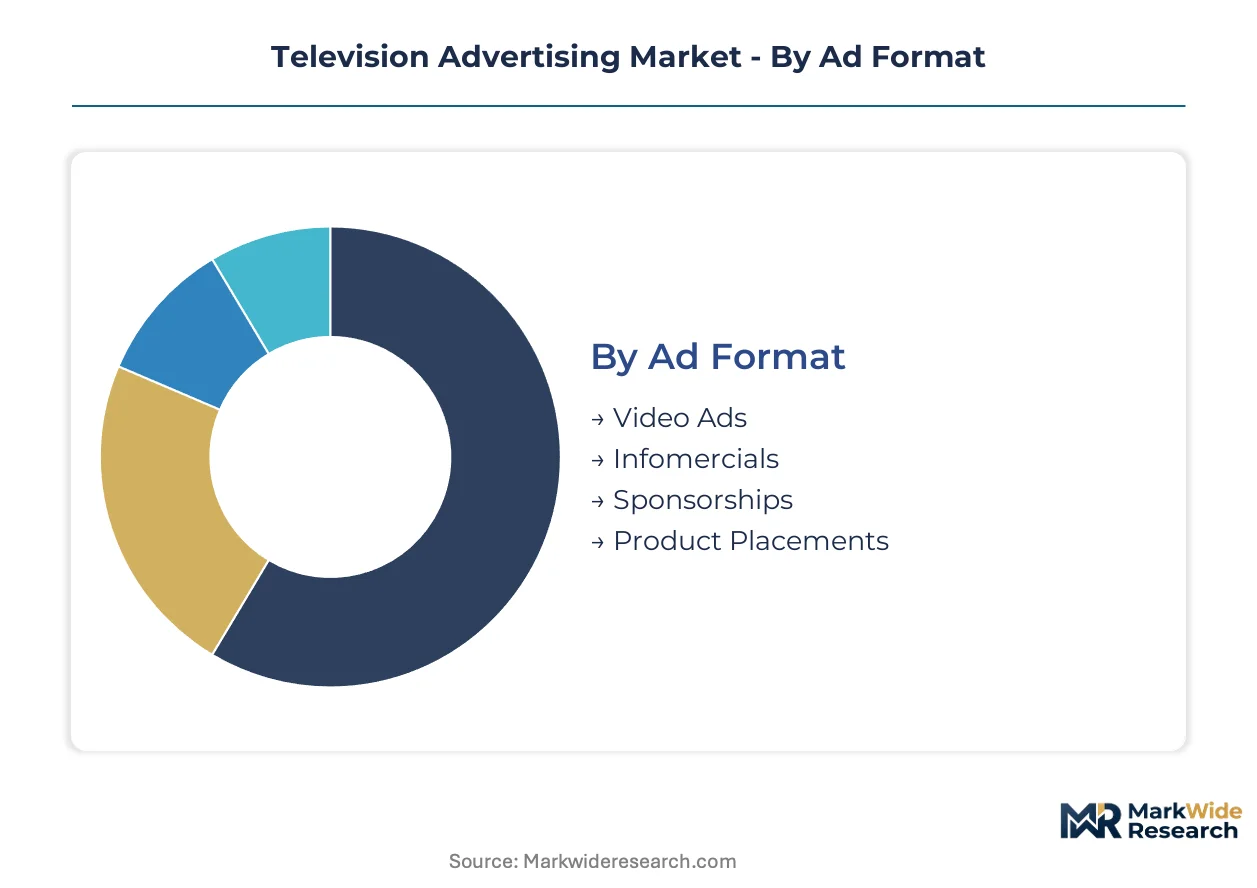
Television advertising inventory fragments across technical delivery mechanisms, demographic precision, and programming contexts that determine pricing power. Advertisers calibrate spend allocation across these dimensions to optimize reach against frequency trade-offs in an increasingly addressable marketplace.
Ad Format:
Regulatory scrutiny from the FTC intensifies based on format type, with infomercials facing heightened truth-in-advertising enforcement compared to standard spot inventory.
- Video Ads:Fifteen-to-sixty-second promotional spots delivered during programming breaks. Automotive and pharmaceutical buyers concentrate upfront commitments here, driven by mass-reach brand awareness objectives and established measurement currencies.
- Infomercials:Long-form direct-response programming typically running thirty to sixty minutes. Demand clusters among health product marketers seeking direct purchase attribution, though FTC pre-clearance requirements extend campaign launch timelines by two to three weeks.
- Sponsorships:Integrated brand association with specific programs or program segments.
- Product Placements:Embedded brand appearances within scripted or unscripted content.
Leading the category by volume: Video Ads. Growing fastest: Product Placements.
Target Audience:
Pricing tiers diverge sharply based on household composition data, with platforms commanding premiums for audiences demonstrating established purchase patterns in CPG categories.
- Families:Multi-generational households with consolidated purchasing decisions. Retail media networks from Walmart and Target prioritize this segment for closed-loop attribution connecting television exposure to in-store transaction data.
- Young Adults:Eighteen-to-thirty-four demographic with streaming-first consumption patterns. Connected TV platforms capture migration of this audience from linear bundles, expanding addressable inventory pools for digital-native advertisers.
- Seniors:Fifty-five-plus viewers retaining linear television loyalty.
- Kids:Under-twelve audience subject to COPPA and state-level privacy constraints.
Highest CPM concentration: Young Adults. Steepest inventory expansion: Families.
Industry Vertical:
Creative production requirements and regulatory pre-clearance burdens segment vertical demand, with pharmaceutical and financial advertisers facing extended legal review cycles.
- Consumer Electronics:Seasonal product launch cycles drive concentrated Q4 spending. Device manufacturers deploy dynamic creative optimization to localize offers by retail availability without incurring agency production fees.
- Automotive:Dealer co-op funding structures in the United States incentivize hyper-local campaign execution. OEMs maintain in-house studios to generate geographic variants at scale, unbundling media buying from creative production.
- FMCG:Packaged goods brands with continuous purchase cycles.
- Pharmaceuticals:Prescription drug marketers navigating FDA and FTC dual jurisdiction.
Dominant upfront commitment volume: Automotive. Most rapid budget reallocation: Consumer Electronics.
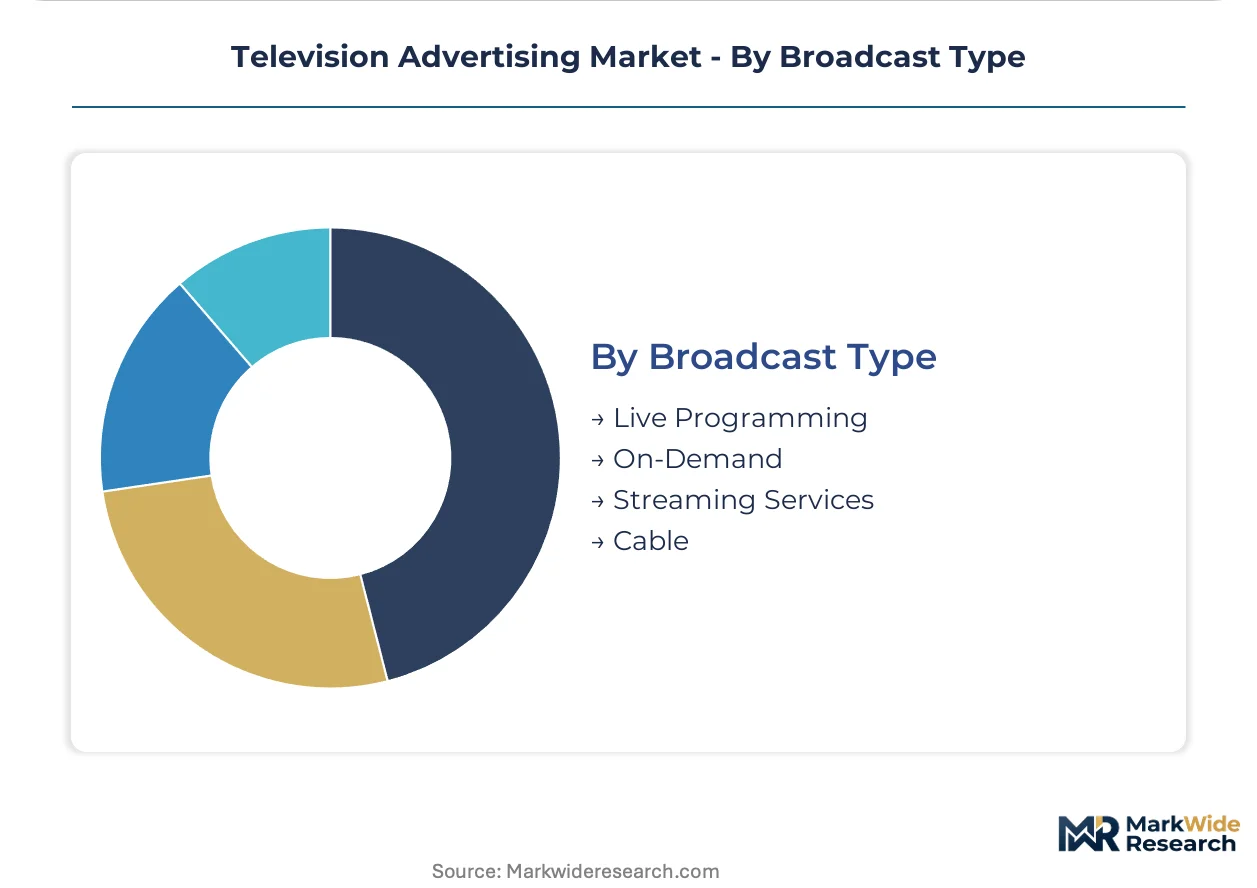
Broadcast Type:
Infrastructure investment requirements and latency tolerance determine which delivery mechanisms support premium live inventory versus addressable precision.
- Live Programming:Real-time content including sports and news with minimal latency tolerance. Professional leagues reserve streaming rights for dedicated platforms, concentrating premium video ad placements in events demonstrating co-viewing resistance.
- Streaming Services:Internet-protocol delivery with server-side ad insertion architecture. NBCUniversal and Paramount Global deploy this technology to consolidate ad decisioning control and eliminate browser-level interference from ad blockers.
- On-Demand:Time-shifted content with personalized ad replacement capabilities.
- Cable:Traditional linear distribution with residual local market penetration value.
Largest current inventory pool: Live Programming. Fastest share gain: Streaming Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Content production concentrates in Los Angeles and New York, while advertising expenditure distributes across major metropolitan consumption clusters. National platforms command premium inventory in dense population corridors. Regulatory fragmentation constrains cross-border campaign execution.
United States
Pharmaceutical and automotive advertisers drive upfront commitments through connected TV platforms. FCC media ownership caps limit station consolidation in designated market areas, preserving local spot competition. New York and Los Angeles anchor content production infrastructure, while Chicago and Dallas-Fort Worth concentrate regional advertising operations for national brand campaigns.
United Kingdom
Broadcasters compete for streaming migration budgets from subscription-fatigued households. Ofcom enforces media plurality rules that restrict cross-media ownership concentration. London dominates creative production and agency headquarters, with Manchester and Birmingham emerging as regional production hubs for addressable advertising technology development.
Germany
Automotive OEMs deploy dealer co-op funding for hyper-local television campaign execution. The Commission for the Protection of Minors in the Media enforces strict content standards affecting ad placement windows. Hamburg and Munich concentrate media company headquarters, while Cologne anchors production facilities for live sports broadcasting infrastructure.
Japan
Consumer electronics brands localize dynamic creative variants for seasonal product launches. METI guidelines govern data usage in addressable advertising systems. Tokyo and Osaka host broadcaster headquarters, with Fukuoka developing streaming technology infrastructure for programmatic ad insertion.
Brazil
FMCG brands redirect spend toward ad-supported streaming tiers as linear subscriptions decline. ANATEL regulates broadcast spectrum allocation affecting regional station reach. São Paulo concentrates advertising agency networks, while Rio de Janeiro maintains production facilities for live entertainment programming.
Television Advertising Market Key Industry Players
Top-tier vendors anchor national broadcast and streaming infrastructure, while mid-tier platforms compete for addressable inventory pools. The market structures around three tiers: integrated media conglomerates controlling content and distribution, technology platforms intermediating programmatic auctions, and specialized streaming services building ad-supported subscriber bases. Competitive moves concentrate on server-side ad insertion architecture deployment and exclusive sports rights acquisition for live event inventory.
Among integrated media conglomerates, Comcast and Walt Disney occupy positions controlling both linear distribution and streaming platform infrastructure. Google represents the technology platform archetype extending demand-side systems into connected TV auctions. These three entities exemplify distinct strategic approaches to consolidating ad decisioning control across broadcast and digital endpoints.
| Leading Market Players |
|---|
| Comcast |
| Walt Disney |
| AT&T |
| NBCUniversal |
| Fox Corporation |
| Amazon |
| Netflix |
| ViacomCBS |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up ad tech specialists have consolidated addressable inventory platforms across designated market areas, tightening supply discipline while extracting premium CPMs from pharmaceutical and automotive advertisers seeking household-level precision. This ownership concentration feeds directly into pricing power, as fragmented broadcasters lack comparable data management infrastructure to resist rate compression.
Pricing Analysis
Margin tightening in streaming inventory reflects programmatic auction liquidity collapsing the premium that linear upfront commitments once commanded. Three-tier pricing structure across premium live sports, standard entertainment programming, and economy remnant tiers segments buyer budgets by latency tolerance and measurement rigor. Cost-down pressure on addressable CTV inventory accelerates because retail media networks from Walmart and Target are building closed-loop attribution systems that undercut platform rate cards. Mid-market FMCG brands exhibit highest price sensitivity, while pharmaceutical direct-to-consumer advertisers demonstrate lowest elasticity due to FDA pre-clearance sunk costs.
Supply Chain Analysis
Regional distribution centers for ad decisioning infrastructure concentrate in Los Angeles, New York, and London, with secondary hubs emerging in Hamburg and Tokyo to reduce latency for live sports auctions. Raw material dependencies include cloud compute capacity from AWS and Azure, third-party data from Experian and Acxiom, and measurement currency from Nielsen and iSpot. Single-source vulnerability in server-side ad insertion technology creates chokepoint risk as NBCUniversal and Paramount Global deploy proprietary architectures. Distribution runs through programmatic pipes that collapse distinctions between linear and digital endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The television advertising market is becoming a vertical-integration race as platforms pursue downstream control over measurement currency to escape Nielsen's accreditation monopoly.
For Market Incumbents: Lock in exclusive sports streaming rights before professional leagues fragment inventory across multiple platforms. Consolidate ad decisioning infrastructure through server-side insertion architecture that eliminates browser-level interference. Threat substitution from retail media networks demands countermeasures via closed-loop attribution partnerships with grocery and pharmacy chains. For New Entrants and Emerging Players: The price-point gap between premium live sports CPMs and economy streaming remnant inventory offers entry space for specialized platforms serving mid-market automotive dealers. Target local broadcast station groups in designated market areas where FCC ownership caps prevent national platform consolidation. Go-to-market leverage rests on dealer co-op funding workflows that incumbent platforms have neglected. For Investors and Strategic Acquirers: Automatic content recognition deployment by smart TV manufacturers is the leading indicator that screen-level data capture will displace set-top-box measurement within the analysis window. Long-term viability favors platforms controlling both content production and ad tech infrastructure. Acquisition target archetype: addressable technology vendors with household graph assets and live event latency optimization. Signal to watch: FTC enforcement actions against health product claims that extend legal review timelines and concentrate spend among compliant platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Server-Side Ad Insertion Deployment | NBCUniversal and Paramount Global consolidate ad decisioning control against ad blocker erosion. |
| Exclusive Sports Rights Acquisition | Professional leagues concentrate premium inventory in platforms demonstrating co-viewing resistance. |
| Retail Media Network Partnership | Walmart and Target connect television exposure to in-store transaction data for FMCG attribution. |
| Dynamic Creative Optimization Buildout | Automotive OEMs localize dealer offers without agency production fees through in-house studios. |
| Measurement Currency Diversification | Platforms reduce Nielsen dependency through iSpot and Samba TV alternative accreditation paths. |
Research Approach
Trade association filings from the Television Bureau of Advertising, FCC ownership databases, and SEC 10-K disclosures from Comcast and Walt Disney formed the secondary backbone for inventory and revenue estimation. Primary interviews with broadcast sales executives, programmatic platform engineers, pharmaceutical marketing directors, and automotive dealer association representatives validated spend allocation assumptions. Bottom-up triangulation across station-level spot rates and top-down reconciliation against national advertising expenditure estimates anchored volume projections.
Bottom-up modeling of addressable impression growth across connected TV platforms combined with top-down constraint from household penetration ceilings. Segmentation dimensions included ad format type, broadcast delivery mechanism, target audience demographic, and industry vertical creative requirements. CAGRs were derived from trend extrapolation of subscription-fatigued household migration to ad-supported tiers, adjusted for privacy regulation friction. Forecast inputs incorporated FCC media ownership rule stability and FTC truth-in-advertising enforcement intensity.
Inputs from Nielsen panel data and digital ad server logs were available through the study window; gaps in cross-platform audience verification introduce uncertainty bands around reach-frequency estimates. Forecasts reflect documented assumptions regarding streaming tier adoption curves and addressable technology deployment timelines. Privacy framework fragmentation and linear inventory erosion constitute primary revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Cloud TV Market
Television
Television Market
Television
Pay TV Market
Television
Holographic TV Market
Television
Global Broadcast Equipment Market
Television
Pay TV Services Market
Television
Cable Television Networks Market
Television
Broadcasting and Cable TV Market
Television
Cloud Television (TV) Market
Television
Digital TV Market
Television
TV Advertising Market
Television
Television and Set Top Box Market
Television
Curved Television Market
Television
Free-To-Air (FTA) Service Market
Television
Traditional TV and Home Video Market
Television
Print Newspapers and Magazines Market