
 Video on Demand Market | 2026-2036
Video on Demand Market Size, Share, and Industry Trends Forecast 2026-2036
Video on Demand Market Analysis
4K HDR streaming tiers is collapsing the gap between theatrical and home viewing experiences. Netflix, Inc. leverages its proprietary encoding pipeline to deliver premium bitrate efficiency across broadband and mobile networks. Amazon.com, Inc. anchors its VoD expansion through Prime Video's integration with AWS infrastructure, sustaining low-latency delivery at scale. The Walt Disney Company differentiates through franchise-exclusive content libraries that command subscriber loyalty across its bundled streaming portfolio.
Video on Demand refers to a digital content distribution system enabling users to select and view video programming on demand via internet protocol delivery, typically employing adaptive bitrate streaming protocols such as HLS or DASH to match content quality to real-time network conditions. The technology serves commercial entertainment distribution, educational content delivery, and enterprise training applications through cloud-hosted content delivery networks. SVOD subscription models dominate revenue pools across mature markets, while AVOD formats capture fastest-growing user bases in price-sensitive regions where ad-supported viewing offsets subscription fatigue. Smart TV device types concentrate the highest average revenue per user due to premium viewing experiences, whereas mobile devices drive volume scale in emerging markets where smartphones serve as primary screens.
The FCC governs net neutrality and broadband classification rules that directly affect streaming quality-of-service guarantees and interconnection fees between content platforms and internet service providers in the United States. GDPR and the EU AI Act impose cross-border constraints on personalized recommendation engines and viewer data monetization, compelling platforms to restructure algorithmic transparency and consent mechanisms for European subscribers. Stakeholders must monitor evolving spectrum allocation decisions and content localization mandates that will determine platform economics in high-growth markets.
Market Dynamics
Adaptive bitrate streaming protocols are compressing infrastructure costs while expanding addressable audiences across broadband-constrained geographies. Platform operators now optimize encoding pipelines to serve tier-one metropolitan fiber subscribers and rural 4G mobile users through unified delivery architectures.
Growth Catalysts
- EU AI Act compliance frameworks:Mandates for algorithmic transparency are accelerating investment in explainable recommendation engines. European platforms restructure data handling to maintain personalization capabilities under stricter consent mechanisms.
- Educational institutional adoption:Universities and K-12 systems deploy lecture-capture and asynchronous learning platforms at scale. Campus network infrastructure upgrades support synchronous streaming for remote degree programs.
- India mobile-first consumption patterns:Regional language content investments attract subscriber bases outside Hindi and English markets. Platform localization strategies target Tamil, Telugu, and Marathi content production.
Market Restraints
- Content licensing cost inflation:Exclusive franchise rights command premium renewal rates. Sports broadcasting agreements compress margins for general entertainment bundling.
- CDN infrastructure concentration:Three hyperscale cloud providers dominate edge server deployment. Platform operators face vendor lock-in risks for low-latency delivery guarantees.
- Net neutrality rule uncertainty:FCC broadband classification shifts threaten quality-of-service prioritization. Interconnection fee disputes between ISPs and streaming platforms escalate operational friction.
Strategic Opportunities
- Live streaming commerce integration:Shoppable video formats merge entertainment with transactional functionality. Chinese platform models demonstrate conversion rates that attract Western market experimentation.
- Enterprise training vertical expansion:Compliance certification and skills credentialing demand secure, trackable video delivery. Corporate learning management system integrations open B2B revenue streams.
- 5G network slicing capabilities:Mobile operators offer guaranteed bitrate tiers for premium streaming subscriptions. Quality-of-service differentiation enables tiered pricing structures beyond standard data plans.
Industry Challenges
- Codec patent pool complexity:AV1, HEVC, and VVC licensing frameworks create royalty stacking risks. Platform engineering teams navigate fragmented intellectual property landscapes for next-generation compression.
- Legacy broadcast system integration:Traditional media companies operate hybrid linear and on-demand workflows. Content management system unification demands substantial middleware investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video on Demand Market |
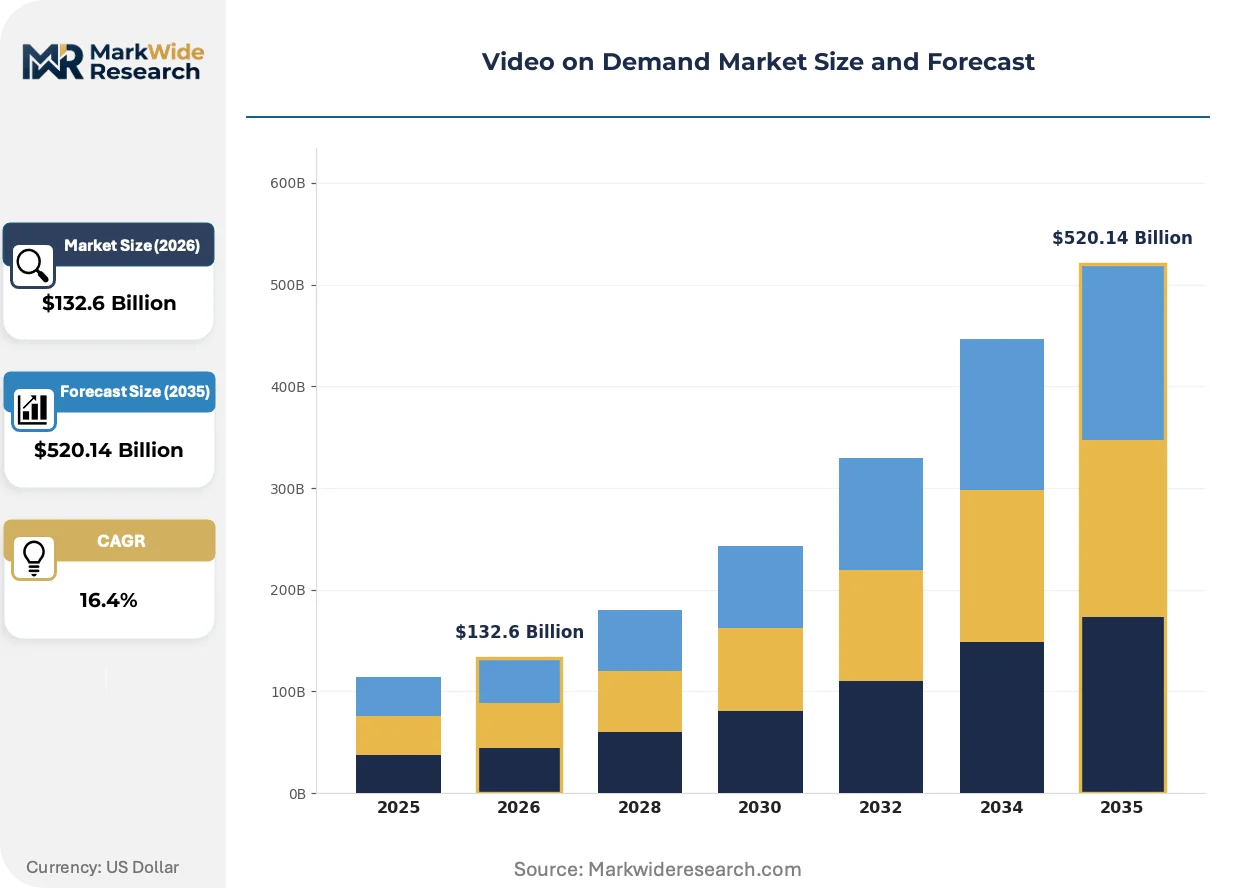
| Market Size in 2026 | $132.6 Billion |
| Market Size in 2035 | $520.14 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: SVOD, AVOD, TVOD, Freemium Content Type: Movies, TV Shows, Documentaries, Sports Device Type: Smart TVs, Mobile Devices, Set-top Boxes, PCs Customer Type: Individual Subscribers, Businesses, Educational Institutions, Family Units |
| Companies Covered | Netflix, Inc., Amazon.com, Inc., The Walt Disney Company, Alphabet Inc. (Google), Apple Inc., Warner Bros. Discovery, Inc., Comcast Corporation, Paramount Global, Tencent Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video on Demand Market Emerging Trajectories
Codec innovation and regulatory compliance are restructuring competitive economics across the streaming value chain. Platform differentiation increasingly depends on proprietary technical infrastructure rather than content library scale alone.
AV1 open-source video compression is displacing H.264 as the default encoding standard for bandwidth-constrained markets. Mid-tier streaming services adopt AV1 to reduce CDN egress costs while maintaining 1080p quality at 30% lower bitrates. This codec transition compresses infrastructure spending for platforms competing against encoding-optimized incumbents.
GDPR and EU AI Act cross-border enforcement is mandating algorithmic audit trails for content recommendation systems. European subscribers now receive explicit explanations for personalized rankings, forcing platforms to reengineer black-box machine learning pipelines. Compliance investments concentrate in France and Germany where CNIL and national regulators impose the strictest interpretation timelines.
Subscription fatigue is fragmenting household spending across multiple niche services rather than two-to-three dominant platforms. Indian and Southeast Asian consumers demonstrate higher tolerance for ad-supported tiers, displacing pure SVOD models in price-sensitive demographics. Platform operators respond with hybrid AVOD-SVOD architectures that match monetization strategy to regional purchasing power.
Video on Demand Market Segmentation
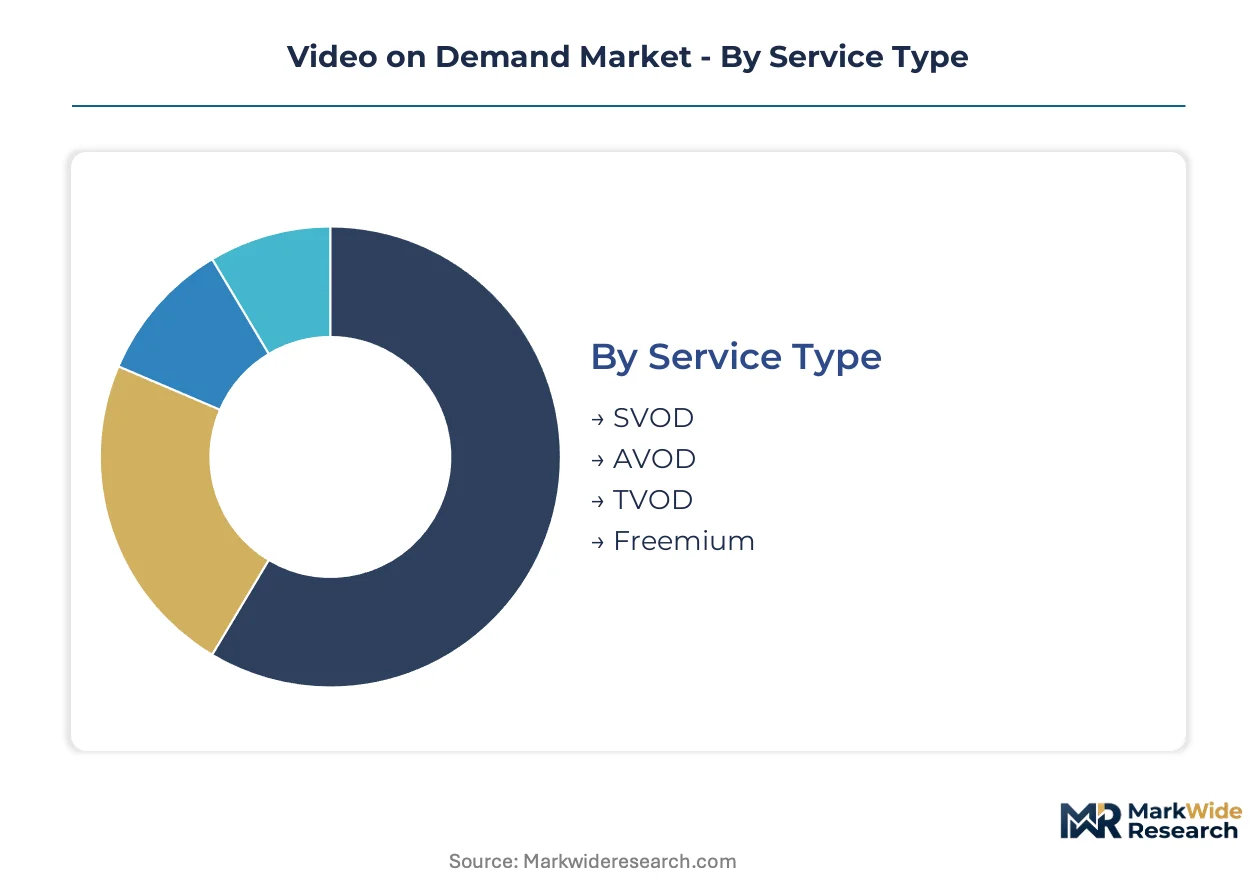
Streaming economics diverge sharply across monetization models and viewing contexts. Platform operators calibrate encoding investments, content licensing strategies, and pricing architectures to match the technical requirements and willingness-to-pay of distinct segment combinations.
Service Type:
SVOD subscriptions flow through direct-to-consumer channels with recurring billing infrastructure, while AVOD monetization depends on programmatic advertising stacks and brand partnership networks.
- SVOD:Subscription video on demand locks consumers into monthly or annual payment cycles with unlimited content access. Households in Germany and France concentrate demand here, driven by GDPR-compliant personalization engines that justify premium pricing through curated libraries.
- AVOD:Ad-supported video on demand eliminates subscription barriers in exchange for commercial interruptions. Indian and Southeast Asian markets drive expansion, where regional language content attracts mass audiences that advertisers covet for demographic targeting.
- TVOD:Transactional video on demand enables single-title rental or purchase without ongoing commitment. Catalog depth in recent theatrical releases sustains this model.
- Freemium:Hybrid tiers combine limited free access with subscription upsell pathways. Conversion optimization from ad-supported to paid tiers shapes platform unit economics.
SVOD dominates installed base in mature broadband markets. AVOD is where expansion concentrates in mobile-first emerging economies.
Content Type:
Production cost tiers and licensing windows structure how each content category reaches audiences through exclusive versus non-exclusive distribution arrangements.
- Movies:Feature-length theatrical releases command premium licensing fees during exclusive streaming windows. Studio franchise properties in the United States drive subscriber acquisition campaigns with billion-dollar production budgets.
- TV Shows:Serialized episodic content generates sustained engagement through binge-release or weekly drop strategies. Korean and Turkish drama exports are climbing the fastest in cross-border catalog licensing.
- Documentaries:Non-fiction programming serves niche but high-retention audience segments. Factual content costs less to produce than scripted alternatives.
- Sports:Live event broadcasting requires specialized low-latency infrastructure and regional rights fragmentation. League-specific exclusivity deals compress margins for general entertainment bundling.
TV Shows dominate installed base through serialized engagement mechanics. Sports is where expansion concentrates as platforms compete for live viewership loyalty.
Device Type:
Screen size and network connectivity profile determine encoding pipeline complexity and quality-of-service guarantees across delivery endpoints.
- Smart TVs:Large-format displays with dedicated streaming applications deliver premium viewing experiences. Living room installations in Japan and South Korea support 4K HDR bitrates that maximize average revenue per user.
- Mobile Devices:Smartphones and tablets operate on variable cellular networks with data consumption constraints. Rural Indian subscribers on 4G networks drive volume scale where adaptive bitrate protocols compress streams to 480p during congestion.
- Set-top Boxes:Operator-managed hardware bridges legacy broadcast and IP-delivered content. Cable and satellite incumbents deploy these for hybrid service retention.
- PCs:Browser-based viewing serves workplace and educational contexts with full keyboard navigation. Desktop sessions show higher documentary and long-form engagement.
Smart TVs dominate installed base in fiber-connected metropolitan markets. Mobile Devices is where expansion concentrates as primary screens in emerging economies.
Customer Type:
Procurement authority and budget source reshape contract structures, from individual credit card transactions to institutional purchase orders with compliance requirements.
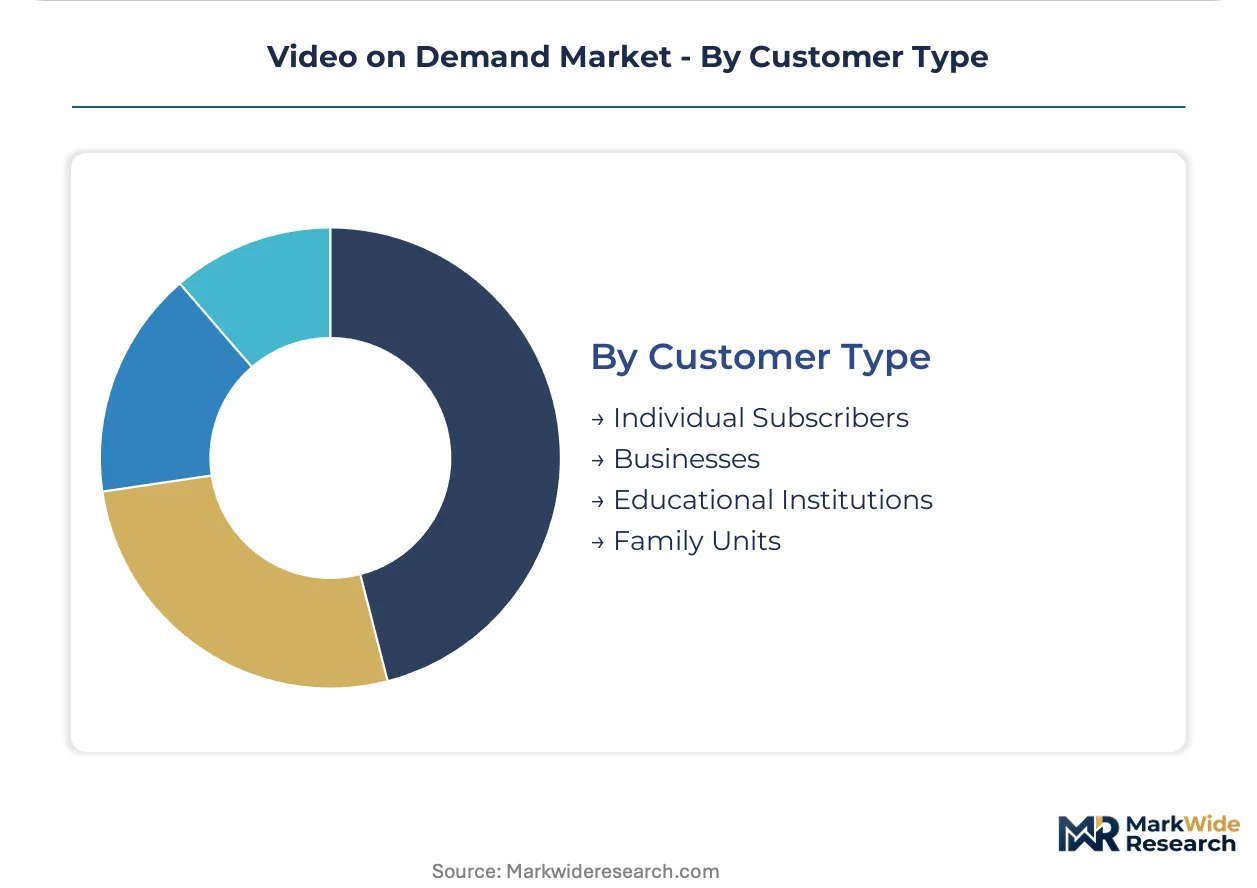
- Individual Subscribers:Consumer households purchase services with personal payment instruments and cancellation flexibility. Urban professionals in Brazil and Mexico demonstrate highest willingness-to-pay for bundled entertainment stacks.
- Businesses:Corporate accounts license content for internal communications, marketing, and customer-facing applications. Enterprise training verticals in the United States require secure delivery with viewership analytics.
- Educational Institutions:Universities and K-12 systems deploy asynchronous learning platforms with lecture-capture integration. Campus network upgrades support synchronous streaming for remote degree programs.
- Family Units:Multi-profile household plans with parental controls and content filtering serve intergenerational viewing. Shared subscription credentials across extended relatives challenge revenue recognition.
Individual Subscribers dominate installed base through direct-to-consumer scale. Educational Institutions is where expansion concentrates as learning management system integrations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian subscribers demonstrate extreme price elasticity with ad-supported tiers dominating uptake, while Japanese and South Korean households sustain premium pricing for 4K HDR experiences. German consumers occupy a middle ground where GDPR-compliant personalization justifies moderate subscription premiums.
United States
FCC net neutrality rulings and broadband reclassification debates create regulatory uncertainty for streaming quality-of-service guarantees. Interconnection fee disputes between ISPs and platforms escalate operational friction in California and New York media corridors. Los Angeles studio clusters anchor original content production investments exceeding billion-dollar annual commitments.
Germany
GDPR and EU AI Act enforcement by CNIL-aligned state regulators mandate algorithmic audit trails for recommendation engines. Bavarian and North Rhine-Westphalia subscriber bases demand transparency in personalized rankings. Berlin-Brandenburg hosts compliance technology vendors reengineering black-box machine learning pipelines for European platforms.
India
Mobile-first consumption patterns and regional language content investments drive platform expansion beyond Hindi and English markets. TRAI data localization requirements reshape content delivery network architectures. Mumbai and Bengaluru production hubs scale Tamil, Telugu, and Marathi original series for smartphone-primary audiences.
Japan
METI spectrum allocation decisions determine 5G network slicing capabilities for premium streaming tiers. Tokyo and Osaka metropolitan fiber networks support 8K experimental broadcasts and ultra-low latency live events. Consumer willingness-to-pay for bundled entertainment stacks sustains highest average revenue per user in Asia-Pacific.
South Korea
MFDS-aligned content rating systems and KCC broadcasting regulations govern streaming platform licensing. Seoul Capital Area smart TV penetration enables 4K HDR at scale with dedicated streaming applications. Busan-Ulsan production clusters specialize in K-drama exports climbing cross-border catalog licensing rankings.
Video on Demand Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the streaming value chain. Encoding-optimized incumbents with proprietary pipelines compete against infrastructure-leveraged challengers achieving scale through cloud partnerships. The market structures around three strategic archetypes: content-integrated studios, platform-native streamers, and telecom-cabled distributors. Dominant competitive moves include franchise-exclusive licensing auctions and regional content localization partnerships.
Within the platform-native tier, Netflix, Inc. and Amazon.com, Inc. occupy positions defined by technical infrastructure investment rather than studio legacy assets. The Walt Disney Company exemplifies the content-integrated archetype where franchise libraries command subscriber loyalty across bundled portfolios. These three entities represent divergent strategic paths—proprietary encoding, cloud-leveraged delivery, and intellectual property monetization—shaping competitive dynamics for mid-tier challengers.
| Leading Market Players |
|---|
| Netflix, Inc. |
| Amazon.com, Inc. |
| The Walt Disney Company |
| Alphabet Inc. (Google) |
| Apple Inc. |
| Warner Bros. Discovery, Inc. |
| Comcast Corporation |
| Paramount Global |
| Tencent Holdings Limited |
| Others |
Supply Flow & Price Mechanics
FCC broadband classification rulings gate both CDN qualification for quality-of-service guarantees and the price differentiation available to platforms negotiating interconnection fees with internet service providers. This regulatory framework simultaneously shapes infrastructure vendor selection and the tiered subscription pricing that platforms can sustain across metropolitan fiber and rural mobile networks.
Pricing Analysis
Ad-supported revenue tiers drive lifetime value for platforms competing in price-sensitive emerging markets. Three-tier pricing structure across premium, standard, and economy levels segments subscribers by device capability and network quality, with Smart TV households in Japan and South Korea sustaining premium 4K HDR rates while mobile-first Indian users gravitate toward free ad-supported entry points. Cost compression in premium encoding pipelines is intensifying because AV1 adoption reduces CDN egress spending for mid-tier challengers. Educational institutions demonstrate lowest price sensitivity due to procurement through campus IT budgets, whereas individual subscribers in Southeast Asia exhibit highest elasticity.
Supply Chain Analysis
Strait of Malacca transit underwrites the submarine cable routes that carry the majority of Asia-Pacific streaming traffic to edge server locations. Hyperscale cloud concentration in the United States, Ireland, and Singapore anchors global CDN infrastructure, with platform operators drawing from AWS, Azure, and Google Cloud for low-latency delivery guarantees. Raw material dependencies span silicon wafers for encoding hardware, rare earth elements for data center magnets, and submarine cable sheathing compounds. Single-source vulnerability concentrates in undersea cable landing stations. Distribution runs through direct-to-consumer app stores and smart TV manufacturer pre-installation agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward educational institutions and enterprise training departments as these segments consolidate procurement through learning management system integrations. This fragmentation among consumer households across multiple niche subscriptions simultaneously weakens platform pricing leverage.
For Market Incumbents: Secure exclusive regional content licensing in Tamil, Telugu, and Marathi markets before local production hubs mature. Deepen backward integration into proprietary encoding pipelines to defend against AV1-optimized challengers. Threat substitution from telecom operators offering 5G network slicing bundles demands pre-emptive quality-of-service tier development. For New Entrants and Emerging Players: Anchor in enterprise training verticals where compliance certification demand outstrips secure video delivery supply. The most penetrable segment sits in healthcare skills credentialing for hospital systems requiring audit-trail viewership analytics. A channel partnership with established learning management system vendors accelerates B2B customer acquisition without consumer marketing spend. For Investors and Strategic Acquirers: EU AI Act algorithmic transparency mandates reshape the acquisition landscape toward platforms with explainable recommendation engine infrastructure already deployed. Long-term viability favors targets with hybrid AVOD-SVOD architectures proven across multiple emerging market regulatory environments. The signal to watch is TRAI data localization enforcement intensity in India, which would advantage domestic platform operators over foreign entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Content Localization Partnership | Tamil and Telugu original series production captures subscriber loyalty outside Hindi-English markets in India. |
| Proprietary Encoding Pipeline Investment | Netflix's custom pipeline delivers bitrate efficiency that compresses infrastructure costs against cloud-dependent rivals. |
| Enterprise LMS Integration | Corporate learning management system partnerships open B2B revenue streams with higher retention than consumer subscriptions. |
| 5G Network Slicing Alliance | Mobile operator quality-of-service guarantees enable premium tier pricing beyond standard data plan limitations. |
| Algorithmic Transparency Compliance | GDPR and EU AI Act audit trail infrastructure defends European market access against regulatory enforcement action. |
Methodological Framework
Initial hypotheses were tested against primary input from streaming platform CTOs, content licensing executives, CDN infrastructure engineers, and educational technology procurement officers and refined through secondary validation. Regulatory filings with the FCC, TRAI submissions, EU AI Act implementation guidance, and hyperscaler capex disclosures anchored quantitative sizing. Bottom-up subscriber and revenue modeling triangulated against top-down market aggregation.
Variance decomposition across service type, content category, device endpoint, and customer procurement authority shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic consumption indicators. Forecast inputs incorporated mobile data pricing trajectories in India, fiber penetration curves in Japan and South Korea, and GDPR enforcement intensity indices for European markets.
Material uncertainties — regulatory reclassification of broadband service tiers, codec patent pool litigation outcomes, and spectrum allocation delays for 5G network slicing — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as FCC net neutrality rulemaking and EU AI Act enforcement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Video Streaming (OTT) Services
Online Streaming Service Market
Video Streaming (OTT) Services
Sports Streaming Platform Market
Video Streaming (OTT) Services
Subscription Video on Demand (Svod) Market
Video Streaming (OTT) Services
Media Streaming Market
Video Streaming (OTT) Services
Streaming Media Services Market
Video Streaming (OTT) Services
Video Streaming Market
Video Streaming (OTT) Services
Asia Pacific Video Streaming Market
Video Streaming (OTT) Services
Global Over-The-Top Content Market
Video Streaming (OTT) Services
Live Streaming Market
Video Streaming (OTT) Services
Global Over-The-Top Market
Video Streaming (OTT) Services
Live Streaming Pay-Per-View Market
Video Streaming (OTT) Services
Global Transactional Video on Demand Market
Video Streaming (OTT) Services
Indonesia OTT Market
Video Streaming (OTT) Services
Advertising-Based Video on Demand Market
Video Streaming (OTT) Services
Mexico OTT TV and Video Market
Video Streaming (OTT) Services
Over the Top (OTT) Services Market