
 Television and Set Top Box Market | 2026-2036
Television and Set Top Box Market Size, Share, and Industry Trends Forecast 2026-2036
Television and Set Top Box Market Analytics
The capital-intensity divergence between display panel fabricators and streaming-platform hardware assemblers is unwinding as OLED fabs demand multi-billion dollar cleanroom investments while set-top box makers scale through outsourced manufacturing. Samsung Electronics Co., Ltd. leverages captive semiconductor and display supply chains to control cost structures across premium television tiers. TCL Technology Group Corp. anchors its expansion on vertically integrated Gen 11 panel lines in Shenzhen and Huizhou. Hisense Co., Ltd. competes aggressively in laser TV projection, a niche where it avoids direct LCD price wars.
Television and set-top box systems encompass display panels, broadcast reception modules, and content decryption hardware engineered for resolutions spanning 720p to 8K with refresh rates up to 120 Hz, serving consumer entertainment and commercial signage applications. Smart TV functionality now demands embedded operating systems with app ecosystems, turning hardware into recurring service revenue platforms. Within technology segments, 4K LCD panels occupy the volume core while 8K and OLED variants capture disproportionate margin pools in residential and commercial end-user categories. Online retail channels are displacing specialty stores for set-top box distribution, though hypermarkets retain television showroom relevance in emerging markets.
The FCC mandates ATSC 3.0 broadcast compatibility, forcing hardware redesigns for US-bound televisions and tuners, while the EU Ecodesign Directive imposes standby power limits that filter inefficient set-top box designs from European markets. China's GB standards for energy-efficient displays and India's TRAI interoperability rules are creating divergent certification burdens for multi-region vendors. Stakeholders must monitor which regulatory jurisdiction tightens hardware efficiency or content accessibility requirements first, as compliance sequencing will determine factory allocation and inventory positioning across product cycles.
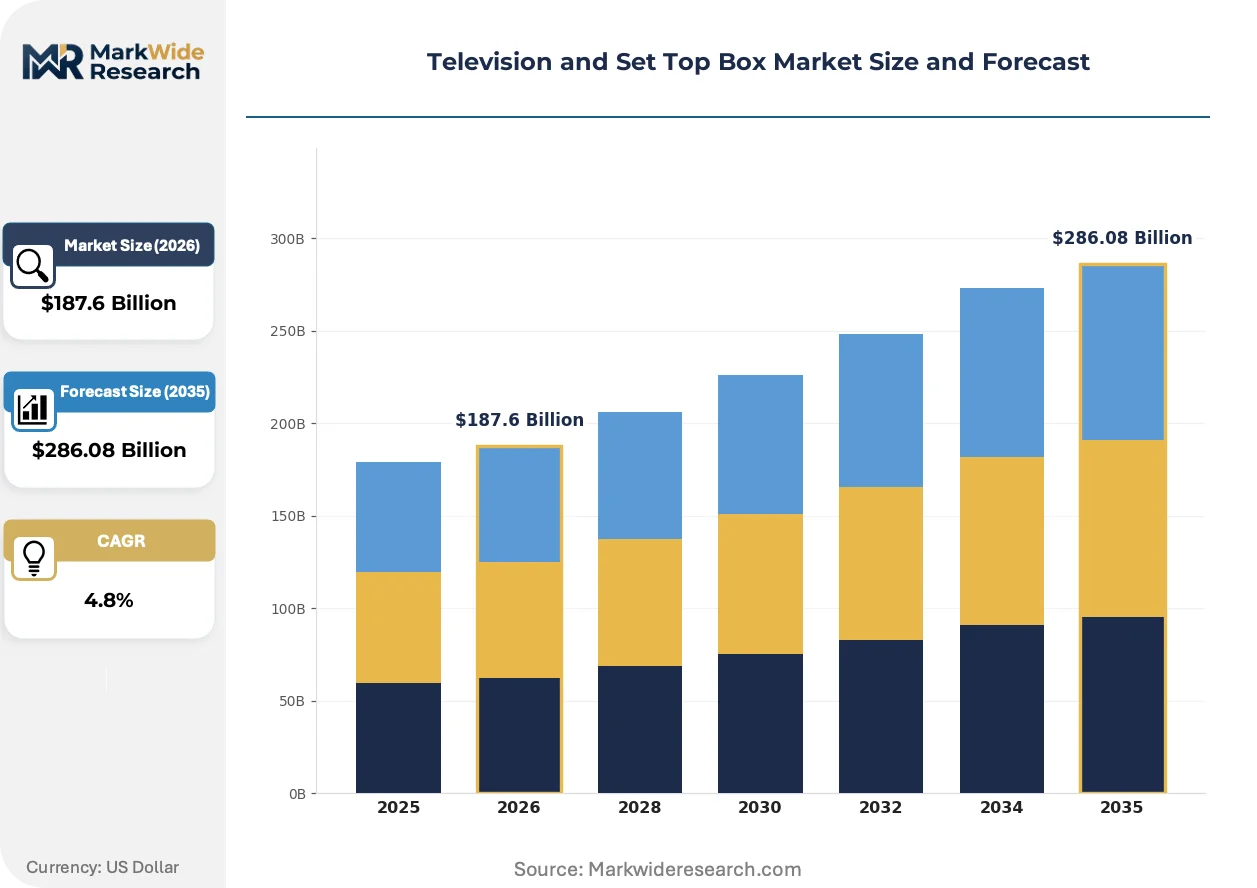
Market Dynamics
The ATSC 3.0 broadcast mandate from the FCC and parallel interoperability rules from India's TRAI are forcing simultaneous hardware redesigns across North American and South Asian supply chains, compressing product development cycles while fragmenting certification requirements.
Growth Catalysts
- Hospitality upgrade cycles:Hotel chains across the United States and Japan are replacing in-room entertainment systems with smart TV platforms that integrate streaming services and property management interfaces.
- TRAI interoperability mandate:India's requirement for transferable set-top boxes is accelerating hardware refresh rates and opening procurement to non-captive suppliers.
- Guangdong cluster expansion:Panel fabrication and ODM assembly concentration in Shenzhen and Huizhou is driving cost efficiencies for export-bound television manufacturers.
Market Restraints
- Display panel input volatility:OLED substrate and driver IC supply constraints are elevating bill-of-material costs for premium television tiers.
- Cleanroom capex concentration:Gen 10.5 and Gen 11 fab construction requires multi-billion dollar investments that lock capital for seven-to-ten year depreciation cycles.
- EU standby power limits:The Ecodesign Directive's efficiency thresholds are filtering older set-top box architectures from European market entry.
Strategic Opportunities
- Laser TV projection niche:Ultra-short-throw projection systems are capturing residential buyers seeking screen sizes above 100 inches without panel freight costs.
- Commercial signage pivot:QSR chains and retail banks are deploying 4K and 8K displays for menu boards and branch messaging, extending panel demand beyond residential replacement cycles.
- Online channel expansion:Direct-to-consumer set-top box distribution through e-commerce platforms is bypassing traditional telecom bundling arrangements in India and Southeast Asia.
Industry Challenges
- Multi-jurisdiction certification complexity:Simultaneous compliance with FCC ATSC 3.0, EU Ecodesign, and China's GB energy standards is elongating product launch timelines.
- Embedded software integration:Smart TV operating systems require sustained engineering investment for app ecosystem maintenance and security patch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Television and Set Top Box Market |
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $286.08 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart TV, OLED TV, QLED TV, LED TV Technology: 4K, 8K, HDR, LCD End User: Residential, Commercial, Educational, Hospitality Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Hisense Co., Ltd., Roku, Inc., Samsung Electronics Co., Ltd., HUMAX Co., Ltd., Huawei Technologies Co., Ltd., LG Electronics Inc., Sony Group Corporation, CommScope Holding Company Inc., TCL Technology Group Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Television and Set Top Box Market Evolving Landscape
Display technology roadmaps and content delivery architectures are diverging across residential, commercial, and hospitality end-uses, creating parallel innovation tracks rather than unified market evolution.
Mini-LED backlighting is bifurcating the premium LCD segment by delivering zone-dimmed contrast performance at price points below OLED alternatives. Hospitality procurement teams in the United States are specifying mini-LED televisions for guest room refreshes that must balance visual quality against five-year replacement budgets. The technology is compressing the addressable market for entry-level OLED panels in commercial installations below 75 inches.
The FCC's ATSC 3.0 mandate is forcing tuner module redesigns for all US-bound televisions and set-top boxes, with broadcasters in Dallas and Phoenix already transmitting next-gen signals. Manufacturers must maintain dual-sku inventories for ATSC 1.0 and 3.0 compatibility during the transition window. The regulation most acutely affects low-margin set-top box assemblers who lack firmware development scale to absorb certification costs.
Streaming service aggregation is displacing traditional channel bundles as the primary content discovery layer for smart TV purchasers. Buyers in India and Indonesia are prioritizing televisions with pre-installed global and regional streaming apps over set-top box rental arrangements. This behavioral shift is most visible in urban Indian households where fiber broadband penetration has crossed thresholds that support 4K streaming without buffering.
Television and Set Top Box Market Segmentation
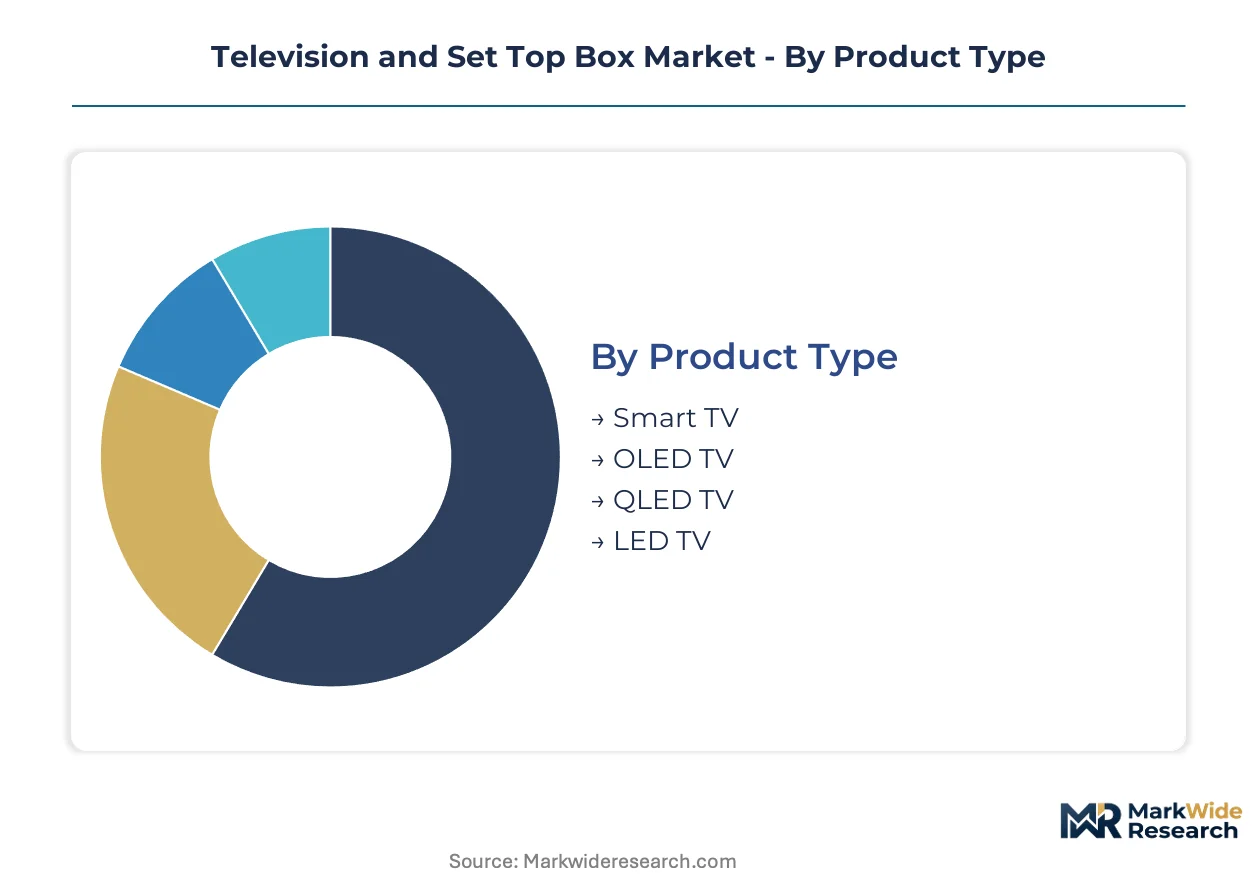
Television and set-top box procurement patterns diverge sharply across display technologies, resolution tiers, and end-use applications. Regulatory mandates on broadcast standards and energy efficiency are fragmenting product configurations by geography, forcing manufacturers to maintain parallel certification tracks.
Product Type:
FCC ATSC 3.0 compatibility requirements and EU Ecodesign standby power limits are filtering which product architectures qualify for North American and European market entry.
- Smart TV:Embedded operating systems with app ecosystems transform hardware into recurring service revenue platforms. Hospitality chains in the United States and Japan are specifying smart TV platforms for in-room entertainment refreshes that integrate streaming services and property management interfaces.
- OLED TV:Self-emitting pixel technology delivers infinite contrast ratios without backlighting layers. Supply constraints on OLED substrates and driver ICs are elevating bill-of-material costs for premium residential tiers in South Korea and Japan.
- QLED TV:Quantum dot-enhanced LCD panels extend color gamut through photoluminescent nanoparticles. Samsung Electronics leverages captive semiconductor supply chains to control cost structures across QLED television tiers.
- LED TV:Edge-lit and direct-lit LCD configurations with LED backlighting serve price-sensitive residential segments. Volume concentration in China's Guangdong province drives cost efficiencies for export-bound LED television manufacturers.
LED TV handles the majority of throughput; OLED TV is climbing the fastest on share.
Technology:
Resolution and display technology choices map directly to customer willingness-to-pay curves and content availability in each geography.
- 4K:Ultra-high-definition resolution at 3840 x 2160 pixels dominates volume shipments across all end-use categories. India's TRAI interoperability mandate is accelerating 4K smart TV penetration as households bypass set-top box rentals for integrated streaming solutions.
- 8K:7680 x 4320 pixel resolution demands panel fabrication at Gen 10.5 and Gen 11 fab scales. Commercial signage deployments by QSR chains and retail banks in Japan and South Korea are absorbing early 8K panel production.
- HDR:High dynamic range processing expands luminance and color volume beyond standard dynamic range boundaries. Streaming service aggregation is making HDR support a baseline expectation for smart TV purchasers in urban Indian and Indonesian markets.
- LCD:Liquid crystal display technology with LED backlighting underpins cost-competitive volume production. TCL Technology anchors LCD expansion on vertically integrated Gen 11 panel lines in Shenzhen and Huizhou.
LCD handles the majority of throughput; 8K is expanding most quickly on share.
End User:
Application-specific requirements for durability, brightness, and integration interfaces are segmenting product development roadmaps.
- Residential:Consumer entertainment applications spanning 720p to 8K resolutions with refresh rates up to 120 Hz. Online retail channels are displacing specialty stores for set-top box distribution in India and Southeast Asia.
- Commercial:Digital signage, menu boards, and branch messaging systems demand sustained brightness and extended operating hours. QSR chains across the United States are deploying 4K displays for drive-through menu boards.
- Educational:Interactive display systems for classroom and campus deployment. Procurement teams prioritize durability and multi-input connectivity over premium image quality specifications.
- Hospitality:Guest room entertainment systems requiring integration with property management and pay-per-view platforms. Hotel chains in Japan are replacing legacy systems with smart TV platforms that support streaming service aggregation.
Residential handles the majority of throughput; Commercial is gaining share fastest.
Distribution Channel:
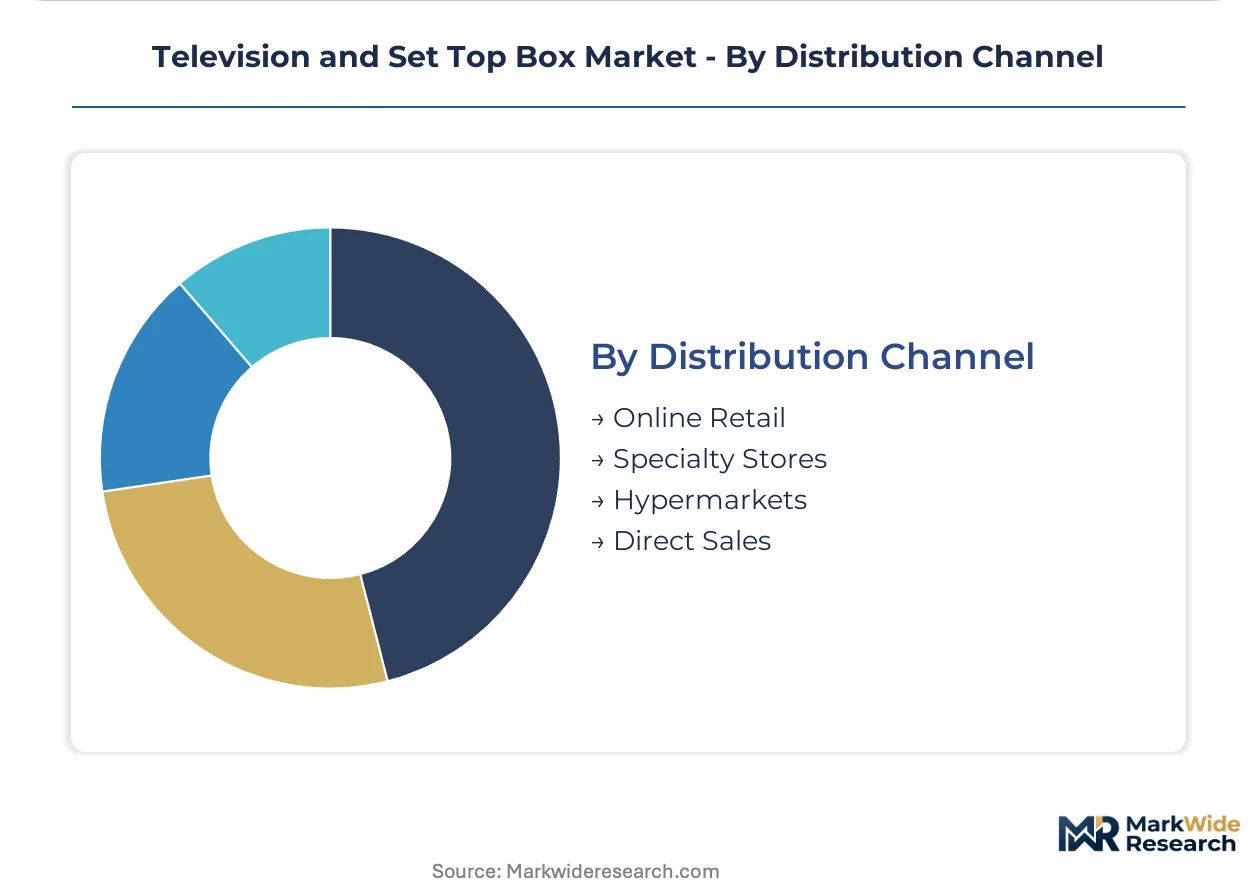
Channel economics and customer acquisition costs are restructuring how manufacturers reach end buyers across geographies.
- Online Retail:Direct-to-consumer distribution through e-commerce platforms. Set-top box sales through online channels are bypassing traditional telecom bundling arrangements in India and Indonesia.
- Specialty Stores:Electronics retailers with trained sales staff and demonstration environments. Hypermarkets retain television showroom relevance in emerging markets where tactile evaluation drives purchase decisions.
- Hypermarkets:Mass merchandisers combining grocery and general merchandise with electronics sections. Price competition and promotional bundling compress margins for television manufacturers.
- Direct Sales:Manufacturer-owned channels and B2B account management for commercial and hospitality procurement. Large-format hospitality contracts in the United States route through direct sales teams with integration engineering support.
Hypermarkets handles the majority of throughput; Online Retail is expanding most quickly on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korea and Japan where OLED substrate scarcity supports premium tier margins, while Chinese manufacturers in Guangdong province compress mid-market pricing through Gen 11 fab scale.
United States
Hospitality chains and QSR operators drive commercial display procurement for guest rooms and drive-through menu boards. The FCC mandates ATSC 3.0 broadcast compatibility, forcing tuner module redesigns for all US-bound televisions and set-top boxes. Dallas and Phoenix broadcasters already transmit next-gen signals, creating dual-sku inventory requirements for manufacturers during transition.
China
Domestic consumption and export manufacturing sustain panel fabrication at Gen 10.5 and Gen 11 scales. GB standards for energy-efficient displays impose certification requirements that filter designs from European and North American markets. Shenzhen and Huizhou clusters integrate OLED and LCD production with ODM assembly lines serving global television brands.
India
Urban households bypass set-top box rentals as fiber broadband penetration supports 4K streaming on smart TV platforms. TRAI mandates interoperable set-top boxes, accelerating hardware refresh rates and opening procurement to non-captive suppliers. Maharashtra and Karnataka absorb expanded manufacturing capacity as brands localize assembly for price-sensitive segments.
Japan
Commercial signage deployments by retail banks and QSR chains absorb early 8K panel production at premium price points. METI efficiency guidelines and broadcaster coordination shape transition timelines for next-generation broadcast standards. Tokyo-Osaka corridor concentrates demand for ultra-large format displays in corporate and public venue applications.
Germany
Industrial and commercial display procurement prioritizes energy efficiency and extended operating lifecycles. The EU Ecodesign Directive imposes standby power limits that filter inefficient set-top box architectures from market entry. Bavaria and North Rhine-Westphalia host system integrators serving European digital signage and hospitality installation projects.
Television and Set Top Box Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where premium OLED specialists compete against scale-driven LCD manufacturers. The vendor base separates into three strategic archetypes: vertically integrated panel fabricators with captive semiconductor supply, streaming-platform hardware assemblers outsourcing manufacturing, and laser projection specialists avoiding direct LCD price competition. Dominant competitive moves include capacity expansion at Gen 11 fab scales and strategic partnerships for embedded operating system integration.
Within the scale-driven tier, TCL Technology Group Corp. and Samsung Electronics Co., Ltd. represent archetypes of vertical integration into panel fabrication, while Hisense Co., Ltd. exemplifies specialization in alternative display technologies. These three companies anchor distinct competitive positions: Shenzhen-based TCL leverages Gen 11 lines for cost structure control, Samsung utilizes captive supply chains across premium tiers, and Hisense occupies the laser projection niche where panel freight costs become irrelevant. Each represents a viable path to margin defense against commodity LCD pricing pressure.
| Leading Market Players |
|---|
| Hisense Co., Ltd. |
| Roku, Inc. |
| Samsung Electronics Co., Ltd. |
| HUMAX Co., Ltd. |
| Huawei Technologies Co., Ltd. |
| LG Electronics Inc. |
| Sony Group Corporation |
| CommScope Holding Company Inc. |
| TCL Technology Group Corp. |
| Others |
Value Network & Pricing Analysis
Long-term panel offtake agreements between Gen 11 fabricators and television OEMs lock in substrate allocation and provide cost visibility across multi-year product cycles, insulating buyers from OLED driver IC spot-market volatility while committing capital to depreciating cleanroom assets in Shenzhen and Huizhou.
Pricing Analysis
The customization-premium spread between standard SKUs and hospitality-configured smart TVs with property management integration runs wide in procurement contracts. Three-tier pricing structure across premium OLED, standard QLED, and economy LED levels separates residential buyers by willingness-to-pay, with hospitality chains in the United States and Japan least sensitive due to five-year replacement budgeting. Cost compression in entry-level LED tiers is intensifying because Guangdong cluster scale has eliminated regional manufacturing cost advantages. Residential consumers in India and Southeast Asia exhibit highest price sensitivity, driving online channel discounting.
Supply Chain Analysis
Inventory buffers for display driver ICs and OLED substrates have extended lead-time profiles beyond traditional LCD component planning horizons. Panel fabrication concentrates in China, South Korea, and Japan, with substrate processing and module assembly drawing from specialized chemical feedstocks and semiconductor-grade glass. Single-source vulnerability for Gen 10.5 and Gen 11 photomask equipment creates bottleneck risk for capacity expansion. Distribution runs through ODM assembly lines in Guangdong province before outbound freight to North American and European retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward hospitality procurement teams and telecom operators in India, where volume consolidation across hotel chains and fiber broadband providers is compressing supplier margins and demanding integration engineering support as table stakes.
For Market Incumbents: Shield premium tier positioning by deepening captive semiconductor supply for OLED driver ICs and securing ATSC 3.0 certification ahead of FCC enforcement windows. Counter margin erosion from Chinese LCD scale by embedding software services that generate recurring revenue and reduce hardware price visibility in customer negotiations. For New Entrants and Emerging Players: Laser projection service-layer gaps in ultra-large format residential and commercial signage applications offer white-space entry below 100-inch panel freight cost thresholds. Target commercial QSR and retail banking deployments in Japan and South Korea where 8K content pipelines support premium pricing. Pursue direct-to-consumer online distribution in India and Indonesia to bypass telecom bundling gatekeepers. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated panel fabricators with Gen 11 capacity and captive semiconductor supply chains that can defend margin structures against commodity LCD pricing cycles. Monitor TRAI interoperability enforcement in India as inflection indicator for set-top box hardware refresh rates and non-captive supplier market access.| Strategic Initiative | Industry Significance |
|---|---|
| Gen 11 Fab Capacity Expansion | TCL's Shenzhen and Huizhou lines compress mid-market LCD pricing through scale economies. |
| ATSC 3.0 Tuner Module Redesign | FCC mandate forces dual-sku inventory for US-bound televisions during broadcast transition. |
| Smart TV Platform Integration | Embedded operating systems transform hardware into recurring service revenue platforms. |
| Laser Projection Technology Licensing | Hisense avoids panel freight costs in ultra-large format residential niche. |
| Direct-to-Consumer Channel Expansion | Online retail bypasses telecom bundling in India and Southeast Asia markets. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with television OEM procurement directors, hospitality technology integrators, and TRAI regulatory affairs specialists; and secondary validation through FCC equipment authorization filings, EU Ecodesign compliance databases, and China customs export records. Bottom-up triangulation against top-down market sizing cross-checked panel shipment volumes with retail channel sell-through data.
Across the analysis window, forecasts model demand by display technology, resolution tier, end-use application, and regional regulatory cluster. CAGRs derive from installed base replacement cycles, hospitality upgrade timelines, and streaming penetration curves. Industry-specific inputs include ATSC 3.0 broadcaster deployment schedules and TRAI interoperability compliance rates.
Forecasts assume regulatory continuity in FCC broadcast standards, EU Ecodesign efficiency thresholds, and India's TRAI hardware mandates; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Global Digital Terrestrial Television Market
Television
Free-To-Air (FTA) Service Market
Television
Cable Television Networks Market
Television
Global Broadcast Equipment Market
Television
Pay TV Operator Market
Television
Mobile TV Market
Television
Curved Television Market
Television
Television Advertising Market
Television
Television Market
Television
Digital TV Market
Television
Traditional TV and Home Video Market
Television
Broadcasting and Cable TV Market
Television
HDTV Market
Television
Pay TV Services Market
Television
Cloud Television (TV) Market
Television
Cloud TV Market