
 HDTV Market | 2026-2036
HDTV Market Size, Share, and Industry Trends Forecast 2026-2036
HDTV Market Analysis
The EU Ecodesign Directive is restructuring procurement criteria for large-format displays across European hospitality and commercial sectors, compelling manufacturers to redesign backlighting architectures and power-management chipsets. Samsung Electronics leverages its in-house semiconductor foundry to integrate custom system-on-chip designs that meet standby-power thresholds. LG Electronics anchors its competitive stance through OLED panel production at scale, sustaining premium positioning in residential and professional segments. TCL Technology Group competes aggressively on cost-engineered QLED architectures, dominating volume shipments into emerging markets.
High-definition television denotes a display system delivering minimum 720p or 1080p native resolution through digital signal processing, utilizing liquid-crystal, organic light-emitting diode, or quantum-dot-enhanced diode backplanes with refresh rates typically spanning 60 Hz to 120 Hz for motion clarity in broadcast and streaming environments. LED panels occupy the largest installed base due to manufacturing maturity and price accessibility, though OLED captures disproportionate margin pools in premium residential and commercial installations where contrast ratio and color accuracy command pricing premiums. QLED variants are gaining fastest in the 65-inch and 75-inch screen-size tiers as quantum-dot film costs decline and brightness specifications align with HDR content mastering standards.
The EU Ecodesign Directive and CE marking requirements shape product access by mandating annual energy-consumption disclosures and standby-power limits, while the EPA ENERGY STAR program in the United States imposes parallel efficiency benchmarks that influence North American retail placement. China's GB standards and MIIT certification protocols govern electromagnetic compatibility and display performance claims for domestic and export-bound production. Stakeholders must monitor divergence between regional efficiency mandates and emerging 8K broadcast standards to align R&D roadmaps with compliance timelines.
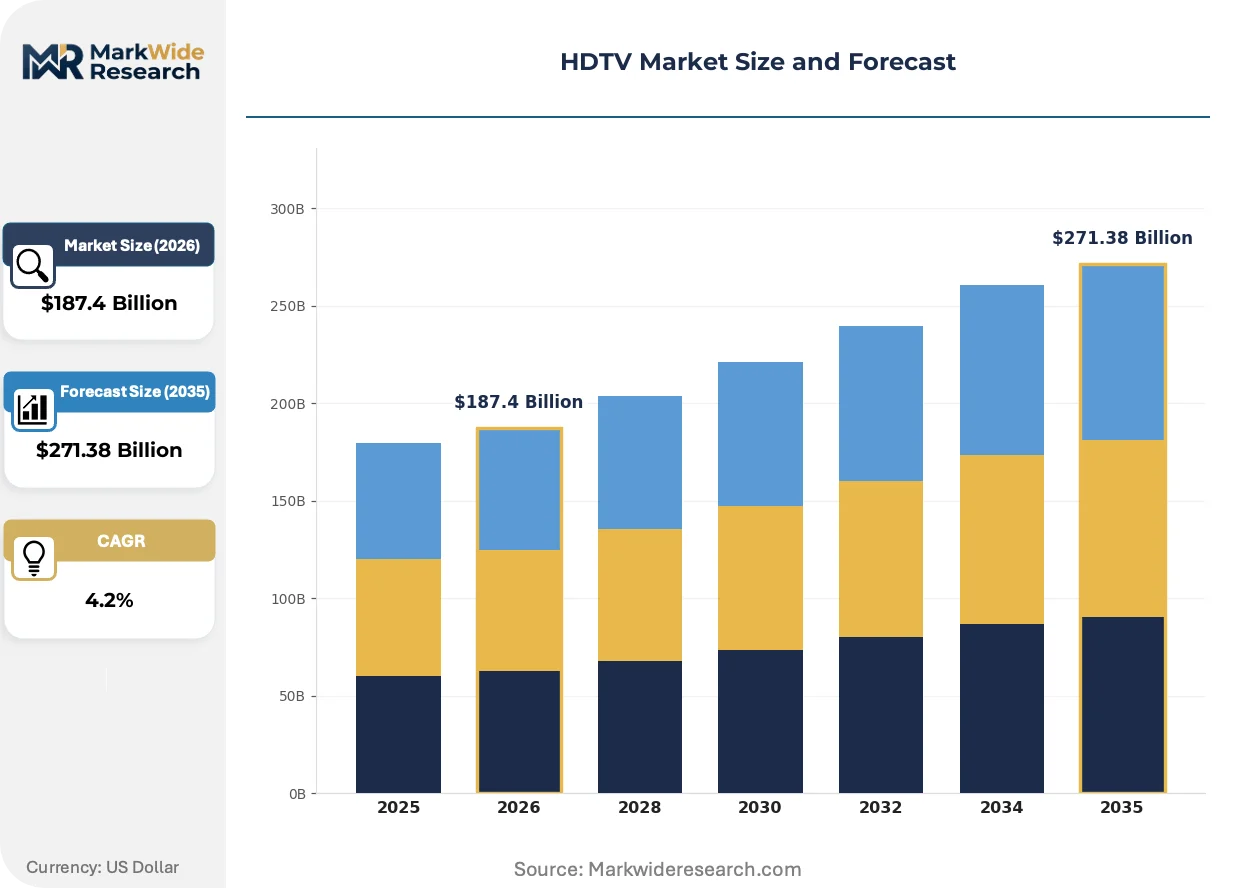
Market Dynamics
The EU Ecodesign Directive is compressing design cycles for backlighting architectures and power-management chipsets, forcing manufacturers to requalify semiconductor suppliers and retest thermal envelopes before CE marking deadlines.
Growth Catalysts
- 8K broadcast infrastructure:Japan's NHK and South Korea's KBS are expanding terrestrial 8K transmission trials, creating replacement demand for compatible reception hardware in residential and commercial installations.
- Hospitality upgrade cycles:Hotel operators in Dubai and Riyadh are mandating 4K minimum specifications for new property openings and renovation rollouts, prioritizing guest-facing technology as a competitive differentiator.
- Quantum-dot cost curves:Film deposition yields at Chinese manufacturing clusters around Guangdong and Shenzhen have improved sufficiently to position QLED variants at price parity with conventional LED in 65-inch and 75-inch tiers.
Market Restraints
- OLED panel supply concentration:Production of large-format organic light-emitting diode substrates remains captive to a limited number of fabrication facilities, constraining volume availability for premium residential and commercial segments.
- Rare-earth phosphor volatility:Europium and terbium price instability affects quantum-dot precursor chemistry costs, compressing margin structures for mid-tier QLED product lines.
- Standby-power compliance friction:Divergence between EU Ecodesign thresholds and EPA ENERGY STAR benchmarks forces manufacturers to maintain dual firmware configurations, adding certification overhead.
Strategic Opportunities
- India residential electrification:Grid expansion in tier-2 and tier-3 cities under the country's national infrastructure programs is creating first-time television ownership demand outside established urban centers.
- Gaming-optimized refresh specifications:120 Hz and 144 Hz panel variants with variable refresh rate support are capturing share from conventional monitors in esports venues and dedicated home gaming installations.
- EU Green Deal procurement mandates:Public-sector and institutional purchasing guidelines are prioritizing repairability scores and modular component designs, rewarding manufacturers with serviceable backlight unit architectures.
Industry Challenges
- 8K content pipeline gaps:Mastering and distribution infrastructure for ultra-high-definition material lags hardware deployment, creating consumer value-proposition friction and extending replacement cycles.
- Legacy hospitality integration:Property management system interfaces and in-room control protocols vary across hotel chains, requiring customized firmware development for each major account.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HDTV Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $271.38 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, OLED, QLED, LCD Screen Size: 32-inch, 55-inch, 65-inch, 75-inch End User: Residential, Commercial, Educational, Hospitality Connectivity: Wi-Fi, Bluetooth, HDMI, USB |
| Companies Covered | Samsung Electronics, LG Electronics, TCL Technology Group, Hisense Group, Sony Group Corporation, Panasonic Holdings Corporation, Sharp Corporation, Vizio Holding Corp., Xiaomi Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HDTV Market Emerging Trajectories
Display technology roadmaps are converging on brightness and color-gamut specifications that satisfy broadcast mastering standards, while regulatory pressure on energy consumption forces simultaneous efficiency gains.
Mini-LED backlighting is unifying the contrast performance of emissive displays with the manufacturing scale of liquid-crystal architectures. Hospitality chains and high-end residential integrators are specifying zone-dimming densities above one thousand local dimming zones. This convergence is unifying premium positioning across OLED and advanced LCD product categories.
REACH substance restrictions and RoHS amendments are tightening limits on cadmium and certain halogenated compounds in display componentry. Manufacturers are reformulating quantum-dot encapsulants and solder alloys to maintain CE marking eligibility. Professional broadcast monitor suppliers face the most acute retesting burdens given their extended product lifecycles.
Commercial buyers are consolidating display procurement through managed service contracts that bundle hardware, installation, and content management. System integrators are displacing traditional electronics distributors in hospitality and corporate verticals. This pattern is most pronounced in Germany and the Netherlands where facility management outsourcing penetration is highest.
HDTV Market Segmentation
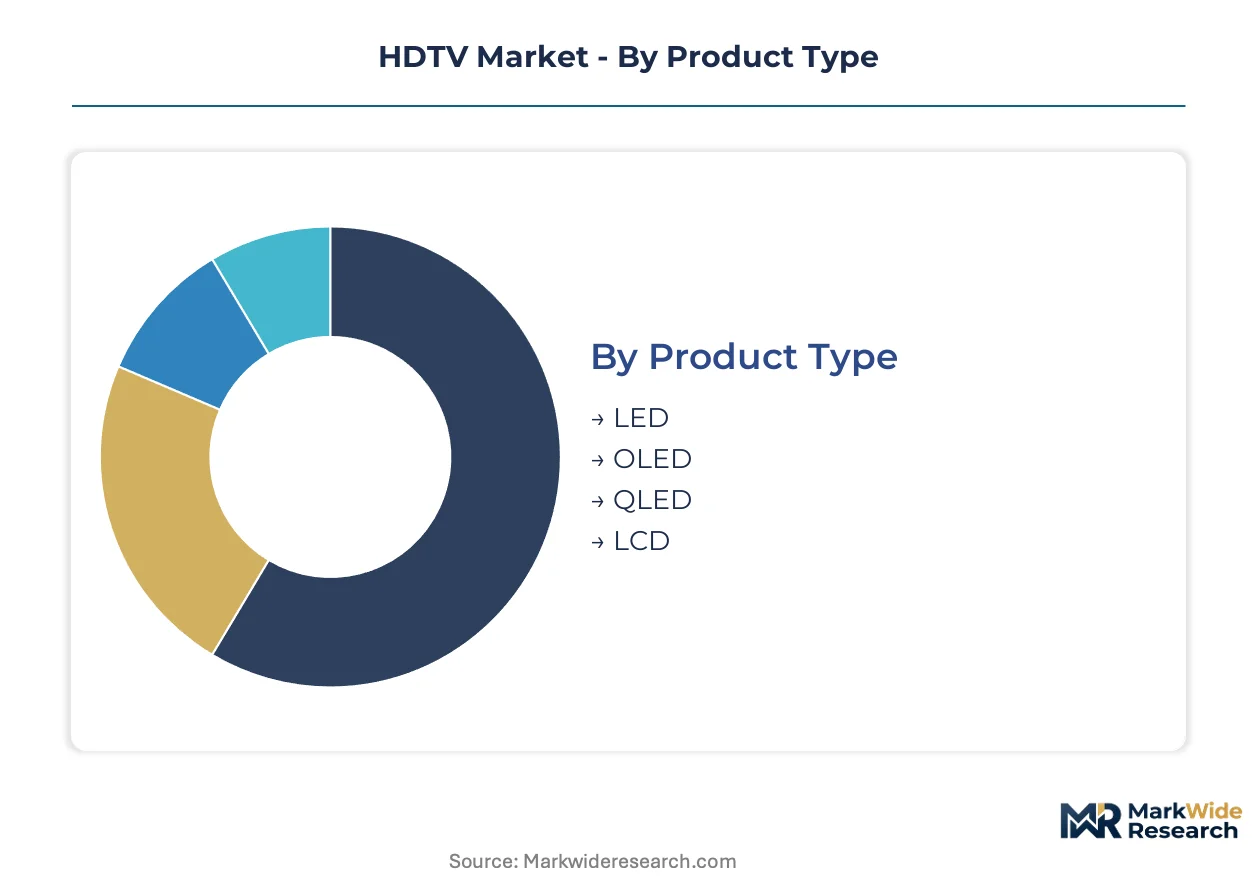
HDTV procurement decisions cluster around display technology, physical dimensions, and installation environment. Manufacturers align production capacity and firmware development to these axes, while regulatory compliance requirements vary sharply across residential versus commercial deployment contexts.
Product Type:
Display architecture determines power consumption profiles, contrast performance, and manufacturing cost structures that shape competitive positioning.
- LED:Liquid-crystal panels with edge-lit or direct-lit diode backlighting dominate volume shipments due to established supply chains and price accessibility. Demand concentrates in India's tier-2 and tier-3 cities where grid expansion under national infrastructure programs is creating first-time television ownership. The EU Ecodesign Directive is compressing design cycles for LED backlighting architectures and power-management chipsets.
- OLED:Organic light-emitting diode substrates deliver emissive pixel-level illumination without backlighting, enabling infinite contrast ratios and sub-2mm panel thicknesses. Production remains captive to a limited number of fabrication facilities, constraining volume availability for premium residential and commercial segments in Dubai and Riyadh hospitality rollouts. LG Electronics anchors its competitive stance through OLED panel production at scale.
- QLED:Quantum-dot-enhanced films boost color gamut and luminance in liquid-crystal architectures, narrowing the performance gap with emissive displays at lower cost points. TCL Technology Group competes aggressively on cost-engineered QLED architectures, dominating volume shipments into emerging markets as film deposition yields improve at Chinese manufacturing clusters.
- LCD:Legacy cold-cathode fluorescent lamp backlit panels persist in budget-tier replacement cycles and developing-market inventory, though diode-backlit variants have displaced most original-equipment manufacturing.
Mature deployment sits with LED. Newer deployment is concentrated in OLED.
Screen Size:
Physical dimensions correlate directly with panel substrate generation, freight economics, and installation infrastructure requirements.
- 32-inch:Compact form factors serve secondary residential rooms, budget hospitality installations, and educational institutional procurement where capital constraints limit per-unit expenditure. Demand concentrates in India's emerging urban centers and Southeast Asian markets where space constraints and purchasing power favor smaller displays.
- 55-inch:The former mainstream standard for residential living rooms is now transitioning to entry-tier positioning as consumer preferences shift toward more immersive viewing experiences.
- 65-inch:Quantum-dot cost curves have positioned QLED variants at price parity with conventional LED in this tier, accelerating share capture for advanced color-gamut specifications. Hospitality chains in Dubai and Riyadh are mandating 65-inch minimums for luxury property segments.
- 75-inch:Large-format panels require specialized freight handling and reinforced wall-mounting infrastructure, limiting deployment to premium residential and commercial installations where spatial allowances accommodate the physical footprint.
Volume concentration favors 55-inch. Margin expansion is steepest in 65-inch and 75-inch tiers.
End User:
Installation environment dictates durability specifications, control protocol requirements, and content management integration needs.
- Residential:Consumer households prioritize streaming application compatibility, voice assistant integration, and aesthetic minimalism. Gaming-optimized refresh specifications at 120 Hz and 144 Hz with variable refresh rate support are capturing share from conventional monitors in dedicated home gaming installations.
- Commercial:Corporate environments and public venues demand extended operating-hour durability, centralized device management, and brightness specifications suited to ambient lighting conditions. System integrators are displacing traditional electronics distributors in this vertical.
- Educational:Schools and universities require interactive whiteboard compatibility, robust physical construction, and procurement frameworks aligned with public-sector purchasing guidelines. EU Green Deal procurement mandates prioritizing repairability scores are reshaping supplier selection.
- Hospitality:Hotels and resorts mandate property management system integration, customized welcome-screen branding, and remote diagnostics capability. Legacy hospitality integration challenges persist as in-room control protocols vary across chains, requiring customized firmware development.
Replacement velocity is highest in residential. Contract value concentration sits with hospitality.
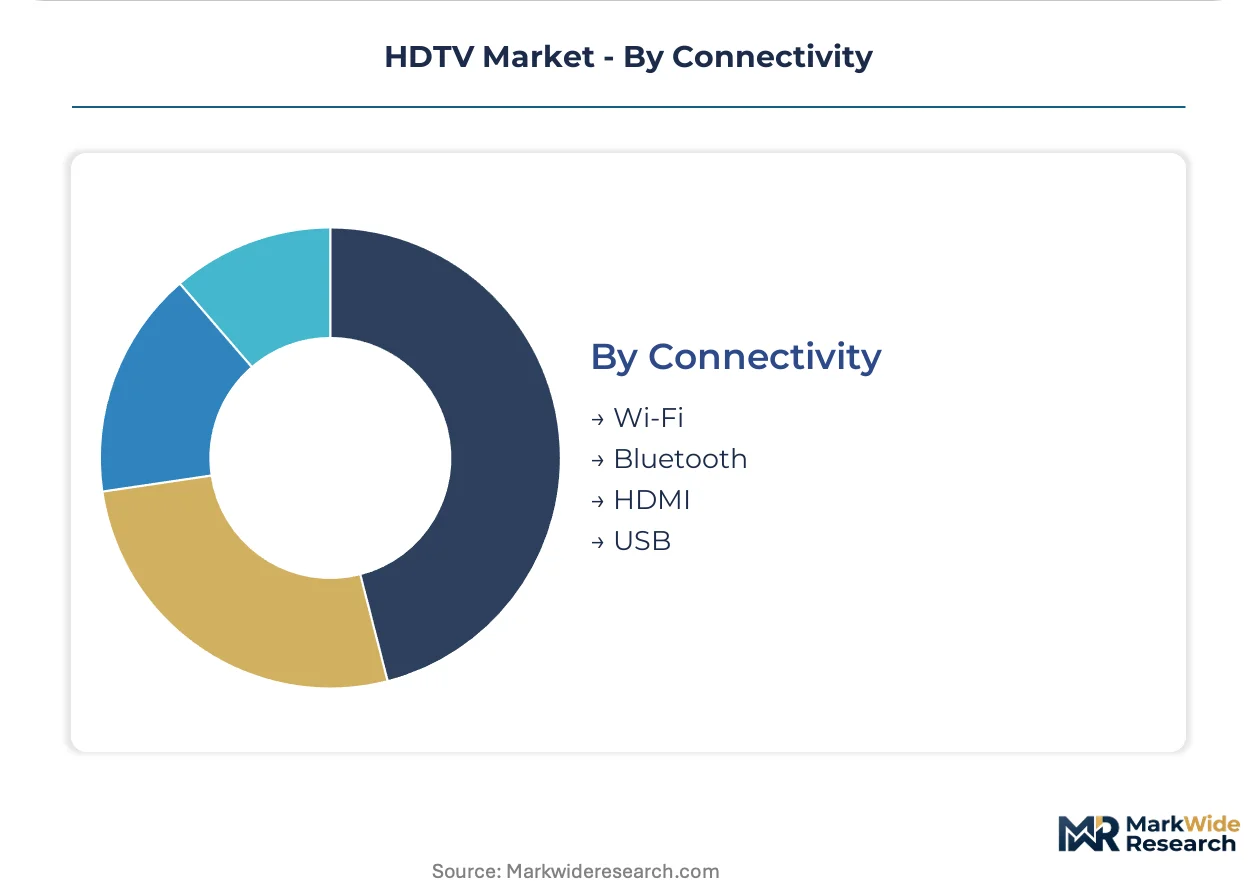
Connectivity:
Interface specifications determine content source compatibility, peripheral integration, and future-proofing against broadcast standard evolution.
- Wi-Fi:Wireless networking enables over-the-air firmware updates, streaming application functionality, and smart home ecosystem integration without physical cabling infrastructure.
- Bluetooth:Short-range wireless supports audio output to external sound systems, remote control pairing, and peripheral connectivity for accessibility devices.
- HDMI:The dominant physical interface for video transmission carries uncompressed digital signals with audio return channel capability, though version fragmentation across 2.0 and 2.1 specifications complicates feature support verification.
- USB:Universal serial bus ports enable local media playback, firmware update via storage device, and power delivery for streaming sticks or signal conditioning hardware.
HDMI remains the non-negotiable baseline. Wi-Fi is gaining mandatory status as streaming displaces broadcast.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors the world's densest concentration of panel fabrication and television assembly, with Guangdong Province housing vertically integrated supply chains that feed export markets across every continent.
China
Guangdong and Shenzhen manufacturing clusters achieve unmatched production scale for QLED and LED panel architectures. MIIT certification protocols govern electromagnetic compatibility and display performance claims for domestic and export-bound production. The Pearl River Delta corridor concentrates thin-film transistor substrate fabrication, backlight unit assembly, and final television integration within a 200-kilometer radius.
United States
Residential replacement cycles and hospitality procurement in Texas and Florida drive demand for 65-inch and 75-inch displays. The EPA ENERGY STAR program imposes efficiency benchmarks that influence retail placement decisions. The Southeast manufacturing corridor, spanning Georgia and South Carolina, hosts final assembly operations serving North American distribution networks.
Germany
Commercial display procurement through managed service contracts concentrates in facility management outsourcing hubs across Bavaria and North Rhine-Westphalia. The EU Ecodesign Directive mandates standby-power limits and annual energy-consumption disclosures. The Eindhoven-Frankfurt logistics corridor enables rapid fulfillment of large-format panels for corporate and institutional installations.
Japan
NHK's terrestrial 8K transmission trials create replacement demand for compatible reception hardware in residential and broadcast monitoring applications. METI oversees industrial standards coordination between domestic manufacturers and international broadcast bodies. The Kanto region around Tokyo maintains specialized fabrication capacity for professional broadcast monitor substrates.
India
Grid expansion in Maharashtra and Gujarat under national infrastructure programs is creating first-time television ownership demand outside established urban centers. BIS certification requirements govern safety and electromagnetic compatibility for imported and domestically assembled units. The Delhi-Mumbai Industrial Corridor is attracting component packaging investments to serve northern and western state markets.
HDTV Market Vendor Landscape
The competitive structure tilts toward diversified electronics conglomerates with captive semiconductor or panel production. Market participation clusters around three archetypes: vertically integrated display manufacturers controlling upstream substrate fabrication; contract assemblers leveraging Chinese manufacturing scale for cost-engineered portfolios; and premium-tier specialists emphasizing broadcast-caliber color accuracy. Capacity expansion and strategic technology licensing represent the dominant competitive vectors as firms reposition around Mini-LED and quantum-dot process improvements.
Within the diversified conglomerate tier, Samsung Electronics and LG Electronics exemplify archetypes built on in-house semiconductor foundry operations and OLED panel production at scale respectively. TCL Technology Group occupies a position among cost-engineered QLED specialists competing aggressively on film deposition yields at Chinese manufacturing clusters. These three anchors illustrate how competitive positioning diverges between premium emissive display architectures and volume-oriented quantum-dot liquid-crystal strategies.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| TCL Technology Group |
| Hisense Group |
| Sony Group Corporation |
| Panasonic Holdings Corporation |
| Sharp Corporation |
| Vizio Holding Corp. |
| Xiaomi Corporation |
| Others |
Supply Flow & Price Mechanics
Rare-earth europium and terbium price volatility cascades through quantum-dot precursor chemistry into tiered pricing structures, compressing margin structures for mid-tier QLED product lines while OLED panel scarcity sustains premium positioning in Dubai and Riyadh hospitality rollouts.
Pricing Analysis
Contrast-ratio performance anchors value-based pricing across emissive and transmissive display architectures. Three-tier pricing structure across premium OLED, standard QLED, and economy LED levels segments buyer willingness-to-pay by installation environment and content mastering requirements. Pricing pressure stems from quantum-dot film cost compression as Chinese manufacturing clusters achieve yield improvements. Hospitality chains in Dubai and Riyadh exhibit lowest price sensitivity due to guest-experience differentiation mandates, while India's tier-2 and tier-3 residential markets concentrate volume demand at aggressive price points.
Supply Chain Analysis
Direct-to-OEM channels handle hospitality and corporate procurement volumes, while retail distribution serves residential replacement cycles. Panel substrate fabrication concentrates in China, South Korea, and Japan, with final assembly anchored in Guangdong Province and the Southeast United States manufacturing corridor. Supply chain configuration draws from rare-earth phosphor deposits, thin-film transistor glass substrates, and semiconductor power-management chipsets. Single-source vulnerability persists for large-format OLED substrates given production concentration at limited fabrication facilities. Distribution runs through system integrators displacing traditional electronics distributors in Germany and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where EU Ecodesign Directive compliance costs and dual-firmware certification overhead force sub-scale assemblers toward exit or acquisition.
For Market Incumbents: Anticipate margin compression in mid-tier QLED segments as TCL Technology Group and Hisense Group escalate cost-engineered competition. Defensive positioning requires backward integration into semiconductor power-management chipsets to meet standby-power thresholds without dual-firmware overhead. Samsung Electronics exemplifies this lever through captive foundry operations. Channel control through managed service contracts in Germany and the Netherlands insulates against distributor displacement.
For New Entrants and Emerging Players: Mini-LED zone-dimming architectures offer a technology-first wedge into hospitality specification cycles where local dimming densities above one thousand zones command premium positioning. India's tier-2 and tier-3 cities present the most penetrable geography as grid expansion creates first-time ownership demand outside established urban centers. Gaming-optimized 144 Hz panel variants with variable refresh rate support represent a white-space application capturing share from conventional monitors in esports venues.
For Investors and Strategic Acquirers: Distressed-cycle entries favor contract assemblers with established MIIT certification pathways and Guangdong manufacturing footprints as smaller players face EU Ecodesign retesting burdens. Long-term viability across the projection horizon hinges on positioning around 8K broadcast infrastructure deployment and quantum-dot cost curve trajectories. The signal to monitor is NHK and KBS terrestrial transmission trial expansion as inflection indicator for compatible hardware replacement demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Mini-LED Backlighting Scale-Up | Enables zone-dimming densities satisfying hospitality specifications in Dubai and Riyadh luxury segments. |
| Dual-Firmware Consolidation | Eliminates certification overhead from divergent EU Ecodesign and EPA ENERGY STAR standby-power thresholds. |
| Quantum-Dot Film Yield Investment | Positions QLED variants at price parity with conventional LED in 65-inch and 75-inch tiers. |
| Managed Service Contract Expansion | Captures hospitality and corporate verticals as system integrators displace traditional distributors. |
| 8K Broadcast Hardware Certification | Aligns product roadmaps with NHK and KBS terrestrial transmission infrastructure deployment. |
Methodological Framework
Independent corroboration across semiconductor procurement executives, hospitality technology directors, and panel fabrication engineers underwrites the qualitative findings. Primary fieldwork incorporated structured interviews with display subsystem designers, power-management chipset suppliers, and system integrators serving German and Dutch facility management outsourcing markets. Secondary validation drew from MIIT certification registries, EPA ENERGY STAR qualified product listings, and EU Ecodesign implementing measure disclosures. Bottom-up shipment analysis across technology tiers reconciled with top-down value aggregation across the analysis window.
Rate-of-change decomposition separated replacement cycle dynamics from first-time ownership penetration in emerging markets. The analytical framework modeled display technology architecture, screen size tier, end-user installation environment, and regional regulatory cluster throughout the forecast period. CAGRs derived from panel substrate generation transitions, quantum-dot film cost trajectories, and broadcast standard evolution timelines. Forecast inputs incorporated hospitality upgrade cycle visibility from Dubai and Riyadh property development pipelines alongside India's grid expansion schedules.
Several conditions sit outside the modeled scope, including geopolitical disruption to rare-earth supply corridors and unilateral broadcast standard adoption acceleration by national regulators. Forecasts reflect assumptions regarding quantum-dot deposition yield improvements and OLED substrate capacity expansion timelines. Periodic stress-testing of base assumptions is recommended given divergence risk between EU Ecodesign thresholds and emerging 8K energy-consumption profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Global Broadcast Equipment Market
Television
Pay TV Market
Television
Print Newspapers and Magazines Market
Television
Free-To-Air (FTA) Service Market
Television
Broadcasting and Cable TV Market
Television
Cable Television Networks Market
Television
Digital TV Market
Television
Holographic TV Market
Television
Pay TV Operator Market
Television
Traditional TV and Home Video Market
Television
TV Advertising Market
Television
Television Services Market
Television
Cloud Television (TV) Market
Television
Television Market
Television
Pay TV Services Market
Television
Curved Television Market