
 Cable Television Networks Market | 2026-2036
Cable Television Networks Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Television Networks Market Analysis
Skinny bundle packaging is shifting subscriber preferences away from traditional expanded basic tiers toward curated channel collections. Comcast leverages its broadband-video convergence to sustain bundled pricing power across residential footprints. Charter Communications anchors market presence through dense metropolitan network infrastructure. Altice USA differentiates via fiber-deep upgrade programs in underserved Northeast corridors.
Cable television networks distribute linear and on-demand video programming through hybrid fiber-coaxial and all-fiber infrastructure, typically operating within 54-1000 MHz downstream spectrum allocations with DOCSIS 3.1 enabling gigabit throughput. These systems serve as the primary commercial video delivery mechanism for multichannel programming across residential, commercial, and institutional environments. Video on demand occupies the dominant margin pool as subscriber self-selection reduces content licensing waste relative to linear broadcast. Internet protocol television represents the fastest-growing technology segment as operators sunset analog plant and migrate quadrature amplitude modulation streams to packet-based delivery.
The FCC enforces must-carry and retransmission consent rules that govern network affiliation agreements and local station carriage obligations. The EPA's energy efficiency standards for consumer premises equipment shape set-top box design requirements and power consumption profiles. State-level franchise authorities in California, New York, and Texas impose build-out conditions that constrain network extension economics. Stakeholders must monitor spectrum auction outcomes and streaming rights fragmentation as these forces determine the residual value of linear distribution infrastructure against direct-to-consumer alternatives.
Market Dynamics
IP-based video delivery migration is compressing traditional linear infrastructure economics while forcing operators to reconverge broadband and video platforms under unified packet architectures.
Growth Catalysts
- DOCSIS 3.1 Deployment:Gigabit-capable downstream throughput enables operators to bundle symmetrical broadband with 4K video tiers, capturing residential upgrade cycles.
- Hospitality Venue Expansion:Hotels and corporate campuses are scaling commercial subscriptions to integrated video-data packages, diversifying revenue beyond residential footprints.
- Brazil Infrastructure Modernization:Pay-TV operators are accelerating analog-to-IP plant conversions, creating equipment replacement demand across Latin America's largest cable market.
Market Restraints
- FCC Spectrum Reallocation:Compression of analog bandwidth availability below 1 GHz limits downstream capacity expansion for legacy QAM systems.
- Content Licensing Escalation:Retransmission consent fees from broadcast networks are compressing video segment margins faster than subscriber ARPU recovery.
- Over-the-Top Substitution:Direct-to-consumer streaming platforms are fragmenting viewing hours and eroding the exclusivity value of linear channel bundles.
Strategic Opportunities
- Commercial IoT Integration:Smart building energy management and security systems can ride converged fiber-coaxial infrastructure, opening non-video revenue streams.
- Addressable Advertising:Dynamic ad insertion technology enables household-level targeting, recovering CPM premiums lost to digital platforms.
- Edge Computing Co-location:Distributed video caching and cloud gaming servers at hub sites monetize underutilized plant power and real estate.
Industry Challenges
- Plant Modernization Cadence:Fiber-deep upgrades require sustained capex deployment across decades-old coaxial neighborhoods with uncertain payback timelines.
- Workforce Retraining:Field technician pools skilled in RF alignment and IP provisioning remain scarce relative to migration velocity demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Television Networks Market |
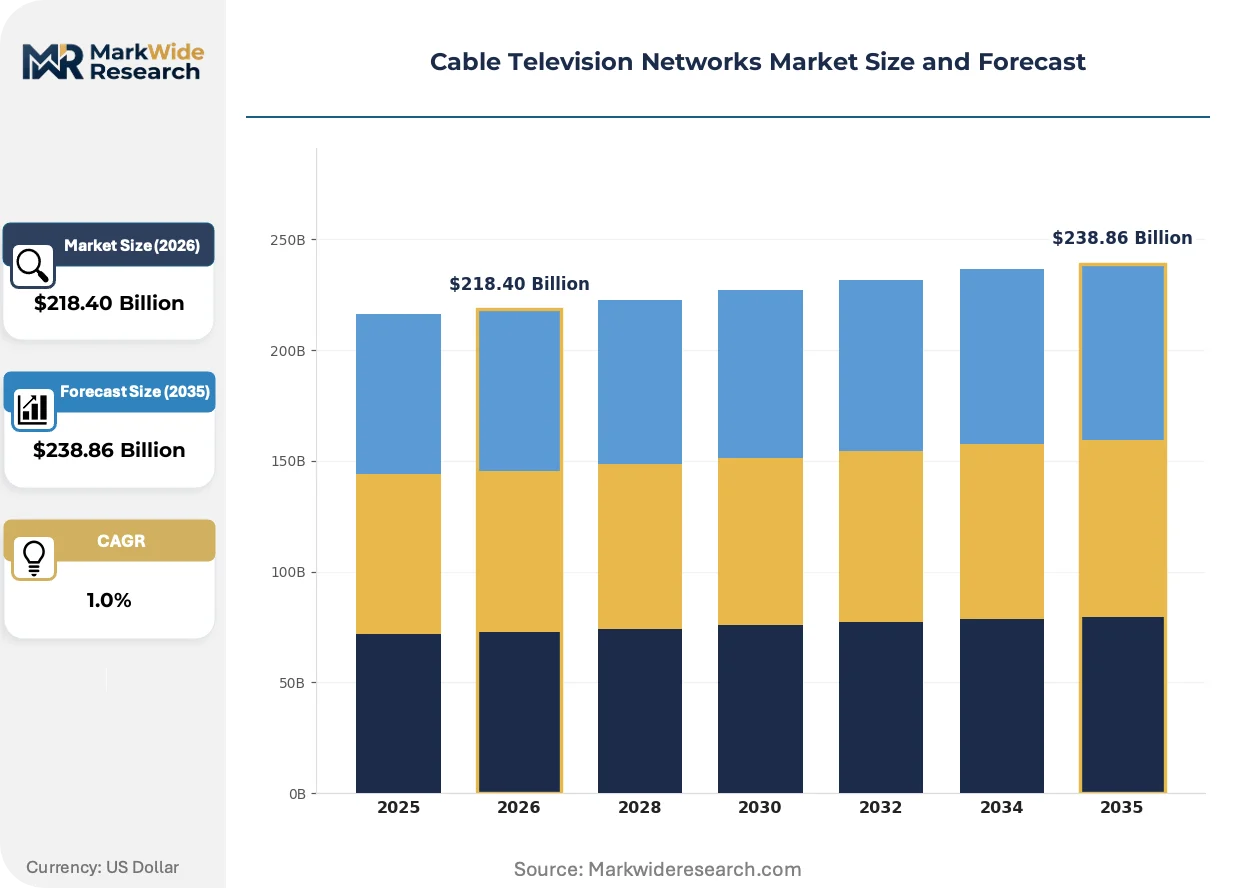
| Market Size in 2026 | $218.40 Billion |
| Market Size in 2035 | $238.86 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Video On Demand, Live Streaming, Pay-Per-View, Pre-recorded Content Technology: Digital Cable, Analog Cable, Internet Protocol Television, Satellite End User: Households, Commercial Establishments, Educational Institutions, Government Agencies Customer Type: Residential Users, Business Users, Institutional Clients, Others |
| Companies Covered | Dish Network, Altice USA, Comcast, Verizon, Mediacom, Charter Communications, Cox Communications, Cogeco, DirecTV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Television Networks Market Emerging Trajectories
Software-defined access architectures are dissolving the hardware boundaries between video distribution and data transport, enabling operators to collapse parallel network layers.
Cloud-native video headends are automating channel origination, packaging, and encryption functions previously executed in physical broadcast facilities. Tier-1 operators are migrating linear feeds to virtualized environments within eighteen-month windows. This compression of capital intensity is automating the transition from facility-based to service-based video economics.
The FCC's must-carry and retransmission consent framework is constraining negotiation leverage against broadcast affiliates. Local station carriage obligations force operators to absorb cost increases or risk regulatory sanction. Smaller market cable systems bear disproportionate compliance burden relative to their subscriber scale.
Viewing behavior is fragmenting across time-shifted and on-demand modalities, compressing the relevance of scheduled linear programming. Younger demographics are bypassing traditional bundles entirely for direct subscriptions. Brazil exhibits the most pronounced pivot, where IPTV subscriber growth is outpacing legacy cable additions.
Cable Television Networks Market Segmentation
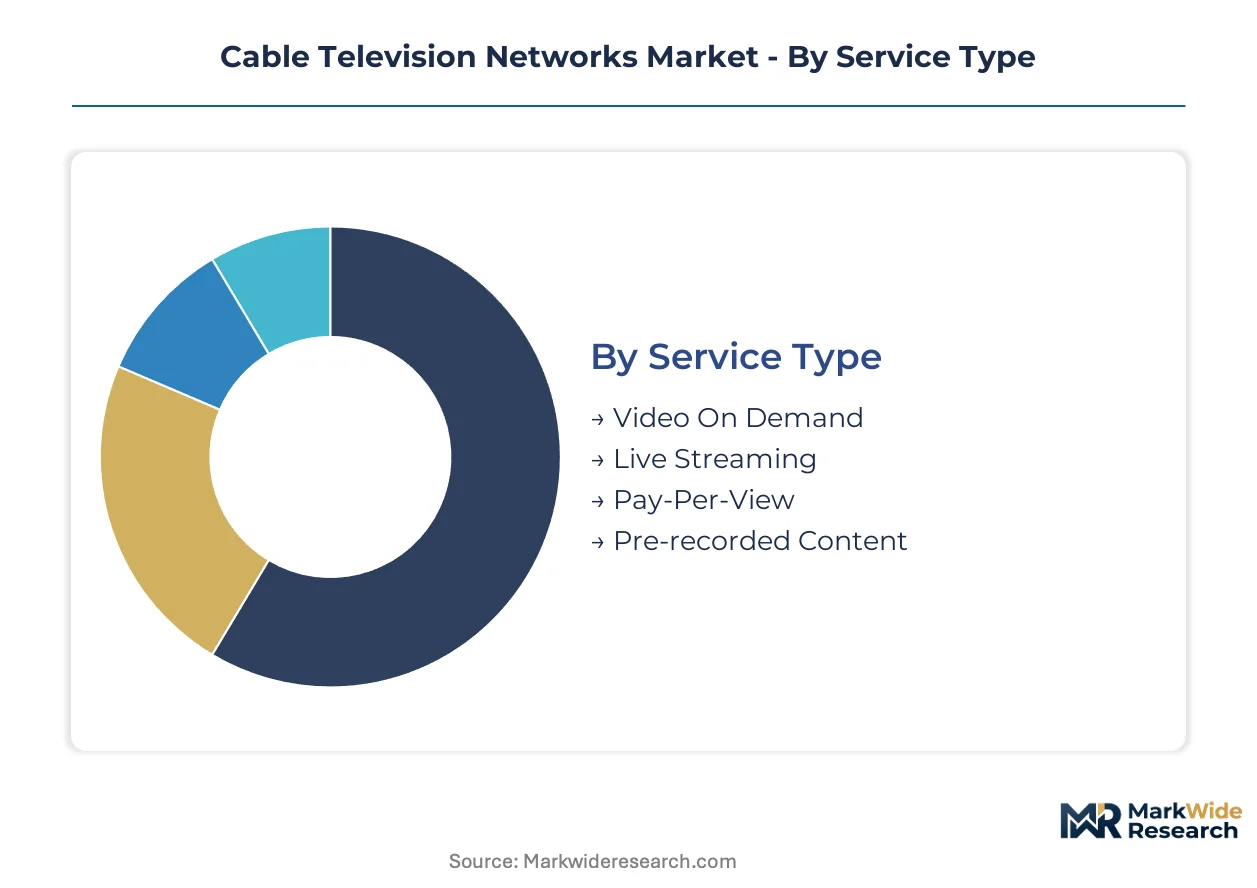
Cable television networks fragment across service delivery modes, underlying transmission technologies, and subscriber categories with distinct infrastructure requirements. Each segmentation axis reveals divergent margin profiles and capital intensity thresholds that shape operator strategic positioning.
Service Type:
FCC must-carry obligations and retransmission consent frameworks impose differential compliance burdens across programming formats, with live linear feeds carrying heavier regulatory overhead than on-demand libraries.
- Video On Demand:Library-based content delivery enables subscriber self-selection that minimizes content licensing waste relative to scheduled broadcasts. Demand concentrates in residential broadband bundles where Comcast and Charter leverage DOCSIS 3.1 throughput to deliver 4K libraries without dedicated broadcast windows.
- Live Streaming:Real-time linear distribution over packet networks requires sub-two-second latency engineering and adaptive bitrate protocols to match traditional QAM reliability. Hospitality venues in Brazil are scaling commercial subscriptions for live sports and news as hotels modernize in-room entertainment systems.
- Pay-Per-View:Transactional event access generates concentrated revenue spikes around combat sports and premium entertainment specials with elevated per-unit margins.
- Pre-recorded Content:Time-shifted programming libraries support binge-viewing patterns with lower distribution costs than synchronous delivery infrastructure.
Video On Demand sits at the top of the volume ranking, with Live Streaming climbing the fastest.
Technology:
Plant modernization cycles separate segments by capital intensity, with legacy analog systems requiring spectrum reallocation compliance while IP-native platforms face software-defined migration costs.
- Internet Protocol Television:Packet-based video delivery dissolves hardware boundaries between linear distribution and broadband transport, enabling unified service convergence. Brazilian operators are accelerating analog-to-IP conversions as the country's pay-TV infrastructure modernizes, creating equipment replacement demand across Latin America's largest cable footprint.
- Digital Cable:QAM-based downstream delivery within 54-1000 MHz spectrum allocations remains the dominant commercial video mechanism for multichannel residential service. Dense metropolitan networks in the US Northeast sustain this technology where fiber-deep upgrades proceed gradually.
- Analog Cable:Legacy RF transmission faces FCC-mandated bandwidth compression below 1 GHz that limits downstream capacity expansion for unupgraded plant.
- Satellite:Geostationary and low-earth-orbit alternatives serve rural and remote footprints beyond cable franchise boundaries with distinct regulatory compliance through the FCC's satellite licensing framework.
Digital Cable maintains the largest installed base, while Internet Protocol Television gains share fastest.
End User:
Subscriber environment determines network architecture requirements, with commercial and institutional deployments demanding higher service level agreements and redundant infrastructure than residential counterparts.
- Households:Residential subscribers drive volume economics through bundled broadband-video packages with DOCSIS 3.1 enabling gigabit throughput convergence.
- Commercial Establishments:Hotels and corporate campuses require integrated video-data packages with enterprise-grade reliability and centralized billing systems.
- Educational Institutions:Campus networks demand multicast-capable distribution for lecture capture and distributed learning applications.
- Government Agencies:Municipal and federal facilities require secure, compliant delivery with encryption standards exceeding consumer-tier specifications.
Households dominate subscriber counts, with Commercial Establishments expanding most quickly.
Customer Type:
Contract structures and pricing power vary sharply across customer categories, with institutional clients negotiating multi-year terms against residential month-to-month volatility.
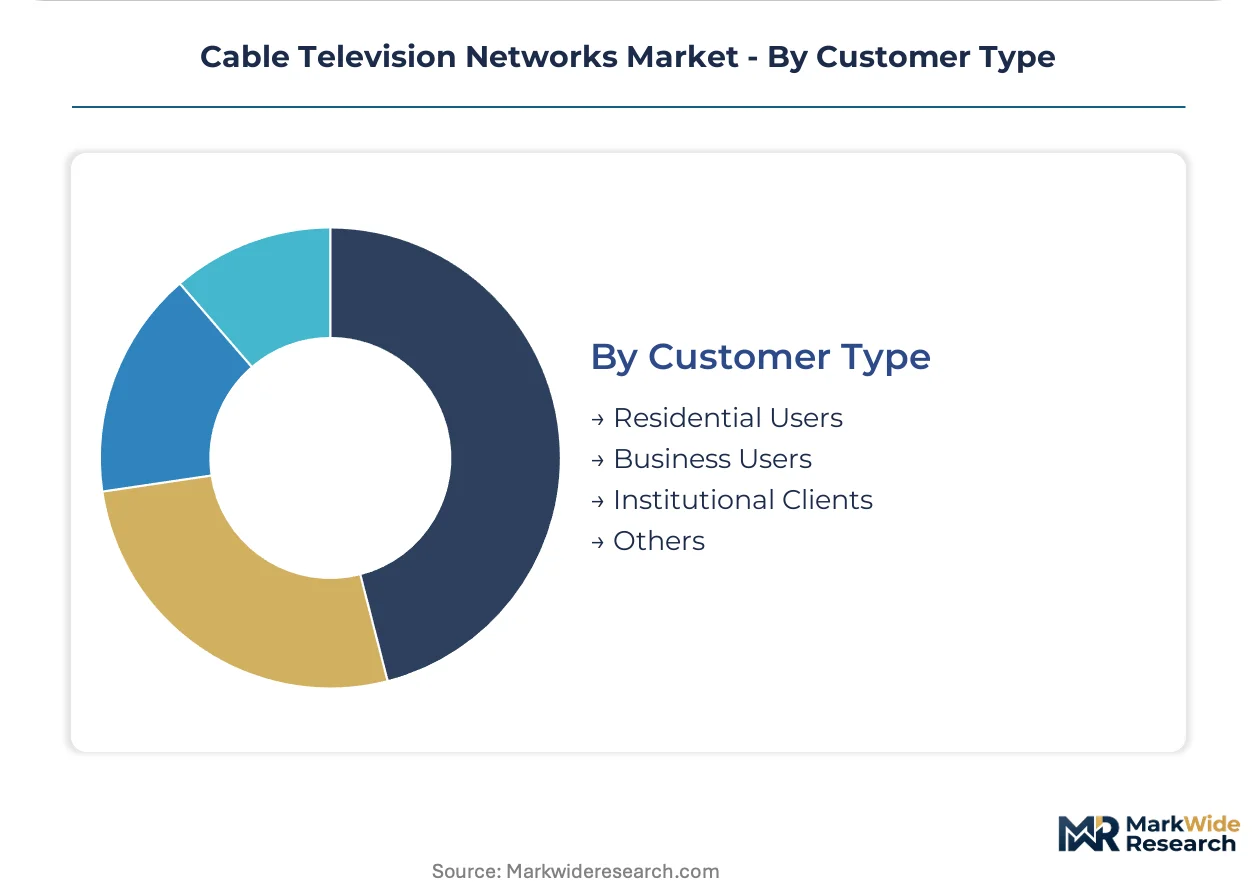
- Residential Users:Individual subscribers anchor ARPU through bundled service tiers with skinny bundle packaging shifting preferences toward curated channel collections.
- Business Users:Commercial accounts generate premium pricing through service level guarantees and dedicated support infrastructure.
- Institutional Clients:Universities, hospitals, and government entities procure through formal RFP processes with extended evaluation cycles and compliance documentation requirements.
- Others:Niche subscriber categories include temporary event infrastructure and specialized vertical applications with non-standard technical specifications.
Residential Users account for the greatest revenue concentration, with Business Users showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cable television networks originated in the United States during the late 1940s as community antenna television systems in mountainous Pennsylvania and Oregon valleys. These early coaxial deployments solved broadcast reception problems before evolving into the multichannel programming infrastructure that now spans hybrid fiber-coaxial and all-fiber architectures worldwide.
United States
Residential broadband-video bundles and hospitality venue commercial subscriptions drive infrastructure investment across dense metropolitan footprints. The FCC enforces must-carry and retransmission consent rules that govern network affiliation agreements and constrain operator negotiation leverage. Comcast and Charter Communications anchor competitive positioning in the Northeast and Southeast corridors where DOCSIS 3.1 gigabit throughput enables 4K video tier convergence.
Brazil
Pay-TV operators are accelerating analog-to-IP plant conversions as subscriber preferences pivot toward internet protocol television delivery. ANVISA and the country's national telecommunications regulator impose equipment certification requirements on imported network infrastructure. São Paulo anchors Latin America's largest cable modernization cycle, with operators replacing quadrature amplitude modulation systems across decades-old coaxial neighborhoods.
Germany
Commercial IoT integration and smart building energy management systems create non-video revenue streams riding converged fiber-coaxial infrastructure. The country's federal network agency enforces broadband deployment obligations under the Telecommunications Act. North Rhine-Westphalia concentrates cable headend virtualization projects where operators collapse parallel network layers under software-defined access architectures.
Japan
Edge computing co-location and distributed video caching monetize underutilized hub site real estate as cloud gaming servers deploy. METI promotes energy efficiency standards for consumer premises equipment that shape set-top box power consumption profiles. The Kanto region around Tokyo leads IP-based video delivery migration as operators sunset analog plant and migrate to packet-based architectures.
Canada
Educational institutions and government agencies procure multicast-capable distribution systems for lecture capture and secure compliant delivery. The country's national telecommunications regulator imposes build-out conditions that constrain network extension economics in remote territories. Ontario and Quebec concentrate fiber-deep upgrade programs where operators address workforce retraining gaps for field technicians skilled in RF alignment and IP provisioning.
Cable Television Networks Market Vendor Landscape
Premium-margin players sit above commodity-margin players across bundled service convergence and fiber-deep infrastructure density. The vendor base organizes around three strategic archetypes: broadband-video converged operators leveraging DOCSIS 3.1 throughput, fiber-first specialists pursuing plant modernization cadence, and satellite alternatives serving rural footprints beyond cable franchise boundaries. Dominant competitive moves include fiber-deep upgrade programs in underserved corridors and strategic partnerships for cloud-native video headend virtualization.
Within the converged-operator tier, Comcast and Charter Communications exemplify scale-driven positioning across residential broadband footprints, while Altice USA occupies a specialist position through fiber-deep upgrade concentration in the Northeast. These three entities anchor the competitive structure by representing divergent infrastructure strategies—dense metropolitan hybrid fiber-coaxial density, nationwide metropolitan coverage, and targeted fiber-deep penetration—each capturing distinct subscriber upgrade cycles and commercial venue expansion opportunities.
| Leading Market Players |
|---|
| Dish Network |
| Altice USA |
| Comcast |
| Verizon |
| Mediacom |
| Charter Communications |
| Cox Communications |
| Cogeco |
| DirecTV |
| Others |
Supply Flow & Price Mechanics
Content licensing fees from broadcast networks cascade through cable operator pricing tiers as retransmission consent negotiations compress video segment margins faster than residential ARPU recovery. These escalating carriage obligations force operators to absorb cost increases or pass them to subscribers, with skinny bundle packaging emerging as the primary mechanism to manage price sensitivity across customer segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments residential subscribers by bandwidth consumption and channel count. Price differentiation hinges on DOCSIS 3.1 throughput tiers and 4K video enablement, with hospitality venues and corporate campuses showing lowest price sensitivity due to centralized billing systems. Cost compression in expanded basic tiers is intensifying because broadcast network retransmission fees outpace subscriber growth, while premium fiber-deep upgrades command pricing power through gigabit convergence.
Supply Chain Analysis
Freight costs for hybrid fiber-coaxial equipment and DOCSIS 3.1 modems concentrate manufacturing dependencies across China, South Korea, and Taiwan. Raw material inputs draw from copper conductor suppliers, gallium arsenide semiconductor foundries, and optical fiber preform producers. Single-source vulnerability sits with specialized QAM encoder chipset suppliers as operators accelerate analog-to-IP plant conversions. Distribution runs through Tier-1 operator procurement divisions and regional systems integrators serving smaller MSOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in commercial IoT integration and addressable advertising as operators monetize underutilized plant infrastructure. Cloud-native video headend virtualization compresses capital intensity while enabling service-based economics to displace facility-based models.
For Market Incumbents: Hedge against OTT substitution by accelerating fiber-deep upgrade programs in underserved corridors where satellite alternatives retain footholds. Prioritize backward integration into edge computing co-location services at hub sites, capturing cloud gaming and distributed caching demand. Defend subscriber bases through broadband-video convergence that locks residential customers into gigabit throughput bundles with elevated switching costs.
For New Entrants and Emerging Players: The price-point gap between premium fiber tiers and economy digital cable packages creates entry space for IP-native operators targeting Brazil's analog-to-IP conversion cycle. White-space concentrates in commercial venue subscriptions for hotels and corporate campuses requiring integrated video-data packages with enterprise-grade SLAs. A channel partnership route through hospitality technology integrators bypasses direct infrastructure build-out requirements.
For Investors and Strategic Acquirers: Consolidation pressure builds where sub-scale operators face disproportionate FCC must-carry compliance burdens relative to subscriber scale. Long-term viability favors converged broadband-video platforms with fiber-deep density in metropolitan corridors over pure-play video distributors. Acquisition targets should demonstrate software-defined access migration progress and commercial IoT revenue pilots. The signal to watch is retransmission consent fee escalation velocity against skinny bundle ARPU recovery rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Fiber-Deep Infrastructure Upgrade | DOCSIS 3.1 deployment enables gigabit throughput convergence across residential and commercial footprints. |
| Cloud-Native Video Headend Virtualization | Virtualized channel origination collapses capital intensity from facility-based to service-based economics. |
| Commercial IoT Integration | Smart building systems monetize converged fiber-coaxial infrastructure beyond video delivery. |
| Addressable Advertising Technology | Dynamic ad insertion recovers CPM premiums lost to digital platforms through household-level targeting. |
| Edge Computing Co-location | Distributed caching and cloud gaming servers monetize underutilized hub site power and real estate. |
Methodological Framework
Coverage spans the United States, Brazil, Germany, Japan, and Canada, with primary inputs from each market's operator ecosystem. The approach combines interviews with network engineering executives, content licensing directors, hospitality procurement managers, and field technician supervisors alongside secondary validation. Secondary sources include FCC spectrum auction records, ANVISA equipment certification filings, METI energy efficiency standards, and operator capex disclosure documents. Bottom-up subscriber and revenue modeling triangulates against top-down market sizing from infrastructure deployment tracking.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled include service delivery mode, underlying transmission technology, subscriber category, and regional regulatory cluster. CAGRs derive from subscriber migration curves between analog, digital, and IP-based platforms. Industry-specific forecast inputs incorporate DOCSIS 3.1 deployment timelines and retransmission consent fee escalation trajectories.
Caveats apply where FCC spectrum reallocation decisions or streaming rights fragmentation could materially shift the outlook for linear distribution infrastructure value. Forecasts reflect assumptions about subscriber upgrade cycle velocity and commercial venue expansion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Television
Cloud TV Market
Television
Curved Television Market
Television
Cloud Television (TV) Market
Television
Pay TV Services Market
Television
Broadcasting and Cable TV Market
Television
Traditional TV and Home Video Market
Television
Television Broadcasting Services Market
Television
Holographic TV Market
Television
Television and Set Top Box Market
Television
Mobile TV Market
Television
Television Market
Television
Digital TV Market
Television
TV Advertising Market
Television
Print Newspapers and Magazines Market
Television
Television Advertising Market
Television
Pay TV Operator Market