
 Russia Food Hydrocolloids Market | 2026-2036
Russia Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Food Hydrocolloids Market Analytics
Bakery applications is pivoting toward hydrocolloid systems that replace synthetic stabilizers in laminated dough and gluten-free formulations. Cargill, Incorporated leverages its deep agricultural supply chain to secure consistent raw material flows into Russian food manufacturing. Tate & Lyle PLC differentiates through specialty starch-hydrocolloid blends tailored to local bakery processing conditions. Soyuzopttorg Group dominates domestic distribution channels, anchoring its position through direct relationships with regional millers and industrial bakeries.
Food hydrocolloids comprise high-molecular-weight polysaccharides and proteins that hydrate in aqueous systems to modify viscosity, gelation, and water-binding behavior; gelatin and pectin function as thermoreversible gelling agents with bloom strength and degree of esterification as critical functional parameters, while carrageenan forms stable gels through potassium-mediated helix aggregation in dairy matrices. Gelatin occupies the largest share of product-type value pools due to entrenched use in confectionery and dairy, though pectin captures accelerating growth from clean-label sauce and beverage formulations. Dairy Products application segments sustain premium positioning through hydrocolloid stabilization of drinking yogurts and processed cheese spreads.
Russia's Federal Service for Surveillance in Consumer Rights Protection and Human Wellbeing (Rospotrebnadzor) enforces Technical Regulation TR CU 029/2012 on food additive safety, while the Eurasian Economic Commission harmonizes maximum usage levels across member states, and national GOST standards specify hydrocolloid purity grades for domestic procurement. These frameworks compel importers and local blenders to maintain dual certification portfolios for EAEU and Russia-specific compliance. Stakeholders must monitor pending amendments to TR CU 029 that could restrict certain carrageenan subtypes or mandate enhanced labeling disclosures before committing to long-term formulation investments.
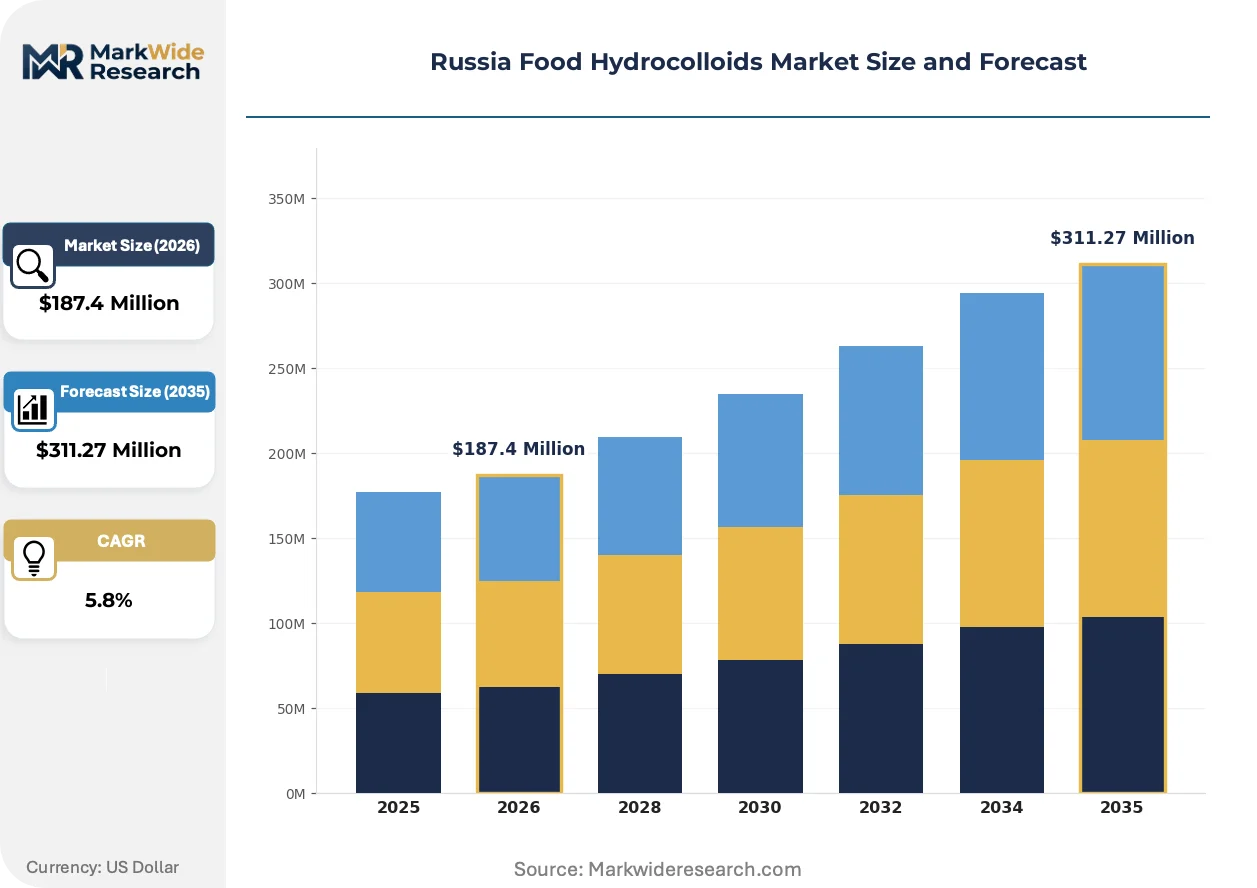
Market Dynamics
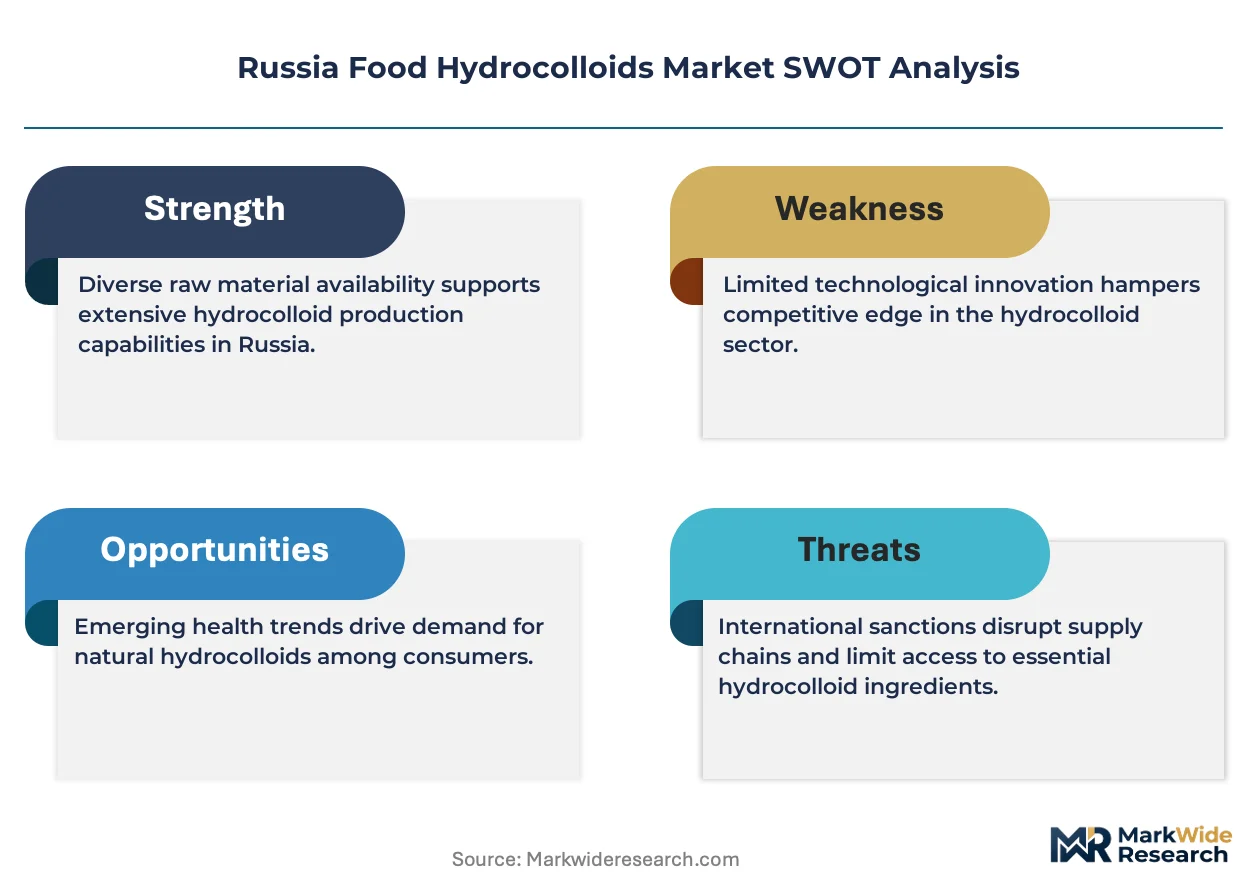
Rospotrebnadzor's tightening enforcement of TR CU 029/2012 purity standards is compressing formulation flexibility and forcing domestic blenders to rebuild certification portfolios around EAEU harmonization.
Growth Catalysts
- Clean-label bakery reformulation:Industrial bakeries in Moscow and Saint Petersburg are replacing synthetic stabilizers with pectin and hydrocolloid blends in laminated dough systems to meet retailer clean-label mandates.
- TR CU 029/2012 harmonization:Eurasian Economic Commission alignment of maximum usage levels across member states is reducing cross-border formulation barriers for Russian exporters targeting Kazakhstan and Belarus.
- Specialty dairy stabilization:Drinking yogurt and processed cheese spread manufacturers are expanding hydrocolloid volumes to achieve texture consistency in high-protein formulations.
Market Restraints
- Gelatin raw material concentration:Bovine and porcine hide supply chains concentrate in South American and Asian rendering facilities, exposing Russian processors to currency volatility and sanitary certificate delays.
- Carrageenan regulatory friction:Pending amendments to TR CU 029 may restrict certain kappa-carrageenan subtypes, forcing reformulation investments before technical clarity emerges.
- Starch-hydrocolloid substitution:Modified starches from domestic grain processors compete on cost in sauce and beverage applications where clean-label positioning is less critical.
Strategic Opportunities
- Gluten-free bakery penetration:Underdeveloped regional markets beyond Moscow and Saint Petersburg present volume expansion potential as celiac awareness rises and retail distribution deepens.
- Plant-based dairy convergence:Hydrocolloid systems combining gellan gum with native starches are capturing formulation trials in oat and soy milk alternatives as EAEU labeling rules clarify plant-protein claims.
- Direct miller relationships:Bypassing traditional ingredient distributors to contract directly with regional flour millers and industrial bakeries reduces margin capture by intermediaries.
Industry Challenges
- Dual certification complexity:Importers must maintain parallel GOST purity grade documentation and EAEU technical regulation compliance, extending product registration timelines.
- Specialized hydrocolloid blending capacity:Limited domestic expertise in shear-thinning rheology modification for UHT dairy applications constrains local production of high-performance stabilizer systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Food Hydrocolloids Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Agar, Pectin, Carrageenan Application: Dairy Products, Bakery Items, Beverages, Sauces End User: Food Manufacturers, Restaurants, Retailers, Catering Services Distribution Channel: Online Sales, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Brenntag, Archer Daniels Midland Company, Cargill, Incorporated, Ashland Inc., Ingredion Incorporated, Tate & Lyle PLC, Soyuzopttorg Group, Koninklijke DSM N.V., CP Kelco, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Food Hydrocolloids Market Evolving Landscape
Formulation science and regulatory harmonization are converging to reshape ingredient selection criteria across Russian food manufacturing, with functionality verification replacing cost-per-kilogram as the primary procurement filter.
Enzyme-modified pectin with tailored degree of esterification is absorbing volume from traditional amidated grades in low-sugar jam and fruit preparation applications. Moscow-based confectionery houses are accelerating adoption to achieve gel strength without calcium sequestration issues. This absorption is compressing demand for standardized pectin imports while rewarding blenders with in-house esterification capabilities.
Rospotrebnadzor's draft amendments to TR CU 029 disclosure requirements are forcing label redesigns across dairy and beverage portfolios. Manufacturers must now declare specific hydrocolloid subtypes rather than generic "stabilizer" designations. The confectionery segment faces the steepest compliance costs due to multi-component recipes and legacy packaging stock.
Buyer consolidation among Russian retail chains is compressing supplier negotiation cycles and unbundling technical service from ingredient supply contracts. Large-format retailers in the Central Federal District now demand dedicated formulation support without volume commitments. This shift is most visible in private-label sauce and dressing development, where speed-to-shelf trumps long-term partnership structures.
Russia Food Hydrocolloids Market Segmentation
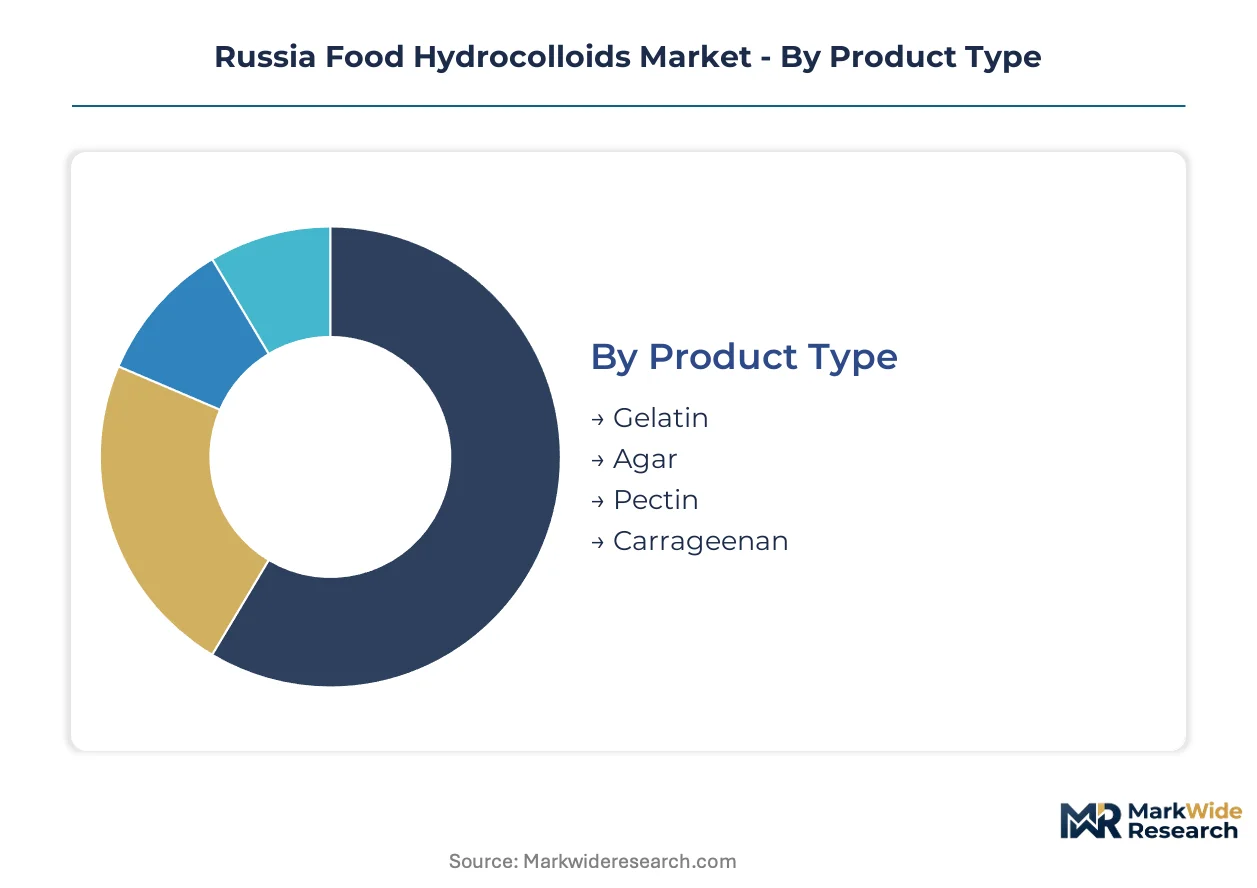
Segmentation in Russia's food hydrocolloids market reveals distinct procurement patterns across product chemistry, application rheology requirements, and channel control points. Each dimension exposes different margin structures and technical service intensity levels that shape supplier selection criteria.
Product Type:
Standalone hydrocolloids dominate commodity procurement where single-function gelling suffices, while embedded multi-hydrocolloid systems penetrate premium reformulation projects requiring synergistic viscosity control.
- Gelatin:Derived from partial hydrolysis of collagen with bloom strength specifications from 50 to 300, this thermoreversible gelling agent anchors confectionery and dairy applications across Moscow industrial zones. Saint Petersburg marshmallow manufacturers source high-bloom grades for aerated candy structures despite exposure to South American hide supply volatility.
- Pectin:Extracted from citrus peel and apple pomace with degree of esterification determining calcium sensitivity, this clean-label hydrocolloid displaces amidated grades in low-sugar jam formulations. Russian bakery reformulation projects in the Central Federal District specify high-methoxyl pectin for laminated dough stability without synthetic stabilizers.
- Agar:Seaweed-extracted polysaccharide with superior thermal stability above 85°C, agar serves niche halal and kosher confectionery segments where gelatin faces religious dietary restrictions.
- Carrageenan:Sulfated galactan from red algae forming potassium-mediated gels, this hydrocolloid stabilizes UHT dairy beverages though pending TR CU 029 amendments threaten certain kappa-subtype approvals.
Gelatin leads volumes today; pectin is gaining share fastest.
Application:
Cost-tier stratification separates premium-positioned applications demanding customized hydrocolloid blends from commodity segments where modified starches compete on price.
- Dairy Products:Drinking yogurt manufacturers in Moscow deploy carrageenan-locust bean gum systems for protein stabilization and syneresis control in high-protein formulations. Processed cheese spread producers require specialized shear-thinning rheology modification that domestic Russian blenders struggle to formulate consistently.
- Bakery Items:Industrial laminated dough operations across Saint Petersburg specify pectin-hydrocolloid blends to replace synthetic stabilizers under retailer clean-label mandates. Gluten-free bread formulations in underpenetrated regional markets beyond the Central Federal District present volume expansion potential.
- Beverages:Juice and nectar processors utilize low-viscosity hydrocolloids for pulp suspension where clean-label positioning commands premium shelf placement.
- Sauces:Tomato and cream-based sauce manufacturers balance cost against functionality, with modified starches capturing volume where label simplicity matters less.
Dairy Products anchor current procurement volumes; Bakery Items exhibit the steepest expansion trajectory.
End User:
Customer-type differentiation tracks formulation sophistication, with large-scale manufacturers integrating technical service into supply contracts while smaller operators purchase through distributor stock programs.
- Food Manufacturers:Moscow and Saint Petersburg-based industrial bakeries and dairy processors dominate hydrocolloid procurement, specifying custom stabilizer systems with dedicated rheology support. These buyers consolidate volumes to extract technical service commitments without minimum volume guarantees.
- Restaurants:Chain kitchen operations in the Central Federal District source pre-hydrocolloidized bases for sauce consistency across outlet networks.
- Retailers:Private-label developers demand speed-to-shelf formulation support, compressing supplier negotiation cycles and unbundling technical service from ingredient supply.
- Catering Services:Institutional feeding operations prioritize cost-stable supply through distributor relationships with limited technical interaction.
Food Manufacturers command the deepest technical engagement; Retailers are restructuring procurement fastest.
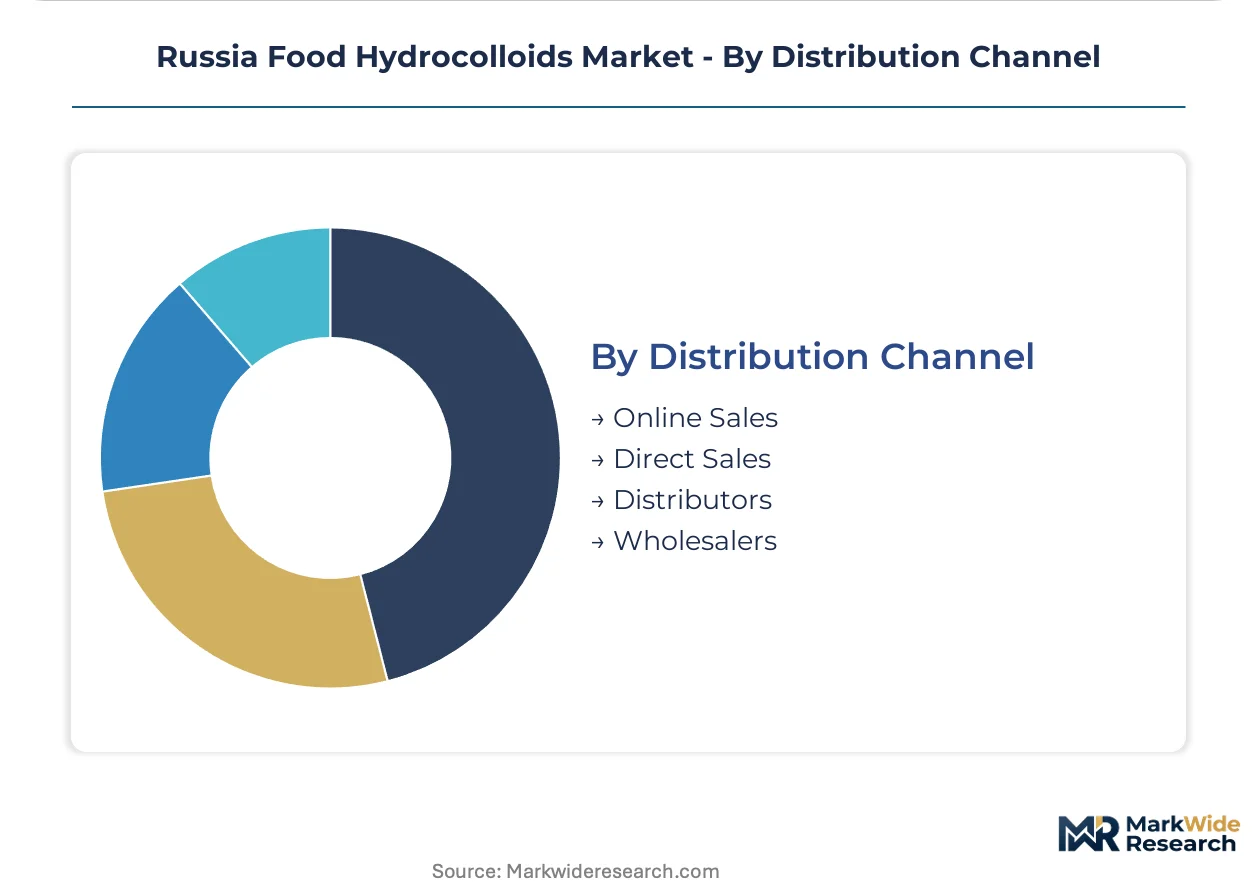
Distribution Channel:
Channel control determines margin capture, with direct miller relationships bypassing traditional distributor markups in concentrated geography while intermediaries penetrate fragmented regional markets.
- Direct Sales:Cargill, Incorporated and Tate & Lyle PLC maintain direct technical sales forces targeting top-tier Moscow and Saint Petersburg food manufacturers with customized formulation development. Soyuzopttorg Group anchors domestic distribution through direct miller relationships in regional flour processing clusters.
- Distributors:Regional ingredient distributors capture margin in secondary cities where fragmented bakery and dairy operations lack volume to justify direct supplier engagement.
- Wholesalers:Commodity-grade gelatin and standard pectin grades flow through wholesale channels serving smaller confectionery operations with limited technical requirements.
- Online Sales:E-procurement platforms emerge for standardized hydrocolloid grades where buyers prioritize transaction efficiency over formulation support.
Direct Sales concentrates premium volumes; Distributors retain deepest regional penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping hydrocolloid sourcing patterns as manufacturers migrate formulation activities toward jurisdictions with streamlined EAEU compliance pathways and lower certification burdens.
Central Federal District
Moscow anchors Russia's hydrocolloid procurement through concentrated dairy and confectionery manufacturing. Rospotrebnadzor enforces TR CU 029/2012 purity standards with particular intensity in this district. Industrial bakeries in the capital specify pectin-hydrocolloid blends for clean-label laminated dough reformulation.
Northwestern Federal District
Saint Petersburg marshallow manufacturers source high-bloom gelatin grades for aerated candy structures despite supply chain exposure to South American hide markets. The district's Federal Service for Surveillance in Consumer Rights Protection maintains stringent import documentation requirements. Regional confectionery clusters face steep relabeling costs from pending TR CU 029 disclosure amendments.
Volga Federal District
Flour millers in this region contract directly with hydrocolloid distributors to bypass traditional ingredient intermediaries. The Eurasian Economic Commission's harmonization of maximum usage levels reduces cross-border barriers for exporters targeting Kazakhstan. Nizhny Novgorod industrial bakeries pilot gluten-free formulations using pectin stabilization systems.
Siberian Federal District
Underpenetrated regional markets present volume expansion potential as celiac awareness rises and retail distribution deepens beyond Moscow-centric supply networks. Local procurement relies heavily on distributor channels due to fragmented bakery operations lacking volume for direct supplier engagement. Novosibirsk food manufacturers face extended product registration timelines from dual GOST-EAEU certification requirements.
Southern Federal District
Grain processors in this region produce modified starches that compete with hydrocolloids in cost-sensitive sauce and beverage applications. The district's proximity to Black Sea logistics corridors influences import routing for carrageenan and agar shipments. Rostov-on-Don dairy operations utilize carrageenan-locust bean gum systems for drinking yogurt stabilization.
Russia Food Hydrocolloids Market Competitive Landscape
Portfolio diversification dominates the current landscape as suppliers rebuild product mixes around clean-label pectin grades and away from carrageenan subtypes facing regulatory friction. The vendor base stratifies into three tiers: multinational agricultural processors with captive raw material supply, specialty ingredient blenders with in-house modification capabilities, and domestic distributors anchoring regional relationships. Strategic archetypes include backward-integrated agricultural conglomerates, esterification-capable formulation houses, and channel-controlling domestic traders. Competitive moves concentrate on direct miller contracting and certification portfolio expansion.
Within the multinational processor tier, Cargill, Incorporated and Tate & Lyle PLC occupy positions defined by agricultural supply chain depth and specialty starch-hydrocolloid blending expertise respectively. Soyuzopttorg Group anchors the domestic distribution archetype through direct relationships with regional millers and industrial bakeries. These three entities exemplify the competitive spectrum: agricultural originators with upstream control, technical specialists with formulation capabilities, and relationship-driven channel operators penetrating fragmented geography.
| Leading Market Players |
|---|
| Brenntag |
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| Ashland Inc. |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Soyuzopttorg Group |
| Koninklijke DSM N.V. |
| CP Kelco, Inc. |
| Others |
Value Network & Pricing Analysis
Bloom gelatin price indices from South American hide markets cascade through Russian distribution channels, compressing margins at importer level while concentrating pricing power among agricultural originators with captive rendering supply. TR CU 029/2012 certification costs layer onto landed costs, forcing three-tier pricing stratification across premium EAEU-compliant grades, standard GOST-certified volumes, and economy-tier wholesale gelatin.
Pricing Analysis
Distributor markups of 12-18% separate direct miller contracts from wholesale channel procurement in secondary cities. Three-tier pricing structure across premium, standard, and economy levels reflects dual certification burden, with EAEU-compliant pectin commanding formulation support bundling. Cost compression in economy-tier gelatin runs through currency volatility on South American hide settlements. Small confectionery operations in Siberian Federal District exhibit highest price sensitivity; Moscow dairy processors least.
Supply Chain Analysis
Gelatin supply rests on Brazilian and Argentine rendering facilities for bovine hides, Indonesian and Thai operations for porcine sources, exposing Russian blenders to sanitary certificate delays. Pectin draws from citrus peel processors in Mexico and apple pomace concentrators in Poland. Single-source vulnerability concentrates in high-bloom gelatin grades for aerated confectionery. Distribution runs through Soyuzopttorg Group's direct miller relationships in Volga Federal District flour clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's food hydrocolloids market functions as a geographic-arbitrage play where EAEU harmonization reduces cross-border formulation costs versus non-member states, while Rospotrebnadzor enforcement intensity creates compliance premiums against Central Asian competitors.
For Market Incumbents: Anticipate pending TR CU 029 amendments restricting kappa-carrageenan subtypes by accelerating pectin blend R&D and securing dual GOST-EAEU certification portfolios ahead of technical clarity. Backward integration into citrus peel sourcing through Polish processor partnerships defends margin position against South American hide volatility. Channel control via direct miller relationships in Volga Federal District anchors volume retention. For New Entrants and Emerging Players: Begin with gluten-free bakery penetration in underpenetrated Siberian Federal District markets where celiac awareness rises and distributor-dependent local bakers lack technical formulation support. Plant-based dairy stabilization in oat and soy milk alternatives presents adjacent white-space as EAEU labeling rules clarify. Go-to-market through e-procurement platforms for standardized grades bypasses incumbent technical service bundling. For Investors and Strategic Acquirers: Asymmetric upside sits with esterification-capable formulation houses possessing in-house pectin modification capabilities and existing EAEU certification infrastructure. Long-term viability hinges on clean-label transition durability across Russian retail consolidation. Acquisition target archetype: domestic blenders with shear-thinning rheology expertise for UHT dairy applications. Watch Rospotrebnadzor draft amendment finalization timing as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Sourcing | Cargill's agricultural supply chain depth secures consistent hide and citrus peel flows into Russian manufacturing. |
| EAEU Certification Portfolio Expansion | Dual GOST-EAEU compliance reduces registration timelines for exporters targeting Kazakhstan and Belarus markets. |
| Direct Miller Relationship Development | Soyuzopttorg Group's regional flour cluster bypass captures margin from traditional ingredient distributors. |
| Clean-Label Pectin Esterification Investment | In-house modification capabilities absorb volume from standardized imports amid TR CU 029 disclosure tightening. |
| Gluten-Free Bakery Technical Service Deployment | Formulation support penetration in Siberian Federal District unlocks underpenetrated regional volume expansion. |
Research Methodology
Direct dialogue with procurement directors at Moscow dairy processors, technical R&D leads at Saint Petersburg confectionery houses, regulatory affairs specialists navigating TR CU 029 compliance, and regional miller operators in Volga Federal District grounded qualitative findings. Secondary validation drew from Rospotrebnadzor regulatory filings, Eurasian Economic Commission harmonization directives, customs import records for hydrocolloid shipments, and GOST standard documentation. Bottom-up volume estimates from application-level consumption patterns triangulated against top-down market sizing from supplier shipment data.
Segment-level projections across product type, application rheology requirements, end-user sophistication tiers, and channel control points fed into analytical framework outputs over the projection horizon. CAGRs derived from regression analysis against macro food manufacturing indices and clean-label reformulation adoption curves. Industry-specific forecast inputs included EAEU regulatory amendment probability weights and South American hide price volatility assumptions.
Caveats apply where Rospotrebnadzor enforcement intensity shifts or EAEU technical regulation amendments could materially shift the outlook. Forecasts embed assumptions around certification timeline stability and raw material supply chain continuity. A small set of named triggers—regulatory amendment finalization, currency volatility spikes, retail consolidation acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Grade Alginate Market
Food Components and Additives
Edible Oil Co-Products and by-Products Market
Food Components and Additives
Food Grade Magnesium Carbonate Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Food Grade Silica Market
Food Components and Additives
Flavonoids Market
Food Components and Additives
Australia Food Hydrocolloids Market
Food Components and Additives
Edible Films and Coating Market
Food Components and Additives
Linoleic Acid Market
Food Components and Additives
Natural Antioxidants Market
Food Components and Additives
Food-Grade Monopotassium Phosphate Market
Food Components and Additives
Spain Food Hydrocolloids Market
Food Components and Additives
South Africa Food Hydrocolloids Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
Citrus Pectin from Mediterranean Juice Side Streams Market
Food Components and Additives
Natural Fatty Acids Market