
 Isoflavones Market | 2026-2036
Isoflavones Market Size, Share, and Industry Trends Forecast 2026-2036
Isoflavones Market Analysis
China is narrowing its dependence on imported isoflavone raw material through domestic soybean processing expansion in Shandong Province. ADM leverages vertically integrated crushing and extraction infrastructure across the American Midwest. Cargill sustains supply chain control through identity-preserved soybean sourcing programs. DSM-Firmenich differentiates via fermentation-derived genistein production that bypasses agricultural variability.
Isoflavones constitute a class of polyphenolic phytoestrogens—primarily genistein, daidzein, and glycitein—extracted from leguminous plants through solvent or supercritical CO2 methods, functioning as selective estrogen receptor modulators in nutraceutical and pharmaceutical applications. Soybean-derived isoflavones dominate volume throughput due to established extraction economics and standardized 40% isoflavone content in commercial concentrates. Dietary supplement applications command premium positioning as clinically dosed menopause support products shift from prescription hormone therapy. Powder formulations lead industrial adoption for bulk blending into functional foods and beverage premixes.
The FDA maintains GRAS status for soy isoflavones in conventional foods while requiring NDIN filings for new dietary ingredient concentrations above historical use levels. EFSA evaluates health claim substantiation under the EU Nutrition and Health Claims Regulation, constraining marketing language for genistein-specific bone density assertions. China's NMPA classifies high-purity isoflavone extracts as active pharmaceutical ingredients subject to drug master file requirements. Stakeholders must monitor evolving pharmacovigilance data on endocrine interaction profiles as regulatory bodies reassess acceptable daily intake thresholds.
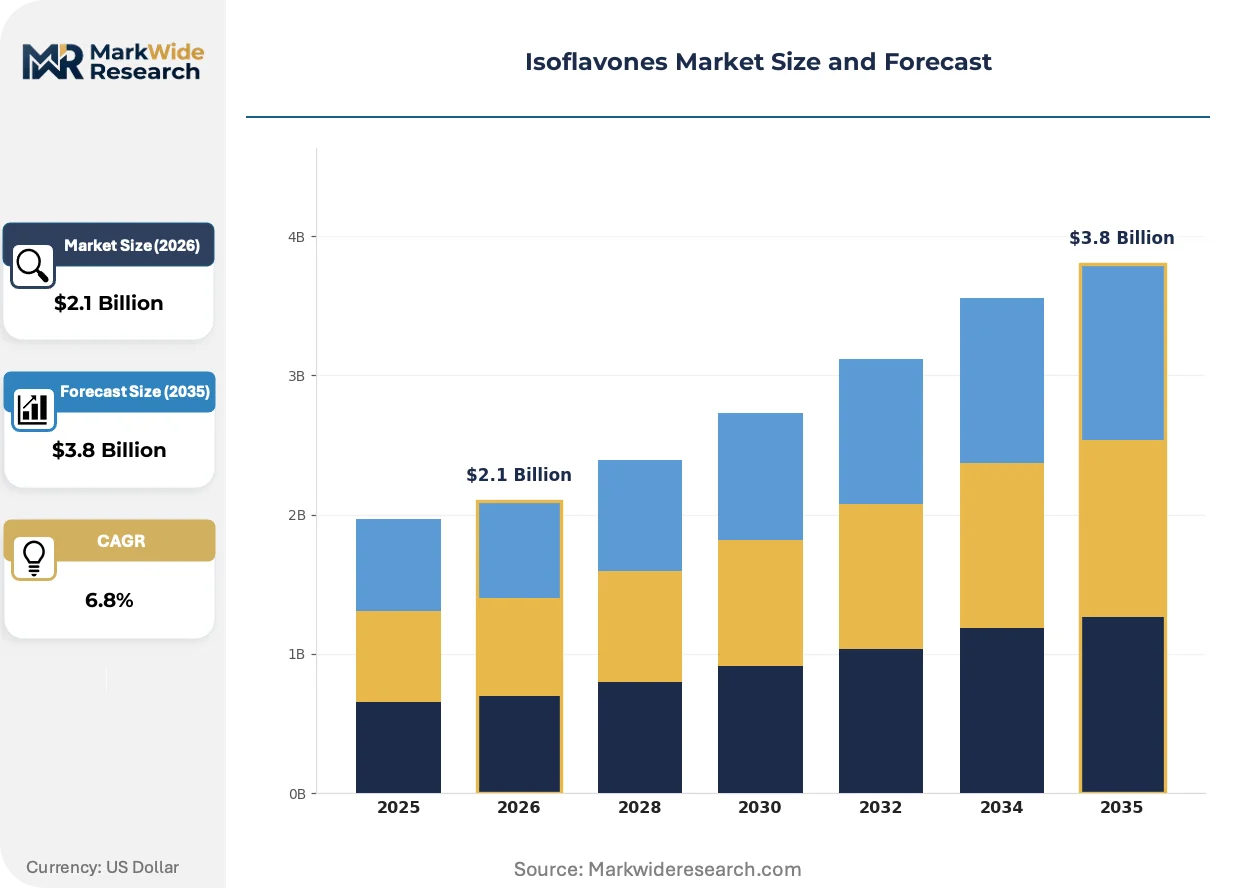
Market Dynamics
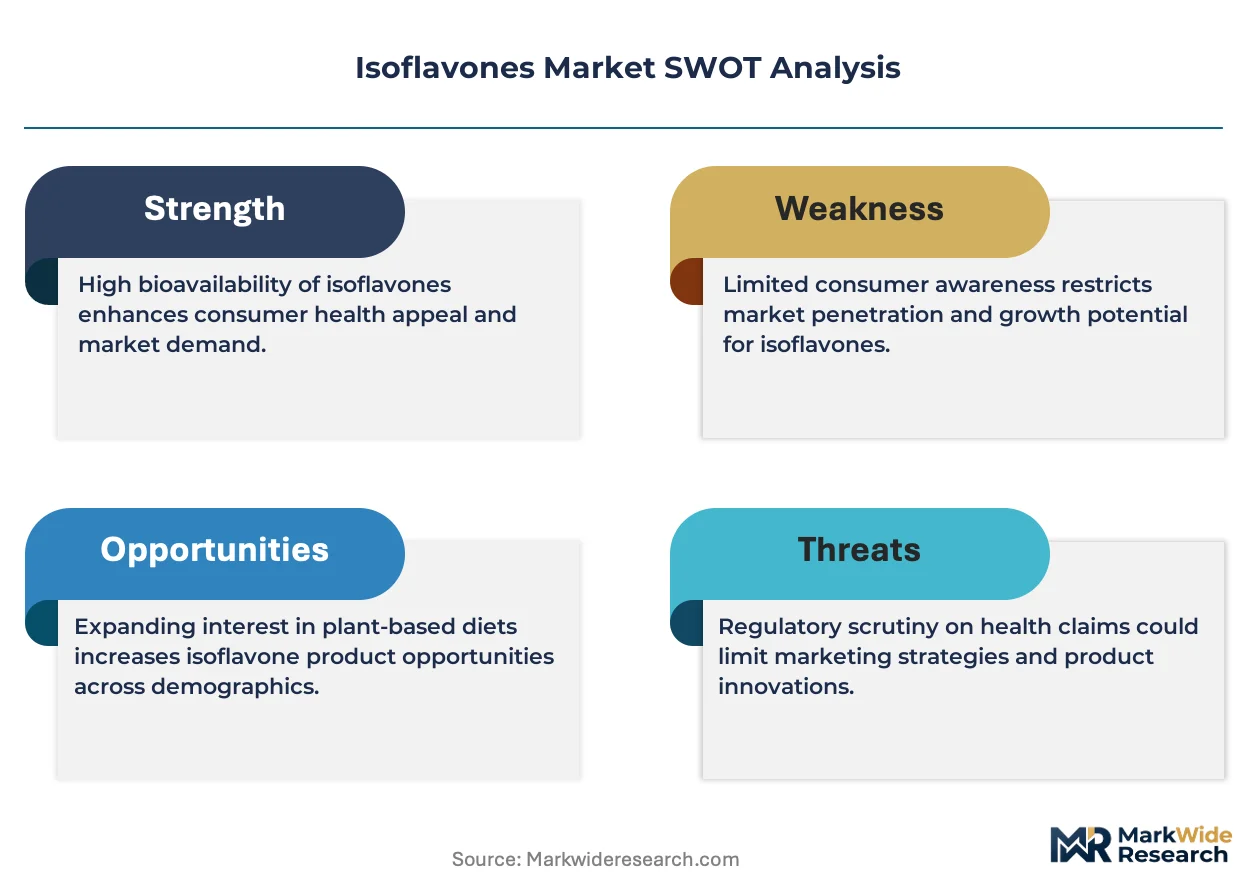
Regulatory divergence between pharmaceutical and nutraceutical approval pathways is fragmenting go-to-market strategies for isoflavone suppliers, forcing parallel compliance investments across FDA NDIN filings, EFSA health claim substantiation, and NMPA drug master file requirements.
Growth Catalysts
- EFSA Bone Health Claims:Validated genistein-specific assertions for post-menopausal bone density maintenance accelerate premium positioning in European dietary supplements, driving clinically dosed formulation demand.
- Shandong Processing Expansion:Domestic soybean crushing capacity growth in China's coastal provinces reduces raw material import dependency while improving extraction cost economics for regional suppliers.
- Fermentation-Derived Production:Microbial biosynthesis of genistein bypasses agricultural yield variability and pesticide residue concerns, enabling pharmaceutical-grade purity without identity-preserved crop programs.
Market Restraints
- Input Cost Volatility:Non-GMO soybean premiums and organic certification requirements for identity-preserved sourcing inflate raw material costs beyond conventional commodity crushing economics.
- Supply Concentration Risk:Midwestern United States crushing infrastructure dominates global isoflavone concentrate throughput, creating geographic single-point vulnerability to climate-driven crop failures.
- Endocrine Interaction Scrutiny:Pharmacovigilance monitoring by FDA and EMA of estrogen receptor modulation effects constrains acceptable daily intake thresholds and limits pediatric or pregnancy-targeted applications.
Strategic Opportunities
- Menopause Support Pharmaceuticals:Prescription hormone therapy displacement creates white space for clinically validated isoflavone-based therapeutics requiring drug approval pathways in Germany and France.
- Functional Food Fortification:GRAS-status soy isoflavones enable beverage and bakery premix integration in United States retail channels, expanding beyond supplement aisle distribution.
- EU Novel Food Tailwinds:Streamlined botanical ingredient approval timelines under consolidated Novel Food Regulation procedures accelerate new legume source market entry for clover and chickpea-derived isoflavones.
Industry Challenges
- Pharmaceutical-Grade Certification Timelines:NMPA drug master file requirements and FDA active pharmaceutical ingredient inspections impose 18-36 month compliance cycles that strain working capital for extractors transitioning from nutraceutical to drug supply.
- Supercritical CO2 Technical Gap:Specialized extraction engineering talent scarcity limits solvent-free processing capacity expansion despite clean-label demand, constraining supply response to organic segment growth.
- Cross-Border IP Complexity:Patent thickets around fermentation-derived genistein production methods create licensing friction for microbial biosynthesis entrants in Asian manufacturing jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isoflavones Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genistein, Daidzein, Glycitein, Others End User: Pharmaceuticals, Dietary Supplements, Food & Beverages, Cosmetics Source: Soybeans, Chickpeas, Red Clover, Others Form: Powder, Liquid, Capsules, Extracts |
| Companies Covered | Archer Daniels Midland Company (ADM), Cargill, Incorporated, DSM-Firmenich, BASF, International Flavors & Fragrances Inc., Indena S.p.A, Nexira Inc., NutraScience Labs, NOW Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isoflavones Market Emerging Trajectories
Fermentation biotechnology and supercritical extraction methods are compressing traditional agricultural supply dependencies while regulatory clarity on health claims reshapes competitive positioning across pharmaceutical and nutraceutical channels.
Microbial biosynthesis platforms utilizing engineered yeast strains are collapsing the link between isoflavone production and soybean cultivation cycles. Pharmaceutical formulators in Germany and Switzerland are adopting fermentation-derived genistein at accelerating rates to secure batch-to-batch consistency. This technology is collapsing price premiums previously commanded by identity-preserved organic soy sources.
EFSA's updated guidance on bone health claim substantiation for genistein is tightening clinical evidence requirements while clarifying permissible marketing language. The regulation compels supplement manufacturers to invest in randomized controlled trial data packages. Menopause support products targeting post-menopausal women in France and Italy face the steepest compliance adjustment costs.
Direct-to-consumer subscription models for personalized menopause support regimens are displacing pharmacy-based hormone therapy dispensing in United States metropolitan markets. Telehealth platforms integrating at-home hormone testing with isoflavone dosing protocols capture patient data that informs formulation development. This channel shift concentrates initially in California and New York wellness ecosystems before diffusing to secondary markets.
Isoflavones Market Segmentation
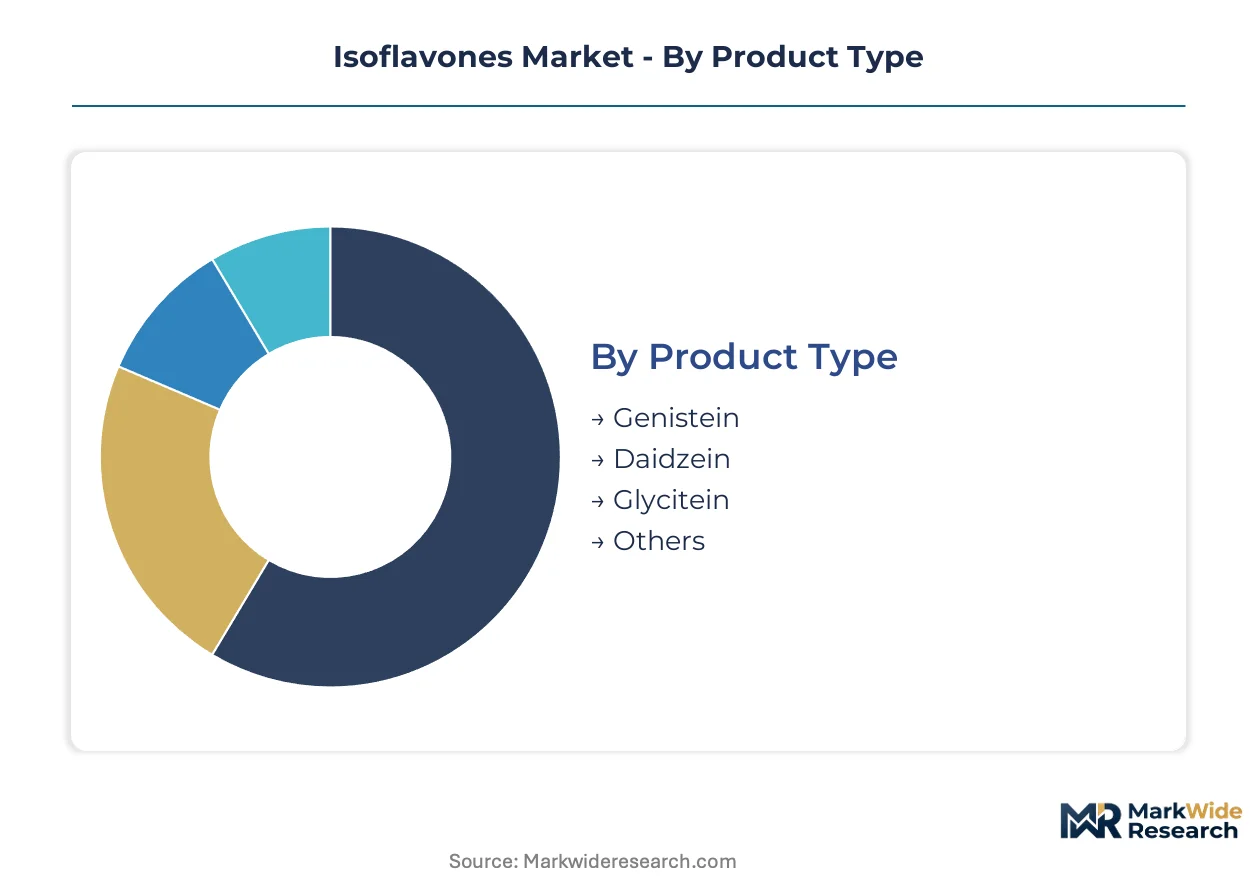
Isoflavone suppliers navigate divergent technical specifications across pharmaceutical-grade purity requirements and food-grade volume applications. Segmentation reveals where formulation complexity commands premium positioning versus commodity throughput economics.
Product Type:
Use-case spectrum spans hormone modulation intensity, with receptor binding affinity determining clinical versus nutraceutical deployment.
- Genistein:Highest estrogen receptor beta selectivity among soy isoflavones drives pharmaceutical prioritization for bone density formulations. German formulators concentrate demand for this specific aglycone in menopause therapeutics, constrained by EFSA's tightened bone health claim substantiation requirements.
- Daidzein:Gut microbiota conversion to equol enhances bioavailability variability, creating formulation standardization challenges. United States dietary supplement manufacturers favor this segment for clinically dosed menopause support products displacing prescription hormone therapy.
- Glycitein:Methoxy-substituted isoflavone with distinct pharmacokinetic profile suited to cosmeceutical antioxidant applications.
- Others:Formononetin and biochanin A from red clover sources occupy niche pharmaceutical research pipelines.
Established volume favors daidzein; emerging adoption favors genistein.
End User:
Cost tier stratification separates drug-grade certification investments from GRAS-status commodity positioning.
- Pharmaceuticals:Active pharmaceutical ingredient purity standards require NMPA drug master file compliance and FDA inspection readiness. German and French prescription menopause therapy expansion drives this segment's steepest expansion trajectory.
- Dietary Supplements:NDIN filing thresholds for concentrated extracts create regulatory moats against commodity competition. United States direct-to-consumer subscription models concentrate demand in California and New York wellness ecosystems.
- Food & Beverages:GRAS-status soy isoflavones enable beverage and bakery premix integration without pharmaceutical compliance burdens.
- Cosmetics:Topical antioxidant claims operate under less stringent substantiation requirements than ingestible health assertions.
Margin concentration sits with pharmaceuticals; volume scale sits with food and beverages.
Source:
Supply geography dictates extraction economics and identity-preserved program premiums.
- Soybeans:Dominant volume throughput leverages established crushing infrastructure across the American Midwest. Shandong Province processing expansion is narrowing China's import dependency while improving regional supplier cost positions.
- Chickpeas:Emerging alternative source benefiting from EU Novel Food Regulation streamlining for botanical ingredient approvals.
- Red Clover:Isoflavone profile rich in formononetin targets pharmaceutical research applications outside standard soy-derived specifications.
- Others:Alfalfa and kudzu sources occupy negligible commercial scale.
Agricultural concentration favors soybeans; regulatory tailwinds favor chickpeas.
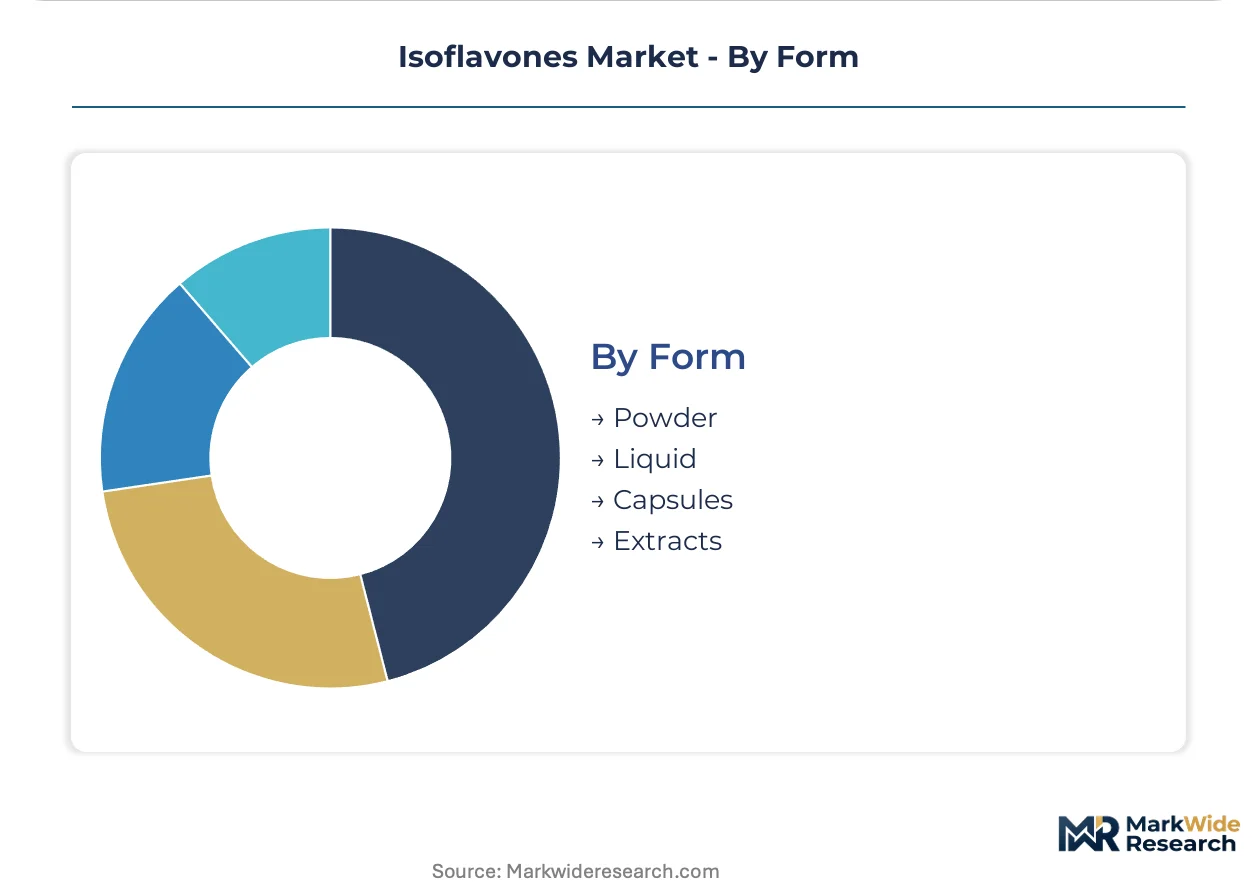
Form:
Customer type determines packaging complexity, with industrial buyers favoring bulk handling and consumers demanding unit-dose convenience.
- Powder:Standardized 40% isoflavone concentrates dominate functional food and beverage premix integration. Bulk blending efficiency drives adoption among United States retail channel formulators.
- Liquid:Solubility-enhanced formulations suit beverage fortification applications requiring homogenous dispersion.
- Capsules:Unit-dose precision enables clinically validated menopause support positioning in pharmacy and direct-to-consumer channels.
- Extracts:Supercritical CO2-derived solvent-free options command organic segment premiums despite capacity constraints from specialized engineering talent scarcity.
Industrial throughput favors powder; clean-label positioning favors extracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA GRAS status for soy isoflavones anchors United States demand concentration, while EFSA bone health claim substantiation reshapes European formulation economics. Shandong Province processing expansion is compressing China's import dependency for raw material sourcing.
United States
Direct-to-consumer subscription models for menopause support regimens concentrate demand in California and New York wellness ecosystems. FDA NDIN filing thresholds for concentrated extracts create regulatory moats against commodity competition. ADM leverages vertically integrated crushing infrastructure across the American Midwest to control supply chain economics.
Germany
Pharmaceutical formulators in Munich and Frankfurt are expanding isoflavone-based menopause therapy portfolios. EMA pharmacovigilance monitoring of estrogen receptor modulation effects constrains acceptable daily intake thresholds. Bavarian fermentation biotechnology clusters are accelerating adoption of microbial biosynthesis for pharmaceutical-grade genistein production.
China
Domestic soybean crushing capacity growth in Shandong Province reduces raw material import dependency. NMPA drug master file requirements classify high-purity isoflavone extracts as active pharmaceutical ingredients. Yangtze River Delta extraction facilities are improving regional supplier cost positions through captive processing infrastructure.
France
Menopause support products targeting post-menopausal women face steep EFSA compliance adjustment costs for bone health claim substantiation. ANSM monitoring of endocrine interaction profiles limits pediatric or pregnancy-targeted applications. Lyon-based pharmaceutical research clusters are driving formononetin-specific therapeutic development from red clover sources.
Switzerland
Swissmedic pharmaceutical-grade certification requirements impose extended compliance cycles for extractors transitioning from nutraceutical to drug supply. Geneva and Basel fermentation biotechnology hubs are adopting microbial biosynthesis platforms to secure batch-to-batch consistency. DSM-Firmenich anchors regional production of fermentation-derived genistein that bypasses agricultural variability.
Isoflavones Market Vendor Landscape
Capability concentration sits with fermentation biotechnology specialists; scale advantage sits with agricultural commodity processors. The market structures around three tiers: multinational ingredient suppliers with crushing infrastructure, pharmaceutical-grade extractors with regulatory certification depth, and fermentation biotechnology platforms with biosynthesis IP. Dominant competitive moves include backward integration into identity-preserved soybean sourcing and technology licensing for microbial production methods.
Within the multinational ingredient supplier tier, Archer Daniels Midland Company exemplifies scale-driven positioning through Midwestern crushing infrastructure, while Cargill, Incorporated occupies a comparable anchor position. DSM-Firmenich represents the fermentation biotechnology archetype, leveraging biosynthesis capabilities that bypass agricultural supply dependencies. These three entities collectively illustrate the competitive divergence between commodity-scale processing and precision biotechnology platforms.
| Leading Market Players |
|---|
| Archer Daniels Midland Company (ADM) |
| Cargill, Incorporated |
| DSM-Firmenich |
| BASF |
| International Flavors & Fragrances Inc. |
| Indena S.p.A |
| Nexira Inc. |
| NutraScience Labs |
| NOW Foods |
| Others |
Supply Flow & Price Mechanics
Midwestern crushing infrastructure concentration determines both pharmaceutical-grade premium spreads and nutraceutical commodity tier positioning, with identity-preserved sourcing programs and fermentation-derived alternatives bifurcating procurement economics across buyer segments.
Pricing Analysis
Price spreads between United States and Chinese supply origins reflect extraction cost differentials and certification burden variations. Three-tier pricing structure across pharmaceutical-grade, nutraceutical-concentrated, and food-grade commodity levels separates NMPA drug master file compliance costs from GRAS-status bulk volumes. Cost compression in standard-grade concentrates intensifies as Shandong Province processing expansion narrows China's import dependency. Pharmaceutical formulators in Germany exhibit lowest price sensitivity due to batch-to-batch consistency requirements, while United States beverage premix buyers prioritize volume scale over purity premiums.
Supply Chain Analysis
Non-GMO soybean feedstock draws from identity-preserved programs across the American Midwest, with Shandong Province crushing expansion and Swiss fermentation biotechnology hubs providing alternative sourcing anchors. Agricultural cultivation cycles, microbial biosynthesis capacity, and supercritical CO2 engineering talent constrain upstream flexibility. Single-source vulnerability concentrates in Midwestern crushing infrastructure exposed to climate-driven crop variability. Distribution runs through vertically integrated multinational suppliers for pharmaceutical channels, while nutraceutical volumes fragment across regional extractors and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Isoflavone incumbents face substitution pressure from synthetic hormone therapy alternatives and peptide-based menopause therapeutics that threaten to displace phytoestrogen positioning in prescription channels.
For Market Incumbents: Insulate pharmaceutical-grade revenue streams through NMPA drug master file completion and FDA active pharmaceutical ingredient inspection readiness before commodity-grade margin erosion accelerates. Backward integration into captive soybean crushing in Shandong Province or Bavarian fermentation biotechnology clusters reduces agricultural yield vulnerability. Channel control via direct-to-consumer subscription platforms in California and New York wellness ecosystems defends against telehealth-integrated competitor entry.
For New Entrants and Emerging Players: French menopause support markets exhibit underpenetration relative to EFSA bone health claim substantiation investment requirements that deter incumbent expansion. Chickpea-derived isoflavones benefit from EU Novel Food Regulation streamlining that accelerates approval timelines versus conventional soy sources. White-space capture requires clinically dosed formulation partnerships with German pharmaceutical formulators seeking alternatives to prescription hormone therapy displacement.
For Investors and Strategic Acquirers: Fermentation biotechnology specialists with microbial genistein biosynthesis IP present acquisition targets as pharmaceutical-grade purity demand outpaces agricultural extraction capacity. Long-term viability hinges on displacement resistance against synthetic selective estrogen receptor modulators entering menopause therapeutic pipelines. Watch FDA pharmacovigilance monitoring of endocrine interaction profiles as the inflection signal for acceptable daily intake threshold revisions that reshape addressable market scope.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Buildout | Microbial biosynthesis platforms bypass agricultural yield variability for pharmaceutical-grade genistein supply security. |
| Regulatory Certification Investment | NMPA drug master file completion and FDA inspection readiness unlock prescription menopause therapy channel access. |
| Identity-Preserved Sourcing Programs | Non-GMO and organic soybean supply chains defend clean-label positioning against commodity concentrate competition. |
| Direct-to-Consumer Channel Launch | Telehealth-integrated subscription models capture patient data informing formulation development in United States wellness markets. |
| EU Novel Food Approval Pathway | Streamlined botanical ingredient procedures accelerate chickpea and red clover isoflavone market entry timelines. |
Methodological Framework
Operator-level perspectives from pharmaceutical formulators, dietary supplement manufacturers, extraction facility engineers, and regulatory affairs specialists anchored the qualitative base for this analysis. Primary interview insights combined with secondary validation from FDA GRAS notices, EFSA health claim opinions, NMPA drug master file registrations, and customs trade data. Bottom-up volume modeling across source type, purity grade, and end-use application triangulated against top-down market sizing from crushing capacity and fermentation biotechnology throughput disclosures.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling spanning isoflavone type, source origin, form factor, and end-user certification tier. CAGRs derived from regression analysis of historical price-volume relationships and capacity expansion announcements. Forecast inputs incorporated EFSA bone health claim substantiation timelines, NMPA pharmaceutical-grade classification enforcement, and United States direct-to-consumer channel penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed processors or breakthrough synthetic biology platforms would shift outcomes beyond modeled ranges. Cross-checking against EMA pharmacovigilance disclosure trends and United States telehealth platform partnership announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Germany Food Hydrocolloids Market
Food Components and Additives
France Food Preservatives Market
Food Components and Additives
Food Antimicrobial Coating Market
Food Components and Additives
Astaxanthin Market
Food Components and Additives
Lutein and Zeaxanthin Market
Food Components and Additives
Food Grade Antifoams Market
Food Components and Additives
Europe Fat Replacers Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
Food Grade Iron Powder Market
Food Components and Additives
North America Food Antimicrobial and Antioxidants Market
Food Components and Additives
Food Grade Magnesium Carbonate Market
Food Components and Additives
Italy Food Hydrocolloids Market
Food Components and Additives
Germany Food Preservatives Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Europe and MEA Food Phosphate Market
Food Components and Additives
Soybean by-Products Market