
 Citrus Pectin from Mediterranean Juice Side Streams Market | 2026-2036
Citrus Pectin from Mediterranean Juice Side Streams Market Size, Share, and Industry Trends Forecast 2026-2036
Citrus Pectin from Mediterranean Juice Side Streams Market Insights
The citrus pectin supply base is splitting between premium-grade LM and amidated pectin for pharmaceutical and nutraceutical contracts and commodity HM pectin for standard food applications. Cargill leverages its integrated citrus processing footprint in Brazil and Spain to secure raw material continuity. Herbstreith & Fox anchors its position through specialized extraction know-how and decades of European pharmaceutical-grade certification. Silvateam competes by dominating the Italian lemon peel supply corridor and extending its output into high-margin amidated grades.
Citrus pectin extracted from Mediterranean juice side streams comprises a heteropolysaccharide rich in galacturonic acid units, typically requiring acidic hydrolysis at pH 1.5–3.0 and temperatures of 60–90°C to release the polymer from flavedo and albedo tissues. The extracted material functions primarily as a gelling agent, stabilizer, and viscosity modifier across food systems, drug delivery matrices, and cosmetic emulsions. HM pectin occupies the largest volume share in conventional confectionery and jam applications where rapid-set gelation dominates procurement specifications. Enzymatic extraction represents the fastest-growing technology segment as personal care producers and nutraceutical firms demand solvent-free certification and lower thermal degradation profiles. The end user industry dimension shows nutraceutical firms capturing the steepest demand trajectory driven by encapsulation-grade pectin for probiotic and controlled-release supplements.
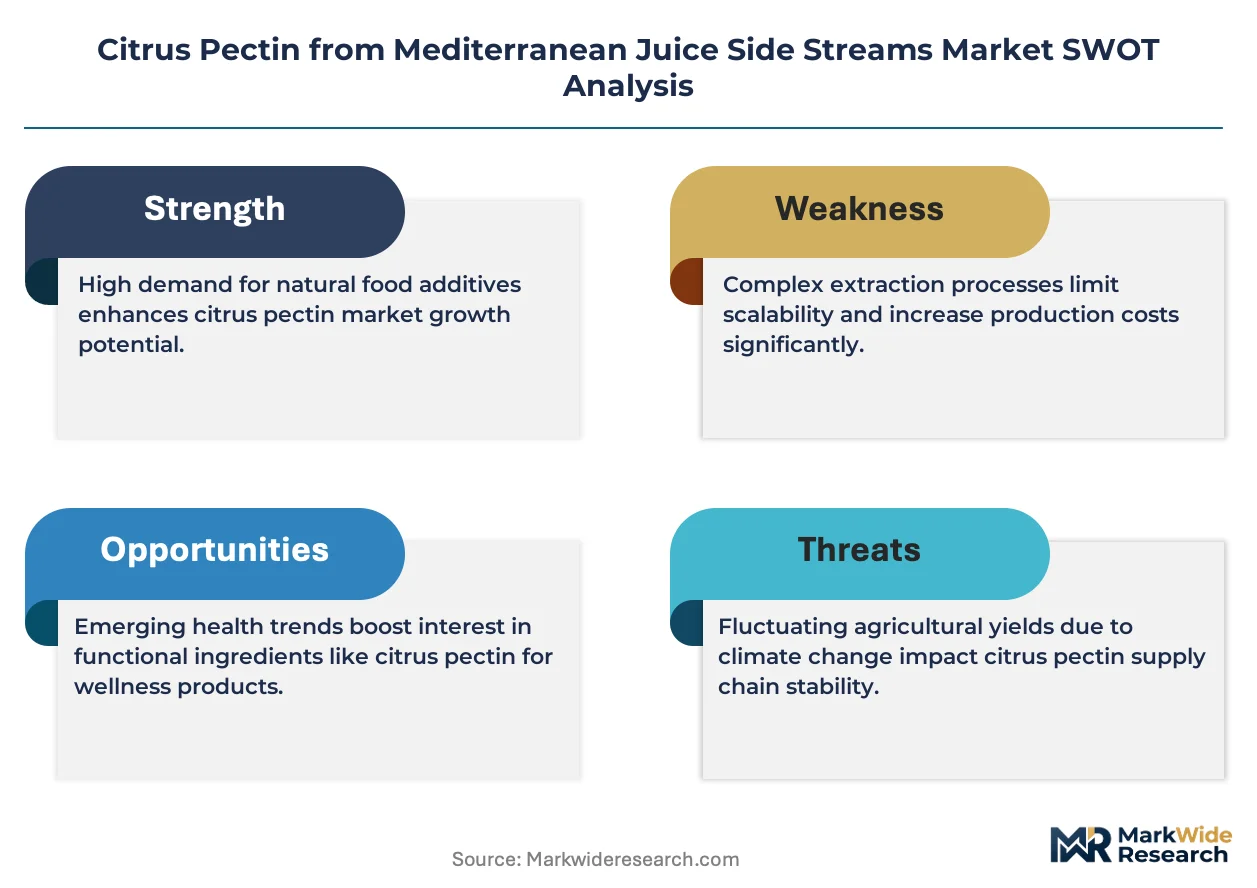
EU Green Deal circular economy directives and REACH chemical safety standards shape extraction chemistry choices and waste-water discharge permits across Spanish and Italian processing zones. EFSA novel food rulings and CE marking requirements for pharmaceutical excipients govern market access for new entrants targeting food and drug applications. Stakeholders must monitor how EU F-Gas Regulation amendments affect refrigeration-dependent citrus storage costs and whether national bioeconomy funding reallocations shift competitive advantage between acid-based and enzymatic extraction routes.
Market Dynamics
EU Green Deal waste-reduction mandates are pressuring Mediterranean juice processors to valorize peel side streams rather than landfill them, splitting the supply base between premium-grade LM pectin for pharmaceutical contracts and commodity HM pectin for standard food applications.
Growth Catalysts
- Clean-label nutraceutical demand:Formulators in probiotic encapsulation are specifying low-methoxyl pectin for its gelling precision and consumer-friendly ingredient lists.
- REACH chemical safety standards:ECHA compliance requirements are accelerating solvent-free enzymatic extraction adoption across Spanish and Italian processing zones.
- Spanish orange peel concentration:Valencia and Murcia processing corridors generate the densest raw material availability in Europe, anchoring supply security for regional extractors.
Market Restraints
- Citric acid price volatility:Acidic hydrolysis at pH 1.5–3.0 depends on citric acid inputs whose costs fluctuate with Brazilian sugarcane ethanol diversion.
- Italian supply corridor concentration:Silvateam's dominance of Sicilian lemon peel creates single-source vulnerability for amidated pectin buyers.
- EFSA novel food rulings:Extended safety assessment timelines delay market access for new extraction variants targeting food applications.
Strategic Opportunities
- Portuguese citrus expansion:Alentejo orange groves remain underexploited for pectin extraction, offering greenfield processing capacity.
- Amidated pectin in drug delivery:Pharmaceutical matrix applications for controlled-release formulations represent an emerging high-margin segment.
- EU bioeconomy funding:National reallocations toward circular economy projects subsidize enzymatic extraction capex for qualifying processors.
Industry Challenges
- Pharmaceutical-grade certification timelines:CE marking requirements for excipient-grade pectin demand 18–24 month validation cycles that strain working capital.
- Enzymatic extraction skill scarcity:Bioprocess engineering talent capable of optimizing solvent-free protocols at commercial scale remains concentrated in specialized academic programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Citrus Pectin from Mediterranean Juice Side Streams Market |
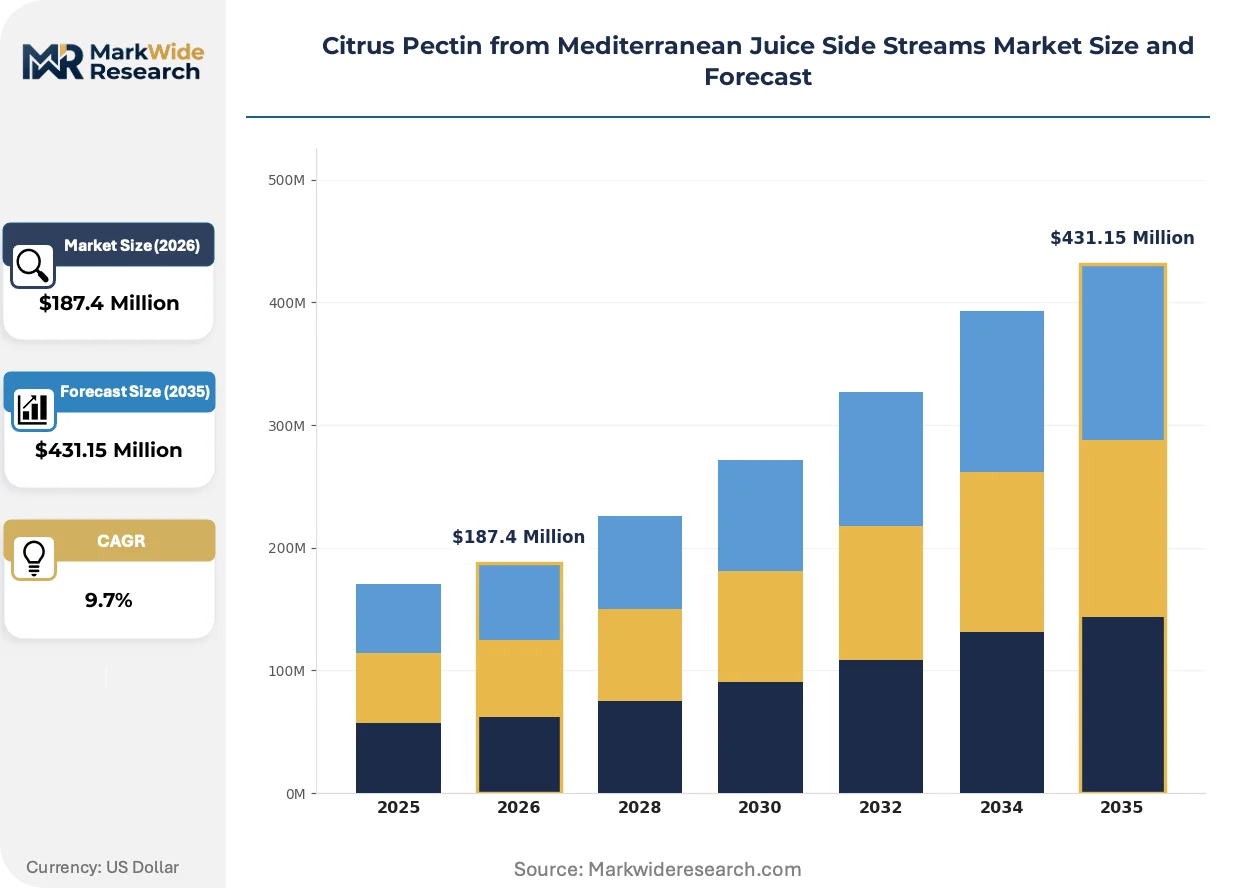
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HM Pectin, LM Pectin, Amidated Pectin, Citrus Peel Pectin, Apple Pectin Application: Food & Beverage, Pharmaceuticals, Cosmetics, Animal Feed, Packaging Extraction Technology: Water Extraction, Acid Extraction, Enzymatic Extraction, Microwave-Assisted, Ultrasound-Assisted End User Industry: Confectionery Manufacturers, Nutraceutical Firms, Personal Care Producers, Feed Manufacturers, Bioplastics Developers |
| Companies Covered | Cargill, Herbstreith & Fox, Silvateam, CEAMSA (Compañía Española de Algas Marinas), IFF, CP Kelco, Ingredion, Tate & Lyle, DSM-Firmenich, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Citrus Pectin from Mediterranean Juice Side Streams Market Trends and Innovations
Extraction technology and procurement specifications are diverging sharply, with enzymatic methods displacing acid hydrolysis in premium segments while regulatory pressure on waste streams accelerates circular economy integration.
Enzymatic extraction technology uses pectinase and cellulase cocktails to release galacturonic acid polymers from flavedo and albedo tissues without thermal degradation. Nutraceutical firms and personal care producers are adopting this method fastest, demanding solvent-free certification for clean-label positioning. This shift is integrating high-purity pectin into pharmaceutical-grade supply chains while compressing margins for conventional acid-based processors.
EU F-Gas Regulation amendments are tightening controls on hydrofluorocarbon refrigerants used in citrus cold storage, raising operational costs for Spanish and Italian juice processors. Industrial consequence includes accelerated investment in passive cooling and modified atmosphere storage to maintain peel quality. Mediterranean extraction facilities are responding by co-lating processing plants with juice concentration sites to minimize refrigerated transport.
Direct contracting between nutraceutical formulators and citrus processors is displacing spot-market purchasing for LM and amidated grades. Large encapsulation houses in Germany and France are establishing multi-year offtake agreements with Valencia-based extractors, bypassing traditional ingredient distributors. This pattern concentrates procurement leverage among buyers with volume scale and certification depth.
Citrus Pectin from Mediterranean Juice Side Streams Market Segmentation
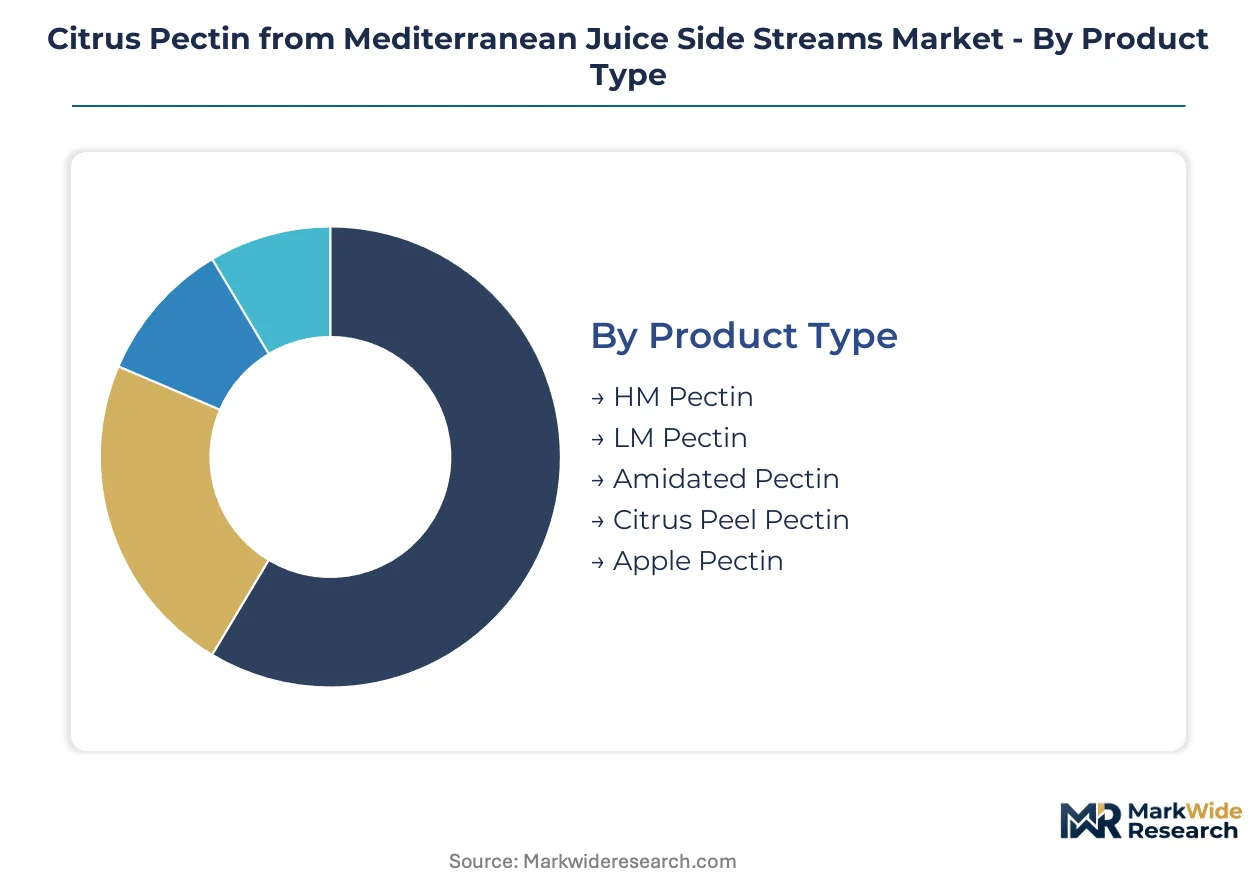
Citrus pectin procurement splits sharply between commodity-grade volumes for conventional food applications and certified grades commanding pharmaceutical premiums. Extraction technology choices and end-user certification requirements further stratify supplier positioning across Mediterranean supply corridors.
Product Type:
Volume concentration favors standardized HM grades, while premium capture concentrates in specialized low-methoxyl and amidated variants.
- HM Pectin:High-methoxyl pectin requires sugar-acid gelation conditions above pH 3.0 and soluble solids exceeding 55%, making it the workhorse for conventional jams and confectionery. Spanish Valencia processors supply bulk volumes to European retail brands where rapid-set specifications dominate procurement tenders.
- LM Pectin:Low-methoxyl pectin enables calcium-reactive gelation without high sugar content, suiting clean-label reformulations. German and French nutraceutical encapsulation houses are specifying LM grades for probiotic matrix applications, driving fastest-expanding demand within the category.
- Amidated Pectin:Modified LM variant with improved calcium sensitivity and thermal stability for pharmaceutical controlled-release matrices.
- Citrus Peel Pectin:Raw extract requiring further purification; primarily feeds on-site upgrading rather than direct commercial sale.
- Apple Pectin:Structurally distinct galacturonic acid profile from pomace sources; competes indirectly on price in standard food gelling.
Mature deployment sits with HM Pectin across retail food channels. Newer deployment is concentrated in Amidated Pectin for drug delivery contracts.
Application:
End-use diversification runs from mass-market food systems through high-margin pharmaceutical matrices to emerging bioplastics feedstock.
- Food & Beverage:Jam, confectionery, and dairy stabilization account for baseline volume demand. Italian and Spanish processors anchor supply contracts with pan-European retail brands where EFSA compliance and kosher certification filter supplier eligibility.
- Pharmaceuticals:Excipient-grade pectin functions in tablet binding, controlled-release coatings, and colon-targeted drug delivery. CE marking requirements and 18–24 month validation cycles restrict supplier pools to established European extractors with documented pharmaceutical-grade histories.
- Cosmetics:Emulsion stabilization and film-forming properties in personal care formulations.
- Animal Feed:Prebiotic fiber applications in poultry and swine nutrition.
- Packaging:Emerging biodegradable film applications from pectin-alginate blends.
Revenue depth clusters in Pharmaceuticals. Volume scale remains anchored in Food & Beverage.
Extraction Technology:
Process selection determines certification tier, thermal degradation profile, and wastewater discharge compliance under REACH standards.
- Acid Extraction:Conventional hydrolysis at pH 1.5–3.0 using citric or nitric acid inputs dominates installed capacity. Valencia and Murcia facilities rely on acid routes for HM pectin bulk production, though citric acid price volatility tied to Brazilian ethanol markets compresses margin stability.
- Enzymatic Extraction:Pectinase and cellulase cocktails release polymers without thermal degradation, yielding solvent-free certification. Nutraceutical and personal care producers are mandating enzymatic provenance for clean-label positioning, with EU bioeconomy funding subsidizing capex conversion for qualifying Spanish processors.
- Water Extraction:Limited commercial deployment due to low yield and extended processing times.
- Microwave-Assisted:Accelerated thermal extraction with reduced solvent volumes; pilot-scale in Italian research corridors.
- Ultrasound-Assisted:Cavitation-enhanced cell wall disruption; energy-intensive at commercial scale.
Installed base concentrates in Acid Extraction. Fastest capacity expansion targets Enzymatic Extraction.
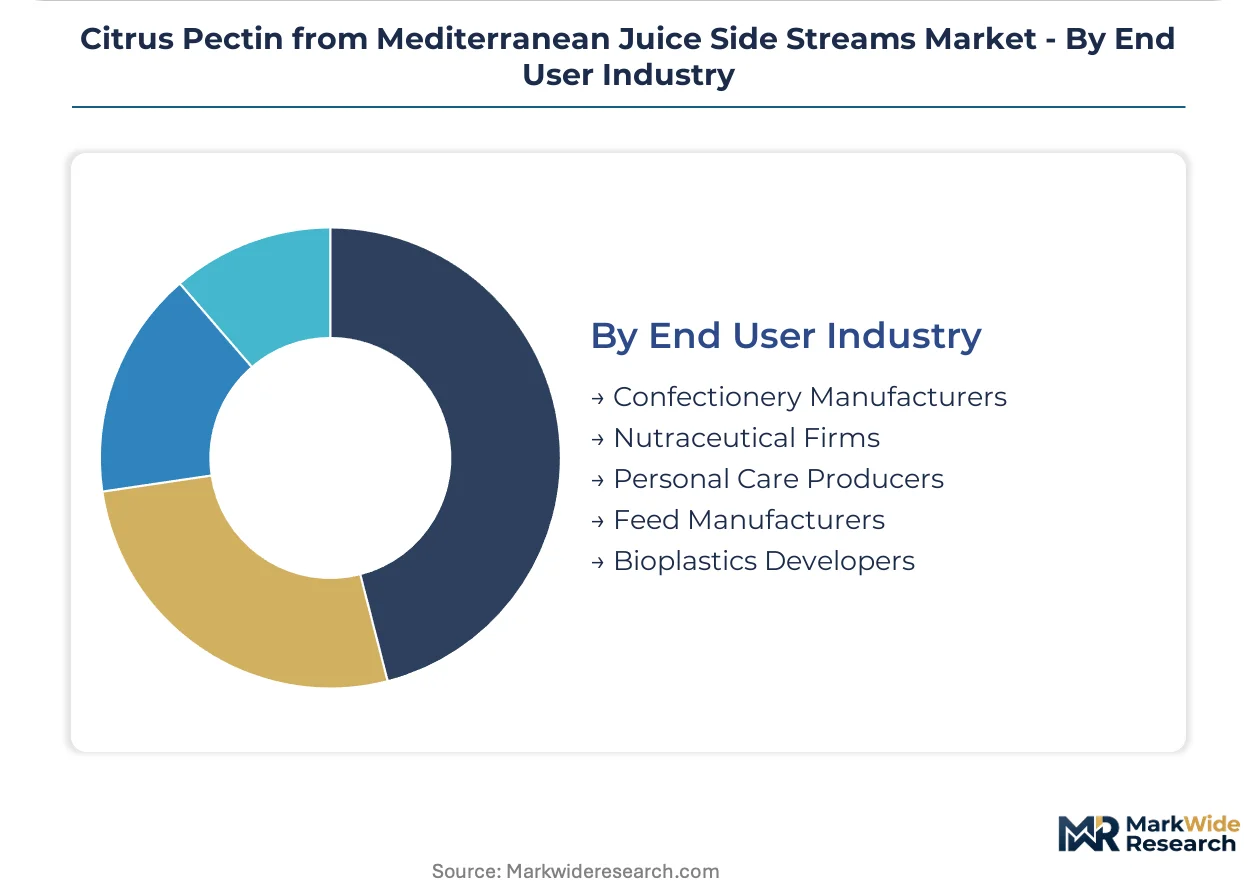
End User Industry:
Customer type dictates specification stringency, contract duration, and supplier qualification depth.
- Nutraceutical Firms:Probiotic encapsulation and controlled-release supplement matrices demand LM and amidated grades with batch-level traceability. Direct multi-year offtake agreements between German encapsulation houses and Valencia extractors are displacing traditional ingredient distribution channels.
- Confectionery Manufacturers:Jam and jelly producers specify HM pectin on rapid-set and slow-set gradations. Price-sensitive procurement through spot markets and annual tenders characterizes this segment, with Italian and Spanish suppliers competing on volume scale.
- Personal Care Producers:Cosmetic emulsion and film-forming applications.
- Feed Manufacturers:Prebiotic fiber specifications for livestock nutrition.
- Bioplastics Developers:Experimental pectin-alginate blends for edible and biodegradable packaging films.
Contract maturity sits with Confectionery Manufacturers. Specification intensity is climbing fastest among Nutraceutical Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Valencia anchors Mediterranean citrus pectin extraction through its dense concentration of orange processing corridors and integrated juice concentration facilities. Spanish peel valorization infrastructure generates the densest raw material availability in Europe. Italian lemon processing clusters in Sicily and Calabria supply specialized amidated grades for pharmaceutical contracts.
Spain
Murcia and Valencia processing corridors generate Europe's densest orange peel supply for HM pectin bulk production. EU Green Deal circular economy directives pressure processors to valorize side streams rather than landfill them. Cargill leverages its integrated citrus processing footprint across Brazilian and Spanish zones to secure raw material continuity for regional extractors.
Italy
Sicilian lemon peel concentration supports specialized amidated pectin output for pharmaceutical controlled-release matrices. EFSA novel food rulings and CE marking requirements govern market access for excipient-grade certification. Silvateam dominates the Italian lemon peel supply corridor, creating single-source vulnerability for buyers seeking amidated grades.
Portugal
Alentejo orange groves remain underexploited for pectin extraction despite expanding citrus cultivation. National bioeconomy funding reallocations subsidize enzymatic extraction capital expenditure for qualifying processors. Portuguese extraction capacity offers greenfield expansion opportunities as Spanish corridors reach saturation.
Germany
German nutraceutical encapsulation houses drive steepest demand trajectory for LM pectin in probiotic matrix applications. REACH chemical safety standards and ECHA compliance requirements accelerate solvent-free enzymatic extraction adoption across supplier networks. Direct multi-year offtake agreements between German formulators and Valencia extractors displace traditional ingredient distribution channels.
France
French personal care producers specify enzymatic-extraction pectin for cosmetic emulsion and film-forming applications. EFSA novel food rulings extend safety assessment timelines for new extraction variants targeting food applications. Paris-based formulators establish procurement leverage through volume scale and certification depth in clean-label positioning.
Citrus Pectin from Mediterranean Juice Side Streams Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a supply base splitting between premium-grade LM and amidated pectin for pharmaceutical contracts and commodity HM pectin for standard food applications. Three archetypes dominate: integrated agribusiness conglomerates with captive citrus processing, specialized European extractors with decades of pharmaceutical-grade certification, and regional peel processors leveraging geographic raw material concentration. Competitive moves concentrate on backward integration into juice processing assets and technology licensing for enzymatic extraction protocols.
Within the specialized extractor tier, Herbstreith & Fox anchors its position through extraction know-how and European pharmaceutical-grade certification history. Cargill exemplifies the integrated agribusiness archetype, leveraging its Brazilian and Spanish citrus processing footprint for raw material continuity. Silvateam occupies a position within the regional concentration archetype, dominating Italian lemon peel supply corridors and extending output into high-margin amidated grades.
| Leading Market Players |
|---|
| Cargill |
| Herbstreith & Fox |
| Silvateam |
| CEAMSA (Compañía Española de Algas Marinas) |
| IFF |
| CP Kelco |
| Ingredion |
| Tate & Lyle |
| DSM-Firmenich |
| Others |
Pricing and Supply Chain Analysis
Citric acid input costs cascade through three pricing tiers, with Brazilian sugarcane ethanol diversion compressing margins for acid-based processors in Valencia while enzymatic extractors capture pharmaceutical premiums. REACH compliance investments and EU F-Gas refrigeration costs further stratify pricing power between commodity HM and certified LM grades.
Pricing Analysis
Pharmaceutical-grade certification anchors value-based pricing, with CE-marked LM and amidated pectin commanding substantial premiums over commodity HM grades. Price differentiation rests on extraction technology provenance and EFSA novel food clearance status, with enzymatic methods justifying solvent-free certification premiums. Pricing pressure stems from citric acid volatility tied to Brazilian biofuel policy, eroding acid-extraction margins. Confectionery manufacturers exhibit highest price sensitivity through spot-market tenders, while German nutraceutical encapsulation houses accept long-term contract premiums for batch-level traceability.
Supply Chain Analysis
Spanish orange peel concentration draws from Valencia and Murcia processing corridors, with Sicilian lemon peel feeding specialized amidated production. Raw material dependencies center on citrus flavedo and albedo tissues, pectinase enzyme cocktails, and calcium chloride for LM gelation. Single-source vulnerability runs through Silvateam's dominance of Italian lemon peel corridors. Distribution runs through direct multi-year offtake agreements between Valencia extractors and German formulators, displacing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peel supply scarcity propped by EU Green Deal landfill bans concentrates procurement leverage among processors with captive citrus assets. Acid-extraction margin compression is accelerating technology migration timelines.
For Market Incumbents: Anchor pharmaceutical-grade certification depth against enzymatic extraction entrants by extending CE-marked capacity in Valencia. Defend against Silvateam's amidated concentration by securing Portuguese Alentejo peel supply through backward integration into juice processing assets. Prioritize enzymatic protocol licensing to capture nutraceutical clean-label premiums. For New Entrants and Emerging Players: The gap between pharmaceutical-grade LM premiums and commodity HM spot pricing offers entry space for mid-tier enzymatic processors. Portuguese Alentejo corridors present the most penetrable geography, with national bioeconomy funding subsidizing capex conversion. Target direct contracting with French personal care producers seeking solvent-free certification as the primary go-to-market angle. For Investors and Strategic Acquirers: German nutraceutical offtake agreement announcements are the leading indicator that Valencia extraction capacity is tightening. The five-to-ten year viability window favors processors with integrated peel supply and enzymatic technology depth. Acquisition targets should display REACH-compliant wastewater infrastructure and documented pharmaceutical-grade batch histories. Watch EU F-Gas amendment implementation timelines as the critical inflection signal for refrigerated storage cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Juice Processing | Cargill's Brazilian-Spanish citrus footprint secures raw material continuity for regional extractors. |
| Enzymatic Extraction Capacity Buildout | EU bioeconomy funding subsidizes solvent-free certification capex for qualifying Spanish processors. |
| Pharmaceutical-Grade Certification Investment | Herbstreith & Fox leverages decades of European CE-marking history to restrict excipient supplier pools. |
| Long-term Supply Agreement with Nutraceutical Formulators | German encapsulation houses bypass distributors through direct Valencia offtake contracts. |
| Geographic Expansion to Portuguese Peel Corridors | Alentejo orange groves offer greenfield capacity as Spanish processing zones approach saturation. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with extraction plant managers, nutraceutical procurement leads, enzyme supplier technical directors, and ECHA compliance officers. Bottom-up triangulation cross-referenced Spanish and Italian peel volume estimates against top-down pharmaceutical excipient demand modeling. EFSA novel food rulings, REACH discharge permits, and EU F-Gas implementation timelines provided regulatory boundary conditions.
Segment-level granularity modeled extraction technology choice, pectin grade tier, and end-user industry certification requirements across the projection horizon. CAGRs derived from peel supply elasticity, nutraceutical encapsulation growth trajectories, and enzymatic capacity expansion schedules. Industry-specific inputs included Brazilian ethanol diversion impacts on citric acid pricing and German probiotic supplement formulation trends.
Underlying measurement precision varies by segment; pharmaceutical-grade volumes carry tighter precision than commodity HM estimates due to CE-marking documentation density. Forecasts reflect assumptions on EU bioeconomy funding continuity and enzymatic enzyme cost curves. Regulatory amendment timelines, Brazilian sugarcane harvest variability, and pharmaceutical excipient validation cycle durations warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Lutein and Zeaxanthin Market
Food Components and Additives
Food-Grade Monopotassium Phosphate Market
Food Components and Additives
Blackcurrant Powder Market
Food Components and Additives
Food Antioxidant Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Food Grade Titanium Dioxide Market
Food Components and Additives
Europe Food Hydrocolloids Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
South America Food Hydrocolloids Market
Food Components and Additives
Fructo-Oligosaccharides (FOS) Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
USA Food Premix Market
Food Components and Additives
Titanium-Free Food Color Market
Food Components and Additives
Food Grade Polyvinyl Acetate Market
Food Components and Additives
Food Grade Silica Market
Food Components and Additives
China Food Hydrocolloids Market