
 Mexico Food Hydrocolloids Market | 2026-2036
Mexico Food Hydrocolloids Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Food Hydrocolloids Market Foresight
NOM-051 nutritional labeling reform is restructuring procurement priorities across Mexican processed food sectors. Cargill Incorporated leverages its Guadalajara distribution infrastructure to supply modified starches and hydrocolloid systems for reformulated sauces and dressings. CP Kelco U.S., Inc. competes through specialized xanthan gum production tailored to Mexican beverage stabilization requirements. Ingredion Incorporated anchors its position with plant-based hydrocolloid portfolios aligned to clean-label dairy alternatives in the Bajío region.
Food hydrocolloids encompass high-molecular-weight polysaccharides and proteins that hydrate in aqueous systems to modify viscosity, gelation, and water-binding properties, typically functioning at concentrations between 0.1% and 2.0% by weight. These colloidal substances stabilize emulsions, control syneresis, and impart texture across processed food matrices. Gelatin maintains mature volume leadership in dairy applications where its melt-in-mouth profile and protein functionality resist substitution. Xanthan gum captures accelerated growth in beverages and sauces where pseudoplastic flow behavior delivers shelf stability under variable shear conditions. Plant-based sourcing expands fastest as Mexican food manufacturers reformulate to meet vegetarian labeling claims and allergen management protocols.
COFEPRIS enforces food additive safety evaluations under NOM-120 while SAGARPA regulates agricultural raw material traceability for hydrocolloid feedstocks. BIS-equivalent conformity assessment through Mexico's national standards body ensures imported hydrocolloids meet local purity specifications. SEDEMA Mexico City imposes additional environmental compliance on manufacturing facilities in the capital region. Stakeholders must monitor pending amendments to NOM-051's front-of-pack warning system, as stricter sugar and calorie thresholds will accelerate reformulation cycles across beverage and dairy categories.
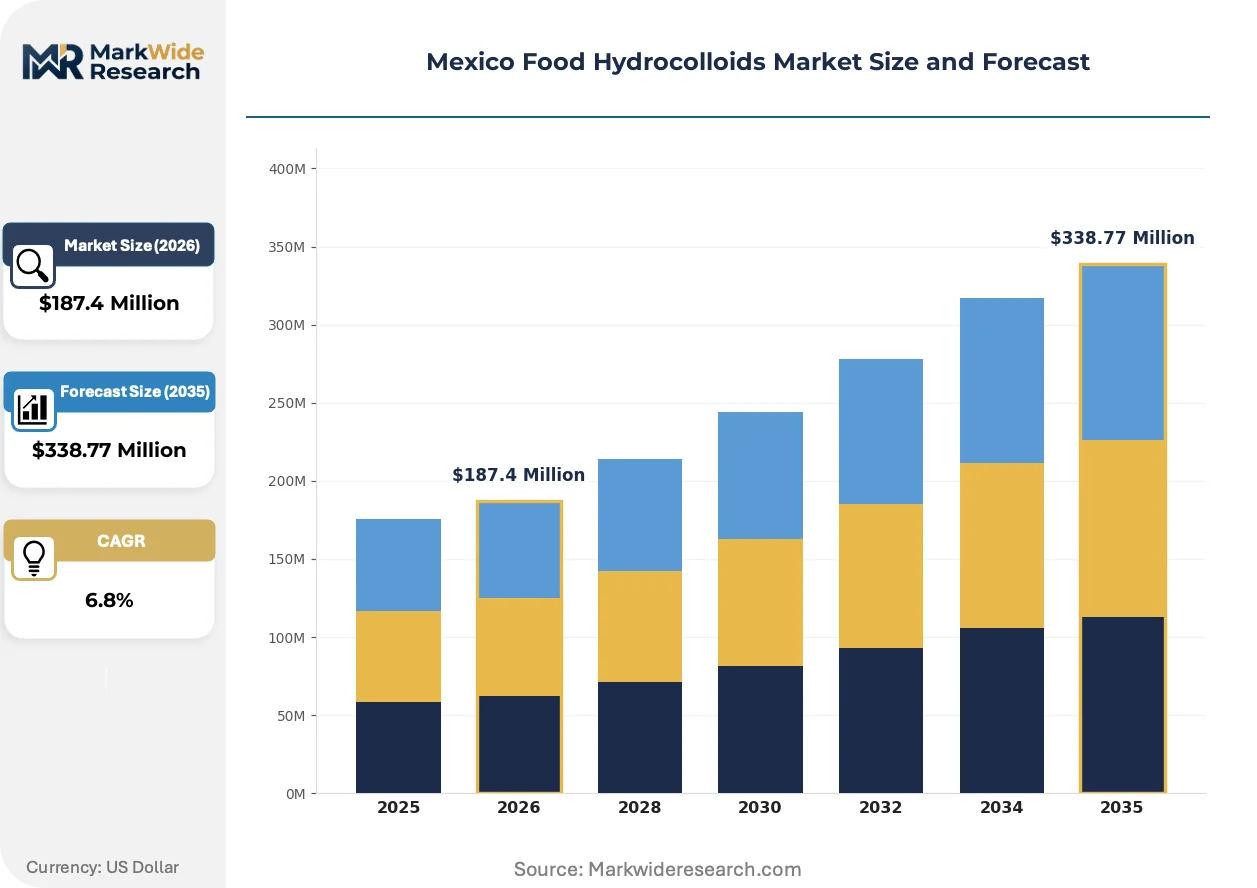
Market Dynamics
NOM-051's front-of-pack warning system is compressing reformulation timelines across Mexican processed food manufacturing, forcing hydrocolloid suppliers to accelerate clean-label solution development for sugar-reduced and calorie-modified products.
Growth Catalysts
- Clean-label reformulation mandates:NOM-051's updated disclosure requirements push bakery and dairy manufacturers toward plant-based hydrocolloid systems that eliminate artificial additives while maintaining texture functionality.
- Beverage stabilization demand:Pseudoplastic flow properties from xanthan gum address shelf stability challenges in acidified drinks and ready-to-drink coffee formulations popular in Jalisco's processing corridor.
- Jalisco and Nuevo León cluster expansion:Concentrated food manufacturing in these states creates localized procurement volumes that justify dedicated hydrocolloid distribution infrastructure and technical service investment.
Market Restraints
- Raw material traceability costs:SAGARPA's agricultural feedstock documentation requirements add compliance overhead to guar gum and tara gum imports from South American suppliers.
- Gelatin substitution limitations:Animal-derived hydrocolloids face vegetarian labeling claim exclusions that restrict their use in plant-forward product lines targeting Mexico's growing flexitarian consumer base.
- COFEPRIS additive evaluation timelines:Novel hydrocolloid approvals under NOM-120 safety protocols extend commercialization cycles by months, delaying ingredient innovation adoption.
Strategic Opportunities
- Bajío region dairy alternatives:Plant-based milk and yogurt formulations in Guanajuato and Querétaro present unserved demand for oat and pea protein-compatible hydrocolloid stabilizers.
- SEDEMA environmental compliance services:Mexico City manufacturing facilities require wastewater and emissions management partnerships that hydrocolloid suppliers can bundle with technical support.
- Direct-to-manufacturer digital channels:E-procurement platforms connecting Jalisco sauce producers with specialty ingredient distributors bypass traditional broker markups and accelerate sample-to-commercial conversion.
Industry Challenges
- Food technologist specialization gaps:Formulation expertise combining hydrocolloid synergy mapping with NOM-051 compliance is scarce in Monterrey's technical workforce, slowing customer support scaling.
- Legacy ERP integration friction:Small and mid-sized Guadalajara bakeries operate on outdated inventory systems that resist real-time lot tracking required for SAGARPA traceability mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Food Hydrocolloids Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gelatin, Pectin, Xanthan Gum, Agar Application: Dairy Products, Bakery Products, Beverages, Sauces Source: Plant-based, Animal-based, Synthetic, Others End User: Food Manufacturers, Retailers, Food Service, Home Cooks |
| Companies Covered | Cargill Incorporated, The Archer Daniels Midland Company, Gelita AG, Norevo GmbH, Silvateam S.p.A, Lonza Group Ltd, Gelnex Industria e Comercio Ltda, CP Kelco U.S., Inc., Ingredion Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Food Hydrocolloids Market Shifts & Advancements
Reformulation automation and regulatory compliance digitization are converging to reshape how Mexican food manufacturers select and source hydrocolloid ingredients. Three developments dominate this transformation.
Enzymatic modification of starches is automating viscosity control in high-shear processing environments. Sauce manufacturers in Nuevo León adopt these precision-tuned hydrocolloids to reduce batch-to-batch variation. The technology is automating quality assurance labor previously dedicated to manual viscosity testing and adjustment protocols.
NOM-051's front-of-pack warning thresholds are tightening sugar and calorie disclosure triggers. Processed food producers accelerate reformulation cycles to avoid mandatory warning labels on retail packaging. Beverage categories face the most immediate pressure, driving xanthan gum and stevia-hydrocolloid hybrid system adoption for mouthfeel restoration in reduced-sugar formulations.
Consolidated procurement by Jalisco and Monterrey co-manufacturers is displacing fragmented ingredient purchasing. Large processing clusters negotiate direct supply agreements with hydrocolloid distributors, extracting volume discounts and technical service commitments previously unavailable to smaller buyers. This concentration is most visible in the ready-to-eat meal segment, where contract manufacturers centralize stabilizer sourcing across multiple brand clients.
Mexico Food Hydrocolloids Market Segmentation
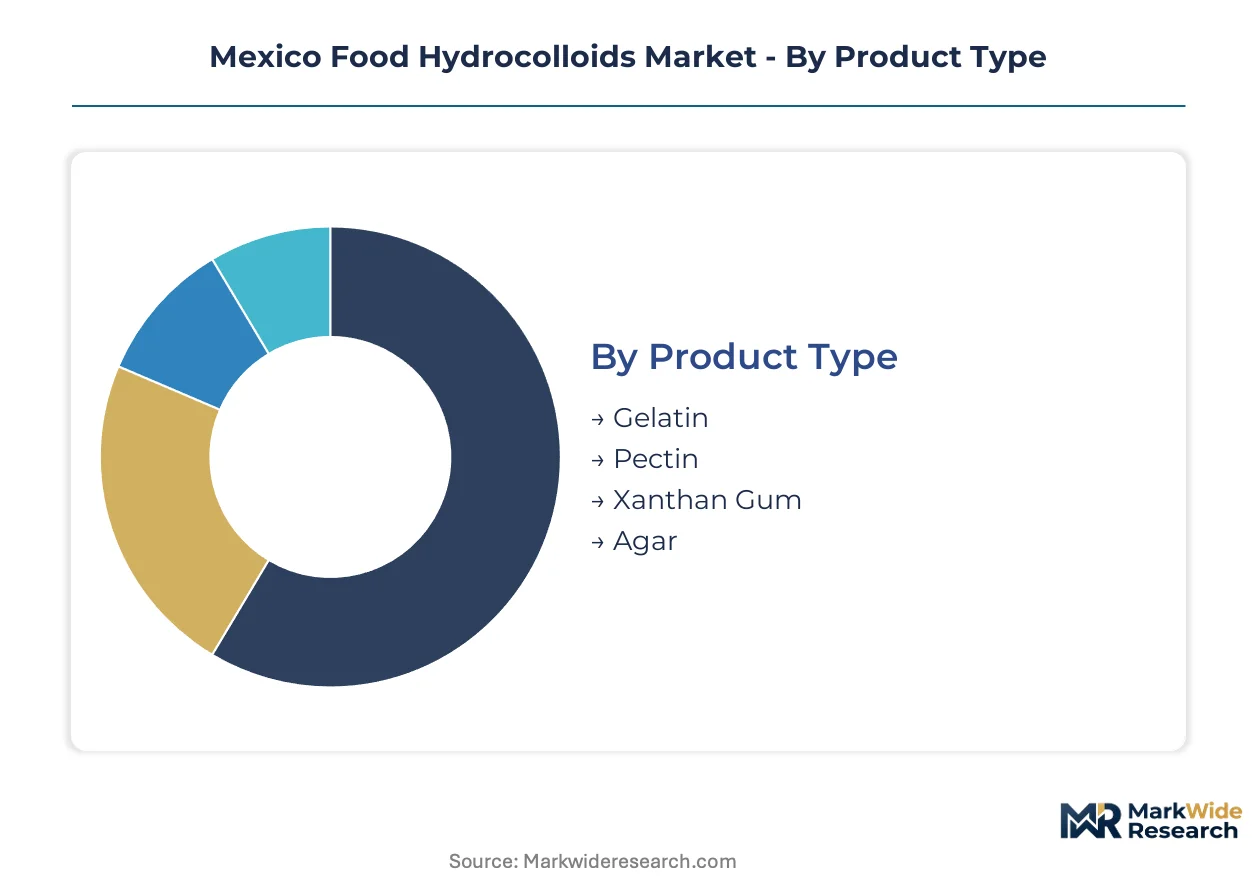
Hydrocolloid selection in Mexico hinges on functional performance requirements, regulatory compliance pathways, and sourcing economics that vary sharply across application matrices. Segmentation reveals where formulation expertise concentrates and where procurement arbitrage opportunities exist.
Product Type:
Viscosity modification mechanisms and gelation thermoreversibility separate these hydrocolloid chemistries into distinct procurement tiers.
- Gelatin:Collagen-derived protein hydrocolloid forms thermoreversible gels with melt-in-mouth characteristics. Dairy processors in Jalisco deploy gelatin for yogurt texture and dessert stabilization where its protein functionality resists plant-based substitution. COFEPRIS NOM-120 clearance for bovine and porcine sourcing variants adds traceability overhead.
- Xanthan Gum:Microbial polysaccharide produced via Xanthomonas campestris fermentation delivers pseudoplastic flow behavior critical for acidified beverage shelf stability. Jalisco's ready-to-drink coffee and juice manufacturers source xanthan for shear-thinning properties under variable processing conditions.
- Pectin:Citrus and apple-derived galacturonic acid polymer requiring controlled calcium reactivity for gel set.
- Agar:Red seaweed extract with high gel strength and syneresis resistance in neutral pH systems.
Mature deployment sits with gelatin. Newer deployment is concentrated in xanthan gum.
Application:
Processing shear rates and pH exposure windows dictate hydrocolloid compatibility across these food matrices.
- Dairy Products:Gelatin and carrageenan systems dominate yogurt, fresh cheese, and dessert applications where protein-hydrocolloid interactions control syneresis. Nuevo León's dairy cluster demands Kosher and Halal-certified variants for export-oriented production.
- Beverages:Xanthan gum and modified starches stabilize pulp suspension and mouthfeel in reduced-sugar formulations avoiding NOM-051 front-of-pack warnings. Acidified drinks in Jalisco's processing corridor require hydrocolloids with pH stability below 4.0.
- Bakery Products:Hydrocolloid moisture retention extends shelf life in Guadalajara's industrial bread production.
- Sauces:Viscosity control and emulsion stability in hot-fill processing environments.
Volume concentration centers on dairy. Reformulation pressure is accelerating fastest in beverages.
Source:
Raw material provenance determines regulatory pathway complexity and clean-label positioning eligibility.
- Plant-based:Pectin, agar, and modified starches from agricultural feedstocks align with vegetarian labeling claims and NOM-051 clean-label positioning. SAGARPA traceability mandates apply to guar and tara gum imports from South American suppliers.
- Animal-based:Gelatin and hydrolyzed collagen face flexitarian consumer exclusion in plant-forward product lines targeting Mexico City's metropolitan market.
- Synthetic:Chemically modified cellulose derivatives with standardized functional specifications.
- Others:Fermentation-derived and novel extraction hydrocolloids pending COFEPRIS evaluation.
Plant-based sourcing commands premium positioning. Synthetic variants retain cost-driven volume in commodity applications.
End User:
Technical sophistication and procurement scale separate these customer tiers into distinct service models.
- Food Manufacturers:Jalisco and Nuevo León processing clusters negotiate direct supply agreements with technical service commitments. Large co-manufacturers consolidate procurement across multiple brand clients, extracting volume discounts unavailable to smaller buyers.
- Food Service:Institutional kitchens and chain restaurants require pre-hydrated hydrocolloid systems reducing on-site formulation labor.
- Retailers:Private-label product development teams sourcing stabilizers through distributor networks.
- Home Cooks:Small-format specialty hydrocolloids distributed through gourmet retail channels.
Food manufacturers anchor procurement volume. Food service represents the steepest expansion trajectory for technical support bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guadalajara anchors Mexico's food hydrocolloid procurement networks through its concentration of processed food manufacturing and reformulation expertise.
Nuevo León
Monterrey's dairy and beverage clusters drive demand for xanthan gum and modified starch systems in reduced-sugar formulations. COFEPRIS enforces NOM-120 additive safety protocols for novel hydrocolloid approvals. Large co-manufacturers in Apodaca consolidate procurement across multiple brand clients, extracting technical service commitments from distributors.
Jalisco
Acidified beverage producers in Zapopan require hydrocolloids with pH stability below 4.0 for shelf-stable juice and ready-to-drink coffee applications. NOM-051's front-of-pack warning system compresses reformulation timelines for sugar-reduced products. The Guadalajara processing corridor hosts dedicated distribution infrastructure from major suppliers serving bakery and sauce manufacturers.
Bajío Region
Plant-based dairy alternatives in Guanajuato and Querétaro present unserved demand for oat and pea protein-compatible stabilizers. SAGARPA regulates agricultural feedstock traceability for hydrocolloid raw materials. Food technologists in León develop clean-label formulations aligning with vegetarian labeling claims targeting flexitarian consumers.
Mexico City Metro
SEDEMA imposes environmental compliance requirements on manufacturing facilities regarding wastewater and emissions management. The metropolitan market's plant-forward consumer base excludes animal-derived hydrocolloids from premium product lines. Reformulation labs in Tlalnepantla specialize in NOM-051 compliance for front-of-pack warning avoidance.
Northern Border States
Export-oriented processors in Tijuana and Ciudad Juárez demand Kosher and Halal-certified hydrocolloid variants for cross-border supply chains. BIS-equivalent conformity assessment through Mexico's national standards body ensures imported ingredients meet local purity specifications. Maquiladora food operations source hydrocolloids through integrated North American distribution networks.
Mexico Food Hydrocolloids Market Competitive Landscape
The competitive structure tilts toward multinational ingredient suppliers with established Mexican distribution infrastructure. Three to five global players control premium hydrocolloid segments through direct technical service relationships with Jalisco and Nuevo León processors. Strategic archetypes include integrated agricultural processors, specialized fermentation-derived hydrocolloid producers, and regional distributors bundling compliance services. Capacity expansion and portfolio diversification toward plant-based sourcing dominate competitive moves as clean-label mandates intensify.
Within the multinational supplier tier, Cargill Incorporated and Ingredion Incorporated anchor procurement relationships with large-scale food manufacturers. CP Kelco U.S., Inc. occupies a specialized position in microbial polysaccharide production. These entities exemplify the scale-driven archetype competing through Guadalajara and Monterrey distribution infrastructure rather than direct manufacturing presence.
| Leading Market Players |
|---|
| Cargill Incorporated |
| The Archer Daniels Midland Company |
| Gelita AG |
| Norevo GmbH |
| Silvateam S.p.A |
| Lonza Group Ltd |
| Gelnex Industria e Comercio Ltda |
| CP Kelco U.S., Inc. |
| Ingredion Incorporated |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between COFEPRIS NOM-120 compliant suppliers and uncertified commodity traders manifests in both pricing premiums and distribution infrastructure investments. Jalisco beverage manufacturers pay yield-based premiums for xanthan gum with documented Xanthomonas campestris strain traceability, while Guadalajara bakeries source modified starches through spot markets with minimal technical support.
Pricing Analysis
Yield-guarantee pricing anchors hydrocolloid procurement contracts, with Jalisco dairy processors paying performance-linked premiums for gelatin systems delivering consistent protein functionality across batch variations. Price differentiation separates NOM-051 compliant clean-label grades from commodity alternatives, with SAGARPA-certified traceability adding documentation costs. Pricing pressure stems from South American guar gum import volatility, squeezing margins in sauce applications. Small-scale Monterrey co-manufacturers exhibit highest price sensitivity, while export-oriented Nuevo León dairy clusters prioritize certification over unit cost.
Supply Chain Analysis
Regional distribution centers in Guadalajara and Monterrey operate hub-and-spoke patterns serving Jalisco and Nuevo León processing clusters with 48-hour replenishment cycles. Geographic supply concentration draws from Argentina and Peru for tara gum, China for xanthan gum fermentation feedstocks, and Brazil for guar gum splits. Raw material dependencies include citrus peel for pectin, red seaweed for agar, and corn starch for enzymatic modification. Single-source vulnerability runs through Xanthomonas campestris culture banks controlled by limited fermentation specialists. Distribution runs through authorized distributor networks with COFEPRIS import clearance capabilities rather than direct mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
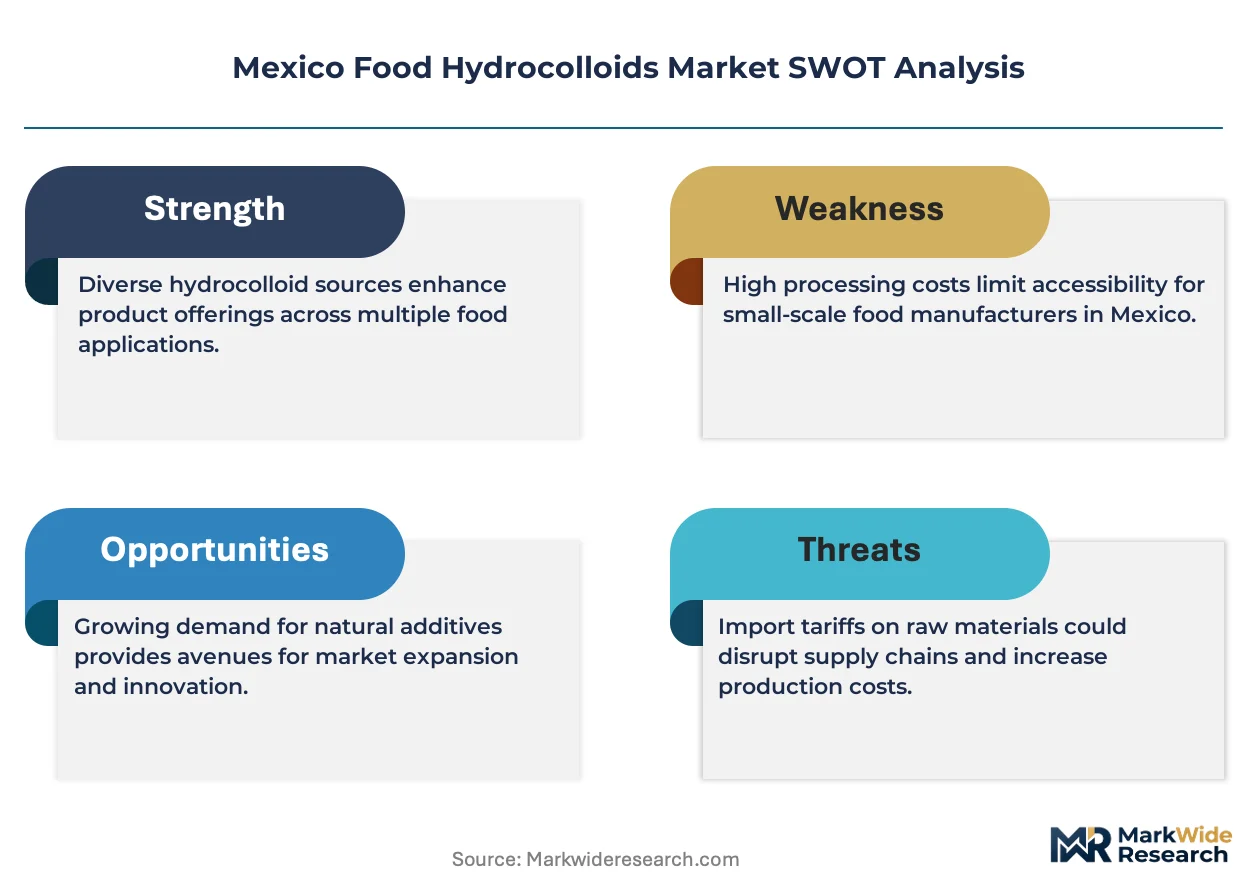
NOM-051's front-of-pack warning system constructs a cost-of-compliance moat where COFEPRIS-registered suppliers capture reformulation contracts unavailable to unregistered traders, entrenching technical service capabilities as the decisive barrier.
For Market Incumbents: Deepen backward integration into South American guar and tara gum agricultural networks to neutralize SAGARPA traceability cost inflation threatening sauce segment margins. Expand NOM-051 technical service teams in Monterrey to defend against emerging regional distributors offering compliance digitization bundles. Capacity addition in Bajío region dairy alternatives anchors plant-based hydrocolloid portfolios before specialty ingredient entrants establish formulation partnerships. For New Entrants and Emerging Players: Capture unserved demand in Guanajuato oat milk stabilizers where incumbent technical coverage remains thin and flexitarian product launches accelerate. Penetrate SEDEMA environmental compliance service bundling for Mexico City manufacturing facilities facing wastewater management mandates. Go-to-market angle: pre-hydrated hydrocolloid systems reducing on-site formulation labor for food service chains with limited R&D infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with fermentation-derived hydrocolloid specialists given xanthan gum's accelerating beverage adoption and pseudoplastic performance moats. Long-term viability over the projection horizon favors producers with captive Xanthomonas campestris strain libraries and COFEPRIS regulatory navigation capabilities. Acquisition target archetype: regional Mexican distributors with NOM-051 compliance digitization platforms and established Jalisco customer relationships. Signal to watch: SAGARPA enforcement intensity on South American agricultural documentation as indicator of traceability cost inflation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Feedstocks | Captive guar and tara gum sourcing neutralizes SAGARPA documentation cost inflation for Jalisco sauce manufacturers. |
| NOM-051 Technical Service Expansion | Dedicated reformulation labs in Monterrey defend incumbent positions against compliance-digitization competitors. |
| Plant-Based Portfolio Diversification | Oat and pea protein-compatible stabilizers address unserved Bajío region dairy alternative demand. |
| Environmental Compliance Service Bundling | SEDEMA-aligned wastewater management partnerships differentiate offerings for Mexico City manufacturing facilities. |
| Fermentation Capacity Scale-Up | Expanded Xanthomonas campestris production secures xanthan gum supply for Jalisco acidified beverage growth. |
Research Methodology
Document review covered COFEPRIS additive registration databases, SAGARPA agricultural trade documentation, and NOM-051 regulatory filings, complemented by interviews with food technology directors at Jalisco beverage manufacturers, procurement leads at Nuevo León dairy processors, hydrocolloid distribution channel managers, and regulatory affairs specialists navigating NOM-120 clearance protocols. Secondary sources included Mexican customs import records, SEC 10-K disclosures from listed ingredient suppliers, and industry association technical bulletins. Bottom-up demand modeling from application-specific consumption rates triangulated against top-down market sizing from supplier shipment data.
Segmented projections across product type, application, source, and end user dimensions generated volume and value trajectories across the analysis window. CAGRs derived from regression analysis of historical consumption patterns adjusted for NOM-051 reformulation acceleration and clean-label substitution elasticities. Industry-specific inputs included xanthan gum penetration rates in reduced-sugar beverages and gelatin substitution dynamics in plant-forward dairy alternatives.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to COFEPRIS enforcement timelines for novel hydrocolloid approvals and SAGARPA documentation requirements for South American agricultural imports. Projections reflect assumptions regarding NOM-051 warning threshold implementation and flexitarian consumer adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Brazil Food Hydrocolloids Market
Food Components and Additives
China Food Hydrocolloids Market
Food Components and Additives
Edible Oil Co-Products and by-Products Market
Food Components and Additives
Russia Food Hydrocolloids Market
Food Components and Additives
Food Antimicrobial Coating Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
Food Grade Sodium Carbonate Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
US Food Hydrocolloids Market
Food Components and Additives
Japan Food Hydrocolloids Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
South Africa Food Hydrocolloids Market
Food Components and Additives
Asia Pacific Food Grade Carbon Dioxide Market
Food Components and Additives
Fillings and Toppings Market
Food Components and Additives
Food Grade Xanthan Gum Market
Food Components and Additives
Italy Food Hydrocolloids Market