
 Inulin and Fructooligosaccharide Market | 2026-2036
Inulin and Fructooligosaccharide Market Size, Share, and Industry Trends Forecast 2026-2036
Inulin and Fructooligosaccharide Market Foresight
The gap between pharmaceutical-grade inulin and commodity chicory fiber is recalibrating procurement strategies across the prebiotic supply chain. BENEO GmbH leverages its Belgian chicory root sourcing to sustain vertical integration from field to extract. Cosucra Groupe Warcoing SA anchors its position through specialized pea and chicory fiber co-production in Wallonia. Roquette Frères competes by extending its multi-plant European network for consistent oligofructose supply to food manufacturers.
Inulin and fructooligosaccharides are non-digestible carbohydrates composed primarily of fructose units linked by beta-2,1 glycosidic bonds, typically extracted from chicory root through hot water diffusion and refined via spray drying to achieve dietary fiber purity levels exceeding 90%. These ingredients function as soluble prebiotic fibers that selectively stimulate beneficial gut microbiota proliferation in human and animal digestive systems. The food and beverage application segment leads volume consumption due to widespread incorporation into dairy alternatives and baked goods, while dietary supplements represent the fastest-expanding margin pool as consumers shift toward gut health concentrates. Powder form dominates industrial handling and blending efficiency, though liquid oligofructose is gaining traction in beverage fortification where dissolution speed matters.
EFSA novel food evaluations and EU Regulation 1169/2011 on food information to consumers shape ingredient labeling requirements and health claim substantiation across European markets. The FDA GRAS notification pathway and FSSAI functional food guidelines in India govern market access for imported prebiotic ingredients, creating divergent compliance burdens for multinational suppliers. Stakeholders must monitor evolving gut health claim restrictions and emerging microbiome research standards that will determine which fiber structures qualify for premium positioning versus commodity classification.
Market Dynamics
The prebiotic ingredient supply chain is consolidating around chicory root processing clusters in Belgium and the Netherlands, where wet-milling infrastructure and EFSA novel food dossier expertise create moats for incumbent suppliers.
Growth Catalysts
- EFSA Novel Food Pathway:Streamlined approvals for chicory-derived fibers are accelerating new product introductions across EU member states.
- Dairy Alternatives Formulation:Oat and almond milk manufacturers are embedding oligofructose for mouthfeel replication and prebiotic claims.
- Hot Water Diffusion Refinement:Continuous extraction systems are improving dietary fiber purity yields above 90% at industrial scale.
Market Restraints
- Chicory Root Supply Concentration:Northern European weather volatility threatens raw material security for processors dependent on Belgian and Dutch agricultural output.
- FDA GRAS Notification Burden:U.S. market entry requires extensive safety substantiation that delays revenue recognition by 18-24 months.
- Synthetic Prebiotic Substitution:Galactooligosaccharide producers are capturing share in infant nutrition applications through lower cost-in-use.
Strategic Opportunities
- Indian Functional Food Expansion:FSSAI guidelines for prebiotic claims remain underdeveloped, creating first-mover positioning for dossier-ready suppliers.
- Pet Nutrition Application:Gut health positioning in premium pet food is absorbing spray-dried inulin at margin premiums exceeding human food grades.
- Precision Fermentation Convergence:Microbial FOS synthesis from sucrose substrates is emerging as a chicory-independent production pathway.
Industry Challenges
- Microbiome Research Standardization:Inconsistent clinical endpoints for gut health claims are forcing redundant efficacy studies across jurisdictions.
- Spray Drying Energy Intensity:Natural gas price volatility is compressing margins for powder form producers operating continuous drying lines.
- Clean-Label Formulation Complexity:Removal of masking agents in high-fiber applications is exposing off-taste profiles that require flavor system redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inulin and Fructooligosaccharide Market |
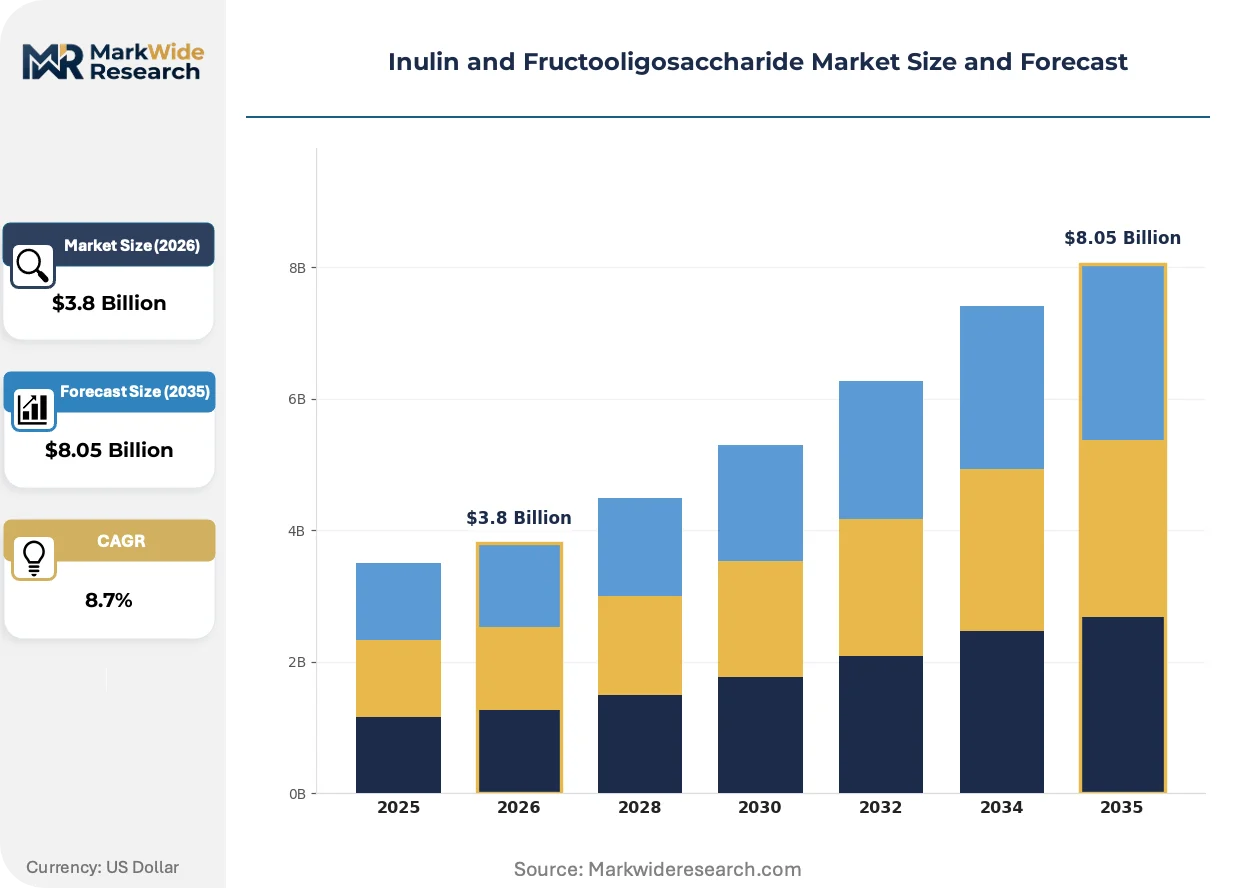
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
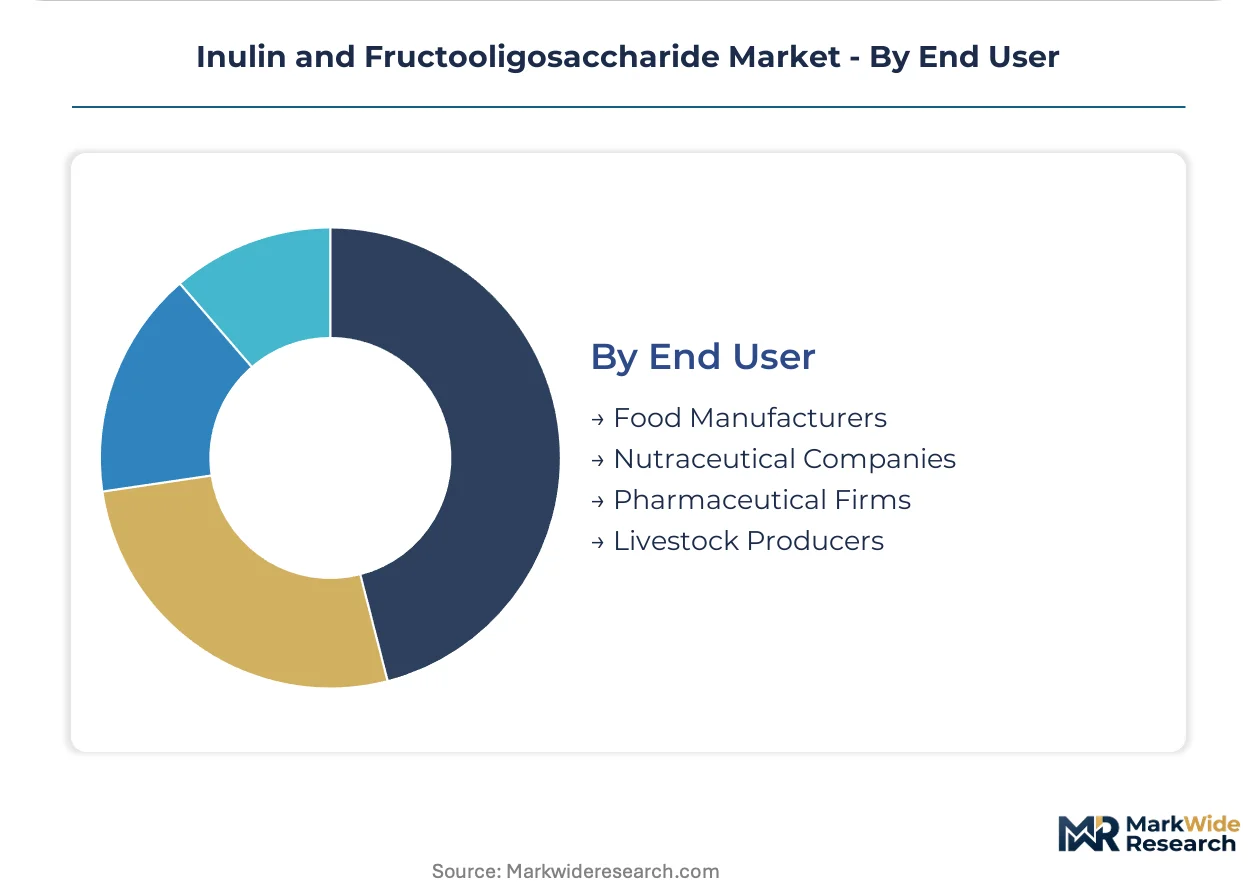
| Segmentation | Product Type: Inulin, Fructooligosaccharides, Chicory Root Fiber, Oligofructose Application: Food & Beverage, Dietary Supplements, Pharmaceuticals, Animal Feed Form: Powder, Liquid, Granulated, Capsules End User: Food Manufacturers, Nutraceutical Companies, Pharmaceutical Firms, Livestock Producers |
| Companies Covered | Cosucra Groupe Warcoing SA, Tate & Lyle PLC, BENEO GmbH, Roquette Frères, The Tierra Group, Cargill Incorporated, Sensus B.V., FrieslandCampina, Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inulin and Fructooligosaccharide Market Shifts & Advancements
Prebiotic ingredient competition is pivoting from fiber purity metrics to microbiome-targeted efficacy claims backed by strain-specific clinical data.
Enzymatic synthesis of short-chain fructooligosaccharides is electrifying the ingredient technology landscape. Biocatalyst immobilization systems now enable continuous FOS production from sucrose feedstocks at commercial scale. Beverage manufacturers in Germany and the Netherlands are adopting liquid oligofructose streams for rapid dissolution in fortified waters.
REACH registration requirements for novel extraction solvents are reshaping supplier qualification protocols for European compounders. The restriction of certain polar aprotic solvents is forcing retrofit investments in chicory processing facilities. Food-grade ethanol replacement programs are accelerating in Wallonia and Flanders processing clusters.
Direct procurement contracts between dairy alternative brands and chicory processors are collapsing traditional ingredient distributor tiers. Oat milk leaders in Scandinavia and plant-based yogurt startups in France are negotiating toll-manufacturing arrangements for customized fiber blends. This disintermediation is most pronounced in the Benelux corridor where extraction capacity sits adjacent to formulation R&D centers.
Inulin and Fructooligosaccharide Market Segmentation
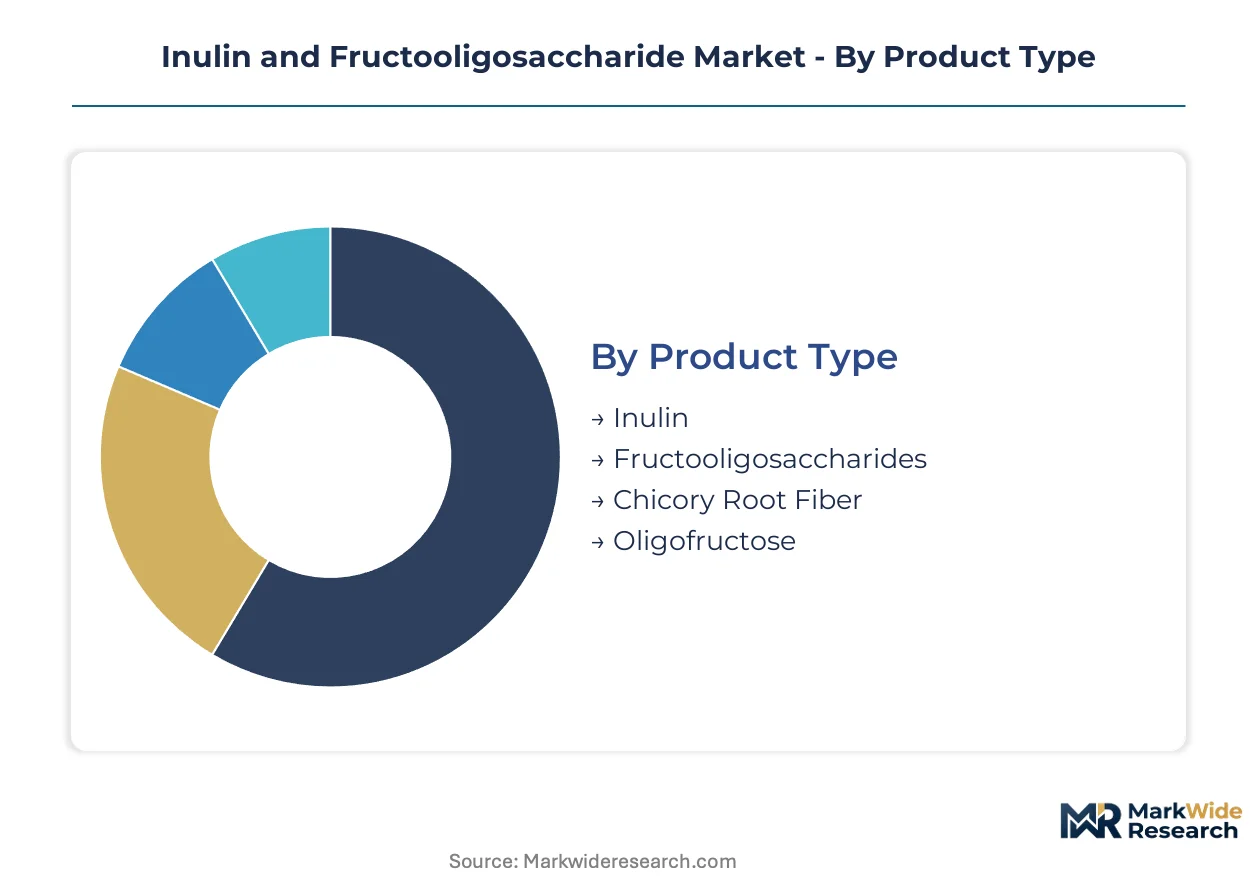
Prebiotic ingredient procurement strategies diverge sharply across buyer categories, with pharmaceutical purity requirements commanding fundamentally different supply chain relationships than commodity food-grade sourcing. Manufacturers segment their offerings around extraction methodology, particle specification, and microbiome-targeted efficacy claims rather than fiber content alone.
Product Type:
Buyers in this category differentiate by chain-length distribution and solubility profiles that determine functional performance in end formulations.
- Inulin:Long-chain beta-2,1 linked fructose polymers with degree of polymerization exceeding 10 units deliver sustained fermentation kinetics in the distal colon. Pharmaceutical firms in Germany specify high-purity grades exceeding 99% inulin for synbiotic formulations, while German dairy processors embed standard grades in yogurt matrices for texture modification.
- Fructooligosaccharides:Short-chain oligomers with DP 2-9 enable rapid fermentation onset and superior solubility in beverage applications. Dutch beverage compounders favor FOS for fortified water systems where immediate dissolution and clean mouthfeel prove critical to consumer acceptance.
- Chicory Root Fiber:Native root extract containing mixed inulin-FOS fractions with residual plant matrix compounds.
- Oligofructose:Partially hydrolyzed inulin yielding enhanced sweetness and reduced viscosity in high-fiber baked goods.
Volume sits with Inulin; growth tilts toward Fructooligosaccharides.
Application:
Margin capture potential varies dramatically by regulatory burden and claim substantiation requirements governing each downstream channel.
- Food & Beverage:Dairy alternatives, baked goods, and fortified beverages absorb the majority of commodity-grade prebiotic volume. Belgian processors supply oligofructose streams to oat milk manufacturers seeking mouthfeel replication of traditional dairy fats combined with fermentable fiber positioning.
- Dietary Supplements:Gut health concentrates in capsule and powder formats command premium pricing contingent upon strain-specific clinical substantiation. EFSA health claim restrictions are forcing supplement brands toward dossier-heavy bifidogenic efficacy demonstrations rather than generic fiber content marketing.
- Pharmaceuticals:Excipient-grade specifications for tablet disintegration and controlled release applications.
- Animal Feed:Pet nutrition and livestock gut health formulations absorbing spray-dried grades at lower purity thresholds.
Food & Beverage dominates current volume; Dietary Supplements exhibits the steepest expansion trajectory.
Form:
Handling economics and dissolution kinetics drive form selection, with industrial scale operations favoring bulk flow properties over consumer convenience formats.
- Powder:Spray-dried particulates optimized for pneumatic conveying and homogeneous blending in high-throughput food manufacturing. Continuous drying lines in Wallonia produce food-grade powders with standardized particle size distributions for automated bakery ingredient systems.
- Liquid:Aqueous oligofructose concentrates enabling rapid incorporation without hydration steps. Netherlands-based beverage toll-manufacturers specify liquid streams for direct dosing into UHT processing lines, eliminating powder dispersion equipment capital expenditure.
- Granulated:Agglomerated forms improving flowability for direct compression tableting operations.
- Capsules:Pre-metered unit doses serving supplement brands with limited in-house encapsulation capability.
Powder commands installed capacity; liquid gains share fastest in beverage fortification.
End User:
Procurement sophistication and quality assurance protocols separate institutional buyers from merchant compounders in this category.
- Food Manufacturers:Multinational dairy and bakery operators with dedicated ingredient qualification teams and multi-year supply agreements. Scandinavian oat milk leaders negotiate direct contracts with Belgian chicory processors, collapsing traditional distributor tiers for customized fiber blend specifications.
- Nutraceutical Companies:Brands combining prebiotics with probiotics in synbiotic formulations requiring documented stability through shelf life. French startups in the plant-based yogurt segment source tailored oligofructose-inulin ratios for specific strain compatibility.
- Pharmaceutical Firms:Dosage form developers subject to GMP audit requirements and drug master file submissions.
- Livestock Producers:Feed compounders integrating gut health additives for production animal performance optimization.
Food Manufacturers anchor current procurement volume; Nutraceutical Companies expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The chicory processing corridor spanning Belgium and the Netherlands anchors upstream supply for prebiotic fiber extraction, with wet-milling infrastructure concentrated in Wallonia and Flanders driving industrial scale.
Belgium
Dairy alternative formulators in Flanders source oligofructose for oat milk mouthfeel replication. EFSA novel food dossier expertise in Brussels accelerates regulatory approvals for chicory-derived ingredients. Wallonia's chicory root processing clusters sustain captive supply integration from agricultural sourcing through spray-dried powder output.
Netherlands
Beverage compounders specify liquid oligofructose streams for fortified water applications requiring rapid dissolution. REACH registration protocols for extraction solvents govern supplier qualification at Rotterdam port chemical handling facilities. Eindhoven-region toll-manufacturers negotiate direct procurement contracts collapsing traditional distributor tiers.
Germany
Pharmaceutical firms in Baden-Württemberg specify high-purity inulin grades exceeding 99% for synbiotic formulations. BfR safety assessments align with EFSA health claim restrictions on gut microbiota marketing. Bavarian dairy processors embed standard inulin grades in yogurt matrices for texture modification and fermentable fiber positioning.
India
Nutraceutical brands in Maharashtra explore prebiotic supplement formulations as gut health concentrates gain consumer traction. FSSAI functional food guidelines for prebiotic claims remain underdeveloped, creating first-mover positioning opportunities. Gujarat-based food manufacturers evaluate imported chicory fiber for clean-label bakery applications.
United States
Dietary supplement brands in California formulate gut health capsules combining prebiotics with probiotics in synbiotic positioning. FDA GRAS notification requirements impose 18-24 month safety substantiation delays for chicory-derived ingredient market entry. Midwest food manufacturers assess oligofructose for high-fiber baked goods as clean-label formulation shifts accelerate.
Inulin and Fructooligosaccharide Market Competitive Landscape
Premium-margin players sit above commodity-margin players across extraction purity and clinical substantiation tiers, with pharmaceutical-grade specifications commanding fundamentally different procurement relationships than standard food-grade sourcing. The supplier base concentrates around Belgian and Dutch chicory root processing clusters where wet-milling infrastructure creates geographic moats. Three archetypes dominate: vertically integrated agricultural processors with captive chicory supply, multi-plant ingredient networks optimizing logistics scale, and specialized fermentation technology developers pursuing sucrose-based FOS synthesis. Competitive moves center on toll-manufacturing arrangements for customized fiber blends and enzymatic synthesis capacity expansion for chicory-independent production pathways.
Among European agricultural processors, Cosucra Groupe Warcoing SA, BENEO GmbH, and Roquette Frères exemplify distinct strategic positioning within the prebiotic fiber supply base. Cosucra occupies a specialist role through its Belgian chicory and pea fiber co-production focus. BENEO represents vertical integration archetype with field-to-extract control over upstream agricultural sourcing. Roquette anchors the multi-plant network model with oligofructose supply consistency across dispersed European manufacturing footprints.
| Leading Market Players |
|---|
| Cosucra Groupe Warcoing SA |
| Tate & Lyle PLC |
| BENEO GmbH |
| Roquette Frères |
| The Tierra Group |
| Cargill Incorporated |
| Sensus B.V. |
| FrieslandCampina |
| Ingredion Incorporated |
| Others |
Supply & Pricing Matrix
Family-owned Belgian agricultural processors with multi-generational chicory cultivation holdings command asymmetric pricing power through captive upstream supply, translating field-to-extract control into margin resilience against natural gas volatility and EFSA compliance cost inflation.
Pricing Analysis
Yield-linked pricing anchors the prebiotic fiber market, with pharmaceutical-grade inulin commanding premiums tied to synbiotic formulation outcomes rather than commodity fiber content. Three-tier pricing structure across pharmaceutical, food-grade, and feed-grade levels separates purity-certified extracts from standard chicory fiber. Cost compression in spray-dried powder grades is intensifying because natural gas price volatility erodes continuous drying line economics. Feed compounders exhibit highest price sensitivity due to volume scale and lower purity thresholds, while pharmaceutical firms accept premium positioning for documented bifidogenic efficacy.
Supply Chain Analysis
Returns of spent chicory pulp for animal feed and biogas digestion create circular material flows that offset raw material costs for Wallonia and Flanders processors. Upstream supply concentrates in Belgium, the Netherlands, and northern France where wet-milling infrastructure clusters around Rotterdam-Antwerp chemical handling corridors. Extraction draws from chicory root, sucrose feedstocks, and immobilized biocatalyst systems as emerging synthesis pathways. Single-source vulnerability in Belgian agricultural output represents structural risk given weather volatility and disease pressure on root crops. Distribution runs through direct procurement contracts collapsing traditional distributor tiers, with Scandinavian oat milk brands and French plant-based yogurt startups negotiating toll-manufacturing arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EFSA novel food dossier requirements and spray drying energy intensity will force sub-scale processors into acquisition or exit, favoring incumbents with captive agricultural supply and regulatory expertise.
For Market Incumbents: Cement backward integration into chicory seed genetics and cultivation contracting to secure raw material security against Belgian weather volatility. Expand enzymatic synthesis capacity for sucrose-based FOS production as a chicory-independent pathway, defending margin position against precision fermentation entrants and synthetic prebiotic substitution in infant nutrition applications. For New Entrants and Emerging Players: Launch via toll-manufacturing partnerships with underutilized Wallonia spray drying assets to bypass capital-intensive infrastructure requirements. Target Indian nutraceutical brands in Maharashtra and Gujarat seeking FSSAI-compliant prebiotic ingredients, exploiting underdeveloped functional food guidelines and first-mover positioning for dossier-ready chicory fiber supply. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap Belgian processors with EFSA-approved novel food dossiers and stranded natural gas contracts in Flanders. Long-term viability hinges on microbiome research standardization enabling strain-specific efficacy claims. Watch for REACH solvent restriction enforcement accelerating ethanol replacement retrofit costs as inflection indicator for facility rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Synthesis Capacity Expansion | Biocatalyst immobilization systems enable continuous FOS production from sucrose at commercial scale. |
| Direct Procurement Contract Negotiation | Scandinavian oat milk brands collapse distributor tiers through customized fiber blend toll-manufacturing. |
| EFSA Novel Food Dossier Investment | Streamlined approvals accelerate new product introductions across EU member states for chicory-derived ingredients. |
| Spray Drying Energy Retrofit | Natural gas price volatility forces continuous drying line efficiency investments in Wallonia processing clusters. |
| Precision Fermentation Partnership | Microbial FOS synthesis from sucrose substrates emerges as chicory-independent production pathway. |
Research Methodology
Multi-period observation of EFSA novel food approval timelines, chicory root harvest yields, and natural gas pricing anchored the trend analysis, supplemented by interviews with chicory processing plant managers, dairy alternative formulation scientists, FSSAI regulatory consultants, and Belgian agricultural cooperative directors. Secondary validation drew from EFSA novel food opinions, REACH registration databases, SEC filings of listed ingredient suppliers, and Benelux customs trade data. Bottom-up volume modeling triangulated against top-down market sizing across extraction methodology tiers.
Input-output matrices mapped chicory root throughput to spray-dried powder and liquid oligofructose outputs across the projection horizon. Segmentation dimensions modeled included chain-length distribution, application regulatory burden, form handling economics, and end-user procurement sophistication. CAGRs were derived from trend extrapolation of prebiotic incorporation rates in dairy alternatives and supplement formulations. Industry-specific forecast inputs incorporated EFSA health claim restriction evolution and FSSAI guideline development trajectories.
Regulatory approval delays, agricultural weather shocks, and energy price volatility are the dominant revision risks for prebiotic fiber demand projections. Forecasts reflect assumptions around EFSA dossier processing efficiency and chicory root yield stability. Practitioners should monitor REACH solvent restriction enforcement and Indian FSSAI guideline finalization for early signals of supply chain disruption or market access expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Food Can Coatings Market
Food Components and Additives
Soybean by-Products Market
Food Components and Additives
Fermentation Defoamer Market
Food Components and Additives
Food Hydrocolloids Market
Food Components and Additives
China Food Hydrocolloids Market
Food Components and Additives
Food Grade Activated Carbon Market
Food Components and Additives
Asia-Pacific Food Anti Caking Agents Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
Edible Oil Co-Products and by-Products Market
Food Components and Additives
Astaxanthin Market
Food Components and Additives
Global Zeaxanthin Market
Food Components and Additives
Food Grade Xanthan Gum Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
USA Food Premix Market
Food Components and Additives
Isoflavones Market
Food Components and Additives
Natural Fatty Acids Market